
 Industrial Aerators Market | 2026-2036
Industrial Aerators Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Aerators Market Analysis
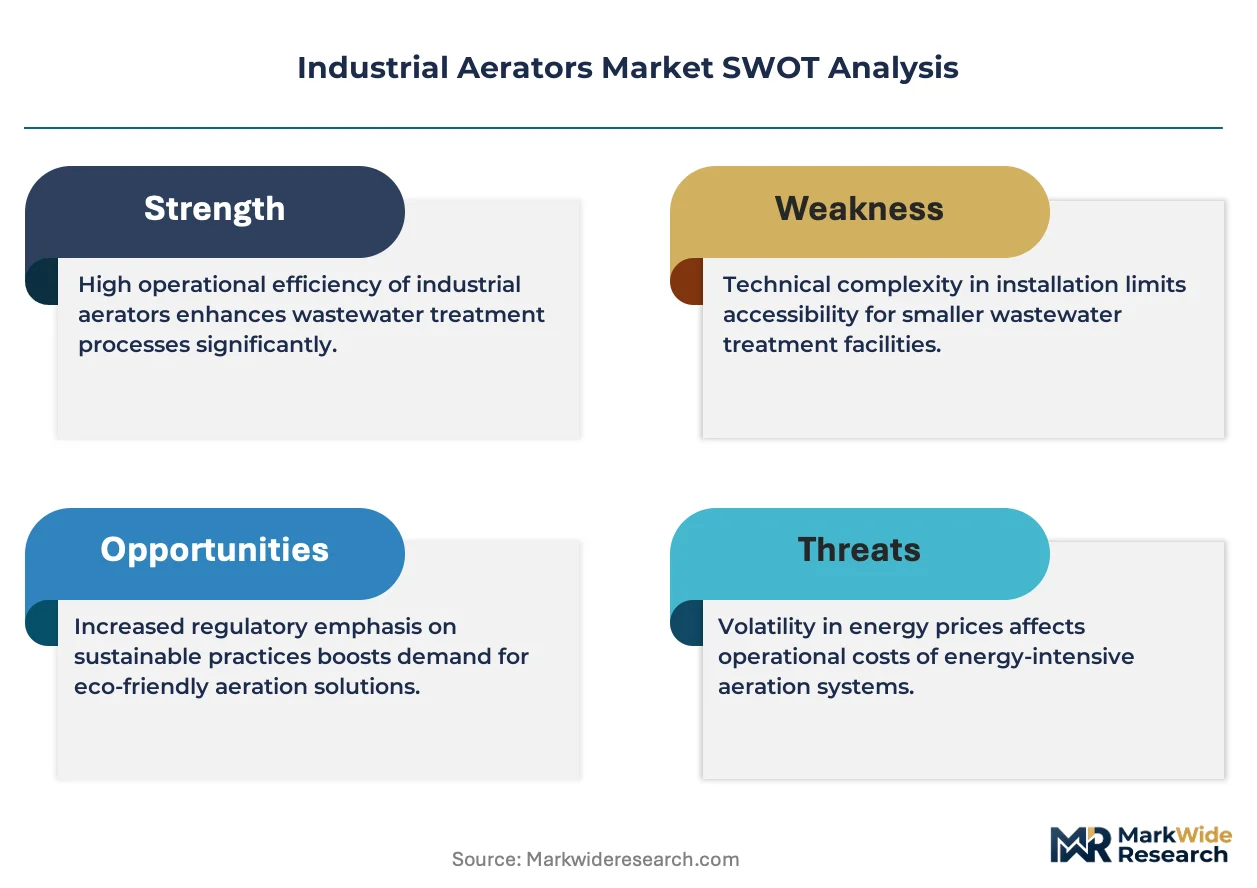
Buyer concentration among municipal water utilities is consolidating as regional authorities merge operations to achieve procurement scale. Xylem Inc leverages its vertical integration across pump and aeration portfolios to sustain pricing power in large infrastructure tenders. Sulzer Ltd. anchors its position through specialized impeller engineering for high-efficiency submersible systems, while Fluence Corporation Limited differentiates via decentralized containerized aeration solutions for industrial clients lacking centralized treatment access.
Industrial aerators are mechanical or pneumatic devices engineered to dissolve oxygen into water bodies at rates typically measured in standard oxygen transfer efficiency pounds per horsepower-hour, serving biological treatment processes that degrade organic pollutants. Surface aerators dominate installed base volumes due to lower capital outlay and simpler maintenance protocols, though submersible aerators capture expanding share in retrofit applications where energy efficiency targets override first-cost considerations. Diffused aeration systems command premium positioning in large-scale municipal plants where fine-bubble membrane diffusers optimize oxygen transfer coefficients.
The EPA enforces effluent limitations through NPDES permits that directly mandate dissolved oxygen thresholds, compelling continuous aeration upgrades. China's MEE implements increasingly stringent GB standards for wastewater discharge that accelerate equipment replacement timelines. India's CPCB enforces sewage treatment plant compliance deadlines that expand addressable demand. Stakeholders must weigh energy efficiency certification thresholds against total lifecycle cost positioning as electricity tariffs escalate and carbon accounting penetrates utility procurement criteria.
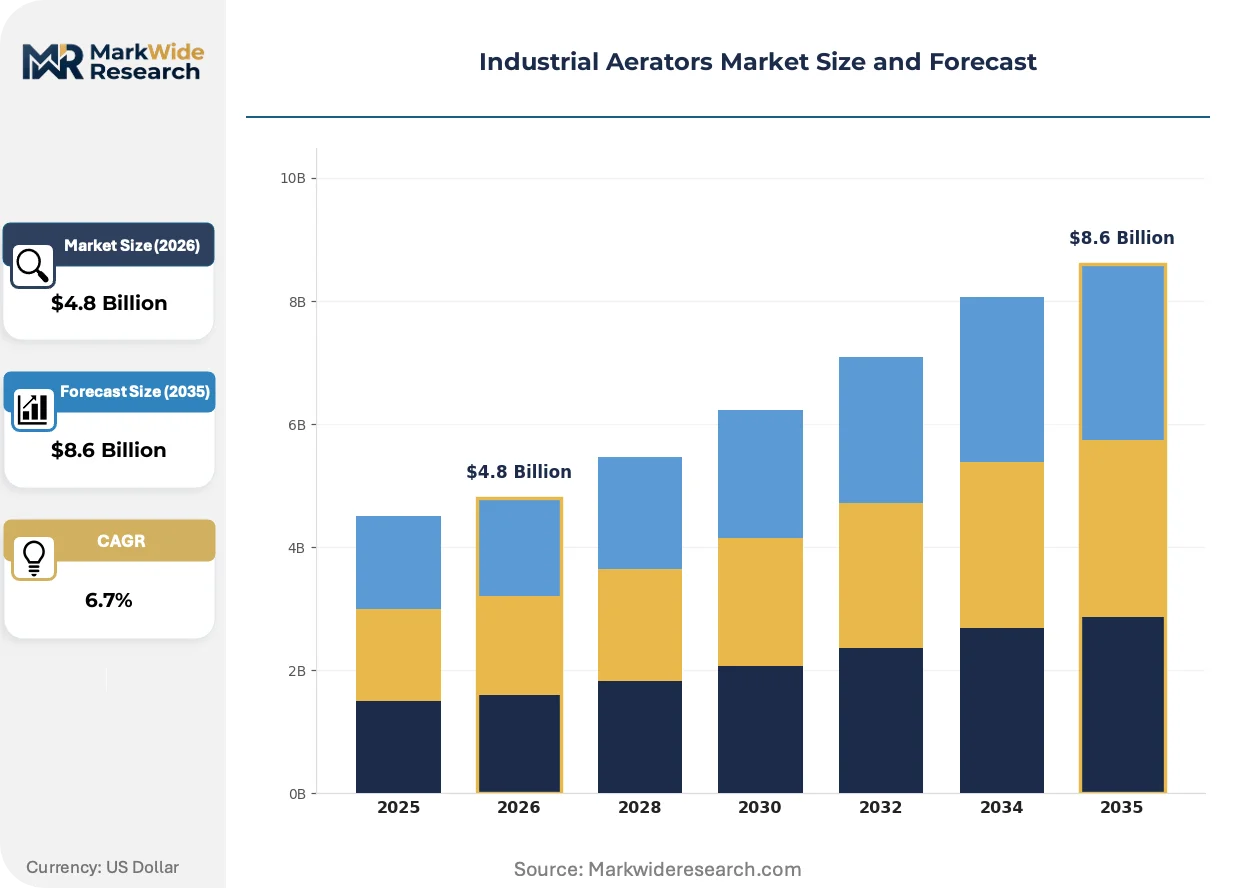
Market Dynamics
Energy efficiency mandates are compressing replacement cycles across municipal wastewater infrastructure, forcing utilities to prioritize lifecycle cost over first-cost procurement. The EPA's NPDES permit renewals and China's GB standard upgrades create synchronized demand pulses for high-transfer-efficiency aeration systems.
Growth Catalysts
- EPA NPDES permit renewals:US municipal utilities face dissolved oxygen threshold enforcement that mandates continuous aeration infrastructure upgrades across aging treatment plants.
- Fine-bubble membrane diffusion:Oxygen transfer coefficient optimization in large-scale facilities is displacing coarse-bubble systems where energy tariffs exceed operational savings thresholds.
- India's sewage treatment compliance:CPCB-mandated STP deadlines in urban clusters are accelerating equipment procurement timelines for submersible aerator deployment.
Market Restraints
- Stainless steel input volatility:Submersible impeller fabrication depends on nickel-alloy price stability that fluctuates with Indonesian and Philippine ore export policies.
- Specialized foundry concentration:High-precision casting capacity for large-diameter surface aerators clusters in China's Jiangsu and Zhejiang provinces, creating single-source vulnerability.
- Legacy system interoperability:Existing SCADA architectures in US municipal plants resist seamless integration with variable-frequency drive retrofits without middleware investment.
Strategic Opportunities
- Brazil's sanitation concession wave:Federal privatization of state-level water utilities under the Marco Legal do Saneamento framework opens tender pipelines for foreign equipment suppliers.
- Containerized decentralized units:Industrial clients without centralized treatment access in India's pharmaceutical clusters seek plug-and-deploy aeration for batch-process effluent.
- EU Green Deal carbon accounting:CSRD disclosure requirements for Scope 2 emissions are tilting procurement criteria toward aerators with verified kWh-per-kg-O2-transfer certifications.
Industry Challenges
- Electromechanical technician scarcity:Submersible motor rewind and impeller balancing expertise concentrates in aging workforces across US Rust Belt manufacturing regions.
- ISO 14001 environmental management certification:Municipal procurement departments now require documented lifecycle carbon footprints that extend supply chain audit timelines by 4-8 months.
- Legacy blower-aerator hybrid retrofits:Existing positive displacement blower infrastructure resists phased upgrade paths that preserve civil works while adding fine-bubble diffusion grids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Aerators Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Aerators, Submersible Aerators, Diffused Aerators, Mechanical Aerators End User: Water Treatment Plants, Wastewater Management, Aquaculture, Industrial Processing Application: Wastewater Treatment, Pond Aeration, Fish Farming, Bioremediation Technology: Electric Aeration, Solar Aeration, Acoustic Aeration, Hybrid Systems |
| Companies Covered | Xylem Inc, Pentair plc, Sulzer Ltd., Aqua-Aerobic Systems Inc, Aeration Industries International, LLC, Fluence Corporation Limited, Airmaster Aerator LLC, Advanced Industrial Aeration, Otterbine Barebo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Aerators Market Emerging Trajectories
Digital instrumentation and predictive maintenance protocols are penetrating aeration infrastructure, shifting competitive advantage from hardware durability to operational intelligence delivery. Equipment suppliers now compete on energy analytics integration rather than mechanical reliability alone.
Variable-frequency drive integration with dissolved oxygen sensors is automating aeration intensity modulation in real-time process control loops. Municipal operators in Germany's Ruhr region are deploying these systems to reduce energy consumption during low-load nighttime periods. The technology is automating manual blower staging decisions that previously required on-site operator intervention, compressing staffing requirements for mid-sized treatment facilities.
The EU F-Gas Regulation phase-down schedules are accelerating membrane diffuser material transitions from EPDM to silicone-based compounds with lower global warming potential footprints. German and Dutch membrane manufacturers are reformulating compound recipes to maintain oxygen transfer efficiency under tighter polymer specifications. Fine-bubble systems in Northern European municipal plants face accelerated replacement timelines as existing EPDM inventory depletes under import quota constraints.
Performance-based service contracting is displacing traditional capital purchase models among US regional water authorities seeking to transfer operational risk. Xylem and Sulzer are restructuring offerings around guaranteed energy savings rather than equipment ownership in California and Texas utility tenders. This restructuring concentrates vendor accountability on kilowatt-hour outcomes, shifting margin capture from hardware markups to long-term service annuities.
Industrial Aerators Market Segmentation
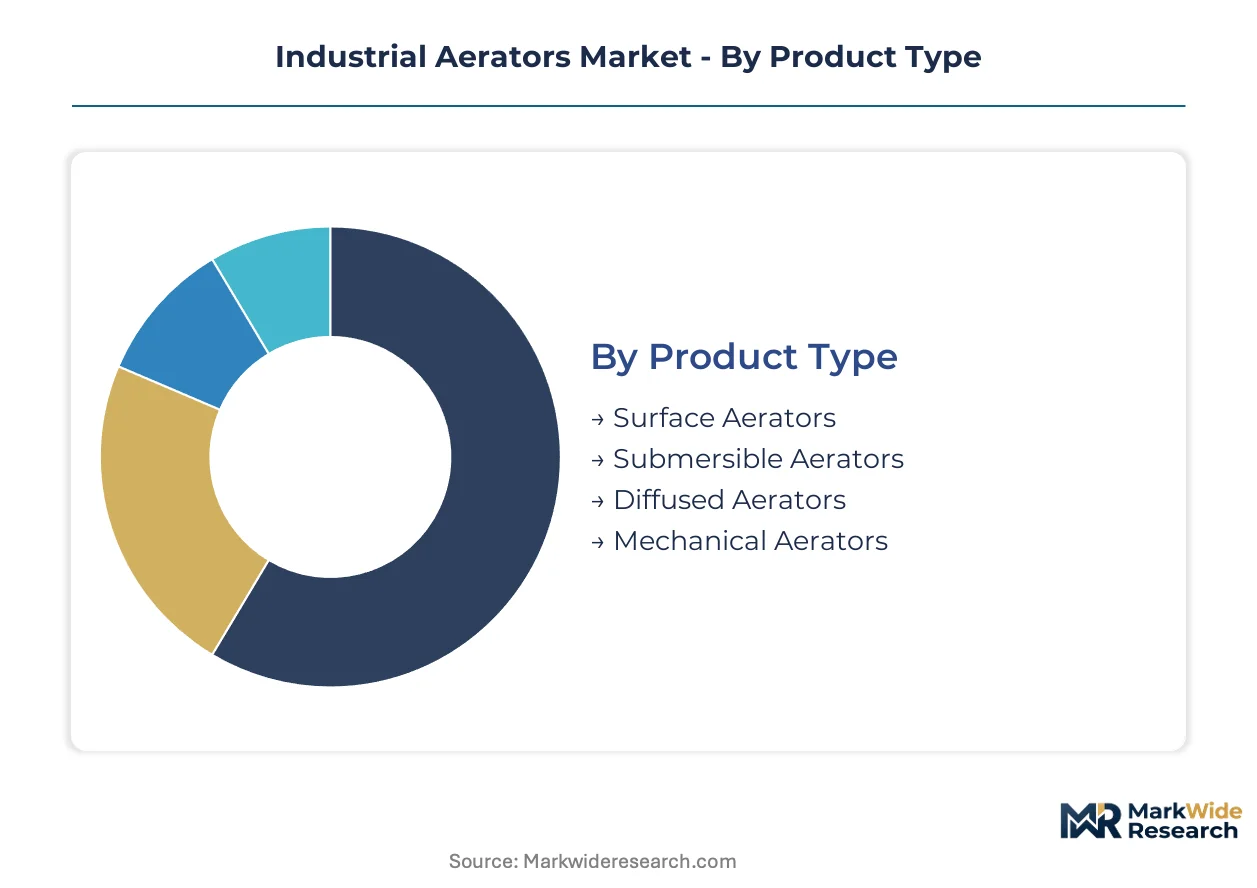
Equipment selection in the industrial aerators market hinges on oxygen transfer efficiency requirements, energy tariff structures, and civil works constraints. Segmentation reveals divergent capital intensity profiles and lifecycle economics that shape procurement decisions across municipal and industrial end users.
Product Type:
Capital intensity varies sharply across aerator architectures, with civil works integration and motor specifications driving upfront investment differentials.
- Surface Aerators:Floating or fixed-mounted impeller systems deliver oxygen through atmospheric contact and hydraulic spray patterns. Municipal utilities in India and Brazil favor these units for their lower installation costs and accessible maintenance protocols, though energy penalties accumulate in high-tariff environments.
- Submersible Aerators:Bottom-mounted turbine or jet-pump configurations force air-water mixing under hydrostatic pressure. Germany's Ruhr region utilities specify these systems for retrofit applications where dissolved oxygen sensor integration with variable-frequency drives justifies premium first costs through tariff savings.
- Diffused Aerators:Bubble generation through perforated membranes or ceramic plates optimizes oxygen transfer coefficients in large basins.
- Mechanical Aerators:Brush or paddle-wheel designs serve lagoon applications with shallow depth constraints.
Surface aerators absorb the bulk of installed capacity; submersible aerators are expanding most quickly.
End User:
Customer procurement sophistication diverges between regulated utilities with lifecycle cost mandates and industrial operators prioritizing operational flexibility.
- Water Treatment Plants:Potable water facilities deploy aeration for iron oxidation and taste-odor control. China's MEE-enforced GB standards for drinking water quality accelerate membrane diffuser procurement in provincial treatment centers.
- Wastewater Management:Biological nutrient removal processes dominate oxygen demand. US EPA NPDES permit renewals compel continuous aeration infrastructure replacement across aging municipal networks.
- Aquaculture:Intensive shrimp and finfish operations require emergency backup aeration capacity.
- Industrial Processing:Food, pharmaceutical, and chemical plants treat process effluent before discharge.
Wastewater management commands the largest equipment volumes; aquaculture shows the steepest expansion trajectory.
Application:
Process intensity and regulatory exposure create distinct equipment durability and automation requirements across use cases.
- Wastewater Treatment:Activated sludge and extended aeration processes consume the majority of industrial oxygen transfer capacity. Brazil's Marco Legal do Saneamento concession tenders are concentrating demand for fine-bubble systems in state-level utility privatizations.
- Pond Aeration:Decorative and stormwater retention basins specify low-profile floating units.
- Fish Farming:Recirculating aquaculture systems demand 24-hour oxygen security with redundant compressor arrays.
- Bioremediation:In-situ groundwater treatment uses sparging and air stripping technologies.
Wastewater treatment anchors equipment deployment; fish farming is climbing the fastest.
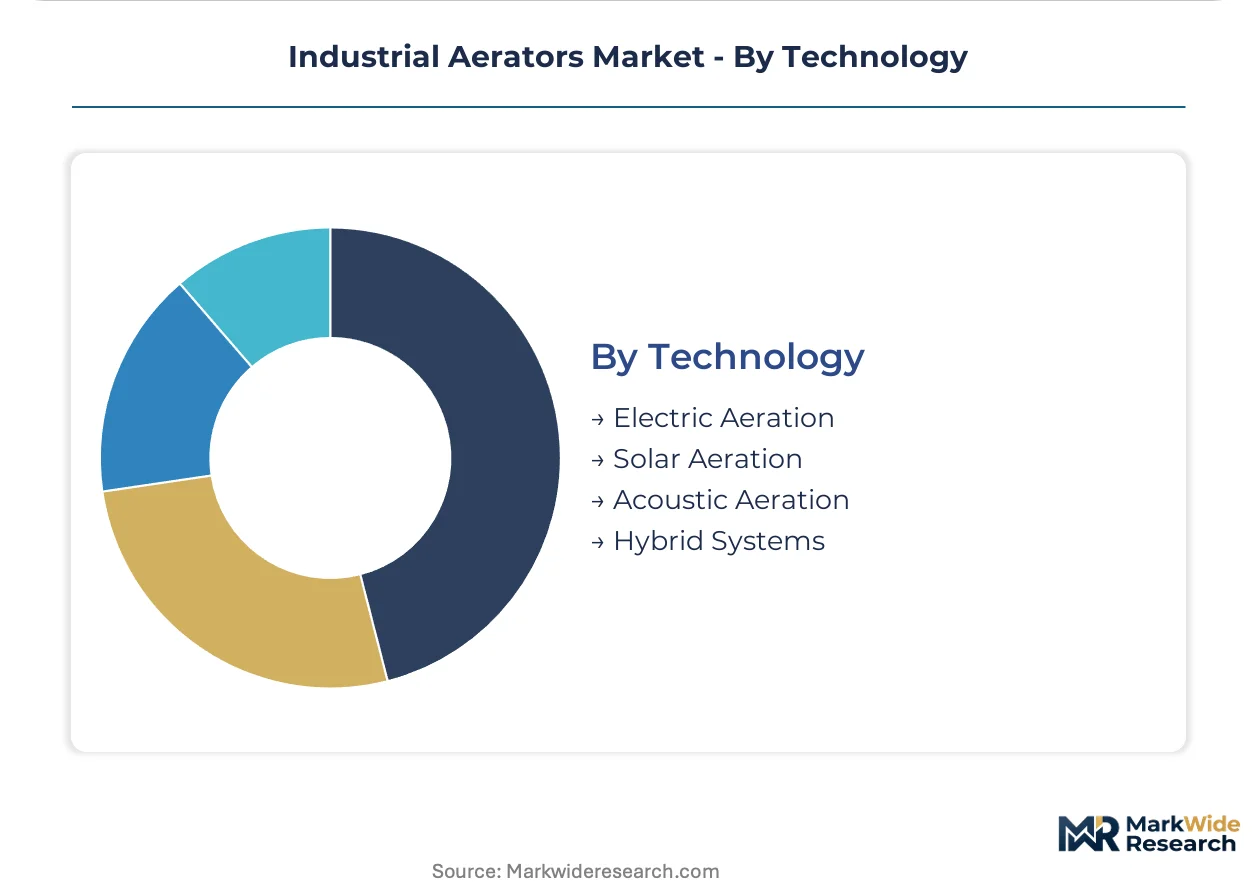
Technology:
Power source selection reflects grid reliability, carbon accounting pressures, and acoustic emission constraints in populated areas.
- Electric Aeration:Grid-powered blowers and motors deliver consistent oxygen transfer with established maintenance protocols. EU Green Deal CSRD disclosure requirements are tilting procurement toward units with verified kWh-per-kg-O2-transfer certifications.
- Solar Aeration:Photovoltaic-powered floating units serve off-grid aquaculture and remote industrial sites.
- Acoustic Aeration:Ultrasonic cavitation systems generate micro-bubbles without mechanical impellers.
- Hybrid Systems:Grid-solar dual-power configurations with battery backup address tariff peak-shaving objectives.
Electric aeration retains dominant installed base; solar aeration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel feedstock from Indonesian and Philippine ore deposits anchors submersible impeller fabrication costs across major aeration markets. Nickel-alloy price volatility ripples through foundry economics in China's Jiangsu province. Regional regulatory enforcement patterns determine equipment replacement cadence.
United States
Municipal utilities in California and Texas face EPA NPDES permit renewals that mandate dissolved oxygen threshold compliance. The EPA enforces effluent limitations through permit structures that compel continuous aeration infrastructure upgrades. Rust Belt manufacturing regions concentrate aging electromechanical technician workforces for submersible motor rewind expertise.
China
Provincial treatment centers in Jiangsu and Zhejiang provinces absorb membrane diffuser procurement pressure under MEE-enforced GB standard upgrades. The MEE implements increasingly stringent wastewater discharge standards that accelerate equipment replacement timelines. Foundry capacity for large-diameter surface aerator casting clusters in these coastal provinces.
Germany
Ruhr region utilities specify submersible systems for retrofit applications where dissolved oxygen sensor integration justifies premium first costs. The EU F-Gas Regulation phase-down accelerates membrane diffuser material transitions from EPDM to silicone-based compounds. German membrane manufacturers reformulate compound recipes to maintain oxygen transfer efficiency under tighter polymer specifications.
India
Urban clusters in Maharashtra and Gujarat face CPCB-mandated sewage treatment plant compliance deadlines that expand addressable demand. The CPCB enforces STP deadlines that accelerate equipment procurement timelines for submersible aerator deployment. Pharmaceutical clusters in these states seek containerized decentralized units for batch-process effluent without centralized treatment access.
Brazil
State-level water utilities under the Marco Legal do Saneamento framework open tender pipelines for foreign equipment suppliers. Federal privatization mandates concentrate concession activity in São Paulo and Rio de Janeiro sanitation authorities. These metropolitan regions drive demand for fine-bubble systems in utility privatization tenders.
Industrial Aerators Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue containerized decentralized solutions for industrial clients lacking centralized infrastructure. The vendor base stratifies across three tiers: integrated pump-aeration portfolios, specialized impeller engineering shops, and plug-and-deploy unit fabricators. Dominant competitive moves include backward integration into foundry capacity and geographic expansion through concession-based service contracting.
Among diversified water infrastructure groups, Xylem Inc and Pentair plc occupy positions that exemplify portfolio breadth across pump and aeration technologies. Sulzer Ltd. anchors the specialized engineering tier with its focus on high-efficiency submersible system design. Fluence Corporation Limited represents the emerging decentralized solutions archetype, targeting industrial clients with containerized deployment models.
| Leading Market Players |
|---|
| Xylem Inc |
| Pentair plc |
| Sulzer Ltd. |
| Aqua-Aerobic Systems Inc |
| Aeration Industries International, LLC |
| Fluence Corporation Limited |
| Airmaster Aerator LLC |
| Advanced Industrial Aeration |
| Otterbine Barebo Inc. |
| Others |
Supply Flow & Price Mechanics
Electromechanical technician scarcity across US Rust Belt manufacturing regions widens pricing-tier spreads between premium service-contract offerings and economy equipment-only sales. Labor-cost differentials between OEM-authorized service networks and independent repair shops translate into three-tier pricing structure across premium, standard, and economy levels for submersible motor rewind and impeller balancing work.
Pricing Analysis
High-volume surface aerator sales compress margins while premium submersible systems with integrated dissolved oxygen sensors capture pricing power through energy-guarantee contracting. Price differentiation rests on ISO 14001 environmental management certification status and after-sales service bundling rather than hardware specifications alone. Pricing pressure stems from stainless steel input volatility as nickel-alloy feedstock fluctuates with Indonesian ore export policies. Municipal water utilities exhibit highest price sensitivity due to procurement consolidation, while pharmaceutical clusters in India prioritize operational flexibility over first-cost minimization.
Supply Chain Analysis
Refurbishment flows for submersible motor assemblies concentrate in US Rust Belt electromechanical shops and German Ruhr region service depots, creating reverse-logistics value recovery for end-of-life equipment. Foundry capacity for large-diameter surface aerator casting clusters in China's Jiangsu and Zhejiang provinces, while membrane diffuser silicone compound production centers on German and Dutch specialty polymer manufacturers. Raw material dependencies encompass Indonesian nickel-alloy ore, Chinese stainless steel billet, and European silicone rubber formulations. Single-source vulnerability in Jiangsu-Zhejiang foundry concentration threatens equipment availability during export quota disruptions. Distribution runs through municipal procurement consortiums in consolidated regional water authorities and direct OEM contracting for industrial processing clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EPA NPDES permit mandates and China's GB standard upgrades erect regulatory moats favoring certified incumbents with documented lifecycle carbon footprints.
For Market Incumbents: Anchor market position through backward integration into Jiangsu-Zhejiang foundry capacity to secure large-diameter casting supply against export policy volatility. Deepen service-contract penetration with performance-based energy guarantees that transfer operational risk from municipal utilities, insulating margin capture from hardware commoditization pressure from containerized decentralized entrants. For New Entrants and Emerging Players: E-commerce-enabled direct procurement channels offer lower customer acquisition costs for penetrating India's pharmaceutical clusters seeking plug-and-deploy containerized units. Target batch-process effluent applications in Maharashtra and Gujarat where centralized treatment infrastructure gaps persist. Pursue white-label manufacturing partnerships with Jiangsu foundries to bypass capital-intensive casting capacity requirements. For Investors and Strategic Acquirers: Re-rating potential sits with specialized impeller engineering shops given EU F-Gas Regulation-driven membrane material transitions and accelerating fine-bubble system replacement timelines. Long-term viability favors acquisition targets with captive silicone compound formulation expertise and verified kWh-per-kg-O2-transfer certifications under CSRD disclosure frameworks. Monitor Indonesian nickel-alloy export policy shifts as inflection indicator for submersible aerator margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Jiangsu-Zhejiang casting capture insulates against stainless steel billet export disruptions. |
| Performance-Based Service Contracting | Guaranteed energy savings models transfer operational risk from California-Texas municipal utilities. |
| Silicone Compound Formulation Investment | German-Dutch polymer expertise aligns with EU F-Gas Regulation EPDM phase-down mandates. |
| Containerized Decentralized Unit Deployment | Plug-and-deploy architectures address India's pharmaceutical cluster infrastructure gaps. |
| Predictive Maintenance Platform Development | Digital instrumentation integration shifts competitive advantage from hardware durability to operational intelligence. |
Methodological Framework
Document review covered EPA NPDES permit filings, China's MEE GB standard documentation, EU F-Gas Regulation implementation guidance, and municipal utility procurement records, complemented by interviews with plant engineers at wastewater treatment facilities, maintenance directors at industrial processing sites, OEM procurement teams, and aftermarket service heads. Secondary validation drew from SEC 10-K filings of listed water infrastructure groups, customs trade data on stainless steel billet flows, and IEA energy efficiency reports. Bottom-up equipment shipment tallies and top-down utility capital expenditure surveys underwent cross-triangulation.
Historical installation base analysis against panel input from regional water authority planning officers anchored growth projections across the analysis window. Segmentation modeling encompassed product architecture, end-user regulatory exposure, application process intensity, and power source carbon accounting tier. CAGRs derived from equipment replacement cycle compression under tightening dissolved oxygen mandates and energy tariff escalation trajectories. Forecast inputs incorporated nickel-alloy price volatility assumptions and foundry capacity utilization rates in Jiangsu province.
The model holds under continued EPA NPDES permit enforcement and MEE GB standard upgrade implementation; deviation in Indonesian ore export policy or EU F-Gas Regulation timeline acceleration would shift equipment cost structures and replacement cadences. Forecasts reflect documented regulatory assumptions and commodity price baselines. Practitioners should monitor Indonesian mining ministry export quota announcements and EU polymer import restriction schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Global Solar-Powered Pump Market
Pumps and Control Devices
Chopper Pumps Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Europe Submersible Pump Market
Pumps and Control Devices
Industrial ASME B73.1 Centrifugal Pumps Market
Pumps and Control Devices
Asia Pacific Side Channel Pumps Market
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Electrostatic Coalescers Market
Pumps and Control Devices
India Solar Water Pump Systems Market
Pumps and Control Devices
Screw Pumps Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Pump Tubes Market
Pumps and Control Devices
Automatic Water Level Controller Market