
 Screw Pumps Market | 2026-2036
Screw Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Screw Pumps Market Outlook
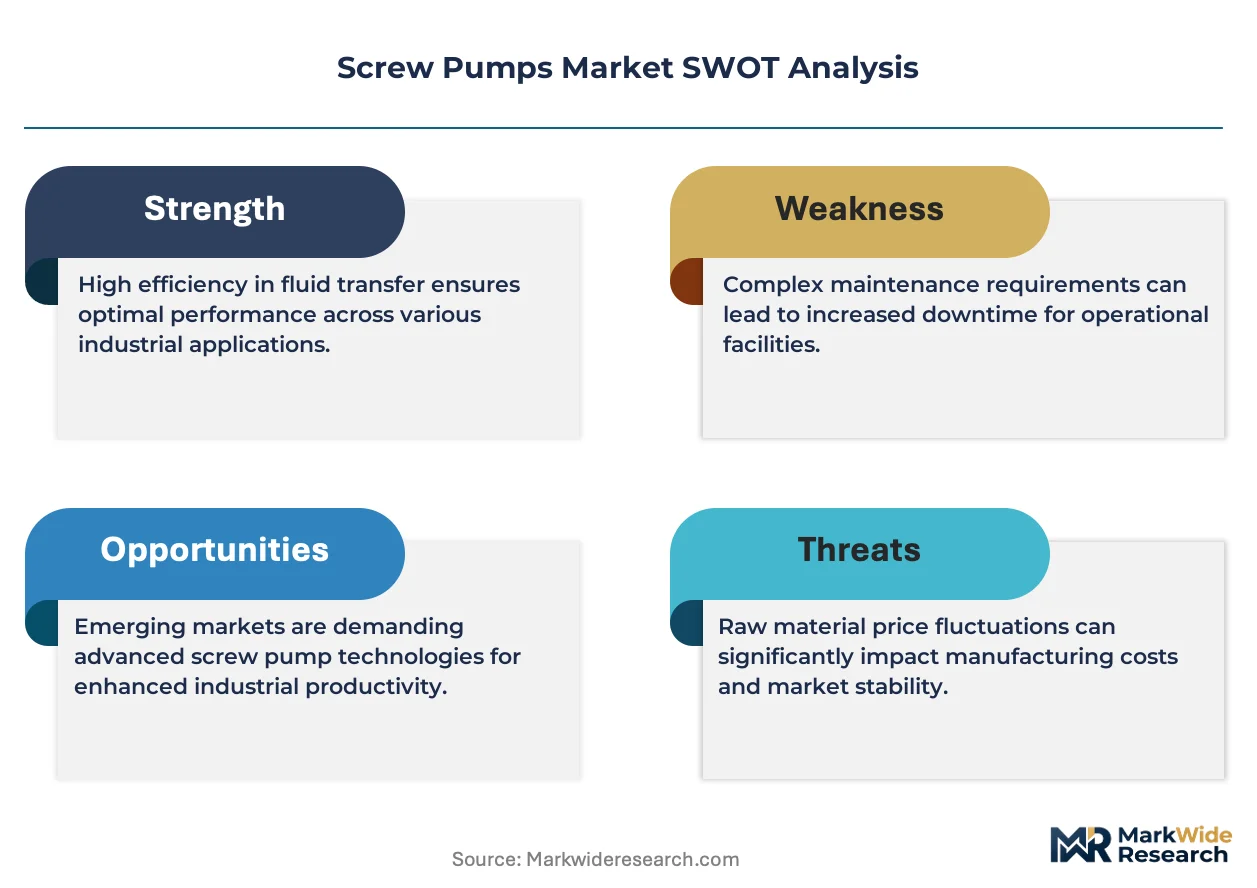
API 676 qualification for rotary pumps is reorganizing competitive access across the Screw Pumps landscape, raising engineering barriers for entrants lacking test-rig infrastructure and metallurgical traceability. Flowserve Corporation leverages integrated foundry-to-test capabilities to sustain qualification throughput across API and non-API product lines. NETZSCH Pumpen & Systeme GmbH anchors its position through deep specialization in progressing cavity geometries for high-viscosity slurries. KSB SE & Co. KGaA competes on hydraulic coverage breadth, extending certified pump families into modular skid packages for downstream installations.
Screw pumps are positive-displacement rotary machines employing one or more intermeshing helical rotors within a close-tolerance housing to move fluids with minimal pulsation, achieving discharge pressures up to 30 bar and handling viscosities from 1 cSt to over 100,000 cSt without efficiency collapse. Their primary industrial purpose centers on continuous, shear-sensitive transfer of crude oil, multiphase flows, polymer melts, and abrasive slurries where centrifugal alternatives suffer cavitation or wear. Twin-screw configurations dominate high-flow hydrocarbon applications due to balanced axial loads and dry-run tolerance, while progressive cavity designs capture margin pools in wastewater and biosolids handling where stator elastomer technology differentiates service life. Single-screw variants retain mature positions in food-grade metering, though growth velocity lags behind multi-screw systems penetrating chemical processing.
FDA regulations govern sanitary screw pump deployments in food and pharmaceutical fluid paths, while EPA effluent standards drive water treatment utilities toward sealed progressive cavity designs eliminating gland leakage. The EU F-Gas Regulation and REACH chemical restrictions are reshaping stator elastomer formulations and lubricant specifications for European-installed units. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these compounds currently pervade high-performance sealing and coating systems throughout the screw pump supply base.
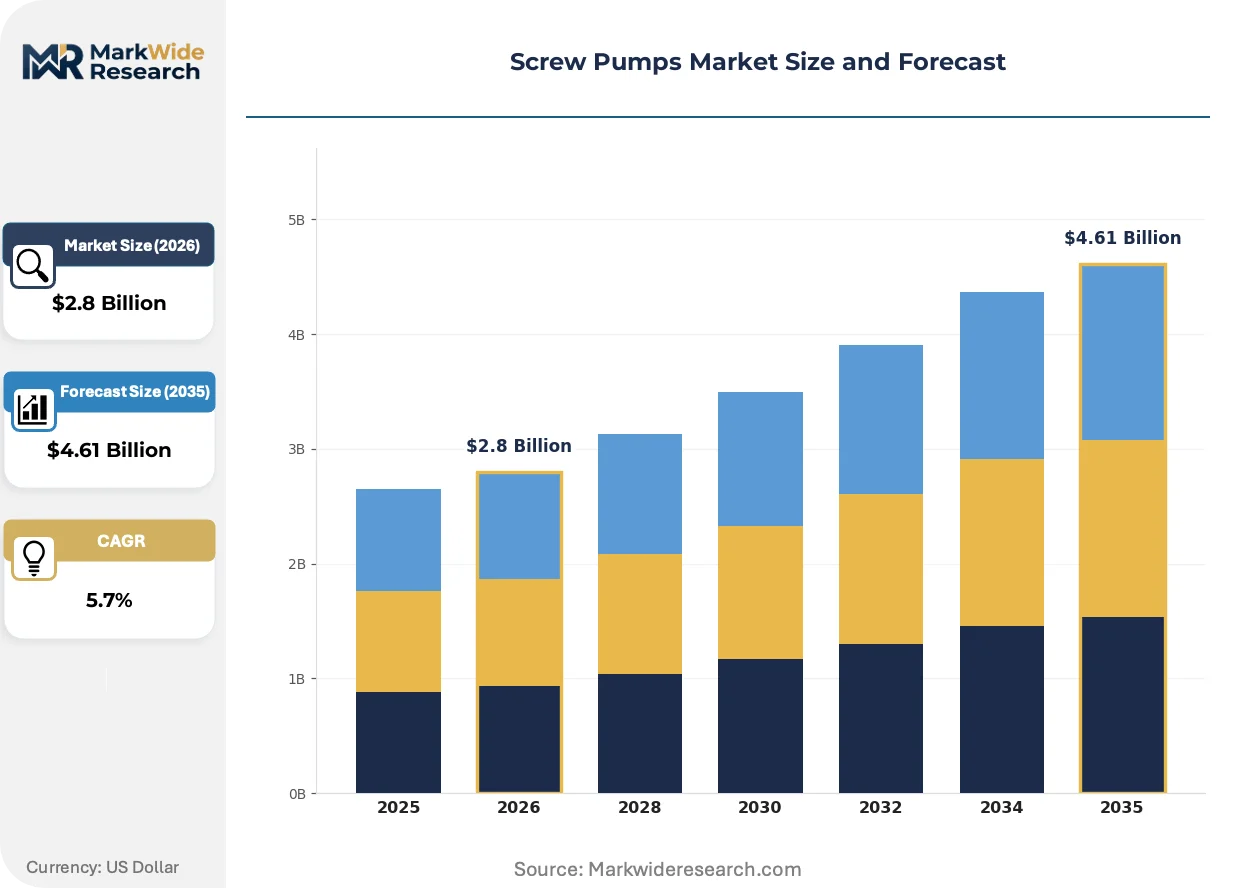
Market Dynamics
API 676 qualification cycles are compressing vendor access windows as test-rig capacity constraints force buyers toward pre-certified suppliers with captive metallurgical traceability systems.
Growth Catalysts
- REACH chemical restrictions:European stator reformulation mandates are accelerating replacement demand for legacy elastomer configurations in chemical processing facilities.
- Twin-screw dry-run tolerance:Hydrocarbon transfer applications favor balanced axial load designs eliminating auxiliary sealing systems.
- German precision engineering clusters:Concentrated procurement pull from Ruhr industrial corridor creates volume aggregation for modular skid packages.
Market Restraints
- High-performance alloy input costs:Nickel-based superalloy price volatility compresses margin pools for custom rotor manufacturing.
- Test-rig infrastructure concentration:North American and European third-party certification capacity limits qualification throughput for mid-tier entrants.
- Centrifugal pump substitution:Low-viscosity crude transfer applications increasingly default to API 610 centrifugal alternatives below 50 cSt thresholds.
Strategic Opportunities
- India wastewater infrastructure:Central Public Health and Environmental Engineering Organisation mandates for sealed sludge handling create progressive cavity demand.
- EU F-Gas Regulation:Refrigerant containment requirements drive sealed system specifications in cooling circuit applications.
- Digital twin convergence:Physics-based rotor wear modeling combined with vibration telemetry enables predictive maintenance service contracts.
Industry Challenges
- Multiphase flow simulation expertise:Computational fluid dynamics specialization for gas-liquid mixtures remains concentrated among legacy hydrocarbon equipment suppliers.
- API 676 documentation timelines:Extended witness test scheduling creates order-to-delivery compression for project-based chemical installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screw Pumps Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Screw, Twin-Screw, Multi-Screw, Progressive Cavity End User: Oil & Gas, Water Treatment, Chemical Processing, Food & Beverage Application: Fluid Transfer, Mixing, Metering, Heating Drive Method: Electric, Hydraulic, Pneumatic, Mechanical |
| Companies Covered | Flowserve Corporation, KSB SE & Co. KGaA, NETZSCH Pumpen & Systeme GmbH, Alfa Laval AB, CIRCOR International Inc., Sulzer Ltd., ITT Inc., SPX Flow Inc., KRAL AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screw Pumps Market Strategic Shifts
Electronics integration and materials science advances are reconfiguring screw pump architectures around predictive capability and seal-less operation.
Magnetic drive coupling technology is miniaturizing across chemical processing installations. Specialty chemical producers in the US Gulf Coast are specifying hermetically sealed twin-screw units for toxic or volatile fluid transfer. The elimination of mechanical seals is compressing maintenance intervals and enabling continuous operation in EPA-regulated emissions-controlled environments.
The EU F-Gas Regulation is tightening refrigerant containment standards for cooling circuit pumps. Equipment suppliers must now certify stator elastomers and lubricant formulations against phasedown schedules for hydrofluorocarbon compounds. Food-grade and pharmaceutical installations across Germany and France are prioritizing F-Gas-compliant progressive cavity configurations for chilled product transfer.
Buyer concentration among integrated energy majors is compressing vendor negotiation cycles. National oil companies in the Middle East are consolidating procurement through framework agreements covering multi-year rotor and stator replacement programs. This aggregation is displacing spot purchasing for standard twin-screw configurations in upstream production facilities.
Screw Pumps Market Segmentation
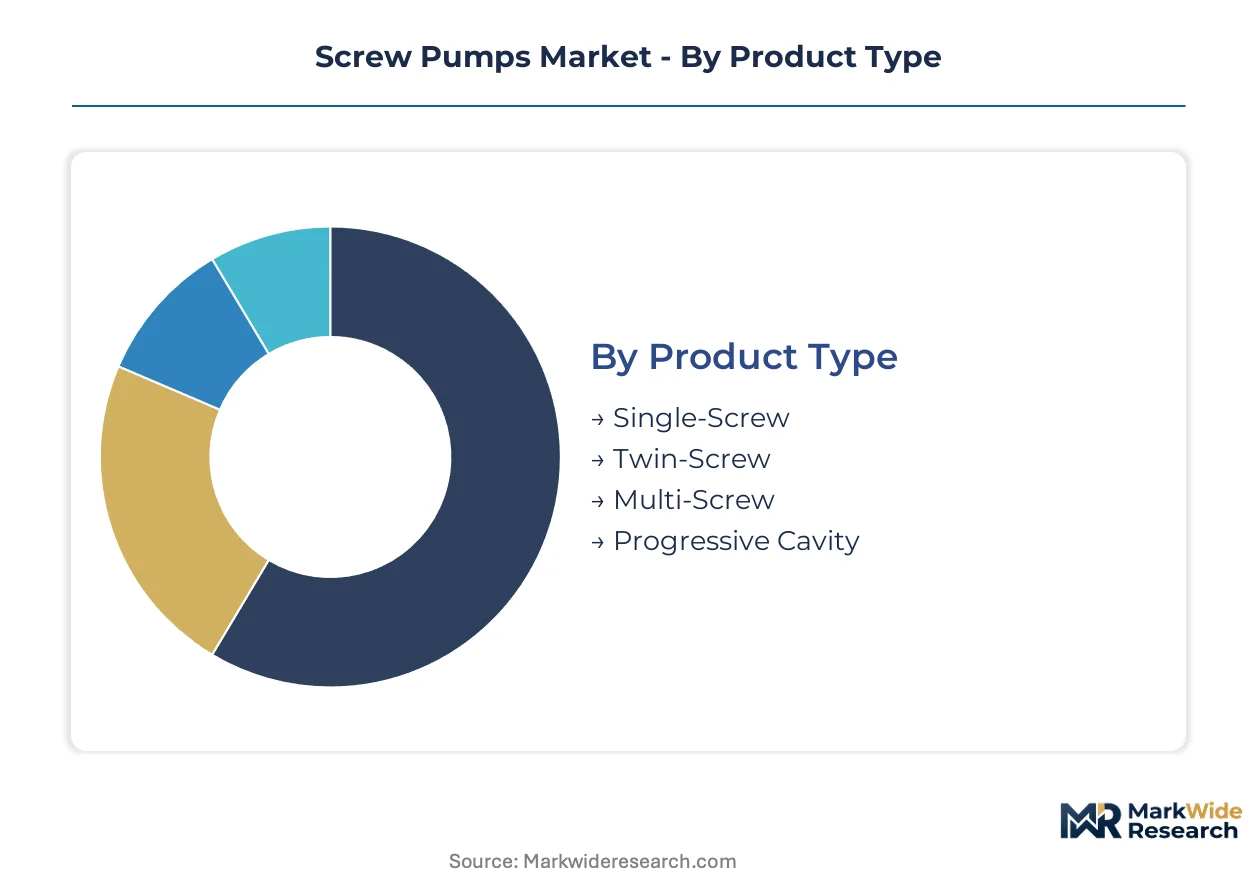
Screw pump architectures diverge sharply across viscosity ranges, sealing requirements, and regulatory exposure. Buyers segment procurement by API 676 qualification status, FDA compliance for sanitary paths, and REACH-mandated elastomer compatibility.
Product Type:
API 676 qualification thresholds and REACH chemical restrictions differentiate rotor-housing configurations across chemical processing and hydrocarbon transfer.
- Twin-Screw:Balanced axial load geometry enables dry-run tolerance without auxiliary sealing. Demand concentrates in German Ruhr corridor refineries where modular skid procurement aggregates volume for leak-free crude transfer.
- Progressive Cavity:Single helical rotor within elastomer stator handles viscosities exceeding 100,000 cSt. Water treatment utilities in India specify sealed configurations meeting Central Public Health and Environmental Engineering Organisation mandates for biosolids handling.
- Single-Screw:Eccentric rotor design serves food-grade metering with FDA-compliant surface finishes.
- Multi-Screw:Three-plus intermeshing rotors deliver pulse-free flow for polymer melt transfer in specialty chemical production.
Twin-screw configurations handle the majority of throughput; progressive cavity designs are expanding most quickly on share as wastewater infrastructure upgrades accelerate.
End User:
Cost tier differentiation separates specification-grade procurement from standard catalog selection across process industries.
- Oil & Gas:National oil companies in the Middle East consolidate multi-year rotor replacement programs through framework agreements. Dry-run tolerant twin-screw units dominate upstream production where API 676 witness testing is mandatory.
- Chemical Processing:US Gulf Coast specialty chemical producers specify hermetically sealed magnetic drive couplings for toxic fluid paths under EPA emissions controls.
- Water Treatment:Progressive cavity pumps with F-Gas-compliant stator elastomers serve chilled sludge transfer in German municipal utilities.
- Food & Beverage:Sanitary single-screw configurations with 3A-certified surface finishes handle shear-sensitive dairy and confectionery products.
Oil & Gas absorbs the largest equipment value; chemical processing is climbing the fastest as magnetic drive adoption compresses maintenance intervals.
Application:
Volume concentration tracks fluid property extremes — multiphase flows, abrasive slurries, and temperature-sensitive polymers.
- Fluid Transfer:Continuous crude oil movement from wellhead to storage dominates installed base. Twin-screw dry-run tolerance eliminates seal failure risk in intermittent-flow gathering lines.
- Metering:Precision dosing of polymer additives and pharmaceutical intermediates demands pulse-free positive displacement. Progressive cavity designs with variable frequency drives achieve ±1% accuracy.
- Mixing:In-line blending of multi-viscosity feedstocks exploits screw pump shear characteristics without mechanical degradation.
- Heating:Jacketed housings maintain bitumen and heavy fuel oil flowability in Arctic and high-latitude installations.
Fluid transfer commands the dominant share of unit shipments; metering applications are gaining share fastest as process analytical technology integration expands.
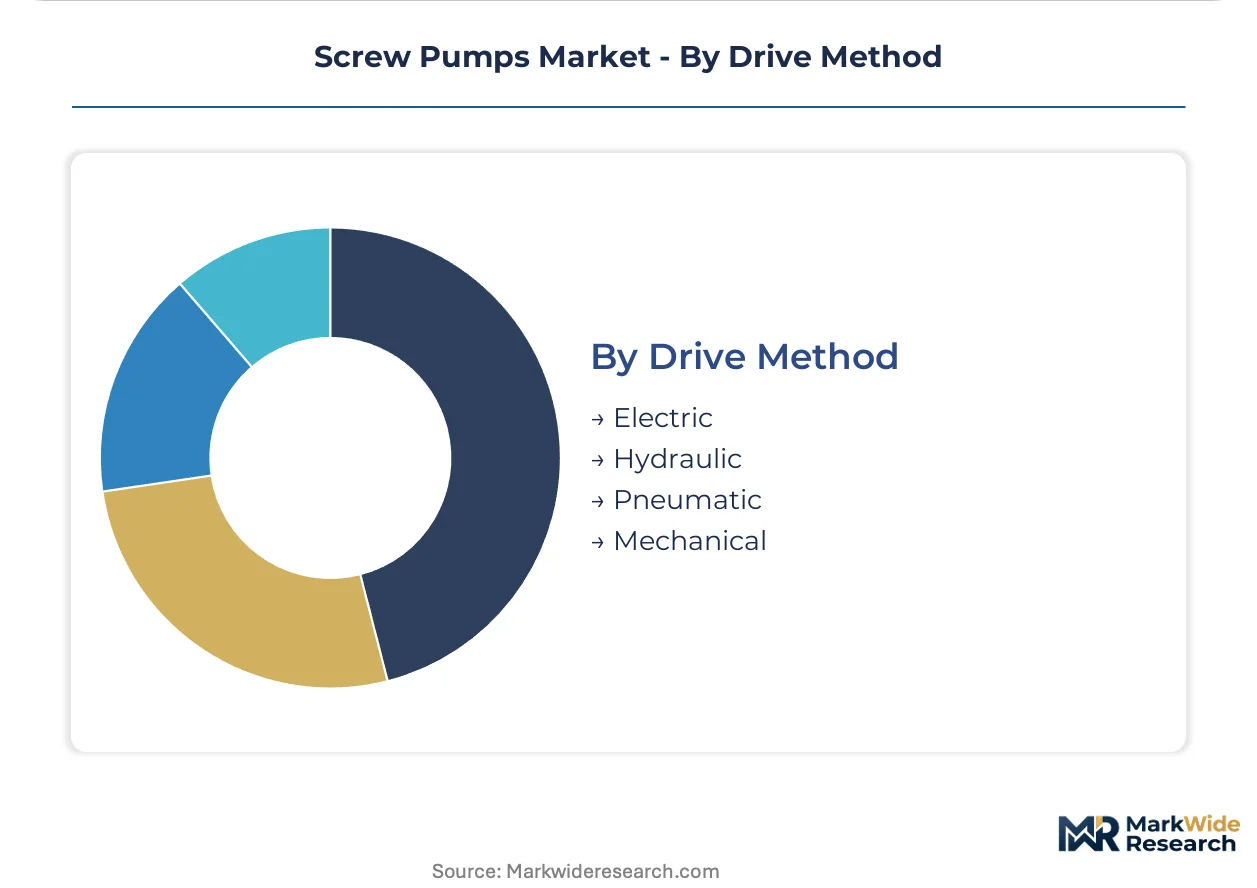
Drive Method:
Customer type splits between integrated energy majors specifying electric drive standardization and remote installations requiring non-grid power.
- Electric:Variable frequency drive compatibility enables precise flow control across viscosity fluctuations. German precision engineering clusters specify IE4 efficiency motors for modular skid packages.
- Hydraulic:Explosion-proof operation in offshore platforms and underground mining where electrical ignition risks are prohibited.
- Pneumatic:Portable dewatering and emergency backup systems in municipal wastewater facilities.
- Mechanical:Direct engine coupling for mobile drilling rig mud pumps and agricultural irrigation.
Electric drive accounts for the majority of new installations; hydraulic systems are expanding share fastest in offshore brownfield retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government infrastructure mandates and process industry clustering are redistributing screw pump procurement across concentrated manufacturing corridors. REACH compliance deadlines in Europe and wastewater expansion programs in Asia are accelerating replacement cycles for legacy elastomer configurations.
Germany
Ruhr industrial corridor refineries aggregate procurement for modular twin-screw skid packages. The EU F-Gas Regulation mandates refrigerant containment standards for cooling circuit pumps. Stuttgart precision engineering clusters supply certified rotor geometries to chemical processing facilities across North Rhine-Westphalia.
United States
US Gulf Coast specialty chemical producers specify hermetically sealed magnetic drive couplings for toxic fluid paths. EPA emissions controls enforce sealed system specifications in regulated environments. Houston-area fabrication yards integrate API 676 witness testing into modular package assembly for downstream deployment.
India
Central Public Health and Environmental Engineering Organisation mandates drive sealed sludge handling specifications for municipal utilities. BIS certification requirements structure equipment qualification for wastewater infrastructure tenders. Gujarat industrial corridors deploy progressive cavity configurations for textile effluent processing.
China
Dual carbon goals accelerate energy-efficient pump retrofits in petrochemical complexes. MIIT equipment standards tighten efficiency thresholds for rotating machinery in process industries. Yangtze River Delta chemical parks consolidate procurement through state-owned enterprise framework agreements.
Saudi Arabia
National oil company framework agreements aggregate multi-year rotor replacement programs. SFDA-equivalent process safety regulations govern hydrocarbon transfer equipment specification. Eastern Province upstream facilities specify dry-run tolerant twin-screw units for intermittent-flow gathering lines.
Screw Pumps Market Competitive Environment
Listed leaders compete with private specialists across certification capacity and metallurgical traceability systems. The vendor base concentrates around pre-qualified suppliers with captive test-rig infrastructure. Three archetypes dominate: integrated foundry-to-test conglomerates, progressing cavity geometry specialists, and hydraulic coverage generalists. M&A activity targets certified product line expansion, while strategic partnerships secure elastomer formulation supply.
Within the integrated capabilities tier, Flowserve Corporation and KSB SE & Co. KGaA occupy positions sustained by foundry-to-test vertical control. NETZSCH Pumpen & Systeme GmbH exemplifies the geometry specialization archetype, anchoring expertise in high-viscosity slurry configurations. These three represent the dominant competitive positioning vectors across API-compliant and sanitary application segments.
| Leading Market Players |
|---|
| Flowserve Corporation |
| KSB SE & Co. KGaA |
| NETZSCH Pumpen & Systeme GmbH |
| Alfa Laval AB |
| CIRCOR International Inc. |
| Sulzer Ltd. |
| ITT Inc. |
| SPX Flow Inc. |
| KRAL AG |
| Others |
Value Chain & Pricing Dynamics
API 676 qualification cycles simultaneously gate supplier access and stratify price tiers across the screw pumps landscape, compressing procurement options toward pre-certified vendors while expanding premium capture for integrated foundry-to-test operators.
Pricing Analysis
Certification level (API 676/FDA-grade) creates the primary spread between equipment tiers. Project-based pricing dominates large chemical installations, with witness testing and metallurgical traceability bundled into base quotes. Price differentiation rests on test-rig availability and stator elastomer formulation compliance with REACH and F-Gas mandates. Cost compression in standard twin-screw configurations is intensifying as centrifugal alternatives capture low-viscosity applications. National oil companies exhibit lowest price sensitivity due to framework agreement structures; municipal wastewater utilities in emerging markets show highest sensitivity.
Supply Chain Analysis
Germany anchors precision rotor manufacturing and API 676 test-rig infrastructure. China and India feed casting and machining capacity for mid-tier component supply. Raw material dependencies center on nickel-based superalloys for high-temperature rotors, specialized elastomer compounds for stator liners, and high-grade alloy steels for housings. Single-source vulnerability concentrates in European-certified foundry capacity for witness-tested units. Distribution runs through OEM-direct channels for large energy projects and specialized distributors for aftermarket rotor-stator replacement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin convergence and predictive maintenance service contracts signal a platform-economics inflection, repositioning screw pump vendors from equipment suppliers to uptime-guarantee platforms with recurring revenue streams.
For Market Incumbents: Compound certification throughput advantages by expanding captive test-rig capacity in the Ruhr corridor and Gulf Coast chemical clusters. Lock in multi-year rotor replacement frameworks with Middle Eastern national oil companies before magnetic drive standardization displaces conventional sealed units. Prioritize physics-based wear modeling R&D to anchor predictive maintenance contracts.
For New Entrants and Emerging Players: Lead with India wastewater infrastructure tenders where Central Public Health and Environmental Engineering Organisation mandates create sealed progressive cavity demand without entrenched incumbent relationships. Target progressive cavity geometries for high-viscosity slurries in textile effluent processing across Gujarat industrial corridors. Pursue joint qualification partnerships with German precision engineering clusters to bypass test-rig infrastructure bottlenecks.
For Investors and Strategic Acquirers: EU F-Gas Regulation phasedown schedules reshape the acquisition landscape toward stator elastomer formulation specialists with compliant polymer portfolios. Five-to-ten year viability favors integrated foundry-to-test conglomerates over pure-play geometry specialists exposed to input cost volatility. Watch for REACH chemical restriction expansion into per- and polyfluoroalkyl substance bans as the signal for accelerated replacement demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| API 676 Test-Rig Capacity Expansion | Captive witness testing infrastructure locks in qualification throughput for German chemical corridor procurement. |
| Magnetic Drive Coupling Integration | Hermetically sealed twin-screw configurations capture US Gulf Coast EPA-regulated toxic fluid transfer demand. |
| Stator Elastomer Reformulation Partnership | F-Gas-compliant polymer sourcing secures European cooling circuit pump specifications against phasedown deadlines. |
| Predictive Maintenance Platform Launch | Physics-based rotor wear modeling combined with vibration telemetry enables recurring service contract revenue. |
| India Wastewater Infrastructure Joint Venture | Sealed progressive cavity production localized for Central Public Health and Environmental Engineering Organisation mandate compliance. |
Study Parameters
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Primary fieldwork combined with secondary validation from API 676 certification databases, customs and trade flow records, SEC equipment supplier filings, and European chemical industry association reports. Bottom-up unit shipment estimates triangulated against top-down value projections across product type, end-use industry, and regional production hub segmentation.
Sensitivity analysis framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include pump architecture, drive method, application viscosity range, and qualification status tier. CAGRs derived from regression analysis of historical shipment patterns against process industry capital expenditure cycles and regulatory compliance deadlines. Forecast inputs incorporated nickel superalloy price volatility indices and test-rig capacity utilization rates.
Forecasts assume regulatory continuity in EU REACH, F-Gas Regulation, and EPA emissions control regimes; material policy shifts would require re-modeling. Specific risks include accelerated per- and polyfluoroalkyl substance restrictions, centrifugal pump technology advancement in low-viscosity applications, and Middle Eastern procurement consolidation beyond framework agreement structures. Recalibration cycles align with material shifts in alloy input costs and certification mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
Global Mobile Hydraulic Pump Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
End Suction Pump Market
Pumps and Control Devices
Hydraulic Dosing Pump Market
Pumps and Control Devices
Heavy Duty Dewatering Pumps Market
Pumps and Control Devices
Cooling Pump Market
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
Reverse Osmosis Pump Market
Pumps and Control Devices
Centrifugal Pumps Machines Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
Dispensing Pump Market
Pumps and Control Devices
Melt & Gear Pump Market
Pumps and Control Devices
Pump Tubes Market