
 Chopper Pumps Market | 2026-2036
Chopper Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Chopper Pumps Market Analysis
Municipal wastewater treatment is shifting toward higher-capacity solids handling as aging infrastructure faces stricter effluent mandates. Sulzer leverages its submersible chopper pump portfolio to anchor European utility contracts. Grundfos competes through integrated digital monitoring systems that reduce unplanned downtime in remote pumping stations. Vaughan Company specializes in severe-duty configurations for agricultural waste applications where fiber content destroys conventional impellers.
A chopper pump combines a centrifugal pumping mechanism with a rotating cutting assembly that macerates solids before they reach the impeller vane, typically operating at motor speeds between 1,750 and 3,600 RPM with hardened tool-steel or tungsten carbide cutters. The equipment serves industries where raw sewage, agricultural slurry, or process waste contains stringy, fibrous, or coarse solids that would clog standard non-clog pumps. Submersible choppers dominate municipal installations due to wet-well integration and reduced footprint requirements, while heavy-duty choppers command premium positioning in chemical processing where abrasive slurries accelerate wear. Food processing represents the fastest-growing application segment as plant operators replace batch handling with continuous-flow systems that demand uninterrupted pump operation.
The EPA enforces Clean Water Act standards that mandate secondary treatment upgrades, while the EU Urban Wastewater Treatment Directive requires nutrient removal in sensitive catchments. China's MEE implements increasingly stringent discharge permits for industrial zones along the Yangtze River basin. Stakeholders must monitor regulatory enforcement intensity in each jurisdiction to align product certification and localization strategies with compliance timelines.
Market Dynamics
Stringent effluent mandates from the EPA and EU Urban Wastewater Treatment Directive are forcing infrastructure owners to replace conventional non-clog pumps with chopper configurations capable of handling higher solids loading without downstream clogging.
Growth Catalysts
- Combined Sewer Overflow Mandates:Germany's wastewater utilities are expanding chopper pump deployment in wet-well stations to process storm-induced solids surges without system bypass.
- Industrial Cluster Expansion:Meat processing facilities in China's Yangtze River corridor require continuous-flow maceration systems to meet MEE discharge permit tightening.
- Abrasive Slurry Handling:Hardened tungsten carbide cutter assemblies now withstand chemical processing environments that previously demanded complete pump replacement every 18 months.
Market Restraints
- High-Alloy Input Volatility:Tool-steel and tungsten carbide prices fluctuate with mining output from concentrated suppliers, compressing margin predictability for manufacturers.
- Technical Limitation on Viscosity Range:Chopper pumps lose efficiency above 12% solids concentration by weight, creating a ceiling in thick slurry applications.
- Regulatory Friction from CE-EPA Divergence:Divergent certification requirements between European CE marking and US EPA environmental equipment standards force dual testing protocols.
Strategic Opportunities
- Underpenetrated Indian Municipal Sector:India's Smart Cities Mission wastewater component lacks chopper pump specification in most tender documents, creating first-mover positioning for technology educators.
- Precision Agriculture Convergence:Integration of chopper pumps with automated lagoon mixing systems allows dairy operations to extract biogas substrate while maintaining pump uptime.
- EU Green Deal Subsidies:Circular economy grants for nutrient recovery facilities favor equipment that enables continuous sludge processing without batch interruption.
Industry Challenges
- Welding Certification Bottlenecks:ASME Section IX qualified welders for hardened cutter fabrication face 14-week backlog at specialized shops, extending delivery timelines.
- Legacy SCADA Integration Complexity:Municipal utilities require chopper pumps to communicate with 1990s-era control architectures lacking modern digital protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chopper Pumps Market |
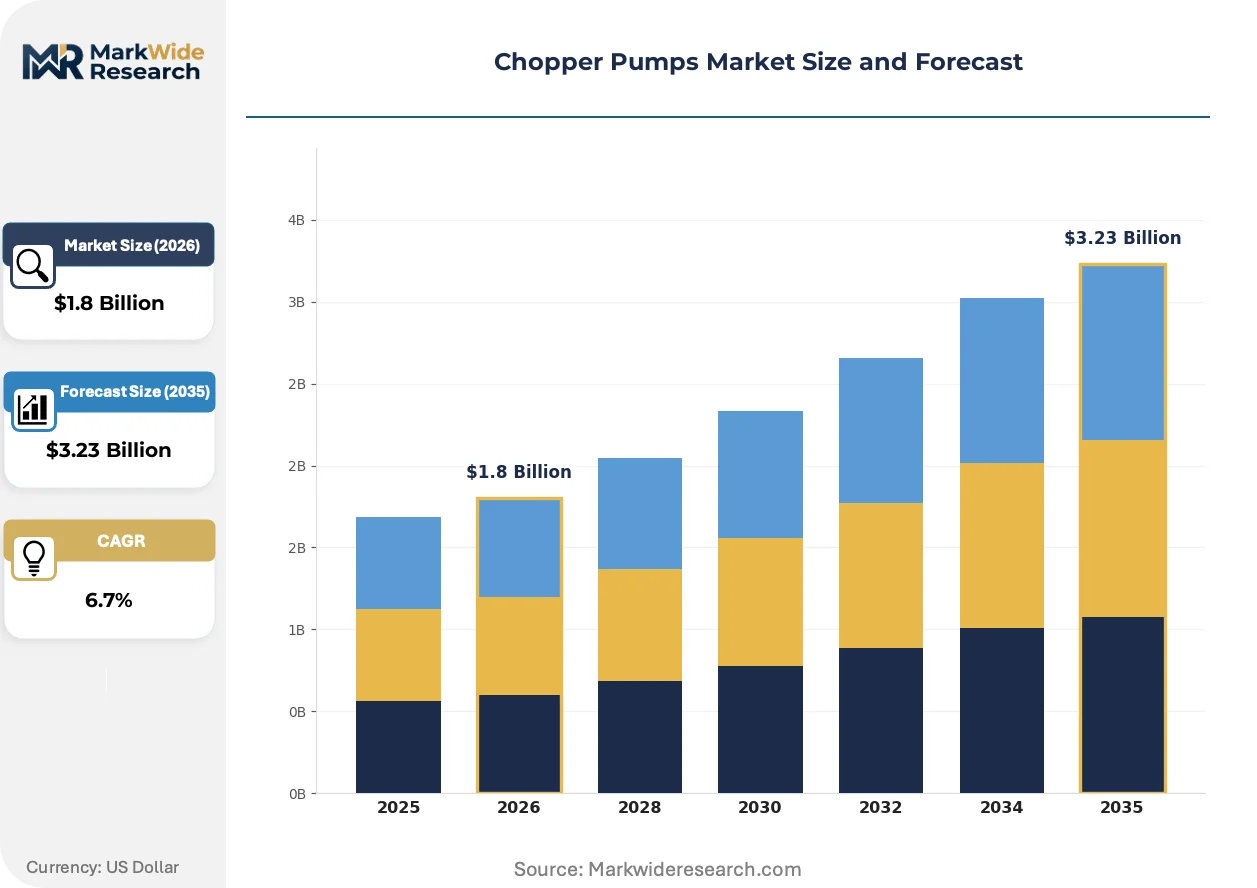
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Chopper, Above-ground Chopper, Portable Chopper, Heavy-duty Chopper Application: Agriculture, Wastewater Treatment, Food Processing, Chemical Processing End User: Municipal, Industrial, Residential, Commercial Technology: Hydraulic, Mechanical, Electrical, Pneumatic |
| Companies Covered | Sulzer, Grundfos, Vaughan Company, ITT Inc., KSB, Pentair, Flowserve Corporation, The Weir Group, Crane Pumps and Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chopper Pumps Market Emerging Trajectories
Digital condition monitoring and predictive maintenance protocols are rewriting equipment specification criteria, while material science advances extend cutter life in abrasive environments previously considered unsuitable for chopper technology.
Edge-mounted vibration sensors paired with cloud analytics platforms are decentralizing maintenance scheduling from calendar-based to condition-based intervals. Meat processing plants in Denmark and the Netherlands now specify pumps with integrated IoT modules that transmit bearing temperature and cutter torque data to centralized reliability dashboards. This shift compresses unplanned downtime from pump failure by enabling intervention before maceration efficiency degrades below process thresholds.
REACH restrictions on hexavalent chromium plating are accelerating adoption of physical vapor deposition coatings for cutter assemblies. European pump manufacturers must reformulate surface hardening processes or face market exclusion from EU procurement channels. The regulatory pressure is most acute in Germany, where municipal tender documents now explicitly exclude chrome-plated components from wastewater equipment bids.
Continuous-flow system design is displacing batch handling in food processing facilities that previously relied on intermittent pump operation with manual clearing cycles. Plant engineers in Brazil's poultry processing belt now specify chopper pumps for entire waste stream conveyance rather than pre-screening and bypass arrangements. This behavioral shift concentrates specification authority with process engineers rather than maintenance departments, altering vendor sales engagement protocols.
Chopper Pumps Market Segmentation
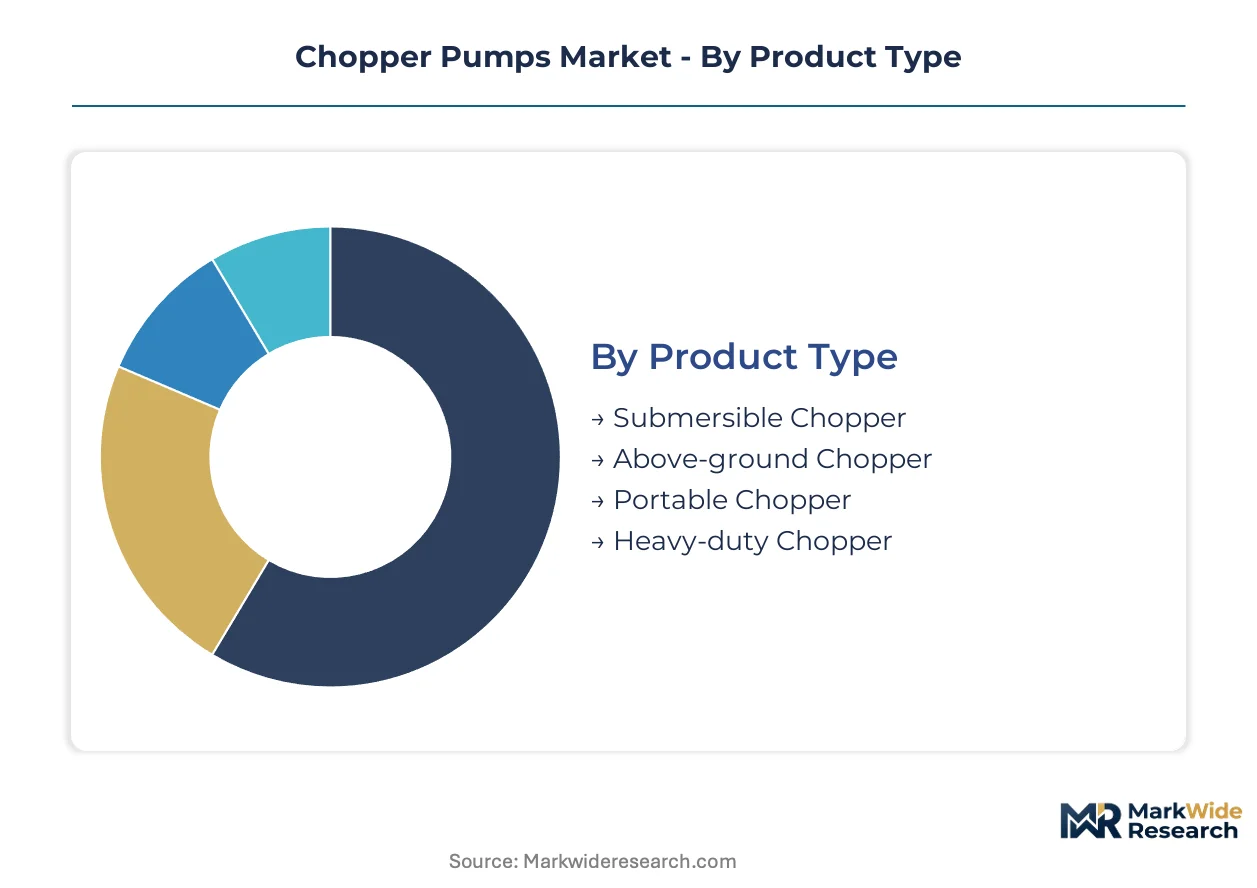
Chopper pump procurement decisions diverge sharply across installation environments, duty cycles, and regulatory exposure. Specification authority shifts between maintenance departments, process engineers, and municipal procurement offices depending on which segmentation dimension dominates the purchase.
Product Type:
Volume deployment favors wet-well integration, while premium positioning attaches to severe-duty configurations requiring hardened alloys.
- Submersible Chopper:Motor and cutter assembly operate fully submerged in wet wells, eliminating suction lift limitations and reducing station footprint. German municipal utilities specify these for combined sewer overflow stations where storm surges demand immediate solids maceration without bypass activation.
- Heavy-duty Chopper:Reinforced bearing housings and tungsten carbide cutter stacks withstand abrasive chemical slurries that destroy standard configurations. Chemical processing clusters along China's Yangtze River basin require these for continuous duty cycles exceeding 8,000 annual operating hours.
- Above-ground Chopper:Dry-pit installations with separate motor cooling suit facilities lacking wet-well infrastructure or requiring frequent maintenance access.
- Portable Chopper:Trailer-mounted or skid-based units serve emergency bypass operations and temporary construction dewatering where permanent installation is uneconomical.
Mature deployment sits with submersible configurations in established municipal networks. Newer deployment is concentrated in heavy-duty variants for industrial cluster expansion.
Application:
End-use concentration tracks regulatory enforcement intensity and solids composition rather than absolute wastewater volume.
- Wastewater Treatment:Secondary and tertiary treatment stages employ chopper pumps to protect downstream membranes and biological reactors from debris. EPA Clean Water Act enforcement drives replacement of conventional non-clog pumps at US municipal facilities facing consent decree deadlines.
- Food Processing:Continuous-flow rendering and slaughterhouse operations demand uninterrupted maceration of bone, fat, and packaging debris. Danish and Dutch poultry processors now specify integrated IoT monitoring to prevent downtime during peak production shifts.
- Agriculture:Dairy lagoon mixing and biogas substrate preparation require pumps handling high-fiber manure slurry with minimal operator intervention.
- Chemical Processing:Abrasive catalyst recovery and spent acid handling accelerate cutter wear, favoring pumps with replaceable hardfaced components.
Specification maturity concentrates in wastewater treatment with decades of operational data. Fastest expansion trajectory belongs to food processing as batch-to-continuous conversion accelerates.
End User:
Procurement sophistication varies from municipal tender compliance to industrial total-cost-of-ownership analysis.
- Municipal:Public utility procurement follows competitive bidding protocols with lifecycle cost evaluation criteria. EU Urban Wastewater Treatment Directive amendments tighten nutrient removal mandates, forcing pump upgrades at older treatment plants.
- Industrial:Meat processing, chemical manufacturing, and pharmaceutical operations prioritize uptime guarantees and predictive maintenance integration over initial capital expenditure.
- Commercial:Hotels, hospitals, and retail complexes specify compact submersible units for grease and solids handling in on-site pre-treatment systems.
- Residential:Septic system upgrades and small-scale biogas installations represent a fragmented, price-sensitive demand pool.
Established specification authority rests with municipal engineering departments. Emerging demand concentrates in industrial facilities integrating chopper pumps into automated process lines.
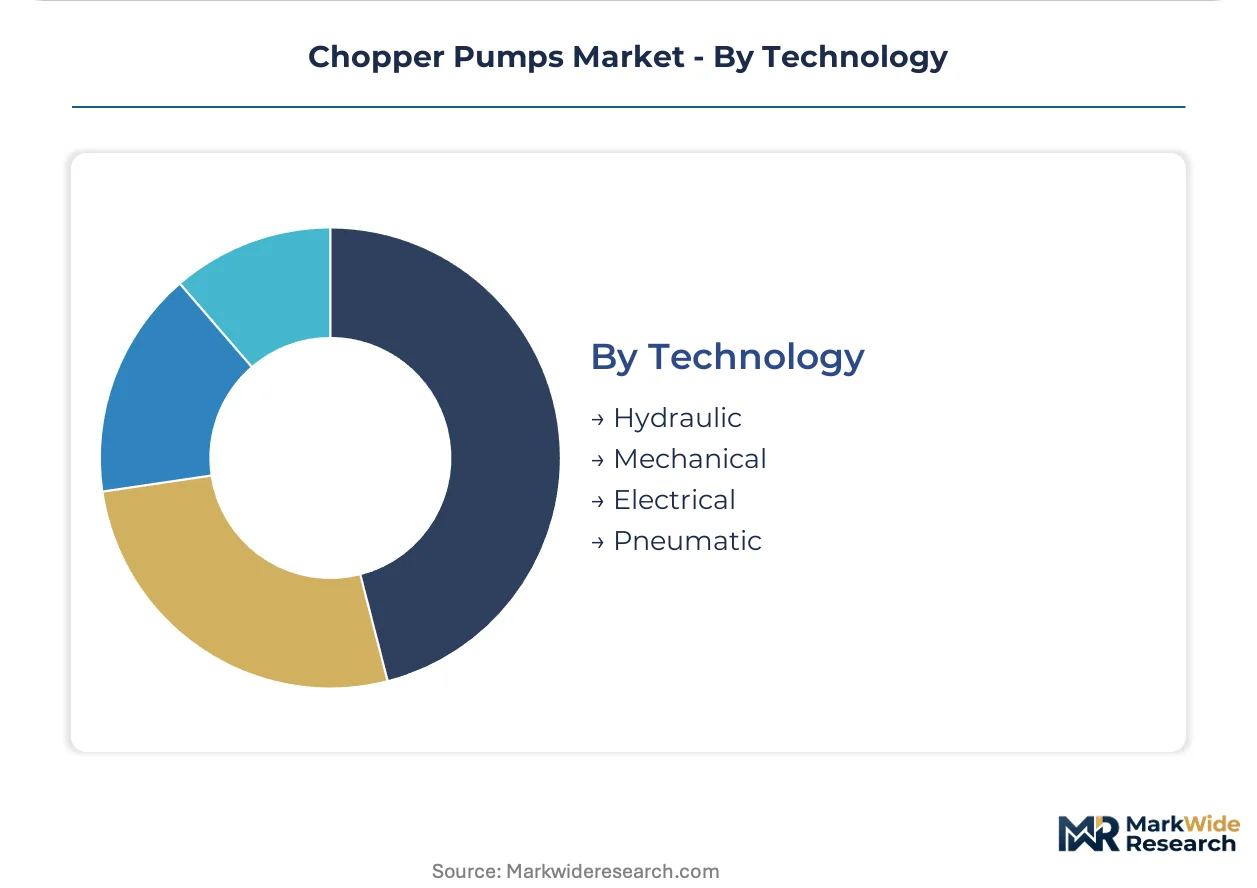
Technology:
Drive mechanism selection balances energy efficiency against maintenance accessibility and explosion-proof requirements.
- Electrical:Standard induction and premium efficiency motors dominate, with variable frequency drives enabling flow modulation without throttling losses. REACH restrictions on hexavalent chromium plating accelerate adoption of physical vapor deposition coatings for cutter assemblies in EU-specified equipment.
- Hydraulic:Explosion-proof hydraulic power units serve chemical processing zones where electrical spark ignition risks preclude standard motors.
- Mechanical:Direct drive configurations from combustion engines or power take-off shafts persist in remote agricultural settings lacking grid connectivity.
- Pneumatic:Compressed air-driven units occupy niche applications requiring intrinsic safety in volatile vapor environments.
Electrical drive systems anchor mature municipal and industrial installations. Hydraulic technology is gaining share fastest in hazardous-area chemical processing expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany, China, and the United States where precision machining capabilities and alloy supply chains support cutter fabrication. Consumption spreads across municipal utilities in established economies and industrial clusters in emerging manufacturing corridors.
Germany
Combined sewer overflow mandates from the EU Urban Wastewater Treatment Directive drive wet-well station upgrades in North Rhine-Westphalia. REACH restrictions on hexavalent chromium plating force surface hardening process reformulation for cutter assemblies. Municipal tender documents in Bavaria now explicitly exclude chrome-plated components from wastewater equipment bids.
United States
EPA Clean Water Act consent decrees compel secondary treatment upgrades at aging municipal facilities. The National Pollutant Discharge Elimination System tightens effluent standards for nutrient removal in sensitive catchments. Meat processing clusters in the Midwest specify continuous-flow maceration systems to replace batch handling with manual clearing cycles.
China
MEE discharge permit tightening along the Yangtze River basin accelerates industrial pump replacement timelines. Dual carbon goals pressure chemical manufacturers to improve process efficiency and reduce equipment failure rates. Heavy-duty chopper procurement concentrates in Jiangsu and Zhejiang provinces where abrasive slurry handling exceeds 8,000 annual operating hours.
India
Smart Cities Mission wastewater components lack chopper pump specification in most tender documents, creating specification gaps for technology educators. Central Pollution Control Board enforcement of sewage treatment plant standards intensifies in metropolitan regions. Dairy operations in Gujarat and Maharashtra explore automated lagoon mixing systems that integrate chopper pumps with biogas substrate extraction.
Denmark
Poultry processors specify integrated IoT monitoring modules to prevent downtime during peak production shifts. EU Green Deal circular economy grants for nutrient recovery facilities favor continuous sludge processing equipment. Rendering operations in the Jutland Peninsula convert from intermittent to uninterrupted maceration of bone, fat, and packaging debris.
Chopper Pumps Market Vendor Landscape
Top-tier vendors anchor municipal utility contracts through submersible portfolios, while mid-tier specialists occupy severe-duty niches requiring hardened alloy configurations. The vendor base stratifies across integrated pump manufacturers, component specialists, and regional fabricators serving price-sensitive procurement channels. Strategic archetypes include digital-integrated solution providers, severe-duty material specialists, and scale-driven standard product manufacturers. Dominant competitive moves encompass predictive maintenance platform development and tungsten carbide cutter stack differentiation.
Among Swiss-anchored industrial pump manufacturers, Sulzer occupies a position exemplifying submersible chopper specialization for European utility networks. Danish pump manufacturer Grundfos represents the digital-integrated archetype through cloud-connected monitoring systems that decentralize maintenance scheduling. Vaughan Company, a Washington-based fabricator, anchors the severe-duty segment for agricultural waste applications where fiber content destroys conventional impeller configurations.
| Leading Market Players |
|---|
| Sulzer |
| Grundfos |
| Vaughan Company |
| ITT Inc. |
| KSB |
| Pentair |
| Flowserve Corporation |
| The Weir Group |
| Crane Pumps and Systems |
| Others |
Supply Flow & Price Mechanics
Municipal tender mandates for tungsten carbide cutter assemblies in Germany and REACH-compliant surface coatings in the EU are forcing manufacturers to reformulate hardening processes and dual-source alloy suppliers, compressing margin predictability while elevating procurement costs for compliant configurations.
Pricing Analysis
Lead-time premiums of 30-45% attach to submersible chopper pumps deliverable within eight weeks, reflecting ASME Section IX welding certification bottlenecks that extend standard delivery to fourteen weeks. Three-tier pricing structure across severe-duty, standard submersible, and portable configurations tracks cutter alloy grade and IoT module integration. Cost compression in economy-tier portable units is intensifying because Chinese fabricators are absorbing margin erosion to maintain volume. Municipal utilities exhibit lowest price sensitivity due to lifecycle cost evaluation criteria, while residential septic contractors face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements for tungsten carbide and tool-steel cutter blanks now appear in 60% of municipal tender documents, reflecting supply security concerns after mining output disruptions. Production gravity centers on Germany, China, and the United States where precision machining capabilities support hardened alloy fabrication. Raw material dependencies include tungsten carbide powder from Chinese concentrate processors, tool-steel billets from Austrian and Swedish mills, and rare earth elements for high-efficiency motor magnets. Single-source vulnerability concentrates in specialized ASME-qualified welding shops facing fourteen-week backlogs. Distribution runs through authorized distributor networks for municipal accounts and direct OEM engagement for industrial process lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chopper pumps market operates as a cost-of-compliance story where EPA consent decrees and EU Urban Wastewater Treatment Directive amendments erect barrier-to-entry moats favoring certified incumbents with established welding protocols and REACH-compliant surface hardening capabilities.
For Market Incumbents: Deepen backward integration into tungsten carbide cutter blank production to insulate margin from mining output volatility and secure supply continuity for municipal contracts. Expand ASME Section IX welding capacity in North America to capture EPA-driven replacement demand. The threat of Chinese fabricators absorbing margin erosion in portable segments demands premium positioning through predictive maintenance platform differentiation. For New Entrants and Emerging Players: EPA consent decrees in the United States open a window for technology educators to penetrate municipal utilities lacking chopper pump specification expertise. Target India's Smart Cities Mission wastewater components where tender documents omit chopper specifications, creating first-mover positioning through demonstration projects in Gujarat and Maharashtra. The go-to-market angle centers on automated lagoon mixing system integration for dairy biogas operations. For Investors and Strategic Acquirers: The window for entry favors severe-duty material specialists with captive tungsten carbide supply and established REACH-compliant coating processes. Long-term viability hinges on regulatory enforcement intensity rather than cyclical infrastructure spending. The acquisition target archetype comprises regional fabricators with ASME welding certifications and municipal utility relationships. The signal to watch is MEE discharge permit tightening velocity along China's Yangtze River basin.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Cloud-connected vibration monitoring reduces unplanned downtime for Danish poultry processors. |
| REACH-Compliant Coating Process Investment | Physical vapor deposition capabilities secure eligibility for German municipal tender participation. |
| ASME Welding Capacity Expansion | Qualified fabrication shops capture EPA consent decree-driven replacement timelines. |
| Automated Lagoon Mixing System Integration | Biogas substrate extraction convergence opens dairy sector specification authority. |
| Heavy-Duty Cutter Stack Differentiation | Tungsten carbide configurations command premium positioning in Yangtze River chemical clusters. |
Methodological Framework
Multi-period observation of municipal tender specifications, EPA consent decree filings, and MEE discharge permit tightening velocities anchored the trend analysis, supplemented by interviews with plant engineers at meat processing facilities, maintenance directors at wastewater treatment utilities, procurement leads at chemical manufacturers, and aftermarket service heads at pump distributors. Secondary validation drew from EPA enforcement databases, EU Urban Wastewater Treatment Directive amendment tracking, China MEE regional discharge permit registries, and SEC filings of listed pump manufacturers. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment forecasts.
Input-output matrices modeled chopper pump demand across product type, application, end user, and technology dimensions over the projection horizon. CAGRs derived from regression analysis of historical deployment patterns against regulatory enforcement intensity indices. Industry-specific forecast inputs included combined sewer overflow station upgrade timelines in Germany, batch-to-continuous conversion rates in food processing, and abrasive slurry duty cycle accumulation in chemical processing clusters.
The model assumes a particular technology adoption path for IoT-integrated condition monitoring; alternative pathways for edge-computing predictive maintenance would alter the outlook for premium pricing realization. Deviation in EPA consent decree enforcement velocity or REACH restriction implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Vacuum Pump Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
Europe Submersible Pump Market
Pumps and Control Devices
Global Positive Displacement (PD) Pumps Market
Pumps and Control Devices
Dewatering Pumps Market
Pumps and Control Devices
Asia Pacific Side Channel Pumps Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Lubrication Pump Systems Market
Pumps and Control Devices
Middle East and Africa Positive Displacement Pumps Market
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Solar Pump Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Chemical Metering Pumps Market
Pumps and Control Devices
Asia Pacific Industrial Pumps Market
Pumps and Control Devices
Vertical Inline Pumps Market