
 Europe Submersible Pump Market | 2026-2036
Europe Submersible Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Submersible Pump Market Foresight
A widening capability gap between capital-intensive integrated manufacturers and assembly-focused regional suppliers is reorganizing competitive tiers across the Europe Submersible Pump Market. Grundfos leverages its in-house motor technology and digital monitoring platforms to command premium positioning in municipal water supply contracts. Wilo anchors its position through deep vertical integration in wet-pit systems, controlling casting operations and distribution networks across Central Europe. KSB competes aggressively on mining and oil extraction specifications, sustaining engineering-intensive customization capabilities that smaller rivals cannot replicate.
A submersible pump is a hermetically sealed centrifugal or positive-displacement unit designed to operate while fully submerged in the pumped fluid, typically constructed with stainless steel or cast iron housings, impeller stages rated for heads exceeding 200 meters, and motor windings protected by oil-filled or water-filled cooling jackets. Its primary industrial purpose is to lift, transfer, or pressurize liquids from boreholes, sumps, or reservoirs without suction lift limitations or priming requirements. Multi-stage configurations dominate high-head applications in mining operations and oil extraction, where margin pools concentrate around corrosion-resistant metallurgy and wear-part longevity. Wet-pit technology leads municipal water supply installations across Southern Europe, while solar-powered systems represent the fastest-growing technology segment in agricultural irrigation across water-stressed Spanish and Italian basins.
CE marking under the EU Machinery Directive, REACH compliance for elastomer and coating constituents, and the Ecodesign Directive's escalating efficiency tiers collectively shape product development timelines and market access conditions for manufacturers serving European buyers. ECHA's restricted substance lists are forcing reformulation of seal materials and motor coolants, adding compliance costs that favor scaled producers with dedicated regulatory teams. Stakeholders must monitor how the EU's F-Gas Regulation and pending carbon border adjustments reshape sourcing decisions for castings and permanent magnet materials.
Market Dynamics
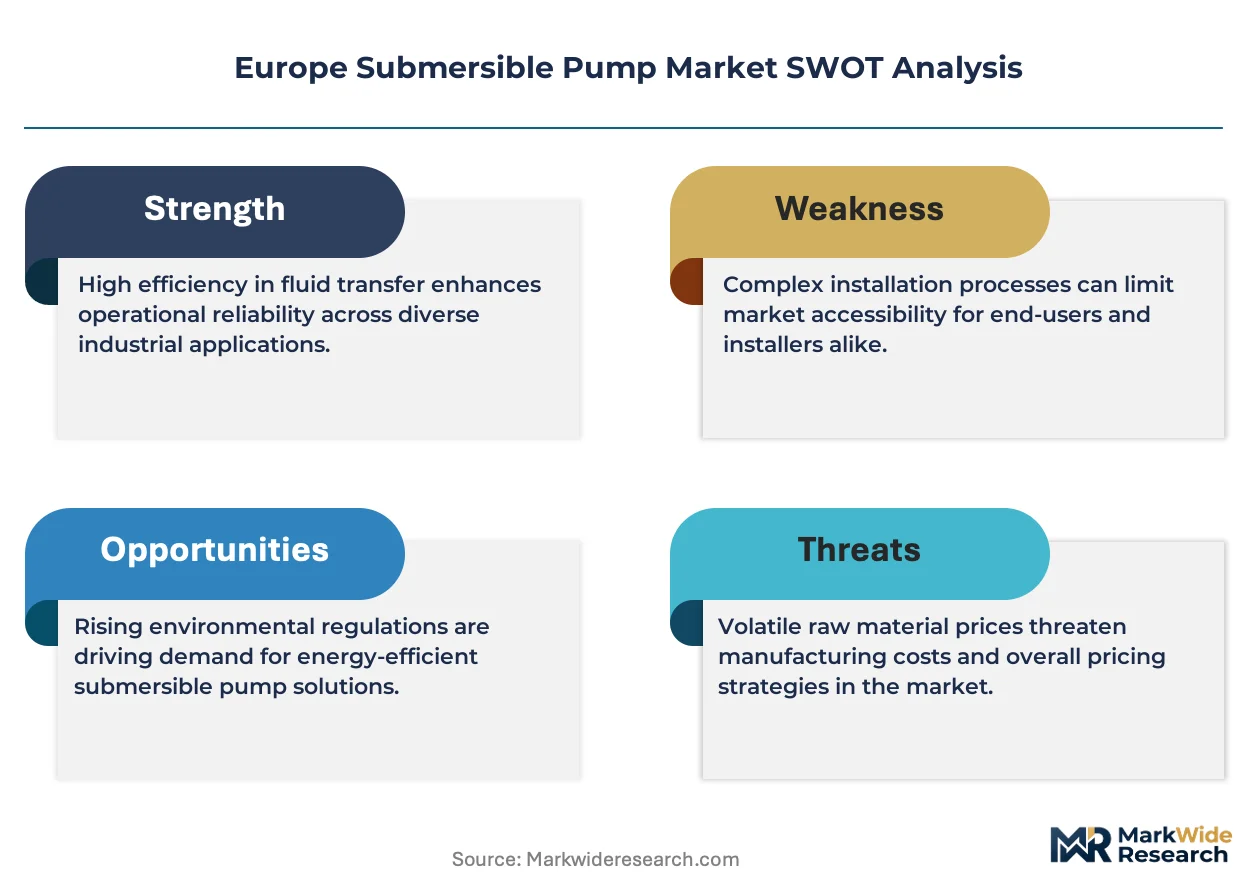
The EU Green Deal's escalating efficiency mandates are compressing replacement cycles and forcing water utilities toward higher-efficiency motor systems, restructuring procurement priorities across municipal and industrial buyer segments.
Growth Catalysts
- Wastewater Infrastructure Modernization:Germany, France, and Italy are accelerating procurement from water utilities as aging sewage networks face compliance deadlines under the Urban Wastewater Treatment Directive.
- REACH-Driven Material Reformulation:ECHA's restricted substance lists are compelling manufacturers to develop fluoropolymer-free seal compounds, creating first-mover advantages for suppliers with dedicated regulatory teams.
- Mining Dewatering Intensity:Deep extraction operations in Poland and Spain require multi-stage submersible configurations rated for heads exceeding 300 meters, sustaining demand for corrosion-resistant metallurgy.
Market Restraints
- Permanent Magnet Supply Concentration:Rare-earth processing dependencies create input cost volatility for high-efficiency motor systems, with sourcing risks concentrated in single-source supply corridors.
- CE Marking Compliance Burden:The EU Machinery Directive's conformity assessment timelines extend product development cycles by 8-14 months, favoring scaled producers with captive certification resources.
- Surface Pump Substitution:Above-ground centrifugal systems with flooded suction configurations are capturing low-head municipal applications where installation depth permits.
Strategic Opportunities
- Solar-Powered Agricultural Irrigation:Water-stressed basins in Spain and Italy are deploying photovoltaic-driven submersible arrays, opening off-grid revenue streams beyond traditional utility channels.
- Digital Twin Integration:Convergence of vibration sensors with cloud-based predictive analytics is enabling condition-monitoring service contracts that capture lifetime value from installed bases.
- F-Gas Regulation Tailwind:The EU's phasedown of hydrofluorocarbon-based cooling systems is accelerating demand for water-filled motor jackets in high-temperature wastewater applications.
Industry Challenges
- Electromechanical Skill Scarcity:Field service networks lack technicians trained in variable frequency drive commissioning and permanent magnet motor diagnostics, extending downtime for digital-enabled pump systems.
- Legacy Control Integration:SCADA retrofit requirements for municipal water authorities impose custom engineering costs that erode margin on standardized product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Submersible Pump Market |
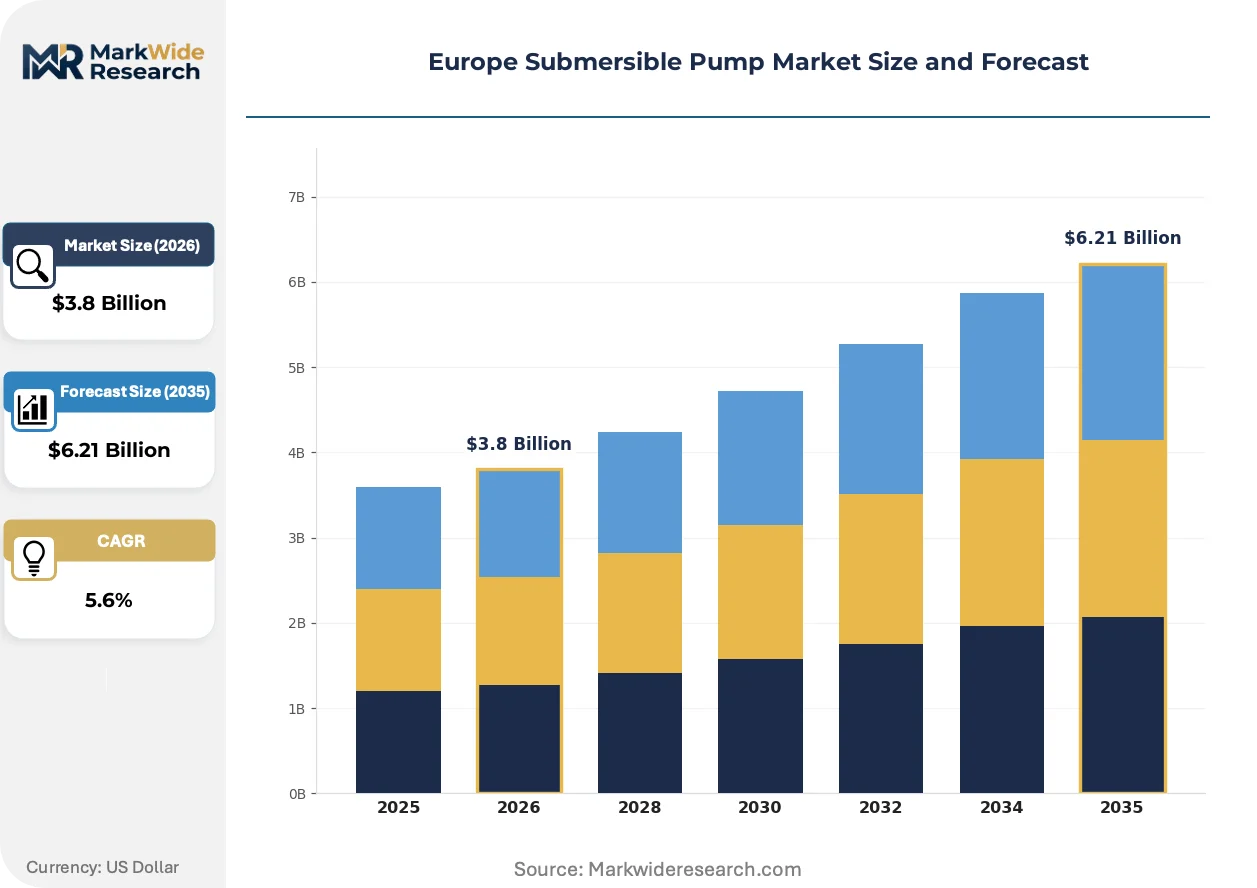
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Multistage, Axial Flow, Mixed Flow, Single Stage, Multi Stage Technology: Dry Pit, Wet Pit, Seal-Less, Motor-Driven, Solar-Powered Application: Mining Operations, Municipal Water Supply, Agricultural Irrigation, Oil Extraction, Fire Protection Systems End User: Water Utilities, Mining Firms, Agricultural Cooperatives, Oil & Gas Producers, Construction Companies |
| Companies Covered | Wilo, Ebara Pumps Europe, Grundfos, DAB Pumps, Caprari, KSB, Xylem, Pedrollo, Sulzer, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Submersible Pump Market Shifts & Advancements
Digital monitoring platforms and advanced materials are restructuring how pump performance is validated, financed, and maintained across European water infrastructure.
Permanent magnet synchronous motors are decomposing the traditional separation between pump and motor procurement. Water utilities in the Netherlands and Denmark are specifying integrated permanent magnet packages that eliminate belt drives and reduce energy consumption by 15-25 percent. This convergence is decomposing the historical dominance of independent motor suppliers in municipal tender processes.
The Ecodesign Directive's 2025 efficiency tiers are mandating minimum performance coefficients for submersible motors rated above 0.75 kW. Manufacturers must redesign stator laminations and rotor geometries to meet IE4-equivalent standards, adding engineering validation costs that disadvantage assembly-focused regional competitors. Mining and oil extraction specifications face the steepest compliance burden due to explosion-proof certification requirements under ATEX directives.
Performance-based service contracts are displacing traditional capital expenditure procurement in Danish and Swedish district heating networks. Operators now contract for guaranteed uptime and energy efficiency outcomes rather than purchasing equipment outright. This shift is most visible in Copenhagen's municipal water authority, where 15-year service agreements now dominate new installations.
Europe Submersible Pump Market Segmentation
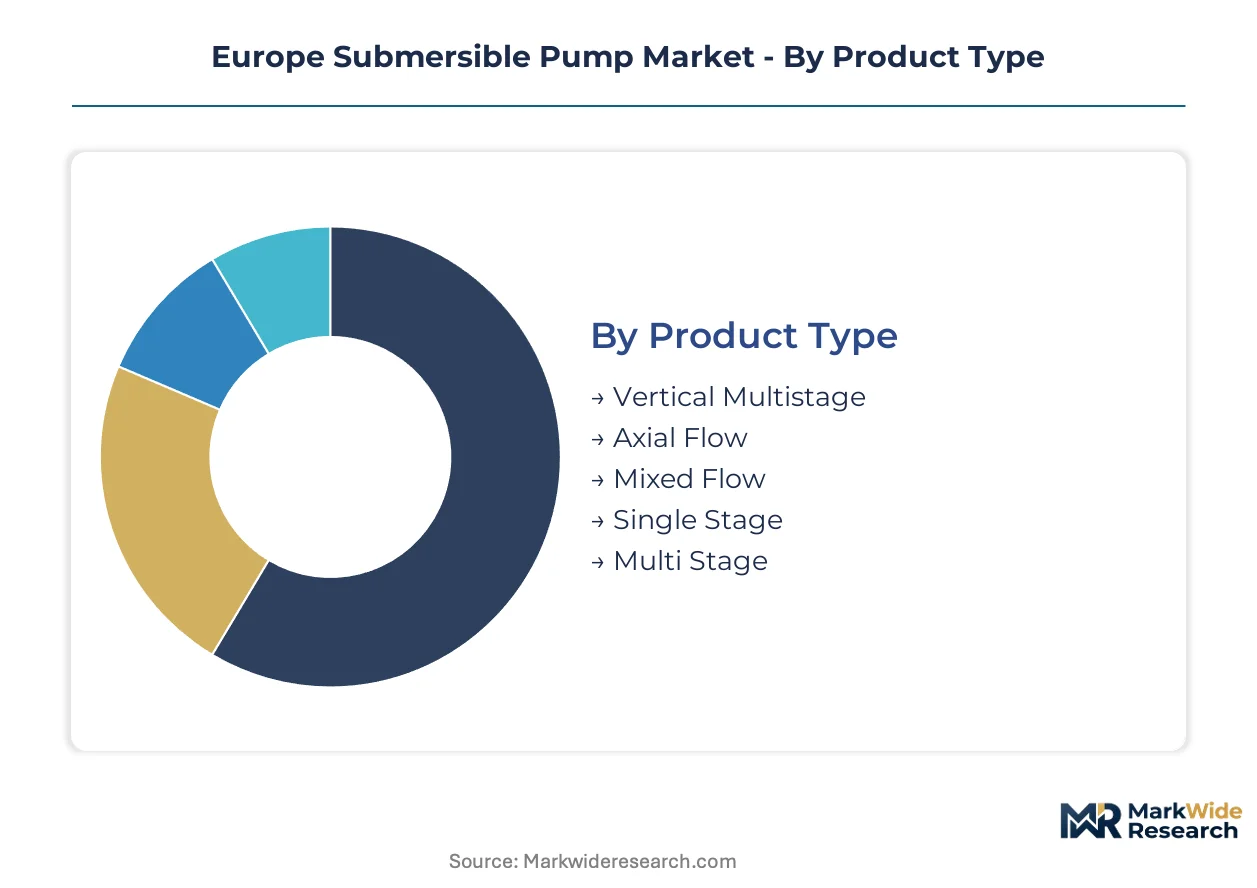
Submersible pump procurement channels diverge sharply by segment, with water utilities favoring wet-pit systems through framework agreements while mining firms source multi-stage configurations via direct engineering contracts. Understanding these channel-segment pairings clarifies where pricing power concentrates and which specifications drive tender complexity.
Product Type:
Channel distribution varies dramatically across pump architectures, with vertical multistage units flowing through municipal procurement frameworks while single-stage products dominate agricultural supply cooperatives.
- Vertical Multistage:Stacked impeller configurations deliver heads exceeding 300 meters through compact borehole installations. German and Polish mining operations specify these for deep dewatering, where corrosion-resistant stainless steel housings command premium positioning against cast iron alternatives.
- Multi Stage:Segmented rotor assemblies enable pressure staging across oil extraction and high-head municipal applications. Italian water utilities in the Po Valley deploy these for groundwater extraction where aquifer depths exceed 150 meters.
- Axial Flow:Propeller-driven designs move large volumes at low heads through flood control and drainage channels.
- Mixed Flow:Hybrid impeller geometry balances pressure and flow rate for industrial cooling and raw water intake.
- Single Stage:Single-impeller simplicity dominates shallow agricultural applications across Spanish irrigation districts.
Vertical multistage dominates installed base. Multi stage is where expansion concentrates.
Technology:
Cost tiers separate these technologies, with wet-pit systems anchoring premium municipal contracts and solar-powered configurations emerging as the economy tier for off-grid agricultural deployment.
- Wet Pit:Submerged motor and pump assembly eliminates suction lift constraints through direct fluid immersion. Southern European water utilities in Spain and Portugal favor these for sewage lift stations where dry-pit construction costs prove prohibitive.
- Solar-Powered:Photovoltaic arrays drive DC motors for borehole irrigation without grid connection. Sicilian and Andalusian agricultural cooperatives are deploying these fastest where diesel transport costs erode conventional pump economics.
- Dry Pit:Above-ground motor accessibility simplifies maintenance for industrial process applications.
- Seal-Less:Magnetic coupling eliminates mechanical seals in chemical transfer and contaminated fluid handling.
- Motor-Driven:Standard AC induction configurations serve general-purpose dewatering across construction sites.
Wet pit commands municipal procurement. Solar-powered is climbing the fastest.
Application:
Customer type alignment determines margin structure, with mining operations tolerating engineering-intensive customization while fire protection systems compete on price through standardized catalog specifications.
- Mining Operations:Multi-stage dewatering systems rated for abrasive slurry and high heads sustain replacement demand. Polish hard-coal basins and Spanish potash extraction specify explosion-proof ATEX configurations that extend development cycles and protect incumbent suppliers.
- Municipal Water Supply:Drinking water and wastewater networks require CE-marked efficiency compliance under Ecodesign Directive tiers. French and Italian utilities are consolidating procurement through multi-year framework agreements that favor scaled manufacturers with captive certification resources.
- Agricultural Irrigation:Borehole and surface water extraction for crop irrigation, concentrated in water-stressed Mediterranean basins.
- Oil Extraction:Artificial lift and drainage for hydrocarbon recovery, governed by offshore and onshore safety protocols.
- Fire Protection Systems:Pressure maintenance and emergency water supply for commercial and industrial facilities.
Municipal water supply dominates installed base. Mining operations is where expansion concentrates.
End User:
Procurement sophistication varies across buyer categories, with water utilities imposing extended efficiency validation and oil producers demanding asset lifecycle guarantees that smaller suppliers cannot underwrite.
- Water Utilities:Municipal and regional authorities managing drinking water, sewage, and stormwater infrastructure. Dutch and Danish operators are pioneering performance-based service contracts that shift capital expenditure to operational expenditure, locking in suppliers for 15-year terms.
- Mining Firms:Underground and open-pit extraction operations requiring continuous dewatering. German and Polish coal operators specify multi-stage corrosion-resistant systems with wear-part availability contracts that prioritize uptime over first cost.
- Agricultural Cooperatives:Collective purchasing entities for irrigation infrastructure across Mediterranean growing regions.
- Oil & Gas Producers:Offshore platform and onshore field operators with stringent safety and reliability requirements.
- Construction Companies:Temporary dewatering for foundation and tunneling projects with short procurement cycles.
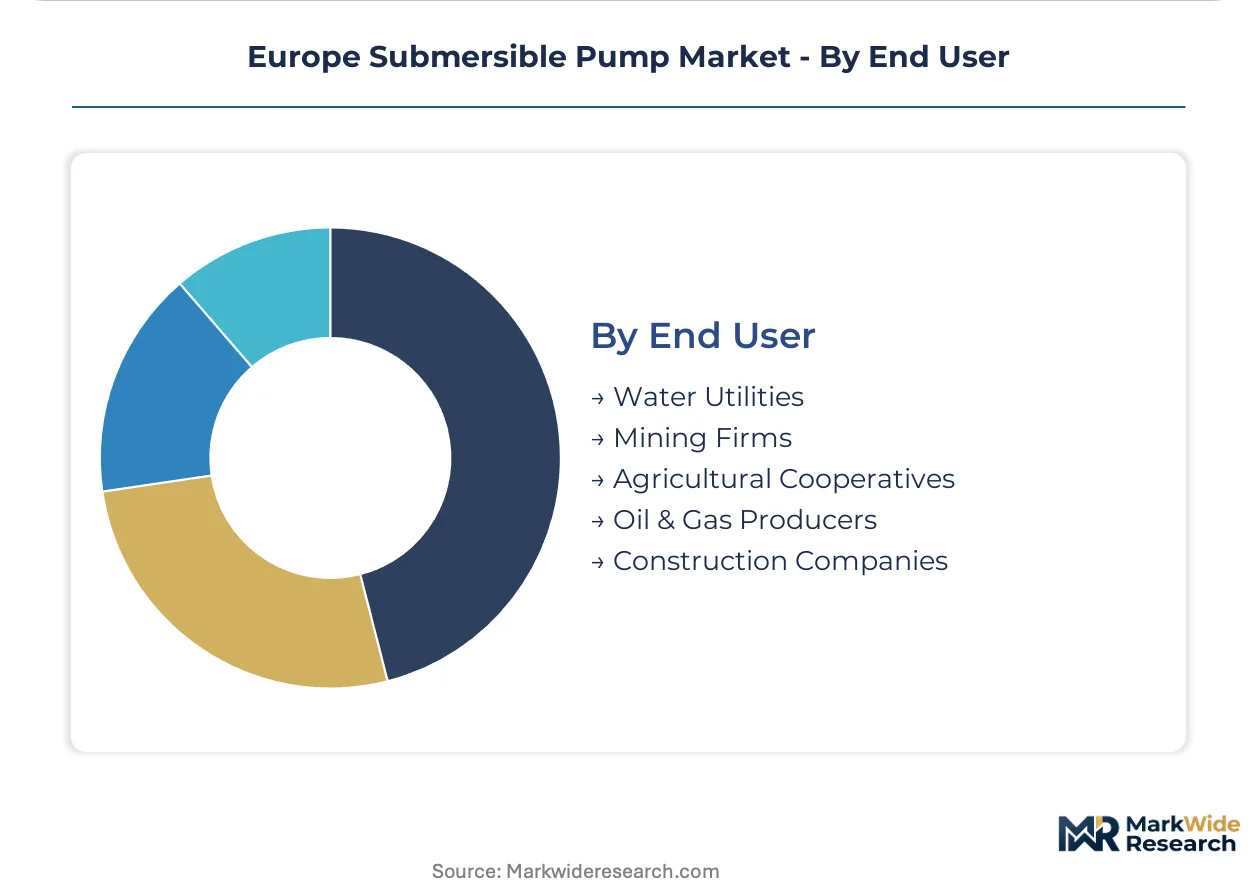
Water utilities dominate installed base. Mining firms is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics within the Europe Submersible Pump Market reveal German and Italian manufacturers shipping corrosion-resistant multi-stage units to Polish mining basins and Spanish agricultural cooperatives, while Danish and Dutch utilities import specialized wet-pit configurations for municipal wastewater networks.
Germany
The Ruhr industrial corridor and Bavarian manufacturing belt sustain demand for high-head dewatering systems in coal operations and precision-engineered municipal pumps. The EU Ecodesign Directive's 2025 efficiency tiers force rapid replacement of legacy motor systems across North Rhine-Westphalia's water utilities. Frankfurt's municipal water authority consolidates procurement through multi-year framework agreements favoring scaled suppliers with captive certification resources.
France
Agricultural irrigation in the Poitou-Charentes basin and offshore oil extraction in the Mediterranean drive divergent specification requirements. REACH compliance deadlines under ECHA's restricted substance lists compel seal material reformulation for manufacturers serving Lyon's industrial water networks. The Paris metropolitan region deploys wet-pit sewage lift stations where dry-pit construction costs prove prohibitive.
Italy
Water-stressed agricultural basins in Sicily and Puglia accelerate solar-powered submersible deployment for borehole irrigation without grid connection. The EU Green Deal's efficiency mandates compress replacement cycles for aging pumps across Emilia-Romagna's municipal networks. Milan's industrial corridor concentrates demand for corrosion-resistant metallurgy in high-abrasion mining applications.
Spain
Andalusian olive cooperatives and Murcian vegetable growers pioneer photovoltaic-driven pump arrays where diesel transport costs erode conventional economics. The F-Gas Regulation's phasedown accelerates demand for water-filled motor jackets in high-temperature wastewater applications across Catalonia. Barcelona's metropolitan water authority pilots performance-based service contracts shifting capital expenditure to operational expenditure.
Poland
Deep hard-coal extraction in the Silesian Basin requires multi-stage configurations rated for heads exceeding 300 meters with explosion-proof ATEX certification. Urban wastewater treatment upgrades under the Urban Wastewater Treatment Directive drive procurement from Kraków and Warsaw utilities. The country's dependence on imported high-efficiency motor systems creates input cost volatility for mine operators.
Europe Submersible Pump Market Competitive Landscape
Concentration sits with integrated European manufacturers possessing in-house motor technology and captive regulatory compliance teams. The vendor base stratifies across three tiers: scaled multinationals with digital monitoring platforms, mid-sized specialists in wet-pit or mining configurations, and assembly-focused regional suppliers dependent on imported components. Dominant competitive moves include backward integration into permanent magnet motor production and strategic partnerships for solar-powered system distribution.
Among Denmark-based integrated pump manufacturers, Grundfos occupies a position exemplifying premium-tier municipal water supply positioning through in-house motor technology. German manufacturers Wilo and KSB anchor the engineering-intensive customization segment for mining and industrial applications. Italian specialists DAB Pumps and Pedrollo represent mid-tier regional fabricators competing on agricultural irrigation specifications across Mediterranean basins.
| Leading Market Players |
|---|
| Wilo |
| Ebara Pumps Europe |
| Grundfos |
| DAB Pumps |
| Caprari |
| KSB |
| Xylem |
| Pedrollo |
| Sulzer |
| Others |
Supply & Pricing Matrix
CE marking under the EU Machinery Directive gates both supplier qualification and price differentiation simultaneously, extending product development cycles by 8-14 months while compressing margins for assembly-focused regional competitors lacking captive certification resources.
Pricing Analysis
Configured-to-order pricing for mining and oil extraction specifications commands a 40-60% premium over standard catalog offerings for municipal water supply. Three-tier pricing structure across premium, standard, and economy levels separates explosion-proof ATEX-certified systems from general-purpose wet-pit configurations and basic agricultural single-stage units. Cost compression in the economy tier is intensifying because Spanish and Italian agricultural cooperatives are consolidating procurement through supply cooperatives. Water utilities prove least price-sensitive due to 15-year service contract structures, while construction companies exhibit highest sensitivity with project-based spot purchasing.
Supply Chain Analysis
Rare-earth processing corridors through China and Myanmar create chokepoint vulnerability for permanent magnet synchronous motors, with sourcing risks concentrated in single-source supply corridors. European manufacturers draw from German cast iron foundries, Italian stainless steel processors, and Chinese rare-earth refineries for critical inputs. Single-source vulnerability in neodymium magnet supply creates input cost volatility that feeds directly into motor system pricing. Distribution runs through municipal procurement frameworks for water utilities, direct engineering contracts for mining operations, and agricultural supply cooperatives for irrigation applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Submersible Pump Market represents an early-cycle expansion story, with solar-powered agricultural irrigation penetration in water-stressed Mediterranean basins just beginning to displace diesel-driven legacy systems.
For Market Incumbents: Fortify captive certification resources to defend municipal framework agreement positioning against mid-tier challengers. Deepen backward integration into permanent magnet motor production to offset rare-earth supply volatility. Prioritize digital twin service contract capabilities to lock in 15-year operational expenditure structures with Dutch and Danish water utilities.
For New Entrants and Emerging Players: Anchor in Sicilian and Andalusian agricultural cooperatives where photovoltaic-driven borehole systems face minimal incumbent saturation. Target solar-powered irrigation specifications where diesel transport cost economics favor off-grid deployment. Pursue distribution partnerships with regional agricultural supply cooperatives rather than direct municipal tender competition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across permanent magnet motor manufacturing as IE4-equivalent efficiency tiers mandate redesigned stator laminations and rotor geometries. Long-term viability favors scaled manufacturers with integrated motor technology and dedicated regulatory compliance teams. Monitor ECHA restricted substance list expansions as the inflection signal for material reformulation cost advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Production | Mitigates rare-earth supply volatility for German and Danish motor manufacturers serving mining specifications. |
| Digital Twin Platform Development | Enables condition-monitoring service contracts with Copenhagen and Amsterdam municipal water authorities. |
| Solar-Powered System Distribution Partnership | Unlocks agricultural cooperative channels across water-stressed Spanish and Italian irrigation basins. |
| Fluoropolymer-Free Seal Material Reformulation | Captures first-mover REACH compliance advantage as ECHA restricts perfluorinated compound usage. |
| Multi-Year Municipal Framework Agreement | Locks in 15-year operational expenditure structures with French and Italian water utilities consolidating procurement. |
Research Methodology
Cross-validation between primary interviews with municipal procurement officers, mining maintenance directors, agricultural cooperative managers, and aftermarket service heads anchors the qualitative findings against secondary validation from EU Ecodesign Directive filings, ECHA restricted substance databases, customs trade data on pump motor imports, and SEC disclosures from listed pump manufacturers. Bottom-up triangulation across installation base surveys and top-down reconciliation against utility capital expenditure frameworks ensures dimensional consistency.
Sensitivity analysis across efficiency tier compliance costs, rare-earth price volatility bands, and solar module cost curves informs the analytical framework over the projection horizon. Segmentation dimensions modeled include product architecture, motor technology tier, application intensity, end-user procurement sophistication, and regional regulatory cluster. CAGRs derive from installed base replacement cycle analysis and penetration rate assumptions for solar-powered agricultural systems, with forecast inputs incorporating EU Green Deal mandate timelines and Urban Wastewater Treatment Directive compliance deadlines.
Material uncertainties — rare-earth supply disruptions, ECHA substance list expansions, and municipal budget cycle compressions — sit outside the modeled envelope. Forecasts reflect documented assumptions on technology substitution rates and regulatory enforcement intensity. Practitioners should keep alternative scenarios live as permanent magnet supply corridor stability and agricultural diesel price spreads evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Dosing Pumps Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Middle East and Africa Positive Displacement Pumps Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
Centrifugal Water Pump Market
Pumps and Control Devices
Screw Pumps Market
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
Canned Motor Pumps Market
Pumps and Control Devices
Steam Jet Ejector Market
Pumps and Control Devices
Latin America Hydraulic Filtration Market
Pumps and Control Devices
Heavy Duty Dewatering Pumps Market
Pumps and Control Devices
Oil and Gas Pumps Market
Pumps and Control Devices
Asia-Pacific Peristaltic Pumps Market
Pumps and Control Devices
Double Diaphragm Pump Market