
 India Solar Water Pump Systems Market | 2026-2036
India Solar Water Pump Systems Market Size, Share, and Industry Trends Forecast 2026-2036
India Solar Water Pump Systems Market Foresight
Gujarat's manufacturing corridor is narrowing the cost gap between imported and domestically assembled solar pump controllers. Shakti Pumps (India) Ltd leverages its vertically integrated foundry operations in Pithampur to dominate the submersible segment. Waaree Energies Ltd anchors the photovoltaic supply side through its Surat module fab, while KSB Limited competes on German-engineered surface pump designs adapted for Indian voltage conditions.
Solar water pump systems integrate photovoltaic arrays with DC or AC motor-driven pumping mechanisms to extract groundwater or surface water without grid dependency, typically operating at 24V to 400V with flow rates from 2,000 to 50,000 liters per day depending on head pressure and solar irradiance. The agricultural end-user segment commands the dominant share of installed base, driven by diesel substitution economics and canal-fed irrigation gaps. Submersible pumps capture the deepest margin pools due to borewell proliferation in depleting water table zones, while programmable controllers represent the fastest-growing technology layer as farmers demand remote monitoring and automated dry-run protection.
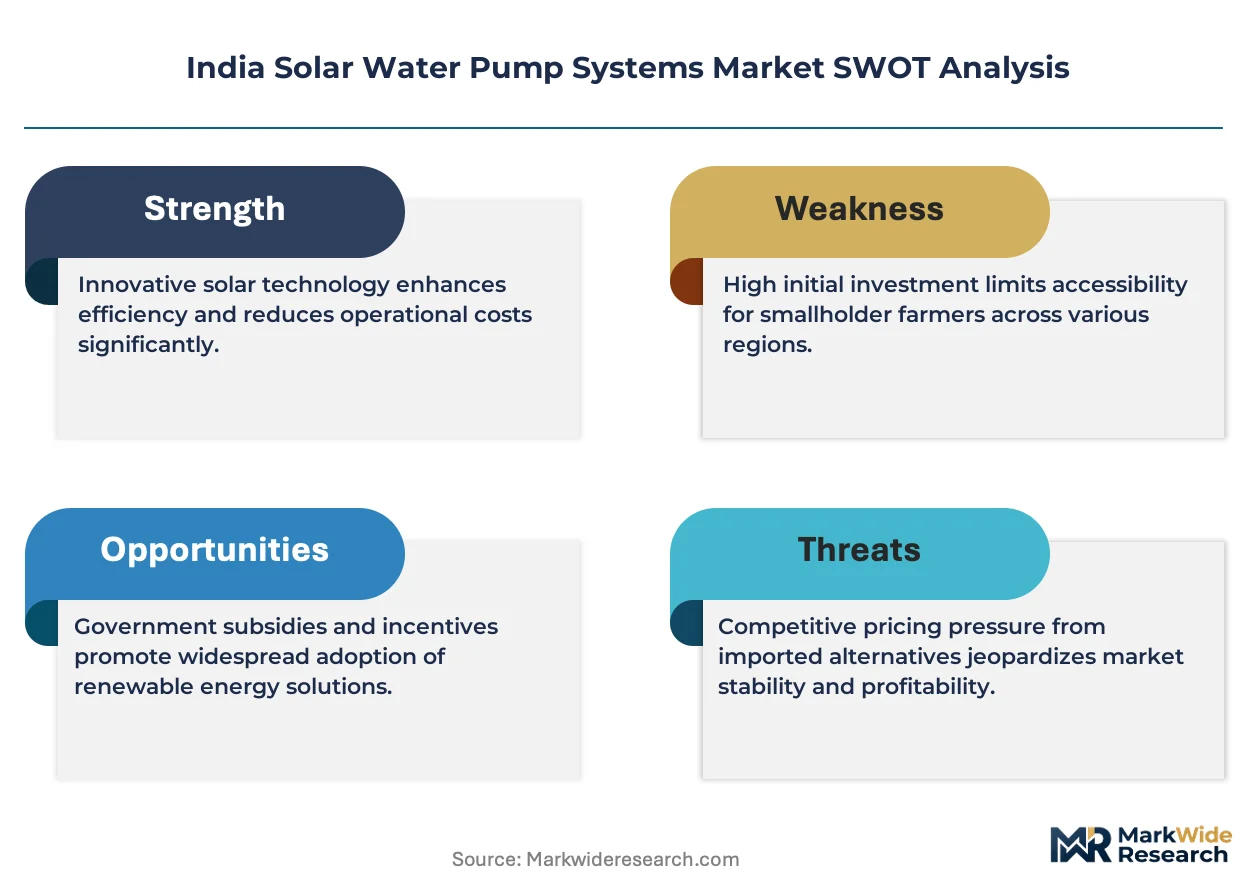
The Ministry of New and Renewable Energy's PM-KUSUM Component B mandates BIS-certified pump sets and restricts subsidy eligibility to domestically manufactured photovoltaic modules, tightening import competition. State nodal agencies in Rajasthan and Tamil Nadu layer additional efficiency requirements that favor vendors with localized service networks. Stakeholders must monitor state-level implementation velocity and component localization rules to calibrate manufacturing footprints against subsidy disbursement timelines.
Market Dynamics
PM-KUSUM subsidy disbursement velocity is compressing vendor cash cycles and forcing assembly localization decisions faster than module cost curves alone would dictate.
Growth Catalysts
- PM-KUSUM Component B:Central subsidy coverage of 30-50% capital cost for grid-connected pumps is unlocking demand in Maharashtra's sugarcane belt where diesel irrigation costs have tripled since 2019.
- Falling polysilicon feedstock prices:Domestic module assembly costs at Mundra and Surat are narrowing the landed cost gap with Southeast Asian imports, accelerating BIS-certified adoption.
- Borewell proliferation:Depleting water tables across Rajasthan's Marwar region are forcing farmers below 80-meter depths where submersible DC pumps outperform surface alternatives.
Market Restraints
- Controller chip import dependence:IGBT and MOSFET supply remains concentrated in Malaysian and Vietnamese packaging facilities, exposing vendors to 12-16 week lead time volatility.
- BIS certification timelines:Pump set testing at NABL-accredited labs in Chennai and Pune creates 4-6 month approval queues that delay subsidy eligibility and working capital recovery.
- Diesel generator substitution economics:Second-hand 5-7.5 kVA gensets from Gujarat's industrial resale market undercut solar pump lifecycle costs for farmers with shallow wells under 40 meters.
Strategic Opportunities
- Haryana's canal-fed districts:Surface pump deployment in Hisar and Sirsa remains underpenetrated relative to borewell zones, offering volume expansion without deep-drilling service infrastructure.
- IoT-enabled predictive maintenance:Integration of GSM-based flow sensors with existing controller architectures creates recurring revenue streams from smallholders previously lost to unorganized repair channels.
- Tamil Nadu's horticulture push:State horticulture department mandates for micro-irrigation compatibility are opening specification windows for variable-frequency drive pumps in Coimbatore's banana belt.
Industry Challenges
- Field technician scarcity:Installation and commissioning of submersible arrays requires electricians certified for 400V DC handling, a credential gap acute in Madhya Pradesh's tribal districts.
- Groundwater variability:Unpredictable aquifer yields in hard-rock Deccan plateau zones force pump oversizing and premature dry-run failures, eroding warranty reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Solar Water Pump Systems Market |
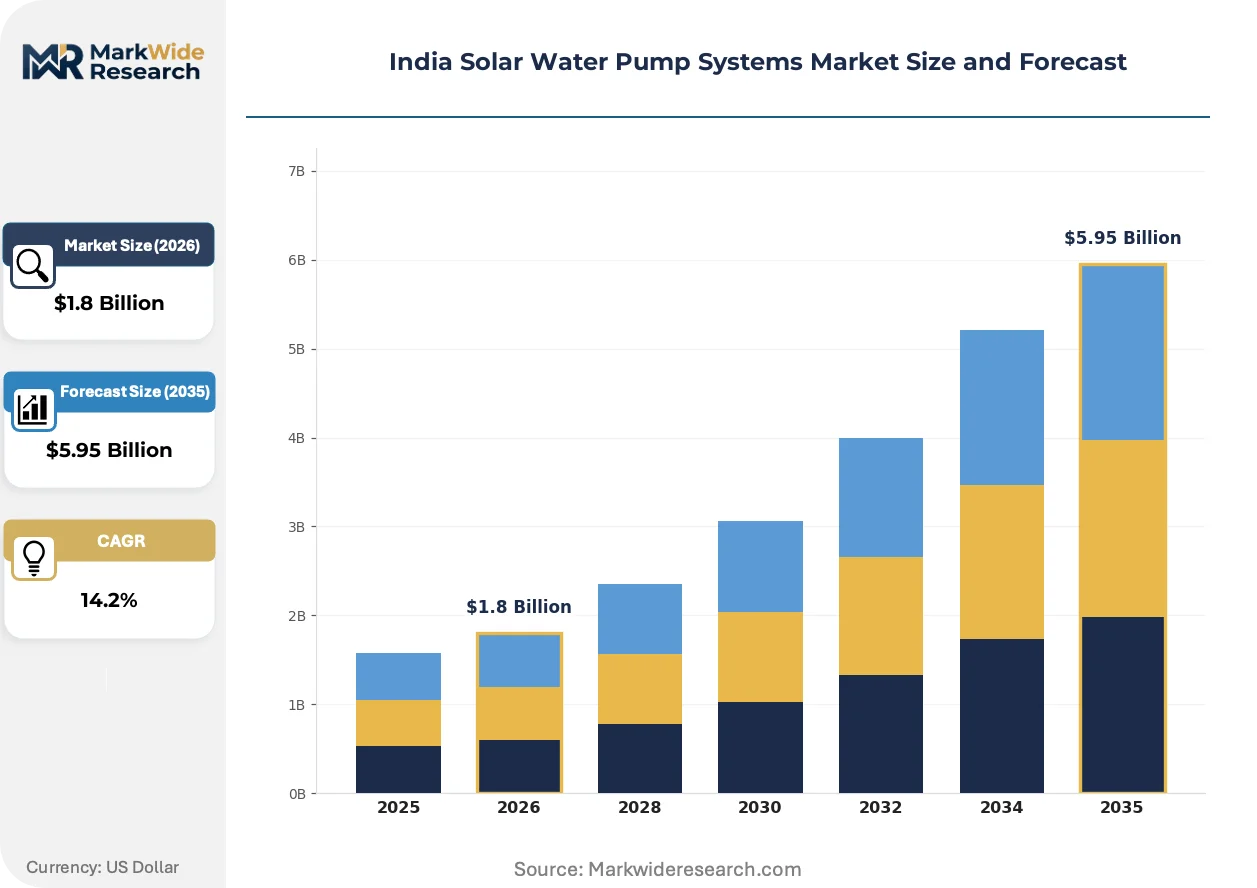
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Surface Pumps, Booster Pumps, Inline Pumps End User: Agricultural Sector, Commercial Users, Residential Users, Industrial Applications Power Rating: 1 HP, 2 HP, 3 HP, 5 HP Technology: Photovoltaic Panels, Programmable Controllers, Water Level Sensors, Variable Frequency Drives |
| Companies Covered | Falcon Pumps Pvt. Ltd., KSB Limited, Shakti Pumps (India) Ltd, Novergy Energy Solutions Pvt Ltd, Crompton Greaves Consumer Electricals Ltd., Waaree Energies Ltd, Aqua Group, Amrut Energy Pvt Ltd, Lubi Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Solar Water Pump Systems Market Shifts & Advancements
Technology convergence between photovoltaic hardware and precision agriculture software is redefining vendor value propositions beyond standalone equipment supply.
Brushless DC motor controllers with integrated maximum power point tracking are collapsing the cost premium between fixed-tilt and tracking array configurations. Gujarat's cooperative irrigation societies are adopting these units at replacement cycle points originally scheduled for AC motor retrofits. The technology is collapsing the traditional segmentation between entry-level and premium pump tiers by embedding automation as standard.
CEA technical standards for grid-interactive solar pumps are mandating smart metering and remote disconnection capabilities for all Component C installations above 7.5 HP. This regulatory architecture is forcing controller firmware upgrades and encrypted communication module integration. Rajasthan's DISCOMs are responding with pilot programs in Jodhpur division that test time-of-day export pricing for agricultural feeders.
Smallholder purchasing committees in Maharashtra are consolidating village-level procurement to negotiate volume discounts and shared maintenance contracts. The disintermediation of district-level dealer networks is accelerating direct manufacturer relationships. This pattern is most visible in Solapur's grape-growing clusters where farmer producer organizations now specify warranty terms and spare parts availability clauses in tender documents.
India Solar Water Pump Systems Market Segmentation
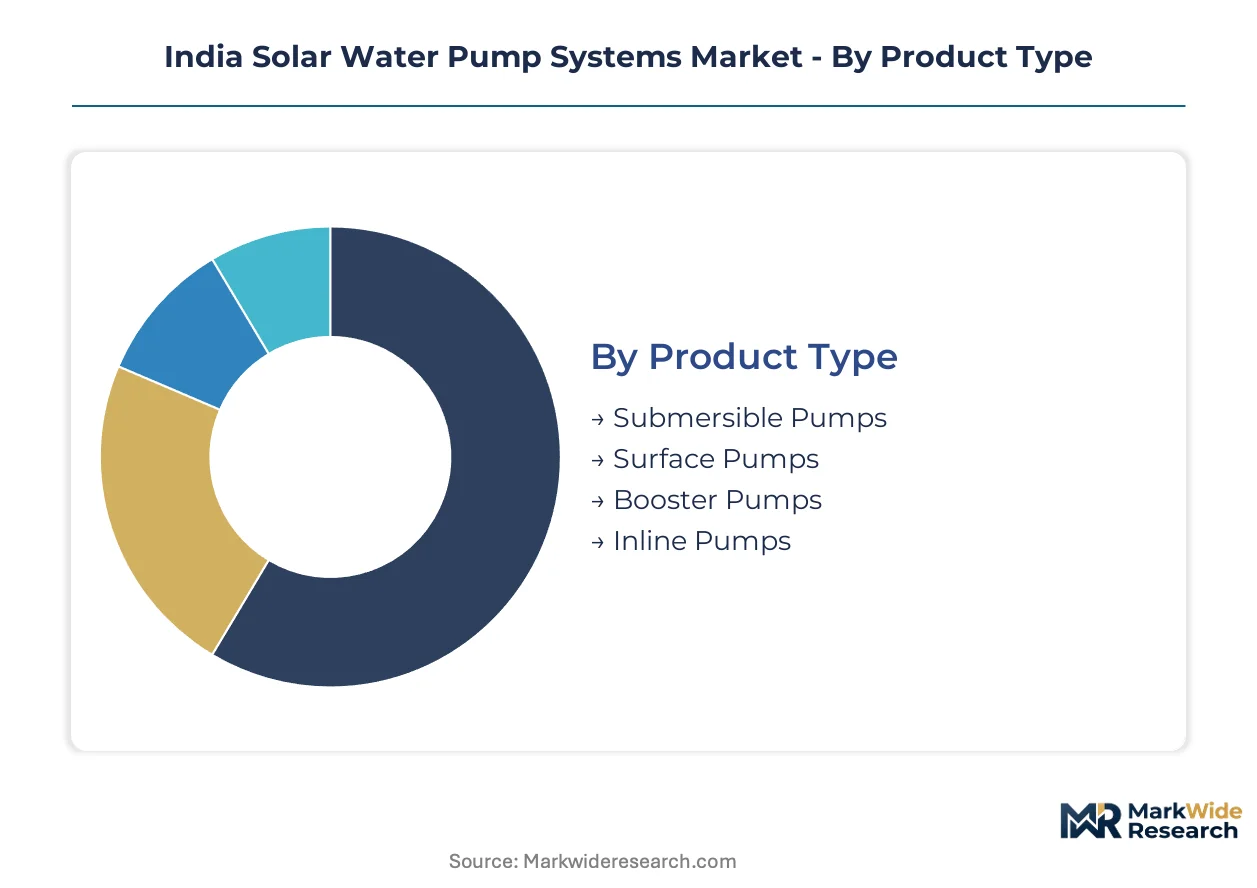
Segmentation in India's solar water pump market reveals how subsidy eligibility rules, groundwater depth variations, and voltage compatibility requirements fragment procurement patterns across states. Vendors must align product portfolios with PM-KUSUM certification tiers and regional aquifer conditions to capture subsidy flows.
Product Type:
After-sales service intensity varies sharply across pump configurations, with deep-borewell installations demanding specialized technician networks that only submersible specialists maintain.
- Submersible Pumps:These units operate below 80-meter depths in depleting aquifer zones across Rajasthan's Marwar region. Demand concentrates where borewell proliferation outpaces surface water availability, with farmers prioritizing dry-run protection and sand-resistant impeller designs. PM-KUSUM Component B subsidies favor these units for their diesel displacement economics in deep drilling scenarios.
- Surface Pumps:Designed for canal-fed irrigation and shallow well applications under 40 meters, these pumps dominate Gujarat's cooperative irrigation societies. Haryana's Hisar and Sirsa districts show underpenetrated deployment potential where canal infrastructure exists but electrification remains erratic.
- Booster Pumps:These pressure-amplification units serve micro-irrigation distribution networks in Maharashtra's horticulture belts.
- Inline Pumps:Compact axial-flow designs address pressurized pipeline requirements in Tamil Nadu's banana cultivation clusters.
Submersible pumps hold the largest share; momentum sits with surface pumps as canal rehabilitation expands across northern plains.
End User:
Capital subsidy access and irrigation scale determine procurement volume tiers, with agricultural cooperatives leveraging collective bargaining power unavailable to individual households.
- Agricultural Sector:Smallholder farming communities across Gujarat, Maharashtra, and Rajasthan drive installed base expansion through diesel substitution economics. PM-KUSUM Component B's 30-50% capital cost coverage targets this segment explicitly, with farmer producer organizations in Solapur's grape clusters now specifying warranty terms directly in tenders.
- Commercial Users:Horticulture estates and agro-processing units in Coimbatore's banana belt require micro-irrigation-compatible variable-frequency systems. Tamil Nadu's state horticulture department mandates create specification windows for higher-horsepower installations with automated flow control.
- Residential Users:Rural homesteads with livestock operations in Madhya Pradesh's tribal districts represent emerging demand for 1-2 HP units.
- Industrial Applications:Textile processing units in Surat's manufacturing corridor deploy solar pumping for effluent recycling compliance.
Agricultural applications command dominant volume; commercial horticulture installations are climbing the fastest as state mandates harden.
Power Rating:
Subsidy disbursement ceilings and groundwater depth requirements create natural procurement bands that vendors must stock against state nodal agency preference lists.
- 1 HP:Entry-level units serve kitchen gardens and small livestock operations where shallow wells suffice. These systems face substitution pressure from second-hand diesel gensets in Gujarat's industrial resale markets.
- 2 HP:Mid-range capacity dominates Maharashtra's sugarcane belt where PM-KUSUM subsidies have compressed payback periods since diesel irrigation costs tripled.
- 3 HP:Standard specification for cooperative irrigation societies replacing AC motor retrofits with brushless DC alternatives.
- 5 HP:Grid-interactive installations above this threshold trigger CEA smart metering mandates for Component C eligibility.
2 HP systems anchor current procurement volumes; 5 HP installations show steepest expansion trajectory as grid-export frameworks mature.
Technology:
Controller firmware capabilities now determine subsidy eligibility tiers, with remote monitoring requirements forcing hardware refresh cycles faster than photovoltaic degradation alone would dictate.
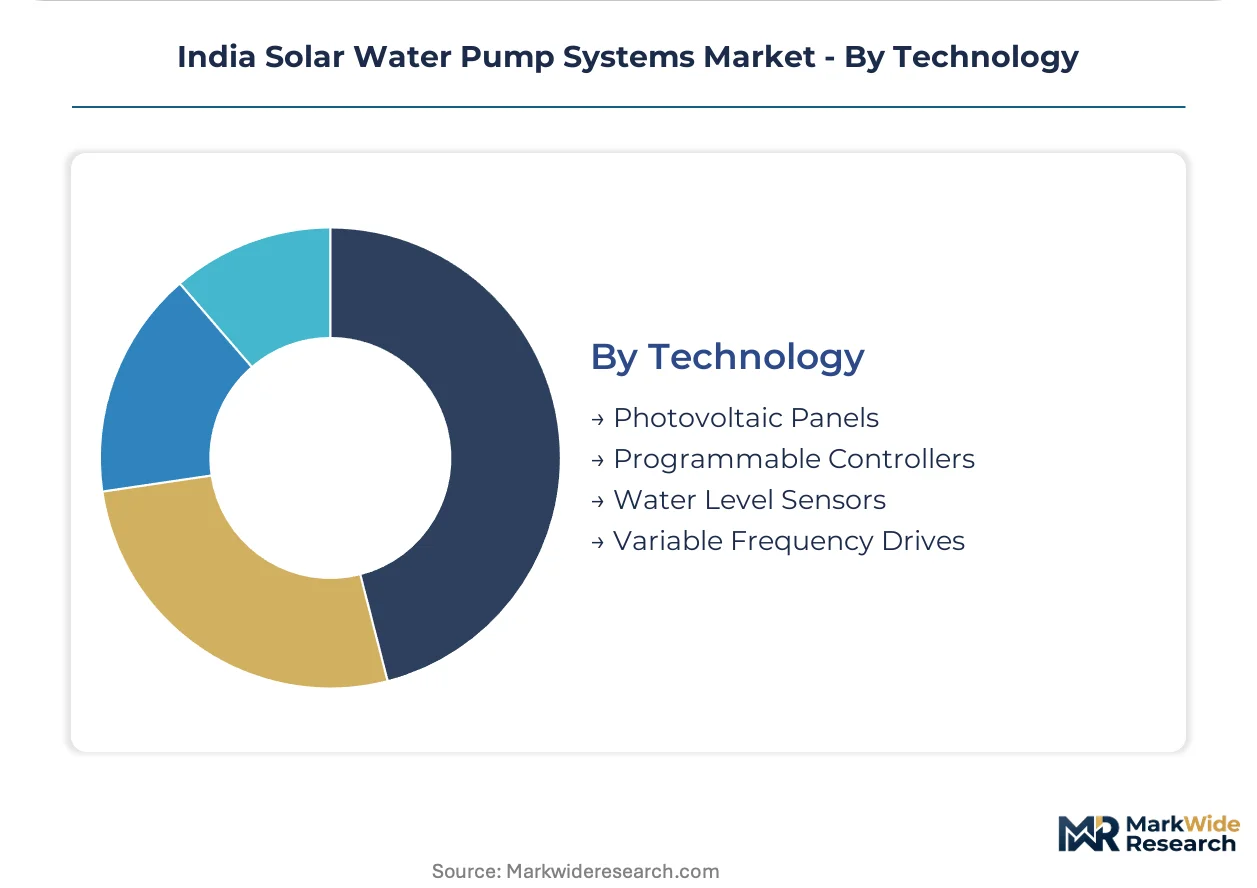
- Photovoltaic Panels:BIS certification mandates restrict subsidy eligibility to domestically manufactured modules, tightening import competition. Waaree Energies' Surat fab and Mundra assembly operations supply the photovoltaic layer for compliant installations.
- Programmable Controllers:Brushless DC motor controllers with integrated maximum power point tracking are collapsing cost premiums between fixed-tilt and tracking arrays. These units embed automation as standard, eroding traditional segmentation between entry-level and premium pump tiers.
- Water Level Sensors:GSM-based flow monitoring creates recurring revenue streams from predictive maintenance contracts in Rajasthan's dispersed borewell networks.
- Variable Frequency Drives:Micro-irrigation compatibility requirements in Tamil Nadu's horticulture push open specification windows for pressure-responsive motor control.
Photovoltaic panels represent the largest technology expenditure; programmable controllers are gaining share fastest as firmware upgrades become mandatory for grid-interactive eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photovoltaic module assembly clusters in Gujarat and Maharashtra concentrate manufacturing capacity, while state-level PM-KUSUM implementation velocity fragments demand patterns across western and northern India.
Gujarat
Cooperative irrigation societies in the Saurashtra belt drive surface pump procurement through collective bargaining structures. The state nodal agency mandates BIS-certified pump sets for subsidy eligibility, tightening vendor qualification. Surat's manufacturing corridor hosts Waaree Energies' module fab, supplying domestically assembled photovoltaic layers for compliant installations.
Maharashtra
Sugarcane belt farmers facing tripled diesel irrigation costs since 2019 are accelerating grid-connected pump adoption. PM-KUSUM Component B's 30-50% capital cost coverage compresses payback periods in Solapur's grape-growing clusters. Farmer producer organizations in this region now specify warranty terms and spare parts availability directly in tender documentation.
Rajasthan
Depleting water tables across the Marwar region force borewell drilling below 80-meter depths, favoring submersible DC pump specifications. State nodal agencies layer additional efficiency requirements that privilege vendors with localized service networks. Jodhpur division DISCOMs pilot time-of-day export pricing for agricultural feeders under Component C frameworks.
Tamil Nadu
Horticulture department mandates for micro-irrigation compatibility open specification windows in Coimbatore's banana belt. The state requires variable-frequency drive pumps for higher-horsepower installations with automated flow control. Surface pump deployment remains underpenetrated relative to borewell zones, offering volume expansion without deep-drilling infrastructure.
Haryana
Canal-fed districts in Hisar and Sirsa present untapped surface pump potential where irrigation infrastructure exists but grid electrification remains erratic. PM-KUSUM subsidy disbursement velocity varies by district, compressing vendor cash cycles. Localized service network density determines vendor success against second-hand diesel genset substitution economics.
India Solar Water Pump Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin from controllers and photovoltaic supply. The vendor base organizes around three archetypes: vertically integrated pump foundries, module-assemblers diversifying downstream, and German-engineered surface pump licensors adapting for Indian voltage conditions. Consolidation pressure operates through subsidy eligibility rules rather than scale economics alone. Dominant competitive moves include assembly localization decisions timed to BIS certification queues and firmware upgrades for grid-interactive eligibility.
Among India-based pump fabricators, Shakti Pumps (India) Ltd and KSB Limited exemplify divergent positioning archetypes. Shakti Pumps occupies the vertically integrated foundry tier through captive manufacturing in Pithampur. KSB Limited represents the licensed-engineering model, adapting foreign designs for domestic voltage compatibility. Waaree Energies Ltd anchors the photovoltaic supply side, its Surat module fab supplying BIS-certified layers that satisfy PM-KUSUM domestic content mandates. These three illustrate how subsidy architecture forces specialization choices across the value chain.
| Leading Market Players |
|---|
| Falcon Pumps Pvt. Ltd. |
| KSB Limited |
| Shakti Pumps (India) Ltd |
| Novergy Energy Solutions Pvt Ltd |
| Crompton Greaves Consumer Electricals Ltd. |
| Waaree Energies Ltd |
| Aqua Group |
| Amrut Energy Pvt Ltd |
| Lubi Electronics |
| Others |
Supply & Pricing Matrix
Malaysian and Vietnamese IGBT packaging facilities concentrate controller chip supply, anchoring margin pools in programmable controller firmware rather than commodity photovoltaic assembly. This upstream concentration forces Indian pump vendors to absorb lead time volatility or advance inventory positions, compressing working capital cycles faster than module cost declines alone would predict.
Pricing Analysis
PM-KUSUM Component B dictates the pricing tier structure by tying 30-50% capital subsidies to BIS-certified pump sets and domestically manufactured modules. Three-tier pricing structure across premium, standard, and economy levels separates vendors with NABL-accredited lab partnerships from unorganized assemblers lacking certification capacity. Cost compression in economy-tier surface pumps is intensifying because second-hand diesel gensets from Gujarat's industrial resale markets undercut lifecycle economics for shallow well applications. Smallholder farming communities in Rajasthan's tribal districts exhibit highest price sensitivity, while commercial horticulture estates in Tamil Nadu's Coimbatore belt prioritize micro-irrigation compatibility over upfront capital outlay.
Supply Chain Analysis
Pithampur foundry operations and Surat module fabrication facilities hold captive manufacturing capacity for vertically integrated pump fabricators. Geographic supply concentration centers on India for cast iron components and final assembly, China for polysilicon feedstock, and Southeast Asia for power semiconductor packaging. Raw material dependencies rest on copper windings, rare-earth magnets for brushless DC motors, and aluminum extrusions for photovoltaic mounting structures. Single-source vulnerability in IGBT and MOSFET supply exposes vendors to 12-16 week lead time volatility. Distribution runs through state nodal agencies and farmer producer organizations, with village-level procurement committees in Maharashtra's Solapur clusters disintermediating traditional district dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified electrician scarcity for 400V DC handling constrains installation velocity in Madhya Pradesh's tribal districts, creating a bottleneck that rewards vendors with captive training infrastructure. This capability gap separates subsidy-eligible vendors from unorganized competitors unable to meet commissioning requirements.
For Market Incumbents: Pre-empt controller chip supply disruptions by advancing inventory positions or qualifying secondary packaging sources in Vietnam. Secure NABL-accredited lab partnerships to compress BIS certification timelines from 4-6 months, accelerating subsidy eligibility and working capital recovery. Defend against farmer producer organization disintermediation by embedding direct service contracts with village-level procurement committees in Maharashtra's grape-growing clusters. For New Entrants and Emerging Players: Haryana's canal-fed districts present underpenetrated surface pump deployment potential where irrigation infrastructure exists but grid electrification remains erratic. Target Hisar and Sirsa with shallow-well pump configurations that avoid deep-drilling service infrastructure requirements. Enter through cooperative irrigation society tenders in Gujarat's Saurashtra belt, leveraging collective bargaining structures to bypass established dealer networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pump fabricators lacking programmable controller firmware capabilities or IoT-enabled predictive maintenance platforms. Long-term viability hinges on subsidy disbursement velocity and component localization rules tightening import competition. Monitor PM-KUSUM Component C grid-interactive pilot programs in Rajasthan's Jodhpur division for signals on time-of-day export pricing adoption. Quarterly review of state nodal agency implementation timelines and BIS certification queue lengths is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Controller Firmware Upgrade | CEA smart metering mandates for Component C eligibility force encrypted communication module integration. |
| Assembly Localization | BIS certification timelines and domestic content rules compress vendor decisions on manufacturing footprints. |
| Service Network Expansion | State nodal agency efficiency requirements in Rajasthan privilege vendors with localized technician density. |
| IoT Platform Integration | GSM-based flow sensors create recurring revenue from predictive maintenance contracts in dispersed borewell networks. |
| Cooperative Society Partnership | Direct manufacturer relationships with farmer producer organizations in Solapur accelerate volume procurement. |
Research Methodology
The analysis maps submersible pump configurations, surface pump deployments, and programmable controller tiers, each validated through installation contractors, state nodal agency procurement officers, and farmer producer organization representatives. Primary interviews with EPC contractors, DISCOM planning officers, and NABL-accredited lab technicians combined with secondary validation from MNRE subsidy disbursement records, CEA technical standards filings, and state horticulture department mandates. Bottom-up pump deployment estimates triangulated against top-down PM-KUSUM budget allocation trajectories.
Assumptions held PM-KUSUM subsidy disbursement velocity and BIS certification timelines fixed at current state-level implementation patterns, while varying polysilicon feedstock price trajectories and groundwater depth migration rates across the projection horizon. Segmentation dimensions modeled include pump type, power rating, end-user category, and state-level regulatory framework. CAGRs derived from installed base expansion rates and replacement cycle timing, with forecast inputs incorporating borewell proliferation patterns in Rajasthan's Marwar region and canal rehabilitation timelines in Haryana's northern plains.
Practitioners should monitor IGBT supply lead times, state nodal agency staffing capacity, and groundwater table depth migration for early signals of forecast revision. Forecasts reflect these assumptions and acknowledge that subsidy disbursement delays, aquifer yield variability in hard-rock Deccan zones, or controller chip supply disruptions could materially alter trajectory. Quarterly review of MNRE Component B implementation bulletins and NABL lab queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
United States Subsea Pumps Market
Pumps and Control Devices
Screw Pumps Market
Pumps and Control Devices
Solar Fountain Pumps Market
Pumps and Control Devices
Twin Screw Pumps Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Pumps and Trigger Spray Market
Pumps and Control Devices
Asia-Pacific Cryogenic Pump Market
Pumps and Control Devices
Plate Heat Exchanger Market
Pumps and Control Devices
Industrial Oil Filter Machine Market
Pumps and Control Devices
Subsea Pumping System Market
Pumps and Control Devices
Package Pumping Station Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Global Pumps Market