
 API 610 Pumps Market | 2026-2036
API 610 Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
API 610 Pumps Market Insights
Modular skid-mounted pump packages is pivoting buyer preference away from field-erected standalone units. Flowserve Corporation leverages integrated lube oil and seal support systems to anchor large refinery contracts in the Americas. Sulzer Ltd sustains manufacturing scale across multistage barrel pump lines for high-pressure hydrogen service. KSB SE & Co. KGaA competes through localized casting and machining capacity in Europe and Asia.
API 610 pumps are heavy-duty centrifugal units engineered to ISO 13709 and API 610 12th Edition standards with minimum 20-year design life, operating at temperatures from minus 160°C to 450°C and handling hydrocarbons, chemicals, and boiler feedwater in continuous process duty. End suction configurations dominate unit volume in chemical processing and water treatment where lower differential pressures suffice. Multistage barrel pumps command premium positioning in oil and gas applications above 100 bar discharge pressure where forged steel casings and API 682 seal plans are mandatory. Vertical turbine installations serve cooling water and crude tank farm sump duties where space constraints and NPSH limitations drive specification.
API 610 12th Edition, ISO 13709, and API 682 seal standards govern material selection, performance testing, and emissions containment across refinery and petrochemical installations. EPA New Source Performance Standards and EU Industrial Emissions Directive enforce methane and volatile organic compound limits that tighten seal specifications and drive dry gas seal conversions. Buyers must weigh spare parts commonality against seal technology migration paths as hydrogen service expands and emission thresholds tighten further.
Market Dynamics
Refinery operators in Saudi Arabia and the UAE are expanding hydrotreater and desulfurization units, tightening procurement specifications around API 682 seal plans and ISO 13709 material upgrades that favor OH2 and BB1 pump configurations.
Growth Catalysts
- EPA New Source Performance Standards:Methane and volatile organic compound limits enforce dry gas seal conversions across US Gulf Coast refineries, mandating API 682 compliant seal support systems.
- Hydrogen service expansion:Middle Eastern refiners in Jubail Industrial City and Ruwais are specifying forged steel casings and multistage barrel pumps for high-pressure hydrogen applications above 100 bar.
- ISO 13709 material upgrades:Procurement specifications now require 20-year design life minimums with operating ranges from minus 160°C to 450°C, displacing non-compliant legacy equipment.
Market Restraints
- Nickel alloy supply concentration:Forged steel casings for high-pressure hydrogen service depend on concentrated specialty alloy supply chains in Western Europe and Japan.
- EU Industrial Emissions Directive:Compliance timelines for volatile organic compound containment create procurement friction for operators with aging seal infrastructure.
- Modular skid packages:Field-erected standalone units face displacement risk as buyers favor integrated lube oil and seal support systems from single-source suppliers.
Strategic Opportunities
- India's petrochemical corridors:Underpenetrated demand for end suction configurations in chemical processing and water treatment offers volume expansion potential.
- API 610 12th Edition adoption:Regulatory tailwind from updated testing and performance standards creates upgrade cycles for installed base replacement.
- Vertical turbine cooling water systems:Space-constrained crude tank farm installations in Singapore and South Korea present NPSH-limited application growth.
Industry Challenges
- Seal technology migration paths:Spare parts commonality conflicts with emission threshold tightening require complex inventory planning for maintenance teams.
- Continuous process duty certification:API 610 12th Edition and API 682 compliance timelines extend procurement cycles for critical path refinery projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | API 610 Pumps Market |
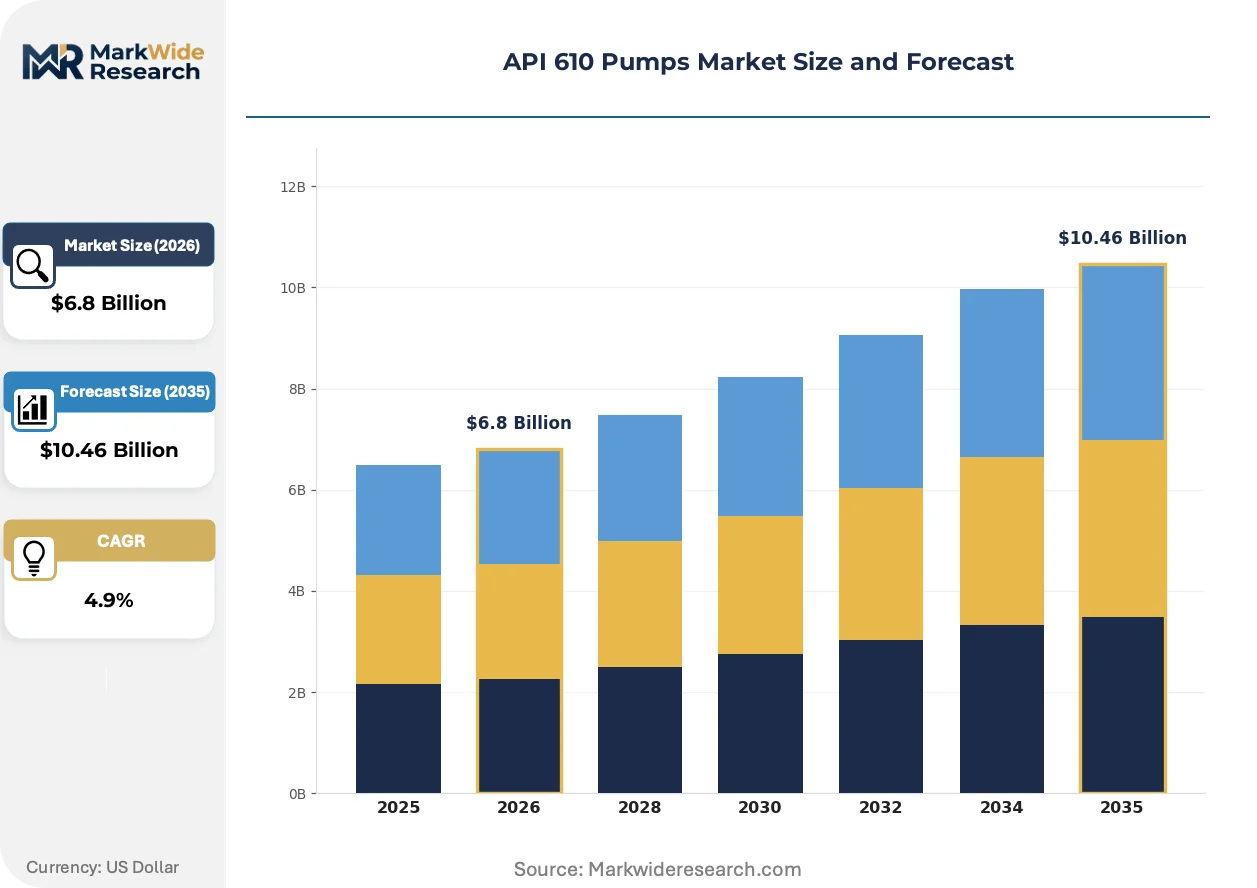
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.46 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: End Suction, API Centrifugal, Vertical Turbine, Multistage Application: Oil & Gas, Water Treatment, Chemical Processing, Power Generation End User: Refineries, Power Plants, Mining, Pulp & Paper Installation Type: Fixed, Portable, Skid-Mounted, Above Ground |
| Companies Covered | Ruhrpumpen Group, Sundyne LLC, Flowserve Corporation, Ebara Corporation, ITT Goulds Pumps, Sulzer Ltd, Trillium Flow Technologies, Pumpworks, KSB SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
API 610 Pumps Market Trends and Innovations
Equipment packaging and emissions containment technologies are compressing procurement cycles while elevating performance verification requirements across refinery and petrochemical installations.
Dry gas seal systems with integrated monitoring instrumentation are displacing conventional liquid barrier seals in hydrocarbon service. Major operators in the US Gulf Coast and Middle East are specifying these configurations for new hydrotreater units. The technology is modularizing pump-seal-lube oil packages into single-source deliverables that compress field installation schedules and reduce commissioning risk.
REACH and the EU F-Gas Regulation are tightening material disclosure requirements for fluoropolymer components used in seal faces and O-rings. Industrial consequences include accelerated qualification of alternative metallurgy and ceramic face materials for high-temperature service. European refiners in Rotterdam and Antwerp are responding with phased seal upgrade programs aligned to maintenance turnaround windows.
Buyer specifications now unbundle after-sales service from initial equipment procurement, with operators self-performing seal maintenance or contracting third-party specialists. This pattern disrupts traditional OEM service revenue models and compresses spare parts margins. The shift is most visible in North American refineries with established maintenance capabilities and in Saudi Arabia's Jubail Industrial City where localized technical labor pools support in-house overhaul capacity.
API 610 Pumps Market Segmentation
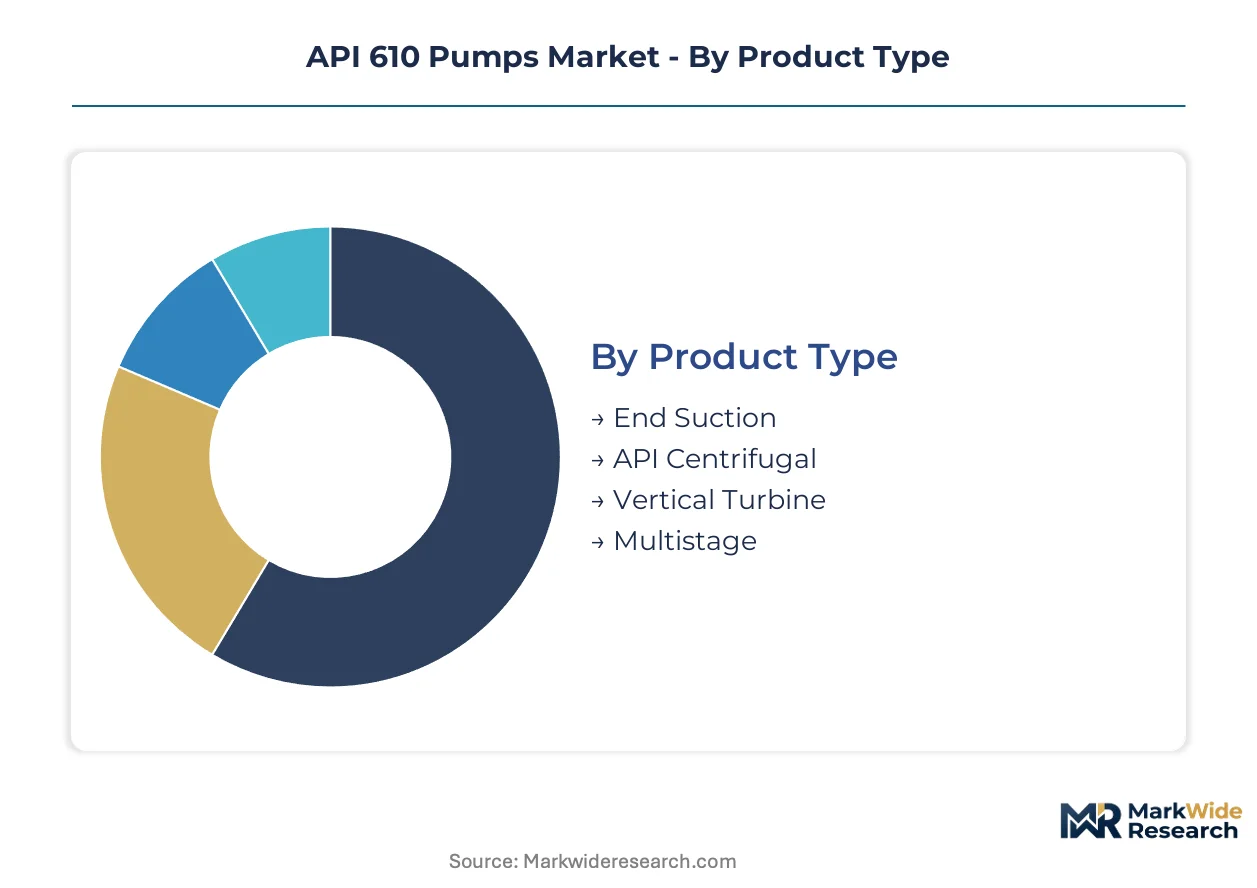
Segmentation in API 610 pumps reveals distinct procurement patterns across standalone field-erected units versus integrated modular packages. Buyers in refinery and petrochemical applications weight seal technology compatibility, pressure rating, and maintenance accessibility differently based on installation configuration and duty cycle requirements.
Product Type:
Standalone configurations dominate chemical processing and water treatment where lower differential pressures allow simpler installation protocols, while embedded multistage systems anchor high-pressure refinery applications demanding forged steel integrity.
- End Suction:Horizontal single-stage units with overhung impeller design handle moderate head requirements up to 100 meters. Demand concentrates in India's petrochemical corridors and Southeast Asian water treatment facilities where capital efficiency outweighs pressure capability needs.
- API Centrifugal:Radially split or axially split casings engineered to ISO 13709 specifications with minimum 20-year design life. Procurement in Saudi Arabia's Jubail Industrial City and UAE's Ruwais refining corridor specifies these for continuous hydrocarbon duty with API 682 seal integration.
- Vertical Turbine:Space-constrained installations in crude tank farm sump duties and cooling water systems where NPSH limitations prohibit horizontal configurations.
- Multistage:Forged steel barrel pumps for discharge pressures above 100 bar in hydrogen service applications.
Volume placements concentrate in End Suction configurations; the faster expansion belongs to Multistage systems as Middle Eastern hydrotreater expansions accelerate.
Application:
Cost tier stratification separates premium-specified refinery applications from standard-duty water treatment, with chemical processing occupying a mid-tier position balancing corrosion resistance against capital constraints.
- Oil & Gas:Upstream production, midstream pipeline, and downstream refining operations requiring API 610 12th Edition compliance with forged steel casings and dry gas seal systems. Demand clusters in US Gulf Coast EPA-regulated facilities and Middle Eastern desulfurization unit expansions.
- Water Treatment:Boiler feedwater and process water applications with lower pressure thresholds and standard metallurgy. Municipal and industrial installations in India and Southeast Asia drive procurement volume through end suction and vertical turbine configurations.
- Chemical Processing:Corrosive fluid handling with specialty alloy requirements for acids, caustics, and polymer feedstocks.
- Power Generation:Boiler feed pumps and cooling water systems in combined cycle and thermal plants.
Capital intensity peaks in Oil & Gas; Chemical Processing gains share fastest as specialty chemical capacity expands in Asia.
End User:
Customer type determines service integration expectations, with refineries demanding full-package procurement including seal support systems while power plants and mining operators favor equipment-only purchases with self-performed maintenance.
- Refineries:Continuous process duty with zero-tolerance reliability requirements drives specification of API 682 compliant seal plans and integrated lube oil systems. Saudi Aramco and ADNOC operations in Jubail and Ruwais mandate 20-year design life with full modular packaging.
- Power Plants:Boiler feed and cooling water applications with scheduled outage windows permitting planned maintenance. Indian and Chinese thermal power expansion sustains demand for multistage barrel and vertical turbine configurations.
- Mining:Abrasive slurry and process water duties with lower pressure requirements and higher tolerance for standard metallurgy.
- Pulp & Paper:Black liquor and chemical recovery applications requiring corrosion-resistant materials.
Procurement value concentrates in Refineries; Power Plants represent the steepest expansion trajectory as Asian generation capacity builds out.
Installation Type:
Supply concentration among integrated package specialists is compressing field-erected standalone market share as buyers prioritize single-source accountability and reduced commissioning risk.
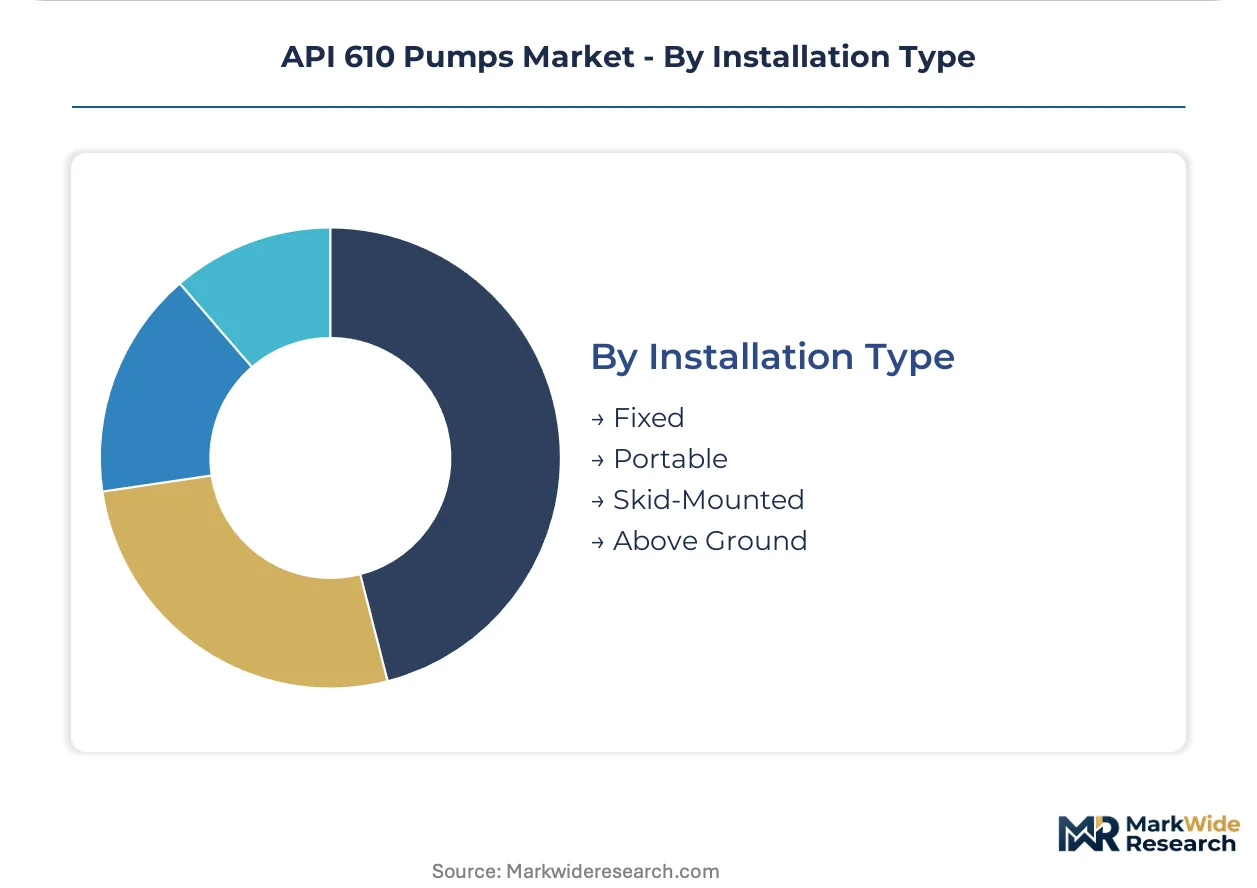
- Fixed:Permanent foundation-mounted installations in greenfield refinery and petrochemical complexes. Saudi Arabia's Jubail Industrial City expansions specify these for hydrotreater and desulfurization units with 30-plus year facility life.
- Portable:Trailer or skid-mounted units for temporary dewatering, construction, and emergency response. Mining operations in Australia and Canada deploy these for pit dewatering with rapid relocation requirements.
- Skid-Mounted:Factory-integrated pump, motor, seal support, and lube oil systems delivered as complete packages. Flowserve and Sulzer anchor major contracts through this configuration, compressing field installation schedules and reducing commissioning risk for US Gulf Coast and Middle Eastern refiners.
- Above Ground:Elevated installations for flood-prone areas and tank farm applications.
Skid-Mounted packages are gaining share fastest; Fixed installations retain the largest installed base in established refining corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity for API 610 pumps concentrates in Germany, Japan, and the United States, while consumption gravity shifts toward Saudi Arabia, the UAE, and India as refinery expansions accelerate. This geographic divergence shapes procurement patterns, with Middle Eastern buyers importing forged steel casings and multistage barrel configurations from established manufacturing bases.
United States
EPA New Source Performance Standards mandate dry gas seal conversions across Gulf Coast refineries, compressing procurement cycles for API 682 compliant systems. Houston and Corpus Christi anchor demand clusters where operators upgrade hydrotreater units. The regulatory enforcement timeline favors skid-mounted packages with integrated seal support.
Saudi Arabia
Jubail Industrial City expansions specify OH2 and BB1 pump configurations for hydrotreater and desulfurization units with 20-year design life requirements. SFDA-aligned procurement protocols tighten material traceability for forged steel components. Localized technical labor pools enable in-house seal maintenance, disrupting traditional OEM service models.
Germany
REACH and the EU F-Gas Regulation accelerate qualification of alternative seal face materials for high-temperature service. Rotterdam and Antwerp refiners source phased upgrade programs through German fabricators. The regulatory pressure concentrates demand for ceramic and advanced metallurgy substitutions in continuous process duty.
India
Underpenetrated demand for end suction configurations in chemical processing corridors offers volume expansion potential. BIS standards adoption lags API 610 12th Edition, creating specification gaps for export-oriented projects. Gujarat and Maharashtra industrial zones drive procurement for water treatment and boiler feed applications.
United Arab Emirates
Ruwais refining corridor operators specify multistage barrel pumps for high-pressure hydrogen service above 100 bar. MOHAP technical regulations align with ISO 13709 material upgrade timelines. Abu Dhabi National Oil Company mandates integrated lube oil and seal support systems for greenfield installations.
API 610 Pumps Market Competitive Landscape
The competitive structure tilts toward integrated package specialists with captive forging and precision machining capabilities. Tier-one positions cluster among full-line manufacturers offering API 682 seal integration alongside pump hardware, while mid-tier players compete on lead time compression for standard end suction configurations. Two strategic archetypes dominate: vertically integrated multistage specialists and modular skid package integrators. Competitive moves center on capacity expansion in nickel alloy forging and strategic partnerships for seal technology licensing.
Among European-headquartered manufacturers, KSB SE & Co. KGaA and Sulzer Ltd occupy positions emphasizing localized casting and machining capacity across continental production networks. Flowserve Corporation anchors the Americas-focused tier through integrated lube oil and seal support system offerings. These three exemplify the shift toward factory-integrated pump-motor packages that reduce field commissioning risk for refinery operators in Saudi Arabia and the US Gulf Coast.
| Leading Market Players |
|---|
| Ruhrpumpen Group |
| Sundyne LLC |
| Flowserve Corporation |
| Ebara Corporation |
| ITT Goulds Pumps |
| Sulzer Ltd |
| Trillium Flow Technologies |
| Pumpworks |
| KSB SE & Co. KGaA |
| Others |
Pricing and Supply Chain Analysis
API 682 seal plan mandates from EPA New Source Performance Standards and EU Industrial Emissions Directive are forcing procurement specifications toward forged steel casings and dry gas seal configurations, compelling supply chains to absorb nickel alloy premium costs or cede position to integrated package specialists with captive forging capacity.
Pricing Analysis
Margin tightening in multistage barrel pumps reflects nickel alloy supply concentration in Western Europe and Japan. Pricing stratifies across API 682 compliant integrated packages, ISO 13709 certified standalone units, and standard end suction configurations. Cost compression accelerates in chemical processing tiers as Indian buyers drive volume procurement. Refinery operators in Saudi Arabia and the UAE exhibit lowest price sensitivity due to 20-year design life requirements and zero-tolerance reliability specifications.
Supply Chain Analysis
Freight costs for forged steel casings from Germany and Japan to Middle Eastern refining corridors compress margins on multistage barrel pumps. Supply draws from concentrated specialty alloy forging capacity in Germany, Japan, and the United States. Raw material dependencies center on nickel alloys, chromium steel billets, and API 682 seal face ceramics. Single-source vulnerability in hydrogen service metallurgy creates procurement risk. Distribution runs through OEM direct sales for refinery projects and authorized distributors for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API 610 12th Edition compliance functions as a cost-of-compliance moat, with EPA New Source Performance Standards and EU Industrial Emissions Directive enforcement timelines creating barrier-to-entry protection for certified incumbents against uncertified competitors.
For Market Incumbents: Anticipate seal technology migration conflicts by deepening backward integration into nickel alloy forging and API 682 seal manufacturing. Capture stranded demand from competitors lacking ISO 13709 material upgrade capacity. Prioritize captive supply of forged steel casings for hydrogen service applications above 100 bar. For New Entrants and Emerging Players: Enter via India's underpenetrated chemical processing corridors with end suction configurations priced below KSB and Sulzer tier-one positioning. Target water treatment applications in Gujarat and Maharashtra where BIS standard gaps permit specification flexibility. Pursue third-party seal maintenance contracts to bypass OEM service revenue models. For Investors and Strategic Acquirers: The window for entry favors vertically integrated multistage specialists with German or Japanese forging relationships and active API 682 seal licensing agreements. Watch for Middle Eastern national oil company procurement shifts toward single-source modular packages as inflection indicator for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Nickel Alloy Forging | Captures stranded demand from competitors lacking hydrogen service metallurgy. |
| API 682 Seal Technology Licensing | Secures dry gas seal integration for EPA-regulated US Gulf Coast refinery upgrades. |
| Modular Skid Package Integration | Compresses field installation schedules for Saudi Aramco and ADNOC greenfield projects. |
| Backward Integration into Casting | Reduces lead time exposure from Western European specialty alloy supply chains. |
| Localized Technical Service Networks | Disrupts OEM service models in Jubail Industrial City and Ruwais refining corridor. |
Research Methodology
Multi-period observation of refinery capital expenditure cycles, seal technology adoption curves, and nickel alloy price movements anchored the trend analysis, supplemented by interviews with maintenance directors at US Gulf Coast refineries, procurement leads at Saudi Aramco and ADNOC operations, plant engineers in India's chemical processing corridors, and aftermarket service heads at major OEM distributors. Secondary validation drew from EPA enforcement action databases, EU ETS emissions trading records, SEC filings from listed pump manufacturers, and customs data on forged steel casing imports. Bottom-up unit shipment estimates triangulated against top-down refinery capacity expansion projections.
Segment-weighting across product type, application, end user, and installation type dimensions structured the analytical framework across the analysis window. CAGRs derived from regression analysis of historical procurement volumes against refinery and petrochemical capacity additions. Industry-specific forecast inputs included hydrotreater unit expansion timelines in the Middle East and dry gas seal conversion schedules under EPA New Source Performance Standards.
Revisions become necessary when nickel alloy supply disruptions, regulatory enforcement timeline accelerations, or breakthrough seal technologies materialize. Forecasts reflect documented assumptions about refinery operator procurement behavior and OEM pricing discipline. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
Subsea Pumping System Market
Pumps and Control Devices
Double Suction Pump Market
Pumps and Control Devices
Chemical Metering Pumps Market
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Submersible Pumps for Mining Sector Market
Pumps and Control Devices
Electric Oil Pump Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
Pumps and Trigger Spray Market
Pumps and Control Devices
Canned Motor Pumps Market