
 Pump Tubes Market | 2026-2036
Pump Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Pump Tubes Market Analytics
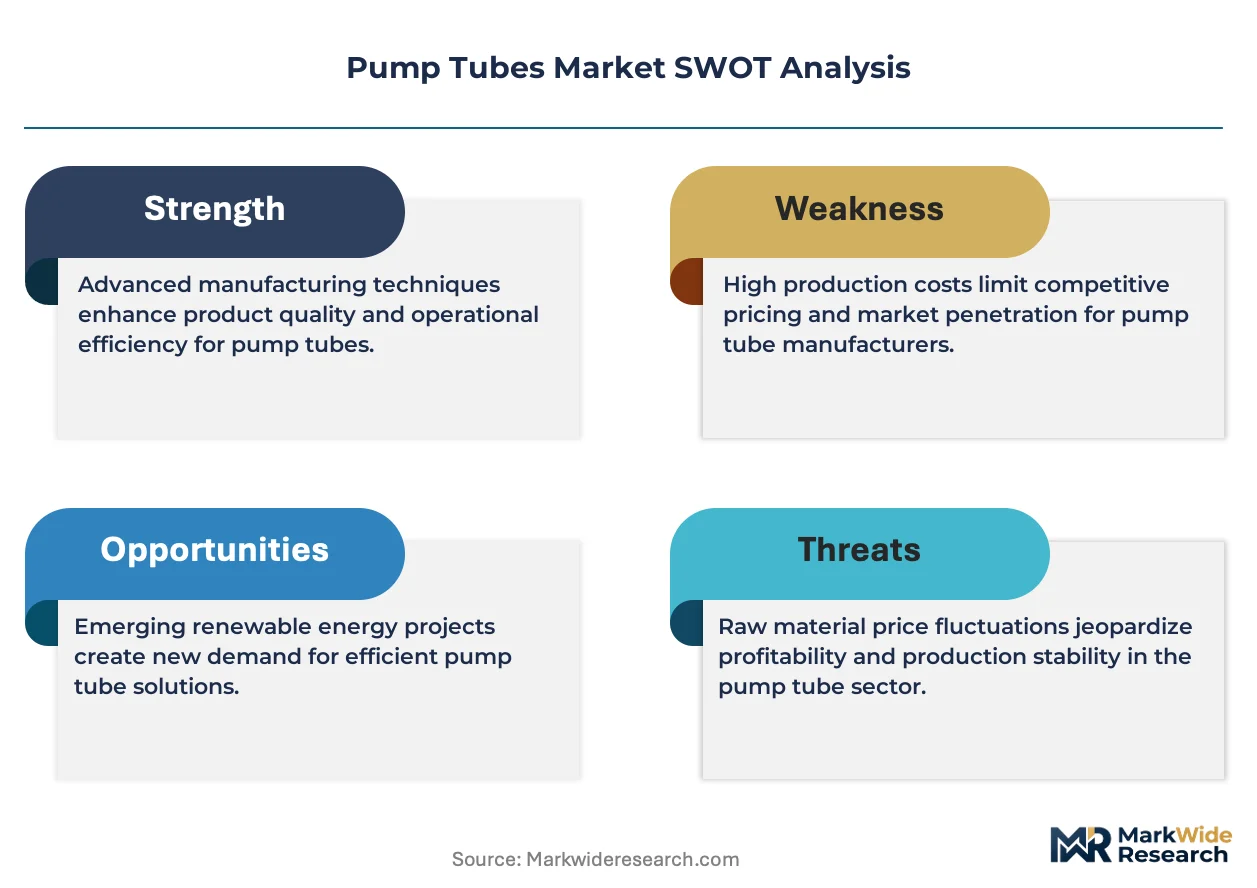
The capability gap between integrated multinationals and regional converters is collapsing as coextrusion and barrier-layer investments democratize performance parity. Berry Global leverages captive resin sourcing and North American blown-film capacity to sustain cost leadership in high-volume healthcare contracts. Hoffmann Neopac anchors European pharmaceutical dispensing demand through Swiss-based precision tube manufacturing and cleanroom certification. Amcor competes via global laminate expertise and healthcare packaging scale that extends into pump tube adjacent categories.
Pump tubes are cylindrical conduits engineered from extruded polymers or elastomers, typically ranging from 2 mm to 50 mm in diameter, designed to transport fluids, gases, or viscous materials under positive displacement, vacuum, or gravity-driven conditions. Wall thickness, Shore hardness, and chemical compatibility ratings determine suitability for pharmaceutical, food-grade, or industrial chemical transfer applications. Flexible tubes lead volume in peristaltic pump configurations where repeated compression cycles demand fatigue-resistant silicone or polyurethane formulations. Rigid tubes command premium positioning in automotive and manufacturing fluid routing where dimensional stability under pressure prevents collapse or kink failure. Custom tubes capture expanding margin pools as OEM dispensing systems require proprietary geometries, multi-layer barrier structures, and integrated connector interfaces that standard catalog products cannot address.
FDA Title 21 CFR regulations govern pharmaceutical and food-contact pump tube materials in the United States, mandating extractables testing and biocompatibility validation that elevates compliance costs for non-specialized converters. EU MDR and REACH frameworks in Europe impose substance restrictions and clinical traceability requirements that favor established suppliers with documented supply chain transparency and notified body relationships. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across both jurisdictions, as fluoropolymer-lined tubes face prospective phase-outs that would redirect material development investments toward silicone and thermoplastic elastomer alternatives.
Market Dynamics
REACH chemical restrictions and EU MDR traceability mandates are compressing the supplier base as converters without cleanroom certification or documented resin sourcing exit pharmaceutical dispensing contracts.
Growth Catalysts
- Peristaltic pump expansion in bioprocessing:Single-use bioreactor adoption demands fatigue-resistant silicone formulations for repeated compression cycles. German pharmaceutical clusters lead implementation.
- REACH PVC displacement:Phthalate and chlorine content restrictions accelerate polyurethane and thermoplastic elastomer substitution in fluid transfer lines across EU medical device applications.
- Automotive electrification fluid handling:Battery thermal management systems require chemically resistant tubing for coolant circulation. Stuttgart and Munich manufacturing corridors concentrate specification development.
Market Restraints
- Medical-grade silicone feedstock concentration:Four specialty chemical producers control pharmaceutical elastomer supply, exposing converters to allocation risk during semiconductor or solar sector demand spikes.
- EU MDR notified body bottleneck:Clinical traceability documentation requirements extend certification timelines 18-24 months for new tube geometries, freezing smaller converters out of contract bidding.
- Fluoropolymer-lined tube phase-out trajectory:Per- and polyfluoroalkyl substance restrictions under REACH and emerging US EPA action threaten high-barrier product lines, forcing premature R&D redirection.
Strategic Opportunities
- Swiss precision manufacturing corridor:Swissmedic-certified cleanroom capacity remains undersupplied relative to pharmaceutical dispensing system demand from Basel and Zurich OEM clusters.
- Integrated connector-tube assemblies:Convergence of 3D-printed manifold interfaces with extruded barriers enables proprietary geometries that lock out catalog competitors.
- Indian pharmaceutical packaging localization:CDSCO medical device rules harmonization and PLI scheme incentives attract contract manufacturing investment for export-oriented tube production.
Industry Challenges
- Multi-layer coextrusion skill scarcity:Barrier-layer thickness control and interlayer adhesion validation require polymer engineering expertise concentrated among aging European specialist workforces.
- Extractables testing capex burden:FDA 21 CFR and USP Class VI validation protocols demand in-house chromatography and mass spectrometry infrastructure that mid-scale converters cannot amortize.
- Legacy dispensing system retrofit complexity:OEMs face integration friction when upgrading tube specifications in validated pharmaceutical production lines with frozen process parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pump Tubes Market |
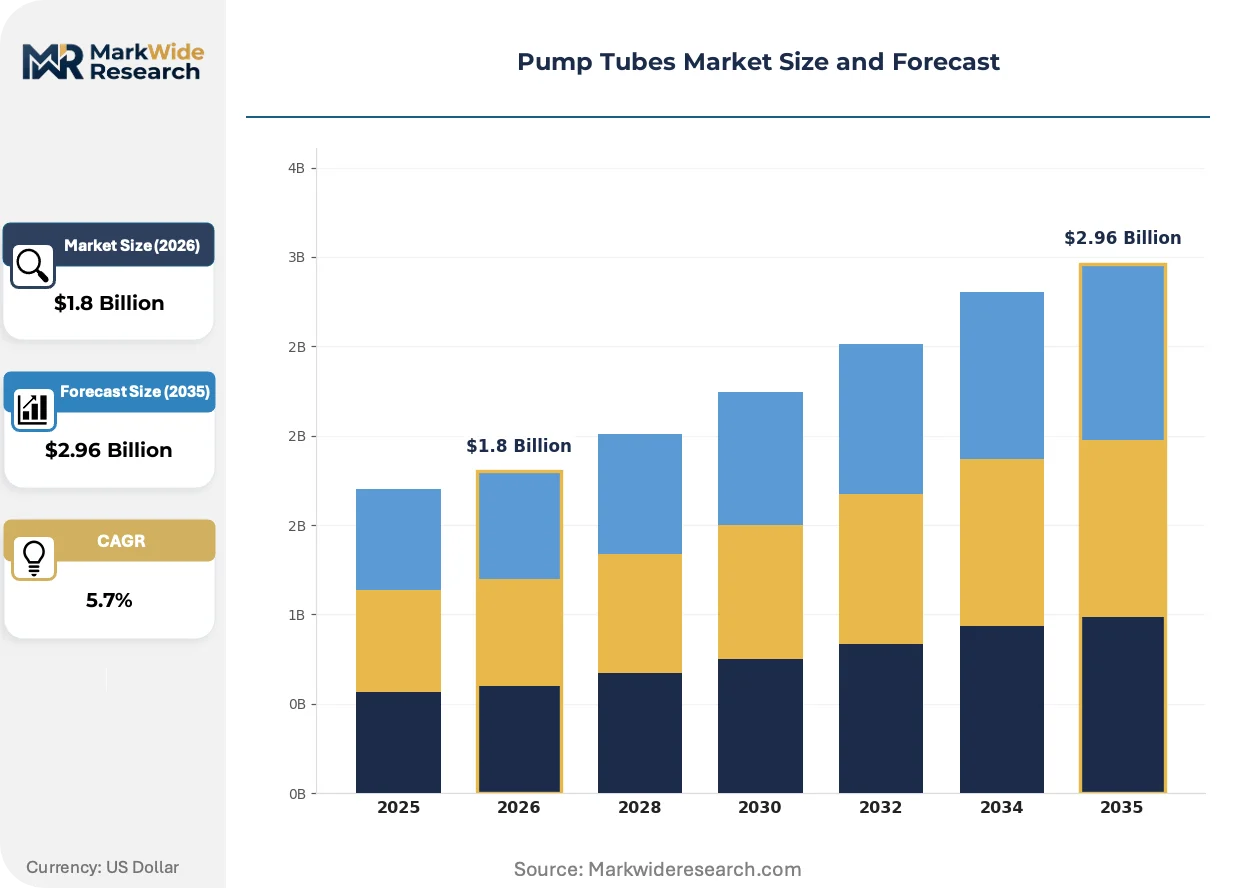
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Tubes, Rigid Tubes, Corrugated Tubes, Custom Tubes Material: Silicone, PVC, Polyurethane, Nylon Application: Fluid Transfer, Dispensing Systems, Vacuum Systems, Food Processing End User: Manufacturing, Healthcare, Agriculture, Automotive |
| Companies Covered | Albea, Berry Global, Hoffmann Neopac, Viva Packaging, Montebello Packaging, Essel Propack, Sonoco Products, Amcor, World Wide Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pump Tubes Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are fragmenting established supply relationships while creating openings for certified specialists with documented resin traceability.
Multi-layer coextrusion with ethylene vinyl alcohol barrier layers is fragmenting the commodity silicone tube segment. Pharmaceutical OEMs in Germany and Switzerland specify these structures for oxygen-sensitive biologic dispensing. The technology compresses margins for single-layer converters while rewarding integrated barrier specialists with multi-year contract locks.
EU MDR Unique Device Identification mandates and FDA 21 CFR traceability requirements are converging on laser-etched lot codes and blockchain resin documentation. Compliance investments favor suppliers with existing notified body relationships and captive polymer sourcing. Swiss and German converters with Swissmedic and TÜV certifications capture specification-setting roles.
Contract pharmaceutical manufacturers are consolidating tube procurement through designated device suppliers rather than direct material sourcing. This disintermediation compresses converter margins while transferring inventory risk to dispensing system integrators. The pattern is most visible in Basel and Frankfurt pharmaceutical clusters where Bayer and Boehringer Ingelheim operations drive vendor reduction programs.
Pump Tubes Market Segmentation
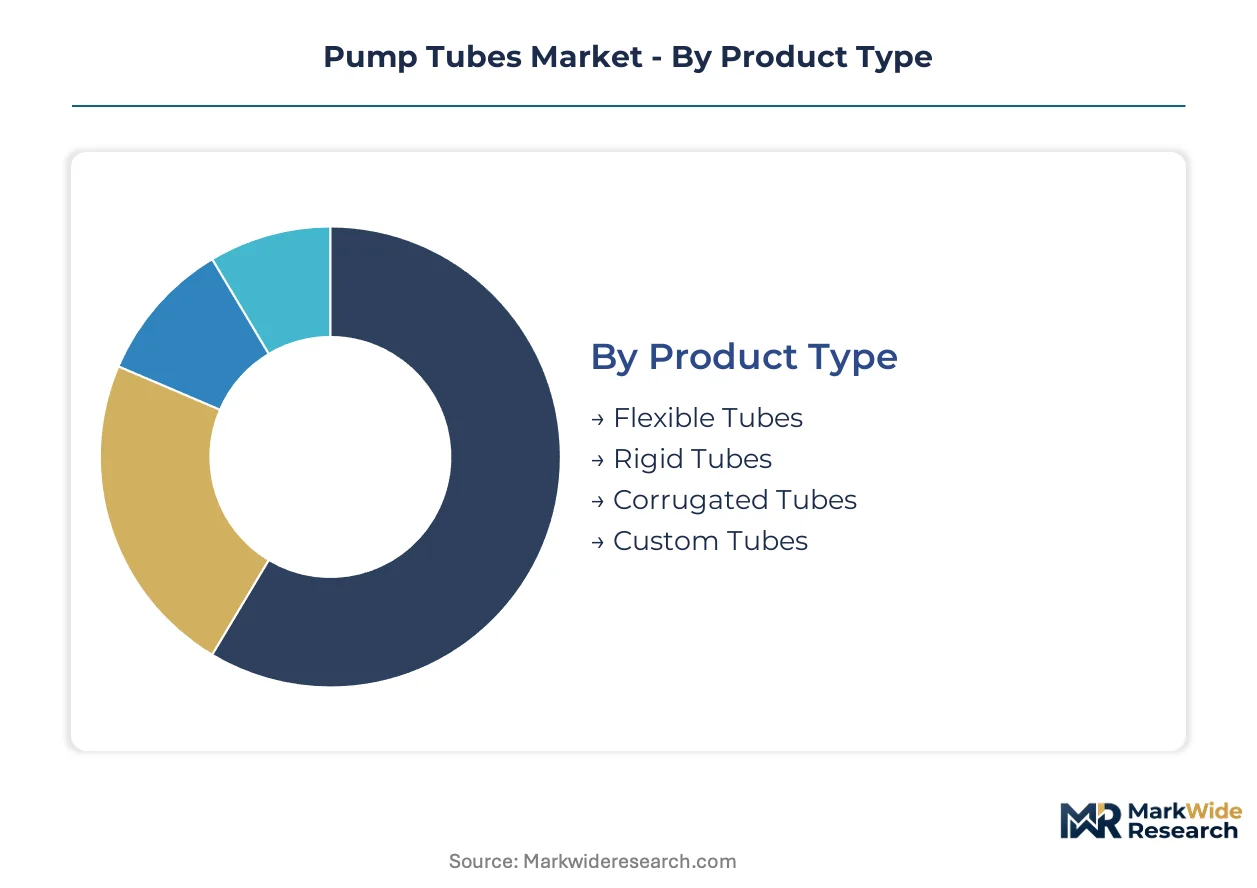
Pump tube segmentation reflects divergent pressure from regulatory chemistry bans and end-use performance requirements. Material substitution dynamics and dispensing system integration complexity fragment what appears as a commodity extrusion market into sharply tiered performance categories.
Product Type:
Flexible tubes face the most acute substitution threat from multi-layer barrier structures in pharmaceutical oxygen-sensitive applications, while rigid tubes defend position through dimensional stability requirements in automotive thermal management.
- Flexible Tubes:Extruded elastomer or thermoplastic constructions with Shore hardness ratings between 40A and 80A enable repeated compression cycles in peristaltic pump configurations. German bioprocessing clusters specify fatigue-resistant silicone formulations for single-use bioreactor lines, though REACH phthalate restrictions accelerate polyurethane displacement of legacy PVC alternatives.
- Rigid Tubes:High-durometer polymer extrusions with wall thickness-to-diameter ratios exceeding 15% maintain structural integrity under pressure or vacuum without collapse. Stuttgart automotive corridors specify these for battery coolant circulation where kink resistance prevents thermal runaway risks.
- Corrugated Tubes:Convoluted wall geometries provide crush recovery and flexibility in constrained routing spaces for industrial vacuum and material handling systems.
- Custom Tubes:Proprietary multi-layer coextrusions with integrated connector interfaces and laser-etched traceability codes capture specification-setting roles in Swiss pharmaceutical OEM dispensing systems.
Flexible tubes retain volume leadership; custom tubes hold the steepest expansion curve.
Material:
Cost tier stratification separates pharmaceutical-grade elastomers from industrial commodity polymers, with REACH substance restrictions compressing the mid-market PVC segment.
- Silicone:Platinum-cured or peroxide-cured polydimethylsiloxane formulations deliver biocompatibility and temperature resistance from -60°C to 200°C. Swissmedic-certified cleanroom production in Basel and Zurich corridors supplies FDA 21 CFR-validated extractables profiles for parenteral drug dispensing.
- Polyurethane:Polyester or polyether-based thermoplastic elastomers offer abrasion resistance and tensile strength superior to silicone in industrial fluid transfer. German automotive manufacturers specify these for battery thermal management as REACH chlorine restrictions eliminate PVC from medical device consideration.
- PVC:Plasticized polyvinyl chloride retains cost advantage in non-regulated industrial applications despite accelerating displacement from healthcare and food-contact segments under ECHA phthalate limitations.
- Nylon:Polyamide formulations provide chemical resistance and low moisture absorption for solvent transfer and hydraulic applications in manufacturing environments.
Silicone commands premium pricing tiers; polyurethane is climbing the fastest on regulatory substitution momentum.
Application:
Customer type concentration distinguishes OEM-integrated dispensing from aftermarket fluid handling, with validation requirements creating divergent margin structures.
- Dispensing Systems:Precision-engineered tubes with documented lot traceability and barrier-layer oxygen permeation specifications integrate into pharmaceutical and diagnostic OEM platforms. Frankfurt and Basel contract manufacturers consolidate procurement through designated device suppliers.
- Fluid Transfer:General-purpose chemical, water, and process fluid conduits span industrial manufacturing and agricultural irrigation with specification diversity that fragments supplier relationships.
- Vacuum Systems:Collapse-resistant wall constructions and connector compatibility with standard pump fittings serve laboratory and industrial suction applications.
- Food Processing:FDA and EU food-contact compliance with migration testing requirements elevates silicone and polyurethane over legacy materials in dairy and beverage handling equipment.
Fluid transfer retains volume leadership; dispensing systems hold the steepest expansion curve.
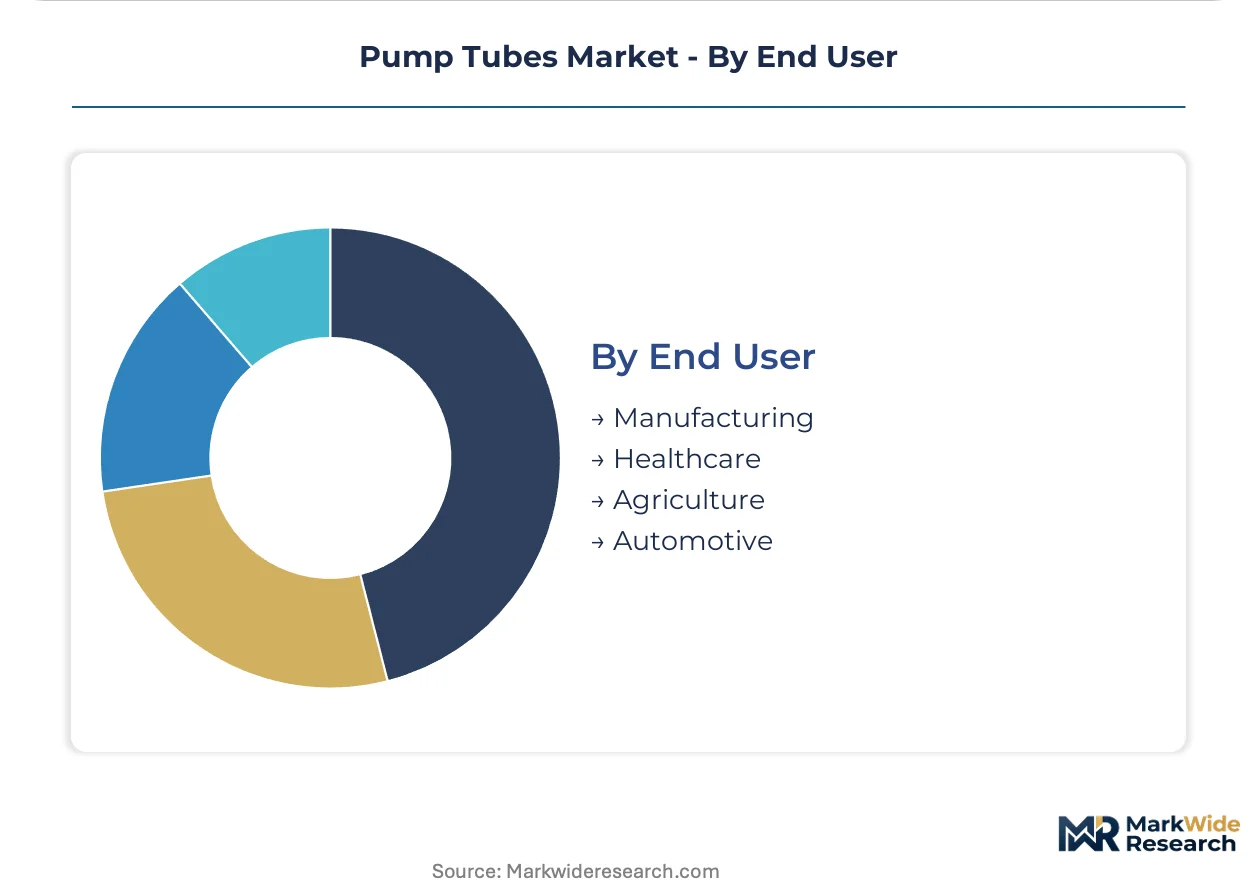
End User:
Supply concentration varies sharply by end-use certification burden, with healthcare and automotive demanding documented resin sourcing that excludes uncertified converters.
- Healthcare:Pharmaceutical manufacturing, diagnostic equipment, and medical device fluid pathways require USP Class VI and ISO 10993 biocompatibility validation. EU MDR notified body relationships and Swissmedic certifications concentrate supply among established European converters.
- Automotive:Battery electric vehicle thermal management and traditional powertrain fluid handling specify chemically resistant formulations with OEM tier-one qualification status. Munich and Stuttgart engineering centers drive specification development.
- Manufacturing:Industrial process equipment, chemical handling, and machinery lubrication systems present fragmented demand with price-sensitive procurement patterns.
- Agriculture:Irrigation, fertilization, and crop protection dispensing applications prioritize UV resistance and cost efficiency over precision certification.
Manufacturing retains volume leadership; healthcare holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss converters command 15-20% pricing premiums over North American peers due to EU MDR certification scarcity and Swissmedic cleanroom capacity constraints. This asymmetry concentrates specification-setting power in Alpine and Rhine corridor manufacturing clusters.
Germany
Stuttgart and Munich automotive engineering centers drive battery thermal management tube specifications for electric vehicle coolant circuits. REACH phthalate restrictions under ECHA guidance accelerate polyurethane displacement of legacy PVC in medical device fluid lines. Bavarian precision manufacturing clusters around Ingolstadt and Regensburg anchor peristaltic pump tube production for single-use bioprocessing systems.
Switzerland
Basel and Zurich pharmaceutical OEM corridors generate concentrated demand for Swissmedic-certified dispensing tubes with documented resin traceability. EU MDR Unique Device Identification mandates favor local converters with existing notified body relationships and blockchain-enabled lot code infrastructure. The Basel-Land canton hosts specialized cleanroom extrusion capacity serving Novartis and Roche contract manufacturers.
United States
FDA Title 21 CFR extractables testing requirements elevate compliance costs for pharmaceutical tube converters without in-house chromatography infrastructure. EPA per- and polyfluoroalkyl substance restrictions threaten fluoropolymer-lined product lines, redirecting material development toward silicone alternatives. New Jersey and Massachusetts biopharma clusters consolidate procurement through designated device suppliers rather than direct material sourcing.
India
CDSCO medical device rules harmonization and PLI scheme incentives attract contract manufacturing investment for export-oriented tube production. Hyderabad and Ahmedabad pharmaceutical packaging corridors expand cleanroom extrusion capacity to serve European and North American OEM qualification programs. Domestic demand from injectable drug manufacturers accelerates USP Class VI validation requirements among local converters.
France
ANSM pharmaceutical manufacturing oversight and REACH substance restrictions compress the supplier base for parenteral drug dispensing applications. Paris-Saclay biocluster specifications favor multi-layer barrier tubes with ethylene vinyl alcohol oxygen protection for biologic stability. Lyon and Strasbourg automotive suppliers develop battery coolant tubing for Stellantis and Renault electrification programs.
Pump Tubes Market Competitive Landscape
Concentration sits with integrated packaging multinationals and Swiss precision specialists that have secured EU MDR notified body relationships and captive resin sourcing agreements. The supplier base fragments across regional converters lacking cleanroom certification or documented polymer traceability. Two strategic archetypes dominate: scale-driven healthcare packaging conglomerates with global laminate expertise, and precision-focused Alpine specialists with Swissmedic-certified production. Competitive moves center on multi-layer coextrusion capacity expansion and backward integration into pharmaceutical-grade silicone feedstock.
Among North American packaging conglomerates, Berry Global and Sonoco Products occupy positions emphasizing blown-film scale and healthcare contract volume. Hoffmann Neopac anchors the Swiss precision tier with Basel corridor cleanroom certification. Amcor exemplifies the laminate-integrated archetype extending global healthcare packaging capabilities into adjacent pump tube categories. These three represent divergent competitive vectors: scale concentration, regulatory certification depth, and materials science breadth.
| Leading Market Players |
|---|
| Albea |
| Berry Global |
| Hoffmann Neopac |
| Viva Packaging |
| Montebello Packaging |
| Essel Propack |
| Sonoco Products |
| Amcor |
| World Wide Packaging |
| Others |
Value Network & Pricing Analysis
REACH-driven polyurethane displacement of legacy PVC simultaneously redraws raw material sourcing maps and compresses mid-tier converter margins as pharmaceutical OEMs in Germany and Switzerland demand documented resin traceability. German automotive clusters now specify thermoplastic elastomer formulations for battery thermal management, fragmenting procurement patterns between certified cleanroom suppliers and commodity extruders.
Pricing Analysis
The customization-premium spread separates Swissmedic-certified cleanroom production from catalog commodity tubes by factors exceeding two-to-one. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, volume scale, and barrier-layer complexity. Price differentiation hinges on EU MDR notified body relationships and captive silicone feedstock agreements. Pricing pressure stems from OEM vendor consolidation programs in Basel and Frankfurt that compress converter margins. Aftermarket fluid transfer buyers exhibit highest price sensitivity; pharmaceutical dispensing system integrators show lowest.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg container terminals amplify working capital requirements for Asian resin imports. Pharmaceutical-grade silicone feedstock concentrates in Germany, Switzerland, and the United States among four specialty chemical producers. Production draws from platinum-cured elastomer formulations, thermoplastic polyurethane pellets, and ethylene vinyl alcohol barrier resins. Single-source vulnerability sits with medical-grade silicone allocation during semiconductor sector demand spikes. Distribution runs through designated device suppliers rather than direct OEM material sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pump tube demand sits in early-cycle expansion as single-use bioprocessing adoption accelerates peristaltic pump specification across German pharmaceutical clusters.
For Market Incumbents: Consolidate cleanroom certification depth and captive resin sourcing to defend against REACH-driven material substitution threats. Backward integration into pharmaceutical-grade silicone feedstock secures allocation priority during semiconductor sector demand spikes. Capacity expansion in Swiss Basel-Land canton captures undersupplied Swissmedic-certified production relative to Novartis and Roche contract manufacturer demand. For New Entrants and Emerging Players: Differentiate on multi-layer coextrusion barrier technology for oxygen-sensitive biologic dispensing in Paris-Saclay and Swiss pharmaceutical corridors. White-space targets include Indian CDSCO-certified export production under PLI scheme incentives and integrated connector-tube assemblies with 3D-printed manifold interfaces. Target Swiss precision manufacturing corridor where cleanroom capacity remains structurally undersupplied. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with notified body relationships and blockchain-enabled lot traceability infrastructure. Long-term viability centers on regulatory chemistry restriction compliance rather than commodity scale. Acquisition target archetype: Swiss or German converters with Swissmedic certification and established pharmaceutical OEM dispensing system integration. Signal to watch: EU MDR notified body bottleneck resolution timelines as inflection indicator for new entrant viability.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Layer Coextrusion Capacity Expansion | Captures pharmaceutical OEM specification-setting roles for oxygen-sensitive biologic dispensing in Basel corridors. |
| Backward Integration into Silicone Feedstock | Secures allocation priority during semiconductor and solar sector demand spikes that strain specialty chemical supply. |
| Swissmedic Cleanroom Certification Investment | Unlocks contract manufacturing opportunities from Novartis and Roche operations in Basel-Land canton. |
| Blockchain-Enabled Lot Traceability Implementation | Satisfies EU MDR Unique Device Identification mandates and FDA 21 CFR documentation requirements. |
| Integrated Connector-Tube Assembly Development | Enables proprietary geometries that lock out catalog competitors through 3D-printed manifold interfaces. |
Research Methodology
Cross-validation between regulatory filing analysis and supply chain documentation anchors the qualitative findings in this study. Primary interviews with cleanroom extrusion plant managers, pharmaceutical OEM procurement leads, notified body certification specialists, and thermoplastic elastomer R&D directors combined with secondary validation from ECHA REACH substance restriction databases, Swissmedic device registrations, FDA 21 CFR guidance documents, and German automotive OEM technical specifications. Bottom-up and top-down triangulation reconciles converter capacity data with end-use demand segmentation.
Sensitivity analysis around REACH phthalate restriction implementation timelines and EU MDR notified body capacity constraints informs the analytical framework. Segmentation dimensions modeled include material grade tier, tube construction type, end-use application, and regional regulatory cluster across the projection horizon. CAGRs derive from installed base replacement cycles, OEM dispensing system qualification patterns, and pharmaceutical manufacturing capacity expansion trajectories. Industry-specific forecast inputs incorporate peristaltic pump adoption rates in single-use bioprocessing and battery electric vehicle thermal management system specifications.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity or EU MDR certification timeline normalization would require recalibration. Forecasts reflect assumptions regarding silicone feedstock allocation stability and pharmaceutical OEM vendor consolidation program persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
Latin America Pumps Market
Pumps and Control Devices
Chopper Pumps Market
Pumps and Control Devices
Melt & Gear Pump Market
Pumps and Control Devices
Air Breathing Hose Market
Pumps and Control Devices
Flow Back Equipment Market
Pumps and Control Devices
Industrial Aerators Market
Pumps and Control Devices
Europe Submersible Pump Market
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
Solar Pump Inverter Market
Pumps and Control Devices
Suction Pump Market
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Rotary Vane Vacuum Pump Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Pumps and Trigger Spray Market
Pumps and Control Devices
Commercial Booster Pumps Market