
 Global Solar-Powered Pump Market | 2026-2036
Global Solar-Powered Pump Market Size, Share, and Industry Trends Forecast 2026-2036
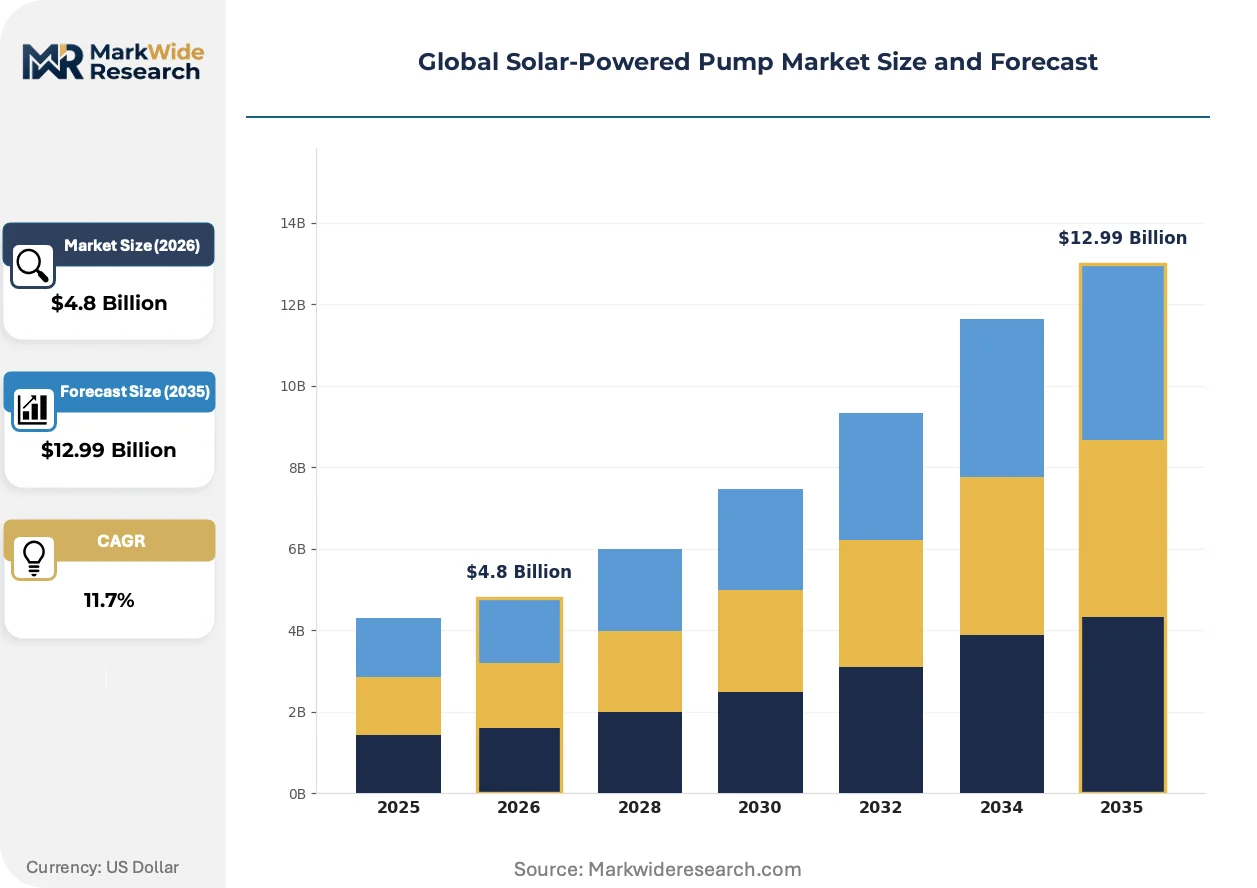
Global Solar-Powered Pump Market Outlook
Pay-as-you-go solar pump leasing is narrowing the capital barrier for smallholder farmers across emerging markets. Shakti Pumps (India) Limited leverages its domestic manufacturing scale to dominate rural distribution networks in South Asia. LORENTZ GmbH anchors its position through German-engineered DC motor technology optimized for off-grid reliability. Grundfos Holding A/S competes via intelligent cloud-connected pump controllers that reduce downtime in remote installations.
A solar-powered pump converts photovoltaic energy into mechanical torque to lift, transfer, or pressurize water without grid dependency, typically achieving 30-70 meters of dynamic head depending on motor configuration and array sizing. Submersible pumps lead installed capacity in deep-borehole applications across arid zones, while surface pumps sustain higher flow rates for open-source irrigation. Smart Controls represent the fastest-expanding technology segment as IoT-enabled variable frequency drives optimize solar array output against real-time water demand.
India's Ministry of New and Renewable Energy administers capital subsidy frameworks under PM-KUSUM, while Kenya's Rural Electrification Authority sets performance standards for off-grid solar irrigation assets. REACH compliance in Europe restricts certain semiconductor materials in motor controllers, altering supplier qualification pathways. Stakeholders must monitor how carbon border adjustment mechanisms and local content rules reshape competitive access across priority installation markets.
Market Dynamics
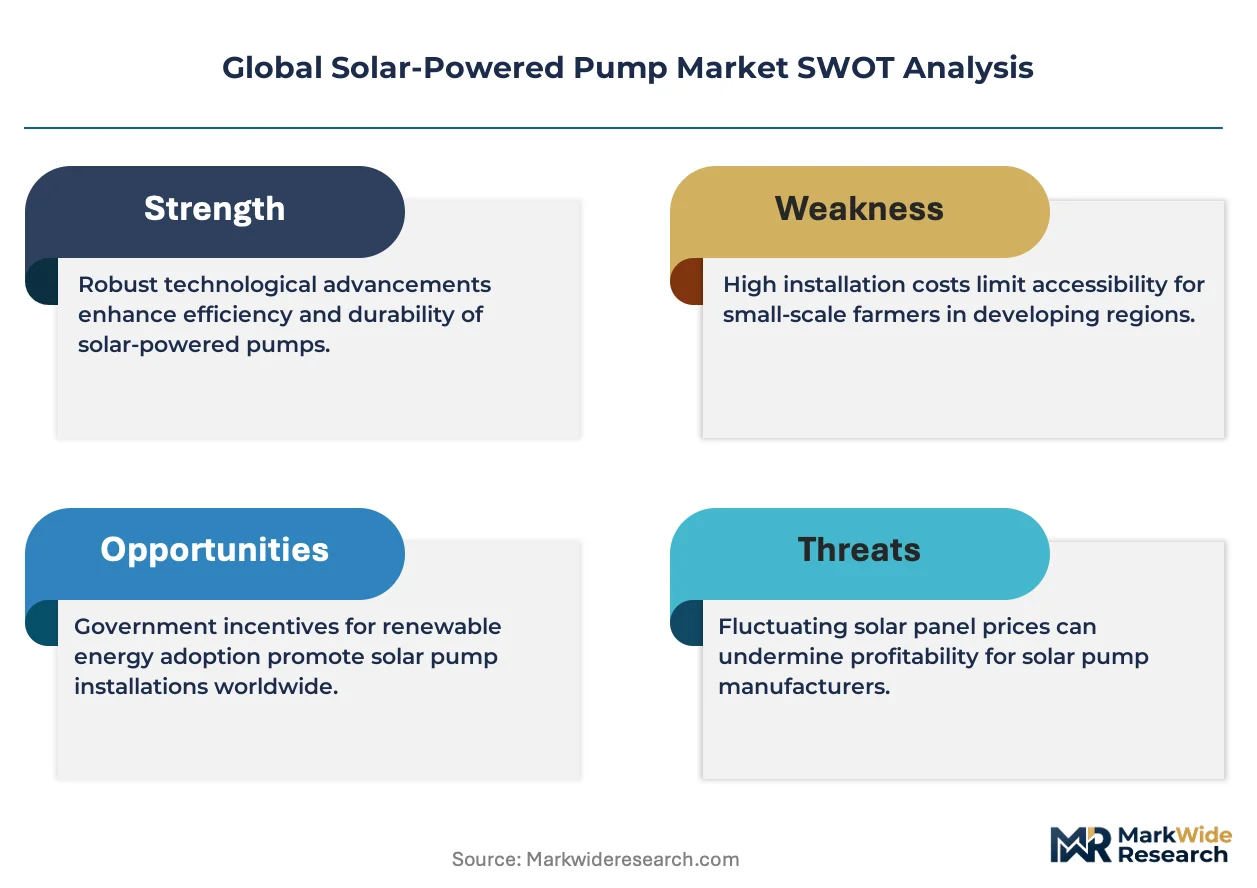
Feed-in tariffs and capital subsidy frameworks are compressing payback periods for solar irrigation assets, redirecting procurement decisions from diesel-powered alternatives toward photovoltaic systems with integrated variable frequency drives.
Growth Catalysts
- PM-KUSUM Scheme:India's component C provisions subsidize standalone solar pumps for off-grid farmers, cutting upfront capital requirements by up to sixty percent for eligible smallholders.
- DC Motor Efficiency Gains:Brushless permanent magnet designs now achieve conversion efficiencies above ninety percent, reducing array sizing requirements for equivalent hydraulic output.
- Brazilian Irrigation Modernization:The country's northeast drought polygon programs prioritize solar pumping for fruit export cooperatives, displacing grid-dependent centrifugal units.
Market Restraints
- Polysilicon Price Volatility:Module cost fluctuations tied to Chinese ingot wafer production constrain project finance predictability for commercial farm operators.
- Deep Borehole Technical Limits:Submersible configurations face head pressure constraints beyond one hundred meters, excluding high-elevation groundwater extraction applications.
- REACH Semiconductor Restrictions:European motor controller suppliers must reformulate power electronics to eliminate restricted rare-earth dopants, extending qualification timelines.
Strategic Opportunities
- Pay-as-You-Go Leasing:East African mobile money platforms enable hardware-as-a-service models for asset-light smallholders previously excluded from formal credit markets.
- Agrivoltaic Convergence:Dual-use arrays combining crop shading with pumping loads unlock marginal land economics for horticulture clusters in water-stressed Moroccan provinces.
- Smart Controller Mandates:Kenya's Rural Electrification Authority performance standards require remote monitoring capability, creating aftermarket retrofit demand for existing installed base.
Industry Challenges
- Photovoltaic Technician Scarcity:Rural service networks lack certified personnel for array diagnostics and inverter troubleshooting, inflating mean-time-to-repair metrics.
- Multi-Standard Certification Burden:Manufacturers face divergent efficiency testing protocols across BIS (India), INMETRO (Brazil), and IEC frameworks, fragmenting product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solar-Powered Pump Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Surface Pumps, Booster Pumps, Centrifugal Pumps Application: Agriculture, Irrigation, Water Supply, Wastewater Management Technology: Photovoltaic, Thermal Energy, Hybrid Systems, Smart Controls End User: Residential, Commercial, Industrial, Municipal |
| Companies Covered | Shakti Pumps (India) Limited, LORENTZ GmbH, Grundfos Holding A/S, Tata Power Solar Systems Ltd., KSB SE & Co. KGaA, Franklin Electric, Bright Solar Limited, Dankoff Solar, Waaree Energies Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solar-Powered Pump Market Strategic Shifts
Solar pump architectures are converging with digital agriculture platforms, embedding telemetry that transforms standalone hardware into data-generating nodes within precision irrigation networks.
Silicon carbide power semiconductors in motor inverters slash switching losses and thermal management mass. Large-scale horticulture operators in Spain and Australia are specifying these units for high-frequency pumping cycles. Conventional silicon IGBT-based controllers are rendering obsolete for premium-tier specifications above fifteen kilowatts.
REACH compliance deadlines in Europe are forcing reformulation of gate driver integrated circuits and magnetic core materials. German and Italian controller manufacturers are accelerating qualification of gallium nitride alternatives to maintain CE marking eligibility. Surface pump product lines targeting Mediterranean greenhouse operators face the steepest redesign cost exposure.
Cooperative procurement consortia are aggregating smallholder demand into volume tenders with standardized technical specifications. Kenyan flower export associations and Indian horticulture federations now contract directly with manufacturers, bypassing traditional agricultural equipment distributors. This channel compression is most pronounced in peri-urban vegetable supply belts surrounding Nairobi and Pune.
Global Solar-Powered Pump Market Segmentation
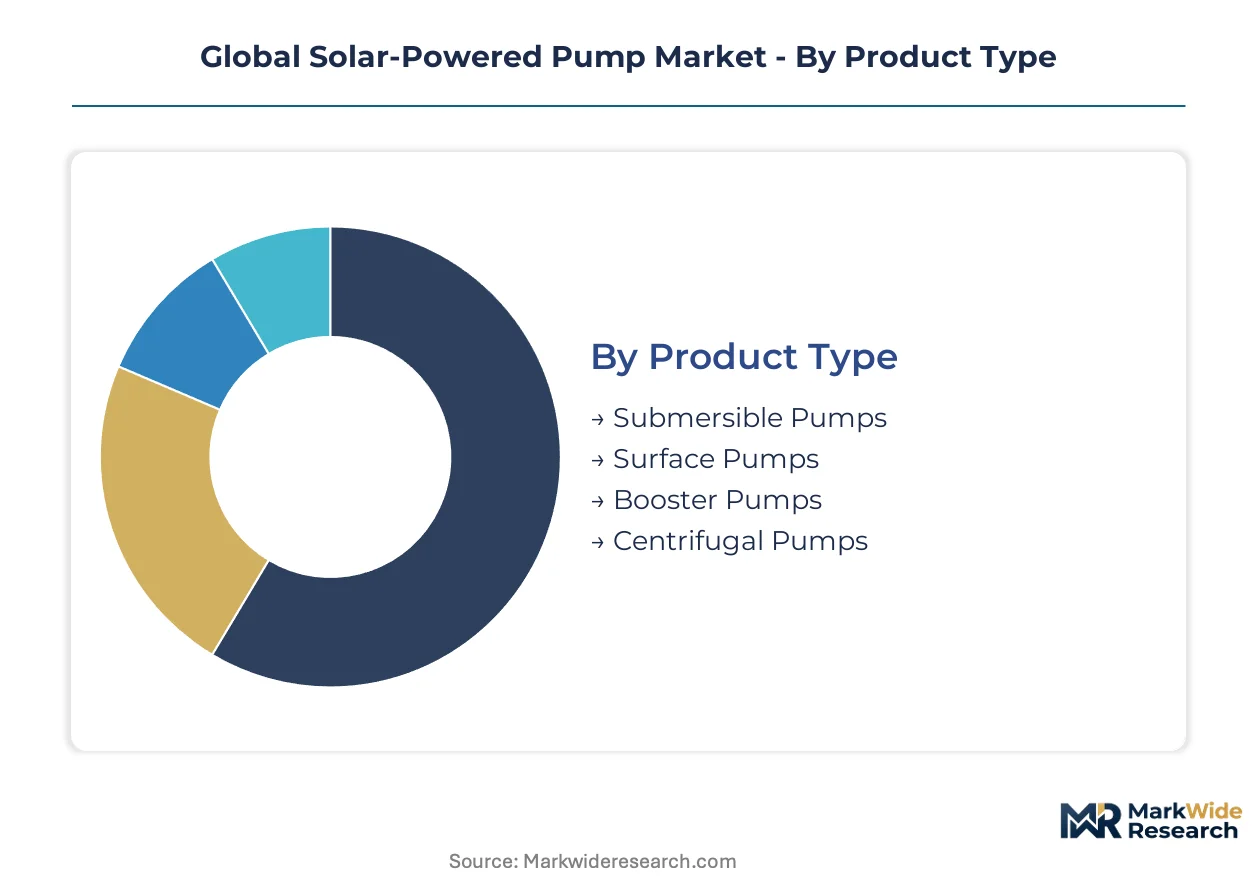
Segmentation in solar-powered pumping reveals distinct service intensity profiles. Submersible installations demand specialized borehole technicians and long-term subsea cable maintenance contracts. Surface pump deployments require less invasive servicing but higher frequency preventive maintenance schedules.
Product Type:
After-sales-service intensity varies dramatically across pump architectures. Submersible units require underwater retrieval capabilities and pressure-sealed component replacement. Surface pumps concentrate maintenance at accessible mounting points.
- Submersible Pumps:These units deploy below groundwater level with hermetically sealed motor housings rated for continuous immersion. Deep-borehole extraction across India's drought-prone Marathwada region and Kenya's Turkana basin drives procurement for irrigation cooperatives facing declining water tables. Motor rewinding and cable splicing dominate lifetime service costs.
- Surface Pumps:Mounted above water sources, these configurations achieve higher flow rates at lower head pressure. Brazil's northeast fruit export belt specifies surface-mounted centrifugal units for open-channel irrigation. Accessibility reduces mean-time-to-repair but increases exposure to environmental degradation.
- Booster Pumps:Pressure-amplification units for distribution networks in peri-urban Moroccan horticulture clusters.
- Centrifugal Pumps:Radial flow designs serving high-volume, low-lift applications in Chinese greenhouse agriculture.
Submersible Pumps holds the largest share; momentum sits with Surface Pumps.
Application:
Cost tier stratification separates capital-intensive commercial irrigation from subsidized smallholder programs. Premium-tier specifications cluster in export-oriented horticulture. Economy deployments dominate domestic food security projects.
- Agriculture:Crop production applications span rain-fed supplementation to full irrigation dependency. India's PM-KUSUM component C targets 3.5 million standalone solar pumps for smallholder farmers. Subsidy structures cap equipment specifications at economy-tier DC motor configurations.
- Irrigation:Dedicated water conveyance systems integrate with drip and sprinkler distribution networks. Spain's Almería greenhouse belt specifies variable frequency drive compatibility for precision scheduling. Water-use efficiency mandates in water-stressed jurisdictions accelerate smart controller attachment rates.
- Water Supply:Rural potable water schemes in Sub-Saharan Africa leverage solar pumping for off-grid community taps.
- Wastewater Management:Solar-powered lift stations for decentralized treatment in peri-urban Indian clusters.
Agriculture commands the dominant share; Irrigation demonstrates the steepest expansion trajectory.
Technology:
Volume concentration favors mature photovoltaic architectures over emerging thermal alternatives. Silicon module supply scale drives cost competitiveness. Hybrid configurations remain niche due to control system complexity.
- Photovoltaic:Direct current motor coupling with crystalline silicon arrays constitutes the installed base majority. Conversion efficiencies above 22% in monocrystalline modules reduce array footprint requirements. India's domestic cell manufacturing under PLI schemes compresses landed costs for rural distribution networks.
- Smart Controls:IoT-enabled variable frequency drives optimize motor speed against real-time solar irradiance and water demand. Kenya's Rural Electrification Authority mandates remote monitoring capability for subsidy eligibility. Cloud-connected diagnostics reduce technician dispatch frequency for dispersed installations.
- Thermal Energy:Concentrating solar thermal systems with Stirling engine drives for high-head applications in Australian remote mining.
- Hybrid Systems:Grid-tied with battery backup configurations for critical water supply in Chinese livestock operations.
Photovoltaic retains the dominant position; Smart Controls are gaining share fastest.
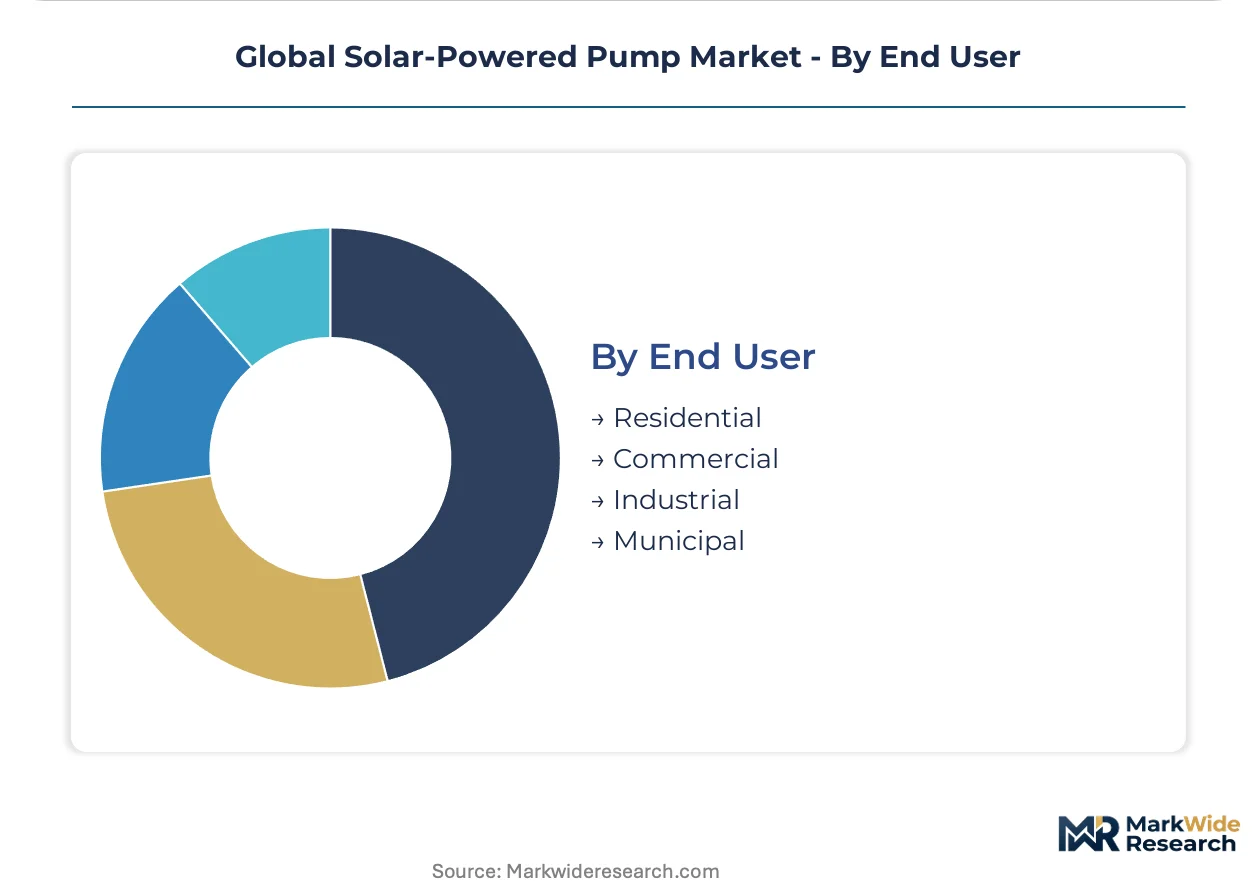
End User:
Customer type determines procurement channel and financing structure. Municipal tenders emphasize lifecycle cost and local content compliance. Residential purchases flow through agricultural extension programs with capital subsidy attachment.
- Commercial:Horticulture enterprises and agricultural cooperatives specify performance-guaranteed installations with service level agreements. Kenyan flower export associations aggregate demand into manufacturer-direct contracts. Volume procurement bypasses traditional equipment distributors.
- Municipal:Public water utilities in Morocco's OCP irrigation perimeters deploy solar pumping for phosphate processing water supply. Tender specifications require INMETRO or BIS certification equivalence. Local content rules favor regional assembly over complete unit import.
- Residential:Individual smallholder farmers accessing PM-KUSUM subsidies in India's Maharashtra and Gujarat states.
- Industrial:Process water for Brazilian ethanol distilleries and mining operations in Chile's Atacama.
Commercial segment leads value capture; Municipal procurement is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smallholder cooperatives and commercial horticulture enterprises concentrate procurement across water-stressed agricultural belts, with subsidy eligibility and export market access determining technology specification tiers.
India
Maharashtra and Gujarat smallholders drive volume demand through PM-KUSUM component C subsidies that cap equipment at economy-tier DC configurations. The Ministry of New and Renewable Energy administers capital subsidy frameworks cutting upfront costs by up to sixty percent for eligible farmers. Marathwada's drought-prone districts concentrate submersible pump deployment as irrigation cooperatives confront declining water tables.
China
Greenhouse agriculture operators in Shandong and Hebei provinces specify high-volume centrifugal units for precision irrigation networks serving domestic vegetable supply chains. MIIT domestic content rules under dual carbon goals favor locally manufactured photovoltaic modules and motor controllers. The Yangtze River Delta clusters smart controller production for export-tier specifications.
Brazil
Fruit export cooperatives in Pernambuco and Ceará states displace grid-dependent centrifugal systems through northeast drought polygon modernization programs. INMETRO certification requirements govern tender specifications for public irrigation perimeter deployments. São Paulo-based equipment distributors face channel compression as cooperatives contract directly with manufacturers.
Kenya
Flower export associations around Lake Naivasha aggregate smallholder demand into volume tenders bypassing traditional agricultural equipment channels. The Rural Electrification Authority mandates remote monitoring capability for all subsidy-eligible solar irrigation assets. Turkana basin deep-borehole extraction projects drive submersible pump procurement for pastoralist cooperatives.
Morocco
Phosphate processing water supply in OCP irrigation perimeters deploys municipal-scale solar pumping with local content rules favoring regional assembly. Agrivoltaic convergence trials in water-stressed provinces unlock marginal land economics for horticulture clusters. Casablanca-Rabat corridor distributors specify INMETRO or BIS certification equivalence for cross-border supply.
Global Solar-Powered Pump Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented rural distribution networks where subsidy eligibility and certification compliance determine market access. The vendor base clusters around three strategic archetypes: domestic manufacturing scale leaders leveraging PLI scheme benefits, German-engineered DC motor specialists optimizing for off-grid reliability, and intelligent controller providers embedding cloud-connected diagnostics. Competitive moves concentrate on cooperative procurement consortia aggregation and silicon carbide power semiconductor qualification for premium-tier specifications.
Within the domestic manufacturing archetype, Shakti Pumps (India) Limited exemplifies scale-driven rural network penetration, while LORENTZ GmbH anchors the German-engineered reliability tier. Grundfos Holding A/S occupies a position representing intelligent cloud-connected pump controller specialization. These three entities collectively illustrate the competitive vectors shaping procurement decisions across subsidy-dependent smallholder markets and premium-tier commercial irrigation specifications.
| Leading Market Players |
|---|
| Shakti Pumps (India) Limited |
| LORENTZ GmbH |
| Grundfos Holding A/S |
| Tata Power Solar Systems Ltd. |
| KSB SE & Co. KGaA |
| Franklin Electric |
| Bright Solar Limited |
| Dankoff Solar |
| Waaree Energies Ltd |
| Others |
Value Chain & Pricing Dynamics
The Nhava Sheva-Mombasa maritime corridor's freight cost dynamics compress margins for Indian motor controller suppliers serving East African cooperatives while amplifying price differentiation between certified premium-tier and economy-grade DC pump configurations across subsidy-dependent procurement channels.
Pricing Analysis
Cost-plus contracts indexed to polysilicon spot markets dominate commercial farm procurement, with module price volatility passing through to installed system quotes within sixty-day adjustment windows. Three-tier pricing structure across premium, standard, and economy levels separates cloud-connected smart controllers with remote diagnostics from basic variable frequency drives and subsidized fixed-speed units. Cost compression in economy-tier hardware is intensifying because domestic manufacturing scale under India's PLI scheme floods rural distribution networks with below-cost entrants. Smallholder farmers accessing PM-KUSUM subsidies exhibit highest price sensitivity, while Kenyan flower export cooperatives prioritize performance guarantees over unit cost.
Supply Chain Analysis
Extended payment terms from sixty to ninety days characterize supplier financing arrangements for Indian distributors serving Maharashtra's irrigation cooperatives, with supply-chain finance facilities bridging working capital gaps during monsoon procurement peaks. Manufacturing concentrates in India, China, and Germany, with crystalline silicon modules drawing from polysilicon ingot wafer production anchored in Xinjiang and polysilicon purification capacity in the Yangtze River Delta. Permanent magnet motor assemblies rest on neodymium-dysprosium supply from Chinese rare-earth separation facilities, creating single-source vulnerability for brushless DC configurations. Distribution runs through agricultural equipment dealerships in South Asia and direct manufacturer contracts with cooperative consortia in Sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar-powered pump market rewards service-attach strategies as remote monitoring subscriptions and preventive maintenance contracts expand faster than hardware shipments across Kenya's mandate-driven retrofit demand.
For Market Incumbents: Build switching-cost moats through embedded telemetry platforms that lock cooperatives into proprietary cloud diagnostics ecosystems. Defend against Chinese controller manufacturers by accelerating silicon carbide inverter qualification for premium-tier specifications above fifteen kilowatts. Expand captive supply of hermetically sealed motor housings to secure submersible pump margins against raw material volatility. For New Entrants and Emerging Players: Build out pay-as-you-go leasing infrastructure targeting East African smallholders excluded from formal credit markets through mobile money integration. The most penetrable white-space sits in agrivoltaic convergence pilots across Morocco's water-stressed provinces, where dual-use arrays remain undersupplied. Partner with horticulture federations for cooperative procurement aggregation bypassing traditional equipment distributors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded solar pump divisions lacking smart controller capabilities. Long-term viability hinges on software-defined service revenue scaling faster than hardware replacement cycles. Watch for Kenya's Rural Electrification Authority expanding remote monitoring mandates to neighboring jurisdictions as the inflection signal for aftermarket retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Controller Mandate Compliance | Kenya's Rural Electrification Authority standards create aftermarket retrofit demand across existing installed base. |
| Silicon Carbide Inverter Qualification | German and Italian manufacturers maintain CE marking eligibility while reducing switching losses for premium-tier specifications. |
| Cooperative Procurement Aggregation | Kenyan flower export associations and Indian horticulture federations bypass traditional agricultural equipment distributors. |
| Pay-as-You-Go Leasing Infrastructure | East African mobile money platforms enable hardware-as-a-service models for asset-light smallholder farmers. |
| Agrivoltaic Convergence Development | Dual-use arrays combining crop shading with pumping loads unlock marginal land economics in Moroccan provinces. |
Study Parameters
Operator-level perspectives from irrigation cooperative managers, photovoltaic technician network heads, agricultural equipment dealership owners, and motor controller R&D directors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against BIS certification records, MNRE subsidy disbursement databases, Kenya Rural Electrification Authority performance standard filings, and customs trade data tracking module imports through Nhava Sheva and Mombasa ports. Bottom-up unit economics from smallholder deployment clusters triangulated against top-down market sizing from manufacturer shipment disclosures.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling spanning pump architecture, application intensity, technology tier, and end-user procurement channel. CAGRs derived from fitted growth curves against historical subsidy penetration rates and irrigation modernization program commitments. Forecast inputs incorporated polysilicon price trajectory assumptions and smart controller attachment rate elasticity against water-use efficiency mandates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese module manufacturers with integrated controller production would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Pump Tubes Market
Pumps and Control Devices
Hydraulic Dosing Pump Market
Pumps and Control Devices
Twin Screw Pumps Market
Pumps and Control Devices
Southeast Asia Submersible Pumps Market
Pumps and Control Devices
Reverse Osmosis Pump Market
Pumps and Control Devices
Vertical Turbine Pumps Market
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
Industrial Aerators Market
Pumps and Control Devices
Marine Pump Market
Pumps and Control Devices
Subsea Pump System Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Sanitary Pumps Market
Pumps and Control Devices
Pump Over Tanks Market
Pumps and Control Devices
Latin America Pumps Market
Pumps and Control Devices
Intelligent Pump Market
Pumps and Control Devices
United States Positive Displacement Pumps Market