
 North America Non-Structural Stainless Steel Fasteners Market | 2026-2036
North America Non-Structural Stainless Steel Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
North America Non-Structural Stainless Steel Fasteners Market Analytics
Carbon steel with zinc plating is realigning toward 316-grade stainless in coastal and chemical-exposure applications as lifecycle cost economics favor corrosion immunity over first-cost savings. Simpson Strong-Tie Company, Inc. dominates engineered structural connector systems and leverages its specification relationships with building code officials. STANLEY BLACK & DECKER, INC. anchors broad distribution through retail and professional channels, while Star Stainless Steel specializes in marine-grade inventory depth and custom alloy sourcing.
North America non-structural stainless steel fasteners encompass corrosion-resistant threaded and non-threaded hardware manufactured from austenitic or martensitic alloys, typically passivated to ASTM A967 standards, designed for load-bearing restraint in assemblies where structural failure does not risk human safety. Screws lead product type volume due to proliferation of composite decking and exterior trim installations, while 316-grade material commands the strongest margin pool from marine and coastal specification lock-in. Automotive end users represent the fastest-growing demand segment as electric vehicle battery tray assemblies require non-magnetic, corrosion-proof fastening solutions.
FCC equipment authorization rules indirectly shape fastener demand by governing enclosure integrity for telecommunications hardware deployed in outdoor environments, while EPA stormwater regulations mandate durable anchoring for permeable pavement and green infrastructure. OSHA fall-protection standards for construction elevate specification rigor for guardrail and decking hardware. Stakeholders must monitor evolving building code amendments in hurricane-prone states and automotive platform electrification timelines to calibrate alloy grade portfolios and inventory positioning.
Market Dynamics
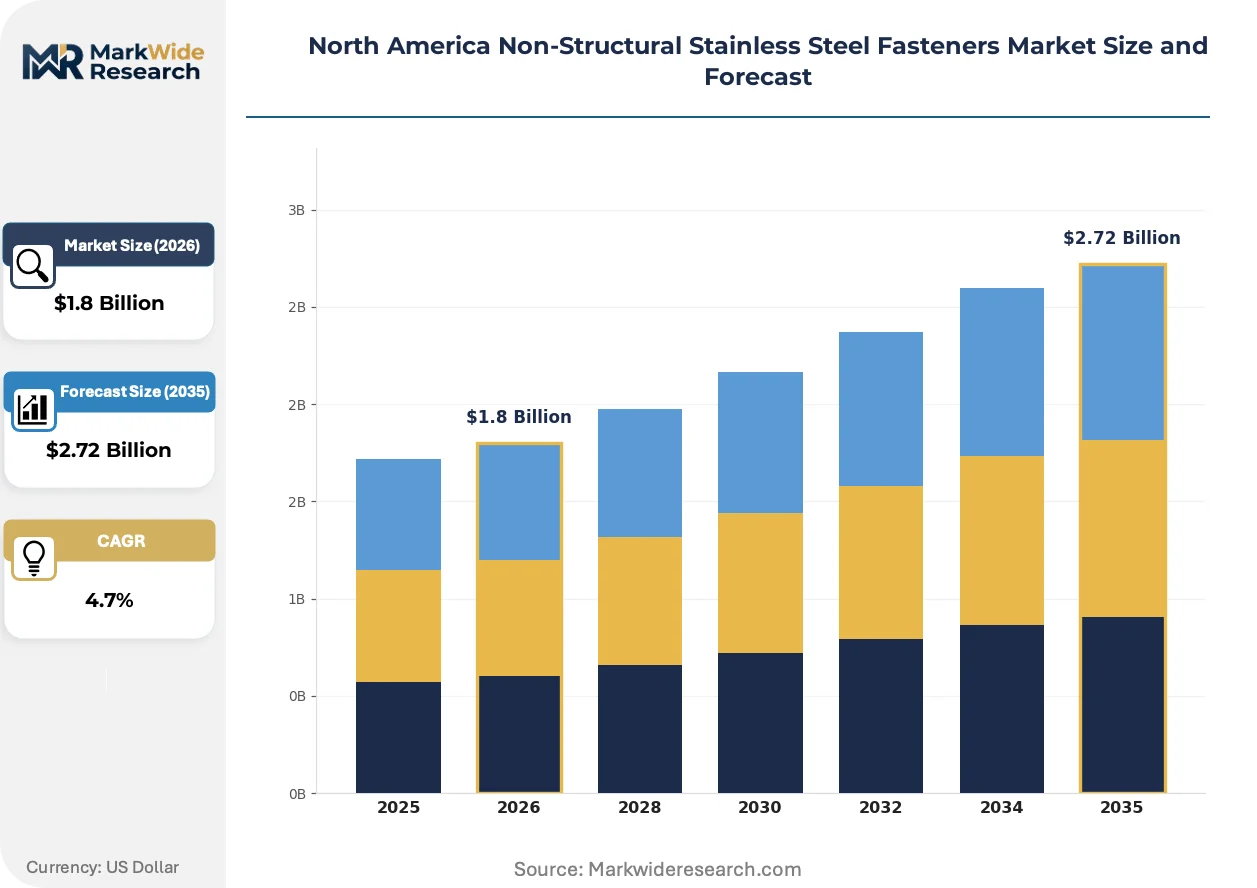
The North America non-structural stainless steel fasteners market is undergoing specification realignment as coastal building codes and electric vehicle manufacturing requirements elevate corrosion-resistant alloy grades over traditional carbon steel alternatives.
Growth Catalysts
- EPA volatile organic compound regulations:Tightened coating standards for fasteners are accelerating specification shifts toward pre-passivated stainless grades that eliminate secondary finishing requirements.
- Electric vehicle battery tray assemblies:Automotive manufacturers require non-magnetic, corrosion-proof fastening solutions that withstand electrolyte exposure and thermal cycling.
- Hurricane-resistant construction codes:Southeastern United States waterfront development is driving premium fastener procurement for marine decking and coastal infrastructure.
Market Restraints
- Nickel price volatility:Austenitic stainless production costs fluctuate with London Metal Exchange nickel contract movements, compressing margin stability for distributors.
- Import concentration risk:Cold-heading wire rod supply concentrates among Asian mill complexes, exposing North American fastener manufacturers to ocean freight and tariff uncertainty.
- Carbon steel substitution economics:Zinc-plated hardware retains first-cost advantage in interior applications where corrosion exposure remains minimal.
Strategic Opportunities
- Permeable pavement anchoring:EPA stormwater regulations mandate durable fastening for green infrastructure installations across municipal procurement programs.
- Telecommunications enclosure integrity:FCC equipment authorization rules govern outdoor hardware deployment, creating specification pathways for passivated stainless fasteners in 5G infrastructure.
- Custom alloy sourcing:Marine-grade inventory depth with specialized molybdenum content addresses salt-air corrosion resistance for yacht builders and marina operators.
Industry Challenges
- ASTM A967 certification timelines:Passivation validation protocols extend qualification periods for new supplier onboarding, slowing procurement agility.
- Alloy grade portfolio complexity:Inventory positioning across 304, 316, and duplex grades strains working capital as end-use specifications fragment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Non-Structural Stainless Steel Fasteners Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolts, Nuts, Washers, Screws End User: Construction, Automotive, Aerospace, Manufacturing Material Grade: 304, 316, 410, 430 Application: Fastening, Joining, Assembly, Repair |
| Companies Covered | Simpson Strong-Tie Company, Inc., Associated Fastening Products, Inc., Starborn Industries, Inc., FastenMaster, The Hillman Group, Inc., STANLEY BLACK & DECKER, INC., KD FASTENERS, INC., Camo Fasteners, Star Stainless Steel, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Non-Structural Stainless Steel Fasteners Market Evolving Landscape
Material science advances and specification digitization are compressing traditional procurement cycles while elevating performance verification standards across coastal and automotive applications.
Additive manufacturing of complex fastener geometries is converging with topology-optimized designs that reduce material weight while maintaining clamp load requirements. Aerospace and motorsport suppliers are piloting electron beam melting for titanium-aluminide threaded components. This convergence is enabling batch-size-one production economics that threaten traditional cold-heading volume thresholds.
OSHA fall-protection standards for construction are elevating specification rigor for guardrail and decking hardware through documented load-rating requirements. Third-party testing laboratories now certify non-structural fasteners to ICC-ES acceptance criteria. Coastal contractors in Florida and the Carolinas are responding by mandating mill test reports for every lot delivered to job sites.
Specification databases are displacing traditional catalog-based procurement as engineered wood product manufacturers embed fastener schedules directly into digital building models. Simpson Strong-Tie and competing connector system providers now distribute BIM-compatible hardware libraries. This behavioral shift is most visible in multi-family residential construction across Texas and California, where design-build contracts compress material selection windows.
North America Non-Structural Stainless Steel Fasteners Market Segmentation
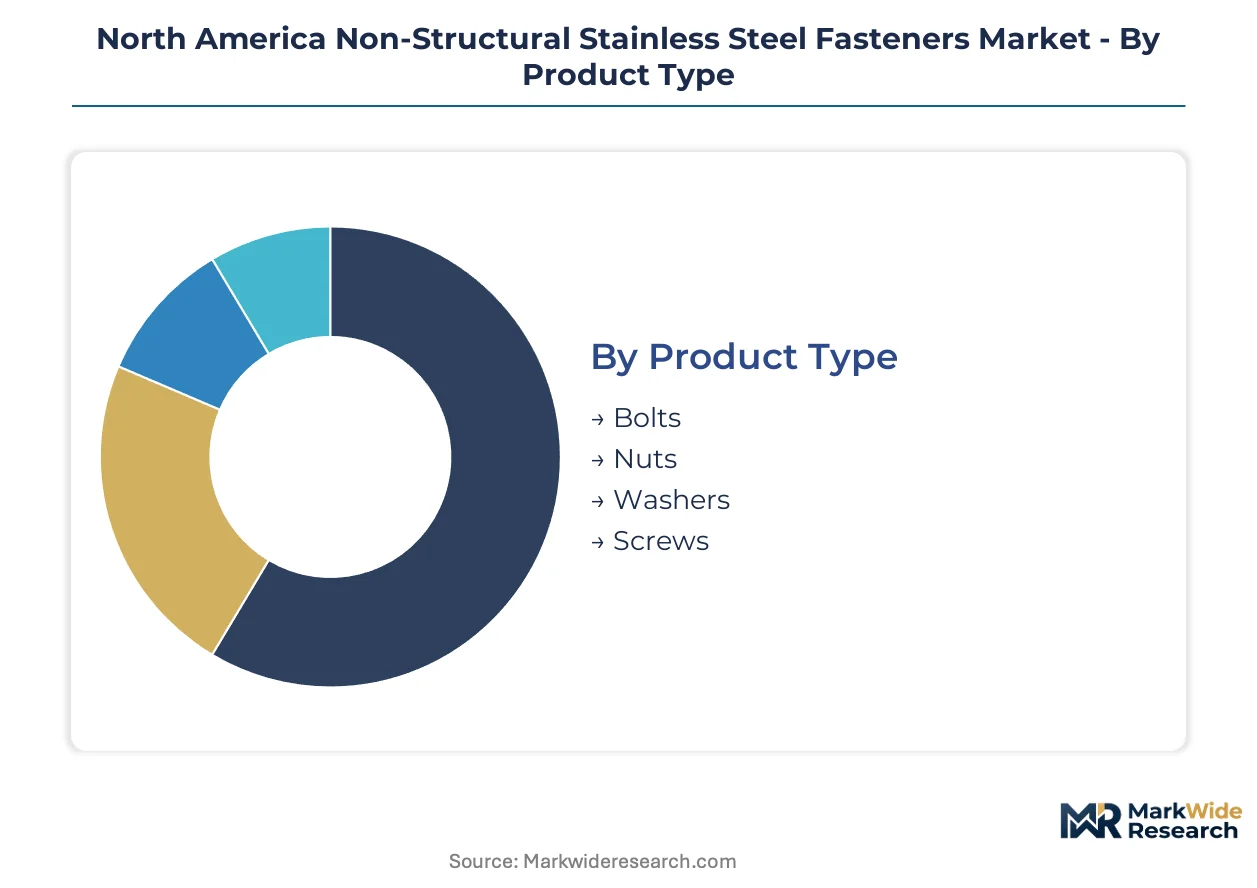
Specification fragmentation across North American non-structural stainless steel fasteners demands granular segmentation. End-use corrosion exposure, alloy chemistry, and installation method each dictate procurement priorities that separate premium-grade coastal contractors from interior manufacturing buyers.
Product Type:
Volume concentration and margin capture diverge sharply based on installation complexity and replacement frequency.
- Screws:Self-tapping and thread-forming designs dominate composite decking and exterior trim installations across Florida and Carolina coastal counties. Hurricane-resistant building codes mandate corrosion-proof fastening for elevated structures exposed to salt-air cycling.
- Bolts:Hex-head and carriage configurations anchor guardrail systems and marine hardware per OSHA fall-protection standards. Third-party ICC-ES certification now accompanies most lot deliveries to Southeastern job sites.
- Nuts:Locking and jam varieties secure battery tray assemblies in electric vehicle manufacturing, where non-magnetic properties prevent electrical interference.
- Washers:Flat, lock, and fender types distribute clamp loads across permeable pavement anchoring systems mandated by EPA stormwater regulations.
Screws lead volumes today; bolts are gaining share fastest in coastal infrastructure procurement.
End User:
Regulatory exposure and lifecycle cost horizons separate specification behavior across buyer categories.
- Construction:Multi-family residential and commercial contractors in Texas and California specify BIM-compatible hardware libraries. Digital building models now embed fastener schedules directly, compressing material selection windows.
- Automotive:Electric vehicle battery tray assemblies require non-magnetic, corrosion-proof solutions that withstand electrolyte exposure. Thermal cycling resistance distinguishes qualified suppliers from commodity distributors.
- Aerospace:Additive manufacturing pilots for titanium-aluminide threaded components target weight reduction while maintaining clamp load requirements. Topology-optimized designs threaten traditional cold-heading volume thresholds.
- Manufacturing:General industrial procurement balances first-cost economics against maintenance access constraints. Interior applications with minimal corrosion exposure retain zinc-plated carbon steel alternatives.
Construction leads volumes today; automotive is expanding most quickly on electrification timelines.
Material Grade:
Molybdenum content and passivation protocols determine salt-air immunity and certification eligibility.
- 316:Austenitic alloy with 2-3% molybdenum content commands premium positioning for marina operators and yacht builders. Pre-passivated finishes eliminate secondary coating requirements under tightened EPA volatile organic compound regulations.
- 304:Standard 18/8 chromium-nickel composition serves interior manufacturing and general construction where chloride exposure remains limited. ASTM A967 certification timelines extend qualification periods for new supplier onboarding.
- 410:Martensitic heat-treatable grade offers hardness for wear-resistant applications with moderate corrosion requirements.
- 430:Ferritic chromium alloy provides cost positioning for decorative and non-structural interior fastening.
304 leads volumes today; 316 is climbing the fastest on coastal specification lock-in.
Application:
Functional purpose dictates torque requirements, reusability expectations, and inspection protocols.
- Fastening:Primary load restraint in guardrail and decking hardware carries documented load-rating requirements per OSHA standards. Mill test reports accompany every lot to Florida and Carolina job sites.
- Joining:Permanent connections in telecommunications enclosures face FCC equipment authorization rules governing outdoor hardware integrity. Passivated stainless grades satisfy enclosure sealing specifications.
- Assembly:Production-line installation of electric vehicle components demands consistent torque-tension relationships and non-magnetic properties.
- Repair:Field replacement of corroded hardware in marine environments requires compatibility with existing passivated surfaces and galvanic isolation considerations.
Fastening leads volumes today; joining is gaining share fastest on 5G infrastructure deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Southeastern United States anchors North American demand for corrosion-resistant fastening hardware. Hurricane-resistant building codes and waterfront development concentrate procurement in coastal counties from Florida through the Carolinas.
United States
Electric vehicle battery tray assembly lines in Michigan and Ohio require non-magnetic, corrosion-proof fastening solutions. EPA volatile organic compound regulations for coatings are accelerating specification shifts toward pre-passivated stainless grades. Coastal contractors in Florida and the Carolinas now mandate mill test reports for every lot delivered to job sites.
Canada
Green infrastructure installations across Ontario and British Columbia drive demand for durable anchoring systems in permeable pavement applications. Health Canada environmental guidelines align with EPA stormwater regulations, reinforcing corrosion-resistant material specifications. Marine decking projects in Vancouver and Victoria prioritize 316-grade alloys for salt-air immunity.
Mexico
Automotive manufacturing clusters in Nuevo León and Baja California are expanding electrification timelines, requiring thermal-cycling-resistant hardware. Mexico's federal environmental regulations are tightening industrial coating standards, favoring pre-finished stainless alternatives. Assembly plants in Tijuana and Monterrey are qualifying new fastener suppliers for battery platform production.
North America Non-Structural Stainless Steel Fasteners Market Competitive Landscape
Global majors compete with regional champions across distribution channels and specification relationships. The vendor base stratifies between engineered connector system providers, broad-line tool and hardware distributors, and marine-grade specialists with custom alloy sourcing capabilities. Three archetypes dominate: specification-driven engineering houses, scale-driven retail distributors, and niche marine specialists. Competitive moves center on BIM-compatible digital libraries and backward integration into cold-heading wire rod supply.
Among specification-driven engineering houses, Simpson Strong-Tie Company, Inc. exemplifies the code-official relationship archetype, while STANLEY BLACK & DECKER, INC. anchors the scale-driven retail distribution tier. Star Stainless Steel occupies a position within the marine-grade specialist segment, representing inventory depth in salt-air corrosion-resistant alloys.
| Leading Market Players |
|---|
| Simpson Strong-Tie Company, Inc. |
| Associated Fastening Products, Inc. |
| Starborn Industries, Inc. |
| FastenMaster |
| The Hillman Group, Inc. |
| STANLEY BLACK & DECKER, INC. |
| KD FASTENERS, INC. |
| Camo Fasteners |
| Star Stainless Steel |
| Others |
Value Network & Pricing Analysis
Coastal contractors in Florida and the Carolinas anchor procurement volume for premium 316-grade fasteners, locking in contract-based long-term offtake agreements that insulate qualified suppliers from spot-market nickel volatility. This buyer concentration rewards ASTM A967-certified mills with pricing power while compressing margins for distributors lacking direct code-official relationships.
Pricing Analysis
Input-cost pass-through from London Metal Exchange nickel contracts governs austenitic stainless pricing, with molybdenum content differentials separating 304 from 316-grade quotations. Three-tier pricing structure across marine-certified, construction-standard, and general-industrial levels reflects certification investment and lot-traceability depth. Pricing pressure stems from carbon steel substitution in interior applications where corrosion exposure remains minimal. General manufacturing buyers exhibit highest price sensitivity, while yacht builders and marina operators accept premium positioning for salt-air immunity.
Supply Chain Analysis
Domestic-content mandates in US federal procurement programs are reshaping sourcing patterns for infrastructure-grade fasteners. Cold-heading wire rod supply concentrates in China, South Korea, and Japan, with North American fastener manufacturers drawing from Asian mill complexes for austenitic stainless feedstock. Nickel and molybdenum alloying elements create raw material dependencies tethered to mining output from Indonesia and Chile. Tariff exposure on Chinese-origin rod strains margin stability. Distribution runs through specification-driven engineering houses, broad-line retail distributors, and marine-grade specialists with custom alloy sourcing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America non-structural stainless steel fasteners market functions as a stable compounder, with hurricane-resistant building code amendments in Southeastern states providing durable demand tailwinds regardless of cyclical construction volatility.
For Market Incumbents: Anticipate specification digitization compressing traditional catalog-based procurement cycles. Defend position by deepening BIM-compatible hardware library investments and securing backward integration into cold-heading wire rod supply. Carbon steel substitution economics in interior applications represent the primary margin threat. Certification investment in ASTM A967 validation protocols creates switching costs that protect share. For New Entrants and Emerging Players: Electric vehicle battery tray assemblers in Michigan and Ohio represent the most penetrable buyer archetype, as electrification timelines force rapid supplier qualification outside established automotive fastener relationships. Target thermal-cycling-resistant hardware with documented non-magnetic properties. Custom alloy sourcing partnerships with molybdenum-specialist mills provide differentiation against commodity distributors. Direct technical sales engagement with OEM platform engineers outperforms traditional channel distribution for this segment. For Investors and Strategic Acquirers: Engineered connector system providers are the most active acquirer in this space, seeking specification relationships with building code officials. The five-to-ten-year viability window favors platforms with coastal infrastructure exposure over interior manufacturing-dependent distributors. Acquisition target archetype: marine-grade specialists with 316 inventory depth and custom alloy sourcing capabilities. Monitor EPA volatile organic compound enforcement actions as inflection indicator for pre-passivated stainless grade acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold-Heading Wire Rod | Captive supply of austenitic stainless feedstock insulates margin from LME nickel volatility and tariff exposure. |
| BIM-Compatible Hardware Library Expansion | Specification databases in Texas and California multi-family residential construction compress material selection windows. |
| ASTM A967 Certification Investment | Passivation validation protocols extend switching costs and accelerate new supplier onboarding timelines. |
| Custom Alloy Sourcing Partnerships | Specialized molybdenum content addresses salt-air corrosion resistance for yacht builders and marina operators. |
| Direct OEM Platform Engineering Engagement | Electric vehicle battery tray assemblers in Michigan and Ohio require rapid qualification outside traditional channels. |
Research Methodology
Multiple input streams — primary interviews with fastener procurement managers at coastal contractors and electric vehicle OEMs, trade data from USITC and Statistics Canada, and SEC filings from listed hardware distributors — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from EPA enforcement databases, ICC-ES acceptance criteria documentation, and regional building code amendment records. Stakeholder roles engaged included specification engineers at engineered wood product manufacturers, marine decking contractors in Florida and Carolina coastal counties, and automotive platform engineers at battery assembly facilities.
Historical volume trajectories were cross-referenced against panel input from distributor inventory managers and mill sales directors to construct the analytical framework. Segmentation dimensions modeled encompass product type, material grade chemistry, end-use corrosion exposure, and regional specification intensity. CAGRs were derived from alloy-grade demand elasticity and electrification timeline assumptions. Forecast inputs included EPA volatile organic compound regulatory enforcement schedules and hurricane-resistant building code adoption patterns across Southeastern states.
Underlying measurement precision varies by segment; automotive battery tray applications and coastal construction procurement carry tighter precision than general industrial manufacturing. Forecasts reflect assumptions regarding nickel price stability and tariff continuity. Supply chain disruption from Asian mill complex output fluctuations or ocean freight congestion could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Middle-East and Africa Engineering Plastics Market
Industrial Materials
Wood Protein Market
Industrial Materials
Paint Knife Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
High Purity Quartz Market
Industrial Materials
Shrink Tanks Market
Industrial Materials
Industrial Anti-Fatigue Mat Market
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Pre-Painted Steel Coil Market
Industrial Materials
Conveyor Belt Materials Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
Flat Enameled Wires Market
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Solid Surface Materials Market
Industrial Materials
Plastic Compounding Machinery Market
Industrial Materials
Middle East Activated Carbon Market