
 Saudi Arabia Industrial Insulation Market | 2026-2036
Saudi Arabia Industrial Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Industrial Insulation Market Insights
Saudi Arabia is fragmenting its industrial insulation supply base as domestic capacity expands alongside mega-project construction. Saudi Rockwool Factory Co. anchors local mineral wool production against Gulf import dependence. KIMMCO Isover leverages Saint-Gobain's technology transfer to sustain premium fiberglass positioning. Owens Corning competes through specialized high-temperature piping systems for refinery turnarounds.
Saudi Arabia industrial insulation comprises engineered thermal barriers—typically mineral wool, fiberglass, or cellular glass with densities from 32 to 200 kg/m³—fabricated to limit heat transfer in process equipment operating between minus 50°C and 850°C. These systems reduce energy loss, prevent condensation corrosion, and protect personnel across continuous industrial operations. Fiberglass dominates piping applications due to cost efficiency and moisture resistance in coastal installations. Rock wool commands equipment and tank specifications where fire resistance ratings above 1,000°C prove mandatory. Polyurethane captures cold-service ducts and cryogenic segments through superior lambda values.
SFDA building safety codes and Saudi Building Code thermal efficiency chapters shape product certification requirements for industrial facilities. The Saudi Standards, Metrology and Quality Organization enforces material testing protocols that filter out uncertified imports. Stakeholders must track Royal Commission for Jubail and Yanbu project timelines to align capacity commitments with construction waves.
Market Dynamics
Saudi Aramco's energy efficiency mandates and SFDA building safety protocols are compressing procurement cycles while elevating thermal performance thresholds across Eastern Province industrial corridors. Domestic mineral wool capacity expansion is fragmenting import dependence as mega-project construction accelerates.
Growth Catalysts
- SFDA Building Safety Codes:Mandatory fire resistance ratings above 1,000°C for petrochemical equipment are accelerating rock wool specification in Jubail Industrial City's downstream processing corridors.
- Saudi Aramco Energy Mandates:Process efficiency targets are tightening thermal barrier requirements across refinery turnarounds and continuous operations.
- Downstream Processing Concentration:Petrochemical complex expansion in the Eastern Province is anchoring sustained material consumption for high-temperature piping systems.
Market Restraints
- Raw Material Volatility:Basalt and slag feedstock price swings for mineral wool production compress margin predictability for domestic manufacturers.
- Import Concentration Risk:Specialized cellular glass and cryogenic polyurethane segments remain dependent on Gulf supply chains with extended lead times.
- Technical Limitation:Fiberglass degradation above 400°C restricts deployment in furnace lining applications where ceramic alternatives dominate.
Strategic Opportunities
- Yanbu Industrial City:Red Sea coastal petrochemical development is creating underpenetrated demand for corrosion-resistant coastal insulation specifications.
- Cryogenic LNG Infrastructure:Emerging cold-service applications for polyurethane foam are opening new specification channels beyond traditional process equipment.
- Saudi Standards Certification:SASO material testing protocol expansion is creating regulatory tailwinds for locally certified producers against uncertified import competition.
Industry Challenges
- Specialized Installation Labor:Shortage of certified industrial insulation applicators for high-temperature systems delays project commissioning in remote Eastern Province sites.
- SASO Compliance Timeline:Extended product certification cycles for new material formulations create working capital strain during qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Industrial Insulation Market |
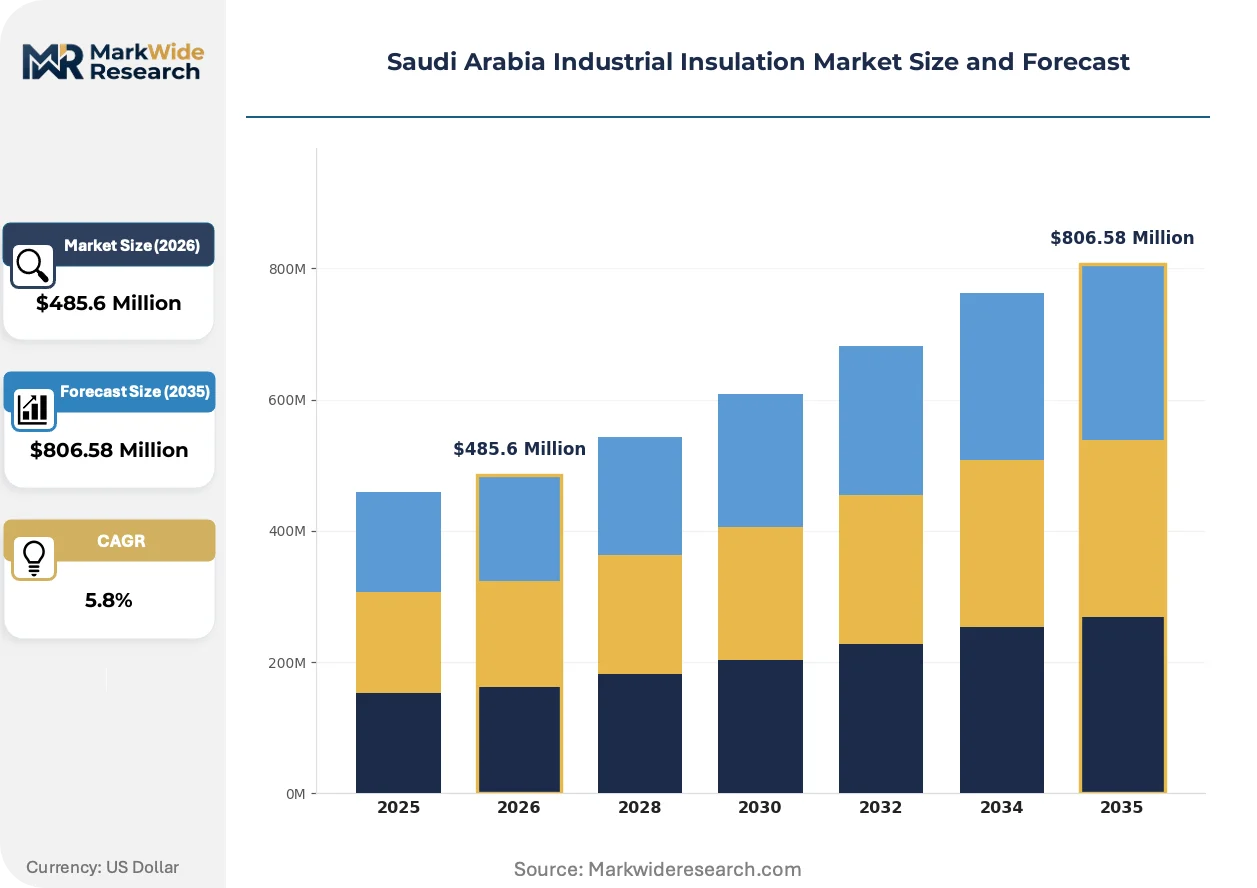
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $806.58 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Rock Wool, Cellular Glass, Polyurethane Application: Piping, Equipment, Ducts, Tanks End User: Oil & Gas, Chemical, Power Generation, Manufacturing Installation: Onshore, Offshore, Industrial Plants, Commercial Buildings |
| Companies Covered | Saudi Insulation Company, KIMMCO Isover, Saudi Rockwool Factory Co., Owens Corning, Saint-Gobain, Zamil Industrial, Urethane Foam Products Co. Ltd., Kingspan Insulation, Al-Fanar Insulation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Industrial Insulation Market Trends and Innovations
Digital monitoring systems are penetrating thermal barrier installations as operators seek predictive maintenance capabilities. Material science advances and procurement model evolution are simultaneously reshaping competitive positioning across Saudi Arabia's industrial insulation value chain.
Smart sensor-embedded insulation systems are digitizing asset performance tracking across Saudi Aramco's refining network. These integrated thermal barriers transmit real-time temperature and moisture data to central monitoring platforms. Maintenance teams now receive automated degradation alerts before failure events, compressing unplanned turnaround frequency.
SFDA building safety code amendments are tightening fire resistance documentation requirements for industrial facilities. Manufacturers must now submit third-party test reports for every batch of high-temperature insulation. Rock wool producers in Jubail are responding by investing in in-house fire testing laboratories to accelerate compliance turnaround.
Long-term service agreements are displacing transactional material supply contracts among major Eastern Province petrochemical operators. Procurement teams now bundle installation, inspection, and replacement cycles into multi-year performance contracts. This shift concentrates vendor selection authority with engineering procurement divisions rather than traditional purchasing departments.
Saudi Arabia Industrial Insulation Market Segmentation
Industrial insulation procurement in Saudi Arabia fragments across material specifications, installation environments, and end-use thermal requirements. Understanding these segment boundaries clarifies where domestic capacity expansion competes against import dependence.
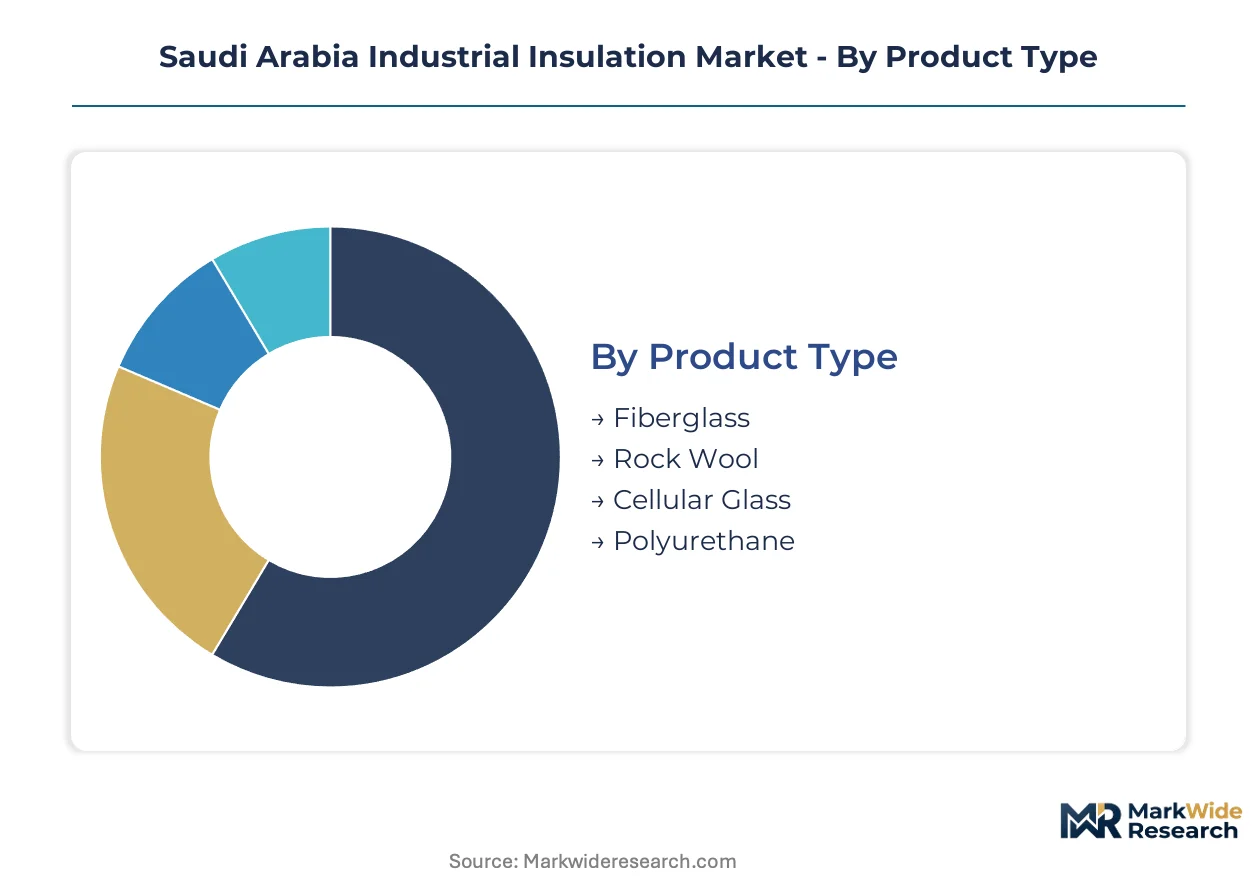
Product Type:
Mature mineral wool formulations anchor high-temperature specifications while emerging polymer systems capture cryogenic niches.
- Fiberglass:Glass fiber matrices with densities between 32 and 96 kg/m³ deliver cost-efficient thermal barriers for piping networks. Demand concentrates in Jubail Industrial City's coastal refineries where moisture resistance and corrosion protection drive specification against salt-laden atmospheres.
- Rock Wool:Basalt and slag-based mineral wool achieves fire resistance ratings exceeding 1,000°C critical for furnace linings and vessel insulation. Eastern Province petrochemical complexes specify rock wool for equipment and tank applications where SFDA mandates strict fire safety documentation.
- Cellular Glass:Rigid closed-cell glass foam provides moisture-impermeable insulation for buried piping and cryogenic service.
- Polyurethane:Spray and board-form polyisocyanurate systems deliver superior lambda values for cold-service ducts and LNG infrastructure.
Fiberglass handles the majority of throughput; polyurethane is expanding most quickly on share as cryogenic applications multiply.
Application:
Cost tier differentiation separates continuous-process specifications from intermittent maintenance cycles.
- Piping:Straight-run and pre-formed insulation jackets for process and utility piping dominate material volume across refinery and chemical plant networks. Jubail and Yanbu industrial corridors consume extensive piping insulation for steam distribution and hydrocarbon transfer lines operating between 150°C and 550°C.
- Equipment:Custom-fabricated removable insulation blankets for pumps, valves, and heat exchangers command premium pricing against permanent installations. Turnaround schedules in Saudi Aramco's refining complex drive replacement demand for high-temperature equipment blankets.
- Ducts:HVAC and process air handling systems utilize lightweight fiberglass boards and wraps.
- Tanks:Large storage vessel insulation for temperature maintenance and fire protection applies rock wool and cellular glass systems.
Piping absorbs the largest material tonnage; equipment applications are climbing the fastest as turnaround frequency intensifies.
End User:
Volume concentration tracks hydrocarbon processing capacity while customer type determines procurement contract structures.
- Oil & Gas:Upstream production facilities, midstream pipelines, and downstream refineries constitute the dominant demand pool. Saudi Aramco's energy efficiency mandates compress thermal performance thresholds across the entire value chain from wellhead to export terminal.
- Chemical:Petrochemical crackers, aromatics complexes, and specialty chemical plants in Jubail Industrial City specify fire-rated insulation for high-temperature reactors and distillation columns. SABIC affiliate operations anchor consistent material offtake against project cyclicality.
- Power Generation:Combined cycle and thermal power plants require boiler and turbine insulation.
- Manufacturing:Cement, steel, and food processing facilities apply industrial insulation for process heat containment.
Oil & Gas commands the dominant share; chemical end use is gaining share fastest on downstream expansion momentum.
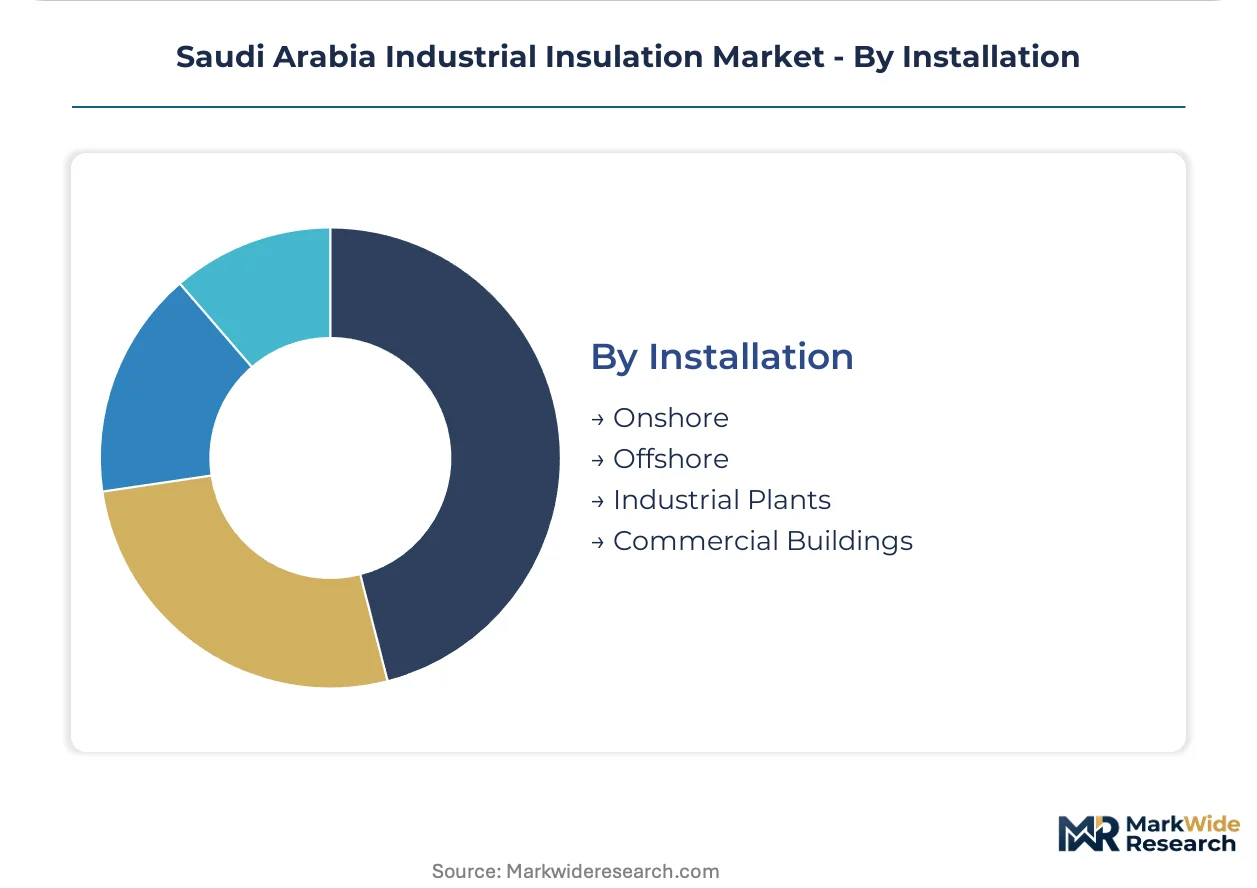
Installation:
Geography of deployment shapes logistics costs and labor certification requirements.
- Onshore:Terrestrial industrial facilities across the Eastern Province account for the bulk of installation activity. Royal Commission for Jubail and Yanbu project timelines synchronize construction waves with material supply commitments.
- Offshore:Platform and subsea pipeline insulation for Arabian Gulf production infrastructure faces specialized logistics and certified applicator scarcity. Extended lead times for cellular glass and cryogenic polyurethane segments concentrate risk in offshore procurement cycles.
- Industrial Plants:Process facility construction and maintenance represents the core installation environment.
- Commercial Buildings:Non-industrial applications including district cooling and building services constitute a peripheral segment.
Onshore installations handle the majority of throughput; offshore work is expanding fastest on Red Sea development activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Fahd Industrial Port in Jubail underwrites the Eastern Province's dominance, handling bulk mineral wool feedstock and finished insulation materials for petrochemical corridor expansion.
Eastern Province
Jubail Industrial City's downstream processing corridors anchor rock wool consumption for furnace linings and vessel insulation. SFDA building safety codes mandate fire resistance ratings above 1,000°C for petrochemical equipment. Yanbu Industrial City's Red Sea coastal development is creating demand for corrosion-resistant specifications against salt-laden atmospheres.
Riyadh
Central Saudi Arabia's manufacturing belt consumes fiberglass insulation for power generation and cement production facilities. SASO material testing protocols filter uncertified imports from domestic distribution channels. The Riyadh-based industrial zone is attracting insulation fabricators seeking proximity to government procurement centers.
Western Region
Jeddah Islamic Port facilitates cellular glass and cryogenic polyurethane imports for specialized cold-service applications. MOHAP facility construction standards influence hospital and pharmaceutical plant insulation specifications. The King Abdullah Economic City corridor is emerging as a logistics hub for Red Sea distribution.
NEOM Northwest
The linear city development is specifying high-performance thermal barriers for sustainable industrial zones operating on renewable energy. Giga-project construction timelines are compressing procurement cycles for advanced insulation systems. The Tabuk province site is attracting technology transfer partnerships for next-generation material formulations.
Saudi Arabia Industrial Insulation Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material supply. The Saudi Arabia industrial insulation market structures around three tiers: multinational technology licensors, domestic mineral wool producers, and regional distribution specialists. Consolidation pressure is intensifying as long-term service agreements displace transactional supply contracts. Dominant competitive moves include backward integration into raw material processing and strategic partnerships for technology transfer.
Within the domestic production tier, Saudi Rockwool Factory Co. anchors local mineral wool capacity against Gulf import dependence. KIMMCO Isover occupies a position as the premium fiberglass specialist leveraging Saint-Gobain's technology base. Owens Corning represents the multinational high-temperature systems archetype competing through specialized piping solutions for refinery turnarounds.
| Leading Market Players |
|---|
| Saudi Insulation Company |
| KIMMCO Isover |
| Saudi Rockwool Factory Co. |
| Owens Corning |
| Saint-Gobain |
| Zamil Industrial |
| Urethane Foam Products Co. Ltd. |
| Kingspan Insulation |
| Al-Fanar Insulation |
| Others |
Pricing and Supply Chain Analysis
King Fahd Industrial Port freight corridors compress logistics costs for Eastern Province mineral wool producers while amplifying price differentiation between Jubail-based domestic supply and Red Sea import alternatives. This corridor dynamic concentrates procurement leverage with petrochemical operators who can arbitrage coastal delivery premiums against inland distribution markups.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and volume commitment. SASO-certified mineral wool commands 15-25% premiums over uncertified Gulf imports, while project-scale offtake agreements unlock standard-tier pricing for mid-volume buyers. Price differentiation hinges on fire resistance documentation and installation service bundling. Cost compression in economy-tier fiberglass is intensifying because Saudi Rockwool Factory Co. expanded captive basalt processing. Chemical end users exhibit highest price sensitivity due to turnaround-driven spot purchasing; power generation utilities show lowest sensitivity given long-term performance contracting.
Supply Chain Analysis
Tariff exposure between GCC member states and non-Gulf cellular glass producers dominates supply chain risk assessment for cryogenic applications. Raw material sourcing draws from Oman for slag feedstock, Egypt for glass cullet, and South Korea for specialized polyurethane precursors. Single-source vulnerability concentrates in high-temperature ceramic fiber segments where European technology licensors control proprietary formulations. Distribution runs through Jubail Industrial City stockyards for onshore projects, while Jeddah Islamic Port handles Red Sea coastal logistics for Yanbu and NEOM developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified industrial insulation applicator shortages across remote Eastern Province sites constrain project velocity and create asymmetric capability advantages for firms with in-house installation teams. This scarcity dynamic rewards early investment in technical workforce development and SASO qualification pipelines.
For Market Incumbents: Build regulatory compliance moats by accelerating in-house fire testing laboratory investments ahead of SFDA documentation tightening. Capture margin protection through backward integration into basalt quarrying and slag processing to offset feedstock volatility. Defend against emerging polyurethane specialists by locking multi-year performance contracts with SABIC affiliates before cryogenic LNG infrastructure scales.
For New Entrants and Emerging Players: Establish a beachhead in Yanbu Industrial City's corrosion-resistant coastal specifications where salt-laden atmosphere requirements filter out standard-grade competitors. Target cryogenic polyurethane foam for emerging LNG cold-service applications beyond traditional process equipment. Lead with digital monitoring system integration as a bundled service differentiator against legacy material suppliers.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational industrial conglomerates seeking to divest non-core insulation divisions amid portfolio rationalization. Long-term viability centers on regulatory certification depth and installation service density rather than commodity material throughput. Watch Royal Commission project announcement velocity as the inflection signal for capacity commitment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Processing | Saudi Rockwool Factory Co. secures feedstock cost predictability against Gulf slag price volatility. |
| In-House Fire Testing Laboratory Investment | Accelerated SASO batch certification compresses compliance turnaround for Jubail petrochemical tenders. |
| Long-Term Performance Contracting | SABIC affiliates bundle installation and replacement cycles, displacing transactional material supply. |
| Smart Sensor-Embedded System Development | Saudi Aramco refining network adoption enables predictive maintenance revenue streams. |
| Cryogenic Polyurethane Capacity Addition | LNG infrastructure cold-service specifications open specification channels beyond traditional process equipment. |
Research Methodology
Operator-level perspectives from plant engineers, EPC contractors, procurement leads at petrochemical operators, and SASO certification officers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through Saudi customs trade data, Royal Commission for Jubail and Yanbu project databases, and SEC filings of listed industrial conglomerates. Bottom-up material volume estimates triangulated against top-down petrochemical capacity expansion forecasts.
Scenario-bracketing framed the analytical approach across conservative, baseline, and expansion cases throughout the forecast period. Segmentation dimensions modeled include material type, application environment, end-use industry, installation geography, and thermal performance tier. CAGRs derived from installed base replacement cycles and new-build project pipelines. Industry-specific inputs incorporated Saudi Aramco energy efficiency mandate compliance timelines and SFDA building safety code amendment trajectories.
Stress conditions across basalt feedstock price volatility, project construction delays, and certified labor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and mega-project sanctioning velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
HV Glass Insulator Market
Industrial Materials
Middle East Activated Carbon Market
Industrial Materials
Industrial Films Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Encapsulated Gaskets/Seals Market
Industrial Materials
Metal Stamping Market
Industrial Materials
High Performance Random Packing Market
Industrial Materials
Neoprene Foam Market
Industrial Materials
North America Machined Seals Market
Industrial Materials
Natural Industrial Absorbents Market
Industrial Materials
Powder Funnels Market
Industrial Materials
Global Metal Anodizing Market
Industrial Materials
Injection Molding Market
Industrial Materials
High Shear Mixer Market
Industrial Materials
High Speed Steels Market
Industrial Materials
Polyurethane Processing Machine Market