
 Plastic Molds Market | 2026-2036
Plastic Molds Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Molds Market Outlook
Direct-to-manufacturer digital quoting platforms is rewriting how mold buyers source tooling across North America and Asia. Proto Labs leverages rapid-turn injection molding services to capture prototype-to-production workflows for medical device and electronics clients. EVCO Plastics anchors its position through deep vertical integration across mold design, build, and high-volume part production in the Midwest. TDL Mould competes on cost-engineered aluminum and steel tooling exported from China's Pearl River Delta to automotive Tier-1 suppliers in Germany and Mexico.
Plastic molds are precision-engineered hollow forms, typically machined from hardened steel or aluminum alloys with tolerances measured in micrometers, into which molten thermoplastic or thermoset polymer is injected, blown, or compressed to produce dimensionally consistent parts. Injection molds dominate value capture due to their centrality in mass-producing complex geometries for automotive interiors and medical housings, while blow molds serve high-volume packaging and fluid containment applications with faster cycle times but lower per-unit tooling investment. Aluminum tooling is gaining share in short-run and prototype segments where heat dissipation speed offsets durability trade-offs against hardened steel.
EPA regulations on volatile organic compound emissions from mold manufacturing processes are pushing fabricators toward closed-loop cooling and solvent recovery systems in US-based operations. REACH restrictions on chromium and nickel compounds in Europe are reshaping surface treatment specifications for steel molds exported into EU supply chains. China's GB standards for mold steel grades, enforced by SAMR, create compliance thresholds for domestic producers and import substitution incentives. Stakeholders must track how dual carbon goals in Beijing and the EU Green Deal's embodied-carbon reporting requirements will recalibrate material sourcing and tool lifecycle accounting across multinational mold supply networks.
Market Dynamics
Automotive electrification is compressing mold development cycles while simultaneously expanding part complexity requirements, forcing fabricators to retool for aluminum-intensive prototyping and hardened steel production workflows.
Growth Catalysts
- EV Battery Enclosures:Automotive OEMs demand larger, geometrically intricate polymer housings for thermal management systems, pulling multi-cavity mold investment into supplier order books.
- REACH Recyclability Mandates:ECHA restrictions on mold steel surface treatments are accelerating adoption of chrome-free hard-coating processes across EU-bound export tooling.
- Aluminum Heat Dissipation:Prototype segments favor aluminum tooling where cycle speed outweighs durability trade-offs, expanding addressable volume in short-run medical device and consumer electronics workflows.
Market Restraints
- Specialty Alloy Volatility:H13 and P20 mold steel pricing fluctuates with nickel and chromium spot markets, compressing margin visibility for mid-cap tool-and-die operations.
- Pearl River Delta Concentration:China's eastern manufacturing corridor hosts disproportionate share of global mold exports, creating geographic single-point-of-failure exposure for automotive Tier-1 procurement teams.
- Dimensional Tolerance Ceilings:Micrometer-grade precision requirements in medical housing applications limit viable supplier pools to shops with five-axis machining capability and climate-controlled finishing floors.
Strategic Opportunities
- Mexico Nearshoring Corridor:Automotive assemblers are qualifying mold suppliers in Querétaro and Nuevo León to compress logistics lead times for US-bound polymer components.
- Closed-Loop Cooling Systems:EPA volatile organic compound regulations are creating aftermarket retrofit demand for solvent recovery infrastructure among legacy US mold fabricators.
- Digital Quoting Platforms:Direct-to-manufacturer sourcing interfaces are disintermediating traditional mold broker networks, capturing prototype-to-production workflow margin previously allocated to intermediaries.
Industry Challenges
- Five-Axis Machining Talent Scarcity:Toolpath programming for complex cavity geometries requires specialized operators, with training pipelines failing to match replacement demand in Midwest and Guangdong manufacturing clusters.
- Dual Certification Timelines:Medical device mold suppliers face elongated validation cycles combining FDA 21 CFR Part 820 with ISO 13485, stretching working capital deployment before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Molds Market |
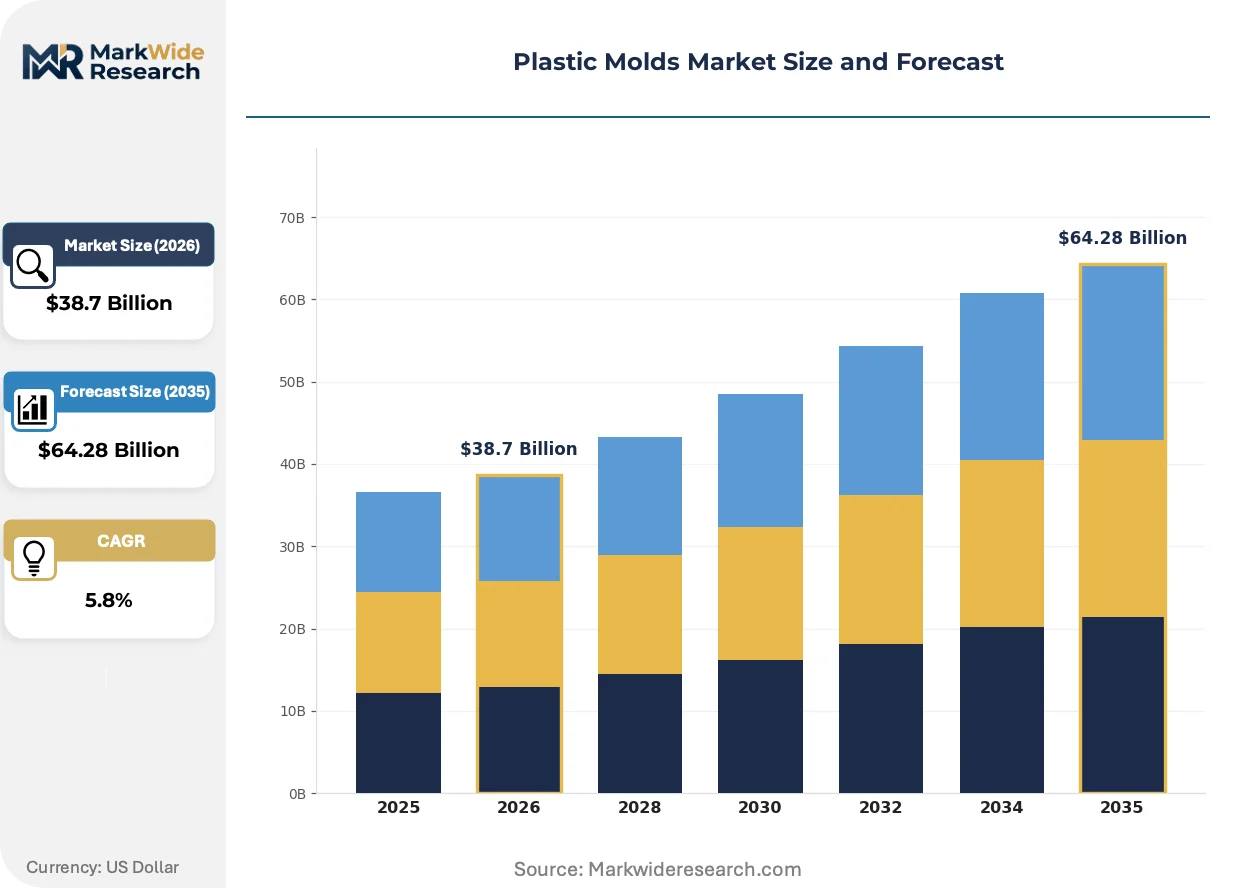
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molds, Blow Molds, Compression Molds, Rotational Molds Material: Steel, Aluminum, Bronze, Polymer Application: Automotive Parts, Consumer Goods, Medical Devices, Electronics End User: OEMs, Tier-1 Suppliers, Manufacturing Firms, Aftermarket Providers |
| Companies Covered | Proto Labs, EVCO Plastics, The Rodon Group, Crescent Industries, Murray Plastics, TDL Mould, Nicolet Plastics, AMK Plastics, Majors Plastics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Molds Market Strategic Shifts
Digital thread technologies are collapsing the design-to-tooling handoff timeline, compressing iteration cycles that previously spanned months into weeks while simultaneously raising fidelity requirements for simulation-driven cavity optimization.
Generative design software is virtualizing mold cooling channel architecture, enabling conformal layouts that follow part geometry rather than straight-line drilling constraints. Medical device manufacturers are adopting these tools fastest, driven by housing complexity for drug-delivery systems. The technology is virtualizing thermal management optimization, compressing the traditional trial-and-error iteration cycle between mold designer and injection process engineer.
EPA enforcement of volatile organic compound emissions from mold manufacturing processes is tightening in Michigan and Ohio tool-and-die corridors, pushing fabricators toward aqueous cleaning chemistries and closed-loop coolant systems. The regulatory pressure is elevating capital requirements for smaller shops, accelerating consolidation among sub-fifty-employee mold builders in the Great Lakes region.
Medical device OEMs are unbundling mold ownership from part supply contracts, shifting toward tooling-as-a-service arrangements where fabricators retain asset title and charge per-shot fees. This model is displacing traditional capital purchase workflows in cardiovascular and diagnostic housing segments. The shift is most visible in Minnesota and Massachusetts medical technology clusters, where cash-flow-conscious startups favor operational expenditure treatment over mold capex on balance sheets.
Plastic Molds Market Segmentation
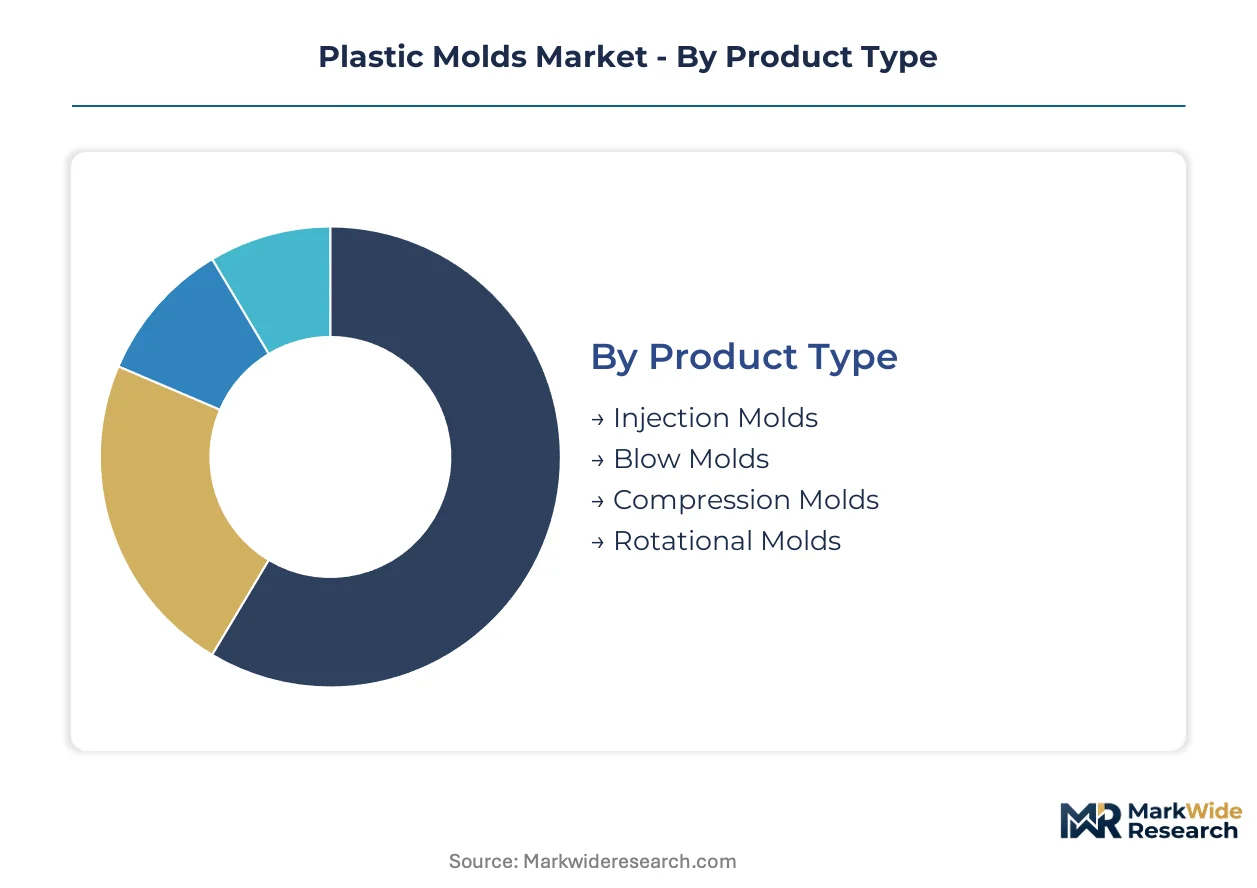
Plastic mold segmentation reveals divergent capital intensity and tooling lifecycles across product architectures, material grades, and buyer categories. Fabricators optimize production scheduling and inventory positioning by matching segment-specific lead times against end-user just-in-sequence requirements.
Product Type:
Cycle times vary dramatically: blow molds turn fastest for packaging runs, while injection molds lock capital longest due to multi-cavity complexity and surface finishing demands.
- Injection Molds:Multi-cavity steel or aluminum tooling engineered for high-pressure thermoplastic injection, achieving micrometer-grade tolerances through hardened cavity surfaces and conformal cooling channels. Automotive interior panels and medical device housings in Germany and Mexico drive specification intensity, with EV battery enclosure demand pulling larger mold footprints into supplier order books.
- Blow Molds:Hollow-form tooling for extrusion or injection blow molding of fluid containers and packaging geometries, characterized by faster heat cycling and lower per-unit tooling investment versus injection architectures. High-volume beverage and personal care packaging lines in China's eastern manufacturing corridor favor aluminum blow mold variants for rapid thermal recovery.
- Compression Molds:Matched-die tooling for thermoset polymer forming, common in electrical insulator and automotive underhood component production where heat resistance outweighs cycle speed priorities.
- Rotational Molds:Biaxial rotation tooling for large hollow parts including tanks and recreational equipment, occupying niche volume with extended heating cycles and lower cavity pressure requirements.
Injection molds anchor the volume base while blow molds gain share at the steepest rate in short-run consumer packaging workflows.
Material:
Cost tiers stratify sharply: steel commands premium positioning for million-shot durability, aluminum penetrates prototype and bridge-tooling segments, while bronze and polymer occupy specialized thermal or corrosion-resistant niches.
- Steel:H13 and P20 grade tool steels delivering hardened cavity surfaces for multi-million shot production runs, with vacuum heat treatment and chrome-free hard-coating processes responding to REACH surface treatment restrictions. Automotive Tier-1 procurement in Germany and Mexico specifies steel tooling for interior trim and powertrain component programs.
- Aluminum:7075 and QC-10 aluminum alloys prioritized for prototype-to-production workflows where thermal conductivity accelerates cycle times despite reduced durability versus hardened steel. Medical device startups in Minnesota and Massachusetts favor aluminum for drug-delivery housing development cycles.
- Bronze:Copper-tin alloys deployed in specialized applications requiring superior thermal conductivity or corrosion resistance, including certain blow mold pinch-off zones and marine-facing components.
- Polymer:Composite and engineered polymer tooling for ultra-short-run prototyping and soft-tooling applications, limiting heat exposure and shot counts but enabling rapid turnaround at minimal material cost.
Steel retains the dominant revenue share while aluminum expands most quickly in medical device and EV prototyping segments.
Application:
Application mix tracks end-use durability requirements and regulatory validation intensity, with medical and automotive segments imposing the longest qualification timelines.
- Automotive Parts:Interior panels, underhood components, and EV battery enclosures requiring geometric complexity and thermal management integration, with OEMs specifying multi-cavity steel tooling for high-volume programs.
- Medical Devices:Drug-delivery housings, diagnostic enclosures, and surgical instrument components subject to FDA 21 CFR Part 820 and ISO 13485 validation protocols, favoring climate-controlled machining environments and extended qualification cycles.
- Consumer Goods:Packaging, appliances, and personal care items with faster design turnover and lower per-tool investment thresholds, often served through aluminum prototyping workflows.
- Electronics:Smartphone housings, connector components, and wearable device enclosures requiring miniaturization tolerance and EMI shielding integration, concentrated in China's Pearl River Delta tool-and-die clusters.
Automotive parts command the largest tooling investment volumes while medical devices deliver the highest margin per cavity due to certification barriers.
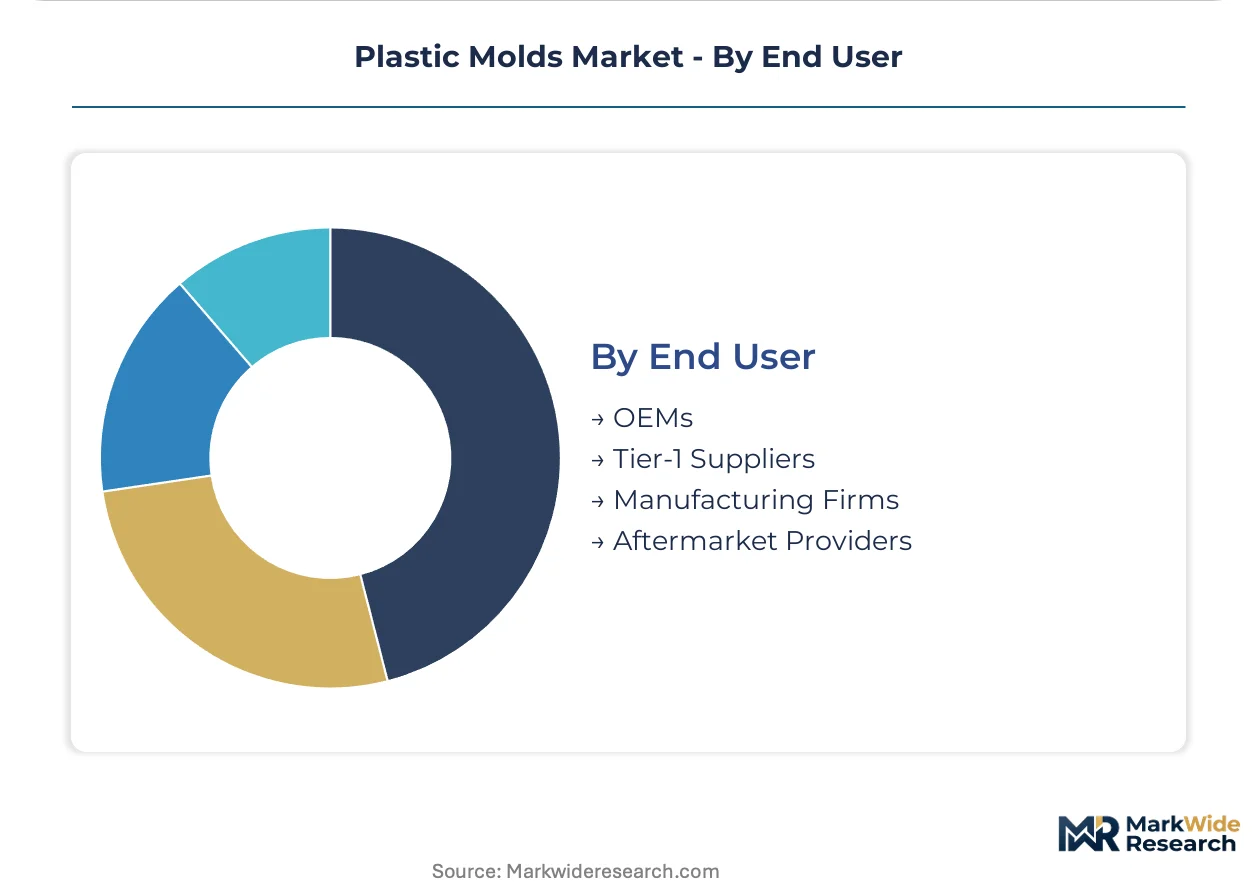
End User:
Buyer sophistication and contract structure vary: OEMs retain mold ownership in traditional arrangements, while Tier-1 suppliers and manufacturing firms increasingly adopt tooling-as-a-service models.
- OEMs:Original equipment manufacturers in automotive and medical verticals specifying proprietary mold designs, often retaining asset title and amortizing tooling across multi-year production agreements.
- Tier-1 Suppliers:Component integrators serving OEM assembly lines, qualifying mold fabricators in Mexico's Querétaro and Nuevo León corridors to compress logistics lead times for US-bound polymer components.
- Manufacturing Firms:Contract manufacturers and private-label producers leveraging digital quoting platforms to source rapid-turn tooling, favoring operational expenditure treatment over mold capex on balance sheets.
- Aftermarket Providers:Replacement part producers and restoration specialists requiring low-volume tooling replication, often reverse-engineering legacy molds without original design documentation.
OEMs anchor the high-value contract base while manufacturing firms are shifting fastest toward per-shot pricing arrangements and digital sourcing interfaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in mold exports, while the Rhine-Main corridor's inland waterway network anchors European tooling logistics.
United States
Automotive electrification in Michigan and Ohio is pulling multi-cavity mold investment into supplier order books. EPA enforcement of volatile organic compound emissions is accelerating closed-loop cooling retrofits among legacy Great Lakes fabricators. Chicago's tool-and-die corridor hosts climate-controlled machining floors serving medical device OEMs in Minnesota and Massachusetts.
Germany
EV battery enclosure programs for BMW and Volkswagen are demanding larger mold footprints with conformal cooling integration. ECHA restrictions on chromium and nickel compounds in REACH are reshaping surface treatment specifications for steel molds. Stuttgart's automotive Tier-1 cluster qualifies Chinese export tooling while maintaining captive mold design capabilities in Baden-Württemberg.
China
Domestic EV brands and consumer electronics assemblers are concentrating demand in the eastern manufacturing corridor. SAMR enforcement of GB standards for mold steel grades creates compliance thresholds for domestic producers. Shenzhen and Dongguan in the Pearl River Delta export cost-engineered aluminum and steel tooling to automotive suppliers in Germany and Mexico.
Mexico
Nearshoring momentum is qualifying mold suppliers in Querétaro and Nuevo León to compress logistics lead times for US-bound polymer components. PROFEPA industrial emissions protocols are elevating environmental compliance costs for new market entrants. Monterrey's manufacturing base is absorbing transfer tooling from shuttered US operations while scaling five-axis machining capacity.
Japan
Miniaturization tolerance requirements for electronics housings are sustaining premium positioning for domestic mold fabricators. METI industrial standards for precision tooling are creating non-tariff barriers against lower-cost Asian imports. Nagoya's Chubu region maintains captive mold production for Toyota and Honda interior trim programs.
Plastic Molds Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream capturing margin on discrete process steps. The vendor base stratifies across rapid-turn digital platforms, vertically integrated regional fabricators, and cost-engineered export specialists. Three archetypes dominate: digital-first quoting engines, captive production shops with in-house mold design, and Pearl River Delta exporters competing on tooling economics. Consolidation pressures are elevating capital requirements for environmental compliance and five-axis machining capability.
Among US-based fabricators, Proto Labs exemplifies the digital platform archetype with rapid-turn injection molding services, while EVCO Plastics anchors the vertically integrated Midwest position. TDL Mould represents the China export specialist tier competing on cost-engineered tooling for automotive Tier-1 procurement. These three occupy positions across the pricing and capability spectrum without overlapping strategic territory.
| Leading Market Players |
|---|
| Proto Labs |
| EVCO Plastics |
| The Rodon Group |
| Crescent Industries |
| Murray Plastics |
| TDL Mould |
| Nicolet Plastics |
| AMK Plastics |
| Majors Plastics Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in five-axis machining floors across the Great Lakes and Guangdong clusters is elevating premium-tier pricing power while compressing margins for commodity-grade tooling. This utilization asymmetry drives supplier selectivity toward medical and EV battery enclosure programs while forcing price concessions in consumer electronics prototyping segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates mold procurement, with certification-grade medical tooling commanding substantial premiums over uncertified consumer goods variants. Price differentiation rests on ISO 13485 compliance status and five-axis machining capability, with FDA-validated suppliers capturing margin premiums from Minnesota and Massachusetts device clusters. Cost compression in economy-tier aluminum prototyping is intensifying because of Pearl River Delta capacity expansion. Contract manufacturers and startup device firms exhibit highest price sensitivity, while captive OEM tooling programs demonstrate lowest elasticity due to qualification lock-in effects.
Supply Chain Analysis
Contract manufacturing concentration among EVCO Plastics, Proto Labs, and TDL Mould anchors tiered capacity allocation across North American and Asian production networks. Tool steel supply draws from German and Japanese specialty alloy producers, with H13 and P20 grades sourced through long-term offtake agreements. Distribution runs through automotive Tier-1 procurement hubs in Querétaro, Stuttgart, and Detroit, with logistics lead times determining supplier qualification decisions. Single-source vulnerability concentrates in China's eastern manufacturing corridor, where SAMR-enforced GB standards create import substitution thresholds for domestic mold steel grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against additive manufacturing and 3D-printed tooling workflows that threaten prototype and short-run segments. Incumbents must differentiate through validation depth and cycle-time performance that polymer deposition cannot replicate.
For Market Incumbents: Entrench position through captive five-axis machining capacity additions in climate-controlled Midwest facilities, insulating against talent scarcity in Guangdong. Deepen backward integration into conformal cooling channel design software to accelerate iteration cycles beyond what digital-native competitors can match. Defend against tooling-as-a-service displacement by embedding per-shot pricing into long-term medical device supply agreements with Minnesota and Massachusetts OEMs.
For New Entrants and Emerging Players: Pursue white-space opportunity in Mexico's Querétaro and Nuevo León corridors, where nearshoring momentum outpaces qualified supplier availability. Target aftermarket mold replication services for legacy automotive and industrial equipment lacking original design documentation. Establish go-to-market presence through direct-to-manufacturer digital quoting platforms that disintermediate traditional broker networks and capture prototype-to-production workflow margin.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tooling-as-a-service providers serving cardiovascular and diagnostic housing segments, where per-shot pricing models generate predictable cash flows across multi-year OEM agreements. Long-term viability favors vertically integrated fabricators with in-house mold design, build, and high-volume part production capabilities. Monitor EPA enforcement intensity in Michigan and Ohio as inflection indicator for environmental compliance capital requirements and consolidation pressure among sub-fifty-employee mold builders.
| Strategic Initiative | Industry Significance |
|---|---|
| Conformal Cooling Channel Integration | Generative design tools enable thermal layouts that follow part geometry rather than straight-line drilling constraints. |
| Closed-Loop Cooling Retrofit | EPA volatile organic compound regulations create aftermarket demand for solvent recovery infrastructure among legacy fabricators. |
| Tooling-as-a-Service Transition | Per-shot pricing models displace capital purchase workflows in Minnesota and Massachusetts medical technology clusters. |
| Mexico Nearshoring Qualification | Querétaro and Nuevo León suppliers compress logistics lead times for US-bound automotive polymer components. |
| Chrome-Free Hard-Coating Adoption | ECHA REACH restrictions on chromium compounds reshape surface treatment specifications for EU-bound export tooling. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with mold design engineers, Tier-1 automotive procurement managers, medical device regulatory affairs leads, and five-axis machining floor supervisors; and secondary validation through customs trade records, SAMR GB standard filings, EPA enforcement disclosures, and SEC 10-K filings from listed fabrication groups. Bottom-up tooling shipment estimates triangulated against top-down polymer consumption models to reconcile volume figures.
Forecast inputs span injection versus blow mold architecture splits, steel versus aluminum material grade trajectories, and automotive versus medical versus electronics application mix shifts across the analysis window. Modeled dimensions include product type, material grade, end-use application, and buyer category. CAGRs derived from segment-level volume trajectories indexed to polymer feedstock demand and OEM production schedules, with EV battery enclosure demand and REACH recyclability mandates incorporated as scenario variables.
Sensitivities concentrate around H13 and P20 alloy price volatility, Pearl River Delta logistics disruptions, and dual carbon goal acceleration in Beijing that could recalibrate domestic mold steel sourcing incentives. Quarterly review of EPA enforcement intensity, ECHA surface treatment restriction updates, and SAMR GB standard revision timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
2-in-1 Material Rack Correction Machine Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Global Glass Wool Board Sales Market
Industrial Materials
High Performance Random Packing Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
GCC Welding Consumables Market
Industrial Materials
Weatherstrip Seal Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
Industrial Kiln Market
Industrial Materials
Wedge Wire Screen Market
Industrial Materials
Plastic Injection Mold Market
Industrial Materials
Twin Screw Extruders Market
Industrial Materials
High Pressure Braided Tubing (HPBT) Market
Industrial Materials
Atomizing Metal Powder Market
Industrial Materials
Magnet Rings Market
Industrial Materials
Vinyl Extrusion Equipment Market