
 Global Hydroxy Ethyl Cellulose (HEC) Market | 2026-2036
Global Hydroxy Ethyl Cellulose (HEC) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydroxy Ethyl Cellulose (HEC) Market Foresight
ISO 9001 certification is rotating the competitive threshold for HEC suppliers seeking entry into pharmaceutical and personal care supply chains. Ashland leverages its backward integration into ethylene oxide and cellulose feedstock to secure cost positions in North American paints and coatings. Dow Chemicals sustains technical leadership through proprietary manufacturing scale across multiple viscosities. Shin-Etsu Chemicals Co., Ltd. anchors its position in Asian electronics and cosmetics applications with ultra-high-purity grades.
Hydroxy ethyl cellulose is a non-ionic water-soluble polymer produced by reacting alkali cellulose with ethylene oxide, yielding substitution degrees that govern viscosity from 2,500 to 150,000 mPa·s in aqueous solution. It functions primarily as a thickener, protective colloid, and rheology stabilizer across aqueous formulations in construction, personal care, and oilfield chemistry. Powder grades dominate volume shipment due to shelf stability and freight efficiency, though solution formats command margin pools in just-in-time cosmetics manufacturing. Paints and coatings applications lead absolute consumption, while personal care and oil and gas drilling represent the fastest-growing demand poles as formulation chemists replace synthetic thickeners with bio-based alternatives.
EPA oversight under the Toxic Substances Control Act shapes permissible ethylene oxide residuals in HEC destined for U.S. consumer products, while REACH registration in the European Union mandates full toxicological dossiers for cellulose ether imports. China's SAMR enforces GB standards for food-contact and cosmetic-grade HEC, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions as bio-based content claims and carbon footprint disclosures become embedded in procurement specifications.
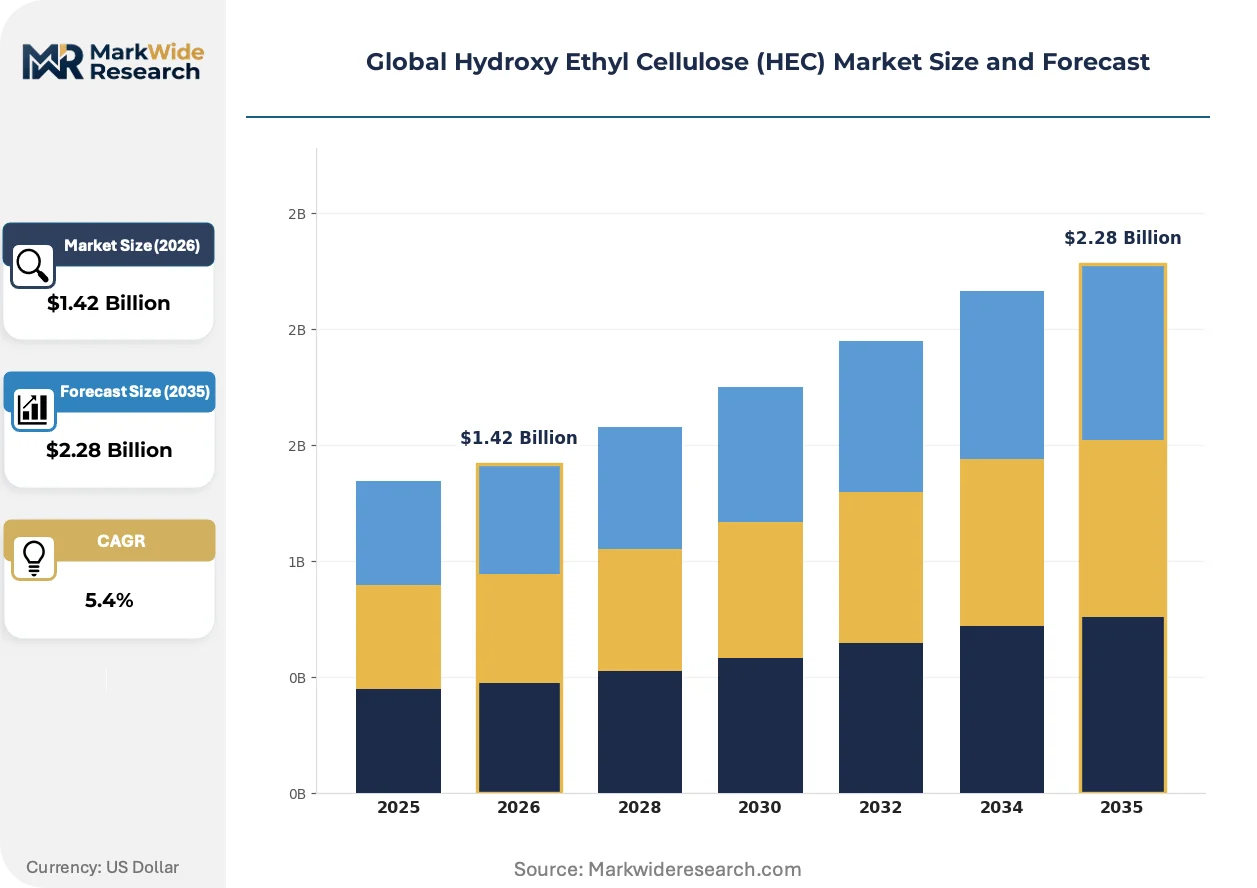
Market Dynamics
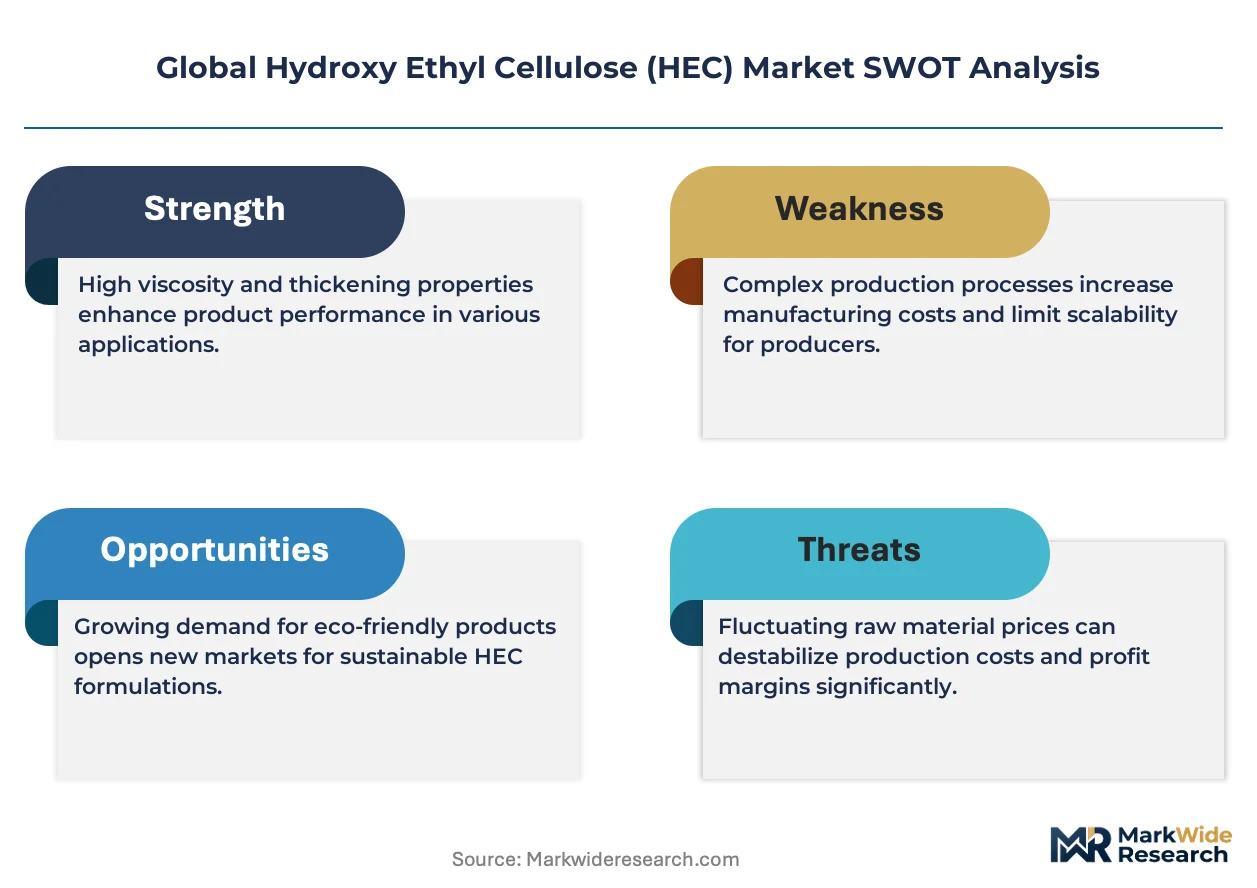
REACH compliance deadlines and EPA residual limits are compressing formulation windows for HEC suppliers, forcing simultaneous purity upgrades across European and North American supply chains while coating manufacturers accelerate bio-based thickener substitution programs.
Growth Catalysts
- Water-based architectural coatings:Formulation chemists in Germany and China are expanding HEC incorporation as VOC regulations tighten solvent-borne alternatives.
- EPA residual thresholds:The Toxic Substances Control Act is pulling high-purity grades into U.S. consumer-facing applications ahead of compliance deadlines.
- Ethylene oxide feedstock control:Captive supply of this critical input is insulating integrated producers from spot-market volatility.
Market Restraints
- Ethylene oxide price volatility:Feedstock cost swings transmit directly into HEC margin compression for non-integrated suppliers.
- Chinese supply concentration:Downstream coating production clusters in Shandong and Jiangsu provinces create geographic demand risk.
- Synthetic polymer substitution:Polyacrylate thickeners retain cost advantages in cost-sensitive construction applications.
Strategic Opportunities
- Indian pharmaceutical excipient demand:CDSCO registration pathways for cellulose ethers remain underexploited by Western suppliers.
- EU Green Deal bio-content mandates:Procurement specifications are embedding renewable carbon claims that favor HEC over petrochemical alternatives.
- Direct-to-formulator digital channels:Specialty chemical distributors are launching just-in-time platforms for mid-volume cosmetics manufacturers.
Industry Challenges
- ISO 9001 certification timelines:Pharmaceutical and personal care supply chains demand 12-18 month audit cycles for new entrants.
- Legacy formulation integration:Paint manufacturers face revalidation costs when switching thickener grades in certified product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydroxy Ethyl Cellulose (HEC) Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Solution, Fiber, Flake Application: Personal Care, Paints & Coatings, Oil & Gas Drilling, Adhesives & Sealants, Detergents End User Industry: Cosmetics Manufacturers, Coating Producers, Energy Sector, Industrial Chemicals, Cleaning Formulators Packaging Type: Bag, Drum, Bulk Container, Box, Pail |
| Companies Covered | Ashland, Dow Chemicals, Shin-Etsu Chemicals Co., Ltd., AkzoNobel N.V., Daicel Corporation, Lotte Fine Chemicals, Chemcolloids Ltd., Zhejiang Haishen New Materials Limited, Wuxi Sanyou New Material Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydroxy Ethyl Cellulose (HEC) Market Shifts & Advancements
Formulation science is pivoting toward bio-derived rheology modifiers as regulatory thresholds harden and procurement teams embed carbon accounting into supplier scorecards across industrial coatings and personal care.
Continuous etherification reactor designs are supplanting batch processes in HEC manufacturing. Shin-Etsu Chemicals and Dow Chemicals have commissioned semi-continuous units that cut ethylene oxide consumption per ton by enabling tighter substitution degree control. The technology is compressing capital intensity for new entrants while raising purity floors.
REACH registration dossiers now mandate full toxicological profiles for cellulose ether imports into the European Union. ECHA's 2024 updated guidance on polymer characterization is forcing suppliers to resubmit existing registrations with expanded ecotoxicity data. Cosmetic-grade HEC faces the steepest compliance cost escalation.
Formulator procurement teams are consolidating thickener suppliers to reduce qualification overhead. Paints and coatings manufacturers in Germany now require single-source accountability for rheology modifier performance across water-borne and solvent-borne lines. The shift is visible most acutely in automotive refinish segments where OEM certification cycles compress switching flexibility.
Global Hydroxy Ethyl Cellulose (HEC) Market Segmentation
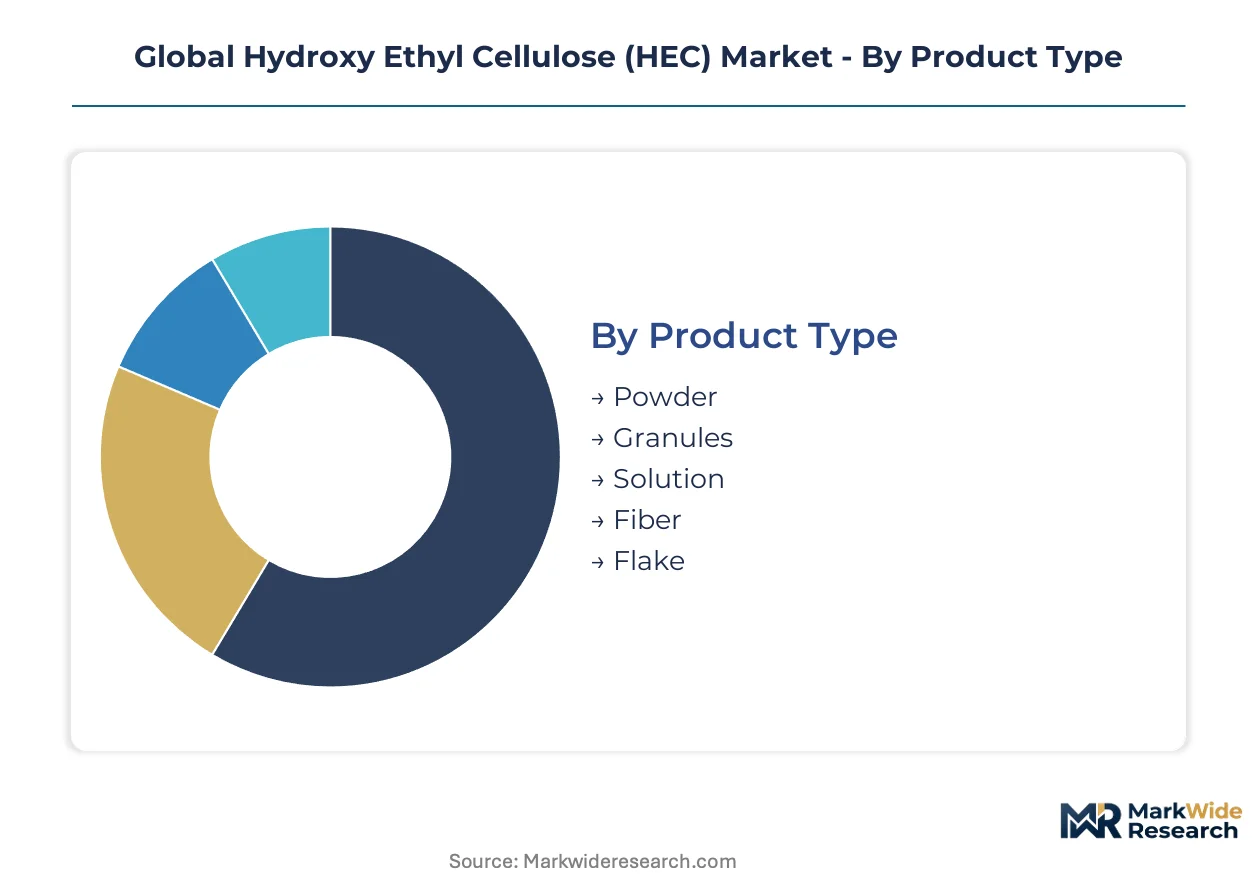
HEC suppliers navigate distinct qualification barriers across product formats and end-use specifications. Segmentation reveals where captive feedstock control versus distribution agility determines competitive position.
Product Type:
Powder and solution grades split between domestic formulation supply and export-driven specialty channels, with freight economics and shelf stability dictating geographic reach.
- Powder:Spray-dried particles with moisture content below 5% enable extended storage without viscosity degradation. Coating producers in Germany and China absorb rising volumes as water-borne architectural formulations displace solvent systems under tightening VOC rules.
- Solution:Pre-hydrated liquid concentrates eliminate dust handling and dissolution time for cosmetics manufacturers running continuous production. Just-in-time delivery contracts in personal care command premium positioning over powder equivalents.
- Granules:Intermediate particle size reduces airborne dust versus powder while retaining faster dissolution than flake grades.
- Fiber:Elongated morphology suits specialized rheology modification in cementitious construction admixtures.
- Flake:Compressed sheet form targets legacy oilfield drilling fluid formulations with established handling protocols.
Powder commands the established base. The steepest expansion runs through solution formats.
Application:
Cost tier stratification separates commodity construction uses from certified pharmaceutical and cosmetic grades requiring extended audit cycles.
- Paints & Coatings:Rheology stabilization in water-borne systems represents the volume anchor, with formulation chemists specifying viscosity grades from 5,000 to 100,000 mPa·s. German automotive refinish and Chinese architectural coating clusters drive specification intensity.
- Personal Care:Shampoo and lotion formulators specify ultra-low ash content below 0.5% with full REACH dossier compliance. CDSCO registration pathways in India remain underexploited by Western suppliers relative to FDA and EMA precedents.
- Oil & Gas Drilling:Fluid loss control in shale formations demands salt-tolerant polymer grades with thermal stability above 150°C.
- Adhesives & Sealants:Tile adhesive and caulk formulations utilize mid-viscosity HEC for open-time extension.
- Detergents:Liquid laundry and dish formulations incorporate HEC as a secondary thickener behind primary surfactant systems.
Paints & Coatings anchors volume throughput. Personal Care is climbing the fastest on bio-based substitution mandates.
End User Industry:
Customer type concentration determines whether suppliers prioritize ISO 9001 certification investment or commodity scale economics.
- Coating Producers:Formulation houses in Shandong and Jiangsu provinces consolidate thickener suppliers to reduce qualification overhead, demanding single-source accountability across water-borne and solvent-borne lines.
- Cosmetics Manufacturers:Multinational personal care brands audit HEC suppliers for 12-18 month cycles before pharmaceutical-grade approval, with ECHA's expanded ecotoxicity requirements escalating compliance costs.
- Energy Sector:Oilfield service companies specify HEC for drilling mud viscosity in North American shale basins.
- Industrial Chemicals:Construction admixture blenders source powder grades for cement modification at volume scale.
- Cleaning Formulators:Detergent manufacturers balance HEC cost against polyacrylate alternatives in price-sensitive household segments.
Coating Producers dominate procurement volume. Cosmetics Manufacturers show the steepest margin expansion trajectory.
Packaging Type:
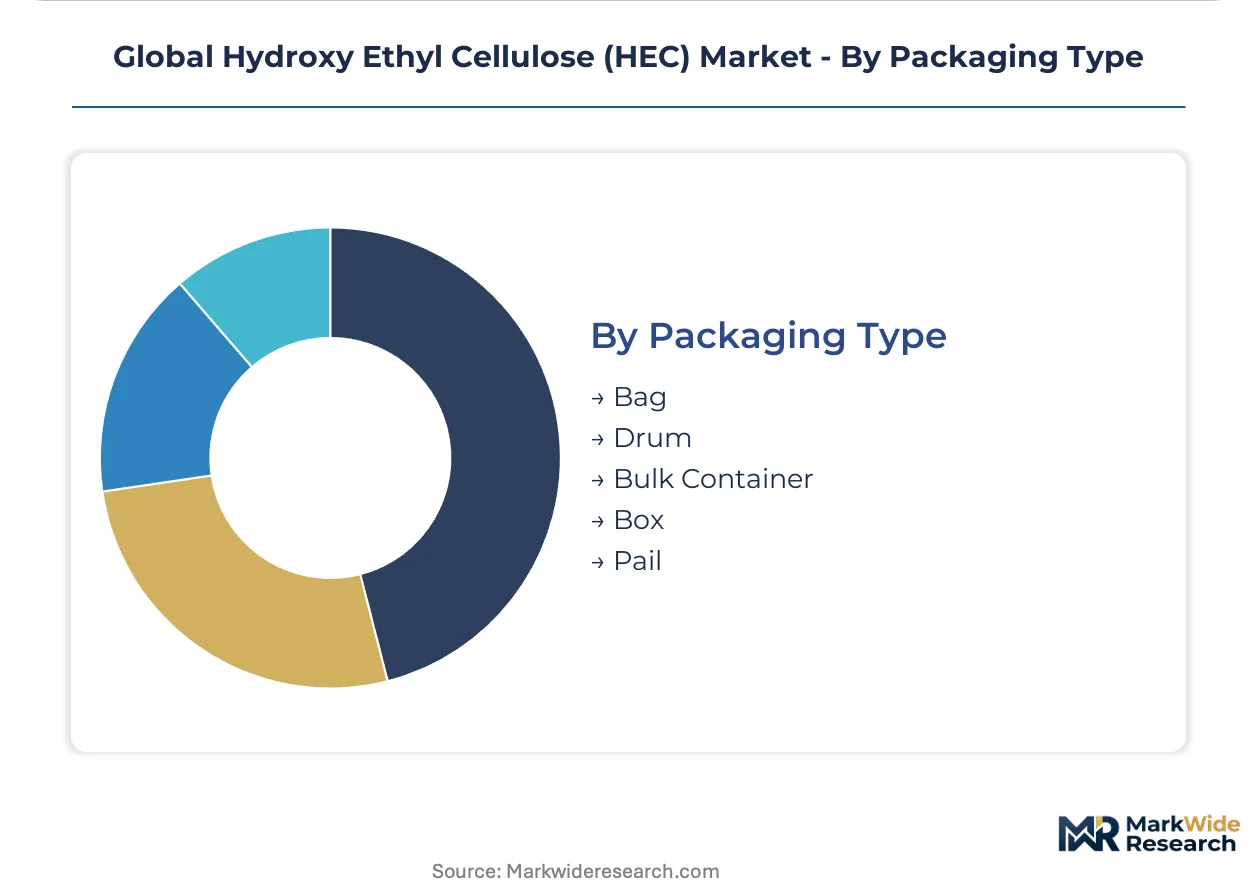
Supply concentration in bag and bulk formats reflects downstream manufacturing scale, while drum and pail segments serve mid-volume formulators lacking bulk handling infrastructure.
- Bag:Multi-wall paper sacks with polyethylene liners dominate powder shipment to coating plants and construction sites. German and Chinese coating clusters receive containerized bagged volumes through Rotterdam and Shanghai ports.
- Bulk Container:Flexible intermediate bulk containers reduce per-kilogram packaging cost for large coating manufacturers with pneumatic conveying systems.
- Drum:Steel and fiber drums protect solution grades from contamination in cosmetics and pharmaceutical channels.
- Pail:Five-gallon plastic pails target mid-volume adhesives and sealants compounders.
- Box:Corrugated containers with inner bags serve specialty fiber and flake grades in lower-volume oilfield applications.
Bag formats command the established base. Bulk Container adoption is gaining share fastest on logistics cost pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal bio-content mandates are redirecting procurement specifications toward renewable carbon claims, while China's dual carbon goals accelerate water-borne coating substitution in manufacturing clusters. This regulatory divergence is fragmenting compliance pathways for cellulose ether suppliers.
China
Shandong and Jiangsu province coating producers are absorbing rising HEC volumes as water-borne architectural formulations displace solvent systems. SAMR enforces GB standards for cosmetic-grade cellulose ethers, creating distinct registration requirements from Western markets. The Yangtze River Delta concentration of paint manufacturers is driving fastest-incorporation rates for rheology modifiers.
Germany
Automotive refinish and industrial coating formulators in Bavaria and North Rhine-Westphalia specify viscosity grades from 5,000 to 100,000 mPa·s under tightening VOC regulations. REACH registration dossiers mandate full toxicological profiles for cellulose ether imports, with ECHA's 2024 polymer characterization guidance forcing resubmissions. The Ruhr industrial corridor anchors European demand for certified construction-grade HEC.
United States
EPA residual thresholds under the Toxic Substances Control Act are pulling high-purity HEC grades into consumer-facing applications ahead of compliance deadlines. Texas and Louisiana host ethylene oxide production clusters that feed captive supply strategies for integrated cellulose ether producers. Gulf Coast oilfield service companies specify salt-tolerant polymer grades for shale formation drilling.
India
Pharmaceutical excipient demand in Maharashtra and Gujarat is climbing as CDSCO registration pathways for cellulose ethers remain underexploited by Western suppliers relative to FDA precedents. The national pharmaceutical regulator is streamlining approval timelines for excipient imports. Mumbai-Pune industrial corridor formulators are qualifying bio-based thickeners for generic drug manufacturing.
Japan
Ultra-high-purity HEC grades for electronics and cosmetics applications face METI chemical substance reporting requirements alongside PMDA pharmaceutical excipient standards. The Kanto region around Tokyo concentrates personal care manufacturing demanding 12-18 month supplier audit cycles. Osaka-Kobe industrial zone electronics chemical blenders are specifying low-ash content below 0.5% for display manufacturing.
Global Hydroxy Ethyl Cellulose (HEC) Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive ethylene oxide supply and regional specialists with purity-focused positioning. Market structure shows moderate consolidation at the premium tier alongside fragmented mid-scale supply. Three archetypes dominate: backward-integrated multinationals with feedstock control, Asia-Pacific purity specialists serving electronics and cosmetics, and regional distributors with formulation technical service. Competitive moves center on continuous reactor technology licensing and single-source accountability contracts with coating manufacturers.
Among integrated chemical producers, Ashland and Dow Chemicals exemplify the feedstock-control archetype through in-house production of critical inputs. Shin-Etsu Chemicals Co., Ltd. occupies a position within the ultra-high-purity specialist tier, anchoring quality differentiation for Asian electronics and personal care channels. These three represent divergent strategic postures: captive supply insulation, manufacturing scale across viscosity grades, and purity-grade certification depth respectively.
| Leading Market Players |
|---|
| Ashland |
| Dow Chemicals |
| Shin-Etsu Chemicals Co., Ltd. |
| AkzoNobel N.V. |
| Daicel Corporation |
| Lotte Fine Chemicals |
| Chemcolloids Ltd. |
| Zhejiang Haishen New Materials Limited |
| Wuxi Sanyou New Material Technology Co., Ltd. |
| Others |
Supply & Pricing Matrix
Bio-based thickener substitution in water-borne coatings is simultaneously redrawing procurement geography around Shandong and Jiangsu provinces and compressing margin structures for non-integrated HEC suppliers lacking captive ethylene oxide supply.
Pricing Analysis
Cost-plus contracts indexed to ethylene oxide spot markets dominate long-term supply agreements between integrated producers and coating manufacturers. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and construction-grade levels separates certified supply chains from commodity volumes. Cost compression in construction-tier HEC is intensifying because polyacrylate thickeners retain cost advantages in price-sensitive tile adhesive applications. Coatings producers show highest price sensitivity due to volume consolidation and single-source accountability demands, while cosmetics manufacturers accept premium positioning for just-in-time solution delivery.
Supply Chain Analysis
Inventory cycles stretch 6-10 weeks for powder grades moving through Rotterdam and Shanghai ports, compressing to 2-3 days for solution formats serving just-in-time cosmetics manufacturing. Manufacturing concentrates in China, the United States, and Germany, with ethylene oxide feedstock anchoring location decisions. The supply chain draws from cellulose pulp, ethylene oxide, and caustic soda inputs, with ethylene oxide price volatility transmitting directly into margin pressure. Single-source vulnerability runs through Shandong province coating clusters where downstream formulators consolidate thickener suppliers. Distribution runs through specialty chemical distributors with technical service capabilities for mid-volume formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between REACH, EPA, and SAMR compliance pathways fragments qualification requirements, creating specialist niches for purity-focused suppliers and regional certification experts.
For Market Incumbents: Shield market position through captive ethylene oxide supply expansion in Texas and Louisiana production clusters, while accelerating ISO 9001 certification depth for pharmaceutical-grade supply chains. Synthetic polymer substitution in construction applications and emerging Chinese purity specialists represent converging threats. Backward integration into cellulose feedstock secures cost insulation against pulp price volatility.
For New Entrants and Emerging Players: Technical service gaps in CDSCO registration support for Indian pharmaceutical excipient demand offer immediate white-space access. Target Maharashtra and Gujarat formulators with streamlined regulatory dossier preparation, leveraging underexploited pathways relative to FDA precedents. Direct-to-formulator digital channels for mid-volume cosmetics manufacturers provide a defensible go-to-market angle against established distributor relationships.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors purity-grade specialists with established ECHA dossiers and Asian electronics channel access. Long-term viability hinges on continuous reactor technology licensing positions and single-source accountability contracts with German automotive refinish manufacturers. Watch for ethylene oxide feedstock control acquisitions as the inflection signal indicating margin compression acceleration for non-integrated competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive supply insulation from spot-market volatility secures cost positions in North American coatings. |
| Continuous Reactor Technology Licensing | Semi-continuous etherification designs cut feedstock consumption per ton while raising purity floors. |
| CDSCO Registration Pathway Investment | Streamlined Indian pharmaceutical excipient approvals unlock underexploited demand in Maharashtra clusters. |
| Single-Source Accountability Contracts | German automotive refinish manufacturers consolidate thickener suppliers to reduce qualification overhead. |
| Just-in-Time Digital Platform Launch | Specialty distributors target mid-volume cosmetics manufacturers with solution-grade delivery contracts. |
Research Methodology
A spread of perspectives from plant managers at integrated cellulose ether producers, procurement leads at German coating manufacturers, distribution channel partners, and technical R&D directors converged on the working assumptions. Primary interview insights combined with customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration dossiers. Bottom-up volume modeling triangulated against top-down value estimates across viscosity grades and end-use specifications.
Segmentation dimensions modeled include product format, application tier, end-user industry, packaging type, and regional production hub across the analysis window. CAGRs were derived from elasticity-adjusted demand projections and substitution rate assumptions. Forecast inputs incorporated REACH compliance cost escalation, EPA residual threshold enforcement timelines, and water-borne coating penetration rates in Chinese architectural markets.
Underlying assumptions cover regulatory enforcement intensity, feedstock price correlation stability, and substitution elasticity between HEC and synthetic thickeners, with deviation risk concentrated in ethylene oxide supply disruptions and Chinese environmental policy shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
Global Cyclodextrin Market
Specialty Chemicals
Carnauba Wax Market
Specialty Chemicals
Sandarac Market
Specialty Chemicals
Epoxidized Soybean Oil Market
Specialty Chemicals
Specialty Methacrylate Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Ethyl Cellulose Market
Specialty Chemicals
Structure Directing Agents Market
Specialty Chemicals
Phytosphingosine Market
Specialty Chemicals
North America Aerosol Cans Market
Specialty Chemicals
Metominostrobin Market
Specialty Chemicals
Plastic Stabilizer Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Spiroglycol Market