
 Metal Stamping Market | 2026-2036
Metal Stamping Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Stamping Market Intelligence
Maintenance contracts and predictive tooling services is pivoting how press operators monetize capacity beyond per-piece billing. Gestamp Automoción leverages its European die-shop network to anchor long-term service agreements with vehicle assemblers. Magna International Inc. competes through North American stamping scale while integrating sensor-based die monitoring. Kenmode, Inc. specializes in precision progressive-die work for medical and electronics customers, sustaining premium pricing through tight tolerance capability.
Metal stamping is a cold-forming process wherein flat sheet metal—typically steel, aluminum, or copper alloys ranging from 0.1 mm to 6.35 mm thickness—is shaped between hardened dies under pressures exceeding 1,000 tons to produce dimensionally repeatable components. Its primary industrial purpose is high-volume manufacture of complex geometries at cycle speeds below one second per part for automotive body panels, appliance housings, and electronic enclosures. Progressive die stamping commands the largest share of installed press capacity owing to its compatibility with coil-fed automation and continuous throughput economics. Fine blanking captures disproportionate margin pools in aerospace and powertrain applications where shear-edge quality eliminates secondary machining. Servo press technology is displacing mechanical flywheel drives in new installations as programmable slide motion reduces die wear and enables warm-forming of advanced high-strength steels.
EPA emissions standards and NHTSA corporate average fuel economy rules in the United States compel automakers to adopt lighter stamped aluminum and multi-material assemblies, directly shaping alloy procurement and die design requirements. REACH chemical restrictions in Europe limit lubricant formulations and surface treatment chemistries used in stamping plants, elevating compliance costs for exporters. China's GB standards for automotive structural components mandate specific tensile strength ratings that press shops must certify through accredited testing laboratories. Stakeholders should monitor how carbon-border adjustment mechanisms and evolving crash-test protocols in target export markets redefine material qualification timelines and capital equipment replacement cycles.
Market Dynamics
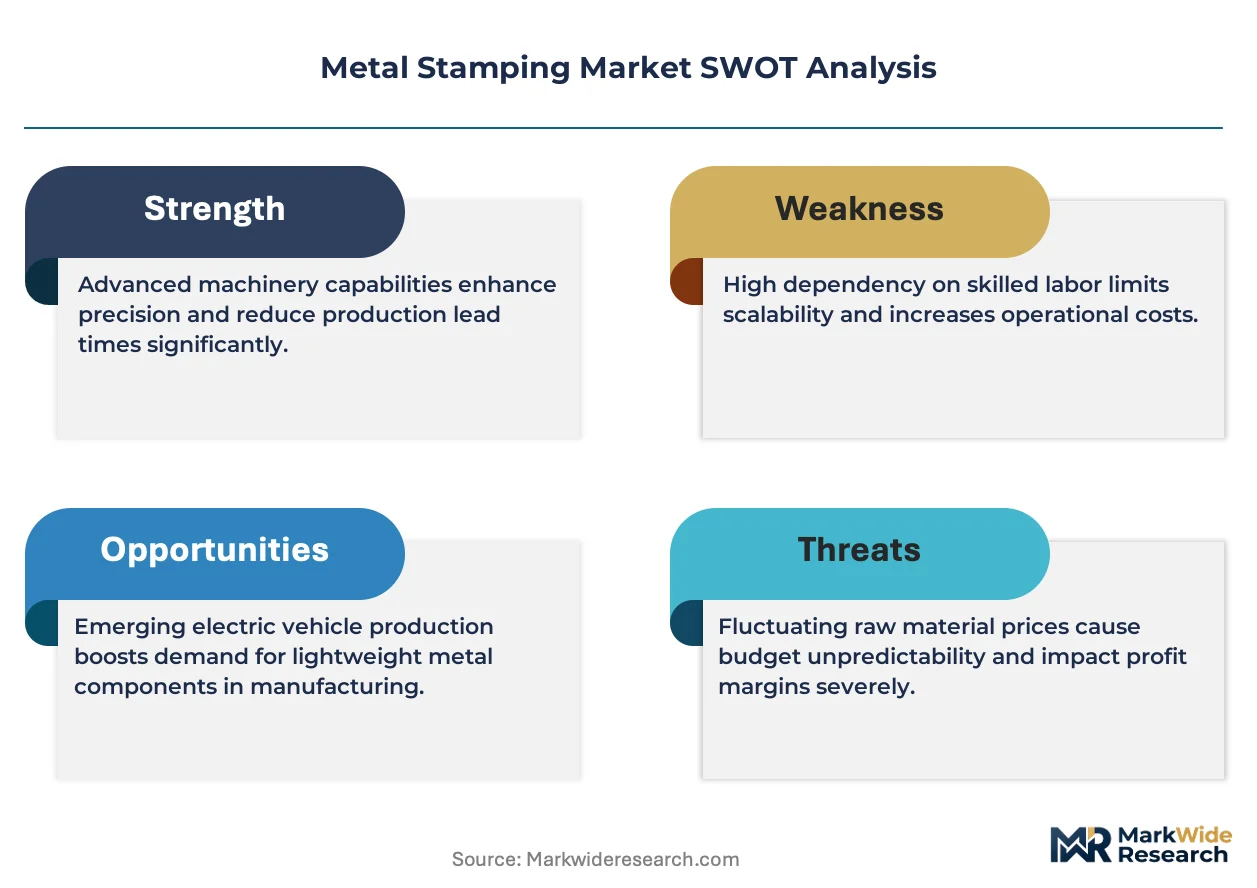
Servo-electric press technology is compressing die-changeover windows and enabling warm-forming of advanced high-strength steels, forcing capital equipment replacement cycles across automotive supply chains.
Growth Catalysts
- EPA and NHTSA fuel economy mandates:United States emissions rules compel automakers to adopt stamped aluminum chassis components, directly expanding alloy-capable press capacity requirements.
- Progressive die automation:Coil-fed continuous throughput economics in automotive body-in-white production sustains demand for high-tonnage mechanical and servo press installations.
- China's GB structural standards:Mandatory tensile strength certifications for automotive components require press shops to maintain accredited testing laboratory relationships, filtering out sub-scale operators.
Market Restraints
- Tool steel supply concentration:Premium die materials concentrate among specialized European and Japanese metallurgical suppliers, exposing stampers to alloy price volatility and extended lead times.
- REACH chemical restrictions:European lubricant formulation limits elevate compliance costs for exporters serving EU automotive OEMs, compressing margin on legacy contract structures.
- Die fabrication bottleneck:Skilled tool-and-die craft scarcity in Germany and the United States extends new program development timelines beyond 18 months for complex progressive dies.
Strategic Opportunities
- India automotive manufacturing expansion:PLI scheme incentives for electric vehicle production create virgin demand for localized stamping capacity serving domestic and export OEM assembly.
- Predictive tooling services:Sensor-integrated die monitoring enables outcome-based maintenance contracts that monetize press uptime rather than per-piece volume alone.
- Fine blanking convergence:Hybrid servo-hydraulic press architectures are penetrating aerospace and medical device applications where shear-edge quality eliminates secondary machining operations.
Industry Challenges
- Controls engineering talent scarcity:Servo press programming and motion optimization expertise concentrates among a narrow cohort of technicians, constraining fleet upgrade velocity.
- Multi-material joining qualification:Aluminum-steel dissimilar metal stamping assemblies require new adhesive and mechanical fastening certifications that prolong automotive program approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Stamping Market |
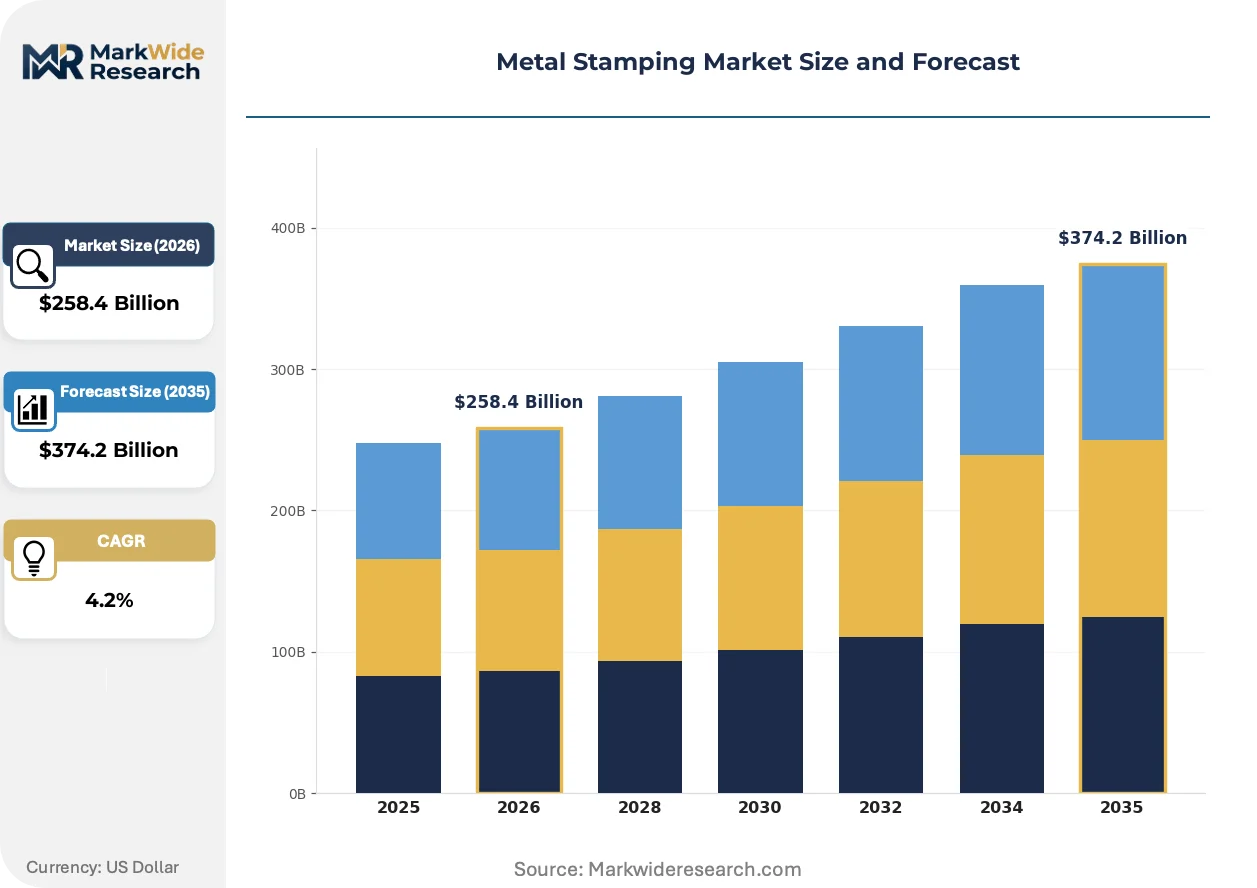
| Market Size in 2026 | $258.4 Billion |
| Market Size in 2035 | $374.2 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Progressive Die, Transfer Die, Compound Die, Fine Blanking, Coining Technology: Hydraulic, Mechanical, Pneumatic, Servo, Magnetic Application: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers End User Industry: Consumer Electronics, White Goods, Aerospace, Agriculture Equipment |
| Companies Covered | Gestamp Automoción, Arconic Corporation, Magna International Inc., AAPICO Hitech Public Company Limited, Kenmode, Inc., Manor Tool & Manufacturing Company, D&H Industries, Inc., Clow Stamping Company, Interplex Holdings Pte. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Stamping Market Strategic Shifts & Innovations
Servo press architectures are rewriting forming process control, die longevity economics, and warm-forming feasibility for advanced alloys across automotive and industrial end-uses.
Servo-electric press technology is absorbing the programmable slide motion and energy-recovery functions that mechanical flywheel drives cannot replicate. Automotive OEMs in Germany and Japan are specifying servo architectures for new greenfield installations at accelerating rates. The technology is absorbing capital allocation that would otherwise flow to refurbished mechanical presses, compressing the installed base of legacy equipment.
REACH chemical restrictions and evolving EU Green Deal carbon-border adjustment mechanisms are reshaping lubricant procurement and surface treatment process selection. Stamping exporters to Europe must document full chemical compliance across coating and cleaning chemistries or face market access barriers. Automotive tier-one suppliers in China and the United States are accelerating water-based and dry-film lubricant qualification to preempt regulatory friction.
After-sales service unbundling is fragmenting traditional per-piece contract structures into discrete die monitoring, predictive maintenance, and tooling refresh subscriptions. Automotive OEM procurement teams in North America are piloting uptime-guarantee agreements that transfer die-wear risk to stampers. This shift is most visible in long-term chassis component supply agreements where vehicle platform lifecycles exceed seven years.
Metal Stamping Market Segmentation
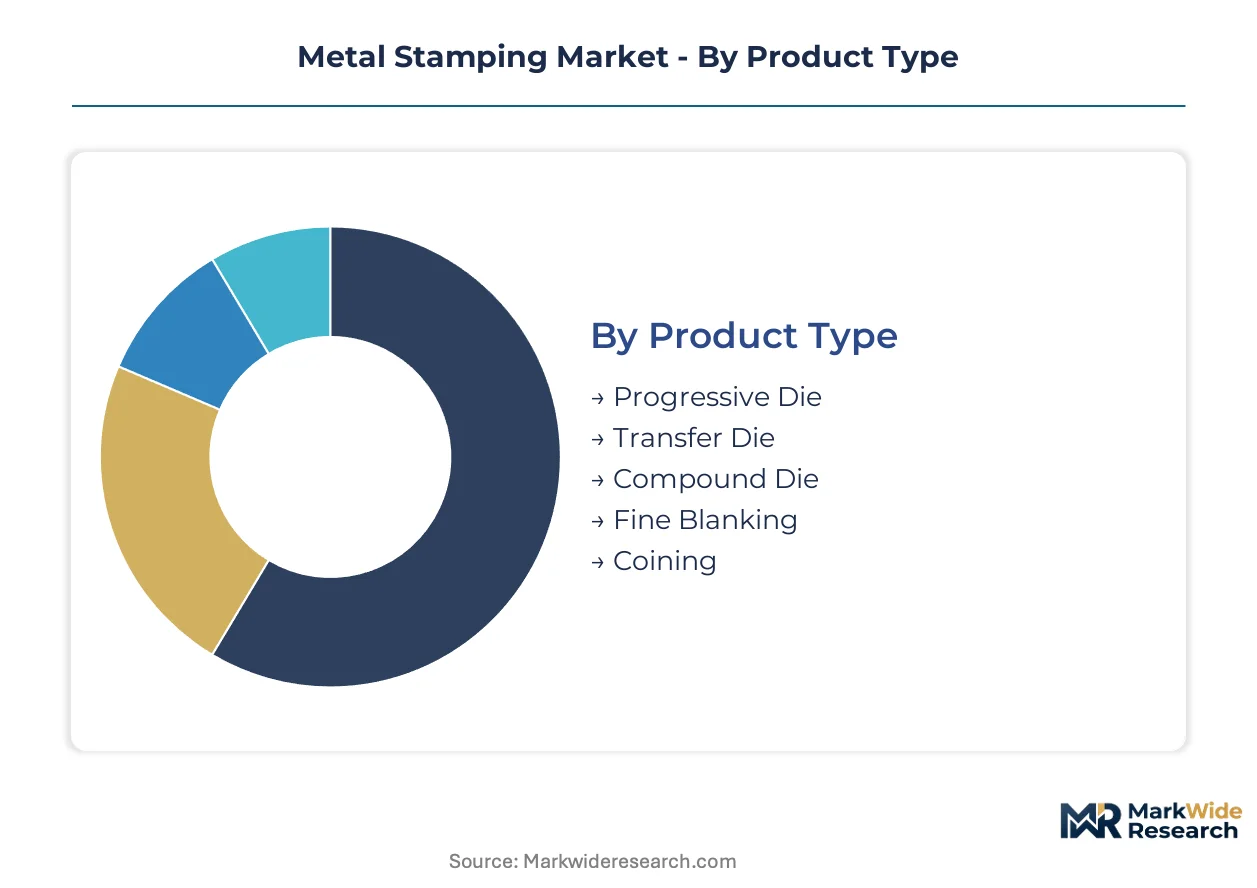
Process selection in metal stamping directly determines capital intensity, tooling lead times, and contract eligibility for automotive and industrial OEMs. Segment boundaries reflect how buyers prioritize throughput economics against precision requirements and alloy flexibility.
Product Type:
Buyers differentiate by production volume thresholds and geometric complexity tolerance.
- Progressive Die:Coil-fed continuous forming through sequential die stations achieves sub-second cycle times for high-volume automotive body panels. Demand concentrates in Germany and the United States where vehicle assemblers mandate uninterrupted supply for just-in-sequence manufacturing.
- Transfer Die:Robotic part transfer between discrete stations accommodates deeper draws and larger blanks than progressive configurations permit. Tier-1 chassis suppliers in China deploy transfer lines for pickup truck bed and door inner panels where material thickness exceeds 2mm.
- Compound Die:Single-station piercing and blanking suits low-volume appliance and hardware applications with minimal tooling investment.
- Fine Blanking:Triple-action press kinematics produce shear edges with 90% clean-cut ratio, eliminating secondary machining for powertrain and aerospace components.
- Coining:High-pressure compression forming creates precise surface relief for decorative hardware and electronic connector contacts.
Progressive die leads volumes today; fine blanking is gaining share fastest.
Technology:
Power source selection shapes energy recovery, slide programmability, and warm-forming capability for advanced high-strength steels.
- Servo:Programmable crank motion with regenerative braking reduces die wear and enables velocity profiling for aluminum warm-forming. Japanese and German OEMs specify servo architectures for new greenfield installations.
- Mechanical:Flywheel-driven crank presses dominate legacy installed base with lowest capital cost per ton, constraining fleet upgrade velocity amid controls engineering scarcity.
- Hydraulic:Constant tonnage through full stroke suits deep-drawing operations for agricultural equipment housings and fuel tanks.
- Pneumatic:Compressed air systems serve low-force blanking and forming in electronics and medical device workshops.
- Magnetic:Linear motor direct drive eliminates mechanical transmission losses for precision micro-forming applications.
Mechanical retains installed base dominance; servo is expanding most quickly.
Application:
Contract structure and qualification burden vary sharply by buyer integration level and platform lifecycle exposure.
- Vehicle Assemblers:Direct OEM relationships carry seven-year platform commitments, predictive maintenance obligations, and die-wear risk transfer. NHTSA fuel economy mandates compel aluminum stamping adoption.
- Tier-1 Suppliers:Intermediate position demands dual qualification for OEM systems plus modular design flexibility across vehicle programs.
- OEMs:Captive stamping operations in appliance and electronics sectors prioritize die standardization across product generations.
- Aftermarket Providers:Low-volume, short-lead replacement panels and repair components tolerate higher per-piece costs.
Vehicle assemblers anchor revenue concentration; Tier-1 suppliers show steepest contract expansion.
End User Industry:
Surface finish specifications, alloy portfolios, and certification requirements segment demand by downstream sector.
- Consumer Electronics:Stainless steel and aluminum enclosures for smartphones and laptops demand tight tolerances below 0.05mm with cosmetic surface quality.
- White Goods:Refrigerator and washing machine panels prioritize corrosion-resistant coated steels with cost-optimized blanking strategies.
- Aerospace:Titanium and heat-resistant alloy forming for structural brackets and engine components requires NADCAP-accredited heat treatment and non-destructive testing.
- Agriculture Equipment:Thick-gauge steel components for tractors and harvesters emphasize durability over precision, tolerating rougher edge conditions.
White goods leads volume absorption; aerospace commands premium margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed press capacity, while Germany concentrates the most sophisticated die engineering expertise. Mexico is absorbing relocated North American automotive stamping volume at accelerating rates.
China
Domestic EV production by BYD and NIO is driving aluminum stamping adoption for battery enclosures and lightweight chassis. GB standards for automotive structural components mandate tensile strength certifications that filter out sub-scale operators. The Yangtze River Delta clusters in Shanghai and Jiangsu province host the densest concentration of high-tonnage servo press installations serving vehicle assemblers.
Germany
Premium vehicle platforms from BMW and Mercedes-Benz require precision progressive-die capacity for aluminum-intensive body-in-white assemblies. REACH chemical restrictions limit lubricant formulations, elevating compliance costs for surface treatment processes. The Stuttgart and Munich industrial corridors concentrate captive stamping operations and specialized tool-and-die craft labor pools.
United States
EPA emissions standards and NHTSA fuel economy rules compel Detroit Three automakers to adopt stamped aluminum chassis components. The Inflation Reduction Act domestic content provisions are reshaping alloy procurement toward North American-sourced aluminum. Michigan and Ohio anchor the densest supplier networks, with Indiana emerging as a greenfield servo press destination.
Mexico
Nearshoring of North American automotive supply chains is driving greenfield stamping investments for export-oriented assembly plants. The country's automotive regulator aligns safety certifications with US FMVSS standards to maintain cross-border market access. Nuevo León and the Bajío Region concentrate new capacity serving Tesla, BMW, and General Motors assembly operations.
Japan
Hybrid and hydrogen fuel cell vehicle programs sustain demand for precision fine blanking in powertrain component manufacturing. METI industrial decarbonization roadmaps are pressuring stampers to electrify press fleets and document carbon intensity. The Nagoya industrial belt in Aichi prefecture hosts Toyota's captive stamping network and its tier-one supplier base.
Metal Stamping Market Key Industry Players
Top-tier vendors anchor long-term OEM service agreements, while mid-scale specialists compete on die-changeover flexibility and alloy-specific expertise. The market structure reflects a tiered hierarchy where scale-driven chassis suppliers coexist with precision-focused medical and electronics stampers. Three archetypes dominate: integrated automotive tier-ones with captive die shops, independent high-volume contract manufacturers, and niche specialists in fine blanking or progressive-die microminiature work. Consolidation is accelerating through die-shop network acquisitions, while technology licensing agreements spread servo press programming capabilities beyond original equipment vendors.
Within the European integrated tier, Gestamp Automoción and Magna International Inc. exemplify scale-driven automotive suppliers with continental die-shop networks. Kenmode, Inc. occupies a position among North American precision specialists serving medical device and electronics end-uses. AAPICO Hitech Public Company Limited represents Southeast Asian contract manufacturing expansion serving Japanese and Korean OEM assembly in Thailand.
| Leading Market Players |
|---|
| Gestamp Automoción |
| Arconic Corporation |
| Magna International Inc. |
| AAPICO Hitech Public Company Limited |
| Kenmode, Inc. |
| Manor Tool & Manufacturing Company |
| D&H Industries, Inc. |
| Clow Stamping Company |
| Interplex Holdings Pte. Ltd. |
| Others |
Cost & Logistics Intelligence
Servo-electric press adoption is simultaneously compressing per-piece forming costs and concentrating procurement power among tier-one suppliers capable of justifying capital replacement cycles. This technology transition feeds back into alloy sourcing decisions as warm-forming capability for advanced high-strength steels becomes a contract qualification threshold for automotive OEMs.
Pricing Analysis
Capacity additions in Mexico are reshaping price floors for North American chassis component contracts. Three-tier pricing structure across premium, standard, and economy levels separates OEM direct relationships with predictive maintenance obligations from spot-market transactional work. Cost compression in standard-tier progressive die services is intensifying because transfer press capacity is expanding faster than qualified die engineering labor pools. Tier-one suppliers with captive servo press fleets show lowest price sensitivity; independent job shops competing for appliance and hardware contracts face acute margin pressure.
Supply Chain Analysis
Tool steel supply rests on specialized metallurgical producers in Germany, Japan, and Austria. Premium die materials, servo motor drives, and precision ball screw assemblies feed from concentrated upstream tiers. Single-source vulnerability in specialized European and Japanese alloy suppliers exposes stampers to extended lead time risk. Distribution runs through tier-one supplier networks anchored to vehicle assembler clusters in Michigan, Stuttgart, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Mexico's manufacturing cost structure undercuts legacy Midwest capacity while maintaining NHTSA-aligned regulatory access. The spread between US Inflation Reduction Act domestic content requirements and Mexico's nearshoring incentives creates relocation pressure.
For Market Incumbents: Lock in long-term die-wear risk transfer agreements with Detroit Three and German premium OEMs before predictive maintenance contracts commoditize. Secure captive tool steel supply relationships with ThyssenKrupp or Nippon Steel subsidiaries to isolate alloy price volatility. Vertical integration into in-house die fabrication compresses development timelines below the 18-month industry average. For New Entrants and Emerging Players: Medical device OEMs with sub-0.05mm tolerance requirements represent an underserved buyer archetype where Kenmode's premium positioning leaves mid-scale capacity gaps. Target Indian electric vehicle stampers under the PLI scheme before domestic servo press capacity saturates. Lead with NADCAP-accredited fine blanking capability to bypass commodity progressive die competition. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale German tool-and-die shops facing craft labor scarcity and family succession transitions. Long-term viability hinges on servo press programming talent retention and automotive platform lifecycle exposure. Watch for carbon-border adjustment mechanism implementation in EU automotive supply chains as inflection indicator for alloy sourcing cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Servo Press Fleet Conversion | Programmable slide motion reduces die wear and unlocks aluminum warm-forming contracts with BMW and Mercedes-Benz. |
| Die Shop Network Acquisition | Captive tool fabrication compresses program development timelines below 18 months for complex progressive dies. |
| Predictive Maintenance Service Launch | Sensor-based die monitoring enables uptime-guarantee contracts that monetize press availability beyond per-piece billing. |
| India Greenfield Capacity Buildout | PLI scheme incentives for electric vehicle production create virgin demand for localized aluminum stamping capability. |
| REACH-Compliant Lubricant Qualification | Water-based and dry-film chemistry certification preserves EU automotive OEM market access against chemical restriction barriers. |
Research Approach
Multiple input streams — press OEM technical documentation, automotive tier-one procurement interviews, and customs trade flow records — were reconciled to construct bottom-up and top-down market estimates. Primary discussions with die engineering directors, OEM platform sourcing managers, servo press controls specialists, and aftermarket service heads were validated against secondary sources including EPA emissions filings, NHTSA fuel economy compliance data, vehicle production databases, and SEC 10-K disclosures from stamped component suppliers.
Data-stream reconciliation across product type, technology architecture, application tier, and end-user industry dimensions anchored volume and value projections throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macro automotive production trajectories and capital equipment replacement cycle analysis. Servo press adoption curves, GB standard certification timelines, and REACH chemical compliance cost burdens served as industry-specific forecast inputs.
Inputs from automotive OEM procurement teams and press manufacturer order backlogs were available through the study window; gaps in privately held job shop financial performance introduce uncertainty bands in independent contractor market sizing. Forecasts reflect documented assumptions regarding vehicle platform lifecycle durations and alloy substitution elasticities under fuel economy mandates. A small set of triggers — carbon-border adjustment mechanism rollout, tool steel tariff restructuring, and servo controls engineering wage inflation — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Modified Wood Market
Industrial Materials
Soil Stabilization Materials Market
Industrial Materials
Polymer Bearing Market
Industrial Materials
Extruders and Compounding Machines Market
Industrial Materials
Industrial Standoff and Spacer Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Lip Seals Market
Industrial Materials
Metal Heat Treatment Market
Industrial Materials
Wood Fiber Insulation Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
Middle-East and Africa Engineering Plastics Market
Industrial Materials
Fiberglass Tanks Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Mesh Nozzle Plates Market