
 Plastic Gears Market | 2026-2036
Plastic Gears Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Gears Market Outlook
The EU Green Deal is recalibrating material selection protocols across European manufacturing supply chains, compelling gear producers to validate lifecycle emissions for every polymer grade. Vigor Precision Limited leverages captive injection-molding capacity across southern China to serve robotics OEMs with tight tolerance acetal gearing. Oechsler AG anchors its competitive position through medical-grade cleanroom production that meets FDA and MDR requirements for surgical device actuators. Gleason sustains technology leadership in gear metrology systems that verify plastic tooth profiles against AGMA and ISO accuracy standards.
Plastic gears are mechanical power transmission elements injection-molded or machined from engineering thermoplastics such as acetal, nylon, polycarbonate, or reinforced PEEK, typically operating at loads and speeds below equivalent metal counterparts while offering corrosion immunity, weight reduction, and acoustic damping in precision motion systems. Spur gears dominate unit volume due to their geometric simplicity and lowest mold tooling cost, though helical variants capture expanding share in consumer electronics camera modules where noise suppression commands premium positioning. Medical devices represent the fastest-growing application segment as single-use instrument mandates and sterilization compatibility requirements drive resin formulation innovation toward gamma-stable polymer grades.
FDA 21 CFR material compliance and EU MDR biocompatibility frameworks govern medical device gear acceptance, while automotive OEMs enforce IATF 16949 quality management with PPAP submission protocols that filter out undifferentiated molders. EPA regulations on per- and polyfluoroalkyl substances constrain legacy lubricant additives, accelerating dry-running polymer compound development. Stakeholders must monitor evolving EU Ecodesign requirements for repairability and material recyclability, as these standards will determine which polymer platforms retain qualification across next-generation appliance and industrial product categories.
Market Dynamics
Automotive electrification programs are recalibrating procurement specifications across transmission and actuator systems, compelling tier suppliers to revalidate polymer formulations for higher torque densities and thermal cycling endurance.
Growth Catalysts
- REACH restrictions on metal finishing:ECHA's phased constraints on hexavalent chromium plating redirect engineering investment toward molded acetal and nylon alternatives in precision motion systems.
- Medical device single-use mandates:FDA 21 CFR and EU MDR biocompatibility frameworks accelerate gamma-stable PEEK gear adoption in surgical robotics and disposable instrument actuators.
- Industrial automation density:Germany's precision manufacturing corridor concentrates demand from robotics OEMs and packaging machinery builders seeking acoustic-dampening polymer gearing.
Market Restraints
- Resin price volatility:Engineering-grade acetal and reinforced PEEK compound costs fluctuate with caprolactam and polyether ether ketone monomer supply tightness, compressing molder margins on fixed-price contracts.
- Tooling capex concentration:High-cavity injection molds for helical gear profiles require hardened steel tooling investments that concentrate production capacity among specialized toolmakers in southern China and Bavaria.
- Load-speed ceiling:Thermoplastic tooth deflection under sustained torque limits polymer gearing to auxiliary rather than primary powertrain positions in heavy-load industrial applications.
Strategic Opportunities
- Underpenetrated surgical robotics:India's CDSCO medical device registration pathway and expanding private hospital networks create entry points for gamma-sterilizable gear suppliers in laparoscopic instrument actuators.
- EU Ecodesign repairability mandates:Brussels' forthcoming material recyclability standards favor disassemblable polymer gear trains over permanently lubricated metal alternatives in appliance and power tool categories.
- Additive manufacturing convergence:Fused filament fabrication of fiber-reinforced nylon is rewriting prototyping economics and enabling geometrically complex internal gearing for custom robotics integrators.
Industry Challenges
- Metrology skill scarcity:AGMA and ISO plastic gear accuracy verification requires specialized coordinate measuring machine operators and polymer-specific shrinkage compensation expertise that outpaces vocational training output.
- Dual certification timelines:Simultaneous FDA 510(k) and EU MDR technical documentation preparation extends medical gear qualification cycles and strains regulatory affairs bandwidth at mid-cap molders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Gears Market |
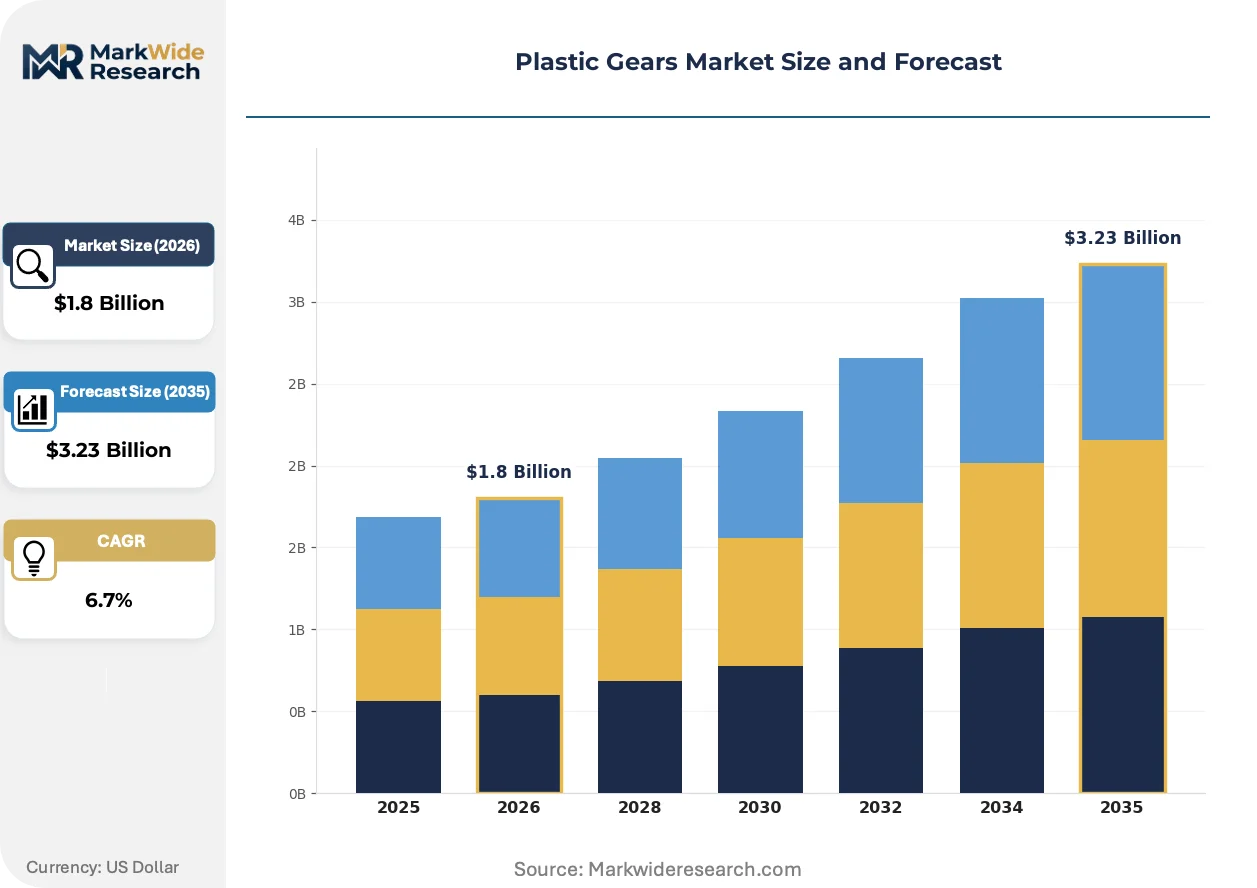
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spur Gears, Helical Gears, Bevel Gears, Worm Gears Application: Automotive, Consumer Electronics, Industrial Machinery, Medical Devices Material: Polycarbonate, Nylon, Acetal, PVC End User: Aerospace, Robotics, Telecommunications, Appliance Manufacturers |
| Companies Covered | Vigor Precision Limited, IMS Gear, Creative & Bright Group, Winzeler Gear, Oechsler AG, Designatronics, Essentra, Gleason, AmTech International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Gears Market Strategic Shifts
Material science breakthroughs and regulatory recalibration are compressing development cycles and expanding addressable applications for precision polymer power transmission components.
Carbon-fiber-reinforced PEEK compounds are rewriting performance boundaries for high-temperature gear applications. Aerospace actuator suppliers and downhole drilling tool manufacturers are qualifying these materials for environments previously reserved for metal gearing. The structural consequence is displacement of stainless steel bevel gears in corrosive chemical processing equipment where dry-running operation eliminates lubricant contamination risks.
EPA regulations on per- and polyfluoroalkyl substances are constraining legacy PTFE lubricant additives in polymer compounds. Compounders are accelerating dry-running formulations with internal lubricants such as silicone and molybdenum disulfide that maintain FDA compliance. Medical device and food processing machinery segments are most affected, with gear producers submitting updated material master files to FDA and EFSA for additive-free resin platforms.
Consolidated procurement by automotive OEMs is compressing supplier qualification timelines and unbundling tooling ownership from production contracts. Tier-one transmission suppliers now specify mold cavity counts and maintenance schedules rather than purchasing molds outright. This pattern is most visible in Germany's automotive supply base, where electrified powertrain programs demand synchronized capacity ramps across multiple polymer gear families.
Plastic Gears Market Segmentation
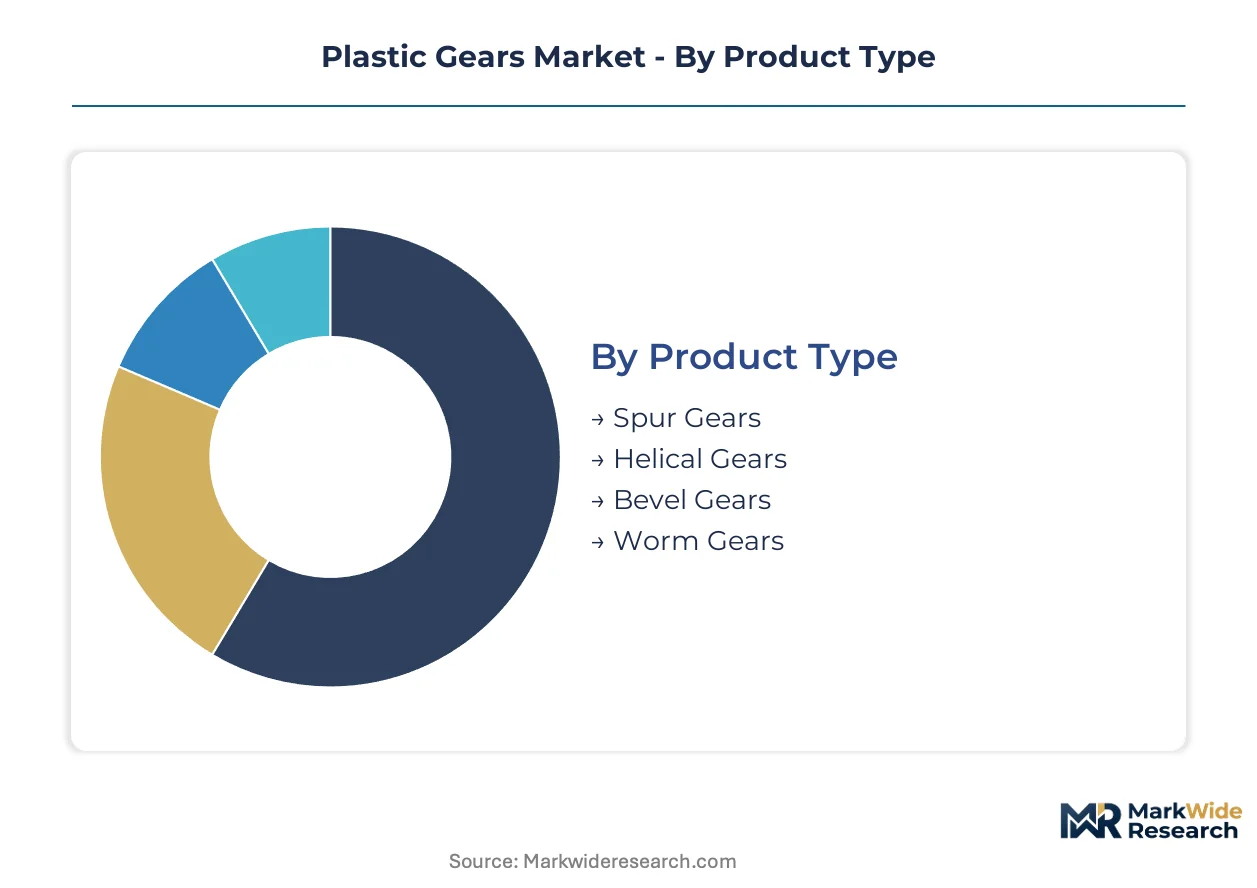
Segmentation in plastic gears determines tooling investment priorities and resin formulation roadmaps. Each dimension—geometry, application, material, and end-use—carries distinct certification burdens and margin structures that shape supplier specialization.
Product Type:
Upgrade cycles in product type follow mold tooling amortization schedules and tolerance tightening in downstream equipment. Manufacturers retire worn cavities as AGMA accuracy classes advance.
- Spur Gears:Simple cylindrical tooth geometry enables lowest-cost multi-cavity tooling and fastest cycle times in injection molding. Automotive electrification programs in Germany specify these for auxiliary actuator positions where noise tolerance permits straight-tooth engagement.
- Helical Gears:Angled tooth profiles distribute load across multiple contact points, reducing acoustic signature in precision motion systems. Consumer electronics camera modules in Japan and South Korea specify helical configurations for smartphone optical stabilization mechanisms where audible click elimination commands premium positioning.
- Bevel Gears:Conical tooth geometry transmits power between intersecting axes in compact driveline arrangements.
- Worm Gears:Screw-and-wheel engagement provides high reduction ratios and self-locking characteristics for lifting and positioning equipment.
Spur gears sit at the top of the volume ranking, with helical gears climbing the fastest.
Application:
Application segmentation maps directly to regulatory exposure and qualification timeline intensity. Medical and automotive verticals impose the longest validation cycles.
- Automotive:Electrified powertrain actuators and transmission subsystems demand thermoplastic gears validated for thermal cycling endurance and torque density. IATF 16949 compliance with PPAP submission protocols filters supplier bases in Germany, Japan, and the United States.
- Medical Devices:Single-use surgical instruments and robotic actuators require gamma-stable polymer grades meeting FDA 21 CFR and EU MDR biocompatibility frameworks. Gamma sterilization compatibility drives resin formulation innovation toward PEEK and specialized acetal compounds.
- Consumer Electronics:Miniaturized gearing for camera modules, wearables, and audio equipment prioritizes acoustic damping and weight reduction.
- Industrial Machinery:Packaging equipment and material handling systems utilize polymer gearing for corrosion immunity in washdown environments.
Automotive commands the largest revenue pool, while medical devices expands most quickly.
Material:
Material selection protocols are recalibrating under EU Green Deal lifecycle emissions requirements and REACH constraints on legacy additives.
- Acetal:Polyoxymethylene homopolymer and copolymer grades deliver low friction coefficients and dimensional stability in precision gearing. REACH restrictions on hexavalent chromium plating redirect engineering investment toward molded acetal alternatives in European industrial automation systems.
- Nylon:Polyamide compounds absorb moisture, requiring gear designers to compensate for dimensional change in tolerance-critical applications. Robotics OEMs in Germany specify glass-reinforced nylon for structural gears in collaborative robot joints.
- Polycarbonate:Optical clarity and impact resistance suit transparent inspection windows and light-guide integration in consumer products.
- PVC:Cost-positioned formulations serve low-load, high-volume appliance applications where temperature exposure remains moderate.
Acetal leads in precision applications, with nylon gaining share fastest in structural robotics gearing.
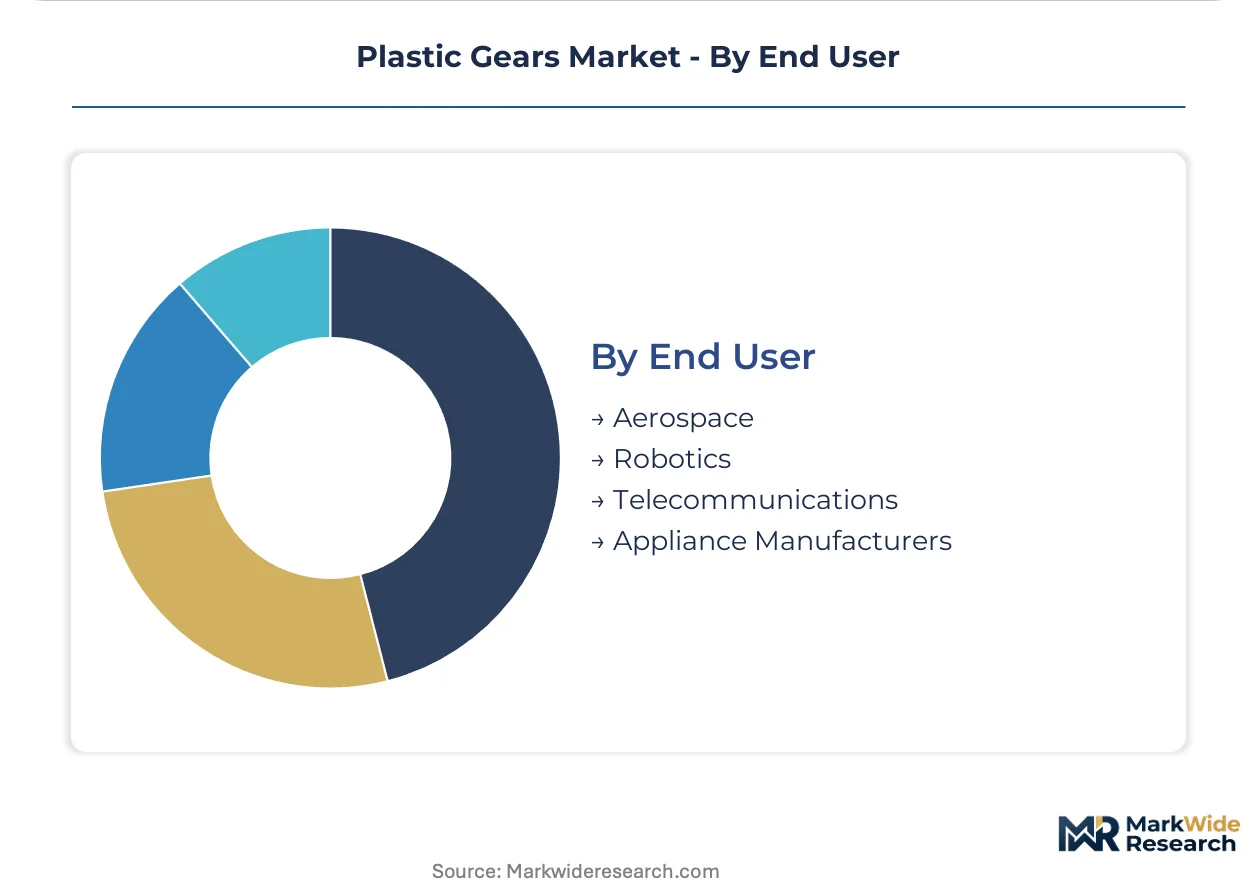
End User:
End user concentration determines geographic clustering of mold tooling and cleanroom capacity investments.
- Robotics:Collaborative and surgical robot OEMs specify tight-tolerance polymer gearing for joint actuators and end-effector mechanisms. Germany's precision manufacturing corridor concentrates demand from KUKA, Franka Emika, and surgical robotics specialists sourcing acoustic-dampening gearing.
- Aerospace:Actuator suppliers qualify carbon-fiber-reinforced PEEK gears for weight-critical flight control systems. Dry-running operation eliminates lubricant leakage risks in cabin-pressure environments.
- Telecommunications:Antenna positioning and fiber optic cable management equipment utilize low-backlash gearing for precise alignment.
- Appliance Manufacturers:Dishwasher, washing machine, and power tool producers specify disassemblable polymer gear trains ahead of EU Ecodesign repairability mandates.
Robotics anchors premium volume, with aerospace posting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision polymer gear manufacturing traces its commercial lineage to post-war Germany, where Bavarian toolmakers pioneered multi-cavity injection molding for automotive timing systems. This engineering heritage now distributes across three continents as electrification and medical device mandates reshape geographic demand patterns.
Germany
Automotive OEMs in Stuttgart and Munich drive procurement of acetal and nylon gearing for electrified powertrain actuators. ECHA REACH restrictions on hexavalent chromium plating redirect engineering investment from metal finishing toward molded thermoplastic alternatives. The precision manufacturing corridor around Nuremberg concentrates tier suppliers serving both domestic brands and export-oriented industrial automation customers.
United States
FDA 21 CFR compliance requirements accelerate gamma-stable PEEK gear adoption in surgical robotics and disposable instrument actuators. EPA regulations on per- and polyfluoroalkyl substances constrain legacy lubricant additives, compelling dry-running polymer compound development. Medical device clusters in Minneapolis and Boston anchor qualification timelines for biocompatible gearing.
China
Robotics OEMs in Shenzhen and Shanghai source tight-tolerance acetal gearing for collaborative robot joints and end-effector mechanisms. MIIT industrial upgrading programs incentivize domestic mold tooling capacity expansion. Southern China's captive injection-molding infrastructure serves both domestic automation builders and export markets.
Japan
Consumer electronics manufacturers in Tokyo and Osaka specify helical gear configurations for smartphone camera modules where noise suppression commands premium positioning. METI carbon neutrality roadmaps recalibrate material selection protocols toward lifecycle-validated polymer grades. Precision molding specialists in Nagoya supply optical equipment and wearable device integrators.
India
Private hospital network expansion and surgical robotics adoption create entry points for gamma-sterilizable gear suppliers in laparoscopic instrument actuators. CDSCO medical device registration pathways extend qualification cycles for foreign molders. Manufacturing investments in Pune and Bengaluru target import substitution for precision polymer components.
Plastic Gears Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the plastic gears market. Integrated molders owning hardened steel tooling and cleanroom capacity face pressure from specialized engineering firms that outsource manufacturing to certified partners. Three archetypes dominate: captive automotive tier suppliers, medical-grade cleanroom specialists, and precision-focused contract manufacturers. Consolidation concentrates among toolmakers in southern China and Bavaria, while mid-cap molders defend position through dual FDA-EU certification and synchronized capacity ramps.
Within the medical-grade specialization tier, Oechsler AG and Vigor Precision Limited exemplify divergent geographic strategies. Oechsler anchors European regulatory compliance through German GmbH structure. Vigor Precision occupies a position serving robotics OEMs from southern Chinese manufacturing bases. Gleason represents the metrology and verification archetype, sustaining technology leadership in gear measurement systems without direct molding operations. These three illustrate how certification intensity and geographic clustering shape competitive positioning across polymer power transmission components.
| Leading Market Players |
|---|
| Vigor Precision Limited |
| IMS Gear |
| Creative & Bright Group |
| Winzeler Gear |
| Oechsler AG |
| Designatronics |
| Essentra |
| Gleason |
| AmTech International |
| Others |
Value Chain & Pricing Dynamics
Captive injection-molding capacity in southern China and Bavaria anchors both supply security and pricing power for precision polymer gear producers serving automotive and medical verticals. Tooling ownership concentration among hardened steel mold specialists creates tiered supplier bargaining positions that cascade through resin procurement and finished gear pricing.
Pricing Analysis
Three-tier pricing structure across medical-grade, automotive-certified, and industrial-economy levels dominates transaction structures in this market. Price differentiation rests on FDA 510(k) clearance status and IATF 16949 certification depth, with gamma-stable PEEK formulations commanding substantial premiums over standard acetal grades. Cost compression in industrial-economy tiers is intensifying because fixed-price contracts expose molders to caprolactam and polyether ether ketone monomer volatility. Automotive OEMs exhibit lowest price sensitivity due to PPAP validation switching costs, while appliance manufacturers face acute margin pressure from EU Ecodesign repairability mandates.
Supply Chain Analysis
Engineering-grade resin supply rests on German specialty chemical producers, Chinese caprolactam manufacturers, and Japanese polyether ether ketone compounders. Raw material dependencies include polyoxymethylene homopolymer, glass-reinforced polyamide, and carbon-fiber PEEK prepregs. Single-source vulnerability concentrates in medical-grade cleanroom molding capacity clustered around Nuremberg and Shenzhen. Distribution runs through tier-one automotive suppliers and specialized medical device contract manufacturers rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by electrified powertrain procurement shifting toward thermal-cycling-validated polymer formulations with documented lifecycle emissions.
For Market Incumbents: Deploy dual-certification capacity as the primary defensive lever. Simultaneous FDA 510(k) and EU MDR technical documentation preparation extends qualification timelines that filter out mid-cap competitors. Backward integration into hardened steel mold tooling in Bavaria or southern China secures cavity maintenance schedules against specialized toolmaker bottlenecks. AGMA accuracy verification expertise represents a scarce capability worth acquiring from retiring coordinate measuring machine operators. For New Entrants and Emerging Players: Begin with surgical robotics actuators in India's private hospital networks where CDSCO registration pathways remain underpenetrated by established gamma-sterilizable gear suppliers. Fused filament fabrication prototyping for custom robotics integrators offers a low-capex entry point before committing to multi-cavity injection molds. Target laparoscopic instrument OEMs seeking second-source redundancy for PEEK gearing qualified under FDA 21 CFR frameworks. For Investors and Strategic Acquirers: Roll-up economics work for medical-grade cleanroom specialists because dual FDA-EU certification timelines create artificial scarcity that concentrates margin in qualified producers. Five-to-ten-year viability hinges on gamma-stable resin formulation IP and synchronized capacity ramps with electrified automotive programs. Watch for EPA final rules on per- and polyfluoroalkyl substances as the signal triggering accelerated dry-running compound substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Dual FDA-EU Certification Investment | Simultaneous 510(k) and MDR documentation captures medical device switching costs. |
| Backward Integration into Mold Tooling | Hardened steel cavity ownership secures maintenance schedules against Bavarian toolmaker bottlenecks. |
| Gamma-Stable PEEK Formulation Development | Sterilization-compatible compounds meet FDA 21 CFR requirements for single-use surgical instruments. |
| Cleanroom Capacity Expansion | Medical-grade production environments satisfy MDR biocompatibility frameworks for robotic actuators. |
| Additive Manufacturing Prototyping Capability | Fused filament fabrication enables geometrically complex internal gearing for custom robotics integrators. |
Study Parameters
Multiple input streams — primary interviews with polymer gear procurement managers at automotive OEMs, regulatory affairs leads at medical device contract manufacturers, and coordinate measuring machine operators at metrology service bureaus — were reconciled against secondary validation from ECHA REACH substance restriction databases, FDA 510(k) clearance filings, and IATF 16949 certification registries. Bottom-up segment sizing across spur, helical, bevel, and worm gear geometries was triangulated against top-down resin consumption estimates from European and Asian polymer compounders.
Data-stream reconciliation applied analytical frameworks across the projection horizon without year-specific anchoring. Segmentation dimensions modeled include gear geometry type, application vertical, resin material grade, and end-user concentration intensity. CAGRs were derived from elasticity-adjusted demand curves incorporating automotive electrification program timelines and medical device single-use mandate adoption curves. Industry-specific forecast inputs captured tool steel lead times and gamma sterilization validation cycle durations.
Several conditions sit outside the modeled scope, including sudden ECHA substance ban expansions beyond hexavalent chromium plating and disruptive ceramic gear material breakthroughs. Forecasts reflect assumptions about REACH implementation pacing and polymer recycling infrastructure development. A small set of named triggers warrants ongoing watch: EPA per- and polyfluoroalkyl substance rule finalization, EU Ecodesign repairability mandate enforcement dates, and MIIT industrial upgrading program subsidy revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
GCC Heat Treating Market
Industrial Materials
Twin Screw Extruders Market
Industrial Materials
Modified Wood Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Vinyl Extrusion Equipment Market
Industrial Materials
Middle East Activated Carbon Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
Hardfacing Rods Market
Industrial Materials
Briquetting Press Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
Paint Knife Market
Industrial Materials
Industrial Gaskets Market
Industrial Materials
Global Cast Acrylic Sheet Market
Industrial Materials
Heat Shrink Tubing and Sleeves Market
Industrial Materials
Industrial Heaters Market