
 Middle East and Africa Laundry Appliances Market | 2026-2036
Middle East and Africa Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Laundry Appliances Market Foresight
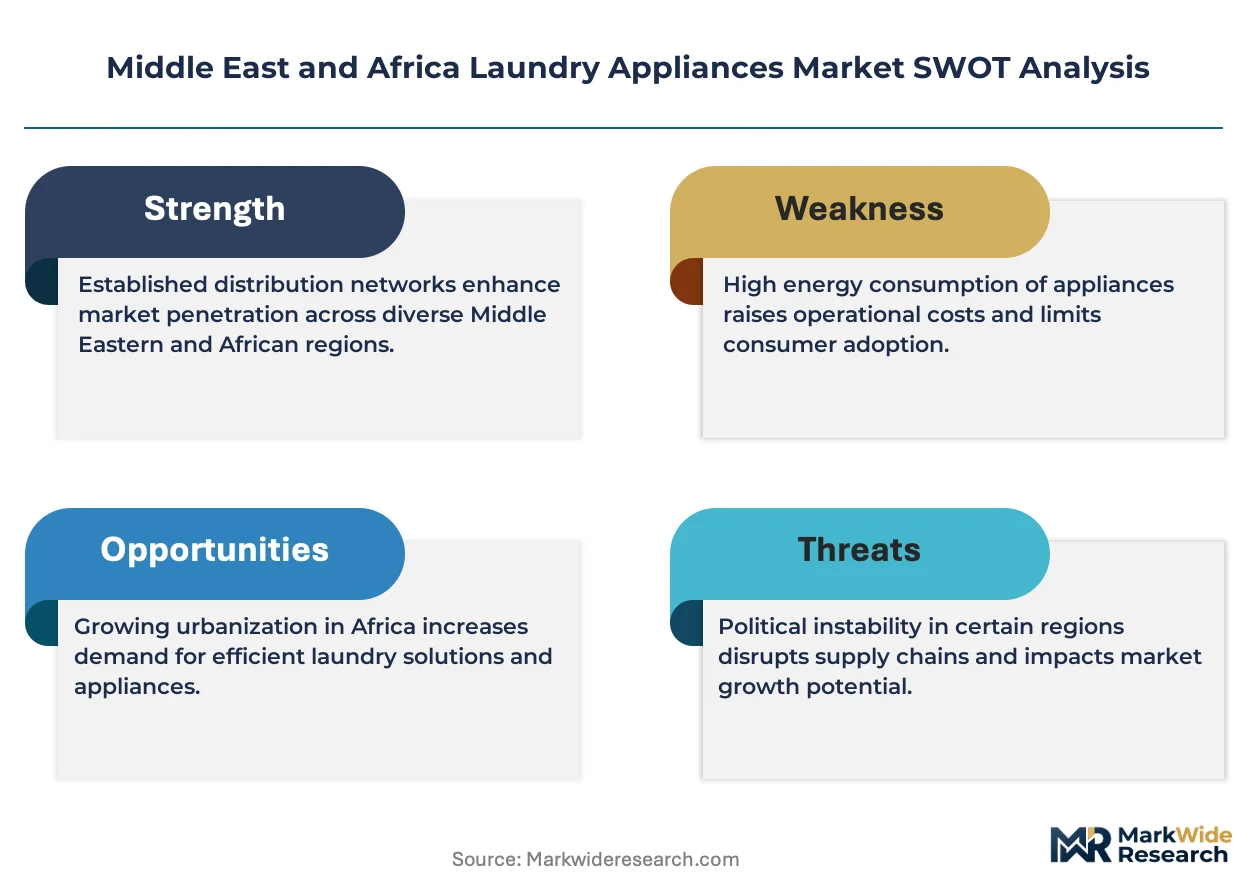
Modular washer-dryer bundling is recalibrating how hospitality and multi-unit residential buyers evaluate total cost of ownership. Electrolux leverages its European engineering heritage to anchor premium commercial installations across Gulf hotel chains. Alliance Laundry System LLC specializes in coin-operated and on-premise laundry systems that sustain recurring revenue streams for property developers. Samsung competes aggressively through smart-connected home appliances that extend consumer touchpoints beyond the initial purchase cycle.
Middle East and Africa laundry appliances comprise electrically powered equipment for washing, drying, and finishing textiles, typically rated between 5 kg and 15 kg capacity for residential units and exceeding 25 kg for commercial tunnel systems, with drum construction from stainless steel or porcelain-coated steel determining longevity in hard-water environments prevalent across the region. Front-load washing machines dominate value contribution due to superior water efficiency and fabric care metrics, while smart technology integration represents the fastest-expanding dimension as Wi-Fi-enabled diagnostics and remote cycle management penetrate Gulf urban households. Washer-dryer combos capture outsized interest in space-constrained apartments across Cairo, Lagos, and Dubai where dedicated drying infrastructure remains limited.
Saudi Standards, Metrology and Quality Organization (SASO) and South Africa's National Regulator for Compulsory Specifications (NRCS) enforce minimum energy performance standards and water efficiency labeling that filter lower-tier imports from regional distribution channels. Egypt's mandatory pre-shipment inspection regime for electrical appliances adds compliance layers that favor established manufacturers with dedicated local certification teams. Stakeholders must monitor evolving efficiency tier thresholds and local content requirements as Gulf states advance industrial diversification agendas that could reshape supplier qualification criteria.
Market Dynamics
Modular washer-dryer bundling is recalibrating how hospitality and multi-unit residential buyers evaluate total cost of ownership across the Middle East and Africa. Electrolux leverages its European engineering heritage to anchor premium commercial installations across Gulf hotel chains. Alliance Laundry System LLC specializes in coin-operated and on-premise laundry systems that sustain recurring revenue streams for property developers. Samsung competes aggressively through smart-connected home appliances that extend consumer touchpoints beyond the initial purchase cycle.
Growth Catalysts
- Hospitality automation:Gulf hotel chains are scaling automated tunnel systems to match surging tourism capacity targets, creating bulk procurement pull for commercial-grade equipment.
- Residential mega-projects:Saudi Arabia's giga-developments are front-loading demand for front-load washer-dryer combos in space-optimized apartment configurations.
- Water efficiency mandates:SASO minimum energy performance standards are filtering inefficient imports and elevating certified product penetration in Saudi distribution channels.
Market Restraints
- Stainless steel input volatility:Drum construction costs fluctuate with global steel pricing, compressing margin buffers for manufacturers serving price-sensitive North African markets.
- Hard-water corrosion:Porcelain-coated steel drums degrade faster in high-mineral water conditions prevalent across the Gulf, limiting product lifespan and warranty exposure.
- Pre-shipment inspection friction:Egypt's mandatory electrical appliance inspection regime adds compliance layers that favor established manufacturers with dedicated local certification teams.
Strategic Opportunities
- Smart convergence:Wi-Fi-enabled diagnostics and remote cycle management are expanding into Gulf urban households, creating service revenue attachment points beyond hardware sales.
- Coin-operated channel innovation:Property developers in Lagos and Cairo are adopting revenue-share laundry room models that shift capex burden from tenants to asset owners.
- South African efficiency tiers:NRCS benchmarks are accelerating replacement cycles in municipal housing stock, opening upgrade pathways for mid-tier efficiency-rated units.
Industry Challenges
- Certification timeline compression:Multiple Gulf states are advancing local content requirements that demand recertification of existing product portfolios against shifting supplier qualification criteria.
- Legacy infrastructure integration:Space-constrained retrofits in older Dubai and Cairo residential blocks face installation constraints that complicate front-load machine deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Laundry Appliances Market |
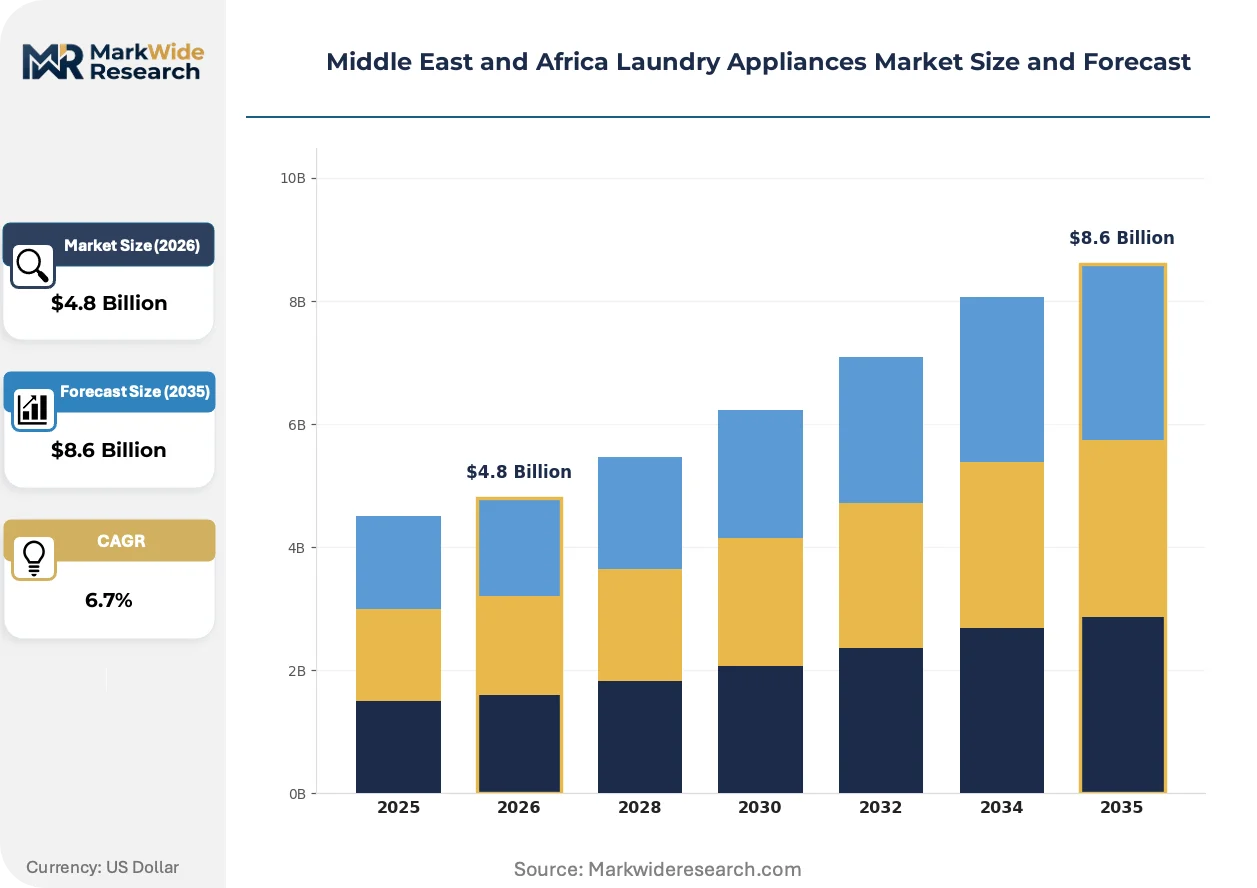
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryer Combos, Specialty Appliances Technology: Front-Load, Top-Load, Smart Technology, Conventional End User: Residential, Commercial, Industrial, Hospitality Sales Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | Electrolux, Alliance Laundry System LLC, Panasonic Middle East, Hitachi Appliances Inc, Robert Bosch Ltda, LG Electronics, Samsung, Arcelik, Whirlpool SA, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Laundry Appliances Market Shifts & Advancements
Smart technology integration represents the fastest-expanding dimension as connectivity features penetrate Gulf urban households and commercial operations alike. Three distinct forces are reshaping competitive positioning and buyer expectations across the region.
Heat-pump drying technology is expanding into premium residential and hospitality segments by slashing energy consumption against conventional vented systems. Saudi hotel operators are piloting these units in sustainability-focused properties. The technology is expanding into markets where electricity tariffs and carbon disclosure requirements are tightening operational cost calculations.
SASO and NRCS efficiency benchmarks are filtering lower-tier imports from regional distribution channels. Manufacturers must maintain dedicated local certification teams to navigate evolving tier thresholds. Commercial tunnel system suppliers face the steepest compliance recalibration as water labeling requirements extend to industrial-scale equipment.
Service unbundling is compressing traditional after-sales revenue models as Gulf buyers demand predictive maintenance contracts tied to connected machine diagnostics. Independent service providers in South Africa are capturing maintenance work that OEMs previously monopolized. This shift is most visible in Johannesburg's multi-unit residential sector where property managers prioritize uptime guarantees over brand loyalty.
Middle East and Africa Laundry Appliances Market Segmentation
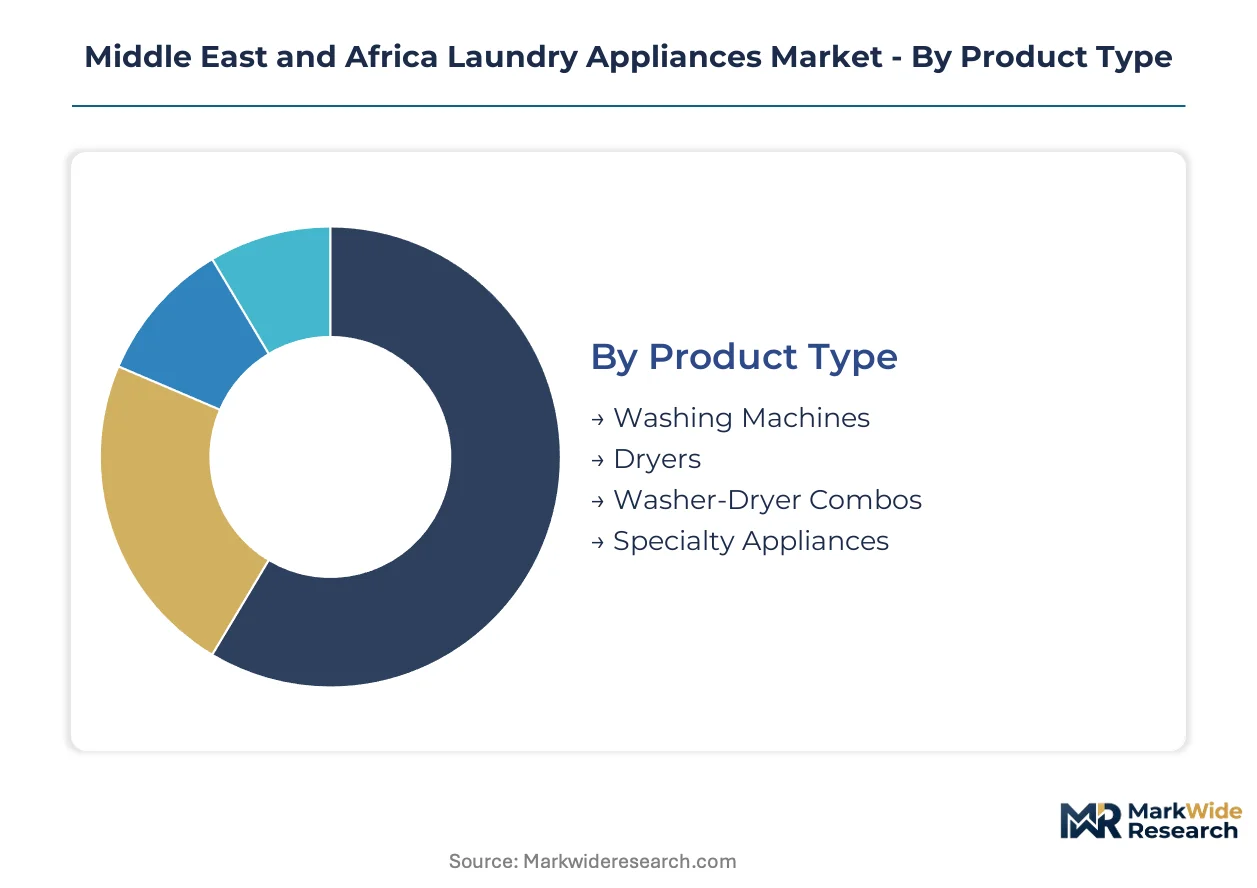
Buyer priorities diverge sharply across Middle East and Africa laundry appliances segments. Water scarcity, space constraints, and tourism infrastructure investments create distinct procurement patterns that manufacturers must address through targeted portfolio configuration.
Product Type:
Commercial buyers prioritize durability specifications; residential purchasers weigh footprint against utility cost.
- Washing Machines:Stainless steel drum construction rated for 5-15 kg capacity dominates residential procurement across Saudi giga-developments. Front-load configurations capture premium positioning in Dubai and Riyadh where SASO water efficiency labeling elevates certified units above commodity imports.
- Dryers:Vented systems retain cost advantage in North African markets with lower electricity tariffs. Heat-pump technology gains traction in Gulf hospitality properties where sustainability disclosures and operational cost controls override capital expenditure sensitivity.
- Washer-Dryer Combos:Space-optimized units address Cairo and Lagos apartment constraints where dedicated drying infrastructure remains absent from older residential stock.
- Specialty Appliances:Industrial tunnel systems serve hotel linen operations in Jeddah and Doha with throughput exceeding 25 kg per cycle.
Volume sits with washing machines; growth tilts toward heat-pump dryers.
Technology:
Efficiency certification tiers now function as market access gates rather than optional premiums.
- Front-Load:Horizontal drum orientation reduces water consumption by 40-50% against vertical-axis alternatives, aligning with NRCS benchmarks in South African municipal housing and SASO minimum performance standards in Saudi distribution channels.
- Smart Technology:Wi-Fi-enabled diagnostics and remote cycle management penetrate Gulf urban households fastest, creating service revenue attachment points beyond hardware margins for manufacturers with connected platform infrastructure.
- Top-Load:Vertical-axis machines retain price-sensitive penetration in Egyptian and Nigerian markets where initial acquisition cost outweighs lifetime utility expenditure.
- Conventional:Non-connected mechanical controls persist in commercial laundromat deployments across secondary African cities where connectivity infrastructure remains unreliable.
Certified front-load configurations anchor current revenue; smart connectivity is climbing the fastest.
End User:
Procurement scale and replacement frequency separate institutional buyers from household purchasers.
- Residential:Individual household acquisitions concentrate in Saudi Arabia's residential mega-projects and South Africa's efficiency-driven replacement cycles, with front-load washer-dryer combos preferred in space-constrained urban configurations.
- Hospitality:Gulf hotel chains deploy automated tunnel systems at scale to match tourism capacity targets, generating bulk procurement pull for commercial-grade equipment with predictive maintenance contracts.
- Commercial:Coin-operated laundry room models shift capital expenditure burden from tenants to property developers in Lagos and Cairo multi-unit residential blocks.
- Industrial:Textile processing and healthcare linen services in Johannesburg and Casablanca demand continuous-batch systems with throughput optimization.
Residential volume dominates unit sales; hospitality commands highest average transaction value.
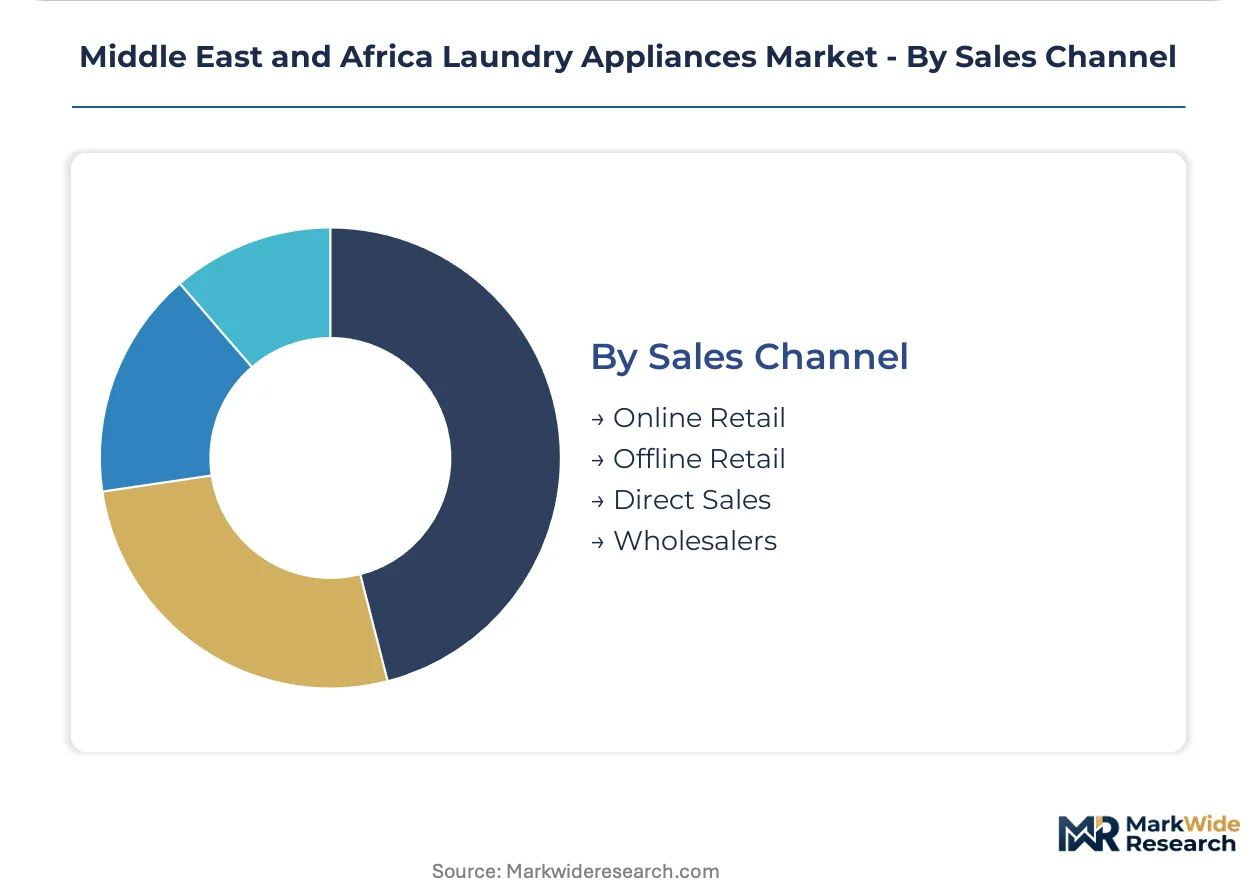
Sales Channel:
Channel selection reflects buyer sophistication and installation service requirements.
- Offline Retail:Physical appliance showrooms across Dubai Mall and Riyadh retail clusters enable tactile evaluation of drum construction quality and interface design before purchase commitment.
- Direct Sales:Manufacturers bypass distribution layers for Gulf hospitality chains and Saudi giga-development contractors, embedding service contracts and spare parts guarantees into negotiated packages.
- Online Retail:E-commerce penetration accelerates in South African urban markets where price transparency and delivery logistics mature faster than North African alternatives.
- Wholesalers:Regional distributors aggregate fragmented demand across secondary African markets, absorbing certification compliance burdens for smaller retailers.
Offline retail retains transaction volume; direct sales is gaining share fastest in commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones across the Gulf Cooperation Council are concentrating appliance manufacturing and distribution capacity. Jebel Ali Free Zone in Dubai anchors regional logistics for premium equipment imports. King Abdullah Economic City is scaling domestic assembly operations to capture Saudi Vision 2030 localization incentives.
Saudi Arabia
Residential mega-projects in Riyadh and Jeddah are front-loading bulk procurement of front-load washer-dryer combos. SASO minimum energy performance standards are filtering inefficient imports from distribution channels. NEOM's linear city development is specifying connected laundry infrastructure for its hospitality and residential districts.
United Arab Emirates
Dubai's hospitality sector is deploying automated tunnel systems to match tourism capacity targets of 25 million annual visitors. MOHAP technical regulations for electrical appliances enforce safety and efficiency benchmarks that reshape import portfolios. Jebel Ali Free Zone clusters warehouse and re-export operations serving East African and South Asian markets.
South Africa
NRCS efficiency benchmarks are accelerating replacement cycles in municipal housing stock across Gauteng and Western Cape provinces. Johannesburg's multi-unit residential sector is adopting revenue-share laundry room models that shift capital expenditure burden from tenants to property developers. Cape Town's water scarcity conditions elevate demand for certified water-efficient machines.
Egypt
Cairo's space-constrained apartment configurations are driving washer-dryer combo penetration where dedicated drying infrastructure remains absent. The country's mandatory pre-shipment inspection regime for electrical appliances adds compliance layers that favor established manufacturers with dedicated local certification teams. Alexandria's port infrastructure handles bulk appliance imports serving Nile Delta population centers.
Nigeria
Lagos property developers are scaling coin-operated laundry room installations in multi-unit residential blocks across Victoria Island and Lekki corridors. The country's central bank foreign exchange restrictions complicate import financing for distributors serving price-sensitive consumer segments. Kano's northern commercial hub channels secondary market distribution across Sahel-adjacent states.
Middle East and Africa Laundry Appliances Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across commercial and residential segments. The vendor base organizes into three tiers: European engineering heritage brands commanding premium hospitality installations, Korean and Japanese electronics conglomerates driving smart connectivity penetration, and regional specialists capturing price-sensitive volume in North African markets. Dominant competitive moves include strategic partnerships with Gulf property developers and geographic expansion through free-zone distribution hubs.
Within the European heritage tier, Electrolux anchors premium commercial installations across Saudi and UAE hospitality chains. Samsung and LG Electronics occupy positions at the smart-connected vector, extending consumer touchpoints beyond hardware sales through platform infrastructure. Alliance Laundry System LLC exemplifies the pure-play specialist archetype, sustaining recurring revenue streams through coin-operated and on-premise laundry system deployments.
| Leading Market Players |
|---|
| Electrolux |
| Alliance Laundry System LLC |
| Panasonic Middle East |
| Hitachi Appliances Inc |
| Robert Bosch Ltda |
| LG Electronics |
| Samsung |
| Arcelik |
| Whirlpool SA |
| Others |
Supply & Pricing Matrix
SASO water efficiency certification requirements are compressing procurement timelines for Saudi giga-developments, forcing distributors to hold premium-certified inventory closer to Riyadh and Jeddah demand clusters. This inventory positioning elevates working capital requirements and transfers cost into spot pricing for urgent deliveries.
Pricing Analysis
Short lead-time premiums dominate commercial procurement across Gulf hospitality chains, where NEOM and Red Sea Project contractors pay markups for certified front-load washer-dryer combos available within 30-day windows. Pricing stratifies across SASO Tier 1 certified units, Tier 2 efficiency-rated alternatives, and uncertified commodity imports. Cost compression in the commodity tier intensifies because Egyptian and Nigerian distributors absorb pre-shipment inspection fees to maintain volume. Multi-unit residential developers in Lagos and Cairo exhibit highest price sensitivity, while Saudi sovereign wealth-backed hospitality operators show lowest.
Supply Chain Analysis
Refurbishment flows for commercial tunnel systems create secondary parts markets in Johannesburg and Casablanca, where independent service providers rebuild heat-pump dryer compressors and stainless steel drum assemblies. Manufacturing concentrates in China, Turkey, and Poland for complete units, with component sourcing drawing from South Korean control board suppliers and German pump specialists. Single-source vulnerability sits with precision motor drives from select East Asian producers. Distribution runs through Jebel Ali Free Zone for Gulf re-export and Alexandria port for Nile Delta penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stainless steel drum foundry capacity constraints in Europe and East Asia are propping pricing for premium commercial equipment, creating a supply-constrained environment where certified manufacturers command margin premiums.
For Market Incumbents: Deepen backward integration into heat-pump compressor supply by qualifying second-source suppliers in Turkey or Southeast Asia. Anchor service contract penetration in Johannesburg's multi-unit residential sector before independent providers capture predictive maintenance revenue streams. SASO tier threshold escalation represents the critical regulatory threat requiring certification team expansion. For New Entrants and Emerging Players: Property developers in Lagos and Cairo present the most penetrable channel partner type, with revenue-share laundry room models offering capital-light entry into coin-operated deployment. Target secondary Egyptian cities where pre-shipment inspection complexity filters smaller competitors. White-space exists in Wi-Fi-enabled diagnostics for commercial tunnel systems where incumbent OEMs underinvest in connectivity platforms. For Investors and Strategic Acquirers: The window for entry favors pure-play commercial laundry specialists with installed base visibility in Gulf hospitality chains. Long-term viability rests on service revenue attachment rates exceeding hardware margins across the projection horizon. Monitor SASO local content requirement announcements as the inflection signal for supplier qualification disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Technology Licensing | Saudi hotel operators piloting these units in sustainability-focused properties gain operational cost control. |
| Certification Team Expansion | Dedicated SASO and NRCS compliance capabilities filter lower-tier imports from regional distribution channels. |
| Revenue-Share Laundry Partnerships | Lagos and Cairo property developers shift capex burden from tenants to asset owners through coin-operated models. |
| Connected Platform Infrastructure | Wi-Fi-enabled diagnostics in Gulf urban households create service revenue attachment beyond hardware margins. |
| Free-Zone Distribution Hub Establishment | Jebel Ali clustering enables warehouse and re-export operations serving East African markets. |
Research Methodology
Trade databases, customs records, and regulatory filing repositories formed the secondary backbone for volume and trade flow estimation. Primary interviews with hospitality procurement directors, appliance distributor principals, certification compliance officers, and property development project managers validated demand assumptions. Bottom-up and top-down triangulation cross-checked manufacturer shipment data against end-user installation records across Saudi giga-developments and South African municipal housing programs.
Bottom-up modeling aggregated unit economics across product type, technology tier, and end-user segment throughout the forecast period. Segmentation dimensions included washing machines, dryers, washer-dryer combos, and specialty tunnel systems crossed with front-load, smart-connected, top-load, and conventional technology tiers. CAGRs derived from fitted growth curves incorporating SASO efficiency mandate implementation timelines and hospitality capacity expansion pipelines. Hard-water corrosion rates and drum replacement cycles informed commercial equipment lifetime value calculations.
Caveats apply where SASO local content requirement announcements or NRCS tier threshold revisions could materially shift the outlook. Forecasts embed assumptions regarding tourism capacity targets in Saudi Arabia and foreign exchange regime stability in Nigeria. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
India Home Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
Europe White Goods Market
Home Appliances
Oman Home Appliances Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
Canada Home Appliances Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
North America Luxury Appliance Market
Home Appliances
South Africa Home Appliances Market
Home Appliances
United States Home Appliances Market
Home Appliances
North America Major Home Appliances Market
Home Appliances
Residential Dishwashers Market
Home Appliances
India Laundry Appliances Market
Home Appliances
India Small Home Appliances Market