
 Outdoor Cooking Equipment Market | 2026-2036
Outdoor Cooking Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Cooking Equipment Market Outlook
Subscription-based fuel and pellet delivery programs is realigning how manufacturers capture recurring revenue alongside hardware sales. Weber leverages its dealer network to sustain brand loyalty in North American specialty retail. Traeger Grills dominates the wood-pellet segment through app-connected temperature control systems. Napoleon anchors its position with stainless-steel fabrication expertise and broad fuel-type coverage across price tiers.
Outdoor cooking equipment encompasses thermally insulated vessels, burners, and ventilation assemblies designed to prepare food in exterior residential or commercial environments, typically operating between 225°F and 700°F depending on fuel source and cooking method. Grills and smokers command the largest installed base, though pizza ovens are gaining traction among homeowners seeking restaurant-style output from compact footprint designs. Gas and charcoal fuels still occupy the majority of unit sales, while electric variants are carving out share in urban settings with open-flame restrictions. The premium and luxury price tiers concentrate margin pools, whereas budget segments compete on seasonal turnover velocity.
EPA wood heater standards and UL safety certifications shape product development timelines and market access requirements for manufacturers distributing in the United States. CE marking under EU appliance regulations governs electromagnetic compatibility and gas safety for equipment sold across European member states. Stakeholders must monitor evolving municipal fire codes and balcony-use ordinances in dense urban centers, as these local rules increasingly determine which fuel types and product formats gain shelf space in adjacent retail channels.
Market Dynamics
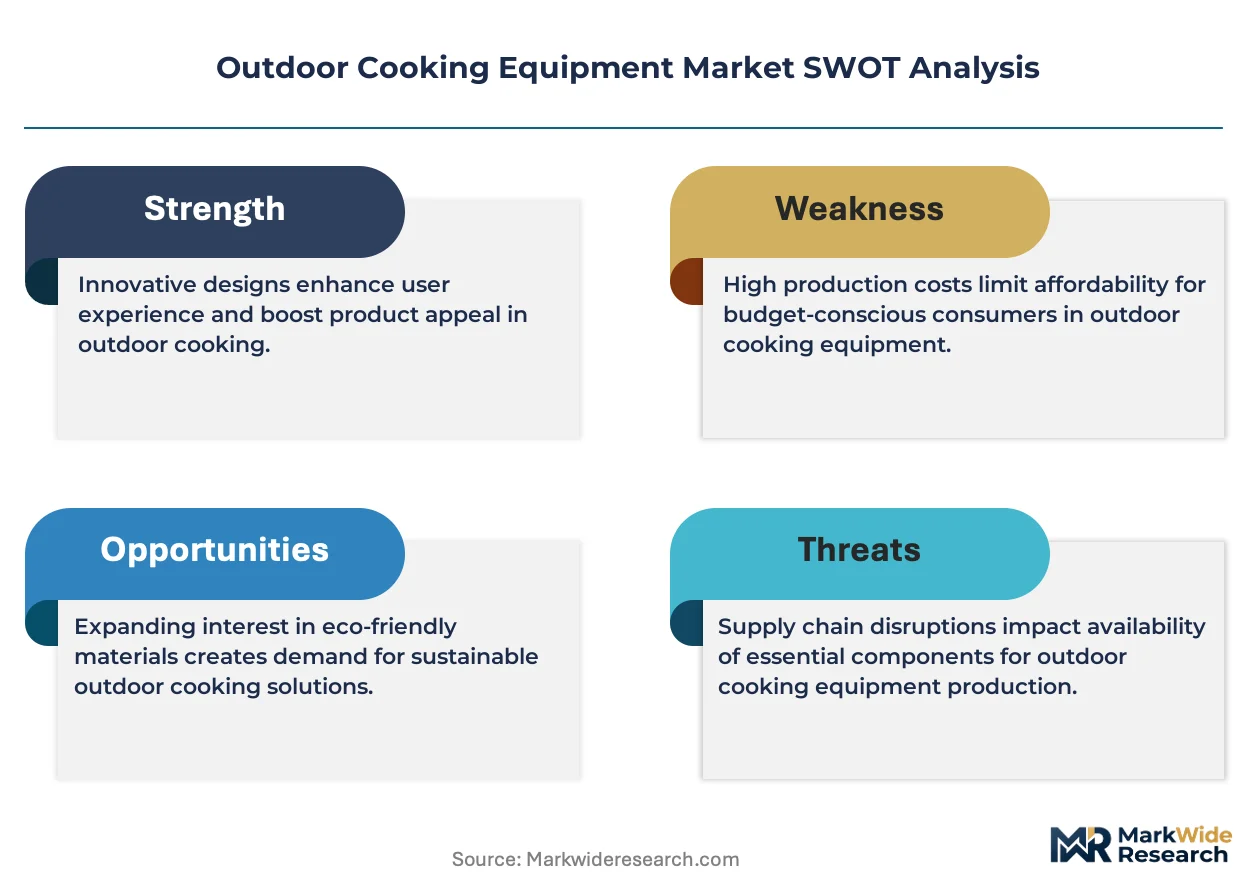
Post-pandemic dining habits have permanently altered commercial outdoor kitchen deployment, while EPA emissions tightening forces combustion redesigns across wood-fired product lines.
Growth Catalysts
- Subscription fuel delivery models:Recurring pellet and propane programs transform one-time hardware transactions into sustained revenue streams. Manufacturers bundle connected inventory sensors with automated replenishment.
- Germany's garden culture:Barbecue traditions sustain compressed replacement cycles for premium gas grills. Homeowners treat outdoor kitchens as permanent residential infrastructure rather than seasonal accessories.
- CE marking harmonization:Unified EU appliance regulations reduce certification duplication across member states. Gas safety and electromagnetic compliance testing now covers 27 markets through single validation.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 price swings compress fabrication margins. Napoleon and Weber hedge through multi-year mill contracts.
- Urban open-flame ordinances:Municipal fire codes in dense US and European cities restrict charcoal and wood-pellet combustion. Electric variants face no such barriers but carry performance trade-offs.
- Technical ceiling on pellet efficiency:Wood-pellet combustion cannot match gas thermal consistency below 225°F. Low-and-slow barbecue applications require hybrid fuel configurations.
Strategic Opportunities
- India's emerging outdoor entertaining segment:Rising disposable income and apartment terrace culture create first-mover advantage for compact electric grills. Local assembly avoids import duty compression.
- Connected temperature control convergence:IoT sensors and PID algorithms merge precision cooking with remote monitoring. Traeger's app ecosystem demonstrates attach-rate potential for subscription services.
- US Inflation Reduction Act residential credits:Electric and high-efficiency gas equipment qualifies for homeowner energy improvement deductions. Retailers train staff on documentation workflows.
Industry Challenges
- Welding certification scarcity:TIG and MIG specialists for food-grade stainless fabrication command premium wages. Training pipelines lag demand in both North American and European manufacturing hubs.
- UL 147 compliance timelines:Portable fuel container and hose assembly testing extends product launch windows by 4-6 months. Parallel-track engineering reduces revenue delay.
- Patent thickets around pellet auger designs:Licensing negotiations consume legal resources for entrants. Incumbents defend feed-system IP through district court filings in Texas and Delaware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Cooking Equipment Market |
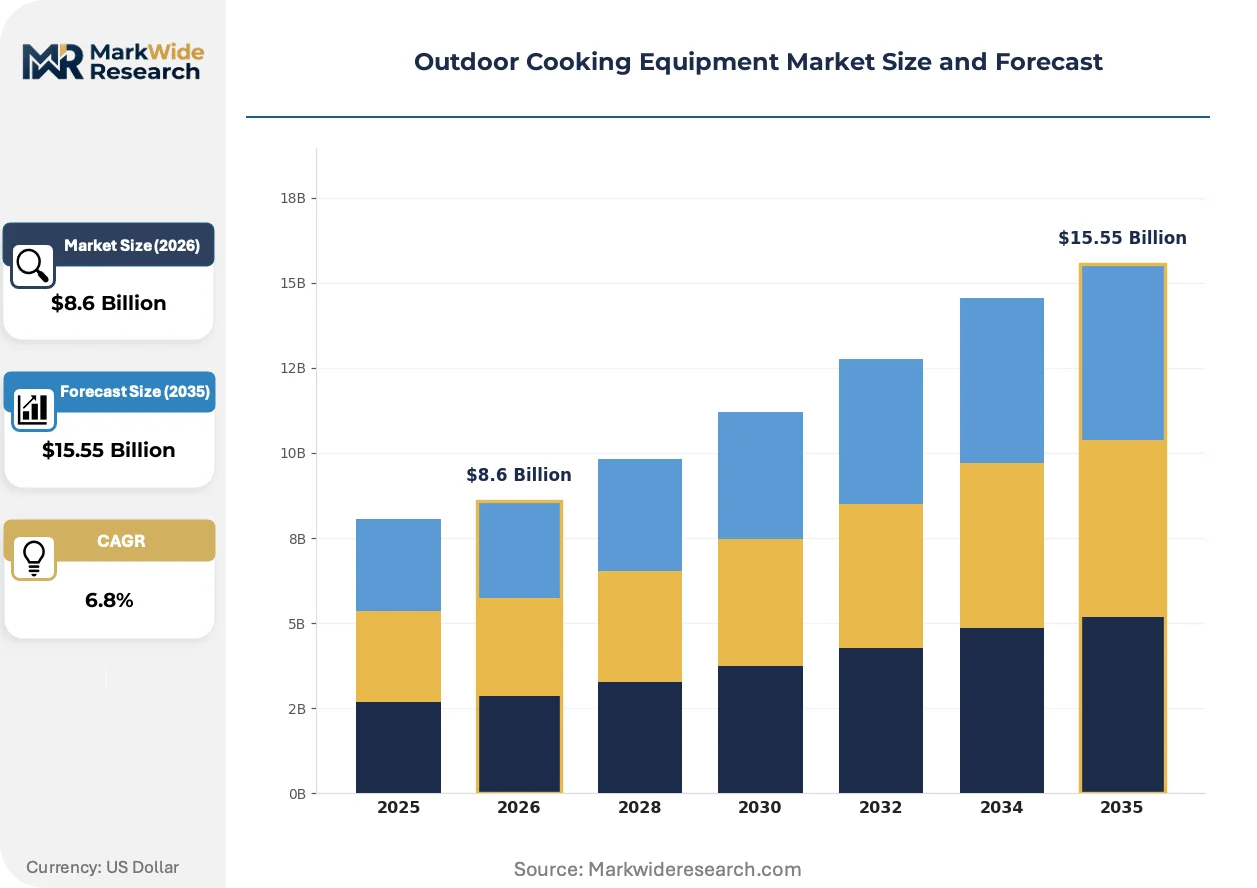
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $15.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grills, Smokers, Pizza Ovens, Portable Stoves Fuel Type: Gas, Charcoal, Wood, Electric End User: Homeowners, Restaurants, Camping Enthusiasts, Catering Services Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | Napoleon, Camp Chef, Weber, Lone Star Grillz, Broil King, Traeger Grills, Kamado Joe, Spider Grills, Big Green Egg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Cooking Equipment Market Strategic Shifts
Equipment form factors are fragmenting into task-specific configurations as buyers reject single-purpose appliances. Manufacturers respond with interchangeable components and shared heat sources.
Smart pellet delivery systems is modularizing how fuel storage integrates with cooking hardware. Homeowners in suburban US markets adopt 200-pound hopper extensions that dock beneath standard grill cabinets. This modularity collapses the distinction between built-in and portable categories.
EPA wood heater New Source Performance Standards are forcing catalytic combustor retrofits across existing product portfolios. Manufacturers redesign fireboxes to maintain output while reducing particulate emissions. The affected segment—traditional offset smokers—faces 15-20% cost inflation passed to commercial barbecue operations.
Restaurant operators now unbundle outdoor kitchen procurement from general contractor scope. Direct equipment specification lets culinary teams dictate burner configuration and ventilation geometry. This disintermediation concentrates in California and Texas, where outdoor dining square footage determines liquor license capacity.
Outdoor Cooking Equipment Market Segmentation
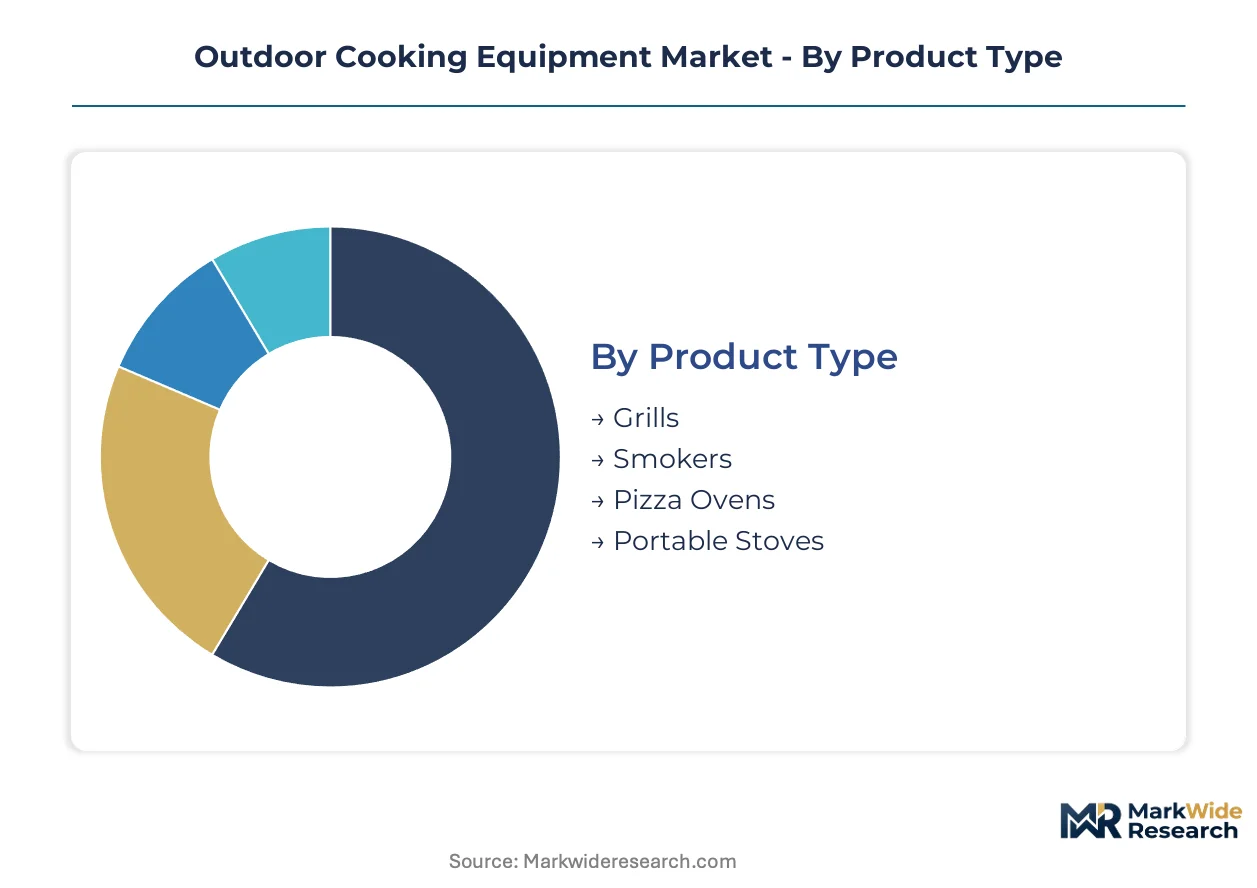
Outdoor cooking equipment segments fragment along fuel compatibility, installation permanence, and thermal output specifications. Manufacturers optimize fabrication workflows and inventory turns by targeting specific price-performance combinations rather than pursuing undifferentiated coverage.
Product Type:
Volume concentrates in multi-fuel platforms with broad temperature range, while premium margin pools form around specialized thermal environments.
- Grills:Open-flame vessels operating between 400°F and 700°F dominate residential installed base. Homeowners in Germany sustain compressed replacement cycles for stainless-steel gas configurations as garden infrastructure investments.
- Smokers:Insulated cabinets with precise airflow control enable 225°F low-and-slow barbecue. Restaurant operators expanding outdoor kitchen installations drive commercial demand for offset and vertical designs.
- Pizza Ovens:Compact refractory domes reaching 900°F+ deliver restaurant-style output from residential footprints. Urban terrace culture in dense European cities favors modular gas and wood-hybrid formats.
- Portable Stoves:Collapsible burner assemblies serve camping enthusiasts and catering services requiring field deployment. Single-burner propane and butane variants compete on pack weight and wind resistance.
Today's leader: Grills. Tomorrow's challenger: Pizza Ovens.
Fuel Type:
Application context determines fuel selection more than performance absolutes, with municipal regulations increasingly constraining combustion options.
- Gas:Propane and natural gas systems deliver instantaneous ignition and thermal consistency across 300°F to 700°F range. Germany's barbecue traditions anchor sustained demand for premium stainless-steel grill configurations.
- Charcoal:Lump and briquette combustion produces distinct flavor profiles through volatile compound release. Urban open-flame ordinances in dense US and European cities restrict charcoal deployment to suburban and rural addresses.
- Wood:Log and pellet variants require EPA-compliant catalytic combustors under tightening emissions standards. Commercial barbecue operations absorb 15-20% cost inflation from firebox redesigns.
- Electric:Resistive heating elements eliminate combustion emissions for balcony and terrace installations. India's emerging outdoor entertaining segment favors compact electric formats to circumvent import duties through local assembly.
Gas commands current volume. Electric gains share fastest where fire codes tighten.
End User:
Procurement authority is shifting from general contractors to culinary teams in commercial settings, altering specification workflows.
- Homeowners:Residential buyers treat outdoor kitchens as permanent infrastructure in Germany, seasonal accessories elsewhere. Subscription fuel delivery programs transform one-time hardware transactions into recurring revenue relationships.
- Restaurants:Foodservice operators unbundle outdoor kitchen procurement from construction scope to dictate burner geometry directly. California and Texas operators leverage outdoor dining square footage for liquor license capacity expansion.
- Camping Enthusiasts:Recreational users prioritize thermal output per gram and rapid setup breakdown. Portable stove demand concentrates in markets with established outdoor recreation infrastructure.
- Catering Services:Mobile foodservice requires NSF-rated equipment with rapid field deployment capability. Event-driven revenue models favor rental and lease arrangements over capital purchase.
Restaurants drive specification innovation. Homeowners sustain replacement cycle velocity.
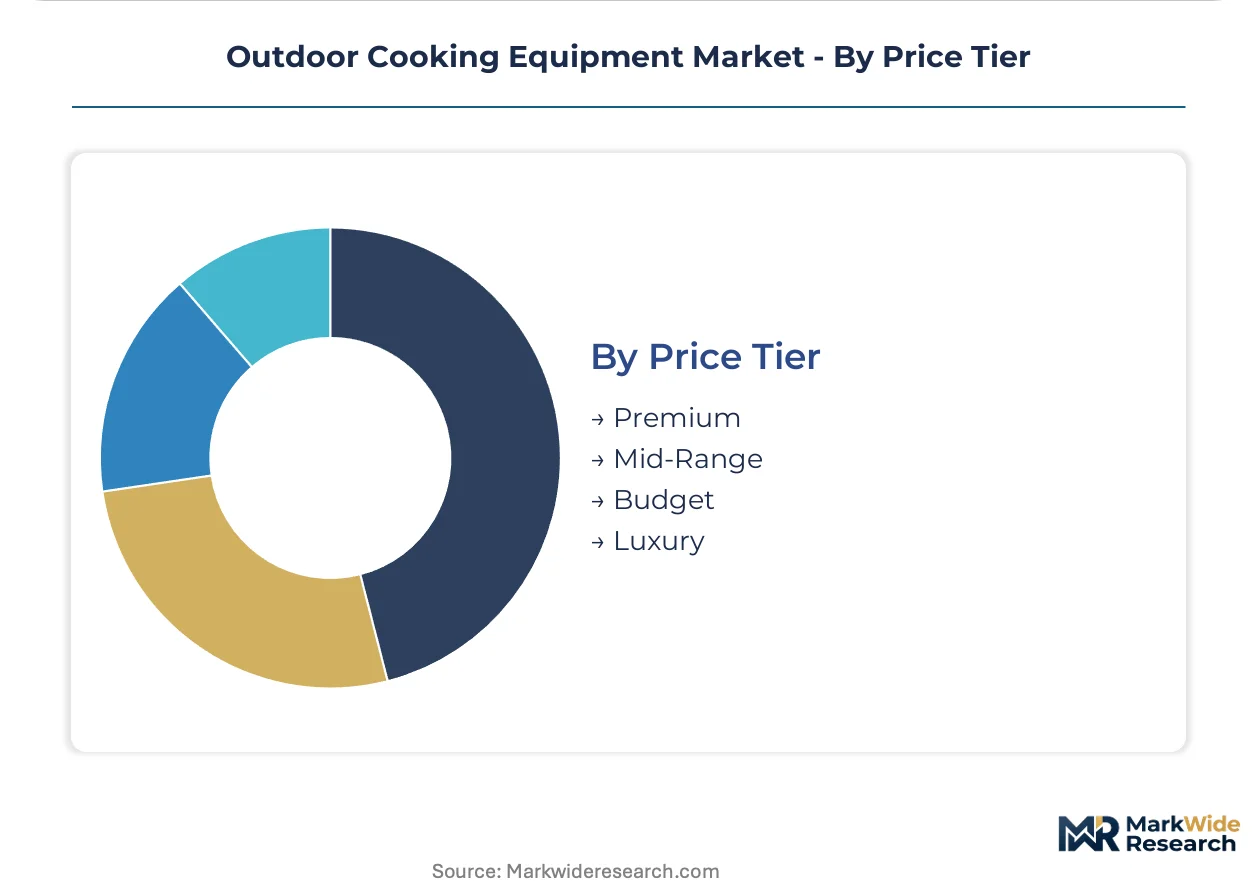
Price Tier:
Margin architecture inverses volume distribution, with premium and luxury tiers capturing disproportionate profit pools.
- Premium:Stainless-steel fabrication with 10-15 year warranty coverage targets replacement-cycle buyers in established barbecue cultures. Napoleon anchors this tier through Grade 304 and 316 expertise.
- Mid-Range:Powder-coated steel and cast-aluminum constructions balance durability with accessible price points. Seasonal turnover velocity determines retail inventory depth.
- Budget:Thin-gauge steel and limited warranty terms serve infrequent users and trial purchasers. Big-box retail placement depends on freight cost minimization and packaging cube efficiency.
- Luxury:Custom fabrication with integrated refrigeration, storage, and ventilation commands project-based pricing. Direct specification by architectural designers bypasses traditional retail channels.
Premium captures margin concentration. Mid-Range defends volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany treats outdoor kitchens as permanent residential infrastructure, while the United States fragments between suburban gas grill replacement cycles and urban electric restrictions. Regulatory divergence across municipalities and national emissions standards is reshaping product availability and fuel-type deployment.
United States
Restaurant operators in California and Texas unbundle outdoor kitchen procurement from general contractor scope to dictate burner geometry directly. EPA wood heater New Source Performance Standards force catalytic combustor retrofits across traditional offset smokers. Commercial barbecue operations in Austin absorb cost inflation from firebox redesigns while leveraging outdoor dining square footage for liquor license capacity.
Germany
Homeowners sustain compressed replacement cycles for premium stainless-steel gas grills as garden culture anchors barbecue traditions. CE marking under EU appliance regulations governs electromagnetic compatibility and gas safety across member states. Fabrication clusters in North Rhine-Westphalia concentrate Grade 304 and 316 expertise for export-oriented manufacturers.
India
Rising disposable income and apartment terrace culture create first-mover opportunity for compact electric grills circumventing import duties through local assembly. BIS certification requirements shape product development timelines for domestic market entry. Assembly operations in Maharashtra and Gujarat target urban consumers in Mumbai and Ahmedabad with balcony-compatible formats.
United Kingdom
Urban open-flame ordinances in Greater London restrict charcoal and wood-pellet combustion to suburban and rural addresses. UKCA marking transition from CE alignment creates temporary certification duplication for cross-channel distribution. Retail concentration in the Southeast favors electric variants for terrace installations in dense metropolitan zones.
Australia
Established outdoor recreation infrastructure sustains demand for portable stoves among camping enthusiasts and catering services. State-level fire restrictions in New South Wales and Victoria determine fuel-type availability during peak summer months. Manufacturing presence in Queensland focuses on powder-coated steel constructions for seasonal turnover velocity.
Outdoor Cooking Equipment Market Competitive Environment
Top-tier vendors anchor premium stainless-steel fabrication, while mid-tier competitors compete on seasonal inventory turns and retail placement. The vendor base stratifies across three strategic archetypes: heritage grill manufacturers with dealer network density, connected-hardware specialists leveraging app ecosystems, and fabrication-focused operators with multi-fuel coverage. Competitive moves concentrate on strategic partnerships for fuel delivery integration and geographic licensing arrangements for patented auger systems.
Within the heritage manufacturer tier, Weber and Napoleon represent established positions through distinct capability emphases. Traeger Grills exemplifies the connected-hardware archetype with app-anchored temperature control systems. Kamado Joe occupies a ceramic-construction specialization alongside Big Green Egg's kamado-format expertise. Lone Star Grillz, Broil King, Camp Chef, and Spider Grills sit within regional fabrication and specialty retail channels.
| Leading Market Players |
|---|
| Napoleon |
| Camp Chef |
| Weber |
| Lone Star Grillz |
| Broil King |
| Traeger Grills |
| Kamado Joe |
| Spider Grills |
| Big Green Egg |
| Others |
Value Chain & Pricing Dynamics
Restaurant operators unbundling outdoor kitchen procurement from general contractor scope have concentrated specification authority among culinary teams, anchoring pricing power in project-based customization rather than standardized unit transactions. This buyer concentration rewards manufacturers with stainless-steel fabrication expertise and penalizes commodity producers dependent on seasonal retail velocity.
Pricing Analysis
Capacity additions in India's Maharashtra and Gujarat assembly corridors are reshaping price floors for compact electric formats through local-content duty circumvention. Three-tier pricing structure across premium, standard, and economy levels stratifies by Grade 304 versus 316 stainless certification and warranty duration. Cost compression in budget segments intensifies as thin-gauge steel imports from Southeast Asia flood big-box channels. Homeowners in Germany exhibit least price sensitivity due to garden-culture infrastructure investment, while India's first-mover electric buyers drive hardest bargain negotiations.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and BIS certification timelines are reshaping sourcing patterns for brands targeting Mumbai and Ahmedabad terrace installations. Stainless steel feedstock draws from Chinese mill complexes, Indonesian nickel processing, and German cold-rolling expertise. Single-source vulnerability concentrates in Grade 316 supply from North Rhine-Westphalia fabrication clusters. Distribution runs through specialty retail networks in Germany, direct-to-restaurant specification in California and Texas, and e-commerce platforms for portable stove categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA wood heater New Source Performance Standards function as a regulatory compounder, forcing catalytic combustor adoption that eliminates marginal manufacturers and consolidates margin pools among compliant incumbents.
For Market Incumbents: To counter patent thickets around pellet auger designs defended through Texas and Delaware district court filings, prioritize backward integration into TIG and MIG welding certification pipelines lagging demand in North American and European manufacturing hubs. Anchor channel control through dealer network density investments that sustain brand loyalty against connected-hardware specialists. For New Entrants and Emerging Players: Capture India's emerging outdoor entertaining segment through compact electric grill formats assembled locally in Maharashtra to circumvent import duty compression. Target Mumbai and Ahmedabad apartment terrace culture with balcony-compatible designs. Deploy direct-to-consumer digital channels bypassing traditional retail gatekeepers. For Investors and Strategic Acquirers: Heritage grill manufacturers with established dealer networks represent the most active acquirer category in this space, seeking app-connected temperature control capabilities to offset hardware commoditization. Long-term viability hinges on recurring fuel subscription attach rates rather than unit shipment velocity. Monitor EPA enforcement consistency as inflection indicator for wood-fired product line rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Fuel Program Launch | Transforms Weber and Traeger hardware transactions into recurring revenue relationships with inventory sensor integration. |
| Catalytic Combustor Retrofit Investment | Enables commercial barbecue operations in Austin to maintain EPA compliance while absorbing 15-20% firebox redesign cost inflation. |
| Local Assembly Partnership in India | Circumvents BIS certification delays and import duties for electric formats targeting Mumbai terrace culture. |
| Dealer Network Density Expansion | Reinforces Napoleon and Weber brand loyalty against Traeger's app-connected ecosystem encroachment in North American specialty retail. |
| Welding Certification Pipeline Development | Addresses Grade 304 and 316 fabrication specialist scarcity commanding premium wages in European and North American hubs. |
Study Parameters
Coverage spans the United States, Germany, India, the United Kingdom, and Australia, with primary inputs from each market cluster combining interviews with restaurant procurement directors, outdoor kitchen contractors, specialty retail buyers, and stainless-steel fabrication plant managers. Secondary validation draws from EPA wood heater compliance filings, CE marking documentation under EU appliance regulations, BIS certification registries, and customs trade data for Grade 304 and 316 steel shipments. Bottom-up unit shipment estimates triangulate against top-down consumer expenditure surveys.
Rate-of-change decomposition separates volume expansion from price mix effects across the analysis window. Segmentation dimensions modeled include fuel type compatibility, installation permanence, thermal output specifications, and end-user procurement authority patterns. CAGRs derive from regression analysis against disposable income indices, housing starts, and regulatory enforcement timelines. Industry-specific inputs incorporate UL 147 compliance timeline delays and municipal fire code adoption curves.
EPA enforcement variance, stainless steel price volatility, and welding certification pipeline lag are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding regulatory harmonization trajectories and replacement cycle compression in established barbecue cultures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Commercial Induction Cooktops Market
Kitchen Appliances
Residential Induction Cooktops Market
Kitchen Appliances
North America Electric Kettle Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Household Cooking Appliance Market
Kitchen Appliances
Europe Household Side by Side Refrigerator Market
Kitchen Appliances
Asia Pacific Household Electric Grills Market
Kitchen Appliances
North America Electric Vegetable Choppers Market
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
Smart Kettle Market
Kitchen Appliances
Built-In Coffee Machine Market
Kitchen Appliances
US Cookware Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
US Induction Cookware Market
Kitchen Appliances
South Africa Kitchen Appliances Market