
 Mexico Kitchen Appliances Products Market | 2026-2036
Mexico Kitchen Appliances Products Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Kitchen Appliances Products Market Insights
A capital-intensity divergence between local assembly and full-scale manufacturing is unwinding competitive dynamics in Mexico's kitchen appliances sector. Mabe leverages its Monterrey manufacturing base and captive component supply to sustain cost advantages across the northern market. LG Electronics anchors its position through inverter technology leadership in refrigeration, while Whirlpool competes on brand recognition and distribution breadth through retail partnerships.
Mexico kitchen appliances products encompass electrically powered equipment designed for food storage, preparation, cooking, and cleaning in residential and commercial settings, typically operating at 127V/60Hz with energy consumption ratings certified under CONUEE labeling protocols. Refrigerators command the largest product type share due to replacement cycles and climate-driven cooling requirements, while smart appliances represent the fastest-expanding technology segment as Wi-Fi connectivity and voice integration penetrate mid-tier price bands. The residential end user category dominates volume, though hospitality procurement is shifting toward energy-efficient equipment to manage operational costs under federal electricity tariffs.
CONUEE energy labeling, NOM-011-ENER standards for refrigeration efficiency, and PROFECO consumer protection frameworks collectively shape product design mandates and market access requirements for imported and domestically manufactured units. Compliance with NOM certification creates barriers for unverified imports while incentivizing local assembly investment. Stakeholders must monitor forthcoming efficiency tier revisions and e-commerce channel regulations as online distribution captures an expanding share of appliance transactions.
Market Dynamics
CONUEE efficiency tier revisions are compressing replacement cycles across Mexico's residential refrigeration segment while simultaneously elevating inverter compressor penetration from premium SKUs into mid-market price bands.
Growth Catalysts
- Urban residential upgrading:Households in Mexico City and Monterrey are replacing legacy units with connected cooking solutions featuring Wi-Fi connectivity and voice integration.
- CONUEE labeling protocols:The national energy efficiency program mandates certified ratings that accelerate inverter technology adoption and disqualify unlabeled imports from formal retail channels.
- Hospitality procurement modernization:Hotels and restaurant chains under federal electricity tariff pressure are specifying NOM-011-ENER compliant refrigeration to reduce operational energy expenditure.
Market Restraints
- Copper and steel input volatility:Compressor and cabinet manufacturing faces margin pressure from commodity price swings that local assemblers cannot fully hedge.
- Monterrey supply concentration:Component fabrication and captive supply chains cluster in Nuevo León, creating geographic vulnerability to logistics disruptions or labor actions.
- NOM certification friction:Import verification timelines and laboratory testing backlogs delay market entry for non-domestic manufacturers lacking established local partnerships.
Strategic Opportunities
- Guadalajara corridor penetration:Jalisco's expanding middle-class housing stock remains underpenetrated by premium appliance retail relative to Mexico City saturation.
- E-commerce channel expansion:Online appliance transactions are capturing share from traditional retail, enabling direct-to-consumer logistics and bypassing distributor markups.
- Smart-kitchen ecosystem convergence:Integration of refrigeration inventory tracking with meal-planning applications creates subscription revenue potential for connected appliance ecosystems.
Industry Challenges
- Inverter technician scarcity:Service networks lack sufficient trained personnel to diagnose and repair variable-speed compressor failures, extending warranty resolution timelines.
- Legacy 127V infrastructure compatibility:Smart appliances requiring stable voltage profiles face performance degradation in older residential electrical systems prevalent in peripheral urban zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Kitchen Appliances Products Market |
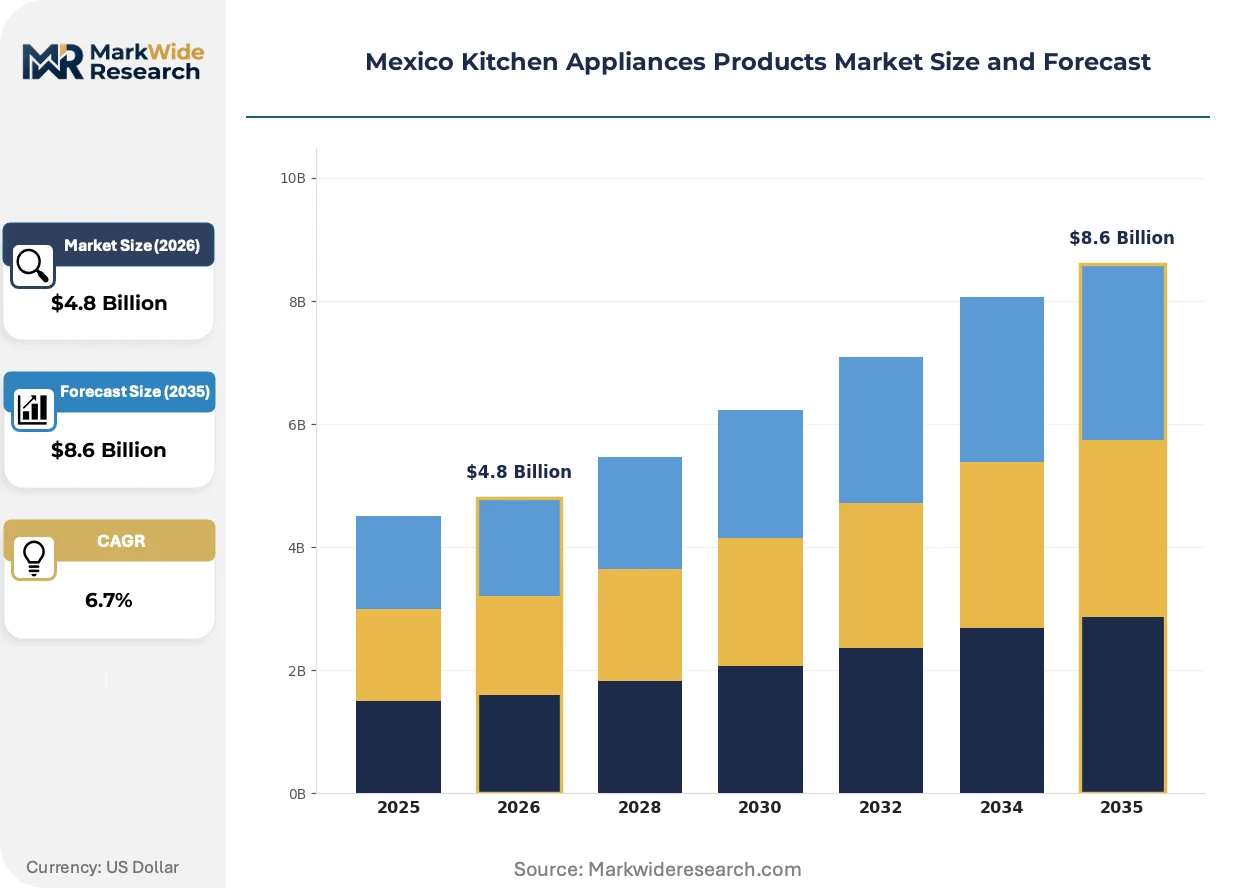
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Dishwashers, Microwaves Technology: Smart Appliances, Energy-Efficient, Conventional, Induction End User: Residential, Commercial, Hospitality, Retail Distribution Channel: Online, Retail Stores, Wholesalers, Distributors |
| Companies Covered | Whirlpool, Mabe, LG Electronics, Samsung Electronics, Electrolux, Haier, Panasonic, BSH Home Appliances (Bosch), Hisense, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Kitchen Appliances Products Market Trends and Innovations
Digital connectivity and predictive maintenance capabilities are redefining value propositions across Mexico's kitchen appliance landscape, shifting competition from hardware specifications toward software-enabled service layers.
Inverter compressor technology is displacing conventional fixed-speed units across mid-tier refrigeration segments. Households in Mexico City's metropolitan area are adopting variable-speed cooling systems at accelerating rates. This transition is compressing price premiums for energy-efficient models and forcing margin recapture through connected feature differentiation.
PROFECO consumer protection frameworks are tightening warranty disclosure requirements and repair parts availability mandates. Manufacturers must now maintain decade-long component inventories for certified models. The residential replacement segment bears the heaviest compliance burden, with distributors restructuring service contracts to absorb regulatory overhead.
Channel fragmentation is reshaping how appliances reach end users. Traditional retail partnerships in Monterrey's industrial corridor face disintermediation from manufacturer-direct online storefronts and marketplace platforms. Puebla and Querétaro housing developments demonstrate the strongest e-commerce penetration, where new construction buyers research specifications digitally before requesting physical showroom confirmation.
Mexico Kitchen Appliances Products Market Segmentation
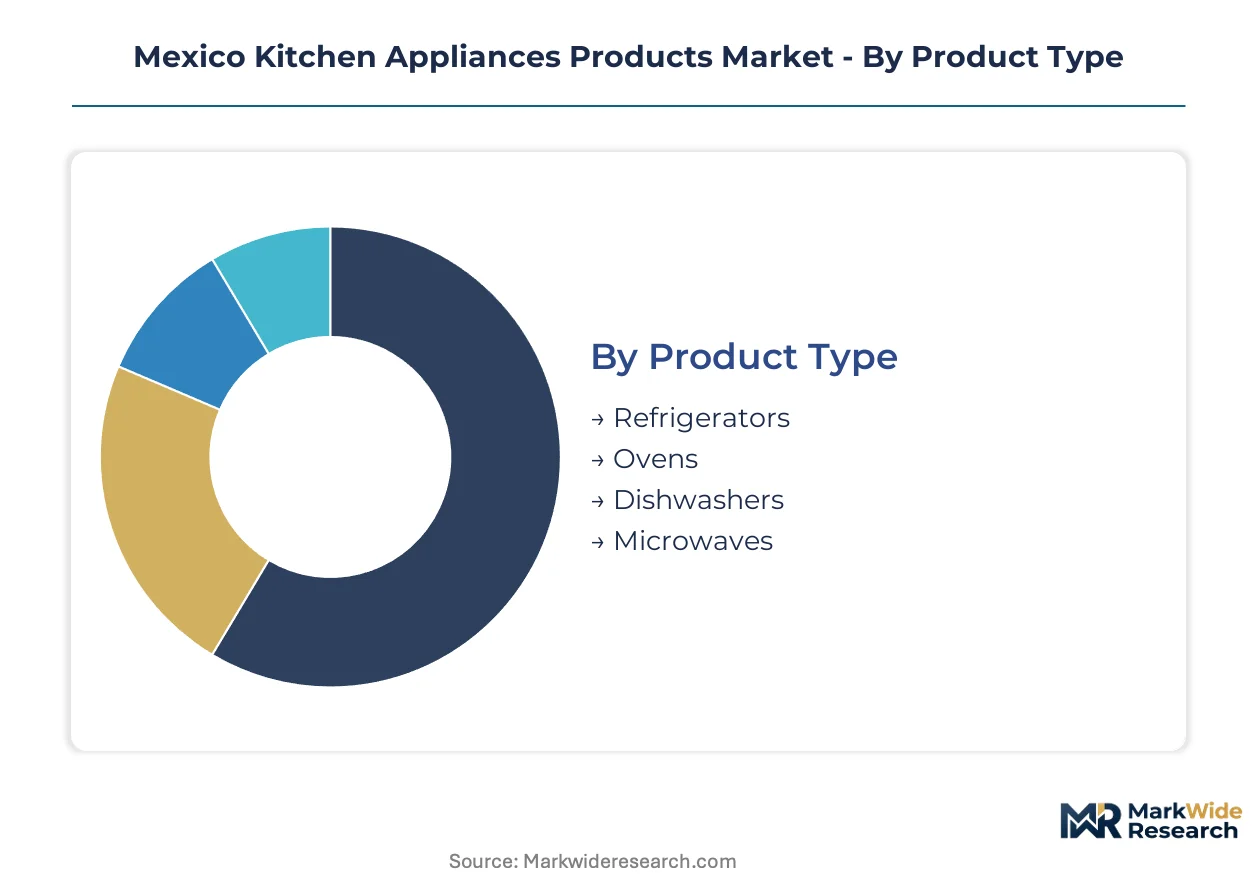
Segmentation in Mexico's kitchen appliances market reveals how CONUEE efficiency mandates and urban electrification patterns reshape demand across product categories. Understanding these divides exposes where inverter technology penetration and smart connectivity create substitution pressure against legacy equipment.
Product Type:
Refrigerators face intensifying substitution pressure from inverter-equipped models as CONUEE labeling disqualifies conventional compressor units from formal retail channels.
- Refrigerators:These units operate at 127V/60Hz with cabinet insulation and compressor systems certified under NOM-011-ENER protocols. Replacement demand concentrates in Mexico City's metropolitan area where climate-driven cooling loads and aging housing stock accelerate upgrade cycles.
- Ovens:Electric and gas-fired cooking enclosures with convection and conventional heating elements. Monterrey's industrial corridor shows the strongest demand concentration as new residential developments specify built-in kitchen configurations.
- Dishwashers:Automated cleaning systems with pump and heating assemblies. Water-scarce regions in northern Mexico limit penetration despite rising middle-class adoption in Guadalajara.
- Microwaves:Magnetron-based rapid heating appliances. Compact form factors and price accessibility sustain volume in secondary cities where full kitchen renovation budgets remain constrained.
Refrigerators retain volume leadership; smart-enabled ovens hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium inverter and connectivity features from baseline compliance-grade equipment across Mexican distribution channels.
- Smart Appliances:Wi-Fi-enabled units with voice integration and mobile application control. Mexico City households drive adoption as connected cooking solutions penetrate mid-tier price bands previously reserved for conventional equipment.
- Energy-Efficient:Inverter compressor and induction heating systems meeting CONUEE A-grade labeling. Federal electricity tariffs push hospitality procurement toward these models to reduce operational expenditure.
- Conventional:Fixed-speed compressor and resistive heating technologies. Price-sensitive segments in peripheral urban zones sustain residual demand despite regulatory displacement from formal retail.
- Induction:Electromagnetic surface heating with rapid thermal response. Monterrey manufacturing clusters supply components while residential adoption lags due to legacy cookware incompatibility.
Energy-efficient models command margin leadership; smart appliances are climbing the fastest.
End User:
Application-specific requirements differentiate residential replacement cycles from commercial procurement specifications and hospitality energy compliance mandates.
- Residential:Household kitchen equipment across owned and rental housing units. Urban centers dominate volume as replacement demand accelerates under CONUEE tier revisions.
- Commercial:Restaurant and foodservice operations requiring high-duty-cycle durability. Operational cost pressures drive specification of NOM-certified refrigeration in formal procurement channels.
- Hospitality:Hotel and extended-stay kitchen installations. Federal electricity tariffs force energy efficiency compliance in new construction and renovation projects.
- Retail:Appliance showroom and warehouse demonstration units. Minimal segment scale with concentrated demand from chain store expansion in Guadalajara and Querétaro corridors.
Residential maintains absolute volume dominance; hospitality procurement shows the sharpest efficiency-driven upgrade trajectory.
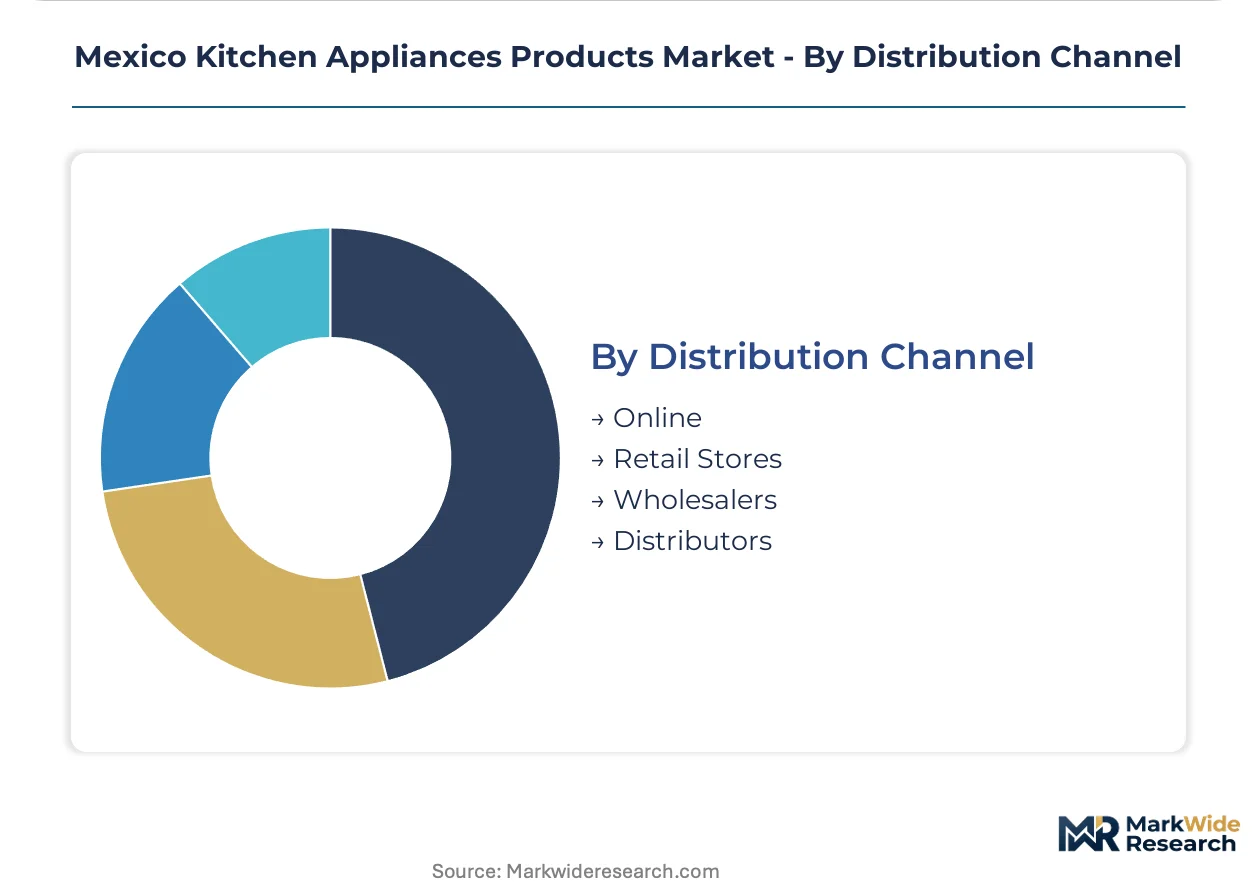
Distribution Channel:
Customer type fragmentation splits between digitally native buyers seeking direct manufacturer relationships and traditional retail-dependent segments requiring physical specification confirmation.
- Online:Manufacturer-direct storefronts and marketplace platforms. Puebla and Querétaro housing developments demonstrate strongest penetration where new construction buyers research digitally before showroom confirmation.
- Retail Stores:Physical appliance showrooms with installation service bundling. Monterrey's industrial corridor retains concentration despite e-commerce share capture.
- Wholesalers:Volume procurement intermediaries serving contractor and developer accounts. Project-based demand concentrates in Mexico City metropolitan new construction.
- Distributors:Regional logistics networks with inventory holding and service capabilities. Geographic coverage gaps in southern states sustain intermediary relevance.
Retail stores retain transaction volume leadership; online channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Mexican sub-markets. Metropolitan buyers absorb inverter technology premiums readily while peripheral states prioritize entry-tier equipment. This divergence shapes regional distribution strategies and inventory allocation priorities.
Mexico City Metropolitan Area
Connected cooking solutions and smart refrigeration drive replacement cycles among affluent households. CONUEE efficiency labeling mandates accelerate inverter compressor adoption in formal retail channels. The urban core concentrates premium appliance showrooms and manufacturer service networks.
Nuevo León
Monterrey's industrial corridor anchors captive component supply and final assembly operations for northern Mexico. The state's manufacturing base benefits from proximity to US border logistics and established technician training programs. New residential developments specify built-in kitchen configurations at above-average rates.
Jalisco
Guadalajara's expanding middle-class housing stock remains underpenetrated by premium appliance retail relative to capital-region saturation. Federal electricity tariffs push hospitality procurement toward NOM-011-ENER compliant equipment in the city's growing hotel sector. E-commerce penetration runs highest among new construction buyers researching specifications digitally.
Bajío Region
Querétaro and Puebla housing developments demonstrate strongest online appliance transaction growth where buyers confirm showroom appointments after digital research. PROFECO warranty disclosure requirements impose compliance overhead on distributors serving these rapidly urbanizing corridors. Regional logistics networks maintain inventory holding gaps that sustain intermediary relevance.
Northern Border States
Price-sensitive demand concentrates in legacy 127V electrical infrastructure zones where smart appliance performance degrades. Copper and steel input volatility compresses margins for assemblers dependent on Monterrey component supply chains. Informal import channels sustain residual demand for unlabeled conventional equipment outside formal retail.
Mexico Kitchen Appliances Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Mexico's kitchen appliances sector. The upper tier combines captive manufacturing with established distribution breadth, while mid-tier players compete on feature differentiation and pricing agility. Three archetypes dominate: vertically integrated domestic assemblers, technology-focused multinational electronics firms, and brand-centric global appliance houses. Competitive moves center on inverter technology licensing partnerships and e-commerce channel bypass strategies that disintermediate traditional retail markups.
Within the integrated domestic tier, Mabe leverages its Monterrey manufacturing presence and captive component supply to anchor cost positioning across northern markets. LG Electronics and Whirlpool occupy distinct competitive vectors—LG exemplifies inverter technology leadership in refrigeration segments, while Whirlpool represents brand recognition and distribution breadth through retail partnerships. These three firms illustrate how geographic manufacturing concentration, technology specialization, and channel control create defensible market positions under CONUEE regulatory pressure.
| Leading Market Players |
|---|
| Whirlpool |
| Mabe |
| LG Electronics |
| Samsung Electronics |
| Electrolux |
| Haier |
| Panasonic |
| BSH Home Appliances (Bosch) |
| Hisense |
| Others |
Pricing and Supply Chain Analysis
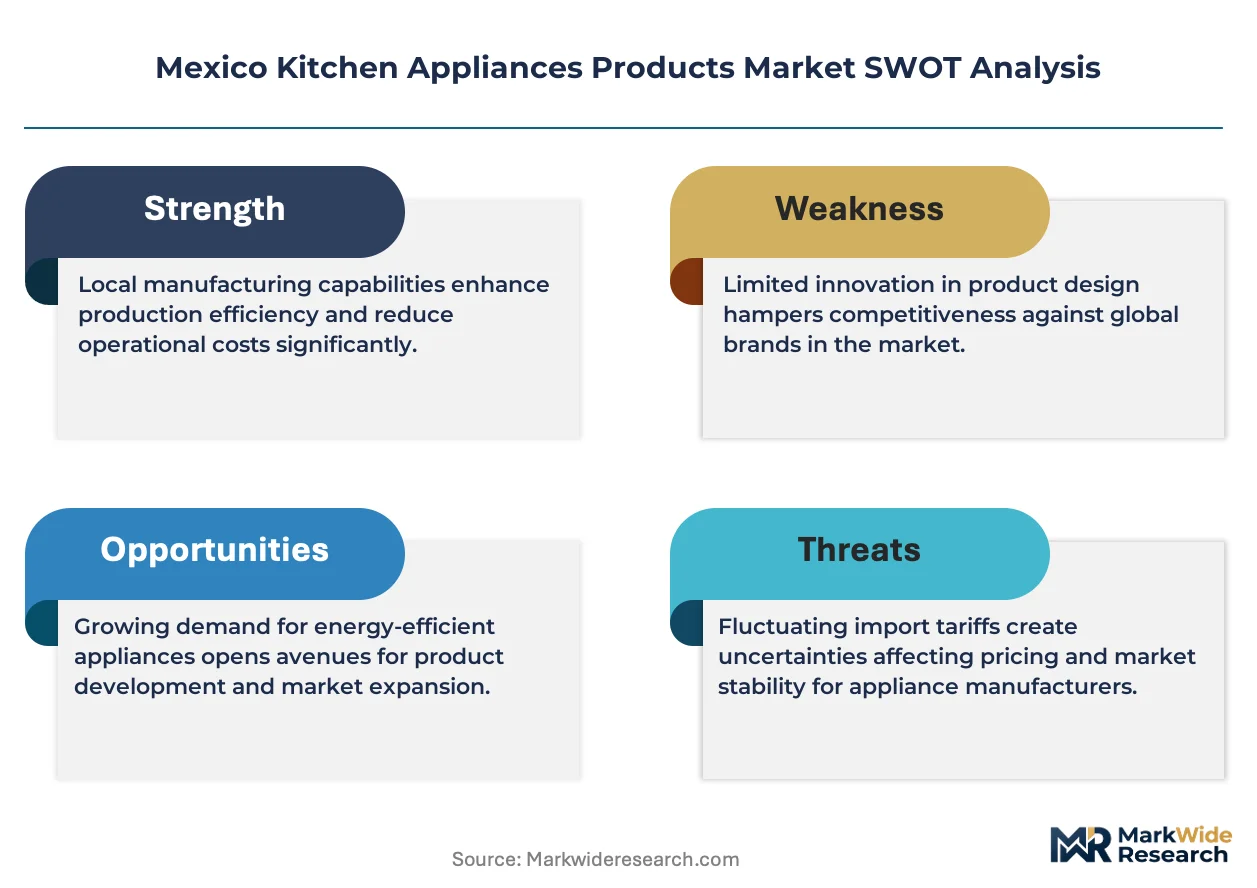
CONUEE energy labeling protocols gate both supply qualification and price differentiation simultaneously in Mexico's kitchen appliances sector. Manufacturers must secure NOM-011-ENER certification to access formal retail channels, while tiered efficiency grades stratify pricing power across inverter and conventional compressor lines.
Pricing Analysis
Extended warranty and service contract revenue drives lifetime value capture for distributors and manufacturers alike. Three-tier pricing structure across premium, standard, and economy levels reflects CONUEE certification grade and smart connectivity bundling. Cost compression in mid-tier inverter models is intensifying because LG and Samsung licensing agreements erode technology premiums. Residential replacement buyers in peripheral urban zones exhibit highest price sensitivity, while hospitality procurement in Mexico City shows lowest sensitivity due to operational cost recovery timelines.
Supply Chain Analysis
Inventory holding periods for inverter compressors and electronic control modules stretch lead times beyond conventional component procurement cycles. Mexico's kitchen appliance manufacturing draws from China for magnetron assemblies, South Korea for inverter drive systems, and domestic Monterrey fabrication for cabinet stampings and insulation foams. Copper and steel input volatility creates margin compression risk for assemblers lacking captive smelter relationships. Distribution runs through regional logistics networks with inventory holding in Nuevo León, supplemented by direct-to-consumer fulfillment from manufacturer online storefronts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's kitchen appliances market sits in cyclical recovery as CONUEE efficiency tier revisions compress replacement cycles and accelerate upgrade demand across aging housing stock.
For Market Incumbents: Compound service network density in Guadalajara and Querétaro corridors to preempt e-commerce disintermediation threats from manufacturer-direct channels. Deepen backward integration into inverter compressor component supply through Monterrey supplier partnerships, securing cost position against emerging Korean and Chinese entrants. For New Entrants and Emerging Players: Anchor in the underpenetrated Jalisco premium retail segment where middle-class housing expansion outpaces established showroom presence. Target hospitality procurement modernization in Guadalajara's hotel construction pipeline with NOM-011-ENER compliant refrigeration specifications, leveraging direct specification relationships with project developers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across smart appliance assembly as modular connectivity platforms reduce R&D duplication costs. Acquisition targets should emphasize regional distributors with decade-long PROFECO parts inventory compliance and established technician training infrastructure. Monitor CONUEE efficiency tier revision announcements as the primary signal for replacement cycle acceleration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Technology Licensing | Partnerships with LG or Samsung compress R&D timelines for mid-tier entrants seeking CONUEE A-grade certification. |
| E-Commerce Channel Expansion | Direct-to-consumer logistics in Puebla and Querétaro bypasses traditional retail markups and captures digitally native buyers. |
| Service Network Densification | Technician training programs in Jalisco address inverter repair scarcity and extend warranty contract attach rates. |
| Backward Integration | Captive component supply in Nuevo León insulates margins from copper and steel commodity volatility. |
| Hospitality Specification Partnerships | Direct relationships with Guadalajara hotel developers secure NOM-011-ENER compliant refrigeration procurement mandates. |
Research Methodology
A standing panel of appliance manufacturing executives, CONUEE certification laboratory directors, retail category buyers, and hospitality procurement managers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from NOM-011-ENER certification databases, PROFECO consumer complaint filings, and customs import records for compressor and electronic component categories. Bottom-up demand modeling across residential replacement cycles and top-down macroeconomic anchoring were triangulated for consistency.
Consistency checks validated volume and value outputs against external benchmarks including housing stock age profiles and federal electricity tariff elasticity studies. The analytical framework modeled product type, technology tier, end-user application, and distribution channel dimensions across the projection horizon. CAGRs were derived from replacement cycle compression rates under efficiency mandate scenarios, with smart appliance connectivity adoption curves and inverter penetration trajectories serving as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable CONUEE regulatory enforcement and continued federal electricity tariff structures; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Japan Kitchen Appliances Market
Kitchen Appliances
Australia Kitchen Appliances Market
Kitchen Appliances
Electric Grill Market
Kitchen Appliances
Kitchen Knife Market
Kitchen Appliances
Residential Cooking Grills Market
Kitchen Appliances
Outdoor Commercial Grills Market
Kitchen Appliances
Kitchen Appliances Market
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
US Cookware Market
Kitchen Appliances
Brazil Kitchen Appliances Market
Kitchen Appliances
Small Kitchen Appliances Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
Toast Maker Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
South Korea Kitchen Appliances Market
Kitchen Appliances
Europe Major Home Appliances Market