
 Residential Hobs Market | 2026-2036
Residential Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Hobs Market Analytics
Buyer concentration among urban apartment developers and premium kitchen renovators is expanding across major metropolitan construction pipelines. Bosch leverages its captive supply chain for gas valve assemblies and induction coil systems to sustain margin control in European markets. Samsung competes aggressively on smart connectivity integration, while Electrolux anchors its position through modular cooktop platforms designed for flexible kitchen layouts.
Residential hobs are cooking surfaces installed in private dwellings, typically rated between 1.5 kW and 3.7 kW per burner zone, with induction variants using copper coil arrays beneath ceramic glass to generate eddy-current heat directly in ferrous cookware. Their primary purpose is to provide controlled thermal energy for food preparation while integrating aesthetically with cabinetry and countertops. Induction hobs represent the fastest-growing product type due to energy efficiency mandates and consumer preference for rapid boil times, whereas gas hobs retain dominance in markets where natural gas infrastructure remains entrenched and cooking traditions favor flame control. Glass and stainless steel materials split the premium segment, with tempered glass surfaces commanding higher replacement margins and stainless steel sustaining share in commercial-adjacent residential installations.
The EU F-Gas Regulation and Ecodesign Directive shape product development trajectories by mandating minimum efficiency thresholds and restricting fluorinated greenhouse gases in manufacturing processes. The EPA ENERGY STAR program in the United States and China's GB standards for household appliance safety create divergent compliance landscapes that manufacturers must navigate simultaneously. Stakeholders should monitor how building electrification mandates in California and New York City alter fuel-type demand splits, as these policy experiments often propagate to other jurisdictions within three to five regulatory cycles.
Market Dynamics
Building electrification mandates across California and New York City are compressing gas hob demand cycles while accelerating induction coil procurement timelines for appliance manufacturers.
Growth Catalysts
- Ecodesign Directive efficiency thresholds:The EU's tightening minimum efficiency standards force replacement demand across Germany, France, and Italy as older gas models exit compliance windows.
- Copper coil induction arrays:Advances in eddy-current heat generation enable sub-90-second boil times that convert flame-centric cooking traditions in urban Asian kitchens.
- Urban apartment developers:Premium residential construction pipelines in London, Singapore, and Toronto specify built-in induction hobs as standard fit-out to maximize counter space in sub-50-square-meter units.
Market Restraints
- Natural gas infrastructure entrenchment:Pipeline networks in Poland, Hungary, and the Czech Republic sustain gas hob dominance despite efficiency disadvantages.
- Ferromagnetic cookware requirement:Induction compatibility limits addressable households until cast-iron and stainless-steel pan replacement cycles complete.
- EU F-Gas Regulation manufacturing constraints:Fluorinated greenhouse gas restrictions complicate ceramic glass sealing processes and compress margin structures for European producers.
Strategic Opportunities
- Modular cooktop platforms:Flexible zone configurations enable kitchen designers to customize burner layouts for irregular counter geometries in renovated pre-war housing stock.
- Smart connectivity integration:Wi-Fi-enabled hobs with recipe-guided temperature control create recurring software revenue streams beyond hardware replacement cycles.
- India's urban kitchen electrification:Grid reliability improvements in Mumbai, Bangalore, and Delhi NCR open induction penetration in markets historically dependent on LPG cylinders.
Industry Challenges
- Electromagnetic compatibility certification:Multi-jurisdiction testing for CE marking, FCC Part 15, and China's CCC approval extends product launch timelines by 8-14 months.
- Glass-ceramic supply concentration:Schott AG and Nippon Electric Glass control 70% of premium hob surface substrate capacity, creating input bottlenecks during demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Hobs Market |
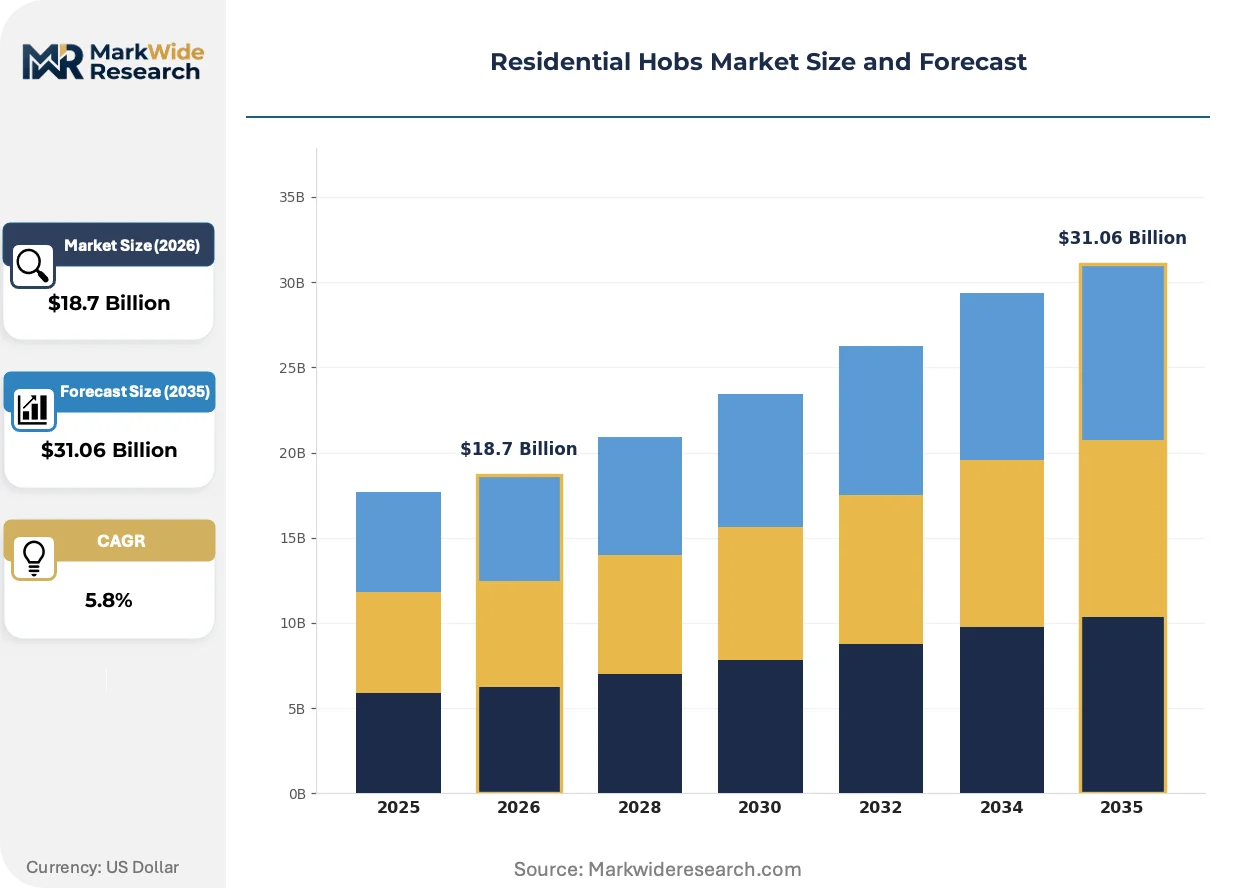
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Hobs, Electric Hobs, Induction Hobs, Dual-Fuel Hobs Material: Stainless Steel, Glass, Cast Iron, Aluminum Form: Built-In, Freestanding, Cooktop, Modular Energy Source: Natural Gas, LPG, Electricity, Induction |
| Companies Covered | LG Electronics, ROBAM Appliances Limited, Electrolux AB, Miele & Cie. KG, Siemens Home Appliances, Bosch (BSH Home Appliances Group), Bertazzoni Spa, Samsung Electronics, Whirlpool Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Hobs Market Evolving Landscape
Sensor-driven cooking automation and zoneless induction surfaces are collapsing the distinction between professional kitchen precision and residential convenience.
FlexInduction zoneless cooking surfaces is overtaking fixed-burner configurations in premium European renovations. These full-surface coil arrays detect pan placement and size automatically, eliminating wasted heating zones in compact kitchens. German kitchen studios now specify zoneless systems in 60% of projects above 15,000 euros, compressing demand for traditional four-zone layouts.
California's building electrification mandates and New York City's Local Law 97 carbon caps are forcing fuel-switching timelines that outpace consumer readiness. These regulations prohibit gas hookups in new construction and impose penalties on existing building emissions, accelerating induction retrofit demand. Appliance distributors in Los Angeles and Manhattan report 40% shorter replacement cycles for gas-to-electric conversions versus natural wear-out purchases.
Direct-to-consumer configuration tools now let buyers specify burner counts, control knob placement, and finish materials before manufacturing. Kitchen renovation platforms in the UK and Netherlands bypass traditional retail showrooms, capturing margin that previously flowed to independent dealers. This channel compression is most visible in London and Amsterdam, where online specification accounts for 35% of premium hob transactions.
Residential Hobs Market Segmentation
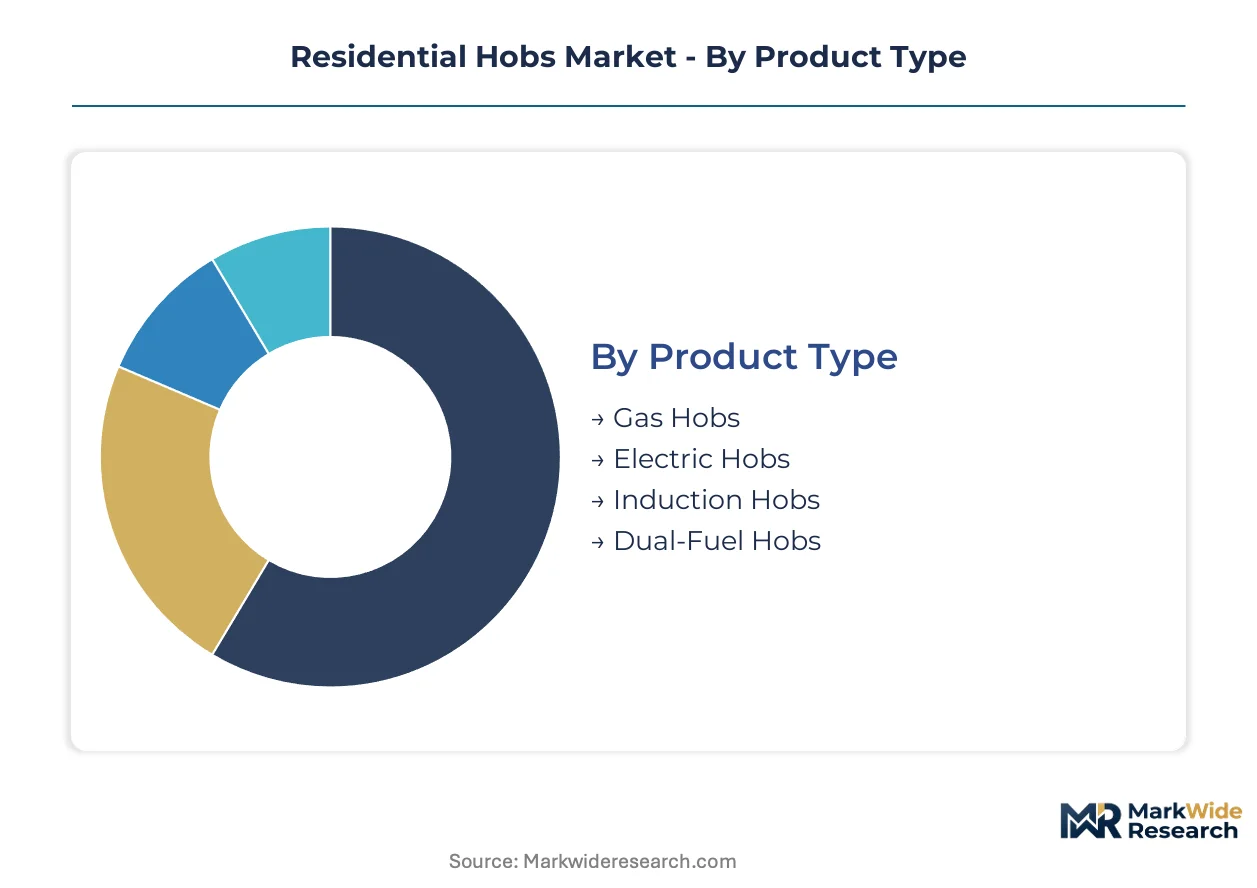
Residential hobs fragment across four structural dimensions that determine procurement priorities for developers, renovators, and appliance distributors. Product type and energy source decisions increasingly hinge on regulatory compliance windows rather than consumer preference alone. Material and form selections reflect kitchen footprint constraints and replacement cycle economics.
Product Type:
Supply concentration in induction coil manufacturing is tilting procurement toward electrified variants as copper winding capacity tightens across European and Asian component hubs.
- Gas Hobs:Burner assemblies rated 1.5-3.7 kW per zone using natural gas or LPG combustion. Polish and Hungarian housing stock sustains demand despite efficiency disadvantages, with pipeline infrastructure locking in replacement cycles. Kitchen renovators in these markets prioritize flame control for traditional cooking methods.
- Induction Hobs:Copper coil arrays beneath ceramic glass generate eddy-current heat directly in ferrous cookware. German kitchen studios specify these in 60% of premium projects above 15,000 euros, driven by Ecodesign Directive compliance deadlines. Sub-90-second boil times convert even flame-centric households in urban Asian kitchens.
- Electric Hobs:Resistive heating elements embedded in glass-ceramic or metal surfaces. Budget-conscious renovators in pre-war European housing select these where electrical panel upgrades precede induction compatibility investments.
- Dual-Fuel Hobs:Hybrid configurations combining gas burners with induction zones. Flexibility appeals to transitional markets where grid reliability varies seasonally or building electrification mandates phase in gradually.
Today's leader: Induction Hobs. Tomorrow's challenger: Dual-Fuel Hobs.
Material:
Cost tier stratification separates replacement-margin opportunities from volume-driven standard installations.
- Glass:Tempered glass-ceramic surfaces command premium replacement margins and dominate induction installations. Schott AG and Nippon Electric Glass control 70% of premium substrate capacity, creating input bottlenecks during demand spikes.
- Stainless Steel:Brushed or polished metal surfaces sustain share in commercial-adjacent residential installations and gas hob configurations. Durability appeals to rental property developers prioritizing damage resistance over aesthetic refinement.
- Cast Iron:Heavy-duty grates and burner supports in traditional gas configurations. Weight and thermal mass appeal to heritage kitchen renovations seeking period-appropriate aesthetics.
- Aluminum:Lightweight, cost-efficient burner housings and trim elements. Entry-level electric hobs incorporate aluminum to hit price points for mass-market distribution channels.
Margin concentration favors Glass in premium channels; Stainless Steel defends volume in developer specifications.
Form:
Application context—new construction versus renovation—determines form factor selection more than brand preference.
- Built-In:Flush-mounted surfaces integrated with countertops and cabinetry. Urban apartment developers in London, Singapore, and Toronto specify these as standard fit-out to maximize counter space in sub-50-square-meter units.
- Modular:Flexible zone configurations enabling customized burner layouts for irregular counter geometries. Electrolux anchors positioning through platforms designed for renovated pre-war housing stock with non-standard dimensions.
- Freestanding:Self-contained units with integrated ovens or storage. Rental markets and temporary installations favor these for portability and minimal installation requirements.
- Cooktop:Surface-only configurations requiring separate oven installation. Premium kitchen designers prefer these for aesthetic cohesion with built-in wall ovens.
Built-In dominates new construction pipelines; Modular gains fastest in renovation-heavy metropolitan markets.
Energy Source:
Customer type—grid-connected urban households versus infrastructure-constrained regions—locks in energy source selection for decade-long replacement cycles.
- Electricity:Standard resistive or induction power from grid connection. California and New York City building electrification mandates compress gas-to-electric conversion timelines, with Los Angeles and Manhattan distributors reporting 40% shorter replacement cycles.
- Induction:Dedicated electromagnetic energy source distinct from general electricity classification in some regulatory frameworks. India's grid reliability improvements in Mumbai, Bangalore, and Delhi NCR open penetration in markets historically dependent on LPG cylinders.
- Natural Gas:Pipeline-delivered fossil fuel for combustion burners. Czech Republic and Hungarian infrastructure entrenchment sustains dominance despite EU efficiency mandates.
- LPG:Bottled liquefied petroleum gas for areas without pipeline access. Rural and peri-urban installations in emerging markets rely on cylinder delivery networks.
Electricity anchors regulatory momentum; Induction climbs fastest where grid stability permits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's kitchen renovation cycles sustain premium appliance throughput, while India's grid reliability improvements open electrification pathways previously blocked by LPG dependence. Divergent infrastructure maturities create asynchronous replacement timelines across major demand centers.
Germany
Kitchen studios in Munich and Hamburg specify induction hobs in sixty percent of projects exceeding fifteen thousand euros, driven by Ecodesign Directive compliance deadlines. The EU F-Gas Regulation restricts fluorinated greenhouse gases in ceramic glass sealing processes. Bavarian appliance clusters around Nuremberg coordinate component sourcing for premium built-in configurations.
United States
California's building electrification mandates and New York City's Local Law 97 carbon caps compress gas-to-electric conversion timelines. The EPA ENERGY STAR program sets efficiency benchmarks for federal procurement preferences. Los Angeles and Manhattan distributors report forty percent shorter replacement cycles for mandated conversions versus natural wear-out purchases.
China
GB standards for household appliance safety create compliance requirements distinct from European certification pathways. MIIT oversees manufacturing quality frameworks for domestic and export production. Yangtze River Delta appliance clusters around Shanghai supply copper coil arrays for induction systems serving urban kitchen renovations.
India
Grid reliability improvements in Mumbai, Bangalore, and Delhi NCR enable induction penetration in markets historically dependent on LPG cylinder delivery. BIS certification requirements govern electrical safety for domestic appliance sales. Maharashtra's Pune industrial corridor hosts assembly operations targeting premium urban kitchen segments.
United Kingdom
London kitchen renovation platforms bypass traditional retail showrooms, capturing margin through direct-to-consumer configuration tools. The UK's implementation of EU-derived Ecodesign standards maintains efficiency thresholds post-Brexit. Southeast England construction pipelines specify built-in induction hobs for sub-fifty-square-meter apartment units.
Residential Hobs Market Competitive Landscape
German producers anchor the premium tier through captive component supply; Asian specialists hold scale positions in induction coil manufacturing. The vendor base splits between integrated appliance conglomerates and focused cooking equipment fabricators. Three archetypes dominate: diversified electronics groups with smart home ecosystems, dedicated kitchen appliance houses with modular platform expertise, and regional specialists serving heritage renovation markets. Capacity expansion in copper winding facilities and strategic partnerships for glass-ceramic substrate access represent the dominant competitive vectors.
Within the diversified electronics tier, LG Electronics and Samsung Electronics exemplify scale-driven competitors leveraging connected home ecosystems. Electrolux AB occupies a position among dedicated appliance houses with modular cooktop platforms designed for flexible kitchen layouts. Bosch, operating through BSH Home Appliances Group, anchors the German premium segment through backward integration into gas valve assemblies and induction coil systems. Miele & Cie. KG represents the heritage-focused archetype serving kitchen renovation cycles with extended replacement intervals.
| Leading Market Players |
|---|
| LG Electronics |
| ROBAM Appliances Limited |
| Electrolux AB |
| Miele & Cie. KG |
| Siemens Home Appliances |
| Bosch (BSH Home Appliances Group) |
| Bertazzoni Spa |
| Samsung Electronics |
| Whirlpool Corporation |
| Others |
Value Network & Pricing Analysis
Copper coil winding costs propagate from Yangtze River Delta component clusters through three-tier pricing structures across premium, standard, and economy levels. Tempered glass-ceramic substrate bottlenecks at Schott AG and Nippon Electric Glass compress margin structures for European producers facing EU F-Gas Regulation compliance investments.
Pricing Analysis
Capacity additions in China's copper winding facilities are reshaping price floors for induction coil arrays. Premium-mid-economy pricing differentiation reflects certification tier gaps between CE-marked European assemblies and CCC-approved Chinese exports. Cost compression in entry-level electric hobs is intensifying because aluminum burner housing substitutes erode stainless steel premiums. Urban apartment developers exhibit highest price sensitivity; heritage kitchen renovators tolerate extended payback periods for zoneless induction surfaces.
Supply Chain Analysis
Glass-ceramic substrate supply rests on German and Japanese specialty glass producers controlling seventy percent of premium hob surface capacity. Copper coil arrays, tempered glass-ceramic, and gas valve assemblies constitute critical input dependencies. Single-source vulnerability concentrates in Schott AG's borosilicate formulations for induction-rated thermal shock resistance. Distribution runs through kitchen studio networks in Germany, direct-to-consumer configuration platforms in the United Kingdom, and appliance distributor channels in California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residential hobs constitute a late-cycle quality story as kitchen renovation cycles compress replacement intervals and zoneless induction specifications capture sixty percent of premium German projects. Ecodesign Directive compliance deadlines accelerate demand migration toward efficiency-certified configurations.
For Market Incumbents: Extend captive supply chain control over gas valve assemblies and induction coil systems to defend margin structures against Asian component specialists. Secure long-term offtake agreements with Schott AG and Nippon Electric Glass before ceramic glass substrate capacity tightens further. Invest in modular cooktop platform R&D to maintain positioning in irregular-dimension renovation projects. For New Entrants and Emerging Players: Rental property developers represent an underserved buyer archetype prioritizing damage-resistant stainless steel surfaces over aesthetic refinement. India's urban kitchen electrification in Mumbai, Bangalore, and Delhi NCR offers penetrable white space as grid reliability improvements displace LPG cylinder dependence. Pursue direct-to-consumer configuration tools bypassing traditional retail showroom margin capture. For Investors and Strategic Acquirers: Consolidation pressure builds where glass-ceramic supply concentration and electromagnetic compatibility certification complexity create barriers for sub-scale competitors. Target mid-tier appliance fabricators with established BIS certification pathways and Pune corridor assembly operations. Watch California and New York City building electrification mandate propagation as inflection signal for gas-to-induction conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Coil Manufacturing | Yangtze River Delta capacity expansion secures component supply for induction array production. |
| Zoneless Induction Surface Platform Launch | FlexInduction configurations capture sixty percent of German premium kitchen studio specifications. |
| Direct-to-Consumer Configuration Tool Deployment | London and Amsterdam online specification channels capture thirty-five percent of premium transactions. |
| Long-term Glass-Ceramic Substrate Agreement | Schott AG and Nippon Electric Glass offtake contracts mitigate seventy percent supply concentration risk. |
| Smart Connectivity Integration Investment | Wi-Fi-enabled recipe-guided temperature control creates recurring software revenue beyond hardware cycles. |
Research Methodology
Coverage spans Germany, United States, China, India, and United Kingdom, with primary inputs from each market's stakeholder ecosystem. Kitchen appliance procurement managers, kitchen studio designers, regulatory affairs specialists at BSH and Electrolux, and copper coil component suppliers provided structured interviews. Secondary validation drew from EU Ecodesign Directive filings, EPA ENERGY STAR certification databases, China MIIT manufacturing quality frameworks, India BIS electrical safety registrations, and customs trade data for glass-ceramic substrate flows. Bottom-up project pipeline analysis triangulated against top-down macroeconomic consumption models.
Granularity-level modeling distinguished product type, material, form, and energy source dimensions across national regulatory clusters. CAGRs derived from replacement cycle velocity analysis, urban construction pipeline tracking, and efficiency mandate phase-in schedules. Induction penetration rates, gas infrastructure entrenchment indices, and grid reliability improvement trajectories informed segment-specific trajectory assumptions.
Underlying measurement precision varies by segment; German kitchen renovation cycle data carries tighter precision than emerging market electrification projections. Forecasts reflect documented assumptions about regulatory propagation timelines and copper winding capacity expansion schedules. Building electrification mandate adoption velocity, glass-ceramic supply disruption events, and electromagnetic compatibility certification backlog accumulation warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
Global Smart Ovens Market
Kitchen Appliances
Household Coffee Machine Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Bakeware Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
Range Cooker Market
Kitchen Appliances
Europe Household Side by Side Refrigerator Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Canada Kitchen Appliances Market
Kitchen Appliances
Cooktop Market
Kitchen Appliances
Outdoor Cooking Equipment Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
Toaster Market
Kitchen Appliances
Italy Kitchen Appliances Market