
 Asia-Pacific Air Fryers Market | 2026-2036
Asia-Pacific Air Fryers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Air Fryers Market Insights
Smart heating algorithms and IoT-enabled temperature control is reconfiguring how air fryer manufacturers engineer precision cooking cycles across the Asia-Pacific. Xiaomi Corporation leverages its connected-device ecosystem to anchor its position in digitally integrated kitchen appliances. Groupe SEB sustains competitive pressure through its specialization in premium multi-functional platforms. Midea Group dominates mass-market manufacturing scale across China's domestic and export channels.
Asia-Pacific air fryers are countertop or built-in electric cooking appliances that circulate superheated air between 150°C and 200°C through a compact chamber to simulate deep-frying with minimal oil, serving residential kitchens and commercial foodservice operations seeking healthier preparation methods. Digital air fryers command the strongest margin pools as consumers prioritize programmable presets and app connectivity, while compact models lead volume in urban apartments across Tokyo, Seoul, and Mumbai. Multi-functional air fryers that combine grilling, baking, and dehydrating functions represent the fastest-growing product configuration as space-constrained households consolidate appliances.
BIS certification requirements in India and China's GB standards enforced by SAMR dictate electrical safety and energy efficiency thresholds that determine market access for imported and domestic brands. Japan's METI energy labeling program shapes consumer preference toward inverter-based heating technologies that reduce power consumption. Stakeholders must monitor how Australia's TGA-equivalent electrical safety frameworks and South Korea's KC marking evolution will harmonize or diverge from existing Asia-Pacific compliance pathways.
Market Dynamics
Smart heating algorithms and IoT-enabled temperature control are reconfiguring how air fryer manufacturers engineer precision cooking cycles across the Asia-Pacific, compressing development timelines and raising certification thresholds simultaneously.
Growth Catalysts
- Urban household consolidation:Space-constrained apartments in Tokyo, Seoul, and Mumbai drive demand for multi-functional appliances that combine grilling, baking, and dehydrating capabilities.
- TRAI digital commerce infrastructure:India's telecommunications regulator accelerates online distribution channels, expanding addressable reach for compact and digital air fryer models in metropolitan corridors.
- GB standards compliance:China's State Administration for Market Regulation enforces kitchen appliance safety protocols that validate product quality and reduce consumer purchase friction.
Market Restraints
- Copper and semiconductor input volatility:Heating element materials and microcontroller chip pricing fluctuations compress margin predictability for manufacturers sourcing across East Asian supply nodes.
- Component concentration in Guangdong:Motor and fan assembly production clusters in China's Pearl River Delta create geographic vulnerability to regional logistics disruptions.
- Inverter technology cost barriers:Premium heating systems required for Japan's METI energy labeling program price out mass-market penetration in lower-tier Indian cities.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:Southeast Asian middle-class expansion in Ho Chi Minh City and Jakarta presents first-mover advantage for compact model localization.
- India's PLI scheme for white goods:Production-linked incentive frameworks reduce effective manufacturing costs for domestic assembly operations serving South Asian export markets.
- Convergence of air frying and steam cooking:Hybrid appliance architectures address health-conscious consumer segments seeking oil reduction without texture compromise.
Industry Challenges
- BIS certification timeline compression:India's Bureau of Indian Standards testing protocols create 4-6 month product launch delays for imported brands unfamiliar with documentation requirements.
- Embedded software talent scarcity:Firmware engineering for IoT-connected presets and app synchronization outpaces available skilled labor pools in tier-two Chinese manufacturing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Air Fryers Market |
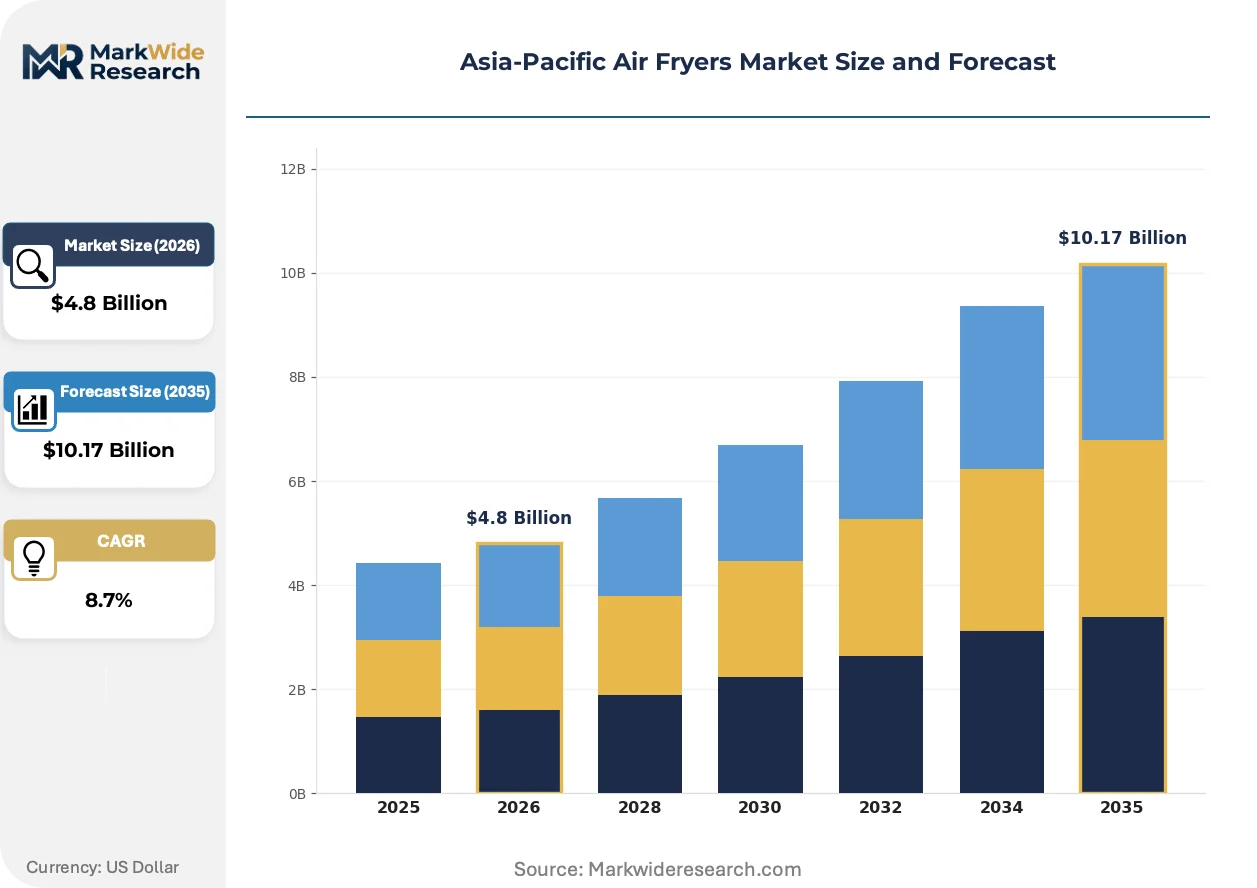
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Air Fryers, Conventional Air Fryers, Digital Air Fryers, Multi-functional Air Fryers End User: Households, Restaurants, Cafeterias, Catering Services Installation: Countertop, Built-in, Portable, Commercial Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Philips, Black & Decker, Havells, Wonderchef, Breville, Groupe SEB, Midea Group, Xiaomi Corporation, Cuisinart Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Air Fryers Market Trends and Innovations
Precision cooking technology and regulatory energy labeling are converging to redefine product architecture and go-to-market sequencing across Asia-Pacific kitchen appliance supply chains.
Smart heating algorithms with machine learning-based temperature modulation are digitizing how manufacturers calibrate cooking cycles for regional ingredient variations. Tier-one Chinese households and South Korean apartment dwellers adopt these systems fastest, demanding programmable presets accessible through mobile applications. This capability compression is digitizing traditional hardware margins into software-enabled recurring revenue streams.
Japan's METI energy labeling program mandates disclosure of inverter-based heating efficiency, redirecting R&D investment toward power consumption reduction. Manufacturers serving the Japanese market must redesign thermal management systems to qualify for preferred retail placement. South Korea's KC marking evolution toward harmonized efficiency metrics is forcing similar architectural adjustments for brands seeking cross-border scale.
Direct-to-consumer channel expansion through live-streaming commerce platforms is fragmenting traditional appliance retail in China and India. Young urban buyers in Shanghai and Bangalore purchase air fryers through influencer-curated sessions rather than brick-and-showroom visits. This disintermediation compresses brand building timelines while elevating returns logistics complexity for manufacturers without localized fulfillment infrastructure.
Asia-Pacific Air Fryers Market Segmentation
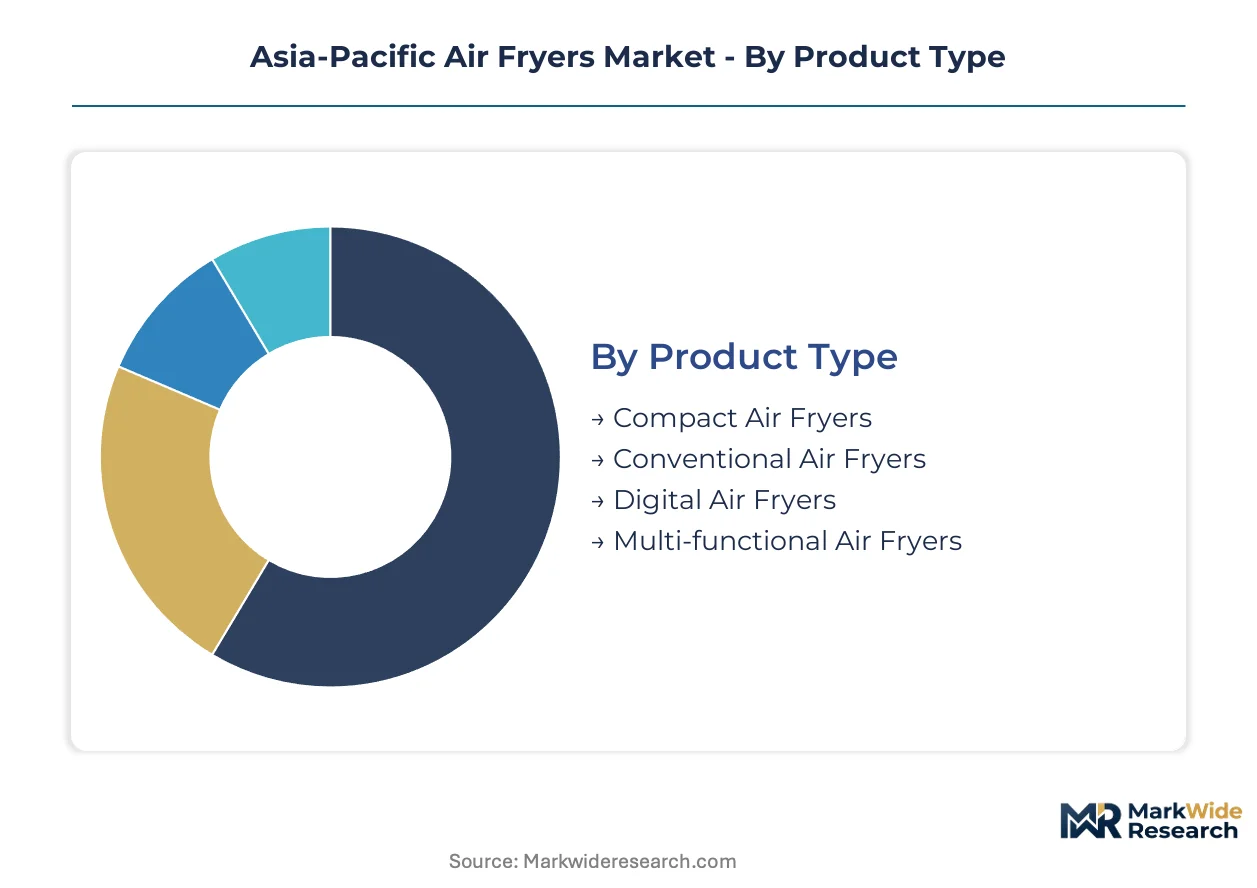
Segmentation in the Asia-Pacific air fryers market reveals distinct procurement patterns across household and commercial buyers, with product configuration and channel preference varying sharply by urban density and regulatory environment. Understanding these divides enables manufacturers to calibrate certification investments and distribution partnerships against addressable margin pools.
Product Type:
Replacement cycles vary dramatically across product configurations, with compact models turning over fastest through impulse channels while multi-functional platforms sustain longer ownership horizons through planned replacement.
- Compact Air Fryers:Single-basket units under 3-liter capacity dominate studio apartments in Mumbai, Seoul, and Tokyo where countertop space commands premium pricing. Demand concentrates in India's metropolitan corridors where TRAI's digital commerce infrastructure accelerates online discovery and same-day fulfillment.
- Digital Air Fryers:Microcontroller-driven units with programmable presets and app connectivity capture the strongest margin pools across Asia-Pacific. China's tier-one cities and South Korean apartment complexes drive adoption as consumers prioritize IoT-enabled temperature calibration and recipe synchronization.
- Conventional Air Fryers:Mechanical dial-controlled units serve price-sensitive first-time buyers in Vietnam and Indonesia's emerging middle-class households.
- Multi-functional Air Fryers:Hybrid platforms combining grilling, baking, and dehydrating functions are gaining share fastest among space-constrained urban households consolidating appliance footprints.
Conventional air fryers dominate installed base across lower-tier cities. Digital and multi-functional configurations are where expansion concentrates.
End User:
Procurement authority separates sharply between residential decision-makers prioritizing aesthetic integration and commercial operators optimizing throughput per square meter.
- Households:Residential buyers in China's tier-one cities and India's metropolitan corridors prioritize compact footprints and energy efficiency credentials under Japan's METI labeling influence. BIS certification requirements in India and China's GB standards shape purchase confidence and retail placement.
- Restaurants:Quick-service operators in Ho Chi Minh City and Jakarta deploy high-capacity units for menu diversification without deep-fryer infrastructure investments.
- Cafeterias:Institutional foodservice in South Korean corporate complexes and Japanese municipal facilities drives demand for durable commercial-grade heating elements.
- Catering Services:Mobile food operators across Southeast Asia favor portable configurations with rapid heat recovery for off-site event execution.
Households anchor volume demand. Restaurants and catering services are climbing the fastest as commercial health-positioning accelerates.
Installation:
Physical integration requirements stratify pricing power, with built-in and commercial installations commanding project-based sales cycles absent from portable segments.
- Countertop:Freestanding units dominate residential adoption across Tokyo apartments and Bangalore condos where lease restrictions prohibit permanent modifications. China's domestic manufacturing scale from Midea Group and others saturates this segment with aggressive cost positioning.
- Built-in:Cabinet-integrated designs penetrate premium kitchen renovations in Seoul and Shanghai where interior designers specify appliance ecosystems. SAMR's GB standards for electrical safety and installation clearance create compliance thresholds that filter out smaller import brands.
- Portable:Lightweight units with carrying handles serve outdoor catering and temporary food stalls across Indonesia's night markets.
- Commercial:High-throughput floor-standing configurations equip centralized kitchens in India's growing cloud-kitchen infrastructure.
Countertop installations dominate current penetration. Built-in and commercial configurations show the steepest expansion trajectory as renovation activity and foodservice outsourcing accelerate.
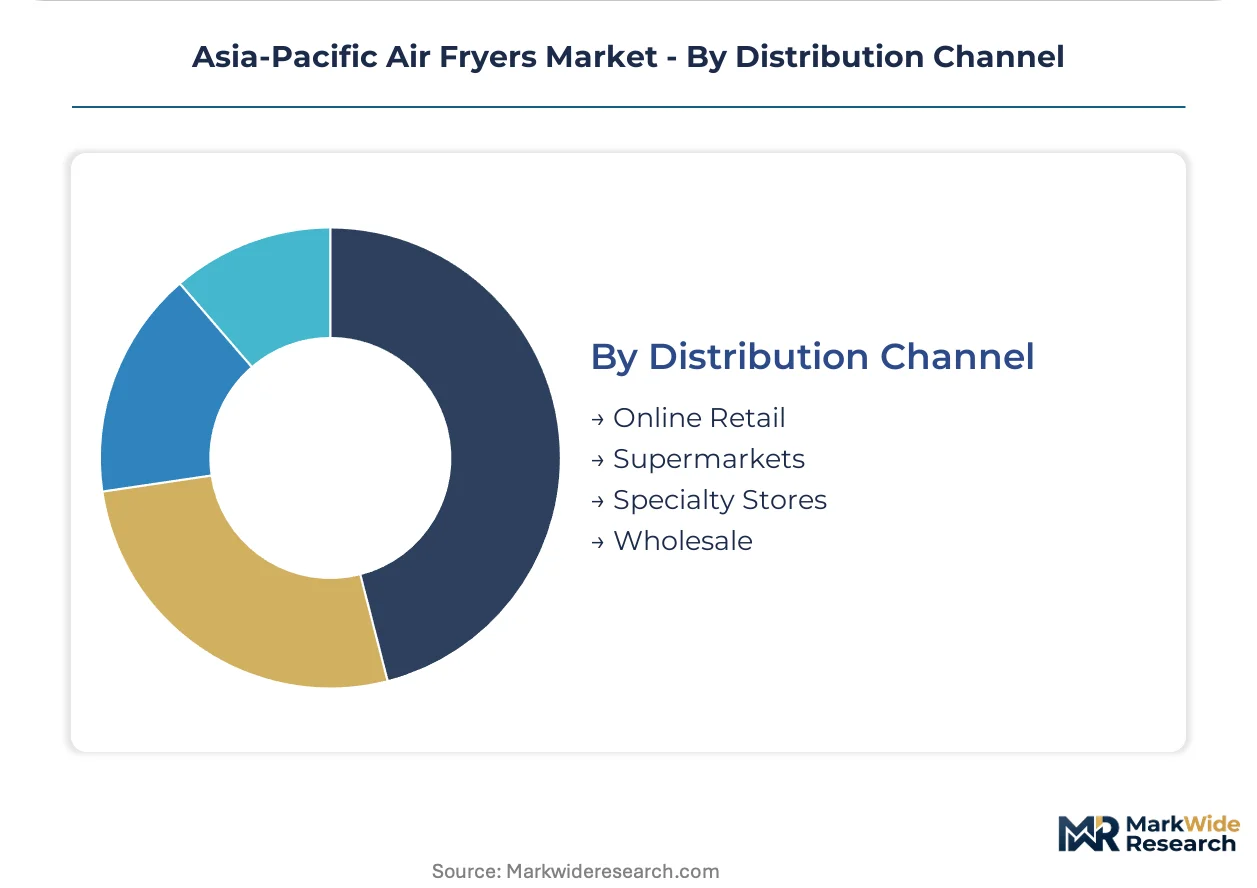
Distribution Channel:
Channel economics diverge between inventory-heavy retail formats and digitally native fulfillment models with fundamentally different working capital requirements.
- Online Retail:Live-streaming commerce platforms fragment traditional appliance retail in China and India, with influencer-curated sessions in Shanghai and Bangalore displacing brick-and-showroom visits. TRAI's digital infrastructure investments compress discovery-to-purchase timelines while elevating returns logistics complexity.
- Supermarkets:Mass-market retailers in Japan and South Korea leverage METI and KC marking visibility to guide energy-conscious selection in physical aisles.
- Specialty Stores:Kitchen appliance boutiques in Australia's metropolitan centers emphasize premium multi-functional demonstrations and extended warranty programs.
- Wholesale:B2B distributors serve restaurant and cafeteria procurement across Vietnam's hospitality supply chains with volume-tiered pricing structures.
Supermarkets and specialty stores anchor established penetration. Online retail is where volume expansion concentrates as digital commerce infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export manufacturing from China and South Korea dominates regional supply, while import-dependent markets in India and Southeast Asia absorb volume through digital commerce channels. Trade flows concentrate through Guangdong's manufacturing clusters and Mumbai's distribution hubs.
China
Tier-one cities including Shanghai and Beijing drive premium digital air fryer adoption with IoT-enabled cooking presets. SAMR enforces GB standards for electrical safety and energy efficiency that filter import brands from retail placement. Midea Group anchors manufacturing scale in Guangdong's Pearl River Delta, supplying domestic and export channels with aggressive cost positioning.
India
Metropolitan corridors in Mumbai and Bangalore accelerate compact model adoption through TRAI-backed digital commerce infrastructure. BIS certification requirements create 4-6 month launch delays for imported brands unfamiliar with documentation protocols. The country's PLI scheme for white goods reduces effective manufacturing costs for domestic assembly operations serving South Asian export markets.
Japan
Tokyo apartment dwellers prioritize inverter-based heating systems under METI's energy labeling program that mandates power consumption disclosure. The regulator's efficiency metrics redirect R&D investment toward thermal management redesign for preferred retail placement. Kanto region households anchor demand for premium multi-functional platforms with extended ownership cycles.
South Korea
Seoul's space-constrained apartment complexes drive multi-functional appliance consolidation combining grilling, baking, and dehydrating capabilities. KC marking evolution toward harmonized efficiency metrics forces architectural adjustments for brands seeking cross-border scale. The capital region's connected-device ecosystem accelerates smart heating algorithm adoption through mobile application integration.
Vietnam
Ho Chi Minh City's emerging middle-class expansion presents first-mover opportunity for compact model localization at accessible price points. The country's national standards body enforces electrical safety protocols that determine market access for imported brands. Southern Vietnam's manufacturing zones attract assembly investment targeting ASEAN distribution networks.
Asia-Pacific Air Fryers Market Competitive Landscape
On the supply side, the industry is tiered between mass-market manufacturers, digitally integrated ecosystem players, and premium multi-functional specialists. Three strategic archetypes dominate: scale-driven OEMs serving private-label and branded channels, connected-device platforms leveraging IoT integration, and premium kitchen appliance houses emphasizing durability and extended warranties. Competitive moves center on backward integration into heating element supply and strategic partnerships with live-streaming commerce platforms for direct-to-consumer reach.
Among Asia-Pacific-based manufacturers, Midea Group and Xiaomi Corporation occupy distinct positions within this structure. Midea exemplifies the scale-driven archetype through captive manufacturing infrastructure. Xiaomi represents the digitally integrated tier, leveraging its connected-device ecosystem for kitchen appliance positioning. Groupe SEB anchors the premium specialist segment through multi-functional platform specialization. Philips, Black & Decker, and Havells serve as regional market anchors with established distribution footprints across their respective home markets.
| Leading Market Players |
|---|
| Philips |
| Black & Decker |
| Havells |
| Wonderchef |
| Breville |
| Groupe SEB |
| Midea Group |
| Xiaomi Corporation |
| Cuisinart Corporation |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Ningbo port corridor's container freight volatility feeds directly into landed cost spreads between Guangdong-sourced compact units and premium Japanese inverter models, compressing margin buffers for distributors while amplifying price stratification across certification tiers.
Pricing Analysis
The pricing gap separating conventional dial-controlled units from microcontroller-driven digital platforms and emerging IoT-enabled next-generation systems spans three distinct technology generations. Three-tier pricing structure across premium inverter-based, standard digital, and economy mechanical tiers reflects divergence in METI compliance costs and BIS certification investment. Pricing pressure stems from copper heating element and semiconductor input volatility squeezing margin predictability for manufacturers. First-time buyers in Vietnam and Indonesia exhibit highest price sensitivity, while Tokyo apartment dwellers purchasing multi-functional platforms show lowest elasticity.
Supply Chain Analysis
Upstream feedstock for heating elements and motor assemblies draws from China's Guangdong Province, South Korea's Gyeonggi manufacturing belt, and Japan's precision component specialists. Copper coil stock, microcontroller chips, and thermal insulation ceramics constitute critical input dependencies. Single-source vulnerability concentrates in Pearl River Delta motor and fan assembly clusters exposed to regional logistics disruptions. Distribution runs through live-streaming commerce platforms and B2B wholesale networks serving restaurant procurement across Southeast Asian hospitality corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific air fryers market constitutes a high-growth disruption propelled by TRAI's digital commerce infrastructure compressing discovery-to-purchase timelines across India's metropolitan corridors.
For Market Incumbents: Insulate core margin pools by securing captive supply of copper heating elements and microcontroller chips against Guangdong concentration risk. Accelerate BIS certification pre-positioning in India to neutralize 4-6 month launch delays threatening first-mover advantage. Defensive R&D investment in inverter-based thermal management addresses METI energy labeling requirements reshaping Japanese retail placement. For New Entrants and Emerging Players: Pursue white-space expansion in Vietnam's Ho Chi Minh City and Indonesia's Jakarta metropolitan zones where compact model penetration remains underdeveloped. Target cloud-kitchen infrastructure operators across India's catering services segment with commercial-grade portable configurations. Anchor go-to-market execution through influencer-curated live-streaming commerce sessions displacing traditional appliance retail. For Investors and Strategic Acquirers: Digitally integrated ecosystem players with IoT firmware capabilities and established app synchronization infrastructure represent priority acquisition archetypes. Long-term viability hinges on software-enabled recurring revenue streams displacing traditional hardware margins across the projection horizon. Monitor KC marking evolution harmonization between South Korea and Japanese METI frameworks as regulatory convergence signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Captive copper coil supply from Guangdong smelters neutralizes input volatility threatening margin predictability. |
| BIS Certification Pre-Positioning | Early documentation investment compresses 4-6 month India launch delays before metropolitan corridor saturation. |
| Inverter Technology R&D Partnership | Collaboration with Japanese thermal engineering specialists secures METI energy labeling compliance for premium tier. |
| Live-Streaming Commerce Platform Integration | Direct-to-consumer channel control through TRAI-backed infrastructure captures urban household impulse procurement. |
| Multi-Functional Platform Extension | Hybrid grilling-baking-dehydrating architectures address space-constrained Seoul and Tokyo apartment consolidation demand. |
Research Methodology
Initial hypotheses were tested against primary input from appliance manufacturing executives, retail category buyers, regulatory compliance officers, and commercial foodservice procurement managers and refined through secondary validation against SAMR GB standards documentation, TRAI digital infrastructure reports, BIS certification protocols, and METI energy labeling guidelines. Bottom-up shipment data triangulation with top-down household penetration modeling anchored volume estimates.
Demand-supply-balance framing across the analysis window calibrated production capacity in Guangdong against metropolitan corridor absorption rates in Mumbai, Bangalore, Shanghai, and Seoul. Segmentation dimensions spanned product configuration, installation type, end-user archetype, and distribution channel intensity. CAGRs derived from logistic adoption curve fitting against urban household consolidation patterns and commercial health-positioning acceleration.
Sensitivities concentrate around copper and semiconductor pricing trajectories, BIS certification timeline variability, and live-streaming commerce platform algorithm shifts altering discovery economics. Cross-checking against customs shipment records and retail audit data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Electric Corkscrew Market
Kitchen Appliances
Household Cooking Appliance Market
Kitchen Appliances
Kitchen Knife Market
Kitchen Appliances
Popcorn Makers Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
Brazil Kitchen Appliances Market
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
Colombia Kitchen Appliances Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
Asia Pacific Induction Hobs Market
Kitchen Appliances
Smart Kitchen Appliances Market
Kitchen Appliances
Bakeware Market
Kitchen Appliances
Middle East Electric Vegetable Chopper Market
Kitchen Appliances
United States Small Kitchen Appliances Market
Kitchen Appliances
Europe Air Fryers Market