
 Electric Fracking Market | 2026-2036
Electric Fracking Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Fracking Market Foresight
North American pressure pumpers is repositioning capital toward dual-fuel and all-electric fleets as diesel economics deteriorate. Halliburton Company anchors the high-horsepower electric segment with turbine-powered deployments across the Permian and Eagle Ford. Liberty Energy Inc. differentiates through its digiFrac all-electric fleet architecture, which eliminates diesel engine maintenance cycles. Baker Hughes Company extends its position via integrated power generation and pumping packages that reduce site footprint and fuel logistics.
Electric fracking replaces diesel-driven mechanical power with grid electricity, natural gas turbines, or fuel cells to drive high-pressure hydraulic pumps, typically operating at 15,000 psi or above for shale stimulation. The technology eliminates engine exhaust at the wellsite while enabling real-time power modulation that matches pump demand curves to reduce fuel waste. Well stimulation services command the largest revenue share as operators outsource capital-intensive fleet conversions, though equipment rental of electric power generators is expanding fastest among independent operators seeking variable-cost structures. Onshore drilling dominates application demand, but tight gas extraction in Appalachia is emerging as a concentrated growth corridor where pipeline proximity supports gas-to-wire economics.
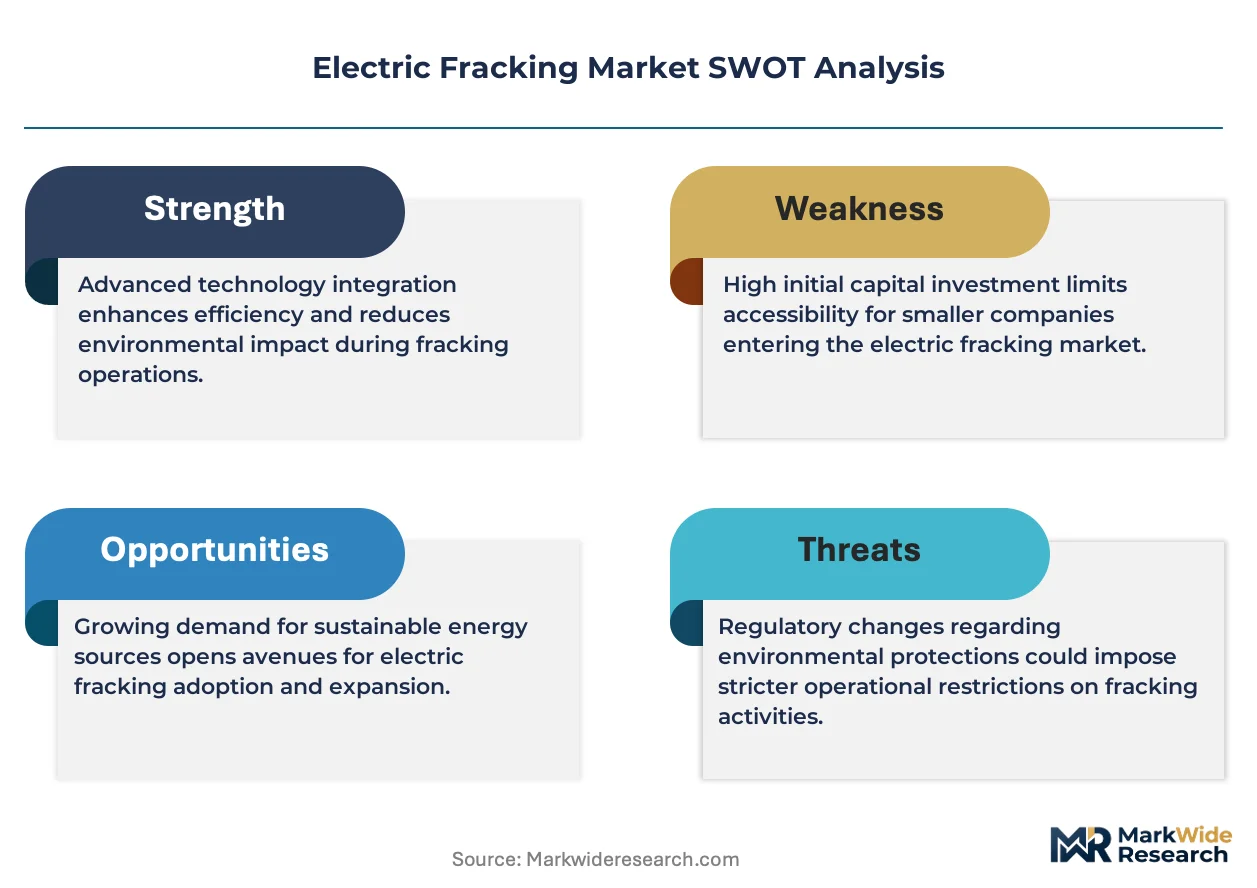
EPA Tier 4 Final emission standards and OSHA combustible dust regulations are reshaping equipment specifications, forcing diesel fleet retirements and elevating electric alternatives. Texas Railroad Commission flaring rules and Colorado Air Quality Control Commission methane intensity thresholds further tighten the operational envelope for conventional pumping. Stakeholders must weigh stranded asset risk in diesel horsepower against the capital intensity and grid dependency of electric fleet conversions.
Market Dynamics
EPA Tier 4 Final emission standards and state-level methane regulations are forcing diesel fleet retirements across unconventional basins, compressing the operational window for conventional pressure pumping while elevating capital allocation toward turbine-powered and grid-tied electric alternatives.
Growth Catalysts
- Texas Railroad Commission flaring restrictions:Operators face gas capture mandates that make turbine-powered electric fleets economically attractive versus diesel alternatives that cannot utilize stranded gas.
- Dual-fuel turbine technology:High-horsepower gas turbines enable real-time fuel switching between field gas and pipeline supply, reducing diesel logistics complexity in Permian Basin operations.
- Appalachian tight gas corridors:Pipeline proximity in Pennsylvania and West Virginia supports gas-to-wire economics for electric fracturing where grid interconnection costs remain manageable.
Market Restraints
- Grid interconnection bottlenecks:Rural transmission infrastructure in West Texas and southeastern New Mexico lacks capacity for multi-megawatt electric fleet draws, forcing operators toward captive gas turbine generation.
- Capital intensity of fleet conversion:Full electric pressure pumping systems require pumpdown unit replacement, power distribution retrofit, and turbine or grid-tie installation that strains independent operator balance sheets.
- Diesel price volatility:Crude-linked fuel costs create margin compression for operators maintaining legacy mechanical fleets while electric alternatives lock in gas-based or grid-priced power.
Strategic Opportunities
- Fuel cell integration:Solid oxide and proton exchange membrane systems offer zero-emission power generation for pressure pumping in methane-intensity regulated basins where combustion turbines face future restrictions.
- Equipment rental channel expansion:Independent operators seek variable-cost electric power generator access rather than capital-intensive fleet ownership, creating aftermarket service revenue pools.
- Colorado Air Quality Control Commission methane thresholds:Stringent intensity caps position electric fracturing as compliance infrastructure rather than optional efficiency upgrade in Denver-Julesburg Basin operations.
Industry Challenges
- High-voltage electrical technician scarcity:Turbine and grid-tie installations require certified power systems specialists that conventional oilfield service labor pools lack, extending commissioning timelines.
- Legacy diesel fleet stranded asset risk:Operators holding conventional horsepower face accelerated depreciation as EPA Tier 4 Final enforcement tightens resale markets and residual values collapse.
- Real-time power modulation integration:Matching variable pump demand curves to turbine output or grid draw requires control system sophistication that exceeds legacy mechanical fleet operational protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Fracking Market |
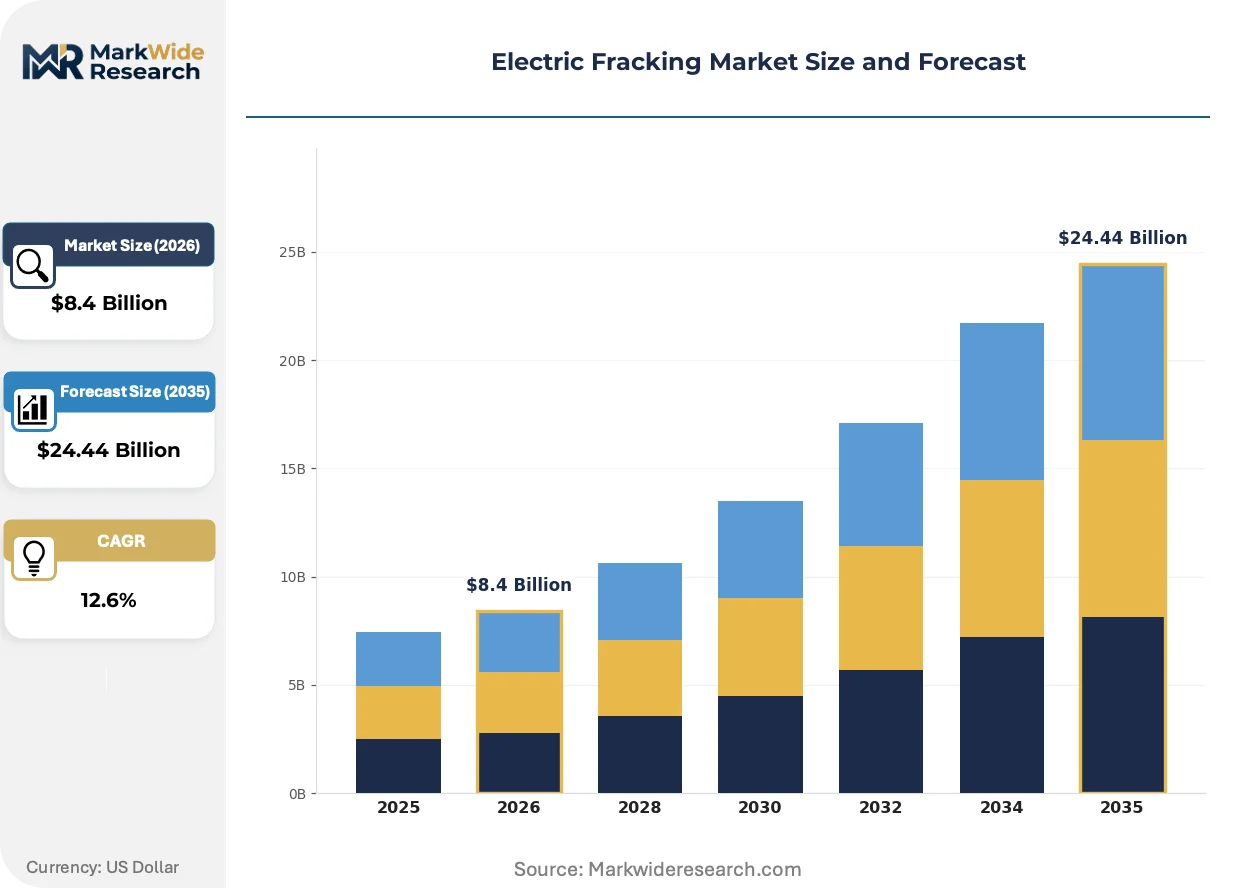
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $24.44 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Hydraulic Pumps, Power Generators, Electric Motors, Pressure Sensors Service Type: Well Stimulation, Fluid Delivery, Equipment Rental, Monitoring Services End User: Oil & Gas Companies, Independent Operators, Service Providers, Government Agencies Application: Onshore Drilling, Offshore Drilling, Tight Gas Extraction, Coalbed Methane |
| Companies Covered | Baker Hughes Company, Weatherford International plc, Liberty Energy Inc., Step Energy Services, Trican Well Service Corp., Halliburton Company, NexTier Oilfield Solutions Inc., ProFrac Holding Corp., Schlumberger Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Fracking Market Shifts & Advancements
Electric fracturing technology is absorbing capital from conventional diesel pressure pumping as emission regulations tighten and fuel economics invert. Three developments are compressing the competitive landscape for well stimulation services.
Turbine-powered electric drive systems are absorbing market share in high-horsepower applications above 2,500 hydraulic horsepower per unit. Permian Basin operators with access to field gas infrastructure are deploying these systems at accelerating rates to bypass diesel logistics entirely. The technology is absorbing the capital that would otherwise flow to Tier 4 Final diesel engine upgrades, effectively shortening the replacement cycle for conventional mechanical fleets.
OSHA combustible dust regulations and EPA regional haze rules are reshaping equipment specifications for pressure pumping operations in multiple basins. These standards mandate particulate emission controls and dust suppression systems that add cost and complexity to diesel engine maintenance. Appalachian tight gas operators are responding by accelerating gas turbine adoption to eliminate on-site combustion particulates entirely.
Service contract structures are fragmenting as operators seek to unbundle power generation from pumping services. Large independents in the Eagle Ford are negotiating turbine-only rental agreements while retaining pumping unit operatorship, reversing the traditional integrated service model. This unbundling is most visible in Texas, where grid interconnection availability and flaring economics create divergent optimal configurations across county lines.
Electric Fracking Market Segmentation
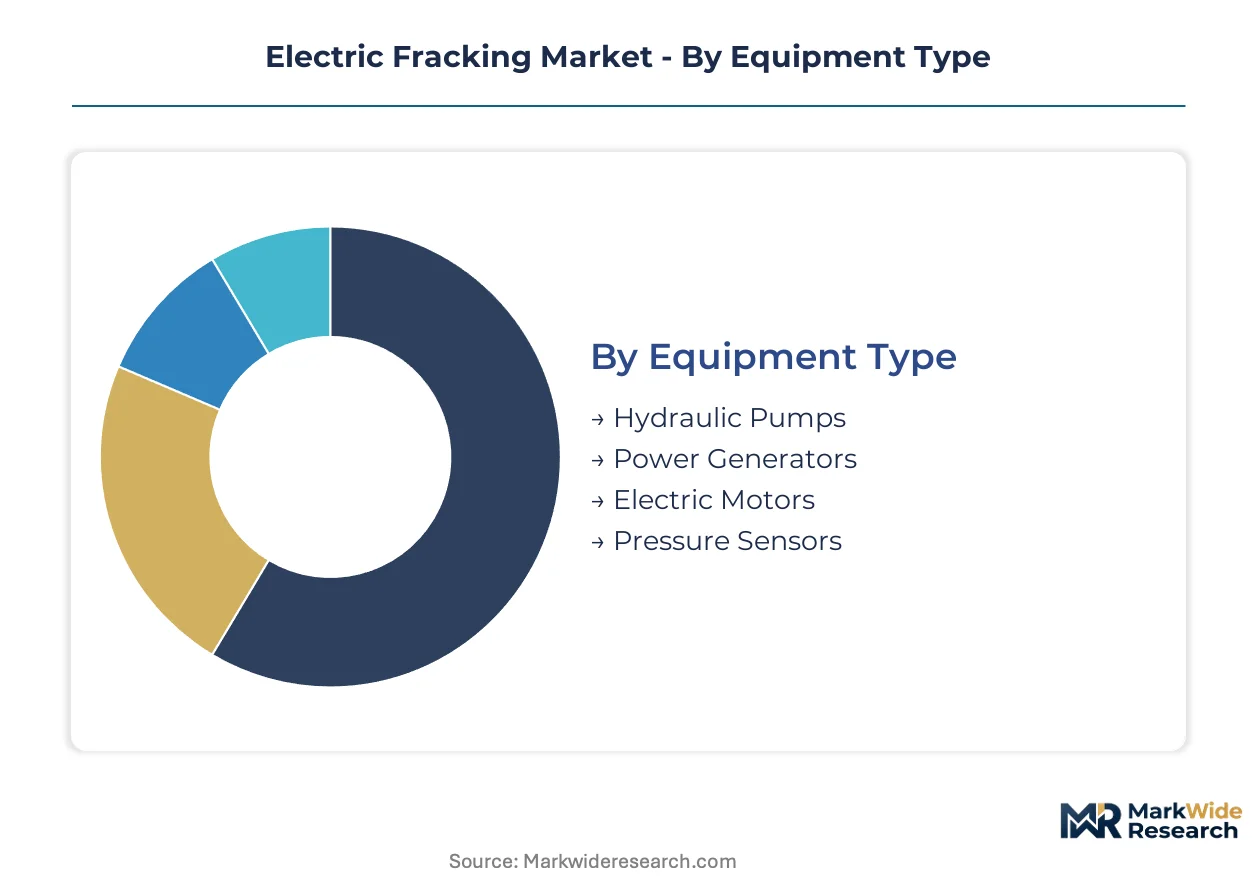
Electric fracturing equipment and services fragment across technical specifications, commercial arrangements, and regulatory exposure. Each segment carries distinct capital intensity, permitting requirements, and operational constraints that determine adoption velocity across unconventional basins.
Equipment Type:
Standardization dominates high-volume components while custom engineering persists in power delivery systems.
- Hydraulic Pumps:High-pressure reciprocating units rated for 15,000 psi continuous duty form the mechanical core of electric fracturing spreads. Permian Basin operators with multi-well pad development programs are standardizing on 2,500+ horsepower electric pump configurations to minimize unit count per site.
- Power Generators:Gas turbine and grid-tie substations convert fuel or utility electricity into fracturing-grade power. Appalachian tight gas corridors favor 25+ MW mobile turbine packages where pipeline proximity enables field gas utilization without diesel logistics.
- Electric Motors:Variable-frequency drive systems enable real-time torque modulation matched to formation-specific pump curves.
- Pressure Sensors:Downhole and surface-mounted transducers feed closed-loop control systems for fracture geometry optimization.
Most installed capacity flows through Hydraulic Pumps. Expansion is steepest in Power Generators.
Service Type:
Capital ownership preferences split the market between integrated service bundles and unbundled equipment access.
- Well Stimulation:Full-scope pressure pumping contracts bundle equipment, personnel, and consumables under per-stage or per-well pricing. Large independents in the Eagle Ford are migrating toward integrated electric fleet contracts to lock in emission compliance and fuel cost predictability.
- Equipment Rental:Standalone turbine generator and power distribution unit leasing enables variable-cost structures for operators with intermittent fracturing programs. Texas Railroad Commission flaring economics make gas-powered rental fleets attractive versus diesel ownership for marginal producers.
- Fluid Delivery:Proppant and slickwater logistics services integrate with electric pumping schedules to minimize non-productive time.
- Monitoring Services:Real-time fracture diagnostics and treatment optimization delivered via remote operations centers.
Well Stimulation commands the dominant revenue share. Equipment Rental is gaining share fastest among capital-constrained independents.
End User:
Balance sheet capacity and regulatory exposure differentiate procurement strategies across customer types.
- Oil & Gas Companies:Integrated and large independent producers with investment-grade ratings deploy owned or long-term contracted electric fleets to meet emission reduction commitments and secure offtake agreements with methane-intensity requirements.
- Independent Operators:Privately held exploration companies with limited capital access favor rental structures and third-party service contracts to preserve liquidity and avoid stranded asset risk in diesel horsepower.
- Service Providers:Pressure pumping specialists building electric fleet capacity to capture market share from conventional mechanical competitors.
- Government Agencies:State-owned petroleum enterprises in regulated basins procuring electric fracturing for emission-compliant development of public mineral estates.
Oil & Gas Companies account for the largest fleet deployment volume. Independent Operators are converting most quickly to rental-based electric access.
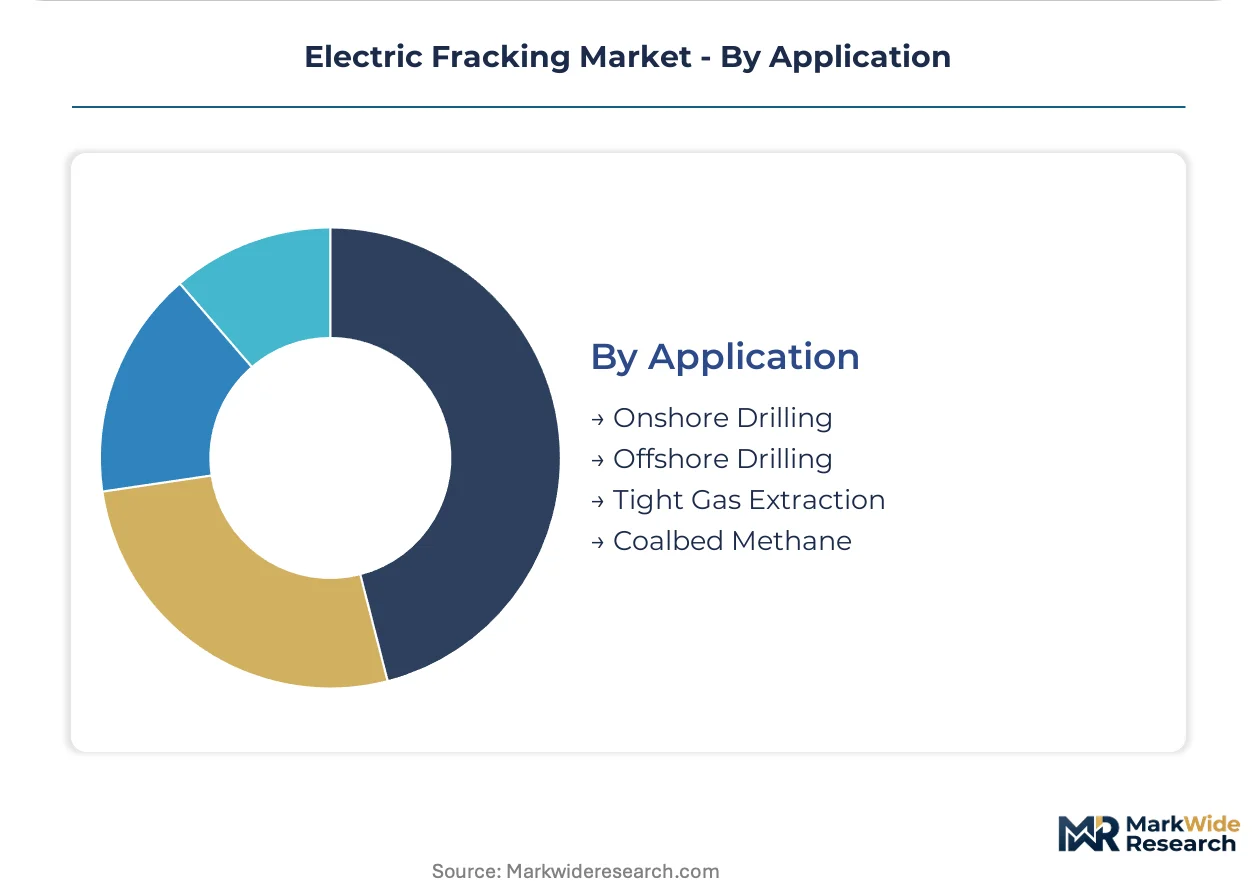
Application:
Formation characteristics and surface constraints determine power system configuration and equipment mobility requirements.
- Onshore Drilling:Multi-well pad development in Texas, New Mexico, and Colorado enables stationary electric infrastructure with grid interconnection or dedicated gas turbine installation. EPA Tier 4 Final enforcement is accelerating diesel fleet retirement in favor of electric spreads for Permian Basin horizontal completions.
- Tight Gas Extraction:Appalachian Basin Marcellus and Utica formations require high-rate, high-pressure stimulation where gas-to-wire economics support dedicated turbine generation. Colorado Air Quality Control Commission methane intensity thresholds position electric fracturing as compliance infrastructure in the Denver-Julesburg Basin.
- Offshore Drilling:Platform-based electric pumping with vessel-supplied power faces space and weight constraints distinct from land operations.
- Coalbed Methane:Lower-pressure stimulation requirements favor smaller electric pump configurations with reduced power draw.
Onshore Drilling absorbs the majority of electric fracturing capacity. Tight Gas Extraction is expanding most quickly on gas-to-wire economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between emission-intense and emission-compliant jurisdictions is redirecting fracturing investment toward basins with favorable power infrastructure and methane capture economics. Operators migrate capital where flaring restrictions and grid access compress the cost gap between diesel and electric spreads.
United States
Permian Basin multi-well pad development and Eagle Ford tight gas corridors drive turbine-powered fleet deployment. EPA Tier 4 Final standards and Texas Railroad Commission flaring rules accelerate diesel retirement. Midland-Odessa operators anchor the highest concentration of grid-tied and gas turbine electric spreads globally.
Canada
Montney and Duvernay tight gas extraction favors mobile turbine packages where pipeline proximity enables field gas utilization. Alberta Energy Regulator methane reduction targets and federal carbon pricing elevate electric fracturing economics. Calgary-based pressure pumpers are converting legacy mechanical fleets to dual-fuel turbine configurations.
Saudi Arabia
Unconventional gas development in the Jafurah Basin creates demand for high-horsepower electric stimulation. Saudi Aramco's methane intensity commitments and domestic gas-to-wire infrastructure support turbine-powered spreads. Eastern Province drilling campaigns are integrating electric pumping with captive gas generation.
China
Sichuan Basin shale gas development and Xinjiang tight oil projects absorb electric fracturing equipment under national dual carbon goals. Ministry of Ecology and Environment emission standards tighten diesel engine permitting. Chongqing and Chengdu industrial clusters host domestic turbine generator manufacturing for oilfield power applications.
Argentina
Vaca Muerta shale formation development faces diesel logistics constraints across the Neuquén Basin. Provincial environmental regulations and federal gas pricing frameworks create captive turbine economics. Neuquén Province operators are piloting gas-to-wire fracturing spreads to reduce imported fuel dependency.
Electric Fracking Market Competitive Landscape
United States-based oilfield service majors anchor one tier; Canadian and Middle Eastern specialists hold regional positions in basin-specific applications. Market structure concentrates around integrated service providers with captive turbine technology and independent pumpers pursuing rental-based electric access. Three archetypes dominate: full-scope electric fleet operators, unbundled power generator lessors, and dual-fuel transition specialists. Competitive dynamics center on fleet conversion timing and power generation partnerships that lock in fuel cost structures.
Within the integrated service tier, Halliburton Company and Baker Hughes Company exemplify the turbine-powered fleet archetype with Permian and Eagle Ford deployment scale. Liberty Energy Inc. occupies a position representing the all-electric digiFrac architecture that eliminates diesel engine maintenance cycles entirely. These three companies illustrate the strategic divergence between turbine-based and fully electric power delivery models in high-horsepower pressure pumping.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Weatherford International plc |
| Liberty Energy Inc. |
| Step Energy Services |
| Trican Well Service Corp. |
| Halliburton Company |
| NexTier Oilfield Solutions Inc. |
| ProFrac Holding Corp. |
| Schlumberger Limited |
| Others |
Supply & Pricing Matrix
Gas turbine electrification of pressure pumping spreads compresses both fuel logistics costs and supplier consolidation around turbine OEMs with field-proven 25+ MW mobile packages. This dual compression elevates pricing power for integrated service providers while squeezing margins for diesel-dependent independents facing Tier 4 Final retrofit bills.
Pricing Analysis
Direct-to-operator contracting eliminates distributor markups that historically padded diesel fleet rentals, shifting margin capture toward power generation lessors with captive turbine supply. Three-tier pricing structure across integrated electric spreads, unbundled generator rentals, and dual-fuel transition fleets reflects divergent capital intensity and emission compliance bundling. Pricing pressure stems from independent operators' liquidity constraints that favor variable-cost rental structures over ownership. Capital-constrained Appalachia producers exhibit highest price sensitivity; investment-grade Permian majors accept premium integrated contracts for fuel cost predictability.
Supply Chain Analysis
Single-source vulnerability sits with industrial gas turbine manufacturers in the United States and Germany that dominate 25+ MW mobile power packages for fracturing applications. High-pressure reciprocating pump forgings draw from specialty steel mills in Japan and South Korea, while variable-frequency drive systems rest on power electronics fabrication concentrated in China and Taiwan. Tariff exposure on Chinese electrical components threatens cost structures for domestic fleet assemblers. Distribution runs through oilfield service majors with direct operator relationships, bypassing traditional equipment distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric fracturing margins expand through fuel cost arbitrage that locks in gas-based power economics against diesel volatility, while premium-tier integrated contracts capture compliance bundling value.
For Market Incumbents: Extend turbine-powered fleet deployments in the Permian Basin to exhaust field gas utilization economics before dual-fuel competitors replicate the model. Secure long-term gas supply agreements with midstream operators to defend against stranded gas pipeline competition. Anchor position through backward integration into power electronics assembly, reducing exposure to Chinese component tariffs that threaten margin stability. For New Entrants and Emerging Players: Capital-constrained Eagle Ford independents represent the most penetrable buyer archetype, with intermittent fracturing programs that reject capital-intensive fleet ownership in favor of rental-based electric access. Equipment rental channels for mobile turbine generators offer white-space entry with lower balance sheet requirements than full-scope stimulation services. Target go-to-market angle emphasizes per-stage pricing transparency that eliminates diesel fuel surcharge complexity. For Investors and Strategic Acquirers: Valuations sit cheapest among conventional diesel pressure pumpers facing accelerated depreciation under EPA Tier 4 Final enforcement. Long-term viability favors integrated service providers with captive turbine technology and grid interconnection capabilities over pure-play pumping specialists. Watch Texas Railroad Commission flaring rule tightening as the inflection signal that collapses residual values in diesel horsepower and triggers consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Turbine Fleet Deployment | Permian Basin operators bypass diesel logistics entirely through field gas-powered 25+ MW spreads. |
| Power Generation Partnership | Long-term gas supply agreements with midstream providers lock in fuel cost structures against volatility. |
| Equipment Rental Channel Buildout | Variable-cost turbine access captures capital-constrained independents avoiding fleet ownership. |
| Grid Interconnection Investment | Texas utility agreements enable electric spreads in counties with transmission capacity surplus. |
| Fuel Cell Technology Pilot | Solid oxide systems position for Colorado methane intensity thresholds that may restrict combustion turbines. |
Research Methodology
Coverage spans the United States, Canada, Saudi Arabia, China, and Argentina, with primary inputs from each market cluster combining interviews with pressure pumping operations directors, E&P procurement executives, turbine OEM technical sales leads, and regulatory compliance officers at state environmental agencies. Secondary validation draws from EPA enforcement databases, Texas Railroad Commission flaring compliance records, EIA drilling productivity reports, and FERC interconnection filings. Bottom-up fleet deployment counts triangulate against top-down service revenue estimates across the analysis window.
Rate-of-change decomposition separates volume effects from price-mix shifts across equipment type, service arrangement, end-user balance sheet capacity, and application formation characteristics. Modeled segmentation spans power delivery architecture, commercial bundling structure, operator credit profile, and basin-specific regulatory framework. CAGRs derive from trend extrapolation of fleet conversion rates constrained by grid interconnection bottlenecks and turbine manufacturing lead times. Forecast inputs incorporate EPA Tier 4 Final enforcement timelines and state methane intensity threshold trajectories without year-specific calibration.
Underlying measurement precision varies by segment; well stimulation contract values carry tighter precision than equipment rental utilization rates where informal spot arrangements predominate. Forecasts reflect assumptions around regulatory enforcement consistency and gas pipeline infrastructure expansion that could revise trajectory materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Global Artificial Lift Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Indonesia Oil and Gas Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Asia-Pacific Oil Country Tubular Goods Market
Oil & Gas
Oilfield Services Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Crown Block Market
Oil & Gas
South America Oil and Gas Hoses and Coupling Market
Oil & Gas
LNG Storage Tank Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Geothermal Drill Bits Market
Oil & Gas
Offshore Oil and Gas Paints and Coatings Market
Oil & Gas
Coal Mining Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market