
 Digital Twin in Oil and Gas Market | 2026-2036
Digital Twin in Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Twin in Oil and Gas Market Outlook
Upstream exploration companies are unwinding their historical reliance on reactive maintenance budgets in favor of predictive digital infrastructure. Honeywell International Inc. leverages its process automation heritage to anchor digital twin deployments across downstream refineries. Microsoft Corporation competes through Azure cloud architecture that sustains real-time reservoir simulation workloads. Siemens Energy specializes in turbomachinery-specific twin models that dominate rotating equipment monitoring.
A digital twin in oil and gas constitutes a dynamic virtual replica of physical assets, processes, or systems that integrates real-time sensor data, physics-based modeling, and machine learning algorithms to mirror operational behavior. The technology fuses IoT telemetry streams with computational fluid dynamics to enable condition-based intervention across drilling, production, and distribution networks. Cloud-based deployment architectures now lead investment flows as majors consolidate fragmented on-premises legacy systems into unified data lakes. Predictive maintenance applications command the deepest margin pools due to quantifiable downtime avoidance, while operational optimization segments show the fastest adoption velocity among independent producers seeking production uplift.
The EPA enforces methane monitoring mandates under revised Clean Air Act protocols that compel operators to deploy continuous emissions surveillance tied to digital twin platforms. API RP 1173 pipeline safety management standards and evolving BSEE offshore facility rules further harden data integrity requirements for virtual asset models. Stakeholders must weigh capital allocation between retrofitting brownfield infrastructure with edge computing layers versus greenfield cloud-native architectures as regulatory compliance windows tighten.
Market Dynamics
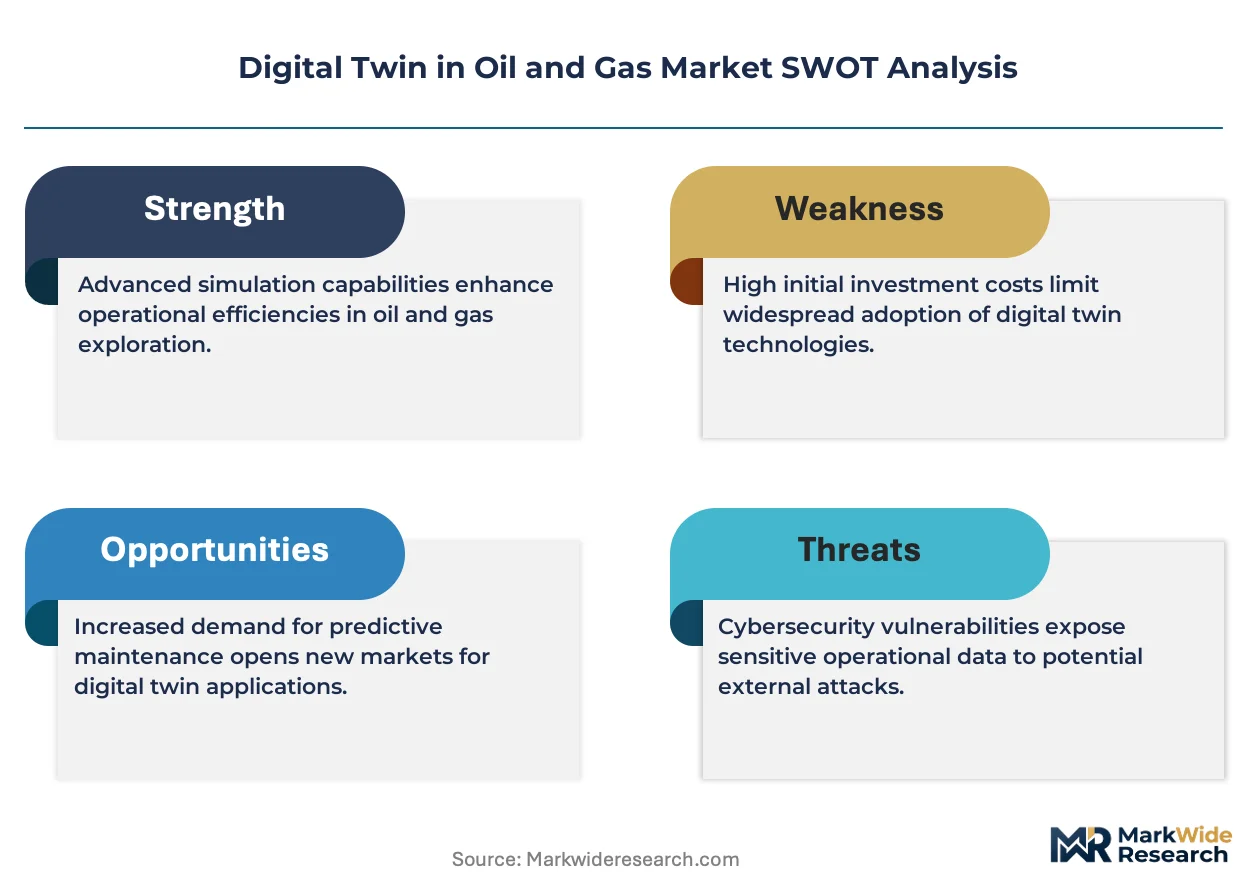
The upstream oil and gas sector confronts a structural pivot from reactive maintenance toward predictive infrastructure, driven by EPA methane surveillance mandates that tie operational licenses to continuous emissions monitoring integrated with virtual asset platforms.
Growth Catalysts
- EPA Clean Air Act Enforcement:Revised methane protocols compel operators to deploy continuous emissions surveillance systems linked to digital twin platforms, hardening compliance-driven procurement across US Gulf Coast production corridors.
- Subsea Asset Monitoring Expansion:Offshore production operators accelerate virtual replica deployments for subsea infrastructure, leveraging physics-based modeling to compress intervention timelines for deepwater risers and manifolds.
- Cloud-Native Architecture Consolidation:Majors dismantle fragmented on-premises legacy systems in favor of unified data lakes, redirecting capital toward Azure and AWS architectures that sustain real-time reservoir simulation workloads.
Market Restraints
- Legacy System Integration Friction:Brownfield facilities face prohibitive retrofit costs for edge computing layers, with decades-old SCADA architectures resisting seamless telemetry fusion with modern twin platforms.
- Specialized Talent Scarcity:Computational fluid dynamics expertise and IoT systems engineering talent concentrates in Houston and Aberdeen, constraining deployment velocity for operators outside these clusters.
- Cybersecurity Surface Expansion:Real-time sensor data streams multiply attack vectors for critical infrastructure, with BSEE offshore facility rules intensifying liability exposure for inadequately secured virtual models.
Strategic Opportunities
- Carbon Capture Integration:Digital twin platforms extend into CCUS project lifecycle management, with virtual replicas optimizing injection well placement and plume migration prediction for saline aquifer storage.
- Independent Producer Segment:Mid-tier Permian and Bakken operators represent underpenetrated demand for production uplift applications, bypassing integrated majors' proprietary systems through SaaS twin deployments.
- API Standards Harmonization:RP 1173 pipeline safety management standards create vendor-agnostic data frameworks, reducing switching costs and opening procurement to specialized turbomonitoring specialists.
Industry Challenges
- Physics-to-ML Model Calibration:Bridging first-principles engineering models with machine learning inference demands rare cross-functional expertise in thermodynamics and neural network architecture, elongating deployment timelines.
- Data Sovereignty Fragmentation:Divergent national cloud residency requirements across Norway, Brazil, and Australia force operators to maintain redundant twin instances, inflating operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Twin in Oil and Gas Market |
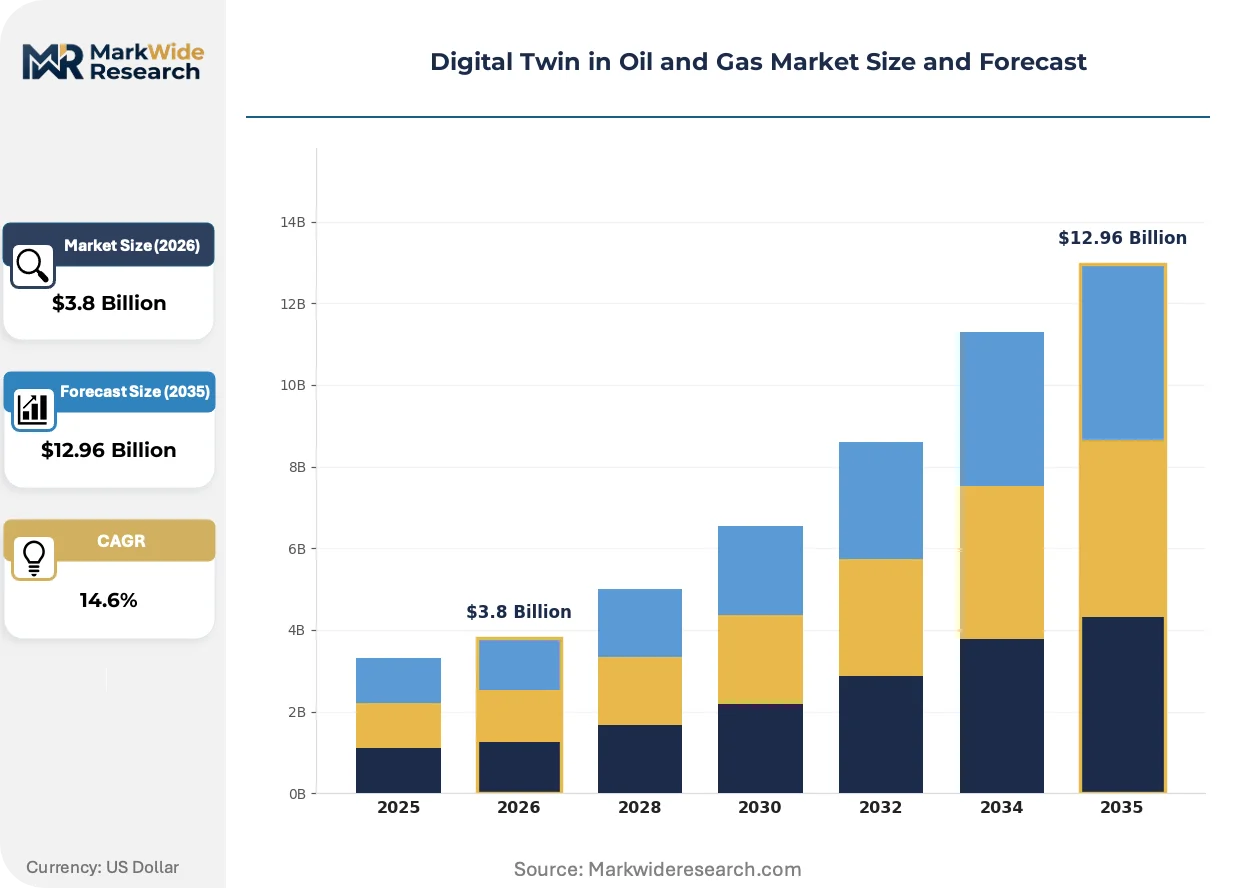
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud-Based, Edge Computing, IoT, Artificial Intelligence Application: Predictive Maintenance, Asset Management, Simulation, Operational Optimization Deployment: On-Premises, Cloud, Hybrid, Remote End User: Exploration Companies, Production Firms, Service Providers, Consulting Firms |
| Companies Covered | Honeywell International Inc., Microsoft Corporation, AVEVA Group Limited, Schneider Electric, IBM, Emerson Electric Co., Siemens Energy, GE, Halliburton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Twin in Oil and Gas Market Strategic Shifts
Edge computing hardware is miniaturizing sensor fusion capabilities, compressing latency between physical asset and virtual replica while expanding deployable environments beyond controlled facility settings into remote wellpads and offshore platforms.
Computational fluid dynamics simulation is miniaturizing onto GPU-accelerated edge nodes, enabling real-time flow assurance modeling at the wellhead without round-trip latency to centralized cloud infrastructure. Independent shale operators in the Permian Basin adopt these compacted simulation units fastest, trimming days from artificial lift optimization cycles. The compression of physics computation onto ruggedized field hardware is displacing dependency on high-bandwidth fiber links to regional data centers.
EU CSRD sustainability reporting standards now mandate granular emissions disclosure for oil and gas majors operating within European waters or selling into EU markets, forcing twin platform enhancements to capture Scope 3 methane leakage across supply chains. This regulatory pressure cascades into API standard revisions for US-based exporters seeking European offtake agreements. Offshore facilities in the North Sea face the steepest compliance timelines, accelerating vendor selection for integrated emissions-operations twin suites.
Buying committees now unbundle predictive maintenance software from captive equipment OEM service contracts, shifting procurement toward standalone analytics platforms with API-accessible physics engines. Integrated majors consolidate vendor relationships through direct cloud marketplace procurement, bypassing traditional systems integrator markups. This disintermediation concentrates in the US Gulf Coast corridor where operator IT procurement functions retain deepest technical staffing.
Digital Twin in Oil and Gas Market Segmentation
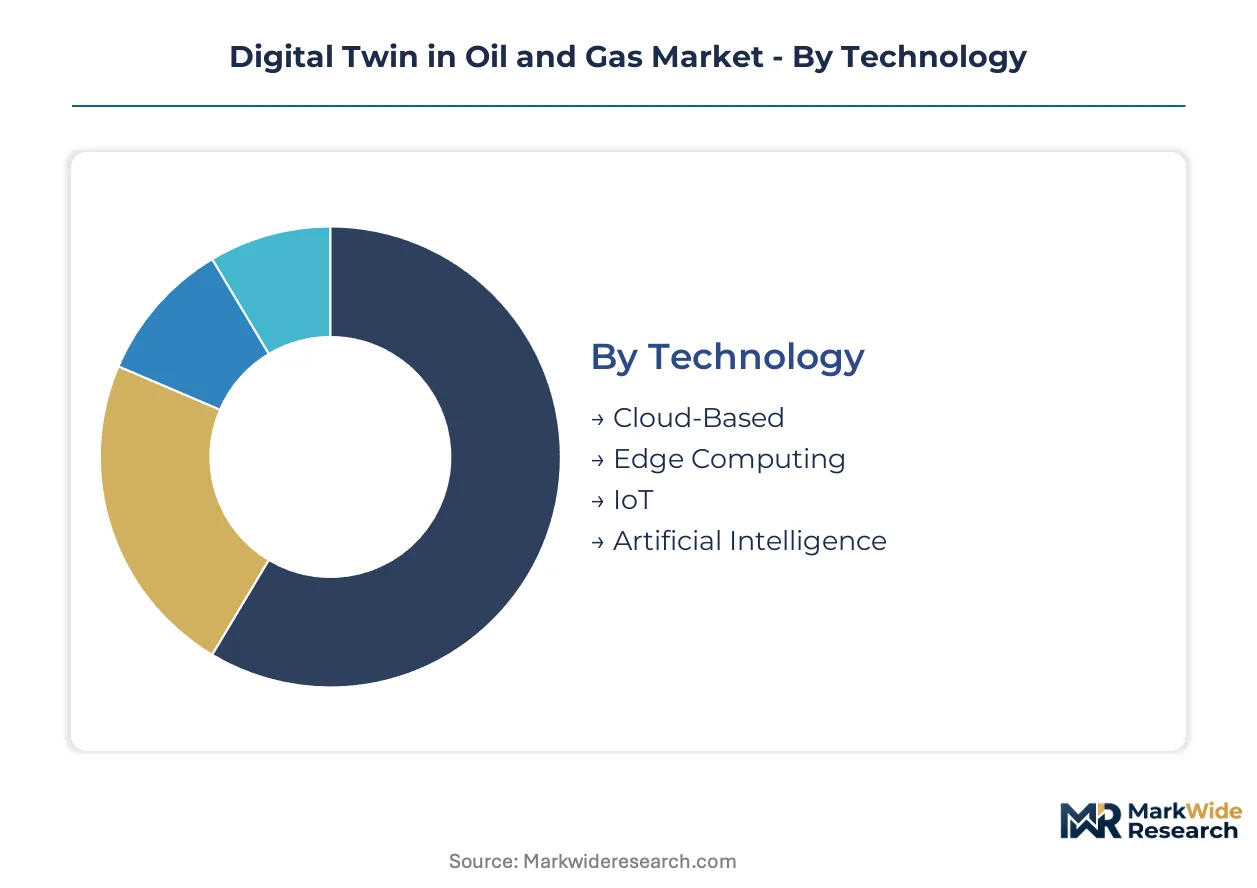
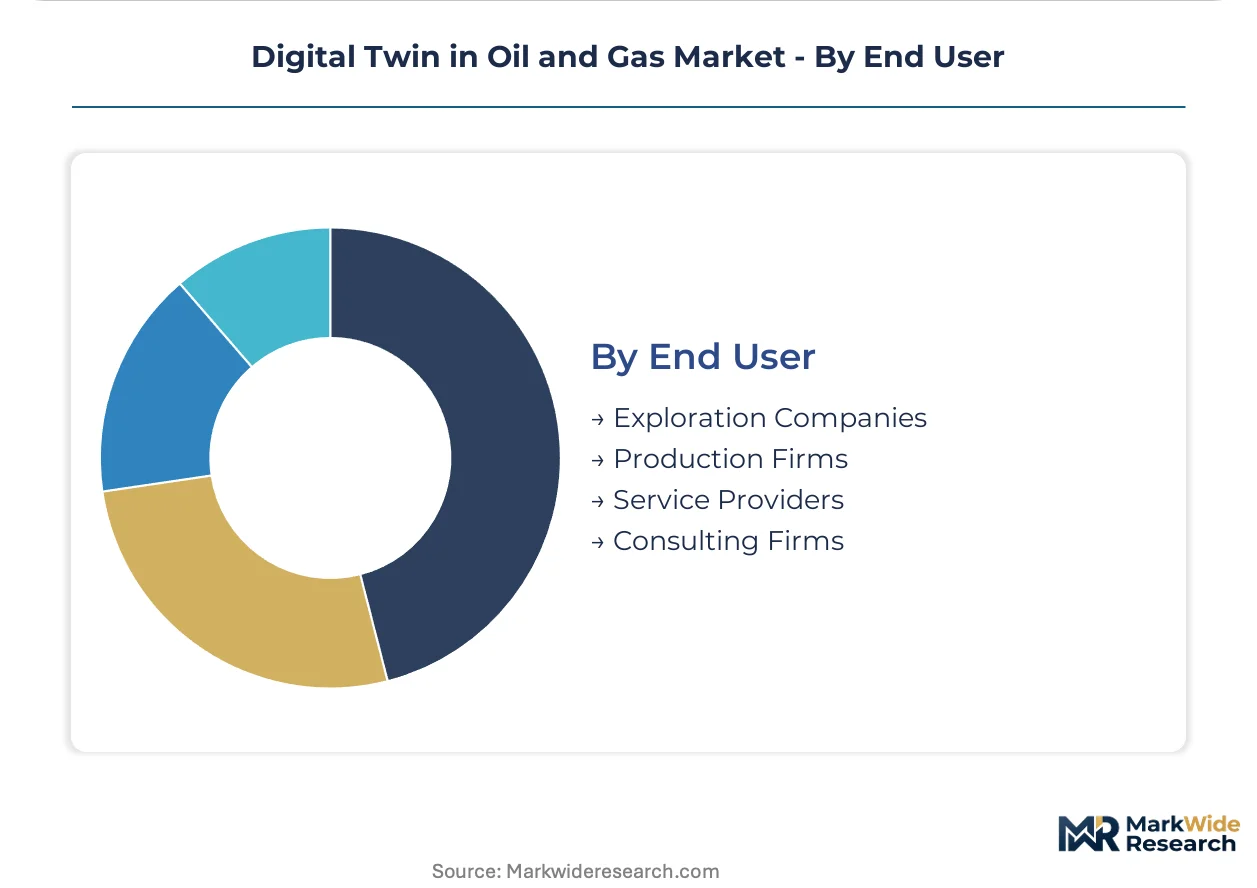
Digital twin architectures fragment across deployment topologies, processing layers, and operational use cases. Each segmentation dimension carries distinct regulatory compliance burdens and capital intensity profiles that shape procurement patterns among upstream and downstream operators.
Technology:
EPA methane surveillance mandates and BSEE offshore facility rules differentiate technology selection based on data residency requirements and real-time processing thresholds.
- Cloud-Based:Unified data lake architectures consolidate fragmented legacy systems, with Azure and AWS sustaining reservoir simulation workloads for majors dismantling on-premises infrastructure. Gulf Coast operators favor this tier for centralized emissions reporting to EPA.
- Edge Computing:GPU-accelerated ruggedized nodes compress physics computation latency for wellhead flow assurance modeling. Permian Basin shale operators deploy these fastest to trim artificial lift optimization cycles without fiber dependency.
- IoT:Sensor fusion hardware miniaturization expands deployable environments into remote wellpads and subsea manifolds.
- Artificial Intelligence:Neural network inference layers bridge first-principles thermodynamics with operational predictions, demanding scarce cross-functional expertise.
Cloud-based deployments handle the majority of throughput; edge computing is the fastest mover on share as latency-sensitive applications proliferate.
Application:
Margin pools concentrate where quantifiable downtime avoidance meets production uplift potential, with independent producers prioritizing operational velocity over integrated majors' maintenance depth.
- Predictive Maintenance:Condition-based intervention systems command the deepest margin pools through quantifiable avoidance of unplanned downtime across rotating equipment and subsea infrastructure. API RP 1173 pipeline safety standards harden data integrity requirements for these deployments.
- Operational Optimization:Production uplift applications show the steepest expansion trajectory among independent Permian and Bakken operators seeking SaaS twin deployments without proprietary system investments.
- Asset Management:Virtual replica lifecycle tracking spans drilling, completion, and abandonment phases for capital-intensive subsea developments.
- Simulation:Computational fluid dynamics modeling enables injection well placement and plume migration prediction for CCUS project integration.
Predictive maintenance captures the largest revenue concentration; operational optimization climbs fastest as mid-tier operators accelerate SaaS procurement.
Deployment:
Capital allocation tensions between brownfield retrofit costs and greenfield cloud-native architectures intensify as regulatory compliance windows tighten.
- Hybrid:Architectures blending on-premises SCADA layers with cloud analytics dominate brownfield facility upgrades, balancing legacy system preservation against unified data lake consolidation.
- Cloud:Native deployments lead greenfield investment flows, particularly among majors consolidating vendor relationships through direct marketplace procurement bypassing systems integrator markups.
- On-Premises:Fragmented legacy architectures persist where data sovereignty requirements or air-gapped security protocols constrain external connectivity.
- Remote:Satellite-linked deployments serve offshore platforms and remote wellpads beyond fiber infrastructure reach.
Hybrid architectures carry the dominant installed base; cloud deployments expand most quickly as majors dismantle legacy fragmentation.
End User:
Procurement sophistication varies sharply across operator scale, with integrated majors consolidating vendor relationships while independents seek unbundled analytics platforms.
- Production Firms:Downstream refineries and upstream operators anchor digital twin investment, with Honeywell process automation heritage penetrating refinery deployments and turbomachinery monitoring dominating rotating equipment surveillance.
- Exploration Companies:Unwinding reactive maintenance budgets in favor of predictive infrastructure, these operators prioritize reservoir simulation integration with seismic interpretation workflows.
- Service Providers:Equipment OEMs face disintermediation pressure as buying committees unbundle predictive maintenance software from captive service contracts.
- Consulting Firms:Systems integrators confront margin compression as direct cloud marketplace procurement concentrates in technically staffed Gulf Coast operator IT functions.
Production firms command the dominant spend share; exploration companies gain adoption velocity fastest as they pivot from reactive maintenance paradigms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast pipeline corridor and offshore platform network anchors the United States' primacy in digital twin deployment. Subsea fiber infrastructure connecting North Sea platforms to Aberdeen data centers underwrites European adoption velocity.
United States
EPA methane surveillance mandates under the Clean Air Act compel Permian Basin operators to deploy continuous emissions monitoring tied to virtual asset platforms. Gulf Coast refineries consolidate vendor relationships through direct Azure and AWS procurement, bypassing systems integrator markups. Houston anchors the deepest concentration of computational fluid dynamics and IoT systems engineering talent.
Norway
North Sea offshore facilities face accelerated compliance timelines under EU CSRD sustainability reporting standards mandating granular emissions disclosure. The Norwegian Petroleum Directorate enforces data residency requirements that force operators to maintain sovereign twin instances. Stavanger and Bergen clusters specialize in subsea asset monitoring for deepwater riser and manifold infrastructure.
Saudi Arabia
Aramco's master gas system and associated pipeline network drives predictive infrastructure investment across upstream and downstream assets. The Saudi Standards, Metrology and Quality Organization (SASO) aligns with API RP 1173 pipeline safety frameworks for virtual model data integrity. Dhahran and Jubail industrial cities concentrate turbomachinery monitoring deployments for rotating equipment surveillance.
Brazil
Pre-salt deepwater production expansion accelerates virtual replica deployment for subsea intervention timeline compression. The Brazilian National Petroleum Agency (ANP) mandates enhanced operational safety reporting for offshore facilities. Rio de Janeiro's technology corridor hosts specialized physics-to-ML calibration expertise for reservoir simulation integration.
United Kingdom
North Sea decommissioning liabilities and remaining production optimization drive asset lifecycle management twin adoption. The Health and Safety Executive (HSE) offshore facility rules harden cybersecurity requirements for virtual models. Aberdeen's engineering cluster sustains vendor-agnostic procurement patterns as buying committees unbundle predictive maintenance from captive OEM contracts.
Digital Twin in Oil and Gas Market Competitive Environment
Listed leaders compete with private specialists across cloud architecture and edge computing dimensions, creating a tiered structure where scale advantages concentrate in platform providers while domain expertise fragments among equipment-specific modelers. Process automation heritage anchors refinery deployment penetration. Turbomachinery specialization dominates rotating equipment surveillance. Strategic moves center on cloud marketplace consolidation and physics engine API accessibility.
Within the platform-provider tier, Microsoft Corporation exemplifies cloud-native architecture dominance through Azure deployments sustaining real-time reservoir simulation workloads. Honeywell International Inc. occupies a position anchored in process automation heritage across downstream refinery implementations. Siemens Energy represents turbomachinery-specific twin modeling specialization for rotating equipment monitoring applications.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Microsoft Corporation |
| AVEVA Group Limited |
| Schneider Electric |
| IBM |
| Emerson Electric Co. |
| Siemens Energy |
| GE |
| Halliburton |
| Others |
Value Chain & Pricing Dynamics
Long-term SaaS subscription contracts with embedded capacity reservations lock in supply access for digital twin platform providers while anchoring price visibility for Permian Basin operators navigating EPA compliance windows. These multi-year arrangements bundle edge computing hardware with cloud analytics tiers, compressing procurement cycles as independent producers bypass fragmented legacy system upgrades.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise, mid-market, and independent operator levels, with API RP 1173 certification compliance commanding premium positioning. Three-tier pricing separates fully-integrated predictive maintenance suites from modular operational optimization tools and basic asset monitoring dashboards. Cost compression in the mid-market tier is intensifying because Azure and AWS marketplace procurement disintermediates systems integrator markups. Independent shale operators in the Permian and Bakken formations exhibit the sharpest price sensitivity, while integrated majors absorbing Gulf Coast refinery deployments show the least.
Supply Chain Analysis
The United States and Norway anchor GPU-accelerated edge node manufacturing for ruggedized field deployments, while Taiwan feeds semiconductor components for sensor fusion hardware. Supply chains draw from rare earth elements for magnet assemblies in subsea monitoring equipment, high-purity silicon for edge computing chips, and specialized composites for deepwater riser instrumentation. Single-source vulnerability concentrates in Taiwan's foundry capacity for AI inference accelerators. Distribution runs through direct cloud marketplace procurement channels that bypass traditional systems integrator networks, concentrating in Houston and Aberdeen engineering clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern tied to upstream capital expenditure cycles, with EPA methane enforcement deadlines compressing procurement timelines into compliance-driven waves.
For Market Incumbents: Consolidate vendor relationships through direct cloud marketplace positioning to defend against SaaS-native entrants unbundling predictive maintenance from captive OEM service contracts. Prioritize backward integration into edge computing hardware manufacturing to capture margin pools migrating from software licensing toward ruggedized field deployments. API standards harmonization represents the critical lever for reducing customer switching costs and locking in platform stickiness. For New Entrants and Emerging Players: Differentiate on physics-to-ML calibration expertise for reservoir simulation integration, targeting the underpenetrated mid-tier Permian and Bakken independent producer segment with lightweight SaaS twin deployments. Carbon capture integration for CCUS project lifecycle management offers the most penetrable white-space application. Lead with satellite-linked remote deployment capabilities for offshore platforms beyond fiber infrastructure reach. For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors specialized turbomonitoring firms with proven BSEE offshore facility compliance track records. Long-term viability hinges on regulatory enforcement durability rather than commodity price cycles, positioning EPA and EU CSRD mandate expansion as the structural demand anchor. Watch for inflection signals in API RP 1173 revision timelines that would accelerate brownfield retrofit procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Consolidation | Majors dismantle fragmented on-premises SCADA architectures into unified Azure and AWS data lakes for EPA emissions reporting. |
| Edge Computing Hardware Miniaturization | GPU-accelerated ruggedized nodes compress physics computation latency for wellhead flow assurance without fiber dependency. |
| Carbon Capture Integration Development | Virtual replicas optimize injection well placement and plume migration prediction for saline aquifer CCUS storage projects. |
| API Standards Harmonization | RP 1173 pipeline safety frameworks create vendor-agnostic data architectures reducing procurement switching costs. |
| Direct Marketplace Procurement | Gulf Coast operators bypass systems integrator markups through Azure and AWS cloud marketplace vendor relationships. |
Study Parameters
The analysis maps cloud-based deployments, edge computing architectures, IoT sensor networks, and AI inference layers, each validated through primary interviews with digital twin platform engineers, EPA compliance officers at upstream operators, turbomachinery maintenance directors, and cloud marketplace procurement leads. Secondary validation draws from BSEE offshore facility rule filings, API RP 1173 documentation, EPA Clean Air Act enforcement records, and hyperscaler capex disclosures. Bottom-up segment sizing triangulates against top-down market boundary estimates from regulatory mandate coverage analysis.
Consistency checks validate volume and value outputs against external benchmarks including cloud infrastructure spending patterns across the analysis window and edge computing hardware shipment trajectories. The analytical framework models deployment topology, processing layer, operational use case, and operator scale segmentation dimensions. CAGRs derive from regression analysis of historical platform adoption curves adjusted for regulatory compliance deadline clustering. Forecast inputs incorporate physics-to-ML model deployment timelines and subsea asset monitoring penetration rates.
Material uncertainties — EPA enforcement intensity variation, EU CSRD implementation delays, and legacy SCADA integration failure rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained methane surveillance mandate durability and cloud residency requirement fragmentation across Norway, Brazil, and Australia. Recalibration cycles align with material shifts in BSEE offshore facility rule revisions and API standards update schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
LNG Loading Skid Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
North America Shale Market
Oil & Gas
Upstream Services Market
Oil & Gas
Intelligent Pigging Services Market
Oil & Gas
Oil Storage Terminal Market
Oil & Gas
FTIR Oil Condition Monitoring Market
Oil & Gas
United States Oil and Gas Midstream Market
Oil & Gas
North America Oil and Gas Storage Tank Market
Oil & Gas
Middle East and Africa Digital Oilfield Market
Oil & Gas
North America Hydraulic Fracturing Fluids Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Well Completion Equipment Service Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market