
 Gabon Oil and Gas Market | 2026-2036
Gabon Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Gabon Oil and Gas Market Foresight
Offshore logistics corridors around Port-Gentil is reconfiguring how crude moves from Gamba basin fields to export terminals. TotalEnergies leverages its pre-existing deepwater infrastructure to sustain production at Anguille and Torpille complexes. Perenco anchors the mature onshore portfolio through rehabilitation of legacy Rabi-Kounga assets. VAALCO Energy competes at Etame Marin, where subsea tiebacks differentiate its cost structure against larger integrated rivals.
Gabon oil and gas encompasses hydrocarbon extraction from offshore and onshore sedimentary basins, with crude typically ranging from API gravities of 30 to 35 degrees and sulfur content below 0.5 percent, serving primarily as feedstock for refining and export to Atlantic basin buyers. Crude oil output dominates the product mix, though natural gas processing for power generation represents the fastest-growing end-use segment as domestic electrification expands. Exploration technology commands disproportionate capital allocation, with 3D seismic and deepwater drilling shaping frontier access off the southern coast near Mayumba.
Gabon's national petroleum regulator and the central environmental authority enforce offshore safety standards and environmental impact assessments for drilling campaigns, while production-sharing contracts now incorporate stricter local content provisions. The country's national oil company participates directly in joint ventures, altering how international operators structure equity and operational control. Stakeholders must monitor fiscal term negotiations and infrastructure access priorities as the government seeks to maximize retained value from declining reserve bases.
Market Dynamics
Revised production-sharing contract frameworks are redistributing economic rents between Gabon's national oil company and international operators, forcing equity restructurings across mature and frontier blocks alike. This contractual evolution sits at the center of how capital now flows into the Gamba-Ivinga basin complex.
Growth Catalysts
- Deepwater drilling technology:Subsea tieback systems unlock stranded reserves in the Etame Marin and southern Mayumba blocks. Operators deploy 3D seismic to reduce dry-hole risk.
- Domestic electrification mandates:Gabon's power generation expansion drives natural gas processing infrastructure. Associated gas capture becomes economically viable where flaring penalties tighten.
- Port-Gentil logistics corridors:Offshore supply base consolidation reduces vessel turnaround times. Export terminal capacity expansions accommodate heavier crude liftings.
Market Restraints
- Reserve base maturity:Rabi-Kounga and Anguille fields face natural decline curves. Brownfield rehabilitation costs exceed greenfield exploration economics at current price bands.
- Local content thresholds:Stricter domestic employment and procurement quotas embedded in revised production-sharing contracts inflate operational overhead for non-integrated operators.
- Atlantic basin refining margins:European demand compression for medium-sweet crudes narrows export market options. Freight rate volatility amplifies netback uncertainty.
Strategic Opportunities
- Mayumba ultra-deepwater frontier:Unexplored southern coastal blocks host untested Cretaceous plays. Licensing rounds target pre-salt analogues at water depths exceeding 1,500 meters.
- Gas-to-power integration:Captive generation for mining and industrial clusters creates anchor demand. Pipeline infrastructure monetizes historically flared associated gas.
- Environmental impact assessment streamlining:Central environmental authority pilot programs compress permitting timelines for low-risk development drilling. Early-mover operators secure rig slotting advantages.
Industry Challenges
- Subsea engineering talent scarcity:Deepwater completion expertise concentrates with a narrow contractor base. Training pipelines fail to match field development schedules.
- Legacy facility integrity management:Aging platforms at Torpille and Grondin require structural reassessment. Decommissioning liability provisioning strains balance sheets.
- Joint venture governance friction:Divergent capital allocation priorities between Gabon's national oil company and minority equity holders delay field investment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gabon Oil and Gas Market |
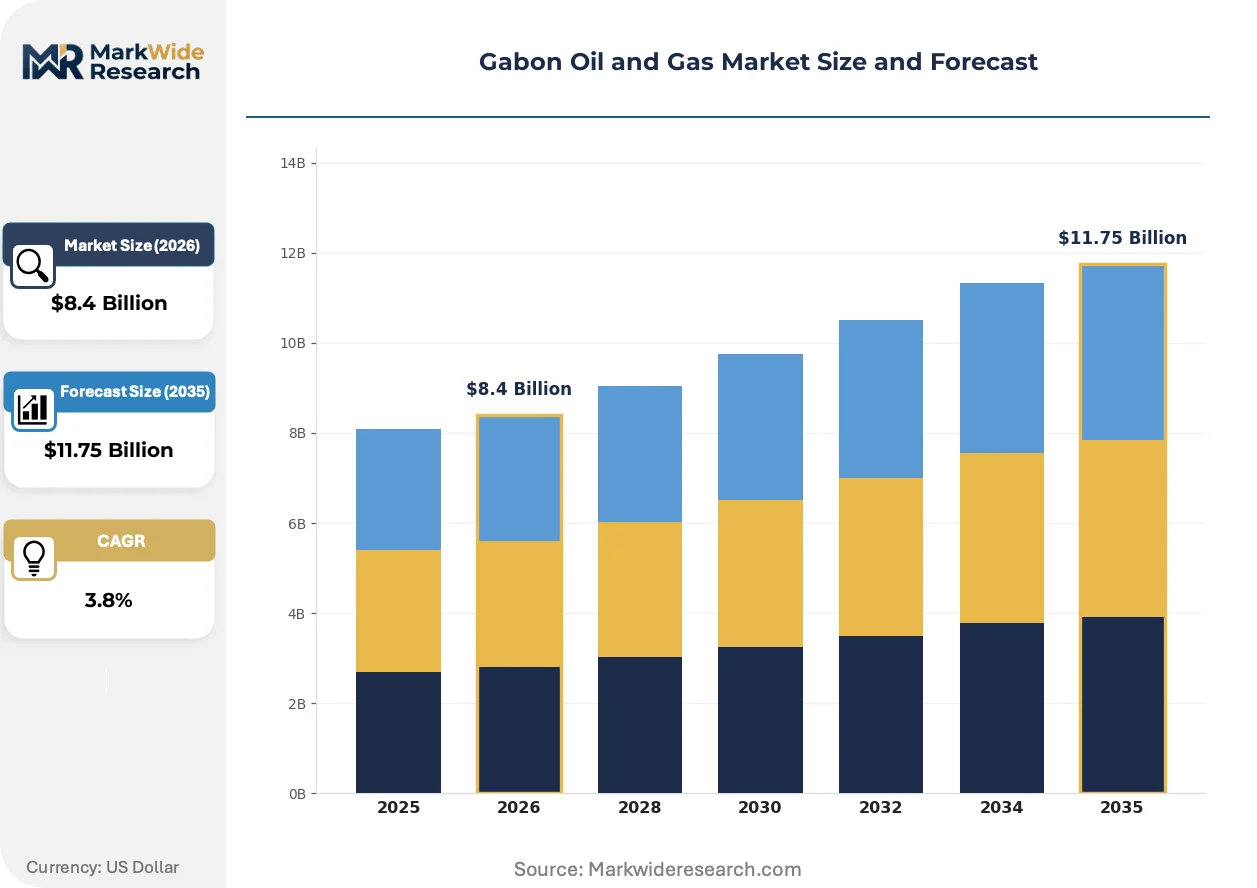
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $11.75 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, LNG, LPG End User: Refineries, Power Plants, Petrochemical Companies, Exporters Technology: Exploration, Drilling, Production, Refining Service Type: Drilling Services, Maintenance, Logistics, Engineering |
| Companies Covered | TotalEnergies, Perenco, Gabon Oil Company, Eni, Maurel et Prom, VAALCO Energy, Assala Energy, Addax Petroleum, Petronas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gabon Oil and Gas Market Shifts & Advancements
Digital reservoir characterization and modular processing architectures are compressing project development cycles across Gabon's offshore portfolio. These shifts alter how operators sequence exploration, appraisal, and production phases.
4D seismic monitoring is collapsing the uncertainty window between initial production and recovery factor optimization. Independent operators at marginal fields deploy permanent seabed sensors to track fluid movement in real time. This capability is collapsing the economic threshold for tertiary recovery investments at mature Gamba basin assets.
Gabon's national petroleum regulator now mandates digital submission of drilling permits through centralized environmental tracking platforms. This policy compresses approval timelines for campaigns with established baseline data. Smaller operators lacking legacy documentation face disproportionate compliance burdens relative to integrated majors with pre-existing environmental databases.
Buyers in Atlantic basin refining markets now preference term contracts with certified low-carbon intensity crudes. Gabonese operators respond by quantifying methane emissions across supply chains and securing third-party verification. European end-users drive this shift through carbon border adjustment mechanisms affecting import eligibility.
Gabon Oil and Gas Market Segmentation
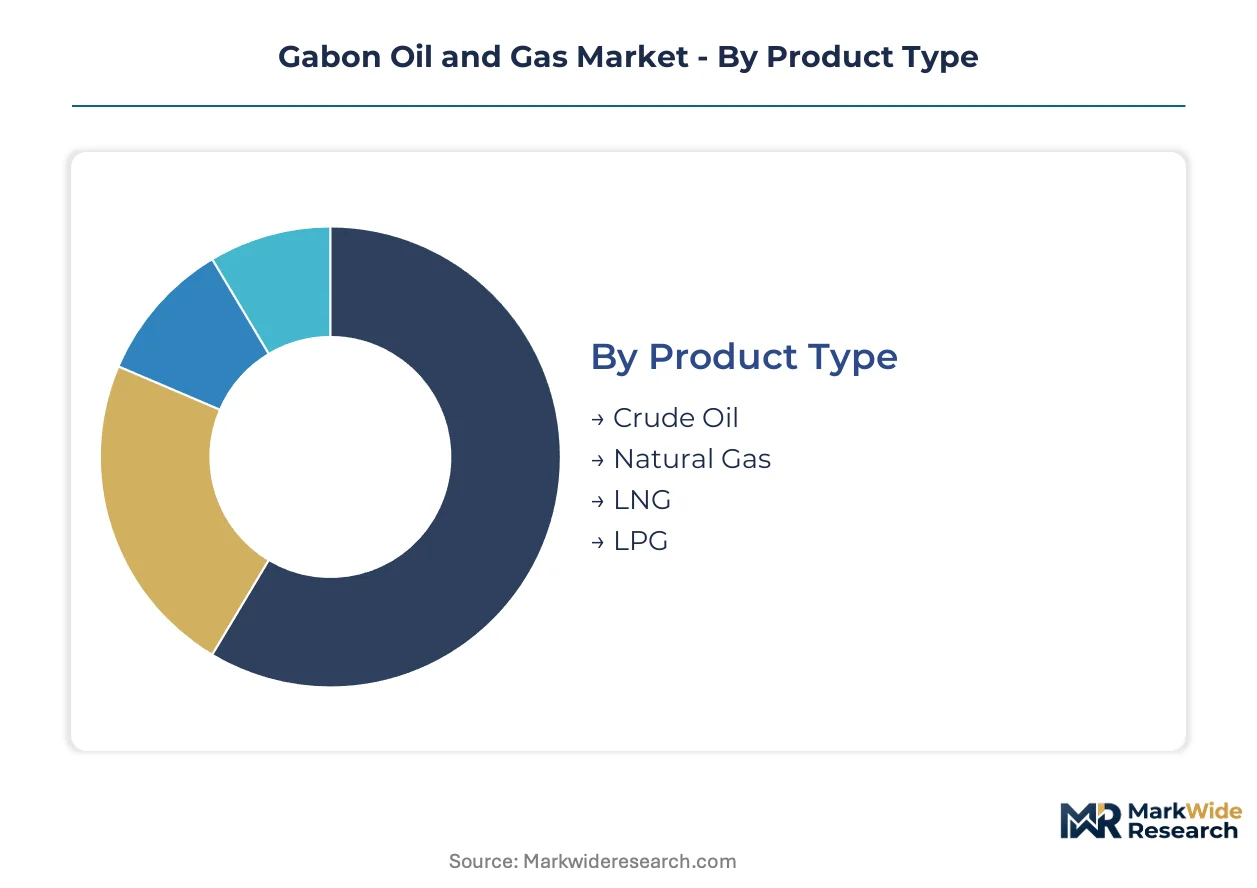
Gabon's hydrocarbon value chain fragments across extraction technologies, processing stages, and destination markets. Each segmentation axis reveals distinct competitive dynamics and capital intensity profiles that shape operator strategies in the Gamba-Ivinga basin complex.
Product Type:
Use-case spectrum spans feedstock flexibility for Atlantic basin refiners through domestic power generation feedstock.
- Crude Oil:Medium-sweet grades with API gravities between 30 and 35 degrees and sulfur content below 0.5 percent dominate export liftings. Gamba basin output feeds European refiners facing carbon border adjustment mechanisms.
- Natural Gas:Associated gas capture from mature offshore fields feeds expanding domestic electrification infrastructure. Stricter flaring penalties at Anguille and Torpille complexes accelerate processing investments.
- LNG:Small-scale liquefaction targets regional West African buyers lacking pipeline connectivity.
- LPG:Fractionation yields serve residential and commercial heating demand in Libreville and Port-Gentil.
The dominant share belongs to Crude Oil, while Natural Gas is closing the gap fastest.
End User:
Customer concentration tracks infrastructure location and offtake contract duration.
- Refineries:SOGARA's Port-Gentil facility processes domestic crude alongside imported feedstocks for regional product distribution.
- Power Plants:SEG and independent generators anchor gas demand growth as electrification targets tighten.
- Petrochemical Companies:Limited downstream integration constrains chemical feedstock absorption.
- Exporters:Atlantic basin term contracts preference certified low-carbon intensity crudes from Gabonese fields.
Refineries absorb the largest volume, though Power Plants are expanding most quickly.
Technology:
Capital allocation follows reserve maturity and water depth economics.
- Exploration:3D seismic and 4D monitoring reduce dry-hole risk in Mayumba ultra-deepwater blocks.
- Drilling:Subsea tieback systems unlock stranded reserves at Etame Marin with lower capital intensity than standalone platforms.
- Production:Brownfield rehabilitation at Rabi-Kounga competes against greenfield frontier economics.
- Refining:Hydrocracker upgrades at SOGARA target middle distillate yield improvement.
Production commands current capital deployment, while Exploration holds the steepest expansion trajectory.
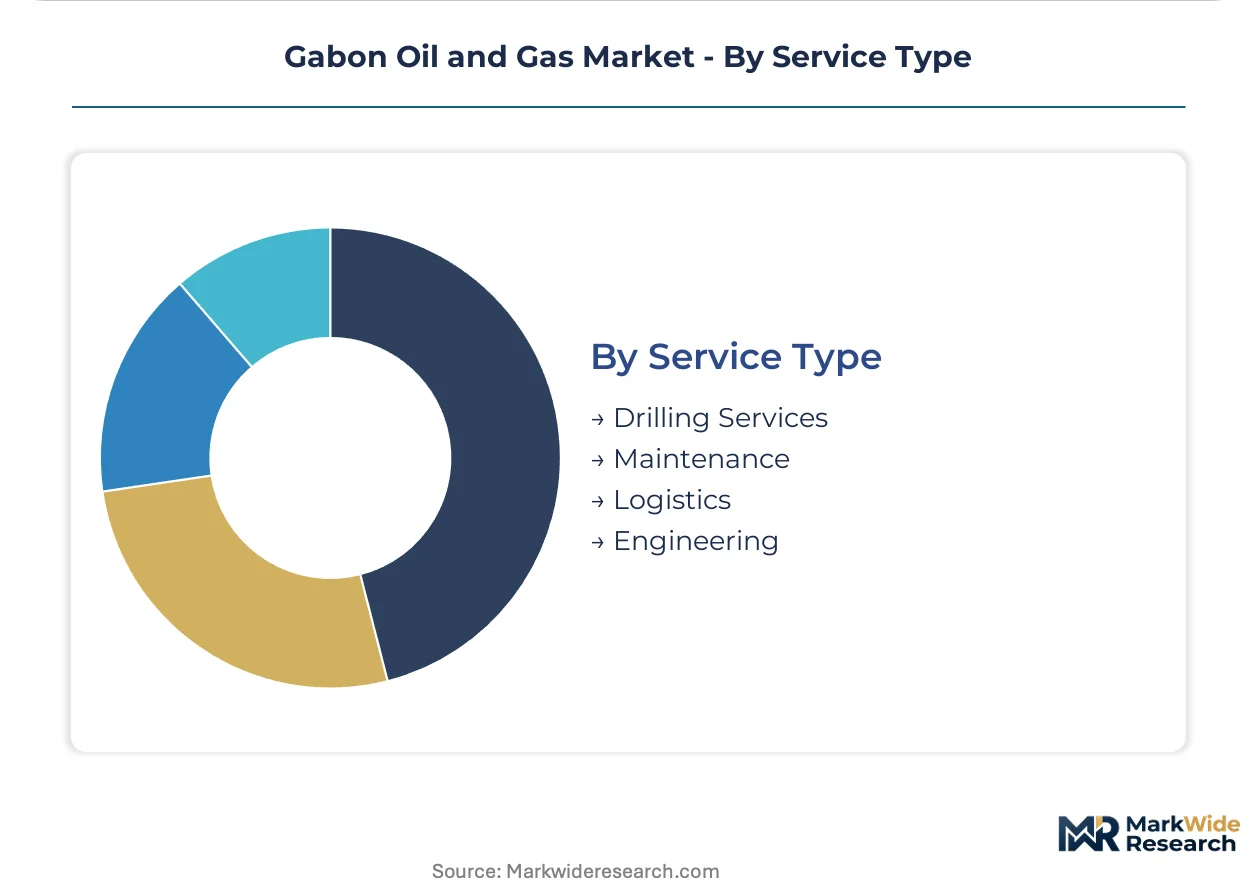
Service Type:
Procurement patterns reflect operator scale and in-house capability depth.
- Drilling Services:Deepwater completion expertise concentrates with narrow contractor bases serving TotalEnergies and Perenco campaigns.
- Maintenance:Aging platform integrity management at Torpille and Grondin drives structural reassessment demand.
- Logistics:Port-Gentil supply base consolidation reduces vessel turnaround for offshore campaigns.
- Engineering:Modular processing architectures compress project development cycles for independent operators.
Drilling Services retain the largest contract value, though Maintenance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Gulf of Guinea coastal terminals while Atlantic basin refining margins compress European offtake terms. West African producers negotiate freight differentials against North Sea and Latin American medium-sweet alternatives. Regional infrastructure access determines netback realization across the basin.
United States
Gulf Coast refiners anchor medium-sweet crude demand through term contracts with carbon intensity verification requirements. EPA methane regulations and proposed carbon border adjustments reshape import eligibility criteria for West African barrels. Houston trading desks price Gabonese grades against WTI and Brent spreads in real-time arbitrage.
Norway
North Sea producers compete directly with Gabonese medium-sweet crudes in Atlantic basin refining markets. Equinor's Johan Sverdrup field output pressures regional price benchmarks through similar API gravity profiles. Stavanger-based trading operations monitor freight rate differentials to Northwest European terminals.
Brazil
Pre-salt production growth displaces West African volumes in Asian and European refining slates. ANP licensing rounds and local content mandates shape capital allocation for frontier deepwater blocks. Rio de Janeiro offshore engineering clusters supply subsea technology to Atlantic basin developments.
Nigeria
Joint venture restructuring between NNPC and international operators mirrors Gabonese PSC renegotiation dynamics. Dangote Refinery startup absorbs regional crude volumes previously exported to European markets. Lagos offshore logistics corridors compete with Port-Gentil for vessel supply base contracts.
Angola
Sonangol's production-sharing contract reforms precede Gabonese regulatory evolution by several years. Cabinda offshore blocks face similar reserve maturity challenges to Gabon's Gamba-Ivinga complex. Luanda refining capacity expansion reduces crude export dependency and alters regional product trade flows.
Gabon Oil and Gas Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in subsea engineering and seismic services. The Gabonese market structures around three operator archetypes: integrated majors with pre-existing deepwater infrastructure, independent specialists in mature field rehabilitation, and national oil company joint venture partners. Consolidation pressure intensifies as reserve base maturity forces portfolio rationalization. Strategic moves cluster around asset divestitures from majors to independents and equity restructuring to satisfy local content mandates.
Within the integrated major tier, TotalEnergies exemplifies infrastructure-led competitive positioning through its Anguille and Torpille complex operations. Perenco and VAALCO Energy represent contrasting archetypes: the former anchors mature onshore rehabilitation strategies, while the latter occupies a position defined by subsea tieback cost structures at Etame Marin. These three operators collectively illustrate how capital intensity and reserve maturity segment competitive positioning in the Gabonese market.
| Leading Market Players |
|---|
| TotalEnergies |
| Perenco |
| Gabon Oil Company |
| Eni |
| Maurel et Prom |
| VAALCO Energy |
| Assala Energy |
| Addax Petroleum |
| Petronas |
| Others |
Supply & Pricing Matrix
Single-source dependency on deepwater drilling contractors headquartered in Houston and Aberdeen determines both pricing tier spreads and supply chain shape across Gabon's offshore developments. This concentration amplifies cost differentials between integrated majors with captive vessel access and independents bidding for scarce rig slots.
Pricing Analysis
Configured-to-order pricing for subsea tieback systems commands substantial premiums over standardized platform development. Contract-based long-term offtake agreements dominate Atlantic basin crude sales, with carbon intensity certification emerging as a critical price differentiation driver between European and Asian buyers. Cost compression in brownfield rehabilitation services is intensifying because Perenco and Assala Energy consolidate vendor relationships. National oil company joint venture partners exhibit lowest price sensitivity due to preferential fiscal terms, while independent operators at marginal fields face acute margin pressure.
Supply Chain Analysis
Tariff exposure between the United States and European Union dominates procurement risk for subsea engineering equipment and specialized drilling components. Gabon's offshore supply chain draws from fabrication yards in Singapore, South Korea, and the United Arab Emirates, with high-grade steel forgings and subsea Christmas trees representing critical input dependencies. Single-source vulnerability concentrates in deepwater completion expertise held by Schlumberger, Halliburton, and TechnipFMC. Distribution runs through Port-Gentil logistics corridors where vessel charter rates and supply base consolidation determine final delivered costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
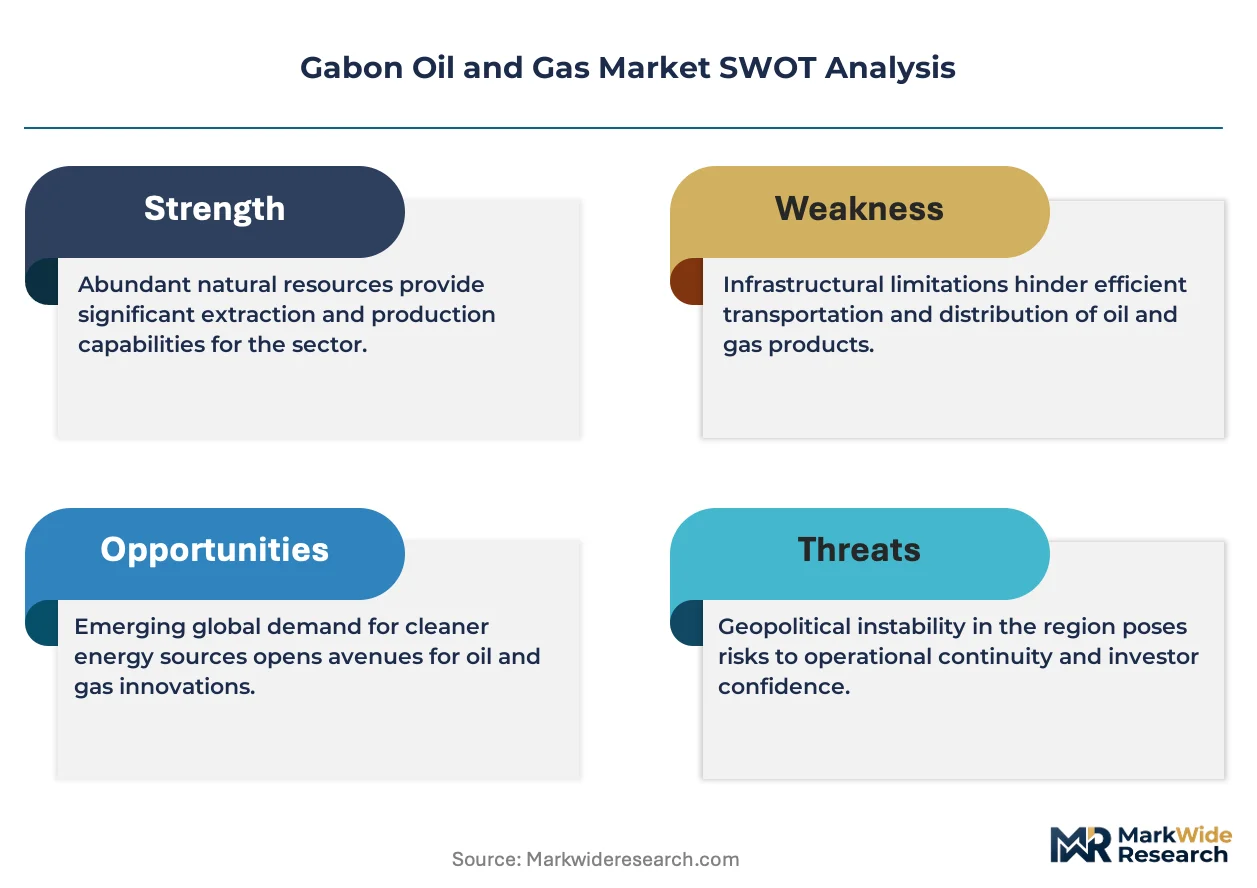
Gabon's oil and gas market functions as a defensive-moat story anchored in regulatory entrenchment. Production-sharing contract renegotiations create structural barriers that favor incumbents with established government relationships and pre-approved environmental baselines.
For Market Incumbents: Pre-empt equity dilution by accelerating rehabilitation investments at Rabi-Kounga and Anguille before local content thresholds tighten further. Secure exclusive rig slotting agreements with Houston and Aberdeen contractors to deny independent operators access to scarce deepwater completion capacity. Vertical integration into Port-Gentil supply base operations strengthens bargaining position against logistics cost inflation.
For New Entrants and Emerging Players: The Mayumba ultra-deepwater frontier offers the most penetrable acreage for operators lacking legacy infrastructure. Target gas-to-power integration projects where captive generation demand anchors offtake certainty and reduces exposure to Atlantic basin refining margin volatility. Partner with Gabon Oil Company early to satisfy joint venture governance requirements and accelerate permitting timelines.
For Investors and Strategic Acquirers: Revised production-sharing contract frameworks reshape the acquisition landscape by elevating national oil company approval requirements above standard antitrust thresholds. Five-to-ten year viability hinges on reserve replacement ratios at mature Gamba basin assets versus frontier exploration success rates. Monitor licensing round participation rates as the inflection signal for government flexibility on fiscal terms.
| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Tieback Deployment | Etame Marin operators reduce capital intensity versus standalone platform investments. |
| Associated Gas Capture Infrastructure | Anguille and Torpille complexes monetize historically flared volumes for domestic power. |
| Carbon Intensity Certification | European border adjustment mechanisms now condition import eligibility for Gabonese crudes. |
| Local Content Compliance Investment | Revised production-sharing contracts mandate domestic employment and procurement quotas. |
| Mayumba Frontier Licensing Participation | Ultra-deepwater blocks host untested Cretaceous plays beyond existing infrastructure reach. |
Research Methodology
Desk research of regulatory filings from Gabon's national petroleum regulator, environmental impact assessment databases, and Atlantic basin crude trade customs data preceded structured interviews with upstream project managers, subsea engineering contractors, and Port-Gentil logistics coordinators. Primary fieldwork with SOGARA refining executives and SEG power generation planners validated secondary assumptions on domestic demand trajectories. Bottom-up field-level production estimates and top-down basin-wide reserve assessments underwent iterative reconciliation.
Forecast assumptions held constant the current production-sharing contract framework and Atlantic basin carbon border adjustment implementation timeline while varying crude price bands and exploration success rates across the analysis window. Segmentation modeling incorporated product type, end-user infrastructure location, water depth economics, and operator scale classifications. CAGRs derived from production decline curve analysis at mature assets and greenfield development schedules at frontier blocks, with natural gas processing capacity buildout serving as a key demand-side input.
Practitioners should monitor licensing round bid intensity and joint venture restructuring announcements for early signals of fiscal term flexibility or rig availability constraints. Forecasts reflect assumptions regarding exploration success rates and contractor capacity expansion that operating reality may revise. Continuous validation against drilling campaign announcements and production-sharing contract amendment filings is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
Global Seismic Survey Market
Oil & Gas
Nigeria Oil and Gas Upstream Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
North America Oil Storage Market
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Whipstocks Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Kazakhstan Oil and Gas Market
Oil & Gas
Mining and Oil & Gas Fasteners Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Peru Oil and Gas Downstream Market
Oil & Gas
South America Oil and Gas Storage Tank Market