
 Sucker Rod Market | 2026-2036
Sucker Rod Market Size, Share, and Industry Trends Forecast 2026-2036
Sucker Rod Market Analysis
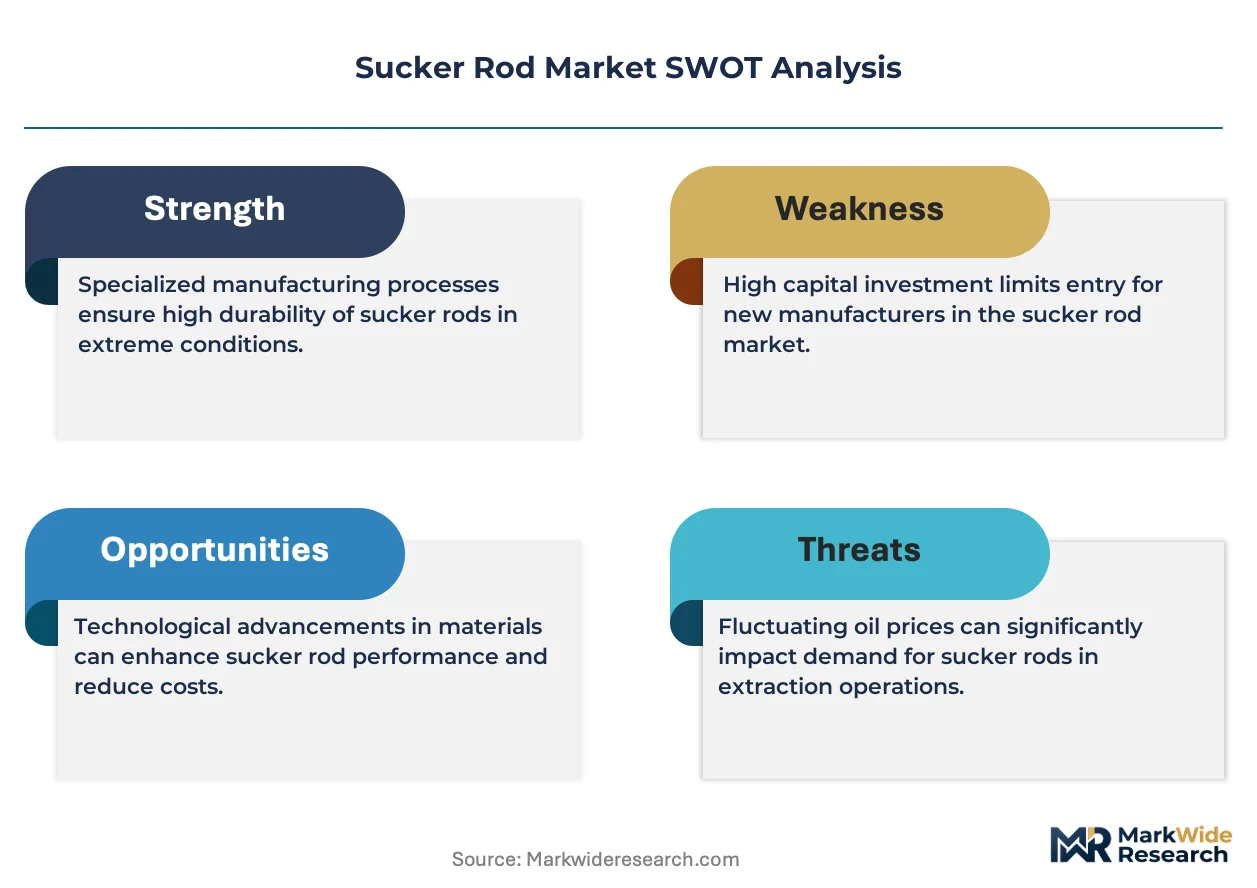
Fiberglass-reinforced polymer is recalibrating sucker rod economics across corrosive well environments. Tenaris leverages integrated seamless pipe capacity to captive-produce high-strength alloy rod grades. Kerui Group anchors its position through backward integration into bar steel and heat-treatment operations. Weatherford International differentiates via downhole monitoring systems bundled with rod string design.
A sucker rod is a solid or hollow steel or composite bar, typically 25 to 30 feet in length and 0.5 to 1.25 inches in diameter, that transmits reciprocating surface motion to a downhole pump in beam-pumped oil wells. Steel product types retain volume dominance in standard load applications, though fiberglass segments command premium positioning in CO2-flooded and sour-gas fields where corrosion fatigue governs replacement cycles. Onshore production applications absorb the majority of unit demand, while artificial lift system integration is shifting procurement toward packaged rod-pump configurations rather than standalone bar sales.
API 11B standards govern dimensional tolerance and mechanical property requirements for sucker rods in US fields, while China's GB/T 28259 specifies equivalent performance benchmarks for domestic suppliers. EPA methane-emission regulations indirectly shape rod selection by extending well-run intervals and favoring materials that reduce workover frequency. Stakeholders must monitor composite-material qualification progress and assess whether fiberglass rod manufacturing scale can challenge steel cost structures in basins beyond the Permian and Eagle Ford.
Market Dynamics
API 11B specification revisions are tightening fatigue-resistance requirements, forcing rod manufacturers to upgrade metallurgical capabilities and heat-treatment protocols while absorbing certification costs. This regulatory compression is redistributing competitive advantage toward suppliers with captive steelmaking and in-house testing infrastructure.
Growth Catalysts
- Permian Basin shale expansion:Artificial lift deployment in West Texas and New Mexico tight-oil fields is accelerating rod-string replacement cycles as lateral lengths extend beyond 15,000 feet.
- EPA methane regulations:Emission-control mandates are extending well-run intervals, favoring corrosion-resistant materials that reduce workover frequency and unplanned downtime.
- Fiberglass-reinforced polymer qualification:Composite rod advancement is opening sour-gas and CO2-flooded reservoirs previously uneconomical for carbon-steel strings.
Market Restraints
- Alloy steel input volatility:Chrome-molybdenum bar stock prices fluctuate with scrap metal and ferroalloy markets, compressing margin predictability for non-integrated producers.
- Chinese supply concentration:GB/T 28259-certified manufacturers in Shandong and Jiangsu provinces control substantial export capacity, creating geographic supply-risk exposure.
- Steel-to-composite substitution ceiling:Fiberglass rods face load-rating limitations above 25,000 pounds per string, restricting penetration in deep high-volume wells.
Strategic Opportunities
- Eagle Ford underpenetration:South Texas operators are trailing Permian adoption curves for premium alloy grades, creating white-space for specification-upgrading campaigns.
- Downhole monitoring bundling:Rod-string design paired with real-time load and corrosion sensors is creating integrated artificial-lift procurement channels.
- IRA domestic content incentives:US-manufactured rod qualification for federal land drilling permits is favoring domestic heat-treatment and threading operations.
Industry Challenges
- API 11B certification timelines:Revised fatigue-testing protocols are extending qualification periods from 90 to 180 days, delaying new grade commercialization.
- Legacy beam-pump integration:Composite rod retrofitting requires polished-rod and pumping-unit modifications, complicating field deployment economics.
- Metallurgical talent scarcity:Heat-treatment engineers with sucker-rod-specific expertise are concentrating at integrated mills, constraining independent producer technical capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sucker Rod Market |
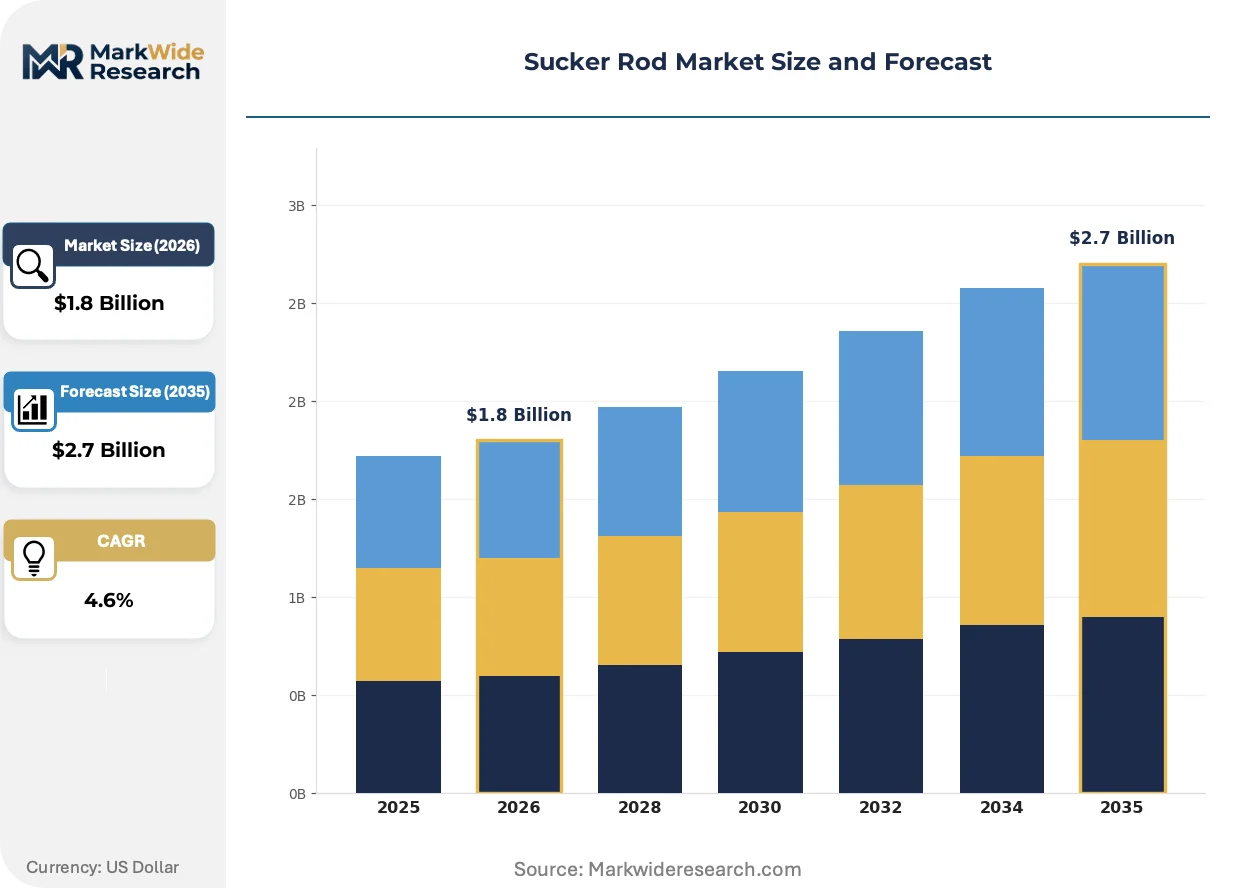
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Fiberglass, Polished Rod, Composite Application: Onshore Production, Offshore Production, Well Servicing, Artificial Lift End User: Oil & Gas Companies, Service Providers, EPC Contractors, Research Institutions Manufacturing Stage: Raw Material Sourcing, Production, Quality Control, Distribution |
| Companies Covered | Dover, Kerui Group, Tenaris, John Crane, Dongying TIEREN Sucker Rod, Weatherford International, Exceed, Vallourec, Nine Ring Petroleum Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sucker Rod Market Emerging Trajectories
Material science advancement and regulatory stringency are converging to reshape product specifications, procurement patterns, and supplier capability requirements across the sucker rod value chain.
Continuous-monitoring fiber-optic systems embedded within rod strings are electrifying predictive maintenance protocols in Permian and Bakken fields. E&P operators are retrofitting existing beam-pump installations with load-cell and corrosion-sensor arrays at accelerating pace. This instrumentation density is compressing replacement-cycle forecasting from calendar-based to condition-based models, rewriting inventory and service-contract structures.
EPA methane-emission standards are extending well-run interval requirements, indirectly tightening material specifications for downhole components. Rod-string selection now incorporates corrosion-fatigue resistance as a compliance variable, not merely an economic optimization. US onshore operators are responding by upgrading from standard carbon grades to chromium-plated or alloy-steel alternatives in marginal gas-lift and waterflood environments.
Integrated artificial-lift procurement is displacing standalone rod-bar purchasing as the dominant transaction model. E&P engineering teams are bundling rod-string design, pump selection, and surface-unit specification into single-source contracts with oilfield service providers. This consolidation is most visible in Delaware Basin operations, where drilling contractors and artificial-lift specialists are absorbing procurement functions previously managed by operator supply-chain departments.
Sucker Rod Market Segmentation
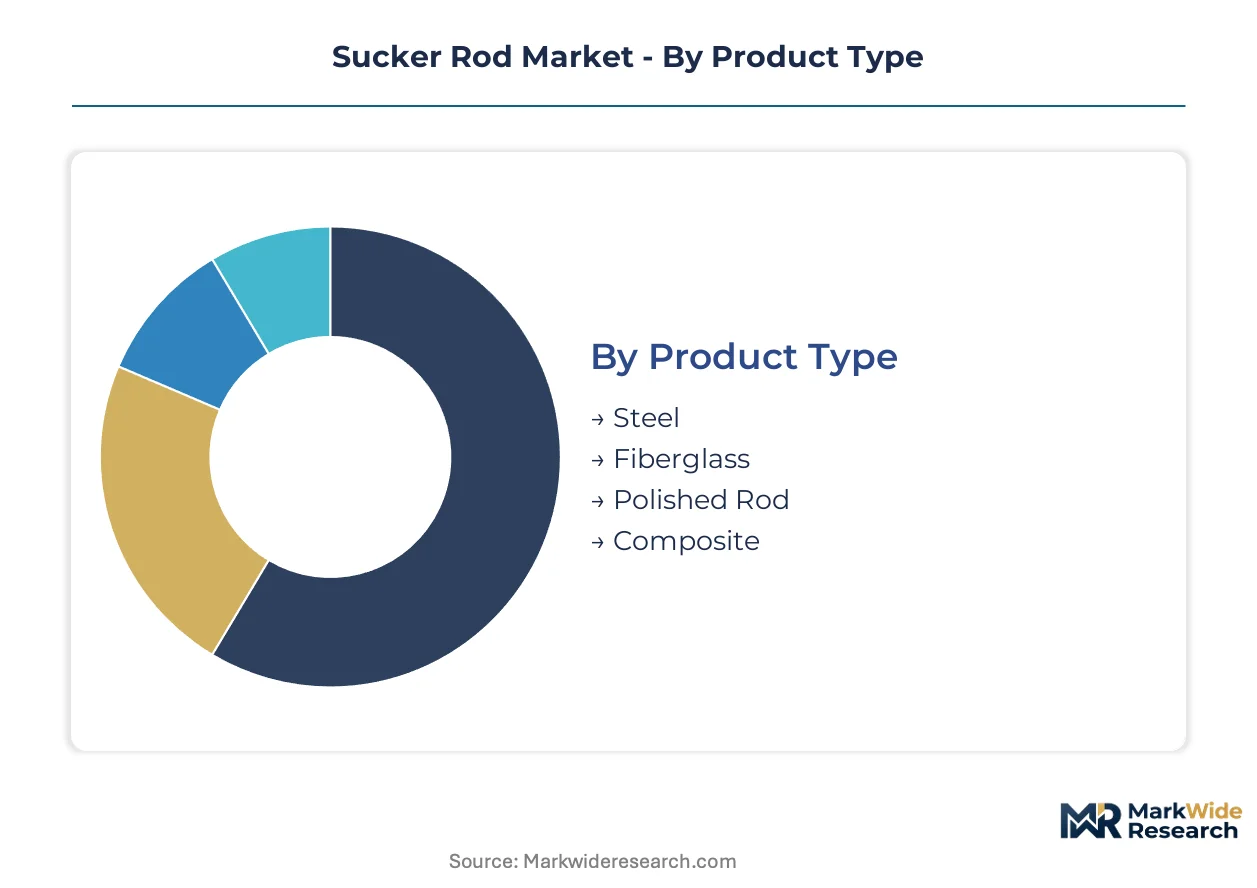
Sucker rod procurement patterns diverge sharply across product grades and deployment contexts. Understanding these fault lines clarifies where specification premiums command pricing power versus where commodity sourcing dominates.
Product Type:
Supply concentration tilts toward integrated steel mills with captive heat-treatment capacity, while composite specialists fragment across regional polymer-processing clusters.
- Steel:Carbon and alloy grades remain the baseline specification for standard-load beam-pump installations across US onshore fields. Permian Basin operators specify API 11B Grade C, D, and K rods for high-cycle fatigue environments where lateral lengths exceed 12,000 feet.
- Fiberglass:Glass-fiber-reinforced polymer rods deliver corrosion immunity in CO2-flooded and hydrogen-sulfide-rich reservoirs. Eagle Ford and Bakken operators are expanding fiberglass deployment where workover economics favor extended run intervals over upfront material cost.
- Polished Rod:Surface-end connector rods machined to tight dimensional tolerances for stuffing-box sealing.
- Composite:Hybrid material systems combining fiber reinforcement with metallic load-bearing cores.
Steel absorbs the bulk of installed capacity; fiberglass is expanding most quickly.
Application:
Cost tier separation runs deepest between continuous-production installations and intermittent well-servicing deployments.
- Onshore Production:Beam-pumped oil wells in tight-shale and conventional sandstone formations constitute the core demand reservoir. West Texas and New Mexico operators replace rod strings on 18-to-36-month cycles as lateral lengths stretch fatigue limits.
- Artificial Lift:Integrated rod-pump system procurement is displacing standalone bar purchasing in Delaware Basin and Midland sub-basin development programs. Bundled contracts now specify rod-string design, pump selection, and surface-unit configuration.
- Well Servicing:Workover rigs and pulling units deploy replacement rods during planned maintenance or failure recovery.
- Offshore Production:Platform-based beam-pump and hydraulic lift installations in Gulf of Mexico and international shallow-water fields.
Onshore Production commands the dominant share of unit volume; Artificial Lift is climbing the fastest as procurement consolidates around integrated suppliers.
End User:
Customer type determines specification authority and contract structure more than raw volume scale.
- Oil & Gas Companies:Supermajors and independents with in-house petroleum engineering teams set material specifications directly. Pioneer Natural Resources, Diamondback Energy, and Permian-focused independents qualify rod grades through centralized supply-chain functions.
- Service Providers:Artificial-lift specialists and drilling contractors bundle rod procurement into integrated service contracts.
- EPC Contractors:Engineering-procurement-construction firms specify rod strings for greenfield facility builds.
- Research Institutions:National laboratories and university programs source rods for corrosion-fatigue and materials-testing protocols.
Oil & Gas Companies retain specification-setting authority; Service Providers are gaining procurement share through bundled artificial-lift contracts.
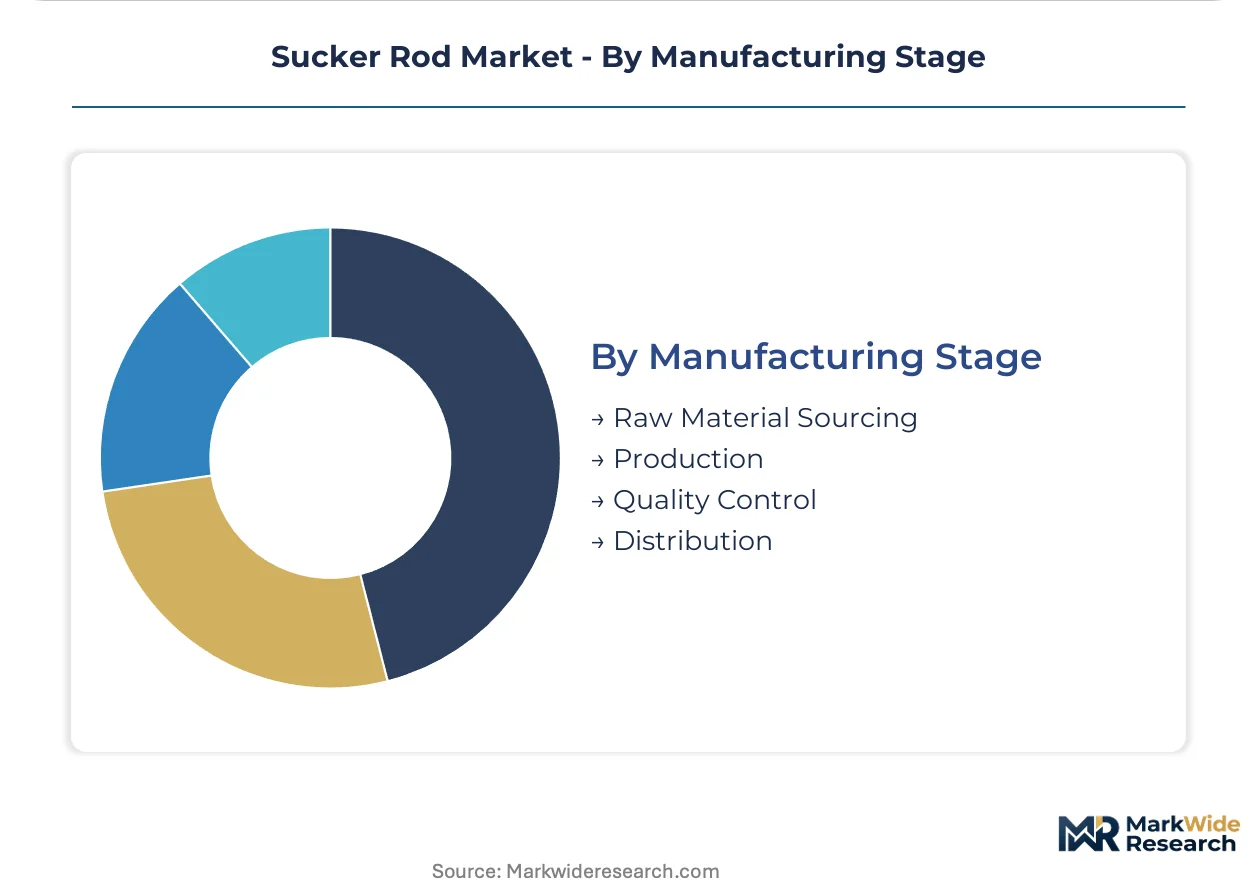
Manufacturing Stage:
Margin capture concentrates at heat-treatment and threading operations where certification barriers exclude commodity processors.
- Production:Forging, rolling, and machining operations transform bar stock into finished rod geometries. Tenaris and Kerui Group anchor capacity at integrated mills with in-house metallurgical laboratories.
- Quality Control:API 11B fatigue testing and dimensional inspection protocols now require 180-day qualification timelines. Captive testing infrastructure separates certified suppliers from bar-stock resellers.
- Raw Material Sourcing:Chrome-molybdenum bar stock procurement from scrap-dependent mini-mills and integrated steel producers.
- Distribution:Regional stocking and threading services for field-delivery logistics.
Production captures the bulk of value-added margin; Quality Control is expanding most quickly as certification timelines extend and testing infrastructure becomes a competitive gate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US onshore fields absorb the dominant share of sucker rod unit demand, with Permian Basin operators replacing strings on compressed cycles as lateral lengths stretch fatigue limits. Artificial lift deployment concentrates in West Texas and New Mexico tight-oil formations where rod-run life directly impacts lifting economics.
United States
Permian Basin shale operators in West Texas and New Mexico specify API 11B Grade D and K rods for high-cycle fatigue environments where laterals exceed 12,000 feet. EPA methane-emission regulations extend well-run intervals, favoring corrosion-resistant alloys that reduce workover frequency. Midland-Odessa anchors the highest rod-string replacement velocity, with Delaware Basin development programs consolidating procurement around bundled artificial-lift contracts.
China
Shandong and Jiangsu provinces host GB/T 28259-certified manufacturers supplying domestic tight-oil fields and export markets. MIIT industrial standards and dual carbon goals pressure heat-treatment operations to upgrade energy efficiency and emission controls. Dongying's petroleum machinery cluster concentrates backward-integrated bar steel and threading capacity for both captive use and international shipment.
Canada
Alberta oil sands and Saskatchewan conventional fields deploy steel rods in thermal and cold-production applications where temperature cycling governs material selection. Health Canada environmental assessments intersect with provincial methane regulations to extend run-interval requirements. Calgary-based operator supply chains qualify domestic and US-manufactured grades for federal land drilling permits.
Brazil
Pre-salt and onshore mature fields in the Campos and Santos basins drive artificial lift procurement as natural pressure declines accelerate. ANVISA industrial equipment standards and Petrobras technical specifications govern material qualification timelines. Rio de Janeiro engineering-procurement-construction firms bundle rod-string design into integrated offshore platform contracts.
Saudi Arabia
Ghawar and Khurais field maturation programs expand beam-pump and rod-lift deployment in waterflood operations. Saudi Aramco engineering standards exceed API 11B fatigue requirements, creating qualification barriers for non-integrated suppliers. Eastern Province industrial cities host heat-treatment and threading facilities serving domestic production and regional export.
Sucker Rod Market Vendor Landscape
Backward integration into captive steelmaking and heat-treatment infrastructure dominates the current landscape as API 11B certification timelines extend from 90 to 180 days. The supplier base stratifies between integrated mills with in-house metallurgical laboratories and independent fabricators dependent on external bar-stock sourcing. Three archetypes occupy distinct positions: seamless pipe producers extending into alloy rod grades, regional machinery specialists with provincial supply-chain control, and oilfield service providers bundling rods with downhole monitoring systems. Competitive intensity centers on certification speed and geographic proximity to Permian and Eagle Ford demand clusters.
Among integrated steel and pipe producers, Tenaris and Vallourec exemplify the seamless-pipe-to-rod extension archetype with captive metallurgical capabilities. Kerui Group anchors the regional machinery specialist position through Shandong-based bar steel and heat-treatment operations. Weatherford International occupies the service-provider integration tier, representing the bundled artificial-lift procurement model displacing standalone rod sales.
| Leading Market Players |
|---|
| Dover |
| Kerui Group |
| Tenaris |
| John Crane |
| Dongying TIEREN Sucker Rod |
| Weatherford International |
| Exceed |
| Vallourec |
| Nine Ring Petroleum Machinery |
| Others |
Supply Flow & Price Mechanics
Permian Basin operators with consolidated artificial-lift procurement functions command contract structures that compress margin capture at independent rod fabricators. Bundled rod-string design contracts favor suppliers with captive heat-treatment infrastructure, reshaping how pricing power distributes across steel and composite segments.
Pricing Analysis
Volume concentration in standard carbon grades runs against margin capture in corrosion-resistant alloy and fiberglass alternatives. Three-tier pricing structure across premium API 11B Grade K, standard Grade D, and economy carbon grades reflects certification timelines and fatigue-testing infrastructure. Cost compression in Chinese-export carbon rod is intensifying because GB/T 28259-certified producers leverage Shandong-based bar steel integration. Independent fabricators without captive steelmaking face the steepest price sensitivity, while integrated mills with in-house metallurgical laboratories retain pricing authority.
Supply Chain Analysis
Single-source vulnerability sits with chrome-molybdenum bar stock drawn from US mini-mills and Chinese integrated producers. Raw material flows rest on scrap metal markets, ferroalloy pricing, and seamless pipe capacity at Tenaris and Vallourec facilities. Tariff exposure on Chinese-threaded rod imports creates qualification bottlenecks for non-integrated US fabricators. Distribution runs through Midland-Odessa stocking points and Delaware Basin field-delivery logistics, with heat-treatment and threading operations capturing downstream value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sucker rod market is transitioning from standalone bar sales toward integrated artificial-lift procurement, with fiberglass-reinforced polymer displacing carbon steel in corrosive well environments. This technology shift rewards suppliers who bundle downhole monitoring with rod-string design.
For Market Incumbents: Lock in captive heat-treatment capacity and API 11B certification infrastructure before qualification timelines extend further. Defend against composite substitution by qualifying hybrid material systems that combine fiber reinforcement with metallic cores. Prioritize Delaware Basin and Eagle Ford proximity to capture bundled procurement contracts from artificial-lift specialists. For New Entrants and Emerging Players: Enter via Eagle Ford underpenetration for premium alloy grades, where South Texas operators trail Permian adoption curves. Target fiberglass rod manufacturing scale-up for CO2-flooded reservoirs beyond the Permian and Bakken. Pursue qualification partnerships with downhole monitoring providers to embed sensor arrays within composite rod strings. For Investors and Strategic Acquirers: The window for entry favors integrated steel mills with seamless pipe-to-rod extension capability and in-house metallurgical laboratories. Long-term viability hinges on certification speed and geographic proximity to Permian demand clusters. Watch composite-material qualification progress at major E&P operators as the inflection signal for steel-to-polymer substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| API 11B Certification Investment | Extended 180-day qualification timelines favor captive testing infrastructure at integrated mills. |
| Fiberglass Manufacturing Scale-Up | Composite rod capacity expansion targets sour-gas fields in Eagle Ford and Bakken basins. |
| Downhole Monitoring Bundling | Sensor-embedded rod strings rewrite procurement patterns toward single-source artificial-lift contracts. |
| Backward Integration into Bar Steel | Captive chrome-molybdenum supply insulates margin from scrap metal and ferroalloy volatility. |
| Permian Basin Field-Delivery Expansion | Midland-Odessa stocking points compress replacement-cycle response times for high-velocity operators. |
Methodological Framework
Independent corroboration across petroleum engineering executives at Permian-focused independents, artificial-lift procurement leads at major E&P operators, and heat-treatment specialists at integrated mills underwrites the qualitative findings. Secondary validation drew from API specification revision documents, EPA methane-emission rulemakings, SEC filings from seamless pipe producers, and customs data on Chinese rod exports. Bottom-up field-level deployment estimates triangulate against top-down steel consumption models for artificial-lift applications.
Historical reference periods spanning pre-pandemic baseline, supply-constrained recovery, and current regulatory-compression phases anchor the projection framework across the analysis window. Modeled segmentation spans product grade, application context, and end-user procurement authority, with CAGRs derived from replacement-cycle velocity and lateral-length extension trends. Forecast inputs incorporate beam-pump installation rates, workover frequency assumptions, and composite-material qualification timelines at major operators.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scrap metal price volatility, Chinese export policy shifts, or accelerated fiberglass substitution in deep high-volume wells. Forecasts reflect documented assumptions on lateral-length trajectories, regulatory stringency evolution, and integrated procurement adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
CO2 EOR Market
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
Liner Hanger System Market
Oil & Gas
FTIR Oil Condition Monitoring Market
Oil & Gas
Reservoir Analysis Market
Oil & Gas
North America Oil Storage Market
Oil & Gas
Italy Oil and Gas Downstream Market
Oil & Gas
Oil and Gas Asset Integrity Management Services Market
Oil & Gas
Frac Stack Market
Oil & Gas
Uzbekistan Oil and Gas Market
Oil & Gas
Global Carbon Steel Tubing in Oil and Gas Lift Applications Market
Oil & Gas
Coal Seam Gas Market
Oil & Gas
Distributed Fiber Optic Sensor in Oil & Gas Market
Oil & Gas
Oman Oil and Gas Pipeline Market