
 Colombia Oil and Gas Midstream Market | 2026-2036
Colombia Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Oil and Gas Midstream Market Outlook
The Colombia oil and gas midstream sector is consolidating around two distinct operational tiers: premium infrastructure with integrated storage and processing capabilities, and commodity pipeline operators serving single-source production fields. Ecopetrol SA leverages its state-backed position to control the majority of trunkline capacity across the Magdalena River valley. Cenit Transporte y Logística de Hidrocarburos S.A. anchors specialized crude transport services from the Llanos Basin to Caribbean export terminals. Promigas S.A. E.S.P. competes aggressively in natural gas distribution, extending its pipeline network toward industrial demand clusters near Barrancabermeja.
Colombia oil and gas midstream encompasses the transportation, storage, and wholesale marketing of crude oil and natural gas between production fields and downstream refineries, typically involving pipeline systems rated for pressures between 800 and 1,440 psi and storage terminals with capacities exceeding 500,000 barrels. The primary purpose is to maintain continuous flow assurance while minimizing hydrocarbon losses across extended distances and varied topography. Pipeline infrastructure dominates capital deployment, with operators prioritizing corrosion-resistant coatings and cathodic protection systems to extend asset life in tropical conditions. Natural gas processing represents the fastest-expanding technology segment, driven by rising associated gas recovery from heavy oil fields and stricter flaring regulations. Terminals and storage facilities command the most stable margin pools, as tariff structures for throughput services insulate operators from crude price volatility.
Colombia's Ministry of Mines and Energy, the National Environmental Licensing Authority (ANLA), and the Superintendency of Industry and Commerce collectively shape market access through environmental impact assessments, right-of-way negotiations, and tariff oversight. ANLA's wetland protection protocols have delayed several pipeline expansions, redirecting investment toward existing corridor upgrades rather than greenfield routes. The Superintendency's price monitoring framework limits tariff escalation for regulated transport services, compressing returns on legacy assets. Stakeholders must weigh the capital intensity of compliance-ready infrastructure against the volume risk of declining exploratory success in mature basins.
Market Dynamics
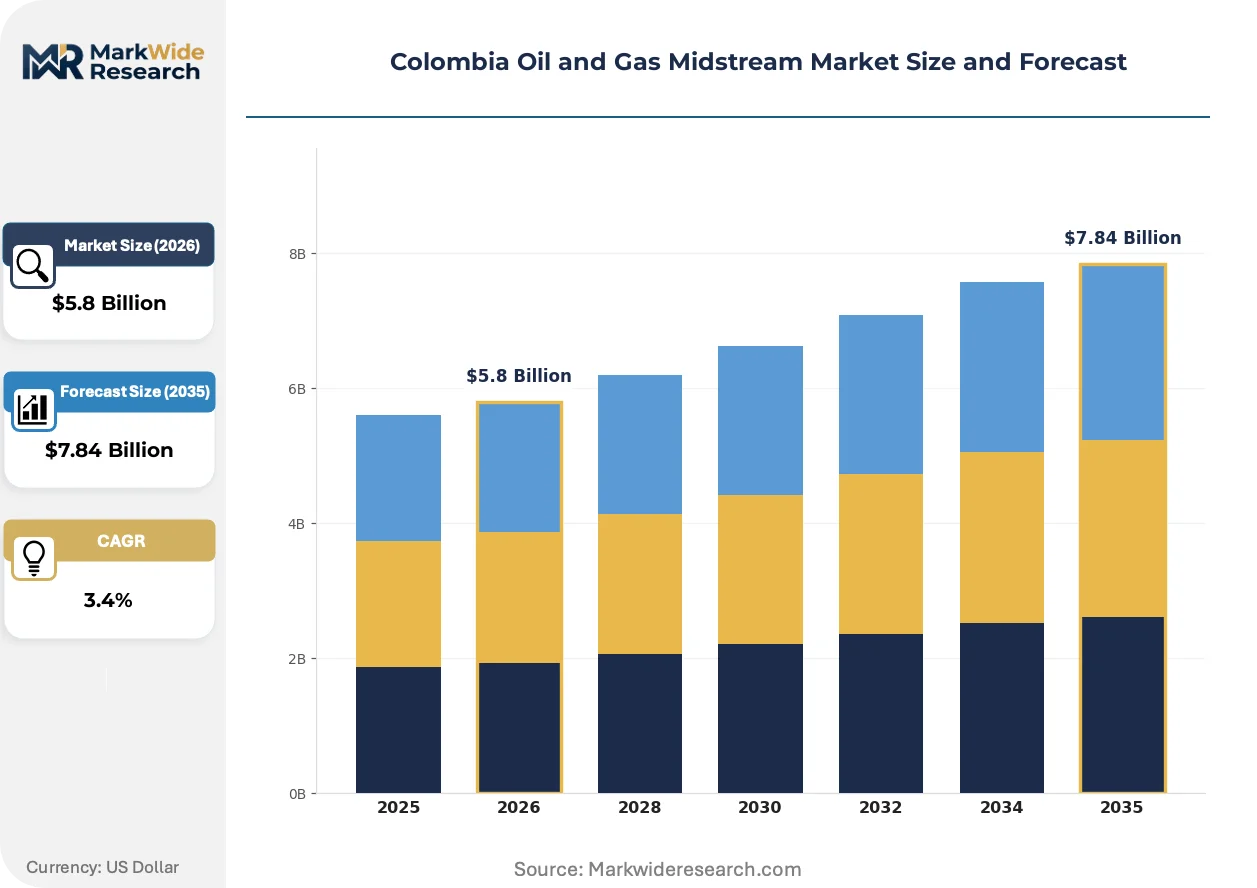
Colombia's midstream sector is consolidating around corridor-specific infrastructure tiers, as ANLA's wetland protection protocols force operators toward brownfield expansions rather than greenfield pipeline routes through sensitive ecosystems.
Growth Catalysts
- Associated gas recovery mandates:The Ministry of Mines and Energy's stricter flaring regulations compel heavy oil producers to capture and process previously vented natural gas, expanding processing plant demand across the Llanos Basin.
- Refinery intake upgrades:Andean refineries are reconfiguring receiving terminals to handle heavier crude blends, requiring new gathering systems and storage compatibility investments.
- Industrial clustering near Barrancabermeja:Petrochemical demand concentration is pulling natural gas distribution networks toward specific manufacturing zones, creating dedicated offtake corridors.
Market Restraints
- Right-of-way cost inflation:ANLA's environmental licensing delays extend land acquisition timelines, inflating project carrying costs before construction begins.
- Legacy asset tariff compression:The Superintendency of Industry and Commerce's price monitoring framework caps regulated transport rate escalations, squeezing returns on existing pipeline systems.
- Exploratory decline in mature basins:Reduced success rates in Colombia's conventional fields threaten long-term volume commitments needed to justify trunkline expansions.
Strategic Opportunities
- Magdalena River valley corridor densification:Existing Ecopetrol-controlled routes offer brownfield expansion potential with lower regulatory friction than new Andean crossings.
- Carbon capture integration:Processing facilities can retrofit amine-based capture systems to monetize CO2 streams under emerging low-carbon fuel standards.
- Digital twin deployment:Advanced leak detection and predictive maintenance platforms reduce insurance premiums and downtime costs for coastal export terminals.
Industry Challenges
- Specialized welding certification scarcity:X-ray qualified pipeline construction crews face acute shortages, extending project schedules for high-pressure trunkline work.
- Cathodic protection system integration:Tropical corrosion conditions demand continuous coating upgrades, complicating maintenance scheduling across dispersed networks.
- Legacy SCADA modernization:Decades-old control systems require phased replacement without disrupting continuous hydrocarbon flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Oil and Gas Midstream Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pipelines, Terminals, Storage Facilities, Pump Stations Technology: Natural Gas Processing, Liquid Transportation, Compression Systems, Maritime Transport End User: Refineries, Petrochemicals, Power Plants, Industrials Capacity: High Capacity, Medium Capacity, Low Capacity, Flexible Systems |
| Companies Covered | Ecopetrol SA, Exxon Mobil Corporation, Chevron Corporation, Shell Colombia SA, Cenit Transporte y Logística de Hidrocarburos S.A., Occidental Petroleum Corporation, Fluor Corporation, Transportadora de Gas Internacional, Promigas S.A. E.S.P., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Oil and Gas Midstream Market Strategic Shifts
Digital infrastructure convergence and regulatory stringency are compressing operational margins while creating technology adoption imperatives across Colombia's pipeline and processing networks.
Integrated pipeline monitoring platforms combining fiber-optic sensing with satellite telemetry are unifying leak detection, pressure management, and third-party intrusion alerts into single-dashboard operations. Midstream operators in the Llanos Basin are deploying these systems to satisfy ANLA's enhanced environmental monitoring requirements. The technology is unifying previously siloed safety and compliance functions, reducing manual inspection headcount while accelerating incident response times.
ANLA's wetland protection protocols now mandate buffer zone rehabilitation and continuous ecological monitoring for any new corridor approval. This regulatory friction has redirected capital toward existing route expansions rather than greenfield construction through the Andean foothills. Pipeline operators are responding by densifying capacity along Magdalena River corridors where environmental clearances already exist.
Refinery procurement teams are consolidating crude supply contracts around integrated transport-and-storage bundles rather than spot throughput arrangements. This purchasing compression favors midstream operators with captive terminal capacity over pure pipeline transporters. The shift is most visible among Caribbean export facilities serving international trading houses seeking guaranteed lifting schedules.
Colombia Oil and Gas Midstream Market Segmentation
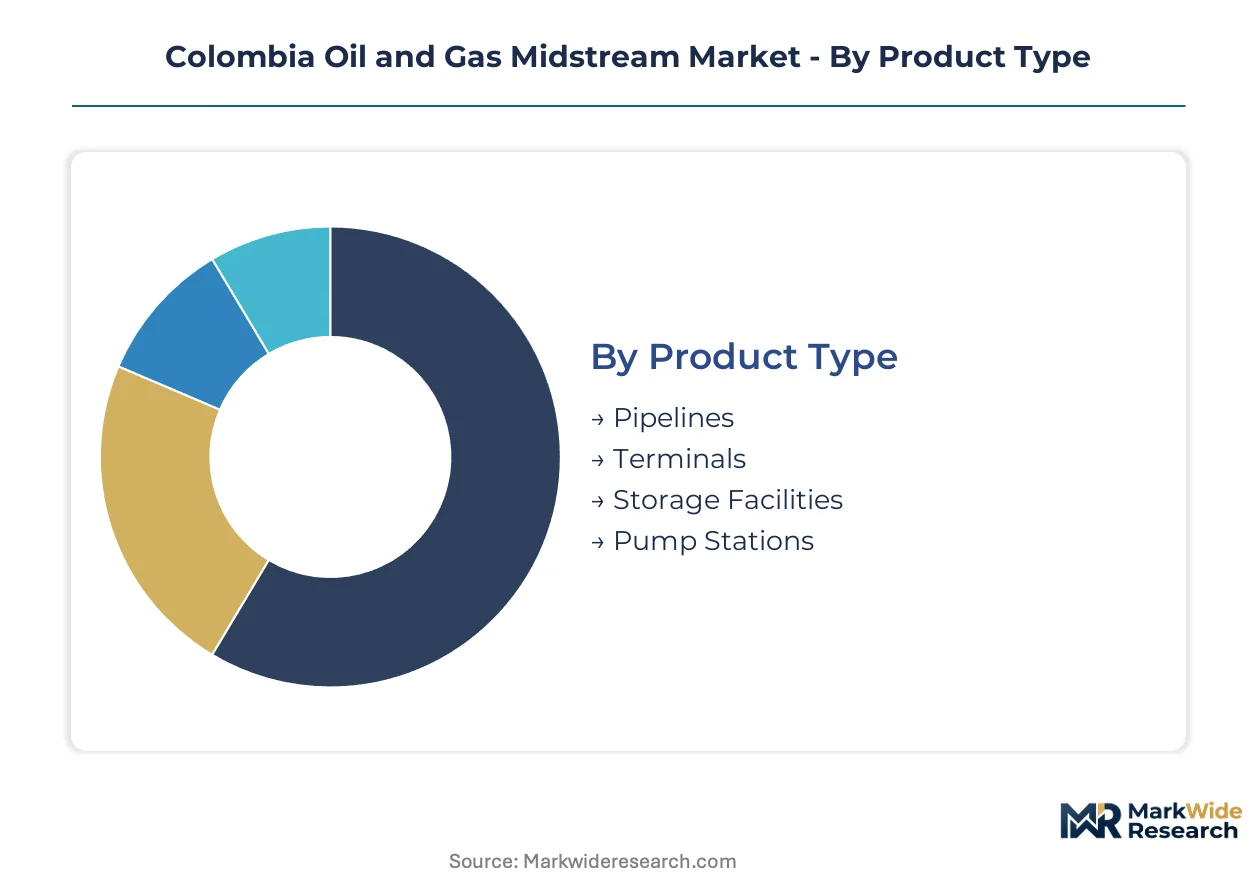
Segmentation in Colombia's midstream infrastructure reveals how capital allocation splits between fixed corridor assets and flexible processing systems. The country's regulatory environment favors brownfield expansions over greenfield routes, concentrating investment in specific technology tiers and capacity bands.
Product Type:
Standalone infrastructure dominates capital deployment, while embedded systems within integrated networks serve specialized basin-to-coast logistics.
- Pipelines:Trunkline systems rated for 800-1,440 psi transport crude from Llanos Basin production fields to Caribbean export terminals. ANLA's wetland protection protocols restrict new corridor approvals, forcing operators to densify existing Magdalena River valley routes rather than build Andean crossings.
- Storage Facilities:Tank farms exceeding 500,000 barrels buffer flow imbalances between production schedules and refinery intake windows. These terminals command the most stable tariff margins, insulating operators from crude price volatility through fixed throughput contracts.
- Terminals:Coastal loading facilities integrate vessel scheduling with pipeline receipts for international trading houses.
- Pump Stations:Compression infrastructure maintains pressure gradients across Colombia's mountainous terrain and tropical lowlands.
Volume placements concentrate in Pipelines; the faster expansion belongs to Storage Facilities.
Technology:
Cost tiers separate mature transport technologies from emerging processing systems requiring specialized operational expertise.
- Natural Gas Processing:Amine-based treatment and cryogenic separation units recover associated gas from heavy oil fields. The Ministry of Mines and Energy's flaring regulations mandate capture infrastructure, pulling investment toward Llanos Basin processing plants.
- Liquid Transportation:Heated pipeline systems maintain crude flow assurance for viscous heavy blends moving from interior production zones to coastal refineries.
- Compression Systems:High-pressure injection infrastructure supports gas lift operations and pipeline throughput maintenance.
- Maritime Transport:Coastal vessel logistics connect pipeline terminals to international offtake markets.
Volume placements concentrate in Liquid Transportation; the steepest expansion trajectory belongs to Natural Gas Processing.
End User:
Application concentration varies between fuel conversion demand and feedstock requirements across Colombia's industrial corridor.
- Refineries:Andean facilities are reconfiguring receiving terminals for heavier crude blends, requiring upgraded gathering systems and storage compatibility investments at Barrancabermeja and Cartagena complexes.
- Petrochemicals:Manufacturing clusters near Barrancabermeja pull natural gas distribution networks toward specific industrial zones, creating dedicated offtake corridors with long-term volume commitments.
- Power Plants:Gas-fired generation assets anchor baseload demand for processed natural gas from Llanos Basin recovery projects.
- Industrials:Cement and steel producers consume pipeline-delivered fuels for process heat applications.
Volume placements concentrate in Refineries; the fastest share gain belongs to Petrochemicals.
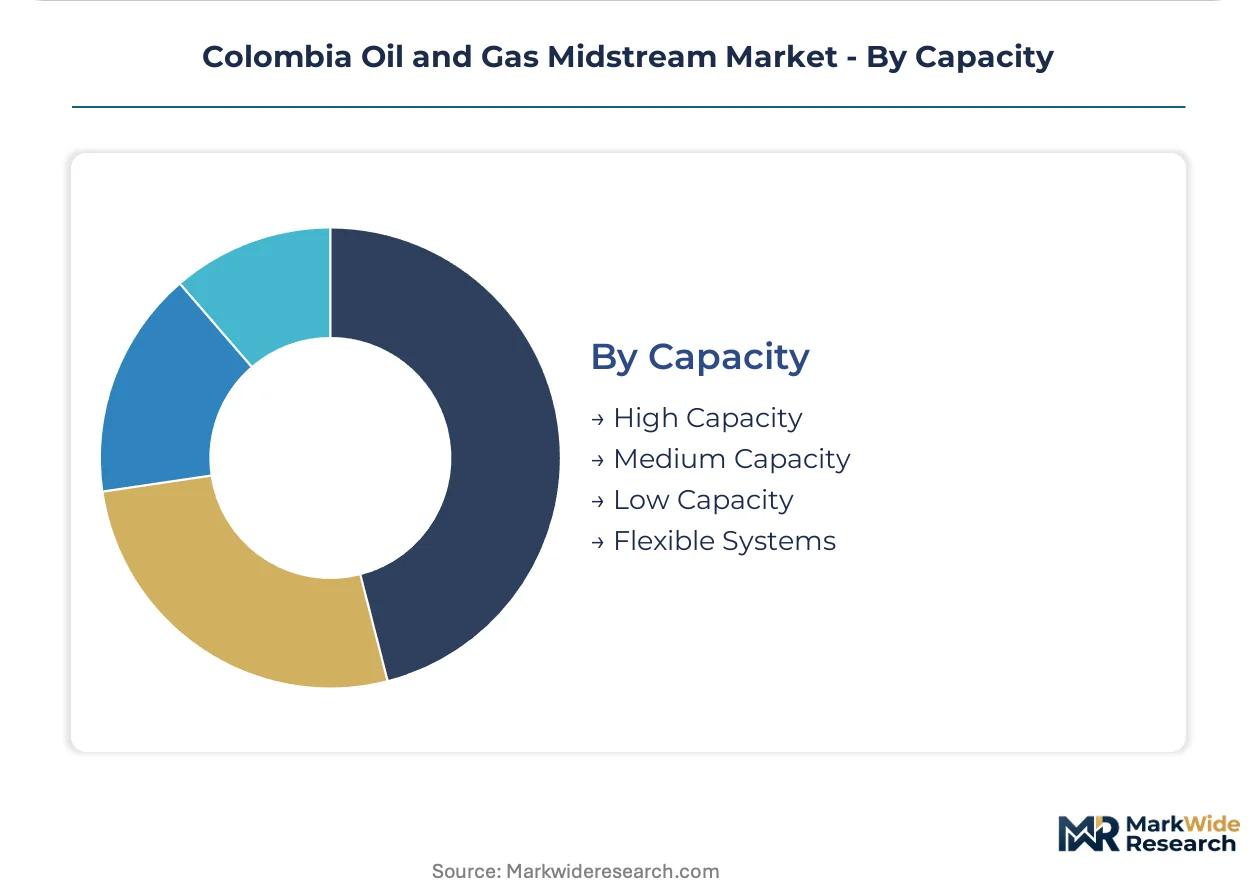
Capacity:
Customer type stratification separates national trunkline operators from basin-specific gathering specialists serving single-source fields.
- High Capacity:Trunkline systems exceeding 200,000 barrels per day move consolidated production from multiple fields to coastal export points. Ecopetrol controls the majority of this tier across Magdalena River corridors.
- Medium Capacity:Regional gathering networks connect mature basin production to mainline injection points with moderate throughput requirements.
- Low Capacity:Single-field tie-ins serve exploratory wells and marginal production zones with intermittent flow profiles.
- Flexible Systems:Modular processing units adapt to variable associated gas yields from heavy oil operations.
Volume placements concentrate in High Capacity; the fastest capacity additions belong to Flexible Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barrancabermeja anchors Colombia's midstream infrastructure as the historic refining and petrochemical hub where pipeline networks converge with heavy crude processing capacity and industrial gas demand clusters.
Llanos Basin
Associated gas recovery from heavy oil fields drives processing plant construction across Meta and Casanare departments. ANLA's wetland protection protocols restrict new pipeline corridors, forcing operators to densify existing gathering networks rather than build greenfield routes. Villavicencio serves as the logistics coordination point for crude consolidation before Magdalena valley trunkline injection.
Magdalena River Valley
Trunkline capacity expansion concentrates along Ecopetrol-controlled corridors connecting interior production to Caribbean export terminals. The Ministry of Mines and Energy's environmental licensing tightens approval timelines for any new Andean crossings. Barrancabermeja refineries anchor demand for heavier crude blend compatibility upgrades and storage terminal investments.
Caribbean Coast
Coastal loading facilities integrate vessel scheduling with pipeline receipts for international trading houses seeking guaranteed lifting schedules. The Superintendency of Industry and Commerce monitors export terminal tariffs under regulated pricing frameworks. Cartagena's refining complex drives specialized storage requirements for intermediate crude grades bound for international markets.
Andean Foothills
Mature basin production decline threatens long-term volume commitments needed to justify trunkline maintenance investments across Boyacá and Santander departments. ANLA's buffer zone rehabilitation mandates extend environmental compliance costs for any corridor upgrades. Cúcuta border logistics face cross-border pipeline integration challenges with Venezuelan infrastructure.
Colombia Oil and Gas Midstream Market Competitive Environment
Capital-heavy pipeline operators compete with asset-light logistics specialists for contract throughput across Colombia's corridor-based infrastructure tiers. State-backed incumbents control trunkline capacity while private operators specialize in basin-specific gathering and gas distribution networks. Two strategic archetypes dominate: integrated transport-and-storage bundlers capturing refinery procurement consolidation, and modular processing specialists monetizing associated gas recovery mandates. Competitive moves center on brownfield corridor densification to bypass ANLA greenfield restrictions, and digital infrastructure deployment to reduce insurance premiums and downtime costs.
Among state-affiliated infrastructure controllers, Ecopetrol SA exemplifies the integrated bundler archetype through its Magdalena valley trunkline dominance. Cenit Transporte y Logística de Hidrocarburos S.A. occupies a specialized position in crude transport logistics from production fields to coastal terminals. Promigas S.A. E.S.P. anchors the natural gas distribution tier, extending pipeline networks toward industrial demand concentration zones near Barrancabermeja.
| Leading Market Players |
|---|
| Ecopetrol SA |
| Exxon Mobil Corporation |
| Chevron Corporation |
| Shell Colombia SA |
| Cenit Transporte y Logística de Hidrocarburos S.A. |
| Occidental Petroleum Corporation |
| Fluor Corporation |
| Transportadora de Gas Internacional |
| Promigas S.A. E.S.P. |
| Others |
Value Chain & Pricing Dynamics
X-ray qualified pipeline construction crews concentrated in Meta and Casanare departments create labor-cost differentials that widen pricing-tier spreads between premium integrated operators and commodity transporters. The scarcity of specialized welding certification forces project premiums for high-pressure trunkline work, compressing margins for brownfield expansions while insulating tier-one bundlers with captive labor pools.
Pricing Analysis
Throughput-guarantee contracts anchor value-based pricing for coastal export terminals serving international trading houses. Three-tier pricing structure across premium, standard, and economy levels separates integrated transport-and-storage bundlers from pure pipeline operators and marginal single-field tie-ins. Price differentiation rests on leak-detection certification grade and storage terminal scale. Pricing pressure stems from the Superintendency of Industry and Commerce's tariff caps on regulated transport services. Single-source field operators exhibit highest price sensitivity; integrated terminal owners with captive refinery contracts show lowest.
Supply Chain Analysis
Domestic-content mandates under Colombia's Ministry of Mines and Energy procurement rules reshape sourcing toward local cathodic protection system installers and coating applicators. High-grade steel plate draws from Brazil, Mexico, and domestic mills. Specialized valves and compression equipment sources from the United States and Germany. Single-source vulnerability concentrates in cryogenic separation unit components for gas processing plants. Distribution runs through Ecopetrol-controlled Magdalena valley corridors to Caribbean export terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
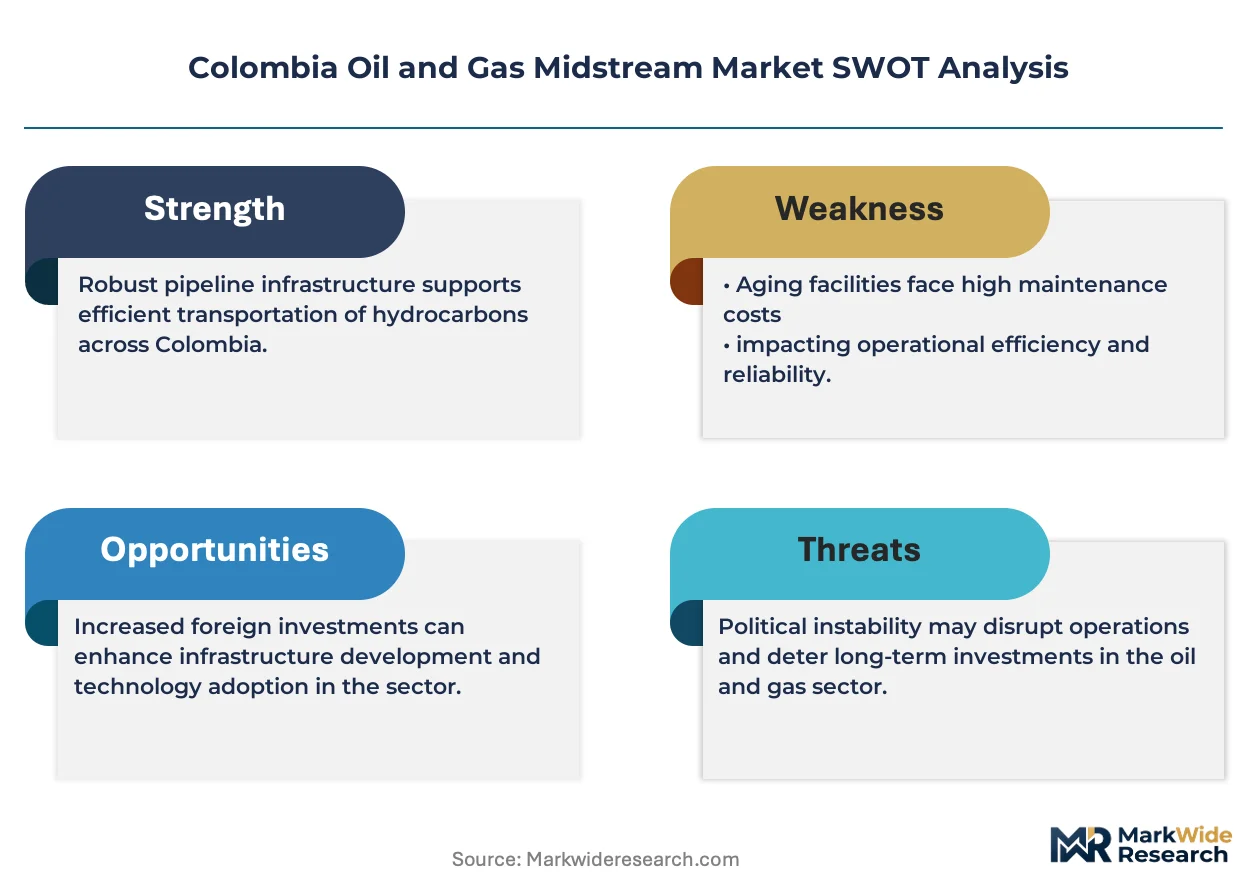
ANLA's wetland protection protocols function as a cost-of-compliance moat, elevating capital requirements for environmental licensing and favoring incumbent operators with established corridor clearances over greenfield entrants.
For Market Incumbents: Deploy digital twin infrastructure to reduce insurance premiums and downtime costs at coastal export terminals. Deepen backward integration into specialized welding certification programs to secure construction crew availability for brownfield expansions. The threat of exploratory decline in mature Andean basins compresses volume commitments needed to justify trunkline maintenance investments.
For New Entrants and Emerging Players: Industrial gas distributors near Barrancabermeja represent the most penetrable white-space target given petrochemical demand clustering and long-term offtake corridor potential. Modular processing specialists can monetize associated gas recovery mandates across Llanos Basin heavy oil fields with lower capital intensity than trunkline builders. A go-to-market angle anchored in carbon capture retrofitting for existing amine-based treatment plants bypasses greenfield regulatory friction.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated transport-and-storage bundlers given refinery procurement consolidation around guaranteed lifting schedules. Long-term viability over a five-to-ten year window favors operators with captive terminal capacity and Magdalena valley corridor density. The acquisition target archetype combines brownfield expansion rights with digital infrastructure deployment capabilities. Watch ANLA licensing velocity as the inflection signal for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Brownfield Corridor Densification | Magdalena valley route expansions bypass ANLA greenfield restrictions while leveraging existing environmental clearances. |
| Digital Twin Deployment | Fiber-optic sensing platforms unify leak detection with satellite telemetry to satisfy enhanced monitoring requirements. |
| Associated Gas Processing Buildout | Amine-based treatment units capture previously vented natural gas under Ministry of Mines flaring regulations. |
| Carbon Capture Retrofit Integration | Processing facilities monetize CO2 streams through low-carbon fuel standard positioning. |
| Specialized Workforce Certification | X-ray qualified crew pipelines secure construction schedules for high-pressure trunkline projects. |
Study Parameters
Regulatory filings from the Ministry of Mines and Energy, ANLA environmental impact assessments, and Superintendency tariff determinations formed the secondary backbone for this analysis. Primary interviews with pipeline operations directors, EPC contractors, refinery procurement managers, and environmental compliance officers at midstream operators triangulated against customs records and infrastructure investment disclosures. Bottom-up capacity modeling across pipeline, storage, and processing segments converged with top-down energy demand projections.
Historical trendline analysis of capital deployment patterns and throughput volumes established baseline growth trajectories across the projection horizon. The analytical framework segmented by product type, technology tier, end-user concentration, and capacity band, with additional modeling of regulatory compliance cost differentials by corridor geography. CAGRs derived from weighted capacity addition schedules and tariff evolution assumptions under the Superintendency's price monitoring framework. Forecast inputs incorporated associated gas recovery mandate timelines and refinery intake reconfiguration capital cycles.
Caveats apply where ANLA licensing delays, exploratory success rates in mature basins, or international crude price volatility could materially shift the outlook. Forecasts reflect assumptions around environmental regulatory continuity and industrial demand clustering persistence near Barrancabermeja. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
North America Oil Country Tubular Goods Market
Oil & Gas
Intelligent Pigging Services Market
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
Well Casing Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
Logging While Drilling (LWD) Market
Oil & Gas
Middle East Natural Gas Market
Oil & Gas
Oil and Gas Refinery Maintenance Services Market
Oil & Gas
Sensors in Oil and Gas Market
Oil & Gas
Wellhead System Market
Oil & Gas
Africa Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Middle East and Africa Coiled Tubing Market