
 Pressure Control Equipment Market | 2026-2036
Pressure Control Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Control Equipment Market Outlook
Deepwater exploration activity is hardening as a priority revenue pool for pressure control suppliers. SLB leverages integrated wellhead systems to sustain offshore contract margins. Baker Hughes Company anchors its position through subsea tree manufacturing scale. Emerson Electric Co. differentiates via electronic control systems that tighten wellhead response times.
Pressure control equipment encompasses valves, blowout preventers, and wellhead assemblies engineered to contain hydrocarbon flows at rated working pressures up to 20,000 psi, typically forged from alloy steels with API 6A compliance for sour service environments. Control valves capture the largest product margin pool due to precision machining requirements and aftermarket parts dependency. Electronic control systems represent the fastest-expanding technology segment as operators replace pneumatic actuation with digitally networked wellhead packages. Choke valves face pricing pressure from standardized trim configurations that commoditize lower-pressure ratings.
API standards, OSHA process safety management rules, and BSEE well control regulations shape product certification timelines and material traceability requirements across the US supply base. The EPA methane emissions rules are forcing retrofit demand for low-leakage valve packing and automated shutdown systems. Stakeholders must weigh captive versus outsourced machining capacity as alloy forging lead times stretch and qualification protocols multiply.
Market Dynamics
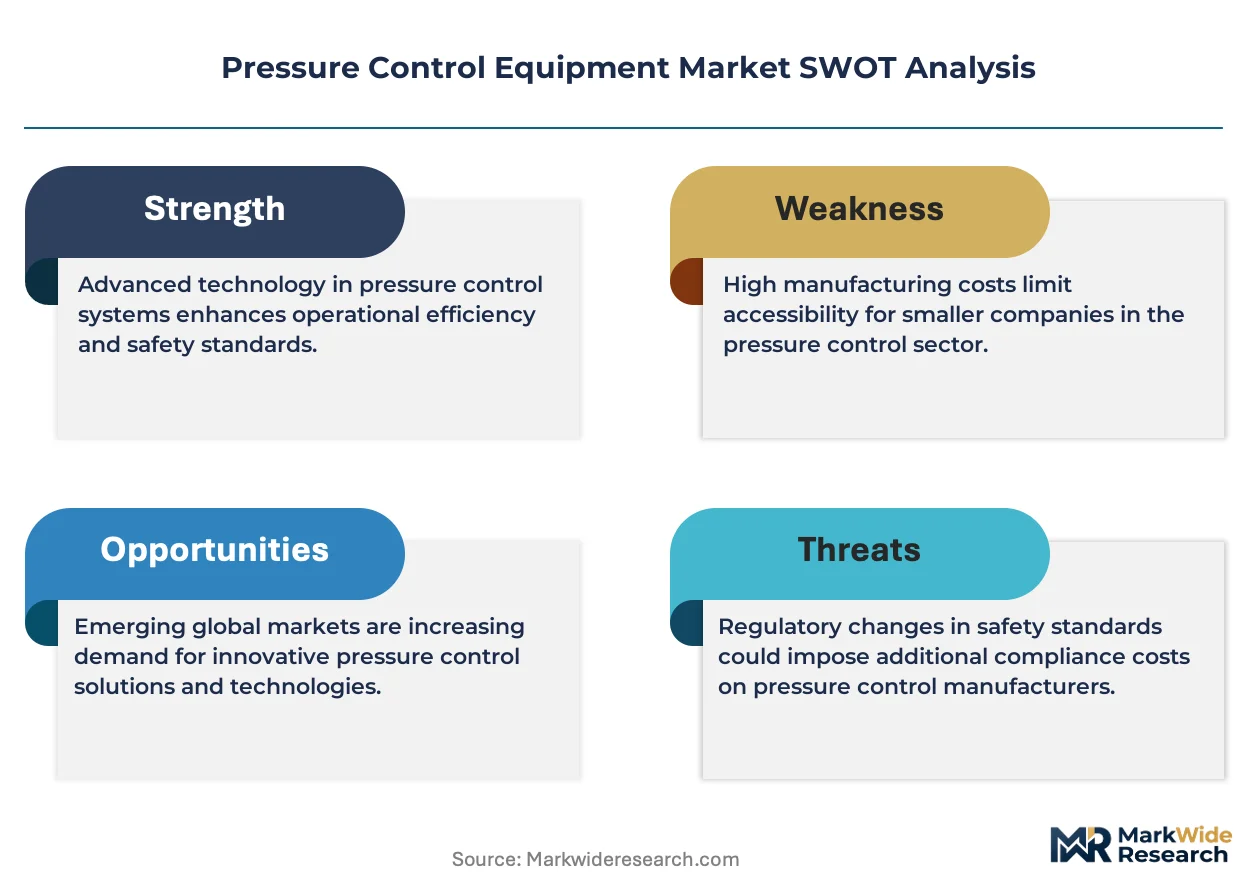
Deepwater operators are automating wellhead response systems to compress blowout prevention timelines, while API 6A material traceability rules are extending qualification cycles for sour service forgings.
Growth Catalysts
- EPA Methane Emissions Rules:Retrofit demand for low-leakage valve packing and automated shutdown systems is accelerating replacement cycles across Permian Basin wellheads.
- Electronic Control Convergence:Digital actuation packages are displacing pneumatic systems, tightening wellhead response times and enabling remote monitoring of subsea trees.
- Gulf Coast Fabrication Clusters:Concentrated demand around Houston and New Orleans is drawing specialized machining capacity and shortening logistics lead times for high-pressure assemblies.
Market Restraints
- Alloy Steel Input Volatility:Nickel and chromium price swings compress margin predictability for forged wellhead components rated above 15,000 psi.
- Subsea Qualification Bottlenecks:API 6A material certification timelines now stretch 18-24 months, freezing supplier qualification pipelines.
- Standardized Trim Commoditization:Lower-pressure choke valve configurations face pricing erosion as offshore procurement teams consolidate specifications.
Strategic Opportunities
- BSEE Well Control Mandates:Strengthened offshore inspection protocols are forcing replacement demand for legacy blowout preventers in deepwater Gulf of Mexico installations.
- Permian Automation White Space:Shale operators expanding wellhead automation programs present captive service contract opportunities for integrated control system vendors.
- Aftermarket Parts Dependency:Control valve precision machining requirements lock operators into long-term spare parts relationships with original equipment manufacturers.
Industry Challenges
- Alloy Forging Lead Time Stretch:Extended mill backlogs for API 6A-qualified sour service materials are forcing fabricators to double inventory carrying costs.
- Pneumatic-to-Digital Integration Complexity:Legacy wellhead infrastructure requires costly retrofit engineering to accept networked electronic control architectures.
- Material Traceability Documentation Burden:Multiplier protocols for subsea certification are consuming engineering resources and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Control Equipment Market |
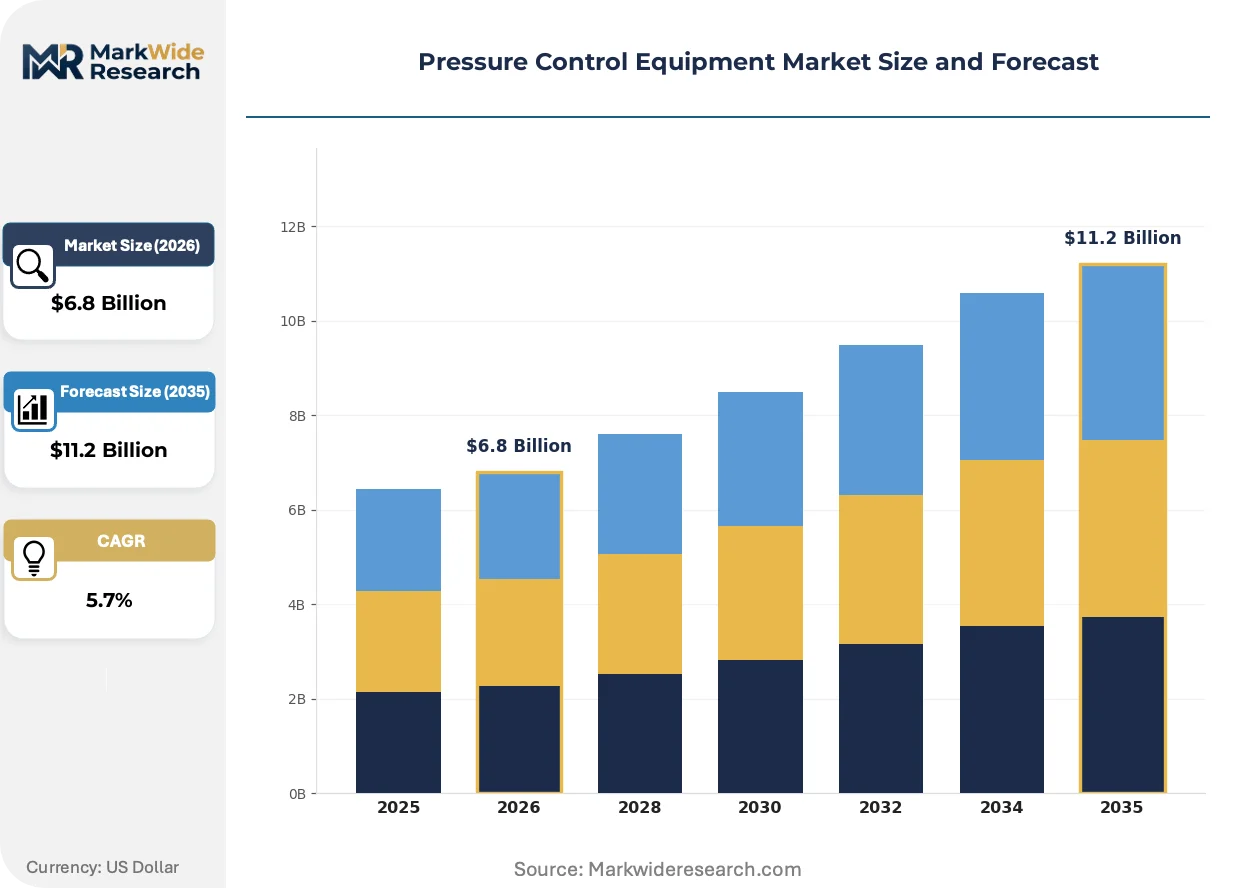
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Relief Valves, Control Valves, Surge Relief Valves, Choke Valves Application: Oil & Gas, Power Generation, Chemical Processing, Water Management End User: Utilities, Petrochemical Industries, Manufacturing, Mining Technology: Mechanical Systems, Electronic Control Systems, Hydraulic Systems, Pneumatic Systems |
| Companies Covered | Weatherford International, Emerson Electric Co., SLB, Flowserve Corporation, Schlumberger Ltd., Baker Hughes Company, NOV Inc, ABB Ltd, Halliburton Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Control Equipment Market Strategic Shifts
Digitalization of wellhead control architectures is compressing emergency response timelines while regulatory tightening around methane leakage is forcing hardware redesign cycles across offshore and onshore installations.
Electronic control systems are automating wellhead valve sequencing through digitally networked actuation packages that replace pneumatic infrastructure. Shale operators in the Permian Basin are deploying these systems at scale to enable remote pressure management during fracturing operations. The technology is automating emergency shutdown protocols and reducing manual intervention requirements in high-pressure sour gas environments.
BSEE well control regulations are mandating redundant barrier verification for deepwater blowout preventers, forcing suppliers to engineer dual-shear ram configurations. This industrial consequence extends factory acceptance testing timelines and raises capital intensity for subsea tree manufacturing. Gulf of Mexico operators are responding by consolidating procurement around qualified suppliers with established BSEE inspection track records.
Integrated service contracting is displacing discrete equipment purchasing as operators seek single-source accountability for wellhead performance. Offshore project teams are bundling control system installation with long-term maintenance agreements, compressing traditional equipment-only vendor relationships. This shift is most visible in deepwater developments where penalty clauses for non-productive time dominate commercial negotiations.
Pressure Control Equipment Market Segmentation
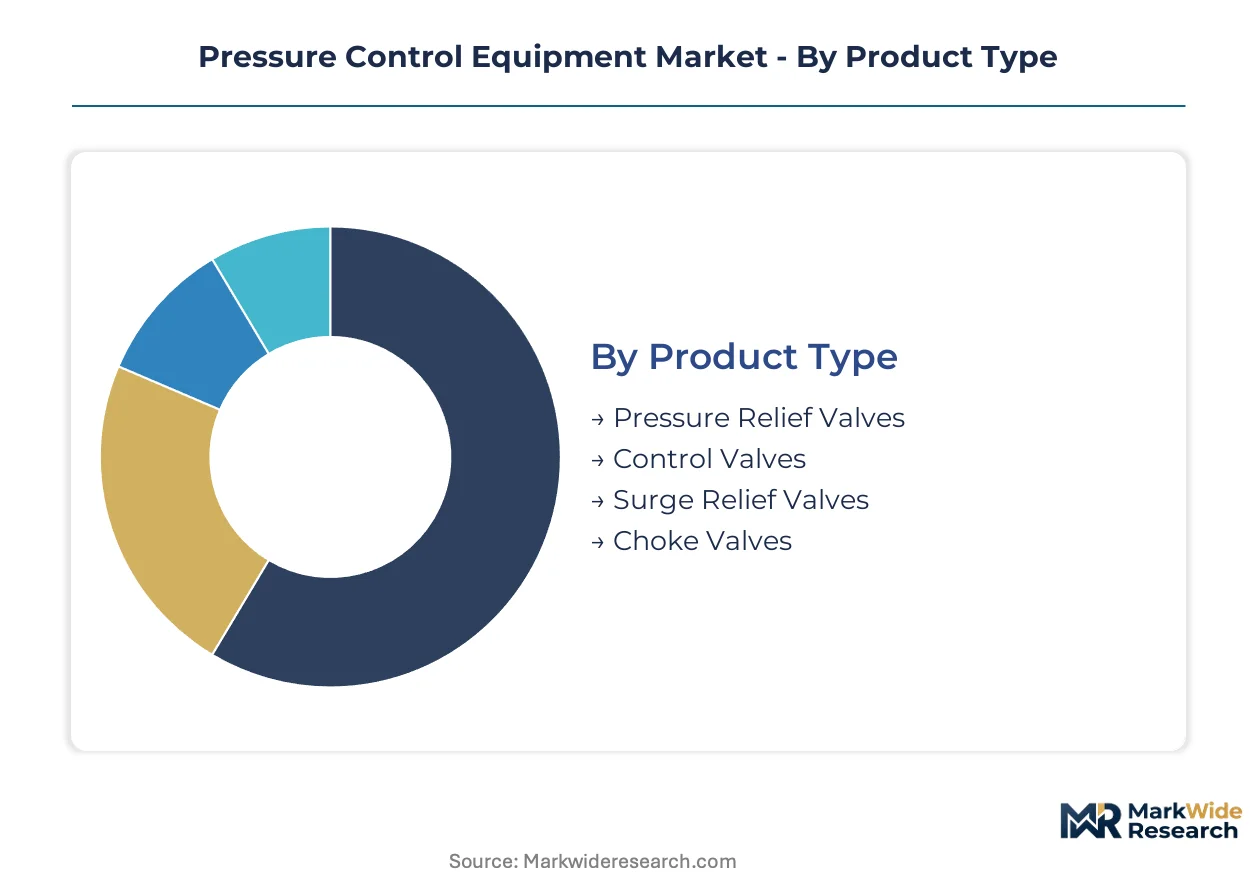
Segmentation in pressure control equipment reveals divergent margin structures across product architectures and automation maturity levels. Equipment specifications fragment sharply between high-pressure sour service applications and standardized onshore configurations.
Product Type:
Control valves command premium positioning through precision machining complexity, while pressure relief valves anchor volume throughput across refinery and upstream installations.
- Control Valves:Precision-machined trim configurations with API 6A sour service ratings demand tight tolerance manufacturing and generate substantial aftermarket parts dependency. Permian Basin shale operators are consolidating procurement around electronically actuated variants to enable remote pressure management during fracturing operations.
- Pressure Relief Valves:Spring-loaded and pilot-operated designs rated up to 20,000 psi protect vessel integrity across downstream processing facilities. Gulf Coast refinery clusters around Houston and New Orleans sustain replacement demand cycles driven by EPA methane emissions compliance deadlines.
- Surge Relief Valves:Rapid-response piston or bladder designs mitigate water hammer in pipeline transmission networks.
- Choke Valves:Standardized trim configurations below 10,000 psi face commoditization pressure from consolidated offshore procurement specifications.
Today's leader: Control Valves. Tomorrow's challenger: Surge Relief Valves.
Application:
Upstream hydrocarbon extraction concentrates specification complexity, while power generation standardization enables manufacturing scale economies.
- Oil & Gas:Subsea tree assemblies and wellhead systems rated for 15,000-20,000 psi working pressure require alloy steel forgings with full material traceability documentation. BSEE well control mandates are forcing replacement demand for legacy blowout preventers across deepwater Gulf of Mexico installations.
- Chemical Processing:Corrosion-resistant trim materials and tight shutoff classifications address aggressive media handling in sulfur recovery and ethylene cracking units.
- Power Generation:Steam conditioning and turbine bypass valves serve combined-cycle and thermal plant configurations with standardized ASME pressure-temperature ratings.
- Water Management:Pressure reducing and sustaining valves regulate distribution network hydraulics with lower metallurgical complexity than hydrocarbon service.
Upstream hydrocarbon applications retain margin leadership. Water infrastructure represents the steepest expansion trajectory as municipal investment accelerates.
End User:
Petrochemical operators drive specification stringency, while utility procurement emphasizes lifecycle cost over initial capital outlay.
- Petrochemical Industries:Ethylene crackers and aromatics complexes demand high-cycle reliability from control valve trim exposed to thermal shock and polymerizing media.
- Utilities:Electric power and water distribution operators prioritize predictive maintenance integration and standardized spare parts interoperability across plant fleets.
- Manufacturing:Compressed air systems and process steam networks utilize commodity-rated pressure control with shorter replacement cycles.
- Mining:Slurry handling and tailings management applications require hardened trim configurations resisting abrasive wear.
Petrochemical Industries dominate premium specification demand. Utilities are gaining procurement leverage through consolidated fleet management programs.
Technology:
Electronic architectures are displacing legacy actuation, though pneumatic infrastructure retains installed base inertia across brownfield installations.
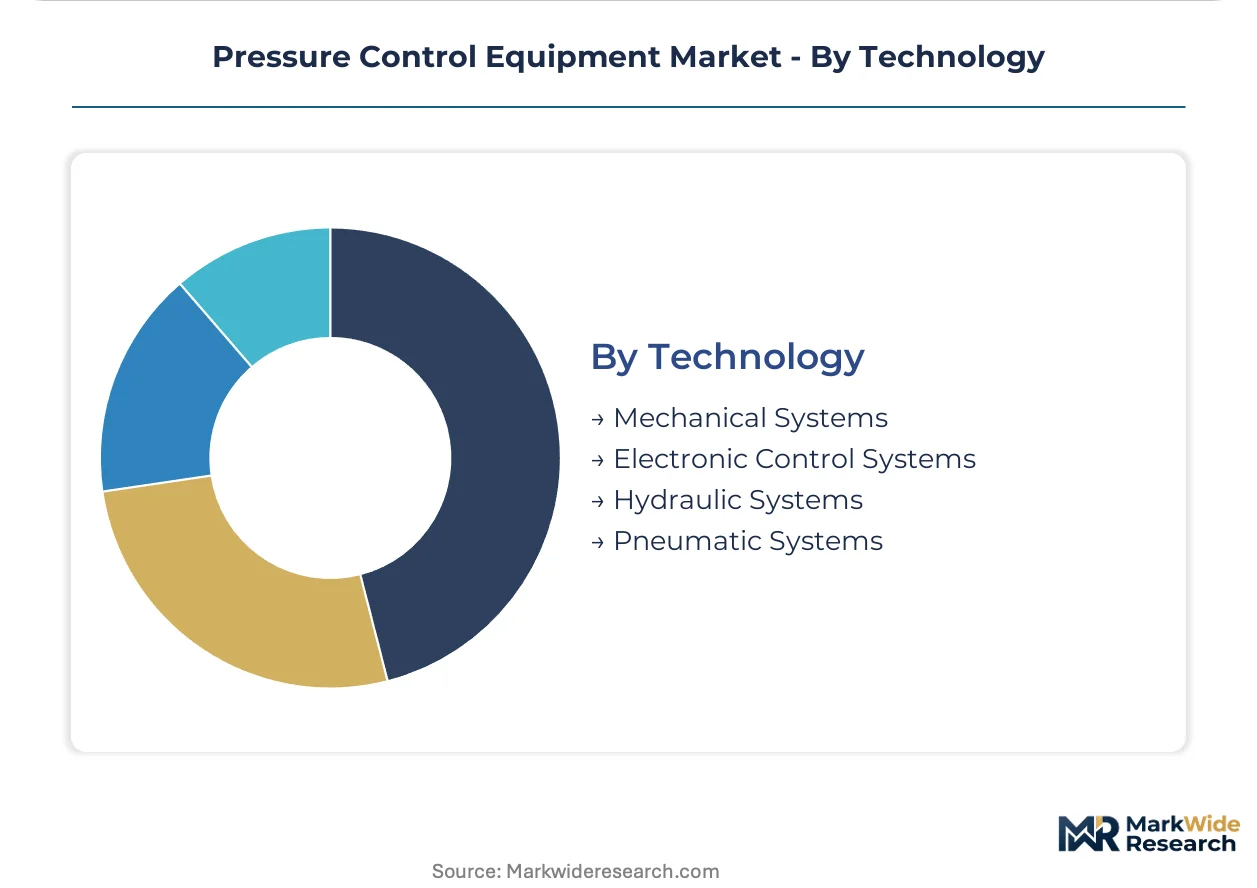
- Electronic Control Systems:Digitally networked actuation packages with position feedback and diagnostic telemetry enable subsea tree monitoring without intervention vessels. Shale operators are deploying these systems at scale to compress emergency shutdown response timelines.
- Pneumatic Systems:Compressed air actuation persists in explosive atmosphere zones where intrinsic safety certification simplifies compliance, though integration with digital control networks requires costly retrofit engineering.
- Hydraulic Systems:High-force actuation for subsea blowout preventer rams operates at depths exceeding electronic pressure ratings.
- Mechanical Systems:Spring-loaded and weight-loaded relief mechanisms provide fail-safe protection independent of external power or signal infrastructure.
Electronic Control Systems are climbing the fastest as operators replace pneumatic infrastructure. Mechanical Systems defend position in safety-critical fail-safe applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping fabrication location decisions as API 6A certification timelines and material traceability burdens vary across jurisdictions. Suppliers are migrating qualified machining capacity toward Gulf Coast clusters where EPA, BSEE, and OSHA requirements create compliance density economies.
United States
Deepwater Gulf of Mexico developments and Permian Basin shale automation are driving specification intensity for subsea trees and wellhead systems. BSEE well control mandates are forcing replacement cycles for legacy blowout preventers. Houston anchors the dominant fabrication cluster, drawing specialized alloy forging capacity from across the domestic supply base.
Brazil
Pre-salt field developments are concentrating demand for high-pressure subsea equipment rated above 15,000 psi. ANVISA and ANP regulations govern equipment import certification and local content requirements. Rio de Janeiro and São Paulo host the primary engineering and procurement centers serving Petrobras-led deepwater projects.
Norway
North Sea decommissioning timelines and electrification of offshore platforms are creating dual demand streams for replacement equipment and modified control systems. Petroleum Safety Authority Norway enforces barrier management regulations that exceed baseline API standards. Stavanger and Bergen concentrate subsea engineering competence and supplier qualification activity.
China
Domestic deepwater exploration in the South China Sea and shale gas development in Sichuan are expanding local specification demand. NMPA and MIIT standards are converging toward API 6A alignment while retaining national certification requirements. Shanghai and Shenzhen fabrication yards are building subsea tree manufacturing capability for regional supply.
United Arab Emirates
Adnoc's sour gas expansion and offshore field redevelopment are concentrating procurement for sour service-rated wellhead assemblies. MOHAP and ADNOC technical specifications govern material traceability and qualification protocols. Abu Dhabi and Dubai serve as the primary logistics hubs for Middle East and North Africa project execution.
Pressure Control Equipment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated service providers capturing deepwater project bundles while component specialists defend aftermarket parts relationships. The vendor base organizes into three tiers: full-system integrators with BSEE qualification track records, precision machining houses focused on control valve trim, and regional fabricators serving standardized onshore configurations. Consolidation pressure is intensifying as alloy forging lead times stretch and API 6A certification costs rise. Strategic moves center on captive machining capacity expansion and integrated service contracting to lock in multi-year maintenance agreements.
Among the integrated system providers, SLB and Baker Hughes Company exemplify the full-service archetype through subsea tree manufacturing scale and offshore contract bundling. Emerson Electric Co. occupies a differentiated position via electronic control system specialization. These three anchors demonstrate how technology convergence and regulatory compliance density are reshaping competitive positioning across deepwater and shale automation segments.
| Leading Market Players |
|---|
| Weatherford International |
| Emerson Electric Co. |
| SLB |
| Flowserve Corporation |
| Schlumberger Ltd. |
| Baker Hughes Company |
| NOV Inc |
| ABB Ltd |
| Halliburton Co. |
| Others |
Value Chain & Pricing Dynamics
Specialized CNC machinists concentrated around Houston and New Orleans command wage premiums that compress margin spreads between premium-tier subsea assemblies and standardized onshore wellhead configurations. Labor-cost differentials across Gulf Coast fabrication clusters directly shape three-tier pricing stratification across API 6A certification grades.
Pricing Analysis
Distributor margins on electronic control systems run 15-25 points above commodity valve trim, reflecting technical support burdens and inventory carrying costs for digitally networked actuation packages. Price differentiation separates sour service-rated forgings with full material traceability from economy-grade onshore configurations lacking subsea qualification. Cost compression in lower-pressure choke valves is intensifying because offshore procurement teams have consolidated specifications around standardized trim. Exploration and production operators exhibit highest price sensitivity on replacement cycles, while deepwater project developers prioritize BSEE qualification track records over unit economics.
Supply Chain Analysis
Alloy steel forging supply rests on domestic US mills with API 6A sour service certification, Japanese specialty steel producers, and select European forging houses with subsea qualification heritage. Critical inputs include nickel-chromium alloy bar stock, precision-machined valve trim, and electronic actuator components. Single-source vulnerability concentrates in qualified sour service material streams where mill backlogs extend qualification timelines. Distribution runs through OEM-direct channels for deepwater projects and distributor networks serving Permian Basin shale automation programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic control system substitution for pneumatic infrastructure creates margin-expansion headroom as software-enabled service contracts displace equipment-only sales. Digital actuation packages command recurring revenue streams that flatten cyclical exposure.
For Market Incumbents: Extend captive machining capacity into alloy forging qualification pipelines to freeze out competitors during 18-24 month API 6A certification windows. Consolidate aftermarket parts relationships through predictive maintenance telemetry that locks operators into OEM service ecosystems. Deepwater project bundling with BSEE inspection track records defends position against emerging Asian fabricators with cost advantages but unproven regulatory compliance density.
For New Entrants and Emerging Players: The $3,000-8,000 per-unit spread between premium electronic actuation and economy pneumatic systems creates entry space for mid-tier digitally retrofitted packages. Target Permian Basin shale automation white space where operators prioritize remote monitoring over full subsea qualification. Pursue captive service contracting models that bypass capital-intensive forging qualification by partnering with established machining houses for hardware supply.
For Investors and Strategic Acquirers: Integrated oilfield service providers are the most active acquirer in this space, seeking electronic control capabilities to complete wellhead system portfolios. Five-to-ten year viability hinges on regulatory compliance density rather than manufacturing scale alone. Acquisition target archetype: precision machining houses with API 6A sour service qualification and established BSEE inspection relationships. Watch EPA methane enforcement intensity as the inflection signal for retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Alloy Forging Capacity Expansion | API 6A qualification timelines reward suppliers with in-house sour service material streams. |
| Electronic Control System Platform Integration | SLB and Emerson Electric Co. leverage digitally networked architectures to compress emergency response timelines. |
| Long-term Maintenance Service Agreements | Integrated contracting displaces equipment-only sales across deepwater Gulf of Mexico developments. |
| Subsea Tree Manufacturing Scale-Up | Baker Hughes Company anchors position through BSEE-qualified production capacity. |
| Joint Venture with Regional Fabricators | Shanghai and Shenzhen yards build subsea capability without full qualification burden. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with wellhead engineering directors, procurement leads at Permian Basin shale operators, subsea project managers at integrated oil companies, and aftermarket service heads at OEMs with secondary validation against API certification databases, BSEE incident reports, EPA enforcement disclosures, and SEC filings from publicly traded equipment suppliers. Bottom-up segment sizing and top-down market reconciliation triangulated volume and value estimates.
Segment-weighting applied product type, application, end user, and technology dimensions across the projection horizon, with control valve precision machining complexity and electronic control system displacement rates as industry-specific demand drivers. CAGRs derived from fitted growth curves calibrated to regulatory mandate timelines and replacement cycle acceleration patterns.
Caveats apply where EPA methane rule enforcement intensity, alloy steel price volatility, or BSEE qualification protocol changes could materially shift the outlook. Forecasts embed assumptions around electronic control adoption curves and sour service material availability. A small set of named triggers—regulatory enforcement cadence, mill qualification backlog duration, and deepwater project sanctioning velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Solenoid Valves Market
Valves
Transmission Overload Protectors Market
Valves
Air Jet Ejectors Market
Valves
Electronic Expansion Valves Market
Valves
Pipeline and Process Services Market
Valves
Global Flow Control Market
Valves
Insulation Flanges Market
Valves
Mechanical Shaft Seal Market
Valves
Three Way Ball Valve Market
Valves
Large Bore Vacuum Insulated Pipe Market
Valves
Expansion Valves Market
Valves
Global Plug Valve Market
Valves
Valve Manifold Box (VMB) Market
Valves
Hot Blast Valves Market
Valves
Valve Grinder Market
Valves
Global Pipeline Safety Market