
 Chad Oil and Gas Market | 2026-2036
Chad Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Chad Oil and Gas Market Outlook
Synthetic drilling fluids are pivoting toward bio-based alternatives as operators cut waste disposal costs in environmentally sensitive concessions. Chevron Corporation leverages its integrated supply chain to source mud systems across West African logistics networks. Société des Hydrocarbures du Tchad anchors state equity positions in all production sharing contracts. China National Petroleum Corporation dominates drilling activity in the Ronier and Mimosa fields through its capital-intensive development program.
Chad oil and gas encompasses crude petroleum extraction, natural gas processing, and refined product distribution from onshore sedimentary basins with API gravities ranging from 18° to 33° across heavy-to-light crude blends. The sector feeds regional power generation, export markets via the Chad-Cameroon Pipeline, and limited domestic refining at the N'Djamena facility. Upstream activity leads value creation due to capital intensity and reserve scale, while midstream infrastructure exhibits structural bottlenecks around pipeline capacity and storage availability. Service Providers represent the fastest-growing segment as international contractors deploy enhanced oil recovery and seismic imaging technologies to stem decline rates in mature Doba Basin fields.
Chad's Ministry of Petroleum and Energy administers production sharing contracts under the Hydrocarbons Code, while the country's environmental regulator enforces waste management standards aligned with OHADA business law frameworks. These rules shape operator cost structures through local content mandates and environmental bonding requirements. Stakeholders must monitor fiscal term negotiations and infrastructure access priorities as the state seeks to maximize rent capture from depleting reserves.
Market Dynamics
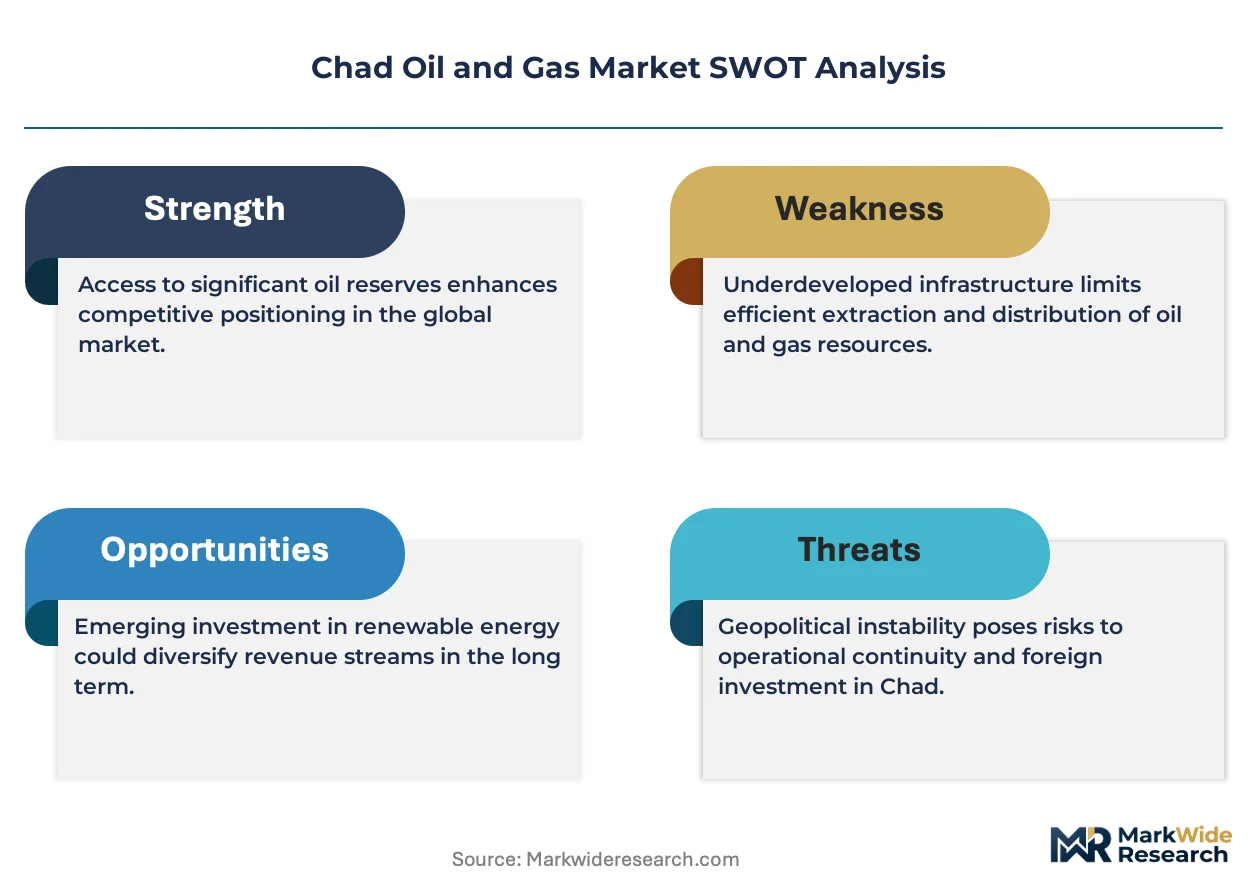
Chad's national hydrocarbon code revisions are compressing operator margins while simultaneously accelerating domestic power generation offtake from Doba Basin fields. This regulatory recalibration is redistributing rent capture between international operators and state equity holders.
Growth Catalysts
- Domestic power generation utilities:State-owned electricity providers are expanding contracted volumes from onshore fields, creating guaranteed demand basins for heavy crude blends previously destined solely for export.
- Enhanced oil recovery deployment:International service contractors are injecting polymer and thermal recovery systems into mature Doba Basin reservoirs to counter natural decline rates and extend field life.
- Chad-Cameroon Pipeline capacity optimization:Midstream infrastructure investments are unlocking stranded reserves in the Ronier and Mimosa fields through debottlenecking of terminal and pumping station throughput.
Market Restraints
- Fiscal term volatility:Hydrocarbons Code amendments are introducing royalty escalators and profit oil splits that compress project economics for capital-intensive deep drilling programs.
- Single-export corridor concentration:Near-total dependence on the Chad-Cameroon Pipeline creates structural vulnerability to transit disruptions, piracy risk in the Gulf of Guinea, and Cameroonian terminal bottlenecks.
- Heavy crude quality discount:API gravities below 25° in southern fields force price concessions versus Brent benchmarks, eroding netbacks for operators without blending infrastructure.
Strategic Opportunities
- Seismic imaging technology convergence:Integration of 4D time-lapse surveys with machine learning interpretation is identifying bypassed pay zones in legacy Doba Basin production corridors.
- N'Djamena refinery expansion:Limited domestic refining capacity creates white space for modular topping unit investments to capture margin currently lost to product imports.
- OHADA business law alignment:Regional commercial code harmonization is streamlining cross-border service procurement and equipment leasing across Central African operator networks.
Industry Challenges
- Specialized drilling fluid chemist scarcity:Local labor pools lack expertise in formulating synthetic and bio-based mud systems for high-temperature, high-pressure carbonate formations.
- Environmental bonding complexity:Waste management standards under OHADA frameworks require upfront cash collateral that strains working capital for exploration-phase operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chad Oil and Gas Market |
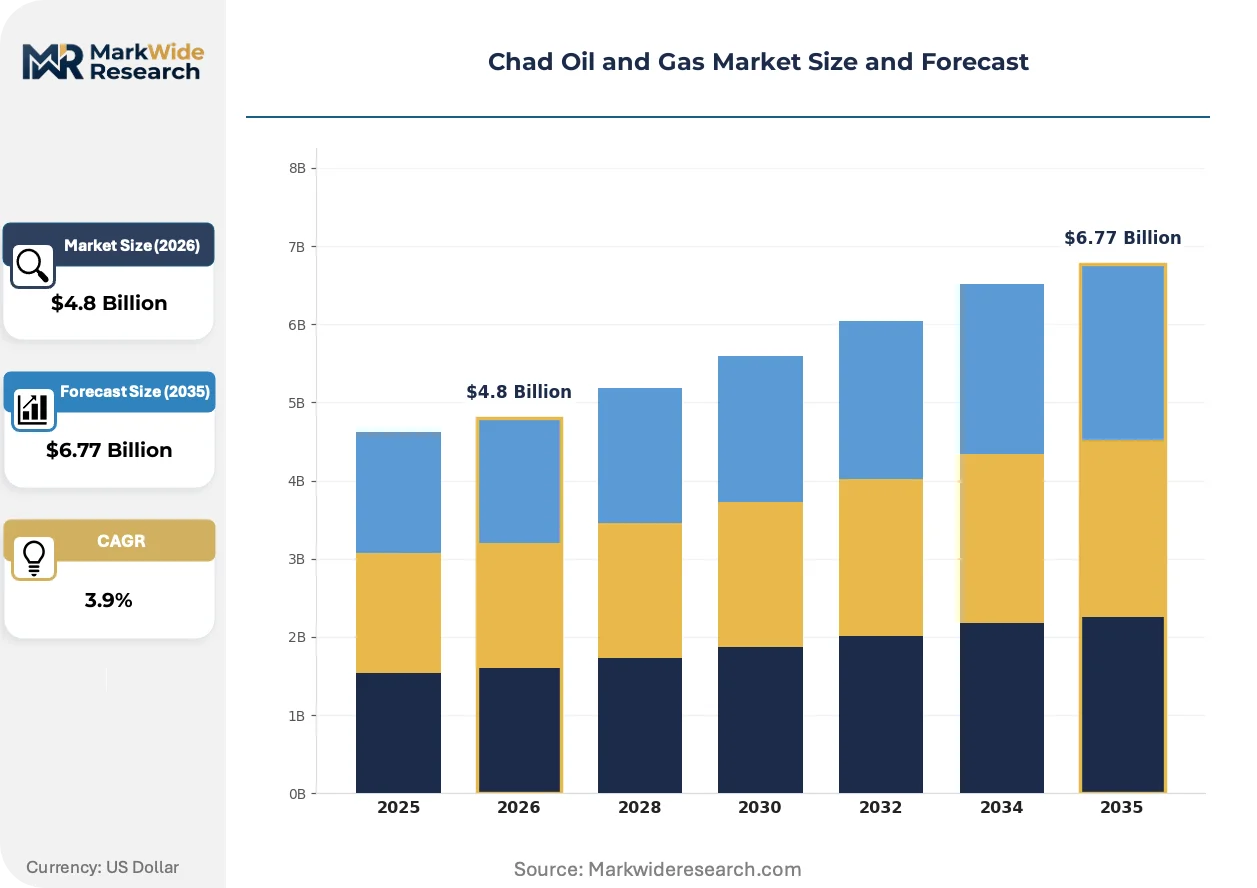
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Upstream, Midstream, Downstream, Service Providers Application: Exploration, Production, Refining, Distribution Technology: Enhanced Oil Recovery, Hydraulic Fracturing, Seismic Imaging, Thermal Recovery End User: Power Generation, Manufacturing, Transportation, Petrochemical |
| Companies Covered | Chevron Corporation, Société des Hydrocarbures du Tchad, China National Petroleum Corporation, Petroliam Nasional Berhad, Delonex Energy Limited, Exxon Mobil Corporation, Glencore PLC, Savannah Energy PLC, Total SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chad Oil and Gas Market Strategic Shifts
Technology adoption in Chad's oil and gas sector is accelerating around modular, capital-efficient systems that reduce upfront exposure in a fiscally uncertain operating environment. Operators are prioritizing solutions that compress project timelines and limit stranded asset risk.
Advanced wellhead monitoring systems are modularizing field architecture across the Doba Basin. These integrated sensor packages enable remote pressure and flow surveillance without permanent facility construction. International operators are deploying them in marginal fields previously deemed sub-economic. The technology is modularizing investment decisions, allowing phased commitments that match expenditure to proven production rates.
Chad's Ministry of Petroleum and Energy is enforcing revised local content mandates under the Hydrocarbon Code that require minimum percentages of national labor and services in all production sharing contracts. This regulatory pressure is redirecting procurement toward domestic subcontractors and joint ventures with Société des Hydrocarbures du Tchad. Drilling and well service segments are most affected, with operators restructuring supply chains to achieve compliance thresholds.
Power generation utilities are consolidating offtake negotiations through centralized procurement desks rather than field-by-field contracting. This buyer concentration is compressing pricing leverage for crude sellers and favoring long-term supply agreements over spot market exposure. The shift is most visible in N'Djamena, where the national utility is aggregating demand from multiple Doba Basin producers to secure volume discounts and supply security guarantees.
Chad Oil and Gas Market Segmentation

Segmentation in Chad's oil and gas sector reveals how capital allocation, technology deployment, and end-use demand concentrate across distinct operational layers. Each dimension carries unique risk-return profiles shaped by the country's single-export corridor structure and state equity requirements.
Type:
Capital intensity varies dramatically across operational layers, with upstream development requiring multi-billion dollar field commitments while service functions deploy modular, scalable assets.
- Upstream:Crude petroleum extraction from onshore Doba Basin and Ronier fields demands extensive drilling programs, reservoir management systems, and production facility construction. Société des Hydrocarbures du Tchad holds mandatory state equity in all production sharing contracts, compressing operator working interest economics. Heavy crude characteristics below 25° API force quality discounts versus international benchmarks.
- Service Providers:International contractors supply drilling fluids, well completion services, and enhanced oil recovery technologies to stem decline rates in mature fields. This segment exhibits the steepest expansion trajectory as operators outsource specialized functions to manage fiscal uncertainty under revised Hydrocarbons Code terms.
- Midstream:Pipeline transportation, storage terminals, and the Chad-Cameroon export corridor handle nearly all production volume. Structural bottlenecks around pumping station capacity and marine terminal throughput constrain field development timing.
- Downstream:Limited domestic refining at the N'Djamena facility and product distribution networks serve narrow local demand. Import dependency for refined products creates margin capture opportunities for modular topping unit investments.
Upstream absorbs the bulk of installed capacity; Service Providers is expanding most quickly.
Application:
Activity sequencing across the value chain determines capital deployment timing, with exploration-phase exposure carrying the highest regulatory and geological risk.
- Production:Sustained extraction from Doba Basin fields including Mimosa and Ronier generates the majority of national hydrocarbon revenue. China National Petroleum Corporation operates the most extensive production infrastructure through its capital-intensive development program.
- Exploration:Seismic surveying and wildcat drilling in frontier basins targets reserve replacement as mature fields deplete. Environmental bonding requirements under OHADA-aligned waste management standards strain working capital for pre-revenue operators.
- Refining:The N'Djamena facility processes limited domestic crude volumes into transportation fuels and power generation feedstocks. Capacity constraints force reliance on imported refined products for unmet demand.
- Distribution:Product logistics networks connect the single refinery to regional consumption centers. Pipeline and trucking infrastructure exhibits coverage gaps in southern production corridors.
Production dominates current revenue generation; Exploration carries the highest risk-adjusted return potential.
Technology:
Technology selection reflects reservoir characteristics and economic constraints, with thermal and chemical methods targeting heavy crude recovery challenges.
- Enhanced Oil Recovery:Polymer injection and chemical flooding systems counter natural decline in mature Doba Basin reservoirs. International service contractors deploy these technologies under long-term performance contracts.
- Seismic Imaging:Four-dimensional time-lapse surveys integrated with machine learning interpretation identify bypassed pay zones in legacy production corridors. This capability is gaining share fastest as operators target incremental barrels without new field development.
- Thermal Recovery:Steam and in-situ combustion methods address viscosity challenges in heavy crude formations. High capital and energy intensity limit deployment to the most productive reservoir zones.
- Hydraulic Fracturing:Limited application in Chad's conventional carbonate and sandstone reservoirs compared to unconventional shale plays elsewhere. Occasional use in tight formation zones requires specialized proppant logistics.
Enhanced Oil Recovery commands the largest technology budget; Seismic Imaging is climbing the fastest.
End User:
Demand concentration patterns reveal how domestic offtake obligations and export commitments compete for limited production volumes.
- Power Generation:State-owned electricity utilities are expanding contracted volumes from Doba Basin fields under centralized procurement arrangements. This demand segment provides guaranteed offtake for heavy crude blends previously destined solely for export.
- Transportation:Refined product consumption for road and aviation fuels depends on import supply chains due to domestic refining limitations. N'Djamena's vehicle fleet and airport operations represent the primary demand nodes.
- Manufacturing:Industrial heat and power requirements from cement, food processing, and construction materials sectors absorb limited direct crude and fuel oil volumes. Scattered demand across small-scale facilities complicates supply logistics.
- Petrochemical:Minimal downstream chemical processing infrastructure exists; potential feedstock supply awaits development of olefins or aromatics capacity. White space for future investment contingent on reserve scale and fiscal stability.
Power Generation secures the largest dedicated offtake volumes; Transportation demand is expanding most quickly with urbanization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power generation utilities across Central Africa are consolidating offtake negotiations through centralized procurement desks, redirecting crude flows from export corridors toward domestic energy security priorities.
Doba Basin Production Corridor
The Doba Basin anchors Chad's hydrocarbon output through the Mimosa and Ronier fields where China National Petroleum Corporation operates extensive production infrastructure. The Ministry of Petroleum and Energy administers production sharing contracts with mandatory state equity participation through Société des Hydrocarbures du Tchad. Drilling activity concentrates around enhanced oil recovery deployments to counter natural decline rates in mature reservoirs.
N'Djamena Industrial Zone
N'Djamena's limited refining capacity at the national facility processes domestic crude into transportation fuels and power generation feedstocks. The national utility aggregates demand from multiple basin producers to secure volume discounts and supply security guarantees. Import dependency for refined products creates margin capture opportunities for modular topping unit investments.
Chad-Cameroon Pipeline Transit Zone
The single-export corridor handles nearly all production volume through pipeline transportation and marine terminal operations at Kribi. Structural bottlenecks around pumping station capacity constrain field development timing for new reserve commitments. Transit disruptions or Cameroonian terminal congestion create systemic vulnerability for operator revenue realization.
Southern Heavy Crude Fields
Fields producing API gravities below 25° force quality discounts versus Brent benchmarks without blending infrastructure investments. Chevron Corporation leverages integrated supply chain networks to source mud systems across West African logistics corridors. Environmental bonding requirements under OHADA-aligned waste management standards strain working capital for exploration-phase operators in this region.
Chad Oil and Gas Market Competitive Environment
State equity participation dominates the current landscape through mandatory production sharing contract requirements that compress international operator working interest economics. The market structure concentrates around three strategic archetypes: integrated multinational majors with capital-intensive development programs, national oil companies holding state equity positions, and specialized service contractors deploying enhanced recovery technologies. Competitive positioning hinges on fiscal term negotiations with the Ministry of Petroleum and Energy and infrastructure access priorities along the single-export corridor.
Among integrated multinational operators, Chevron Corporation and Exxon Mobil Corporation represent the capital-deploying tier with integrated supply chain capabilities across West African logistics networks. China National Petroleum Corporation anchors the state-affiliated international category through its dominant drilling activity in the Ronier and Mimosa fields. Société des Hydrocarbures du Tchad occupies the mandatory state equity position in all production sharing contracts, exemplifying the national champion archetype that redistributes rent capture between international operators and government stakeholders.
| Leading Market Players |
|---|
| Chevron Corporation |
| Société des Hydrocarbures du Tchad |
| China National Petroleum Corporation |
| Petroliam Nasional Berhad |
| Delonex Energy Limited |
| Exxon Mobil Corporation |
| Glencore PLC |
| Savannah Energy PLC |
| Total SA |
| Others |
Value Chain & Pricing Dynamics
Centralized procurement desks at state-owned electricity utilities anchor pricing power in Chad's oil and gas market, compressing netbacks for producers through aggregated volume negotiations and long-term offtake agreements that displace spot market exposure.
Pricing Analysis
Volume commitments versus margin capture split along crude quality lines. Heavy crude blends below 25° API trade at structural discounts to Brent benchmarks, while lighter grades command modest premiums. Price differentiation hinges on blending infrastructure access and domestic power generation contract terms. Cost compression in heavy crude tiers intensifies as fiscal code revisions escalate royalty obligations, making state-backed offtake the least price-sensitive demand segment and export spot markets the most vulnerable.
Supply Chain Analysis
OHADA-aligned waste management certifications gate entry for drilling fluid and well service contractors operating in Chad's production corridors. Equipment and specialized chemicals draw from United Arab Emirates logistics hubs, Chinese manufacturing centers, and European technical suppliers. Synthetic mud systems and high-pressure wellhead components feed from these three source markets. Single-export corridor vulnerability concentrates risk around Chad-Cameroon Pipeline transit disruptions. Distribution runs through Société des Hydrocarbures du Tchad joint ventures and international operator procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chad's oil and gas sector sits at a technology-transition inflection as seismic imaging systems displace conventional exploration methods, rewarding operators who deploy machine-learning-interpreted 4D surveys to identify bypassed pay zones without greenfield drilling exposure.
For Market Incumbents: Anticipate fiscal term volatility by restructuring production sharing contracts to front-load cost recovery phases before royalty escalators trigger. Secure pipeline capacity reservations through Chad-Cameroon Pipeline terminal access agreements. Backward integration into modular wellhead monitoring systems reduces stranded asset risk in marginal fields.
For New Entrants and Emerging Players: Digital procurement platforms connecting domestic subcontractors to international operators offer the most penetrable entry vector. Target enhanced oil recovery service contracts in mature Doba Basin fields where decline rates demand polymer and thermal injection expertise. Partner with Société des Hydrocarbures du Tchad on local content compliance to bypass direct PSC equity barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized service contractors with proven thermal recovery capabilities in southern heavy crude fields. Long-term viability rests on reserve replacement economics rather than exploration upside. Watch for Hydrocarbons Code stabilization signals as the inflection trigger for capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Oil Recovery Deployment | Polymer injection contracts with CNPC extend Mimosa field life against natural decline rates. |
| Seismic Imaging Technology Licensing | 4D time-lapse survey integration unlocks bypassed reserves in legacy Doba Basin corridors. |
| Local Content Joint Venture | Partnerships with SHT satisfy Hydrocarbon Code mandates while securing drilling service contracts. |
| Pipeline Capacity Reservation | Terminal access agreements at Kribi mitigate single-corridor concentration risk for operators. |
| Modular Refining Investment | Topping unit installations at N'Djamena capture margins currently lost to product imports. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drilling contractors, reservoir engineers at international operators, procurement officers at Société des Hydrocarbures du Tchad, and Chad's Ministry of Petroleum and Energy officials cross-validated operational assumptions. Hydrocarbons Code amendments, OHADA business law frameworks, and Chad-Cameroon Pipeline throughput disclosures supplemented field-level intelligence. Bottom-up field production estimates and top-down fiscal revenue projections were triangulated to anchor volume and value outputs.
Data-stream reconciliation across operator production reports, national utility offtake contracts, and export terminal throughput statistics shaped the analytical framework. Segmentation modeling spanned operational type, application phase, recovery technology, and end-use demand across the projection horizon. CAGRs were derived from reserve decline curves, enhanced recovery deployment timelines, and infrastructure capacity expansion schedules. Fiscal term negotiations and domestic power generation procurement patterns served as industry-specific forecast inputs.
The model holds under stable Hydrocarbons Code enforcement and intact Chad-Cameroon Pipeline transit; deviation in fiscal royalty structures or corridor disruptions would shift production timing and investment returns. Forecasts reflect documented assumptions about reserve recovery rates and state equity participation levels. A model refresh is warranted upon material change in hydrocarbon code amendment trajectories or pipeline capacity allocation priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Europe Wireline Logging Services Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Upstream Services Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Multi-Point Ground Flares (MPGF) Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Riserless Light Well Intervention Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
Subsea Well Intervention Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market