
 Middle East Energy Drinks Market | 2026-2036
Middle East Energy Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Energy Drinks Market Insights
Premium sugar-free formulations are redrawing competitive boundaries across the Middle East Energy Drinks Market. Red Bull GmbH leverages its established brand equity to sustain premium positioning in Gulf convenience channels. Abuljadayel Beverages Industries Llc anchors regional manufacturing scale through its Jeddah production complex. Monster Beverage Corporation differentiates via aggressive flavor portfolio extension targeting gym and gaming segments.
Middle East energy drinks are non-alcoholic, caffeinated functional beverages typically containing taurine, B-vitamins, and herbal extracts, manufactured through hot-fill or aseptic bottling processes designed to preserve carbonation and bioactive stability. Their primary commercial purpose is to deliver acute mental alertness and physical performance enhancement for consumers operating under demanding schedules or athletic regimens. Carbonated variants still occupy the largest volume share, though sugar-free lines are capturing the fastest margin expansion as Gulf health authorities tighten sugar taxation frameworks. Young adults dominate end-user spending, while fitness centers emerge as the highest-growth distribution channel as gym memberships multiply across Riyadh, Dubai, and Doha.
Saudi Food and Drug Authority labeling mandates and UAE Ministry of Economy import standards collectively shape product composition thresholds and caffeine disclosure requirements across Gulf Cooperation Council markets. Egypt's national food safety authority applies parallel but less stringent additive rules, creating a dual-track compliance environment for manufacturers serving North African versus Arabian Peninsula demand. Stakeholders must monitor evolving caffeine caps and sugar taxation trajectories as Gulf regulators align consumer protection frameworks with broader public health campaigns.
Market Dynamics
SFDA caffeine disclosure mandates and UAE sugar taxation frameworks are compressing formulation margins while redirecting R&D investment toward clean-label alternatives across Gulf production facilities.
Growth Catalysts
- Fitness Center Expansion:Gym memberships in Riyadh, Dubai, and Doha multiply as wellness culture penetrates urban Saudi and Emirati demographics, creating dedicated on-premise consumption venues.
- Sugar Taxation Thresholds:UAE Ministry of Economy excise frameworks incentivize reformulation toward zero-sugar lines, accelerating portfolio pivot across regional bottlers.
- Aseptic Hot-Fill Bottling:This preservation technology extends shelf stability without chemical preservatives, enabling cleaner ingredient declarations that satisfy Gulf health authority labeling standards.
Market Restraints
- Taurine Import Concentration:Bulk taurine supply concentrates among Chinese and Japanese chemical manufacturers, exposing Gulf formulators to shipping cost volatility and currency fluctuation risk.
- Carbonation Infrastructure Limitations:Aseptic CO2 injection systems require capital-intensive retrofitting of existing Jeddah and Dubai bottling lines, slowing regional production scale-up.
- Herbal Extract Substitution:Traditional qahwa and karak tea consumption persists as zero-cost alternatives among price-sensitive Egyptian and Jordanian consumer segments.
Strategic Opportunities
- Egyptian Retail Modernization:Hypermarket and convenience channel penetration in Cairo and Alexandria remains below Gulf levels, offering first-mover positioning for format-adapted products.
- Gaming Lounge Distribution:Esports venues and dedicated gaming cafés in Kuwait City and Manama represent untapped consumption occasions beyond traditional athletic positioning.
- SFDA Clean-Label Incentives:Saudi regulatory recognition programs for reduced-additive formulations create preferential shelf placement and procurement channel access.
Industry Challenges
- Halal Certification Timelines:Gulf Cooperation Council harmonization delays for novel ingredient approvals extend product launch cycles by 8-14 months.
- Refrigerated Last-Mile Infrastructure:Ambient distribution dominance across Egyptian and Jordanian retail networks limits premium chilled-format penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Energy Drinks Market |
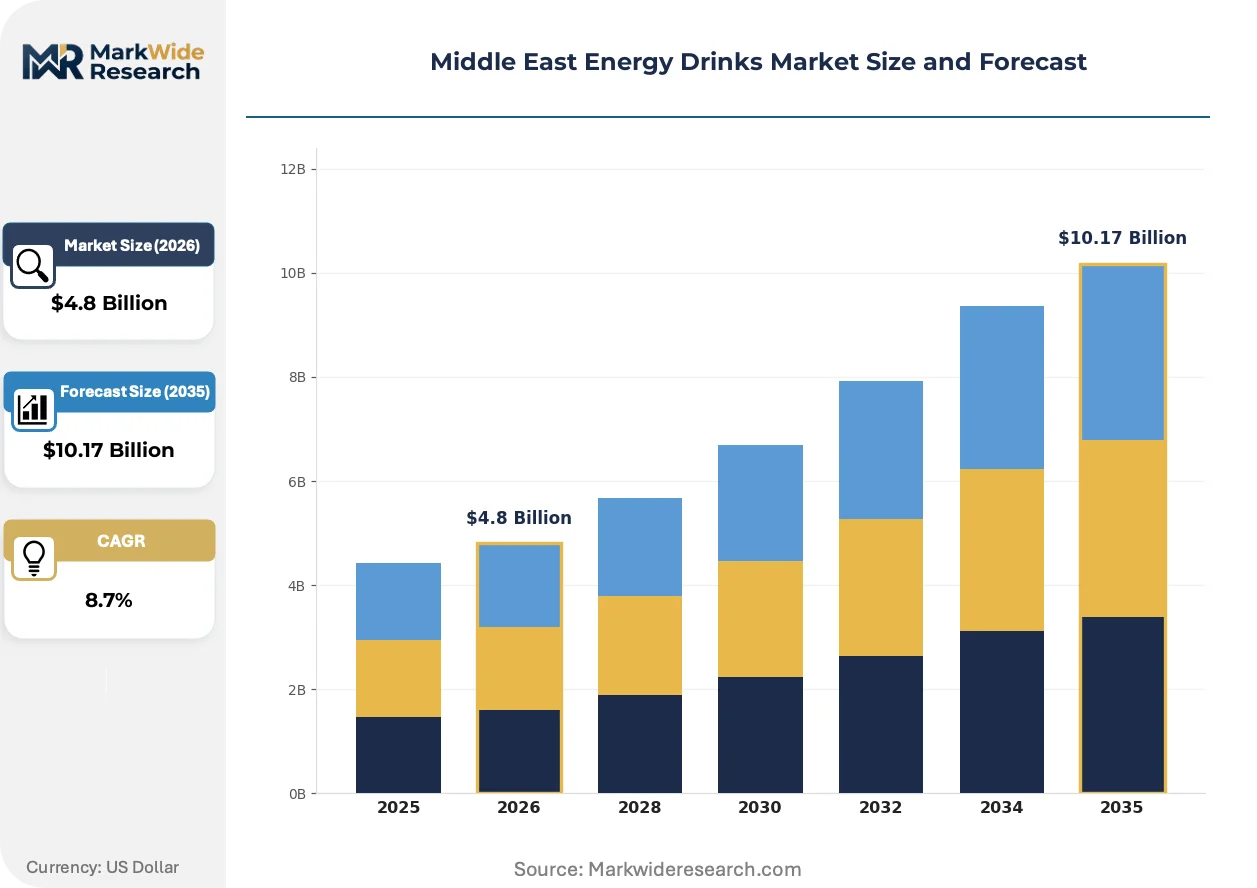
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Sugar-Free, Herbal End User: Teens, Young Adults, Athletes, Professionals Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Fitness Centers Ingredient Type: Caffeine, Taurine, Vitamins, Ginseng |
| Companies Covered | The Coca-Cola Company, Abuljadayel Beverages Industries Llc, Red Bull GmbH, Aujan Coca-Cola, Mahmood Saeed Group of Companies, Monster Beverage Corporation, Power Horse Energy Drinks GmbH, Saudi Food & Fine Chemicals Co., PepsiCo, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Energy Drinks Market Trends and Innovations
Functional beverage architecture is fragmenting as Gulf consumers reject one-size-fits-all energy positioning in favor of occasion-specific formulations targeting sleep, focus, or recovery states.
Microencapsulated caffeine delivery systems are decomposing traditional single-bolus absorption profiles. Fitness-oriented consumers in Saudi Arabia and the UAE adopt these staggered-release formats for sustained training sessions. The technology is decomposing conventional 250ml can economics by enabling premium unit pricing for extended-duration efficacy claims.
SFDA mandatory front-of-pack caffeine disclosure rules compress formulation flexibility for regional manufacturers. Bottlers must now declare exact milligram content per serving, eliminating proprietary blend opacity. Sugar-free and reduced-caffeine SKUs absorb disproportionate compliance attention as brands preempt regulatory threshold tightening.
Gym-based vending and direct-to-locker subscription models displace conventional supermarket purchasing among urban Saudi and Emirati young adults. Digital-native consumers in Riyadh and Dubai prioritize convenience and personalization over price comparison. This behavioral pivot rewards brands with localized delivery infrastructure and customizable flavor profiles.
Middle East Energy Drinks Market Segmentation
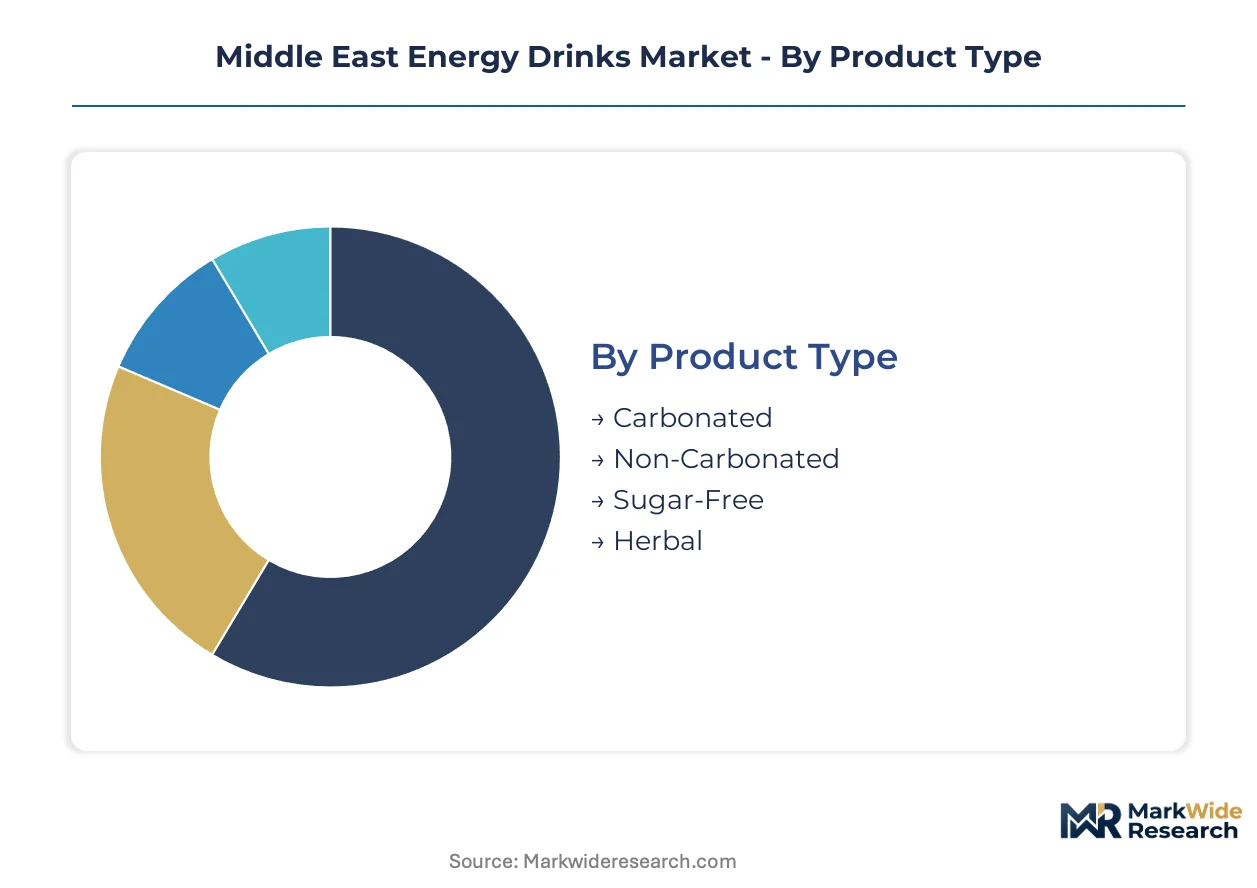
Channel economics in the Middle East Energy Drinks Market fragment sharply across product formats. Carbonated variants dominate ambient retail while sugar-free lines command premium placement in climate-controlled fitness venues.
Product Type:
Supermarket and convenience store shelves favor carbonated and sugar-free formats, whereas herbal variants flow through traditional grocery channels serving qahwa-replacement demand.
- Carbonated:Hot-fill or aseptic bottling preserves CO2 saturation for shelf-stable distribution. Demand concentrates in Saudi Arabia and the UAE where urban retail infrastructure supports chilled cabinet placement and impulse purchase behavior.
- Sugar-Free:Reformulated with alternative sweeteners to satisfy UAE Ministry of Economy excise thresholds. Young adults in Dubai and Riyadh drive fastest adoption as gym culture normalizes zero-calorie functional positioning.
- Non-Carbonated:Still formats target hydration-conscious consumers seeking caffeine without carbonation bloat. Egyptian and Jordanian distribution networks favor these for ambient storage compatibility.
- Herbal:Ginseng and adaptogen blends appeal to consumers avoiding synthetic stimulants. Karak tea substitution patterns in lower-income segments limit volume penetration outside premium urban clusters.
Carbonated dominates installed base. Sugar-Free is where expansion concentrates.
End User:
Cost tier stratification separates occasional teen purchasers from high-frequency professional consumers willing to pay premium per-unit prices for convenience formats.
- Young Adults:Urban Saudi and Emirati consumers aged 18-35 represent the highest per-capita consumption frequency. Fitness center vending and gaming lounge distribution target this cohort with occasion-specific packaging sizes.
- Professionals:White-collar workers in Riyadh and Doha demand sustained-release caffeine for extended work schedules. Microencapsulated delivery systems command price premiums from this segment.
- Athletes:Competitive and recreational gym-goers prioritize electrolyte-enhanced variants. Direct-to-locker subscription models capture recurring revenue from this high-loyalty cohort.
- Teens:Price-sensitive consumption concentrated in convenience store singles purchases. SFDA caffeine disclosure rules and potential age-gating create regulatory headwinds for targeted marketing.
Young Adults anchor current volume. Professionals show steepest expansion trajectory.
Distribution Channel:
Volume concentration varies dramatically by geography—modern trade dominates Gulf markets while traditional trade persists in North African markets with weaker cold-chain infrastructure.
- Fitness Centers:Dedicated on-premise consumption venues multiplying across Riyadh, Dubai, and Doha. Exclusive vending contracts and branded cooler placement capture high-margin immediate consumption.
- Convenience Stores:24-hour urban outlets in Jeddah and Kuwait City serve impulse and late-night demand. Chilled format availability determines brand selection at point of purchase.
- Supermarkets:Hypermarket chains in Saudi Arabia and the UAE drive multi-pack and family-format sales. Shelf space allocation follows SFDA clean-label incentive program participation.
- Online Retail:Subscription and bulk delivery platforms gain traction among digitally native young adults. Last-mile refrigeration limitations constrain premium chilled format penetration outside Gulf urban cores.
Supermarkets dominate installed base. Fitness Centers is where expansion concentrates.
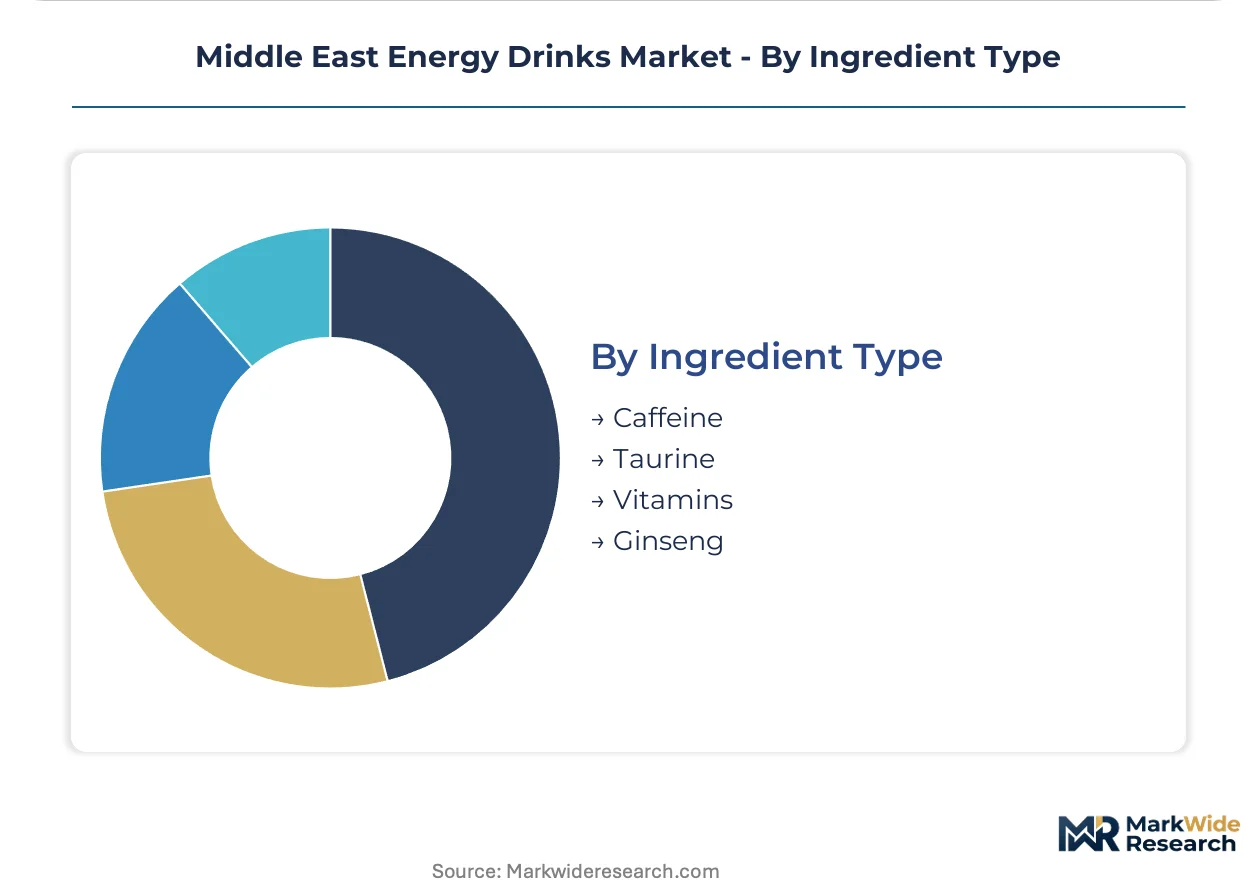
Ingredient Type:
Margin structure diverges sharply between commodity caffeine formulations and premium botanical extracts subject to Halal certification complexity.
- Caffeine:Synthetic and natural caffeine sources form the functional core of all major brands. Front-of-pack milligram disclosure mandates under SFDA rules eliminate proprietary blend opacity.
- Taurine:Amino acid additive standard in performance-positioned variants. Import concentration from East Asian chemical manufacturers exposes formulators to shipping cost volatility.
- Vitamins:B-complex fortification supports metabolic energy marketing claims. Clean-label positioning favors declared vitamin content over undisclosed proprietary blends.
- Ginseng:Herbal extract positioning targets consumers seeking traditional medicine adjacency. GCC Halal certification timelines for novel botanicals extend product launch cycles.
Caffeine dominates installed base. Vitamins is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters around Jeddah and Dubai production complexes, with Gulf Cooperation Council markets absorbing two-thirds of regional volume. Egypt and Jordan serve as secondary demand pools with distinct channel economics.
Saudi Arabia
Fitness center expansion in Riyadh and Jeddah drives premium format demand. SFDA caffeine disclosure mandates and sugar taxation signaling reshape formulation priorities. The Jeddah production corridor anchors Abuljadayel Beverages Industries' regional manufacturing scale.
United Arab Emirates
Dubai's gym culture and gaming lounge proliferation create occasion-specific consumption venues. UAE Ministry of Economy excise frameworks accelerate zero-sugar portfolio pivots. Dubai's retail infrastructure supports the highest per-capita premium placement density in the region.
Egypt
Hypermarket modernization in Cairo and Alexandria lags Gulf benchmarks, preserving traditional trade dominance. The national food safety authority applies additive rules less stringent than SFDA equivalents. Ambient distribution networks favor non-carbonated formats compatible with limited cold-chain reach.
Kuwait
Gaming café and esports venue density in Kuwait City exceeds regional averages, opening distribution beyond athletic positioning. Import standards align with broader GCC harmonization efforts. Convenience channel 24-hour availability supports impulse purchase patterns among young adult demographics.
Qatar
Doha's wellness infrastructure expansion mirrors Saudi and Emirati fitness center growth trajectories. Regulatory frameworks track UAE and Saudi precedents on caffeine labeling. Premium positioning concentrates in West Bay and Pearl-Qatar retail clusters serving expatriate professional segments.
Middle East Energy Drinks Market Competitive Landscape
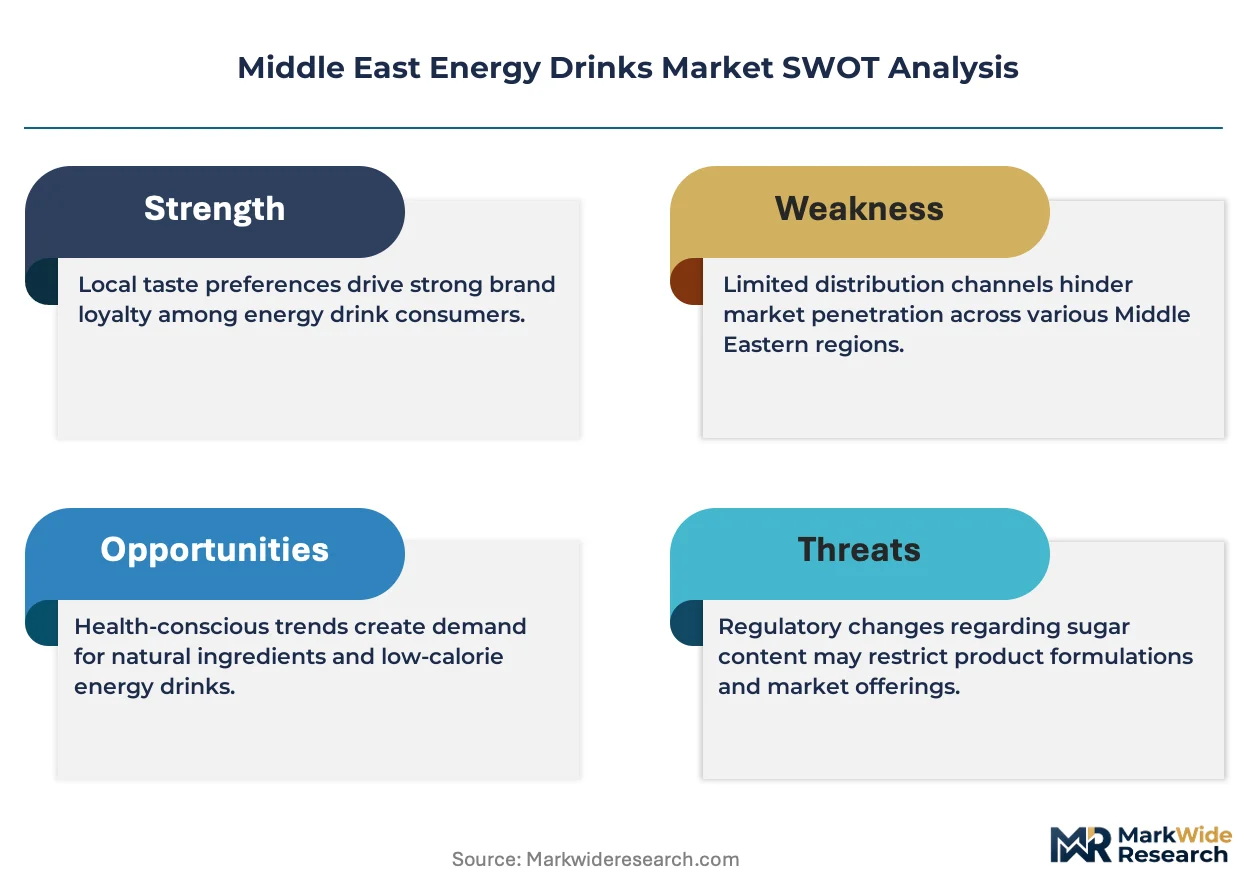
Technology leadership and cost leadership are held by different player archetypes across the Middle East Energy Drinks Market. Gulf-based bottlers leverage aseptic hot-fill infrastructure for clean-label positioning, while multinational concentrate suppliers dominate brand equity and formulation IP. Three archetypes define competitive structure: established global beverage conglomerates with licensed regional production, dedicated regional manufacturers with captive Gulf distribution, and specialist energy drink pure-plays with fitness-channel focus. Consolidation pressure manifests through exclusive vending contracts at fitness centers and strategic cooler placement in convenience networks.
Among global beverage conglomerates, The Coca-Cola Company and PepsiCo exemplify licensed production models through regional partnerships. Red Bull GmbH occupies a distinct premium-tier position anchored in brand equity rather than manufacturing scale. Monster Beverage Corporation represents the specialist pure-play archetype with targeted segment positioning.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| Abuljadayel Beverages Industries Llc |
| Red Bull GmbH |
| Aujan Coca-Cola |
| Mahmood Saeed Group of Companies |
| Monster Beverage Corporation |
| Power Horse Energy Drinks GmbH |
| Saudi Food & Fine Chemicals Co. |
| PepsiCo |
| Others |
Pricing and Supply Chain Analysis
Alternative sweetener substitution for sucrose is compressing formulation economics while simultaneously redrawing procurement geography toward Southeast Asian suppliers and reshaping Gulf pricing tiers as zero-sugar lines absorb disproportionate compliance investment.
Pricing Analysis
SFDA caffeine disclosure mandates dictate the pricing tier structure across Middle East energy drinks. Three-tier pricing structure across premium, standard, and economy levels separates microencapsulated sustained-release formats from conventional carbonated cans and private-label economy lines. Price differentiation hinges on clean-label certification status and gym-channel exclusivity versus mass retail availability. Cost compression in the standard tier is intensifying because UAE sugar taxation frameworks force parallel zero-sugar SKU development. Teen convenience-store purchasers exhibit highest price sensitivity; fitness-center professionals accept premium positioning for extended-duration efficacy claims.
Supply Chain Analysis
China and Japan anchor bulk taurine and synthetic caffeine production for Gulf formulators. Egyptian bottlers draw from regional sugar refineries and domestic B-vitamin compounders, reducing import exposure. Raw material dependencies center on East Asian amino acid manufacturers, Southeast Asian alternative sweetener suppliers, and European aseptic packaging equipment vendors. Single-source vulnerability concentrates in Chinese taurine supply where three chemical manufacturers control global volume. Distribution runs through ambient wholesale networks in North Africa and climate-controlled logistics corridors serving Saudi and Emirati fitness channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as occasion-specific consumption splinters the mass-energy positioning into sleep, focus, and recovery micro-segments, creating defendable niches beyond Red Bull's premium stronghold.
For Market Incumbents: Secure exclusive vending contracts at Riyadh and Dubai fitness centers before facility saturation peaks. Lock in Jeddah aseptic hot-fill capacity expansion to preempt regional clean-label supply constraints. Vertical integration into captive sweetener blending insulates margin pressure from UAE sugar taxation escalation. For New Entrants and Emerging Players: Anchor in Egyptian hypermarket modernization gaps where ambient distribution compatibility favors non-carbonated formats. Target gaming lounge channels in Kuwait City and Manama with occasion-specific sizing absent from athletic-positioned incumbents. Deploy direct-to-locker subscription models to bypass refrigerated last-mile infrastructure limitations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional bottlers holding GCC Halal certification pipelines and Jeddah production corridors. Five-to-ten-year viability hinges on regulatory alignment capacity across SFDA and UAE Ministry of Economy frameworks. Watch for SFDA threshold tightening on caffeine caps as portfolio repositioning catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Hot-Fill Capacity Expansion | Jeddah and Dubai production complexes capture clean-label shelf placement under SFDA incentive programs. |
| Zero-Sugar Portfolio Pivot | UAE Ministry of Economy excise frameworks reward reformulation with hypermarket channel access. |
| Fitness Center Vending Exclusivity | Riyadh and Doha gym networks create high-margin immediate consumption venues beyond price comparison. |
| Gaming Lounge Distribution Entry | Kuwait City and Manama esports venues unlock consumption occasions outside traditional athletic positioning. |
| Direct-to-Locker Subscription Launch | Digital-native young adults in Dubai prioritize convenience and personalization over supermarket price sensitivity. |
Research Methodology
Cross-validation between primary interviews with beverage formulators, fitness center operators, and hypermarket category buyers anchors the qualitative findings against secondary sources including SFDA regulatory filings, UAE Ministry of Economy excise notices, and Gulf customs trade records. Bottom-up volume triangulation from Jeddah and Dubai production complexes converges with top-down demand modeling across Saudi, Emirati, Egyptian, and Kuwaiti consumption clusters.
Sensitivity analysis across alternative sweetener cost scenarios and caffeine threshold regulatory variants shapes the projection framework. Segmentation dimensions span product type, end-user cohort, distribution channel, and ingredient composition across the modeling period. CAGRs derive from installed base growth rates adjusted for channel shift elasticities and gym membership expansion trajectories in Riyadh, Dubai, and Doha.
Material uncertainties — SFDA threshold tightening, UAE sugar taxation escalation, and East Asian taurine supply disruption — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory stability and Halal certification timeline continuity. Recalibration cycles align with material shifts in Gulf health authority labeling standards and fitness infrastructure deployment rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Grape Juice Concentrate for Wine Making Market
Beverages
Bangladesh Energy Drinks Market
Beverages
United States Beverage Contract Bottling and Filling Market
Beverages
Sparkling Juice Drinks Market
Beverages
Root Beer Market
Beverages
North America Cold Pressed Juices Market
Beverages
Fruit Water Market
Beverages
US Bubble Tea Market
Beverages
India Soy Beverages Market
Beverages
Semillon Market
Beverages
Sparkling Water Market
Beverages
Enzyme-Enabled Cold-Brew Concentrates Market
Beverages
Soft Serve Premix Market
Beverages
Detox Drinks Market
Beverages
Orange Juice Market
Beverages
Low Calorie RTD Beverages Market