
 Punica Granatum (Pomegranate) Seed Oil Market | 2026-2036
Punica Granatum (Pomegranate) Seed Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Punica Granatum (Pomegranate) Seed Oil Market Analytics
Subscription-based raw material sourcing is pivoting how cosmetic brands procure pomegranate seed oil, shifting volume commitments from spot purchases to annual supply contracts. Jedwards International Inc. leverages its bulk specialty oil distribution network to serve mid-sized formulators across North America. Henry Lamotte Oils GmbH anchors European supply through its Hamburg refining facility and certified organic handling capabilities. Botanic Innovations LLC differentiates via supercritical CO2 extraction technology that preserves higher punicic acid concentrations than conventional pressing methods.
Punica granatum seed oil is a triglyceride oil extracted from pomegranate seeds, containing 75-85% punicic acid—a conjugated linolenic acid with potent anti-inflammatory and antioxidant properties—and is produced through cold pressing or solvent extraction for use in topical formulations and dietary supplements. Cold pressed grades command premium positioning in skincare applications where unrefined nutrient profiles justify higher price points, while refined variants dominate pharmaceutical applications requiring consistent oxidative stability and neutral sensory characteristics. The cosmetic industry end-use segment leads volume consumption through facial serums and anti-aging formulations, whereas nutraceuticals represent the fastest-expanding demand pool as clinical research on cardiovascular and metabolic benefits accumulates.
REACH registration requirements in the European Union mandate comprehensive safety data for botanical oils used in cosmetic and pharmaceutical applications, elevating compliance costs for smaller exporters while creating barriers to informal trade channels. The FDA's New Dietary Ingredient notification framework governs pomegranate seed oil entry into US supplement formulations, requiring manufacturers to substantiate safety profiles or demonstrate prior marketing history. India's FSSAI has tightened labeling standards for cold-pressed oils in food and supplement categories, compelling domestic processors to upgrade testing infrastructure. Stakeholders must monitor evolving conjugated fatty acid labeling claims across jurisdictions, as regulatory divergence between cosmetic and food-grade classifications threatens cross-border formulation strategies.
Market Dynamics
REACH compliance documentation is restructuring procurement relationships across European cosmetic supply chains, forcing smaller botanical oil exporters to consolidate testing capabilities or exit formal trade channels entirely.
Growth Catalysts
- Cold-pressed extraction protocols:Unrefined nutrient retention in premium skincare formulations is pulling volume commitments from French and German cosmetic formulators toward certified organic handlers with verified punicic acid concentrations.
- FSSAI labeling standardization:India's tightened requirements for cold-pressed oils in supplement categories are accelerating domestic Ayurveda brand investment in captive capsule production infrastructure.
- Clinical cardiovascular research:Accumulating evidence on metabolic benefits is expanding nutraceutical demand pools beyond topical applications into dietary supplement formulations.
Market Restraints
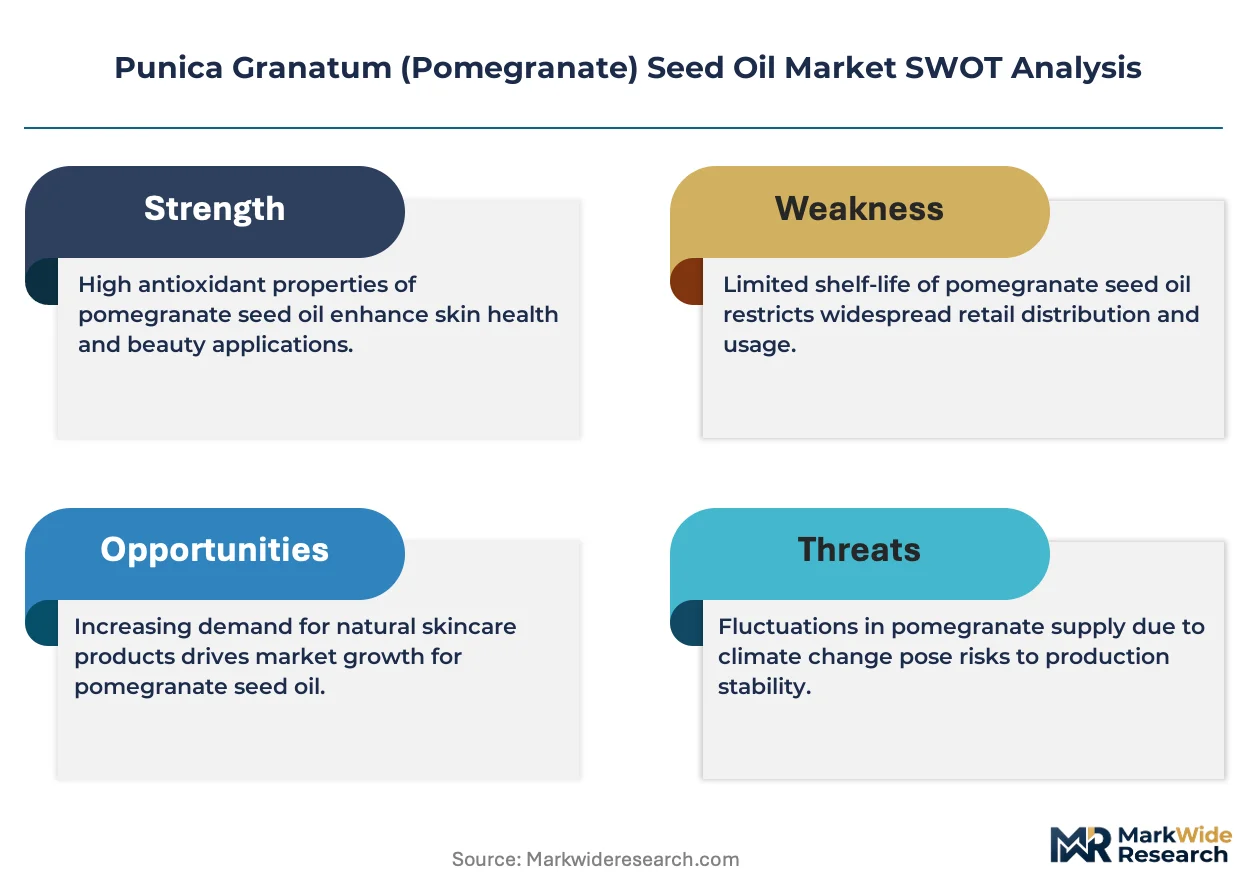
- Pomegranate seed supply volatility:Agricultural yield fluctuations in primary cultivation zones concentrate input cost risk among processors lacking multi-origin sourcing contracts.
- Supercritical CO2 equipment thresholds:Capital intensity for advanced extraction systems limits technology diffusion to mid-scale processors, preserving quality tier fragmentation.
- Grapeseed and rosehip oil substitution:Comparable antioxidant profiles in competing botanical oils exert price ceiling pressure across standard-grade cosmetic applications.
Strategic Opportunities
- Subscription sourcing contracts:Annual volume commitments replacing spot purchases enable processor visibility for capacity planning and inventory optimization.
- Supercritical CO2 extraction convergence:Integration with certified organic handling capabilities creates premium positioning for punicic acid concentration claims in pharmaceutical-grade applications.
- India nutraceutical channel expansion:Domestic Ayurveda brand scaling presents white space for capsule formulation partnerships with established oil refiners.
Industry Challenges
- Conjugated fatty acid labeling divergence:Cosmetic versus food-grade classification inconsistencies across jurisdictions complicate cross-border formulation strategies and compliance documentation.
- REACH dossier compilation timelines:Comprehensive safety data requirements for botanical oil registration extend market entry cycles for new supplier qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Punica Granatum (Pomegranate) Seed Oil Market |
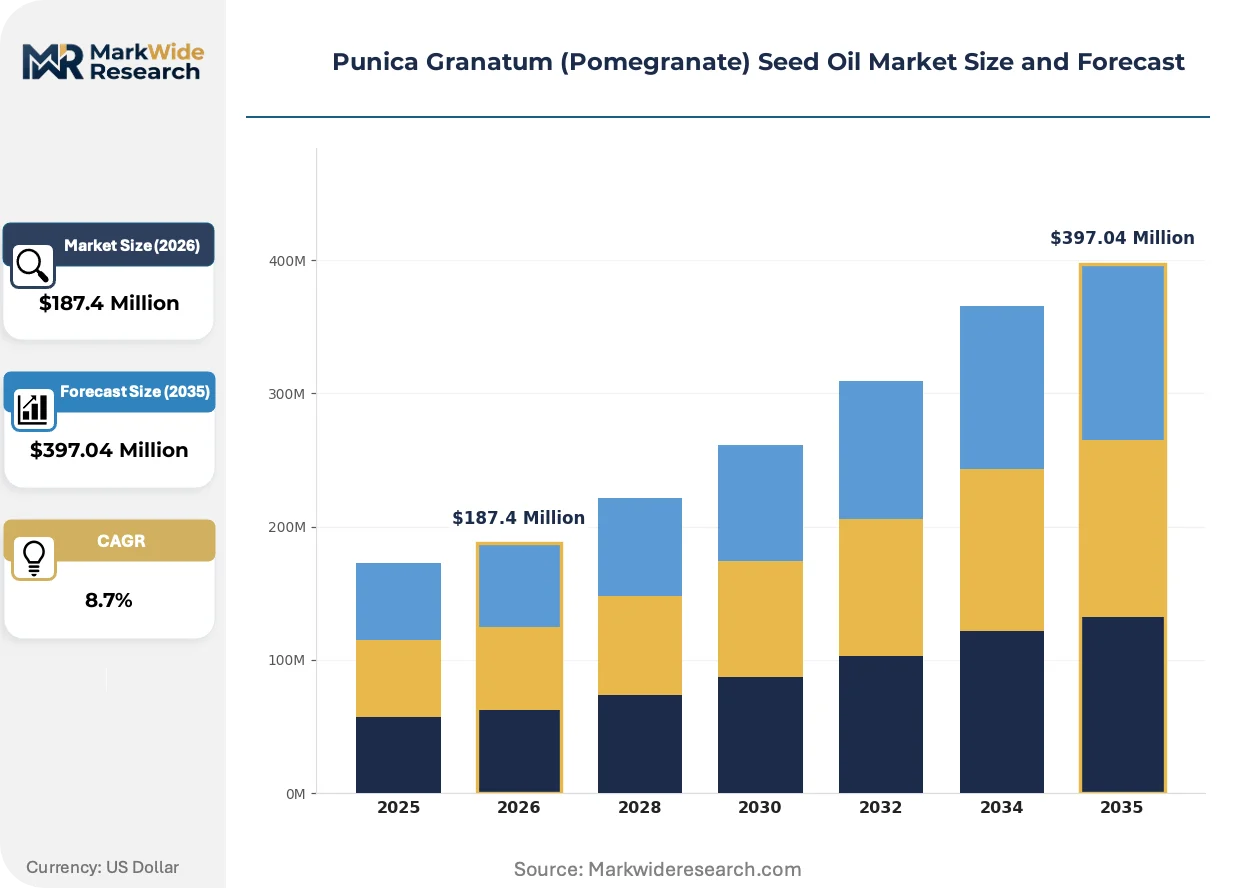
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Pressed, Refined, Organic, Virgin End User: Cosmetic Industry, Nutraceuticals, Food Industry, Pharmaceuticals Application: Skincare, Haircare, Dietary Supplements, Aromatherapy Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Jedwards International Inc., India Essential Oils, All Organic Treasures GmbH, Rakesh Sandal Industries, Talya, Fushi Wellbeing Ltd., AOS Product, Henry Lamotte Oils GmbH, Botanic Innovations LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Punica Granatum (Pomegranate) Seed Oil Market Evolving Landscape
Extraction technology advancement and procurement model restructuring are compressing quality tier boundaries while regulatory documentation requirements deepen supplier capability segmentation.
Supercritical CO2 extraction systems are unifying pharmaceutical-grade purity standards with cosmetic-sector nutrient preservation demands. Mid-sized formulators in North America are adopting these systems at accelerating rates to secure punicic acid concentration advantages. The technology is unifying previously separate premium and pharmaceutical quality tiers into single-source supply relationships.
REACH registration mandates are elevating compliance cost structures for botanical oil imports into European cosmetic and pharmaceutical applications. Smaller exporters face consolidation pressure as comprehensive safety data requirements outscale informal trade channel capabilities. French and German formulators are responding by tightening supplier qualification to certified organic handlers with established ECHA documentation.
Annual supply contracts are displacing spot purchasing across cosmetic brand procurement functions. Mid-sized formulators are locking volume commitments with bulk specialty distributors to secure cold-pressed grade allocations. This behavioral shift is most visible in North American premium skincare lines where unrefined oil scarcity risk has compressed sourcing decision cycles.
Punica Granatum (Pomegranate) Seed Oil Market Segmentation
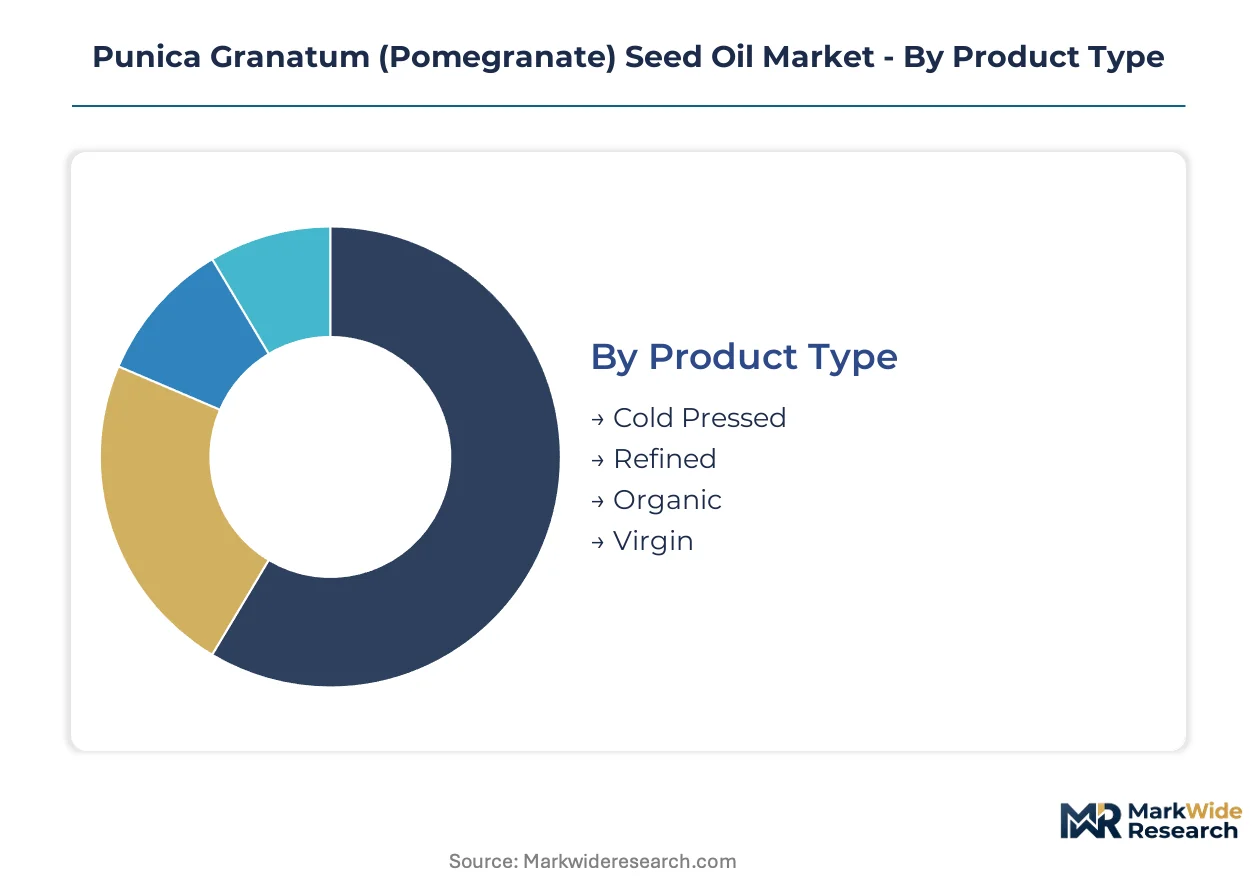
Pomegranate seed oil segmentation reflects divergent purity standards and end-use integration depths. Cold-pressed grades command standalone premium positioning in cosmetic formulations, while refined variants embed into pharmaceutical supply chains with stricter stability requirements.
Product Type:
Cold pressed and refined grades occupy opposite ends of the integration spectrum, with organic and virgin categories bridging premium cosmetic demand.
- Cold Pressed:Unrefined extraction preserves 75-85% punicic acid concentration and native antioxidant complexes. French and German cosmetic formulators concentrate procurement here for facial serum applications where nutrient integrity justifies price premiums.
- Refined:Neutralized, bleached, and deodorized processing removes color and odor for pharmaceutical-grade oxidative stability. Pharmaceutical manufacturers in Switzerland embed this grade into capsule formulations requiring batch-to-batch consistency.
- Organic:Certified cultivation and handling protocols satisfy EU organic regulation compliance for premium skincare lines. REACH documentation requirements elevate supplier qualification barriers.
- Virgin:Single-press extraction without subsequent processing retains maximum bioactive density. Niche Ayurveda brands in India source this grade for traditional medicine positioning.
Cold pressed leads volumes today; organic is gaining share fastest.
End User:
Cosmetic and nutraceutical buyers operate on divergent procurement cycles, with food and pharmaceutical channels imposing distinct regulatory compliance burdens.
- Cosmetic Industry:Facial serums, anti-aging creams, and premium skincare formulations absorb the majority of cold-pressed supply. German formulators at Henry Lamotte Oils GmbH anchor European procurement through Hamburg refining capabilities.
- Nutraceuticals:Capsule and softgel formulations targeting cardiovascular and metabolic health claims represent the steepest expansion trajectory. India's FSSAI labeling standardization accelerates domestic Ayurveda brand scaling.
- Food Industry:Limited culinary applications and functional food fortification use refined grades with neutral sensory profiles. Regulatory divergence between cosmetic and food-grade classifications constrains cross-border formulation.
- Pharmaceuticals:Clinical research on anti-inflammatory and wound-healing properties drives pharmaceutical-grade demand. EMA quality documentation requirements filter supplier bases to established refiners.
Cosmetic Industry leads volumes today; Nutraceuticals is climbing the fastest.
Application:
Skincare and haircare applications emphasize topical bioavailability, while dietary supplements and aromatherapy segments stress systemic delivery mechanisms.
- Skincare:Facial oils, serums, and anti-aging creams leverage punicic acid's conjugated linolenic structure for barrier repair and inflammation modulation. Premium positioning in French and German markets concentrates demand for unrefined grades.
- Haircare:Scalp treatments and conditioning formulations exploit antioxidant properties for follicle health. Mid-sized North American formulators source through bulk specialty distributors.
- Dietary Supplements:Softgel capsules targeting cardiovascular and metabolic endpoints require refined oil with standardized oxidative stability. Clinical evidence accumulation expands addressable patient populations.
- Aromatherapy:Carrier oil applications in essential oil blending prioritize sensory neutrality and extended shelf life. Specialty stores and online retail channels dominate distribution.
Skincare leads volumes today; Dietary Supplements is expanding most quickly.
Distribution Channel:
Direct sales relationships dominate bulk pharmaceutical procurement, while fragmented retail channels serve cosmetic and nutraceutical end-users.
- Online Retail:E-commerce platforms aggregate niche cosmetic and aromatherapy demand from geographically dispersed consumers. Subscription-based sourcing models are pivoting procurement from spot purchases toward annual commitments.
- Specialty Stores:Premium skincare boutiques and natural health retailers curate organic and virgin grade assortments. German and French retail networks concentrate European premium positioning.
- Supermarkets:Mass-market food-grade and standard cosmetic applications reach price-sensitive consumers. Limited shelf space constrains premium cold-pressed placement.
- Direct Sales:Processor-to-manufacturer contracts secure volume allocations for pharmaceutical and large-scale cosmetic formulators. REACH compliance documentation requirements favor established supplier relationships.
Direct Sales leads volumes today; Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France and Germany anchor European procurement through certified organic handling networks, while India accelerates domestic capsule production under tightened labeling standards. The United States channels demand through bulk specialty distributors serving mid-sized formulators. Switzerland and the United Kingdom concentrate pharmaceutical-grade refining capacity.
France
French cosmetic formulators drive cold-pressed grade procurement for premium facial serum lines. ANSM documentation requirements for botanical imports elevate supplier qualification barriers to certified organic handlers. The Provence-Alpes-Côte d'Azur cluster concentrates fragrance and skincare manufacturing where unrefined nutrient profiles command price premiums.
Germany
German formulators at Henry Lamotte Oils GmbH anchor European supply through Hamburg refining capabilities and REACH-compliant handling. ECHA registration mandates restructure procurement relationships toward established documentation holders. The Hamburg facility serves as a distribution hub for pharmaceutical-grade oxidative stability requirements.
India
Domestic Ayurveda brands scale pomegranate seed oil capsule production for cardiovascular and metabolic health positioning. FSSAI labeling standardization for cold-pressed oils accelerates investment in captive testing infrastructure. Maharashtra and Gujarat processing clusters upgrade refining capacity to serve nutraceutical export demand.
United States
Mid-sized cosmetic formulators source through bulk specialty distributors adopting subscription-based annual contracts. FDA New Dietary Ingredient notification requirements govern supplement formulation entry with safety substantiation protocols. California and New York Metro areas concentrate premium skincare brand headquarters driving unrefined grade procurement.
Switzerland
Swiss pharmaceutical manufacturers embed refined grades into capsule formulations requiring batch-to-batch consistency. Swissmedic quality documentation filters supplier bases to established refiners with EMA-aligned standards. The Basel pharmaceutical cluster drives demand for neutralized, bleached, and deodorized processing outputs.
Punica Granatum (Pomegranate) Seed Oil Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with extraction technology capabilities creating tiered supply relationships. Cold-pressed handlers and supercritical CO2 operators occupy distinct premium positioning brackets. REACH-compliant European refiners and FSSAI-certified Indian processors represent the dominant strategic archetypes. Competitive moves concentrate on multi-origin sourcing contracts and extraction technology licensing arrangements.
Within the certified organic handling tier, Henry Lamotte Oils GmbH and All Organic Treasures GmbH exemplify European compliance-focused positioning, while Botanic Innovations LLC occupies the advanced extraction technology vector. These three entities represent the capability segmentation between conventional pressing methods and supercritical CO2 systems that preserve elevated punicic acid concentrations.
| Leading Market Players |
|---|
| Jedwards International Inc. |
| India Essential Oils |
| All Organic Treasures GmbH |
| Rakesh Sandal Industries |
| Talya |
| Fushi Wellbeing Ltd. |
| AOS Product |
| Henry Lamotte Oils GmbH |
| Botanic Innovations LLC |
| Others |
Value Network & Pricing Analysis
Supercritical CO2 extraction technology diffusion is compressing cost economics for pharmaceutical-grade purity while concentrating supply relationships among capital-equipped processors in Germany and India. This production-method transition simultaneously elevates entry thresholds for mid-scale competitors and shifts procurement power toward handlers with certified organic documentation and REACH dossier completeness.
Pricing Analysis
Capacity additions in India are reshaping price floors for refined grades as domestic Ayurveda brands scale captive capsule production infrastructure. Three-tier pricing structure across cold-pressed organic, refined pharmaceutical, and standard cosmetic levels reflects punicic acid concentration verification and ECHA documentation completeness. Cost compression in standard cosmetic tiers is intensifying because grapeseed and rosehip oil substitution exerts ceiling pressure. Mid-sized North American formulators show highest price sensitivity, while Swiss pharmaceutical manufacturers absorb premiums for batch-to-batch oxidative stability.
Supply Chain Analysis
Direct-to-manufacturer contracts handle pharmaceutical and large-scale cosmetic buyer demand with REACH-compliant documentation requirements. Raw material flows concentrate in India, Turkey, and Iran as primary pomegranate cultivation zones, with seed supply drawing from seasonal agricultural harvests. Processing capacity rests on multi-origin sourcing contracts, cold-pressed equipment, and supercritical CO2 systems as critical inputs. Single-source vulnerability in seed supply concentrates risk among processors lacking geographic diversification. Distribution runs through Hamburg refining hubs for European pharmaceutical-grade handling and bulk specialty distributors for North American mid-tier formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European REACH compliance costs and India's FSSAI-standardized domestic production, with regulatory documentation differentials creating 20-40% cost wedges for equivalent purity grades.
For Market Incumbents: Anchor multi-origin sourcing contracts across Turkey, Iran, and India to defend against pomegranate seed yield volatility and agricultural input concentration. Invest in captive supercritical CO2 extraction capabilities to preserve punicic acid concentration advantages against solvent-extraction substitutes. Consolidate ECHA dossier holdings to exploit REACH registration timelines that filter smaller exporters from formal European channels. For New Entrants and Emerging Players: Bulk specialty distributors represent the most penetrable channel partner type for mid-sized North American cosmetic formulators seeking subscription-based annual contracts. Target India's nutraceutical capsule production white space where FSSAI labeling standardization accelerates domestic Ayurveda brand scaling. Pursue white-label partnerships with established Hamburg or Mumbai refiners to bypass capital-intensive extraction equipment thresholds. For Investors and Strategic Acquirers: Roll-up economics work for certified organic handlers with established ECHA documentation because REACH compliance costs fragment the supplier base below viable scale. Acquisition targets should display backward integration into seed sourcing or supercritical CO2 extraction technology licensing. Watch punicic acid clinical trial publication velocity as the inflection indicator for nutraceutical demand pool expansion beyond topical applications.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Licensing | Technology transfer agreements enable mid-scale processors to achieve pharmaceutical-grade punicic acid concentration thresholds. |
| Multi-Origin Sourcing Contracts | Geographic diversification across Turkey, Iran, and India mitigates agricultural yield volatility in seed supply. |
| REACH Dossier Consolidation | ECHA documentation completeness filters informal trade channels and secures European cosmetic procurement relationships. |
| Subscription-Based Annual Contracts | Volume commitments from spot purchases improve processor capacity planning and inventory optimization visibility. |
| FSSAI-Certified Captive Production | Domestic Indian refining investment captures nutraceutical capsule demand under tightened labeling standards. |
Research Methodology
Multiple input streams — primary interviews with extraction technology providers, regulatory affairs specialists at ECHA and FSSAI, cosmetic formulator procurement leads, and Ayurveda brand supply chain managers — were reconciled against secondary validation from customs trade databases, REACH registration filings, FSSAI labeling directives, and botanical oil import records. Bottom-up volume estimates from processor capacity utilization were cross-checked against top-down demand aggregation across cosmetic, nutraceutical, and pharmaceutical end-use segments.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include extraction method tier, certification grade, end-use industry, and regional regulatory cluster. CAGRs were derived through regression analysis of historical price-volume relationships and elasticity assumptions for substitution effects between pomegranate seed oil and competing botanical oils. Forecast inputs incorporated clinical trial publication timelines for punicic acid cardiovascular research and FSSAI enforcement intensity projections for cold-pressed oil labeling.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to agricultural yield shocks, REACH dossier revision timelines, and clinical evidence accumulation rates for metabolic health claims. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
India Bakery Ingredients Market
Ingredients
Lupin Flour Market
Ingredients
Marine Peptides Market
Ingredients
North America Phytosterols Market
Ingredients
Self-Rising Flour Market
Ingredients
Food Grade L-Arabinose Market
Ingredients
Spray-Dried Isolate Market
Ingredients
PHO Oils Market
Ingredients
Alcohol Ingredients Market
Ingredients
Fish Gelatin Market
Ingredients
Europe Protein Market
Ingredients
Quark Powder Market
Ingredients
Malted Wheat Flour Market
Ingredients
Roasted Grain Ingredients Market
Ingredients
Potato Protein Market
Ingredients
Glucosylglycerol Market