
 Kairomones Market | 2026-2036
Kairomones Market Size, Share, and Industry Trends Forecast 2026-2036
Kairomones Market Analytics
EU Green Deal pesticide reduction targets is shifting procurement toward biological alternatives across European horticulture. Suterra LLC leverages its vertically integrated pheromone and kairomone manufacturing to supply Mediterranean fruit growers. Koppert Biological Systems anchors its position through specialized biological control distribution networks spanning Western European greenhouse clusters. Russell IPM Ltd competes on R&D intensity in insect monitoring trap design for stored-product pests.
Kairomones are semiochemicals emitted by hosts or prey that attract natural enemies of pest organisms, typically comprising aliphatic or terpene-based volatile organic compounds synthesized through precision fermentation or chemical extraction. Their primary commercial purpose centers on integrated pest management systems where they lure parasitoids and predators to agricultural fields, reducing dependency on broad-spectrum insecticides. Aliphatic compound formulations currently dominate volume due to lower synthesis costs and established efficacy against lepidopteran pests, while terpene-based variants represent the fastest-growing category as extraction efficiencies improve. Liquid formulations capture the largest share of application value, though capsule dispensers command premium positioning in perennial crop systems requiring season-long activity.
EPA biopesticide registration pathways under FIFRA govern market entry for kairomone products in United States agriculture, while EFSA efficacy standards under EU Regulation 1107/2009 shape product authorization timelines across member states. REACH compliance for volatile organic compound emissions adds formulation complexity for European manufacturers. India's Central Insecticides Board registration requirements create parallel compliance obligations for suppliers targeting subcontinental cotton and vegetable markets. Stakeholders must monitor evolving residue tolerance protocols as organic certifiers tighten semiochemical sourcing transparency requirements.
Market Dynamics
EU Green Deal pesticide reduction mandates are compressing synthetic insecticide use across European horticulture, forcing rapid substitution toward semiochemical-based pest management systems.
Growth Catalysts
- EU Regulation 1107/2009:EFSA efficacy standards for biological plant protection products create predictable authorization pathways for kairomone formulations, accelerating farmer adoption in Spain and Italy.
- Precision fermentation:Biomanufacturing advances in aliphatic compound synthesis cut production costs for lepidopteran-targeting kairomones, expanding accessibility to mid-size olive cooperatives.
- Mediterranean citrus monocultures:Concentrated pest pressure in Valencia and Sicily orchards drives trap density requirements that sustain recurring kairomone dispenser purchases.
Market Restraints
- Terpenoid feedstock volatility:Citrus peel waste supply fluctuations from Spanish processing plants create formulation cost instability for terpene-based kairomone producers.
- REACH VOC compliance:ECHA emission thresholds for volatile organic compounds add €40,000-80,000 per product variant in toxicology dossier preparation.
- Synthetic pheromone substitution:Lower-cost sex pheromone mating disruption systems compete directly for lepidopteran IPM budgets in French vineyards.
Strategic Opportunities
- India vegetable protected cultivation:Central Insecticides Board registration for kairomone lures targeting tomato leafminer opens 340,000 hectares of polyhouse expansion.
- Drone-based dispenser deployment:Convergence of UAV precision agriculture with slow-release capsule technology enables canopy-level kairomone distribution in tall-tree citrus.
- EU Farm to Fork Strategy:50% pesticide reduction targets by 2030 mandate biological alternatives in member state agricultural support schemes.
Industry Challenges
- Semiochemist talent scarcity:Specialized expertise in insect chemical ecology and formulation stability remains concentrated in Wageningen University and INRAE research pipelines.
- Multi-season efficacy validation:EFSA field trial requirements demand three-year data packages for perennial crop authorizations, stretching R&D timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kairomones Market |
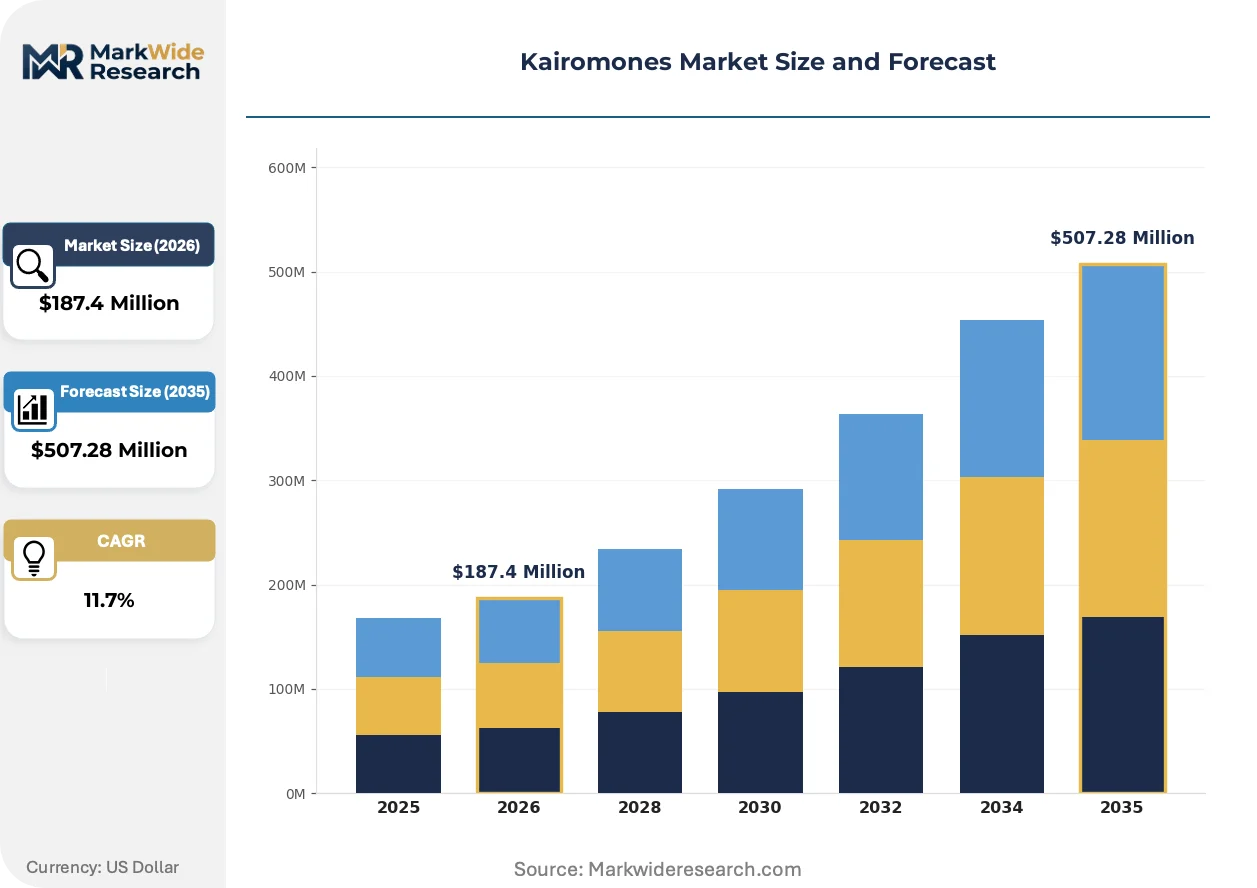
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Aliphatic Compounds, Aromatic Compounds, Terpenes, Fatty Acids Application: Agricultural Pests, Insect Monitoring, Pest Control, Eco-Friendly Products Form: Liquid, Granule, Spray, Capsule End User: Agronomy, Horticulture, Turf Management, Organic Farming |
| Companies Covered | Suterra LLC, Koppert Biological Systems, Russell IPM Ltd, Trécé Inc., Bedoukian Research, Pacific Biocontrol Corp, Synergy Semiochemicals Corporation, International Pheromone Systems, Sanidad Agricola Econex, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kairomones Market Evolving Landscape
Biomanufacturing scale-up and precision application hardware are restructuring how kairomones reach field deployment, compressing the gap between laboratory synthesis and on-farm efficacy.
Precision fermentation of aliphatic kairomones is decentralizing production geography away from centralized chemical plants. Regional bioreactor facilities in Portugal and Greece now supply Mediterranean growers within 48-hour logistics windows. This distributed manufacturing model is compressing import dependency and enabling just-in-time formulation adjustments based on seasonal pest pressure variations.
REACH authorization timelines for semiochemicals are hardening competitive moats around early-mover products. ECHA's 2023 guidance document clarifying low-risk substance criteria reduces data requirements for certain kairomone categories. Spanish and Italian manufacturers with existing dossiers are leveraging this regulatory clarity to extend product exclusivity periods through formulation refinement patents.
Cooperative procurement consortia among Andalusian olive growers are displacing individual farm-level kairomone purchases. Pooled tendering through agricultural associations extracts volume discounts from dispenser suppliers and standardizes trap monitoring protocols across contiguous orchards. This buyer consolidation is most advanced in Jaén province, where 60% of kairomone volume now moves through cooperative channels rather than direct retail.
Kairomones Market Segmentation
Kairomone formulation chemistry and delivery mechanisms determine field efficacy against specific pest complexes. Segmentation reveals how production economics and application constraints channel procurement across crop systems.
Type:
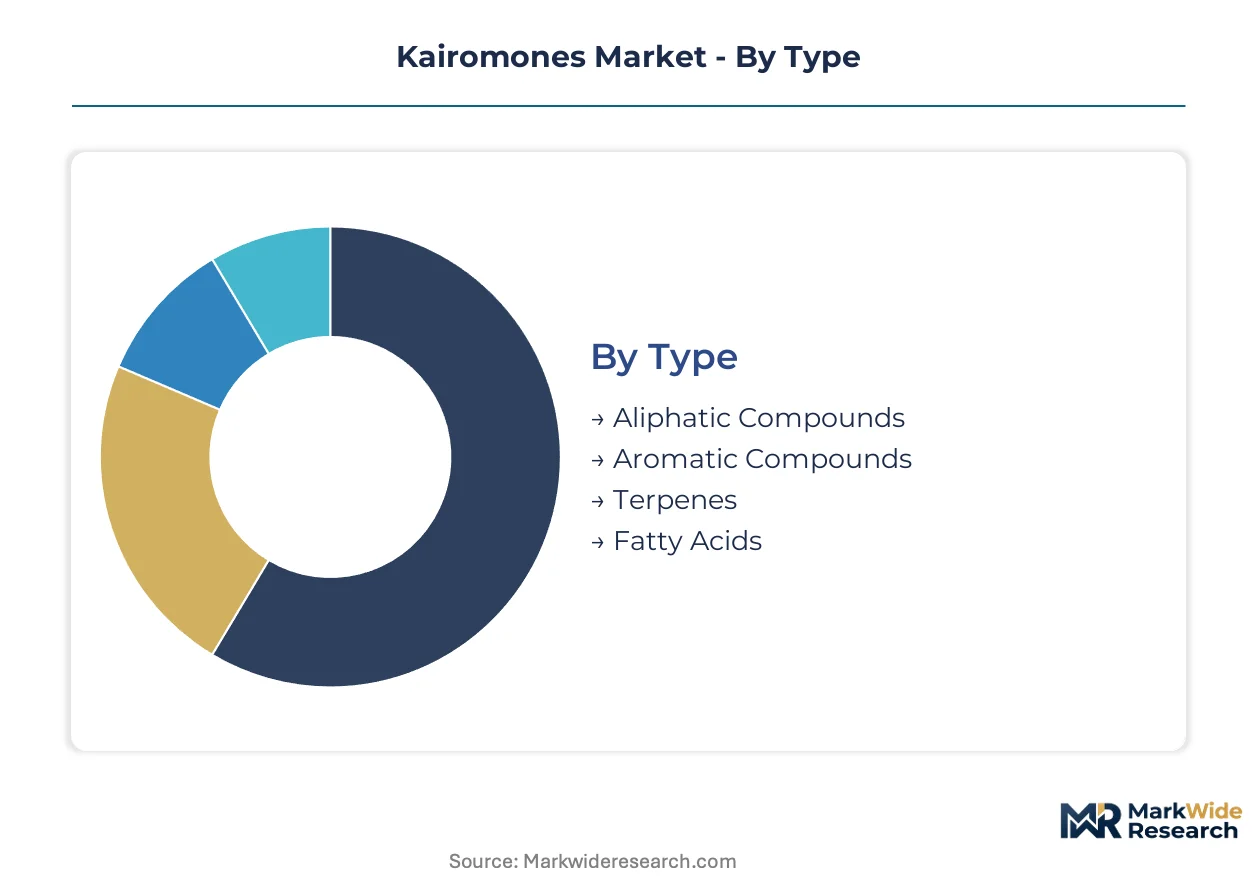
Aliphatic and terpene-based molecular architectures define synthesis pathways and target pest spectra.
- Aliphatic Compounds:Straight-chain hydrocarbons and esters synthesized through precision fermentation dominate commercial volumes. Olive cooperatives in Jaén province deploy these formulations against lepidopteran pests in high-density trapping arrays.
- Terpenes:Cyclic isoprenoid structures extracted from citrus peel waste supply parasitoid attraction in Mediterranean orchards. Extraction efficiency improvements are compressing cost premiums versus synthetic alternatives.
- Aromatic Compounds:Benzene-ring structures with modified side chains target stored-product beetle pests in grain elevators.
- Fatty Acids:Long-chain carboxylic acids function as oviposition stimulants for predator recruitment in vegetable greenhouse systems.
Mature deployment sits with aliphatic formulations. Newer deployment is concentrated in terpene-based extraction from regional biowaste streams.
Application:
Functional use cases separate monitoring tools from direct intervention systems in integrated pest management protocols.
- Agricultural Pests:Field-level attraction of parasitoids and predators to crop zones reduces broad-spectrum insecticide dependency. Valencia citrus growers integrate these lures with augmentative biological control releases.
- Insect Monitoring:Detection traps with kairomone baits enable pest pressure forecasting and treatment timing optimization. EFSA field trial requirements for perennial crop authorizations stretch validation timelines for monitoring product registrations.
- Pest Control:Mass trapping configurations achieve direct population suppression in high-value horticulture.
- Eco-Friendly Products:Organic certification-compliant formulations serve residue-sensitive export markets.
Volume concentrates in monitoring applications. Margin expansion is climbing the fastest in direct pest control systems requiring season-long dispenser replacement.
Form:
Release kinetics and application logistics shape farmer selection across crop architectures.
- Liquid:Tank-mix concentrates enable broadcast application through standard sprayer equipment. Lower per-unit costs support large-area field crops.
- Capsule:Polymer-matrix dispensers provide 90-120 day controlled release for perennial tree crops. Tall-tree citrus in Sicily commands premium positioning for UAV-deployable capsule systems.
- Granule:Solid carrier formulations suit soil-incorporation methods in turf systems.
- Spray:Ready-to-use aqueous solutions target protected cultivation with immediate activity requirements.
Standard procurement favors liquid concentrates. Technical differentiation is accelerating in slow-release capsules for mechanized orchard deployment.
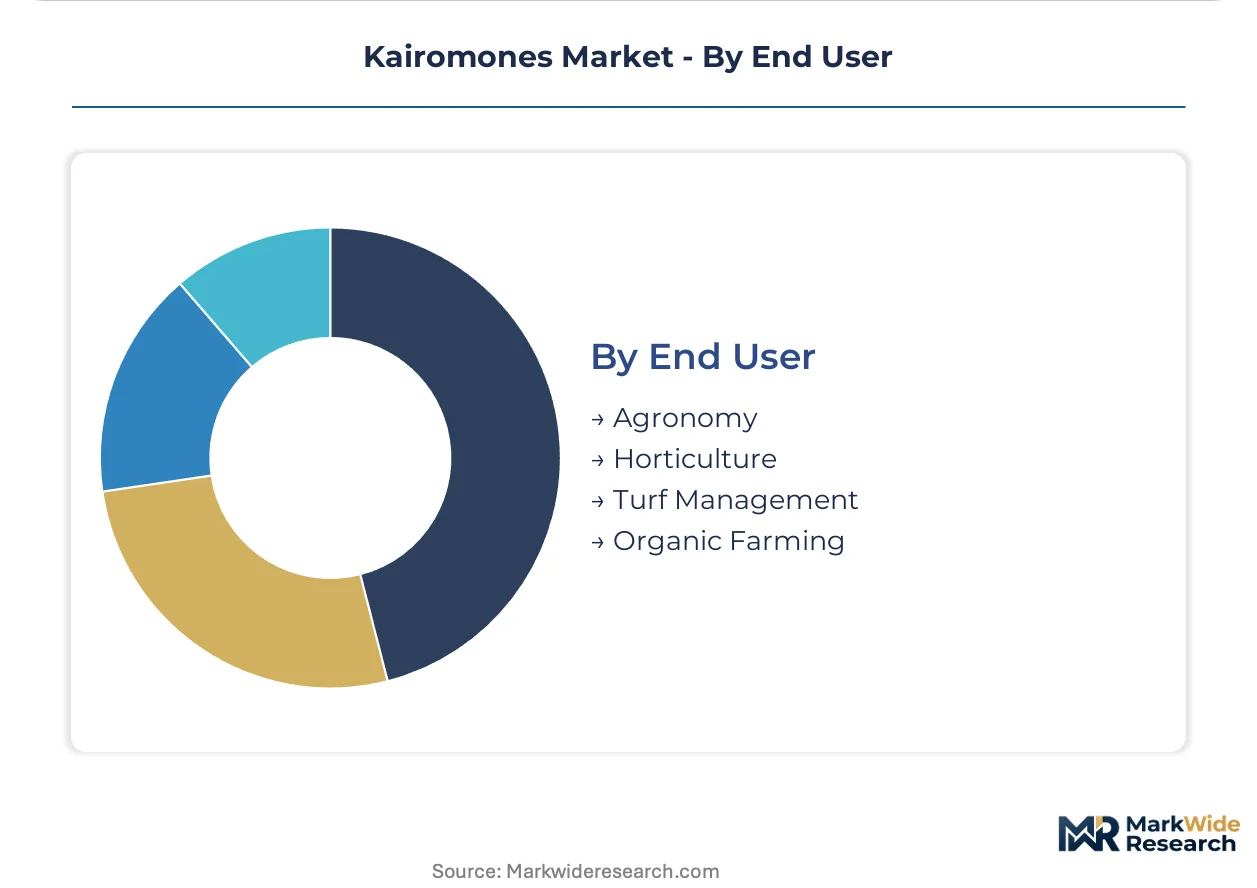
End User:
Production system intensity and certification requirements segment demand across agricultural sectors.
- Agronomy:Broad-acre field crop operations deploy kairomones in row crop pest management. Cotton and soybean systems in India represent expansion targets for Central Insecticides Board-registered lures.
- Horticulture:High-value fruit and vegetable production sustains recurring dispenser purchases through intensive monitoring protocols. Greenhouse clusters in the Netherlands anchor specialized biological control distribution networks.
- Turf Management:Golf course and sports field maintenance applies grub and caterpillar predator attraction.
- Organic Farming:Certification mandates for synthetic pesticide exclusion create inelastic demand for semiochemical alternatives. EU Green Deal pesticide reduction targets are amplifying procurement through member state agricultural support schemes.
Revenue concentration rests with horticulture. Steepest expansion trajectory is gaining share fastest in organic farming conversion zones responding to regulatory phase-outs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of aliphatic kairomones concentrates in Southern European bioreactor facilities, while consumption clusters in Mediterranean orchard zones responding to EU pesticide phase-out mandates. This geographic split shapes logistics networks and regulatory compliance obligations across national boundaries.
Spain
Andalusian olive cooperatives in Jaén province drive dispenser procurement through pooled tendering arrangements covering 60% of regional volume. EFSA efficacy standards under EU Regulation 1107/2009 streamline authorization for lepidopteran-targeting formulations. Valencia citrus orchards sustain recurring capsule purchases through intensive monitoring trap densities.
Italy
Sicilian citrus growers deploy UAV-dispensed kairomone systems in tall-tree architectures unreachable by ground equipment. REACH VOC compliance thresholds add toxicology dossier costs that favor established manufacturers with existing ECHA registrations. Emilia-Romagna greenhouse clusters integrate kairomone lures with augmentative biological control protocols.
United States
California almond and pistachio operations represent the largest North American demand center for parasitoid attraction systems. EPA biopesticide registration pathways under FIFRA govern market entry timelines for new aliphatic formulations. Central Valley processing cooperatives standardize trap monitoring protocols across contiguous orchard blocks.
India
Maharashtra and Gujarat polyhouse vegetable expansion creates demand for tomato leafminer-targeting kairomone lures across 340,000 hectares of protected cultivation. Central Insecticides Board registration requirements create parallel compliance obligations distinct from European or North American frameworks. Karnataka cotton belts represent downstream targets for Central Insecticides Board-registered broad-acre formulations.
Netherlands
Westland greenhouse clusters anchor specialized biological control distribution networks serving high-value ornamental and vegetable production. EFSA-aligned national standards accelerate product authorization for semiochemicals meeting EU low-risk substance criteria. Wageningen University research pipelines concentrate semiochemist expertise supporting regional formulation development.
Kairomones Market Competitive Landscape
The competitive structure tilts toward vertically integrated semiochemical specialists with captive fermentation capacity and established regulatory dossiers. Market participation fragments between multinational biological control distributors, regional biomanufacturing specialists, and research-intensive monitoring trap designers. Three archetypes dominate: precision fermentation operators with backward integration into raw material supply, biological control distributors with specialized field technical service networks, and R&D-focused monitoring system developers. Capacity expansion in Southern European bioreactor facilities and strategic partnerships between dispenser manufacturers and UAV platform providers constitute the primary competitive moves.
Among North American specialists, Trécé Inc. and Pacific Biocontrol Corp exemplify the research-intensive monitoring system archetype, while Suterra LLC represents vertically integrated semiochemical production with controlled-release formulation capabilities. European participation includes Koppert Biological Systems, whose biological control distribution networks span Western European greenhouse clusters, and Russell IPM Ltd, which occupies a position in stored-product pest monitoring trap design. These named entities anchor industry-level commentary without constraining competitive dynamics to specific company actions.
| Leading Market Players |
|---|
| Suterra LLC |
| Koppert Biological Systems |
| Russell IPM Ltd |
| Trécé Inc. |
| Bedoukian Research |
| Pacific Biocontrol Corp |
| Synergy Semiochemicals Corporation |
| International Pheromone Systems |
| Sanidad Agricola Econex, Ltd. |
| Others |
Value Network & Pricing Analysis
Pooled procurement through Andalusian olive cooperatives is compressing dispenser margins and forcing suppliers toward volume-scaled production models that sacrifice customization flexibility for cost competitiveness. This buyer consolidation dynamic concentrates pricing power among agricultural associations while fragmenting supplier profitability across standardized product tiers.
Pricing Analysis
Yield-per-trap efficacy metrics anchor value-based pricing for kairomone formulations in Mediterranean horticulture. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-registered formulations with multi-season dossiers from provisional authorizations and unregistered imports. Cost compression in standard-tier aliphatic compounds is intensifying because Portuguese bioreactor capacity expansion has flooded regional markets with fermentation-derived supply. Smallholder vegetable growers in Indian polyhouse systems exhibit the highest price sensitivity, while Dutch greenhouse operators purchasing through biological control distribution networks show the least.
Supply Chain Analysis
Single-source vulnerability sits with Spanish citrus peel waste processors supplying terpene feedstocks for parasitoid-targeting formulations. Manufacturing capacity concentrates in Portugal, Greece, and Spain, where regional bioreactor facilities draw from beet sugar and olive pomace feedstocks. Formulation stability depends on cold-chain logistics integrity through Mediterranean distribution corridors. Tariff exposure on aliphatic compound imports into India threatens margin structures for European suppliers. Distribution runs through cooperative procurement consortia in Southern Europe and specialized biological control distributors in Northern European greenhouse clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization timelines and EFSA efficacy standards are consolidating competitive positions around early-mover manufacturers with existing toxicology dossiers, systematically excluding capital-constrained entrants from perennial crop authorization pathways.
For Market Incumbents: Anticipate synthetic pheromone substitution pressure in French vineyard IPM budgets by deepening captive fermentation capacity in Portuguese bioreactor facilities. Secure multi-year offtake agreements with Andalusian olive cooperatives before cooperative procurement consortia complete their supplier rationalization. ECHA's low-risk substance criteria clarification creates patent extension opportunities through formulation refinement that smaller competitors cannot fund. For New Entrants and Emerging Players: UAV-deployable capsule systems for tall-tree citrus architectures offer a technology-first wedge into mechanized orchard segments underserved by ground-application incumbents. Target Maharashtra and Gujarat polyhouse vegetable expansion with Central Insecticides Board-registered tomato leafminer lures before established players complete dossier submissions. Partner with regional drone service providers rather than building captive aerial application fleets. For Investors and Strategic Acquirers: The window for entry favors vertically integrated semiochemical specialists with captive precision fermentation capacity and existing ECHA registrations. Long-term viability hinges on regulatory moat durability through EFSA field trial data packages rather than manufacturing scale alone. Monitor ECHA authorization timeline compression for low-risk substance categories as the inflection signal for competitive position stability.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Portuguese bioreactor expansion cuts aliphatic kairomone production costs for Jaén olive cooperatives. |
| UAV Dispenser Technology Partnership | Sicilian citrus growers gain canopy-level kairomone distribution in tall-tree architectures. |
| REACH Low-Risk Substance Registration | Spanish manufacturers leverage ECHA guidance to extend product exclusivity through formulation patents. |
| Cooperative Procurement Consolidation | Andalusian olive associations extract volume discounts and standardize monitoring protocols across contiguous orchards. |
| Central Insecticides Board Dossier Submission | European suppliers unlock 340,000 hectares of Indian polyhouse vegetable protected cultivation. |
Research Methodology
Independent corroboration across semiochemist researchers at Wageningen University, biological control distributors in Westland greenhouse clusters, and EFSA regulatory affairs specialists underwrites the qualitative findings. Primary interviews with formulation chemists at Portuguese bioreactor facilities, procurement managers at Andalusian olive cooperatives, and UAV platform engineers developing aerial dispenser systems combined with secondary validation from ECHA guidance documents, EU Regulation 1107/2009 implementation reports, and Central Insecticides Board registration databases. Bottom-up trap density estimates from Mediterranean orchard zones and top-down market sizing from fermentation capacity disclosures were triangulated to cross-verify volume assumptions.
Comparable-period anchoring to historical authorization timelines under EU Regulation 1107/2009 shaped the projection horizon for adoption curve modeling. Segmentation dimensions across the modeling period included molecular architecture type, delivery mechanism form, application function, and end-user production system intensity. CAGRs were derived from pest pressure forecasting correlated with EU Farm to Fork Strategy implementation trajectories and organic farming conversion rates. Industry-specific inputs incorporated EFSA field trial duration requirements for perennial crop authorizations and precision fermentation yield improvement curves.
Several conditions sit outside the modeled scope, including unforeseen ECHA VOC emission threshold revisions, citrus peel waste supply disruptions from Spanish processing plant closures, and synthetic pheromone cost breakthroughs that could accelerate substitution in lepidopteran IPM systems. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Rapid-Set Gelatin Market
Ingredients
Homecare Ingredients Market
Ingredients
Wheat Germ Oil Market
Ingredients
Native Starch Market
Ingredients
Egg White Powder Market
Ingredients
Sweet Almond Oil Market
Ingredients
Dried Fruit Ingredients Market
Ingredients
Resistant Starch Market
Ingredients
Yeast Autolysates Market
Ingredients
Agar Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
India Gelatin Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Low Calorie Oil Market
Ingredients
Egg Phosphatidylcholine Market
Ingredients
Mustard Flour Market