
 Pastry Margarine Market | 2026-2036
Pastry Margarine Market Size, Share, and Industry Trends Forecast 2026-2036
Pastry Margarine Market Analytics
Premium block margarine with higher melting point specifications is redrawing competitive boundaries in laminated pastry production. Bunge Limited leverages its South American oilseed crushing network to sustain cost-advantaged supply of high-oleic base oils. Fuji Oil anchors Asian bakery channel relationships through specialized emulsifier-margarine blends for croissant and Danish applications.
Pastry margarine is an emulsified fat product formulated from refined vegetable oils or animal fats, containing minimum eighty percent fat content with controlled plasticity and melting profiles engineered for dough lamination and puff pastry construction. Block margarine dominates industrial bakery procurement due to its dimensional stability in sheeting operations, while liquid margarine gains traction in automated food service dispensing systems where pumpability reduces handling labor. Palm oil-based formulations retain volume leadership on raw material cost, though coconut oil variants command margin premiums in clean-label and dairy-free positioning.
FDA standards of identity for margarine in the United States, EFSA novel food assessments for alternative fat bases in Europe, and BIS labeling requirements for edible fats in India collectively shape product formulation pathways and cross-border market access conditions. EU REACH compliance and emerging carbon footprint disclosure rules under CSRD are adding compliance layers that favor suppliers with integrated sustainability certification. Stakeholders must evaluate which regulatory trajectory—clean-label simplification or process transparency mandates—will dictate procurement specifications in their priority markets.
Market Dynamics
EU F-Gas Regulation phase-downs are forcing industrial margarine processors to abandon conventional mechanical refrigeration in favor of lower-emission thermal processing technologies, reshaping capital deployment and supplier qualification criteria across European bakery supply chains.
Growth Catalysts
- Clean-label reformulation:Bakery chains in Indonesia's industrial corridor near Jakarta are specifying palm-free and dairy-free pastry fat bases to meet export-market labeling requirements.
- REACH compliance integration:EU chemical disclosure mandates are accelerating adoption of certified sustainable palm oil through mass-balance chain-of-custody systems.
- Automated lamination:Industrial bakeries are retrofitting sheeting lines with precision temperature control that demands higher-melting-point block margarine specifications.
Market Restraints
- Feedstock concentration risk:Southeast Asian palm oil supply disruptions from El Niño weather patterns expose formulators to input cost volatility.
- Technical limitation in aeration:High-oleic sunflower oil bases fail to replicate the oxidative stability required for extended shelf-life laminated products.
- Regulatory friction from BIS labeling:India's edible fat disclosure requirements create compliance overhead for imported margarine formulations.
Strategic Opportunities
- Underpenetrated geography:Vietnam's organized bakery sector remains below regional penetration rates for premium laminated dough fats.
- Regulatory tailwind:EU CSRD carbon footprint disclosure rules favor suppliers with integrated Life Cycle Assessment certification.
- Technology convergence:Precision fermentation-derived dairy proteins are converging with plant lipid systems to create hybrid clean-label emulsifiers.
Industry Challenges
- Refrigeration engineer scarcity:The shift to CO2 and ammonia-based cooling systems demands process engineering skills in short supply across European margarine processing facilities.
- Certification timeline compression:RSPO and ISCC certification audits for sustainable palm sourcing are extending lead times for new supplier qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pastry Margarine Market |
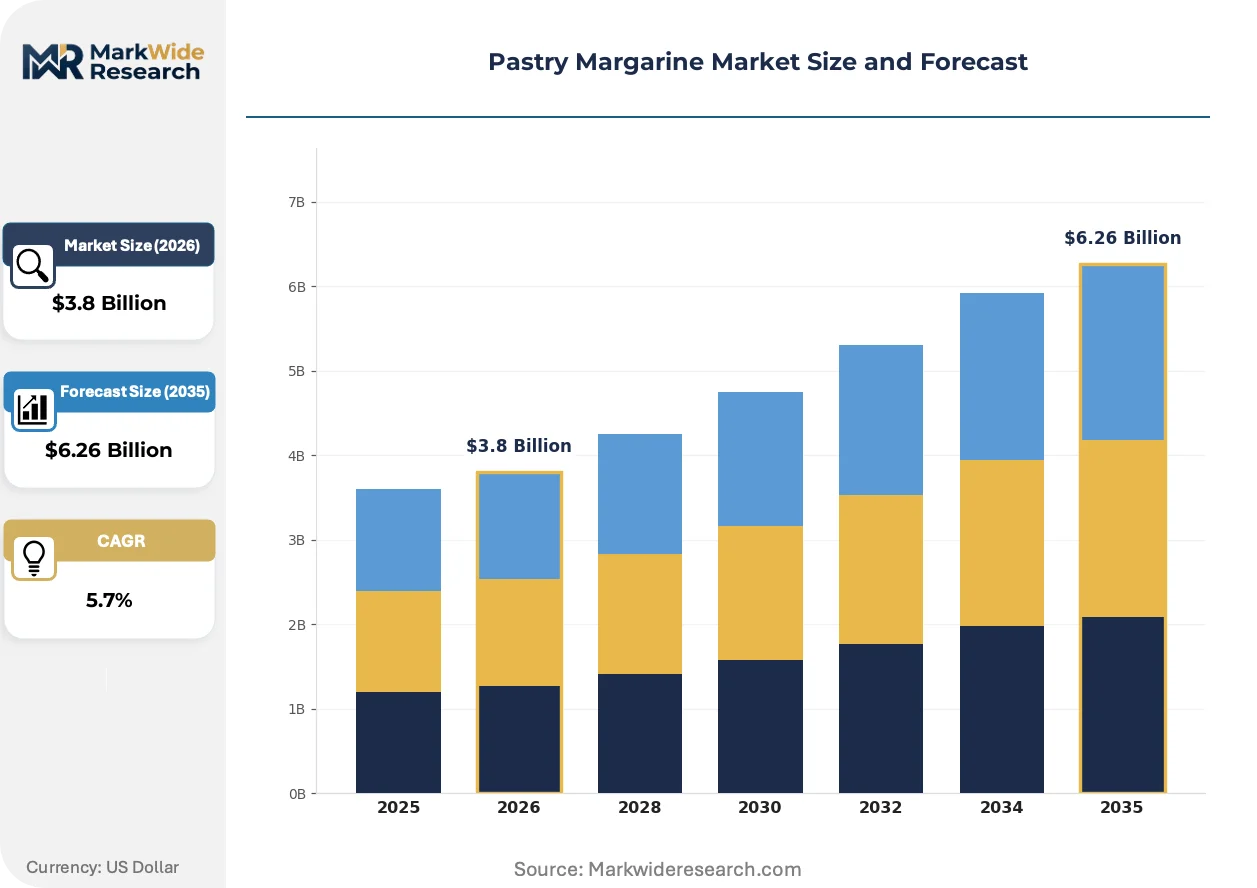
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block Margarine, Liquid Margarine, Spreadable Margarine, Whipped Margarine Ingredient Source: Vegetable Oil, Animal Fat, Palm Oil, Coconut Oil Application: Baking, Spreading, Cooking, Frying End User: Bakery, Food Service, Retail, Catering |
| Companies Covered | AAK AB, Bunge Limited, Cargill, Wilmar International, Fuji Oil, Puratos Group, Vandemoortele, Archer Daniels Midland, IOI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pastry Margarine Market Evolving Landscape
Processing technology and procurement specifications are diverging sharply between premium artisan channels and mass-market industrial bakery, creating parallel innovation tracks with little technology overlap.
Membrane filtration systems for fractionating specialty fats without solvent extraction are miniaturizing. European premium margarine specialists are adopting these units for pilot-scale production of custom melting-profile formulations. The technology is miniaturizing capital barriers for regional processors seeking to compete with multinational commodity suppliers on specification flexibility.
EU F-Gas Regulation bans on hydrofluorocarbon refrigerants above specific Global Warming Potential thresholds are compelling margarine plants to install transcritical CO2 heat pumps. Industrial bakeries in Germany and France now audit supplier processing carbon intensity as a procurement criterion. Facilities without retrofit roadmaps face exclusion from approved vendor lists.
Specification-driven contracting is replacing spot purchasing among Southeast Asian bakery chains. Industrial buyers in Indonesia now negotiate annual volume commitments with technical service attachments rather than commodity tenders. This shift concentrates procurement influence with formulators capable of co-developing laminated dough recipes.
Pastry Margarine Market Segmentation
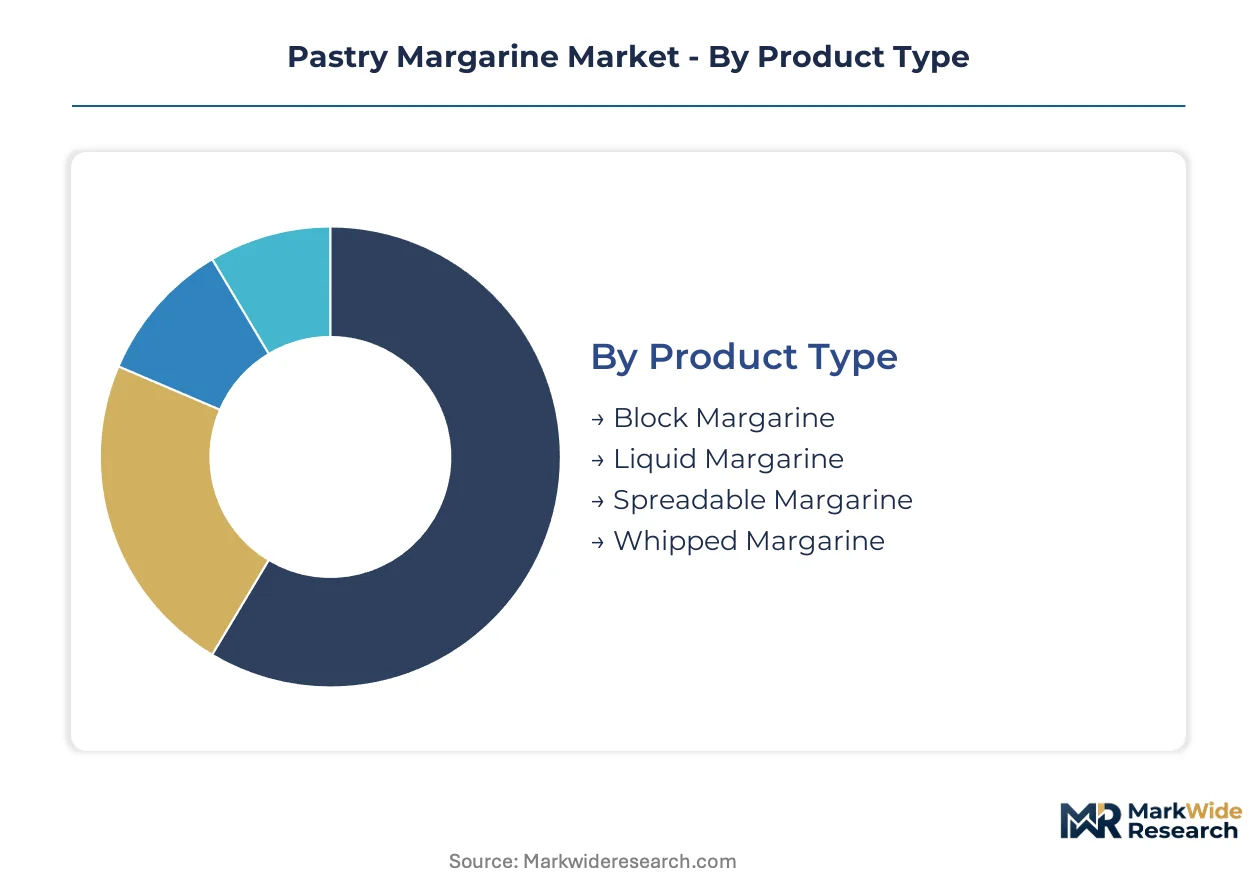
Pastry margarine segmentation reflects divergent technical requirements between industrial lamination and food service dispensing. Specification differentiation across melting profiles, plasticity ranges, and emulsifier systems determines procurement patterns and supplier qualification criteria.
Product Type:
Regulatory differentiation in thermal processing standards separates block formulations from pumpable alternatives across EU F-Gas compliance zones.
- Block Margarine:Dimensional stability in sheeting operations depends on controlled crystallization of high-oleic base oils within narrow temperature bands. Industrial bakeries in Germany and France specify block formats for automated lamination lines requiring precise fat layer deposition.
- Liquid Margarine:Pumpability at ambient temperatures reduces handling labor in automated food service dispensing systems. Demand concentrates in Southeast Asian quick-service chains retrofitting equipment for reduced refrigeration loads.
- Spreadable Margarine:Modified crystalline structure enables knife-spreadability at refrigerated temperatures through interesterification processing.
- Whipped Margarine:Nitrogen-injected aeration yields reduced density for portion-controlled retail and catering applications.
Block margarine handles the majority of throughput; liquid margarine is gaining share fastest among food service operators.
Ingredient Source:
Raw material cost tiers stratify procurement between commodity palm bases and premium coconut alternatives serving clean-label positioning.
- Vegetable Oil:Refined soybean, sunflower, and rapeseed oils provide cost-advantaged bases through South American and Black Sea crushing networks. EU REACH compliance documentation requirements favor suppliers with integrated solvent extraction and refining capabilities.
- Palm Oil:Fractionated palm stearin delivers the crystalline β' polymorph essential for laminated dough plasticity. RSPO mass-balance certification now gates supply contracts with European industrial bakery chains.
- Animal Fat:Tallow and lard bases retain niche demand in traditional European pastry applications requiring specific flavor profiles.
- Coconut Oil:Lauric acid content enables rapid melting and clean flavor release in premium positioning. Indonesia's export-oriented bakery corridor near Jakarta specifies coconut bases for dairy-free labeling compliance.
Palm oil manages the majority of volume; coconut oil is climbing the fastest on clean-label premium positioning.
Application:
Functional performance requirements separate lamination-grade specifications from general cooking applications on oxidative stability and smoke point criteria.
- Baking:Laminated pastry construction demands controlled plasticity across sheeting temperature ranges. Automated production lines in Vietnam's emerging industrial bakery sector specify high-melting-point formulations for croissant and Danish applications.
- Spreading:Table-use margarine requires spreadability at refrigeration temperatures through modified fat crystal networks.
- Cooking:Sauté and sauce applications prioritize flavor neutrality and heat stability.
- Frying:Extended fry life depends on low polyunsaturated fatty acid content and antioxidant systems.
Baking commands the majority of specification-driven procurement; spreading shows the steepest expansion trajectory in retail channels.
End User:
Customer scale and technical service requirements concentrate supply relationships differently across artisan, industrial, and institutional channels.
- Bakery:Industrial producers negotiate annual volume commitments with attached technical service for recipe co-development. Specification-driven contracting now dominates procurement in Indonesia's organized bakery sector.
- Food Service:Pumpable formats and portion control systems drive equipment compatibility requirements.
- Retail:Branded and private-label positioning depends on clean-label claims and packaging differentiation.
- Catering:Bulk formats and extended ambient stability serve institutional feeding operations.
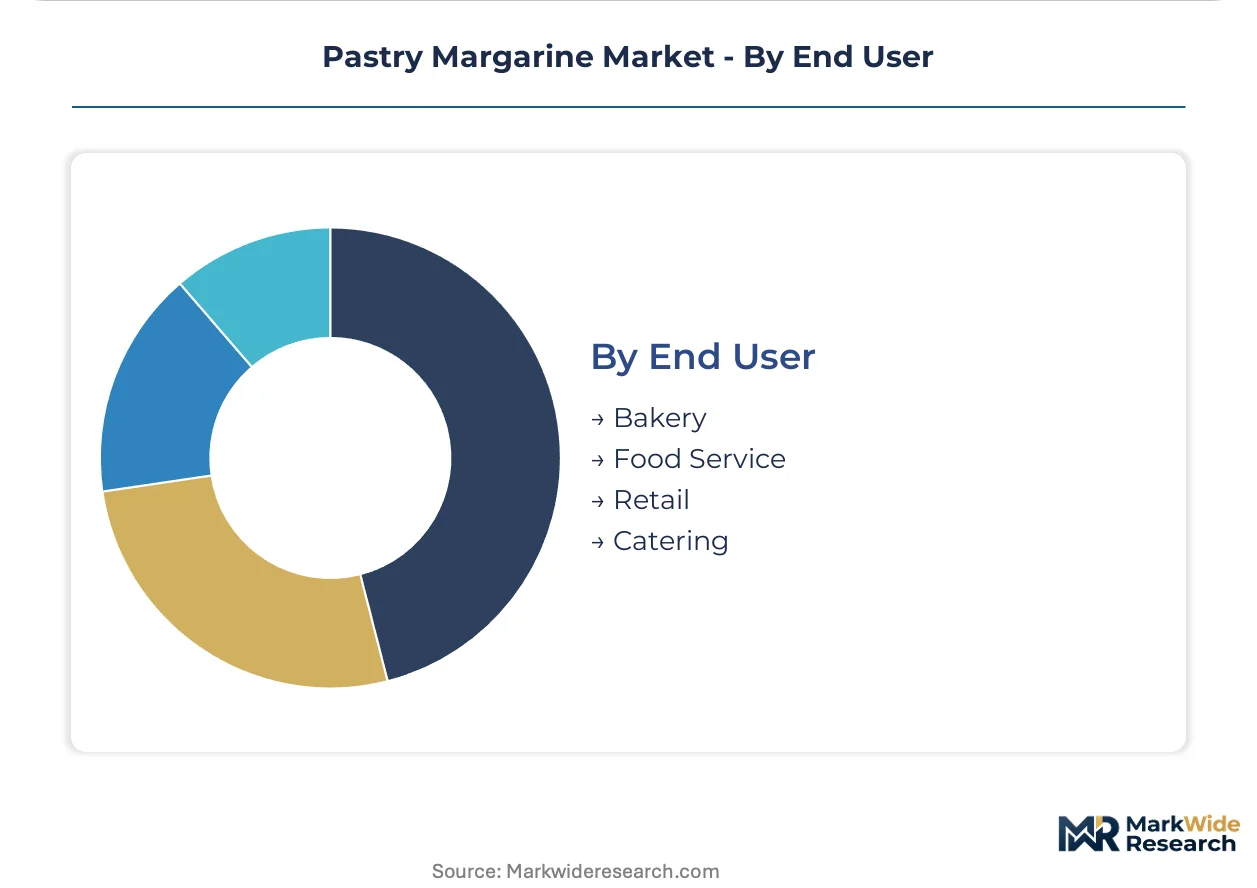
Bakery channels handle the majority of premium formulation volume; food service is expanding most quickly on automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fractionation capacity for specialty fats clusters in Southeast Asian palm processing corridors, while European reformulation demands concentrate procurement leverage with German and French industrial bakery chains. Regulatory divergence on carbon disclosure and clean-label standards is fragmenting supply chain configurations across major consumption zones.
Germany
Industrial bakery automation and EU F-Gas Regulation compliance dominate procurement specifications for transcritical CO2 processing systems. ECHA REACH documentation requirements gate supply contracts with mass-balance chain-of-custody certification. The Rhine-Ruhr industrial corridor hosts margarine retrofit investments targeting approved vendor status with carbon-intensity auditing.
Indonesia
Export-oriented bakery chains near Jakarta specify coconut oil bases for dairy-free labeling compliance in destination markets. BIS-equivalent national standards for edible fat disclosure shape import substitution strategies. The industrial bakery corridor concentrates procurement volume for premium laminated dough applications serving regional quick-service expansion.
France
Artisan bakery chain consolidation drives specification-driven contracting for higher-melting-point block margarine formats. EU CSRD carbon footprint disclosure rules favor suppliers with integrated Life Cycle Assessment certification. The Paris Basin hosts technical service co-development programs linking formulators to automated lamination line retrofits.
Vietnam
Organized bakery sector penetration remains below regional benchmarks, creating procurement expansion potential for croissant and Danish fat specifications. Emerging food safety regulations align with ASEAN harmonization frameworks. Ho Chi Minh City's industrial zones attract Southeast Asian distribution hub investments for pumpable margarine formats.
United States
FDA standards of identity for margarine shape reformulation pathways for high-oleic base oil substitutions. Clean-label positioning in retail channels accelerates interest in palm-free and interesterified alternatives. The Midwest crushing corridor sustains cost-advantaged supply networks for domestic bakery and food service procurement.
Pastry Margarine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the pastry margarine supply base. The market structure consolidates around integrated oilseed processors with captive fractionation capacity, while specialized emulsifier formulators occupy specification-driven niches. Three archetypes dominate: multinational agribusiness conglomerates with South American and Southeast Asian oilseed networks; European premium specialists with membrane filtration pilot capabilities; and Asian channel-anchored blenders with technical service attachments. Competitive moves concentrate on sustainability certification pre-qualification and precision temperature control co-development with industrial bakery automation vendors.
Among integrated agribusiness conglomerates, Bunge Limited and Cargill occupy positions defined by upstream oilseed crushing scale and downstream fractionation integration. Fuji Oil anchors the Asian bakery channel specialist archetype through emulsifier-margarine blend capabilities. AAK AB exemplifies the European premium formulation tier with specialized fat crystallization expertise. Vandemoortele and Puratos Group sit within the continental European industrial bakery service model, while Wilmar International and IOI Corporation represent Southeast Asian palm-based supply concentration. Archer Daniels Midland completes the multinational processor set with North American oilseed network leverage.
| Leading Market Players |
|---|
| AAK AB |
| Bunge Limited |
| Cargill |
| Wilmar International |
| Fuji Oil |
| Puratos Group |
| Vandemoortele |
| Archer Daniels Midland |
| IOI Corporation |
| Others |
Value Network & Pricing Analysis
Annual volume commitments with technical service attachments now dominate procurement contracts between Indonesian industrial bakeries and specialty fat formulators, locking in supply access and price visibility across multi-year horizons while insulating buyers from spot palm oil volatility.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure for pastry margarine across European procurement zones. Three-tier pricing structure across premium, standard, and economy levels separates RSPO-certified sustainable bases from conventional mass-balance formulations and commodity palm alternatives. Cost compression in economy-tier block margarine is intensifying because El Niño weather patterns disrupt Southeast Asian feedstock supply. Industrial bakery chains in Germany exhibit the lowest price sensitivity due to specification-driven contracting, while Southeast Asian quick-service operators show highest sensitivity to pumpable format premiums.
Supply Chain Analysis
Inventory cycles for fractionated palm stearin extend to twelve weeks during monsoon disruptions, compressing formulator margins. Supply concentrates in Indonesia, Malaysia, and the Netherlands, with Rotterdam serving as the primary European entry point for refined specialty fats. Raw material dependencies center on crude palm oil, high-oleic sunflower oil, and coconut oil. Single-source vulnerability from Malaysian port congestion threatens just-in-time delivery to German automated lamination lines. Distribution runs through integrated oilseed processors with captive fractionation capacity rather than independent traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification divergence between artisan and industrial channels fragments procurement influence, creating niche opportunities for regional formulators with membrane filtration pilot capabilities and technical service co-development programs.
For Market Incumbents: Secure RSPO and ISCC certification pre-qualification ahead of EU CSRD carbon disclosure enforcement, insulating approved vendor status from emerging European bakery chain procurement audits. Deepen backward integration into South American high-oleic crushing networks to offset Southeast Asian palm supply disruption risk. Anchor technical service teams within Vietnam's emerging industrial bakery corridor to capture specification-driven contracting before multinational competitors establish relationships. For New Entrants and Emerging Players: Anchor in Vietnam's underpenetrated organized bakery sector, where croissant and Danish fat specifications remain below regional adoption benchmarks. Target food service automation retrofit programs in Ho Chi Minh City industrial zones with pumpable margarine formats designed for reduced refrigeration loads. Pursue co-development partnerships with European membrane filtration equipment vendors to bypass capital barriers blocking commodity supplier competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Asian channel-anchored blenders with annual technical service attachments rather than spot-dependent commodity traders. Five-to-ten year viability favors acquisition targets with integrated Life Cycle Assessment certification and transcritical CO2 processing retrofit roadmaps. Monitor EU F-Gas Regulation enforcement timelines as the inflection signal for stranded asset risk among conventional mechanical refrigeration facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Bunge Limited's South American network demonstrates cost-advantaged high-oleic base oil security. |
| Membrane Filtration Pilot Adoption | European premium specialists deploy solvent-free fractionation for custom melting-profile flexibility. |
| RSPO Mass-Balance Certification | AAK AB leverages chain-of-custody systems to gate supply contracts with German industrial bakeries. |
| Technical Service Co-Development | Fuji Oil anchors Asian bakery relationships through emulsifier-margarine blend recipe partnerships. |
| Transcritical CO2 Retrofit Investment | Rhine-Ruhr facilities target approved vendor status via carbon-intensity auditing compliance. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plant managers at European margarine processing facilities, procurement leads at Indonesian industrial bakery chains, emulsifier R&D directors, and distribution channel partners; and secondary validation through customs and trade data, SEC filings of integrated oilseed processors, ECHA REACH documentation databases, and RSPO certification registries. Bottom-up volume estimates from application-level consumption patterns were triangulated against top-down capacity assessments from fractionation facility disclosures.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, ingredient source, application, and end-user channel, with additional cross-cutting analysis of regulatory compliance tier and sustainability certification status. CAGRs were derived from trend extrapolation of specification-driven contracting adoption rates and automation investment cycles in target geographies. Forecast inputs incorporated EU F-Gas Regulation phase-down timelines and El Niño weather pattern probability distributions affecting Southeast Asian feedstock supply.
Decision-makers should treat outputs as directional under assumptions of continued EU regulatory enforcement and stable ASEAN trade framework conditions; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
South America Ice Cream Market
Bakery Products
Frozen Bakery Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Low-Calorie Pie Market
Bakery Products
Laminated Dough Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
North America Pizza Oven Market
Bakery Products
Wedding Cakes Market
Bakery Products
Tunnel Bakery Oven Market
Bakery Products
Cake Concentrate Market
Bakery Products
Bread Improver Market
Bakery Products
Ice Cream Market
Bakery Products
Bread Market
Bakery Products
Pizza Crust Market
Bakery Products
Middle East and Africa Fortified Bakery Products Market