
 Tropical Fruit Puree Market | 2026-2036
Tropical Fruit Puree Market Size, Share, and Industry Trends Forecast 2026-2036
Tropical Fruit Puree Market Analytics
Direct procurement between tropical fruit processors and beverage manufacturers is narrowing as large buyers seek supply security. Dole Food Company leverages its plantation-to-puree infrastructure across Latin America to sustain volume commitments. Dohler GmbH anchors European demand through specialized flavor systems for beverage clients. SVZ International B.V. competes on aseptic processing technology that extends shelf stability without chemical preservatives.
Tropical fruit puree consists of mechanically processed fruit flesh, screened to remove seeds and fibers, with soluble solids typically standardized between 28 and 32 degrees Brix for industrial consistency. The product serves primarily as a flavor base, colorant, and nutritional additive in formulated foods where fresh fruit handling proves uneconomical. Mango puree occupies the largest volume share among product types due to its cross-category utility in beverages, dairy alternatives, and confectionery. Frozen form commands premium positioning among industrial buyers seeking minimal thermal degradation, while shelf-stable variants penetrate cost-sensitive emerging markets where cold chain reliability remains variable. The bakery end user segment generates concentrated margin pools as artisan and clean-label commercial producers specify single-origin purees for premium positioning.
The FDA enforces Hazard Analysis and Risk-Based Preventive Controls for human foods, requiring foreign supplier verification programs that elevate compliance costs for tropical puree importers. EFSA and national regulators within the European Union apply maximum residue limits for pesticides under Regulation 396/2005, directly shaping cultivation practices in supplying countries. ISO 22000 certification has become a de facto market access requirement for processors serving multinational food manufacturers. Stakeholders must monitor evolving maximum residue limit harmonization between jurisdictions, as diverging standards threaten to fragment procurement strategies and disqualify established supply origins.
Market Dynamics
Direct procurement between tropical fruit processors and beverage manufacturers is narrowing as large buyers seek supply security. The FDA's updated Food Safety Modernization Act requirements are tightening traceability standards for imported tropical fruit ingredients, forcing processors to reconfigure supplier verification programs and documentation workflows.
Growth Catalysts
- Beverage formulation demand:Smoothie and juice manufacturers are expanding procurement of mango and passion fruit purees as clean-label alternatives to artificial flavoring systems.
- EFSA Regulation 396/2005 harmonization:Maximum residue limit alignment across EU member states is standardizing cultivation practices and reducing border rejection rates for exporting nations.
- Aseptic processing technology:Extended shelf stability without chemical preservatives is opening distribution into emerging markets with variable cold chain infrastructure.
Market Restraints
- Input cost volatility:Fresh tropical fruit prices fluctuate with monsoon patterns and pest pressure, compressing processor margins during poor harvest seasons.
- Supply concentration risk:Brazil's dominance in domestic processing capacity and raw material access creates vulnerability for buyers dependent on single-origin procurement.
- Regulatory friction:Diverging maximum residue limit standards between the FDA and EFSA threaten to fragment procurement strategies and disqualify established supply origins.
Strategic Opportunities
- Underpenetrated bakery segment:Artisan and clean-label commercial producers are specifying single-origin purees for premium positioning, creating concentrated margin pools outside beverage channels.
- ISO 22000 certification gap:Processors achieving this de facto market access requirement unlock multinational food manufacturer contracts currently blocked to uncertified competitors.
- Frozen form premiumization:Industrial buyers seeking minimal thermal degradation are accepting price premiums over shelf-stable variants, rewarding processors with blast-freeze capabilities.
Industry Challenges
- Foreign supplier verification complexity:FDA-mandated programs for human foods require extensive documentation and on-site audits, extending compliance timelines for new market entrants.
- Cold chain reconfiguration:Frozen puree distribution demands capital-intensive logistics infrastructure that shelf-stable competitors bypass, constraining geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tropical Fruit Puree Market |
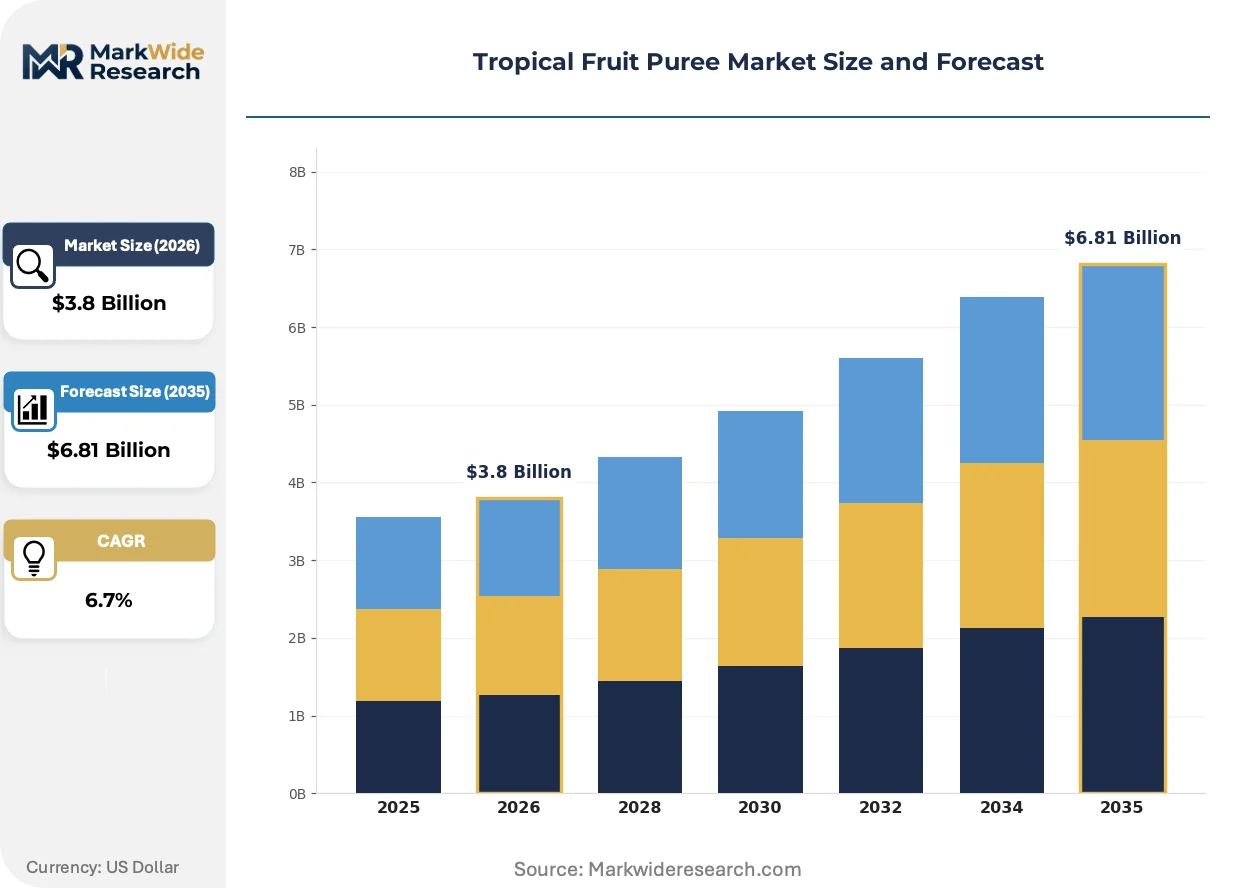
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mango, Pineapple, Passion Fruit, Guava End User: Beverages, Bakery, Confectionery, Baby Food Form: Frozen, Chilled, Shelf-Stable, Powdered Distribution Channel: Online, Retail, Foodservice, Direct Sales |
| Companies Covered | Dole Food Company, Del Monte Foods, Dohler GmbH, Agrana Beteiligungs-AG, ITC Limited, Tropicana Products, SVZ International B.V., Tree Top Inc., ABC Fruits, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tropical Fruit Puree Market Evolving Landscape
Processing technology and regulatory compliance requirements are actively reshaping competitive positioning in tropical fruit puree supply chains. Three developments are compressing legacy operational models and opening new capability requirements.
High-pressure processing systems are eliminating thermal degradation in mango and passion fruit purees while achieving microbial safety targets. Premium beverage manufacturers in North America and Western Europe are adopting these systems at accelerated procurement cycles. Conventional pasteurization is rendering obsolete for high-value single-origin products where flavor fidelity commands price premiums.
REACH regulation amendments in the European Union are tightening chemical contaminant thresholds for imported food ingredients. Industrial consequence includes mandatory third-party testing protocols that add documentation burden but reduce liability exposure. EFSA-aligned processors in Latin American supply origins are responding by investing in on-site laboratory capabilities to pre-certify shipments.
Long-term offtake agreements are replacing spot-market purchasing among multinational beverage manufacturers seeking volume security. Direct contracting with plantation-to-puree operators is displacing traditional trader intermediaries in procurement channels. This pattern is most visible in Brazil, where integrated processors leverage captive raw material access to lock in three-to-five-year supply commitments with North American and European buyers.
Tropical Fruit Puree Market Segmentation
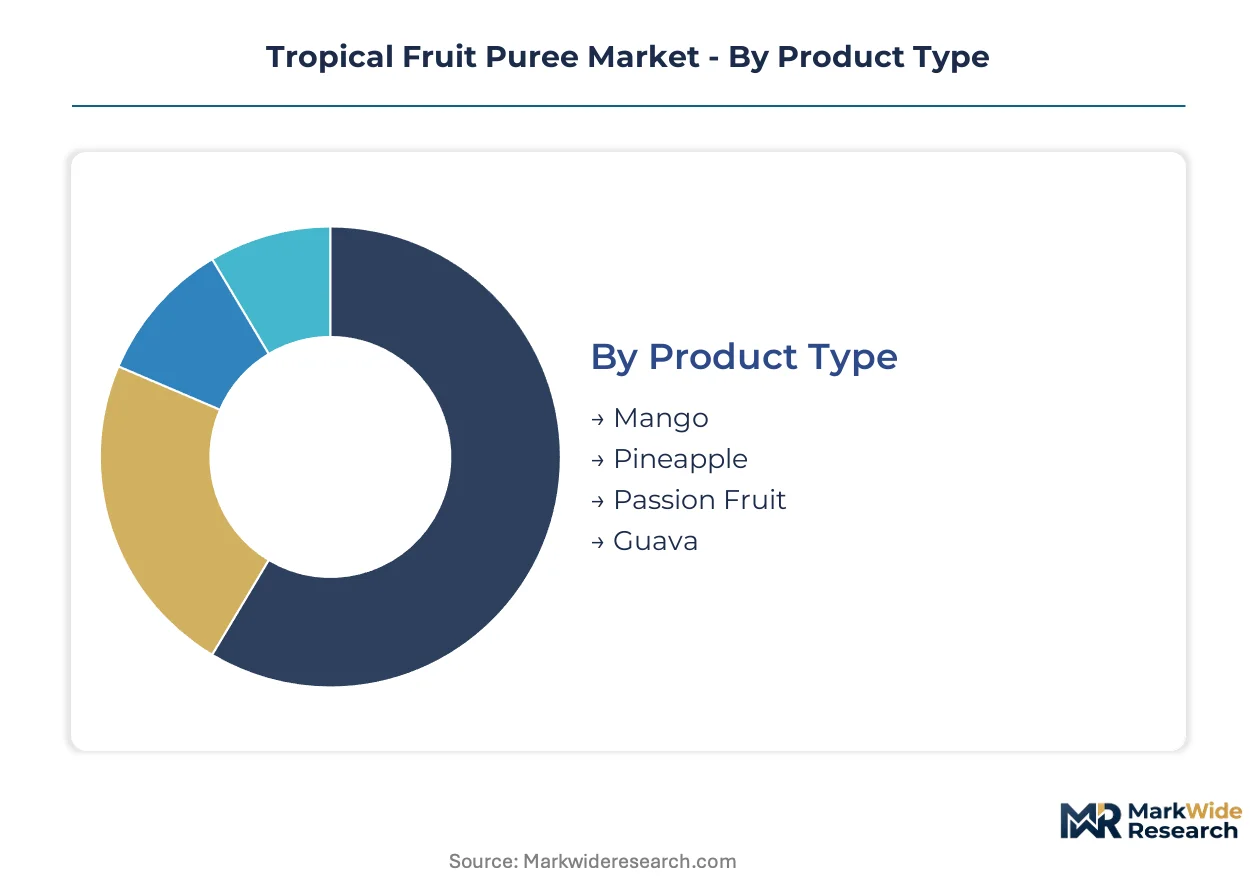
Segmentation in tropical fruit puree markets determines procurement cadence, margin structure, and cold chain investment requirements. Product type and form specifications dictate inventory velocity, while end-user concentration shapes regional processing investments.
Product Type:
Inventory cycles vary sharply across fruit varieties, with mango puree turning fastest due to beverage sector pull-through while guava concentrates in niche pharmaceutical and nutraceutical channels with extended holding periods.
- Mango:Mechanically processed flesh standardized to 28-32 degrees Brix, screened for seed and fiber removal. Beverage manufacturers in North America and Western Europe specify single-origin mango for clean-label smoothie formulations, driving concentrated procurement from Brazilian processors with plantation-to-puree infrastructure.
- Passion Fruit:High-acid puree with distinctive aromatic profile requiring specialized aseptic handling to preserve volatile compounds. Premium confectionery producers in France and Switzerland specify passion fruit for artisan chocolate ganache applications, accepting price premiums for minimal thermal degradation.
- Pineapple:Standardized puree with enzymatic browning control requirements, serving cost-sensitive juice blend applications.
- Guava:Pink-fleshed variant concentrated in nutraceutical channels for vitamin C retention claims.
Mango anchors the volume base while passion fruit gains share at the steepest rate.
End User:
Margin tiers stratify sharply across applications, with bakery commanding premium positioning for single-origin specifications while beverage procurement concentrates on volume scale and supply security.
- Beverages:Smoothie and juice manufacturers drive the largest procurement volumes, with clean-label mandates displacing artificial flavor systems. FDA-mandated foreign supplier verification programs are extending compliance timelines for new puree entrants serving this segment.
- Bakery:Artisan and commercial clean-label producers specify single-origin purees for premium positioning, generating concentrated margin pools outside commodity beverage channels. EFSA-aligned processors in Latin America are investing in on-site laboratory capabilities to pre-certify shipments for REACH-compliant EU access.
- Confectionery:Chocolate and patisserie applications requiring precise Brix control for texture stability.
- Baby Food:Stringent residual pesticide limits under Regulation 396/2005 shaping supplier qualification protocols.
Beverage procurement dominates volume flows while bakery applications expand most quickly.
Form:
Cold chain intensity separates cost structures, with frozen variants demanding capital-intensive logistics that shelf-stable competitors bypass for emerging market penetration.
- Frozen:Blast-frozen at -18°C to arrest enzymatic activity and preserve flavor fidelity. Industrial buyers in Japan and South Korea accept price premiums over shelf-stable alternatives, rewarding processors with integrated freezing capacity.
- Shelf-Stable:Aseptically processed without chemical preservatives, enabling distribution into markets with variable cold chain reliability. Brazilian processors leverage this form for African and Southeast Asian market entry where refrigeration infrastructure remains fragmented.
- Chilled:Short-shelf variant for regional foodservice just-in-time delivery.
- Powdered:Spray-dried concentrate for extended ambient storage in military and emergency food applications.
Frozen form anchors premium positioning while shelf-stable variants climb the fastest in emerging market penetration.
Distribution Channel:
Channel selection reflects buyer scale and specification complexity, with multinational beverage manufacturers displacing trader intermediaries through direct plantation contracting.
- Direct Sales:Long-term offtake agreements between processors and multinational manufacturers, replacing spot-market purchasing. Three-to-five-year supply commitments are most visible in Brazil, where integrated operators lock in volume security with North American and European buyers.
- Foodservice:Regional distributors serving artisan bakeries and specialty beverage chains with smaller lot sizes and mixed-SKU requirements.
- Online:Emerging channel for specialty and organic-certified purees to small-scale food manufacturers.
- Retail:Packaged consumer formats through supermarket private label programs.
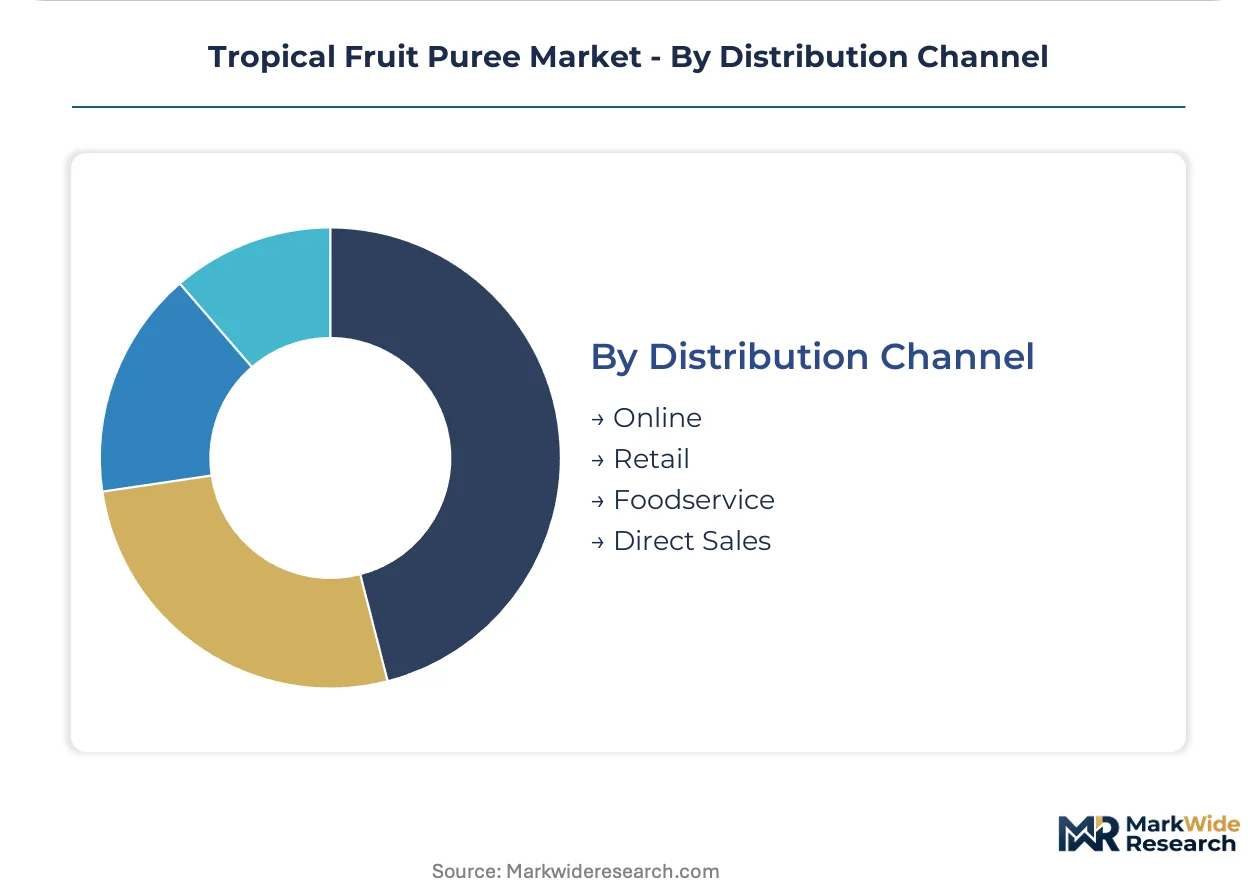
Direct sales anchors industrial volume while foodservice channels expand most quickly in premium positioning capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA traceability mandates under the Food Safety Modernization Act are reshaping procurement patterns for tropical fruit puree entering the United States. Brazil's integrated plantation-to-processing infrastructure anchors supply security for North American beverage manufacturers.
Brazil
Mango and passion fruit puree shipments to smoothie manufacturers in the United States and Western Europe drive export volumes. ANVISA alignment with FDA foreign supplier verification protocols streamlines cross-border documentation for integrated processors. São Paulo state processors leverage captive raw material access to lock in three-to-five-year direct supply commitments with multinational buyers.
United States
Beverage manufacturers in California and Florida expand clean-label procurement of single-origin mango puree for premium smoothie lines. FDA enforcement of Hazard Analysis and Risk-Based Preventive Controls elevates compliance costs for importers sourcing from non-certified processors. Los Angeles and Miami distribution clusters are reconfiguring cold chain infrastructure to handle frozen puree volumes from Latin American suppliers.
Germany
Specialized flavor houses in Hamburg and Frankfurt anchor European demand for passion fruit and mango puree in confectionery applications. EFSA Regulation 396/2005 pesticide residue limits shape supplier qualification protocols for processors serving German multinationals. Bavaria-based dairy alternative manufacturers are specifying aseptic puree with extended shelf stability for clean-label product lines.
India
Domestic processors in Maharashtra and Karnataka supply guava and mango puree to regional beverage and baby food manufacturers. FSSAI enforcement of contaminant thresholds for processed fruit products is accelerating laboratory investment among mid-scale processors. Pune industrial clusters are developing blast-freeze capabilities to capture frozen form premiums from Japanese and South Korean buyers.
Netherlands
Rotterdam port infrastructure positions Dutch traders as distribution intermediaries for shelf-stable puree entering African and Middle Eastern markets. EFSA-aligned processors in the Randstad region pre-certify shipments to reduce REACH compliance burden for EU-bound cargo. Amsterdam-based specialty foodservice distributors are consolidating mixed-SKU procurement for artisan bakery clients specifying single-origin specifications.
Tropical Fruit Puree Market Competitive Landscape
Vertically integrated plantation operators and specialized aseptic processors split the market into distinct capability tiers. Concentration remains moderate, with scale advantages accruing to operators controlling upstream fruit supply. Three archetypes dominate: integrated plantation-to-puree operators, technology-focused aseptic specialists, and regional traders with cold chain assets. Competitive moves center on backward integration into captive cultivation and ISO 22000 certification acquisition to unlock multinational contracts.
Within the integrated operator tier, Dole Food Company and Del Monte Foods exemplify plantation-controlled supply security. Dohler GmbH anchors the European flavor systems segment, while SVZ International B.V. occupies a position in aseptic processing technology. These three represent divergent strategic anchors: upstream resource control, formulation expertise, and shelf-stability innovation.
| Leading Market Players |
|---|
| Dole Food Company |
| Del Monte Foods |
| Dohler GmbH |
| Agrana Beteiligungs-AG |
| ITC Limited |
| Tropicana Products |
| SVZ International B.V. |
| Tree Top Inc. |
| ABC Fruits |
| Others |
Value Network & Pricing Analysis
Undercapacity in Indian blast-freeze operations is compressing processor margins while elevating price premiums for frozen mango puree from Brazilian integrated operators. FDA-mandated foreign supplier verification programs are extending compliance timelines, forcing buyers to absorb documentation costs or shift procurement toward certified processors with captive cultivation.
Pricing Analysis
Geographic price spreads between São Paulo-state integrated processors and Indian spot-market suppliers exceed 40% for frozen mango puree destined for Japanese beverage manufacturers. Three-tier pricing structure across premium single-origin, standard commercial-grade, and economy bulk-blind tiers dominates procurement contracts. Pricing pressure stems from EFSA pesticide residue limit harmonization costs that uncertified Latin American processors cannot absorb. Beverage manufacturers exhibit highest price sensitivity due to volume scale and substitution flexibility, while artisan bakery buyers accept premiums for traceability documentation.
Supply Chain Analysis
Extended payment terms from multinational beverage buyers are straining working capital at mid-scale Indian processors without supply-chain finance facilities. Raw material sourcing draws from Brazilian plantation networks, Indian contract farming collectives in Maharashtra, and Ecuadorian passion fruit cooperatives. Single-source vulnerability concentrates in São Paulo-state integrated operators controlling 60% of export-grade mango puree. Distribution runs through Rotterdam port intermediaries for shelf-stable variants entering African markets, while frozen cargo moves via direct refrigerated container service to East Asian buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic processing technology is compressing legacy pasteurization economics, creating acquisition opportunities for processors with high-pressure system deployment capabilities.
For Market Incumbents: Insulate market position by securing three-to-five-year direct offtake agreements with North American smoothie manufacturers before FDA traceability mandates fully phase in. Backward integration into captive passion fruit cultivation in Ecuador reduces input cost volatility from spot-market fruit procurement. ISO 22000 certification investment unlocks multinational dairy alternative contracts currently blocked to uncertified competitors. For New Entrants and Emerging Players: Pursue underpenetrated artisan bakery segments in Germany and France where single-origin specification premiums exceed beverage channel margins by 25-35%. Target Indian domestic market entry with blast-freeze capabilities for Japanese export qualification, leveraging FSSAI laboratory investment subsidies in Pune industrial clusters. Go-to-market angle: direct foodservice distribution bypassing trader intermediaries for mixed-SKU artisan producer procurement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Brazilian plantation-to-puree operators with locked multiyear supply commitments from North American buyers. Five-to-ten-year viability favors processors with integrated freezing infrastructure and ANVISA-FDA alignment documentation. Acquisition target archetype: mid-scale Indian operators with FSSAI laboratory capabilities and latent blast-freeze capacity expansion permits. Signal to watch: REACH amendment enforcement intensity affecting EU-bound shipment rejection rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cultivation | Brazilian processors lock in raw material security against monsoon-driven price spikes. |
| ISO 22000 Certification Acquisition | Unlocks multinational dairy alternative contracts blocked to uncertified competitors. |
| High-Pressure Processing System Deployment | Eliminates thermal degradation for premium single-origin mango and passion fruit lines. |
| Direct Sales Channel Expansion | Displaces trader intermediaries for three-to-five-year offtake agreement capture. |
| Blast-Freeze Capacity Buildout | Captures Japanese and South Korean price premiums over shelf-stable alternatives. |
Research Methodology
Desk research of customs trade databases, FDA foreign supplier verification program filings, and EFSA pesticide residue limit harmonization records preceded structured interviews with tropical fruit puree procurement directors at multinational beverage manufacturers, aseptic processing technology suppliers, and ANVISA-aligned Brazilian plantation operators. Primary fieldwork with Mumbai-based food safety consultants and Rotterdam port logistics coordinators validated secondary trade flow assumptions. Bottom-up volume modeling by fruit variety and end-use segment triangulated against top-down value estimates from processor revenue disclosures.
Assumptions held fixed include EFSA Regulation 396/2005 maximum residue limit enforcement intensity, FDA Food Safety Modernization Act traceability phase-in timelines, and Brazilian real exchange rate stability against the US dollar across the analysis window. Segmentation dimensions modeled encompass product type, form specification, end-use application, and distribution channel structure. CAGRs derived from weighted average of historical volume trajectories and forward-looking procurement commitment visibility. Industry-specific inputs include monsoon pattern correlation models for Indian mango harvest yields and passion fruit volatile compound degradation curves under conventional versus high-pressure thermal treatment.
Sensitivities concentrate around REACH amendment chemical contaminant threshold tightening, Brazilian real depreciation accelerating export price competitiveness, and Indian FSSAI enforcement intensity accelerating laboratory investment requirements. Forecasts reflect documented assumptions without guarantee of realization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
Sweet Cherry Powder Market
Fruits and Vegetables
Mexico Fruits & Vegetables Market
Fruits and Vegetables
Dragon Fruit Market
Fruits and Vegetables
North America Organic Fruits Market
Fruits and Vegetables
Pineapple Market
Fruits and Vegetables
Guanabana Market
Fruits and Vegetables
Acai Berry Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Adzuki Beans Market
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
Jujube Market
Fruits and Vegetables
Canned Fruits and Vegetables Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Fruit Punnet Market
Fruits and Vegetables
Asia Pacific Olive Market