
 Pumpkin Seed Protein Market | 2026-2036
Pumpkin Seed Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Pumpkin Seed Protein Market Analytics
European organic oilseed processors are expanding cold-press and solvent-free extraction capacity to serve plant-protein formulators. Axiom Foods leverages proprietary allergen-free processing to sustain premium positioning in North American sports nutrition channels. Glanbia Nutritionals anchors global ingredient supply relationships through its dairy-alternative protein portfolio. BENEO differentiates via functional carbohydrate-protein blending expertise for bakery applications.
Pumpkin seed protein denotes the defatted, milled, and often concentrated protein fraction derived from Cucurbita pepo seeds, typically yielding 50-70% protein content by dry weight depending on extraction method, with a balanced amino acid profile notably rich in tryptophan and arginine. Manufacturers employ mechanical pressing followed by aqueous or enzymatic extraction to preserve functional properties including emulsification and water-binding capacity, rendering the ingredient suitable for meat analogues, protein fortification, and clean-label formulations. Powder formats dominate current volume owing to ease of incorporation into blended supplements and beverage bases. Protein supplements within the Application dimension attract the fastest-growing demand as gym-goers and endurance athletes shift from whey to hypoallergenic alternatives. Isolate grades command the deepest margin pools due to superior protein concentration and neutral flavor profile, though concentrate maintains broader accessibility across price-sensitive bakery and snack applications.
FDA food-labeling enforcement and EFSA novel-food authorization pathways shape ingredient market access timelines for new suppliers entering U.S. and European finished-product channels. USDA organic certification and EU organic regulation impose cultivation and handling standards that constrain supply elasticity from non-compliant origins. Stakeholders must monitor evolving amino acid bioavailability testing protocols and allergen threshold definitions, as these technical benchmarks will determine which processing technologies and sourcing regions gain formulation preference across regulated end-use categories.
Market Dynamics
Clean-label certification requirements under EFSA and FDA guidelines are tightening ingredient traceability standards, forcing processors to retrofit solvent-free extraction lines and segregate organic supply chains.
Growth Catalysts
- EU Organic Regulation:Mandatory organic handling standards in Germany and Austria are channeling investment into Styrian processing cooperatives, consolidating regional supply advantages for cold-press infrastructure.
- Sports Nutrition Formulation:Endurance athletes and gym-goers are pivoting from whey to hypoallergenic alternatives, pulling isolate-grade pumpkin seed protein into premium supplement SKUs.
- Enzymatic Extraction:Aqueous and enzymatic methods are preserving functional properties like emulsification capacity, expanding meat-analogue applications for plant-based food manufacturers.
Market Restraints
- Input Cost Volatility:Organic pumpkin seed prices fluctuate with weather-dependent harvests in Styria and Lower Austria, compressing processor margins during poor yield cycles.
- Supply Concentration Risk:Cold-press capacity clusters around Austrian and Slovenian cooperatives, creating single-point vulnerability for North American brands seeking certified organic supply.
- Regulatory Friction:EFSA novel-food authorization pathways impose multi-year timelines on new extraction entrants, delaying market access for alternative processing technologies.
Strategic Opportunities
- Underpenetrated United States:USDA organic certification gaps in domestic pumpkin cultivation create first-mover potential for vertically integrated processors establishing cold-press facilities in Oregon or Illinois.
- Functional Bakery Applications:Protein-carbohydrate blending expertise from European ingredient houses is opening clean-label fortification opportunities in artisan bread and pastry segments.
- IRA Bioeconomy Incentives:U.S. renewable chemical production credits are subsidizing capital expenditure for solvent-free extraction infrastructure serving dairy-alternative protein portfolios.
Industry Challenges
- Skill Scarcity in Enzymatic Processing:Food technologists with expertise in protease selection and hydrolysis control are concentrated in European oilseed hubs, constraining North American facility staffing.
- Capex Intensity for Cold-Press Lines:Mechanical pressing equipment with organic-certified segregation requires substantial upfront investment, limiting mid-scale processor expansion.
- Allergen Threshold Definition Lag:Evolving FDA guidance on seed protein allergenicity is creating labeling uncertainty, forcing reformulation reserves and compliance contingency spending.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pumpkin Seed Protein Market |
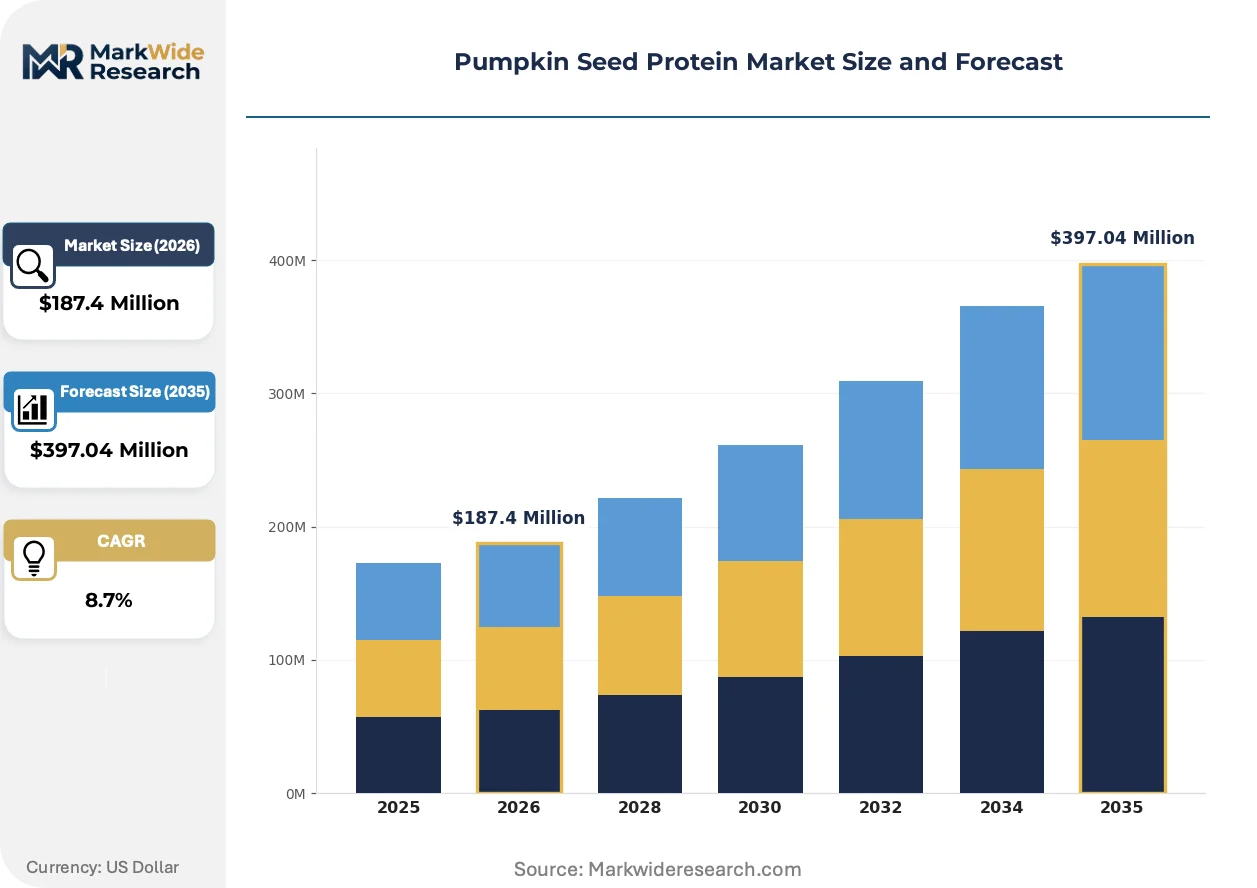
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Oil, Isolate, Concentrate End User: Food & Beverage, Nutraceuticals, Cosmetics, Animal Feed Application: Protein Supplements, Bakery Products, Snack Foods, Functional Foods Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Conagra Brands, Axiom Foods, AIDP Inc., Glanbia Nutritionals, BENEO, Jarrow Formulas, Inc., PepsiCo, BI Nutraceuticals, Bioriginal Food & Science Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pumpkin Seed Protein Market Evolving Landscape
Processing technology and procurement patterns are converging to reshape competitive positioning across certified organic supply chains, with regulatory pressure and buyer behavior shifting in parallel.
Enzymatic hydrolysis systems are modularizing extraction workflows into configurable unit operations that preserve heat-sensitive amino acids. Plant-protein formulators in Germany and the United States are adopting these systems to isolate tryptophan-rich fractions for sleep-support supplements. This modularization is compressing capital requirements for mid-scale processors, enabling cooperative-owned facilities to compete with integrated multinationals on isolate quality.
EFSA novel-food authorization pathways are extending compliance timelines for new pumpkin seed protein entrants, forcing early-stage suppliers to front-load toxicology and bioavailability studies. Finished-product brands are responding by locking multi-year offtake agreements with established processors holding grandfathered regulatory status. Sports nutrition channels in the European Union bear the highest friction, as pre-workout and recovery formulations face stricter substantiation requirements than conventional foods.
Certification-driven preference shifts are consolidating procurement around USDA organic and EU organic dual-certified suppliers. North American sports nutrition brands are disintermediating commodity traders, establishing direct relationships with Styrian processing cooperatives to secure batch-level traceability. This direct-sourcing pattern is most visible in premium isolate contracts, where clean-label claims command price premiums and liability exposure demands documented chain-of-custody.
Pumpkin Seed Protein Market Segmentation
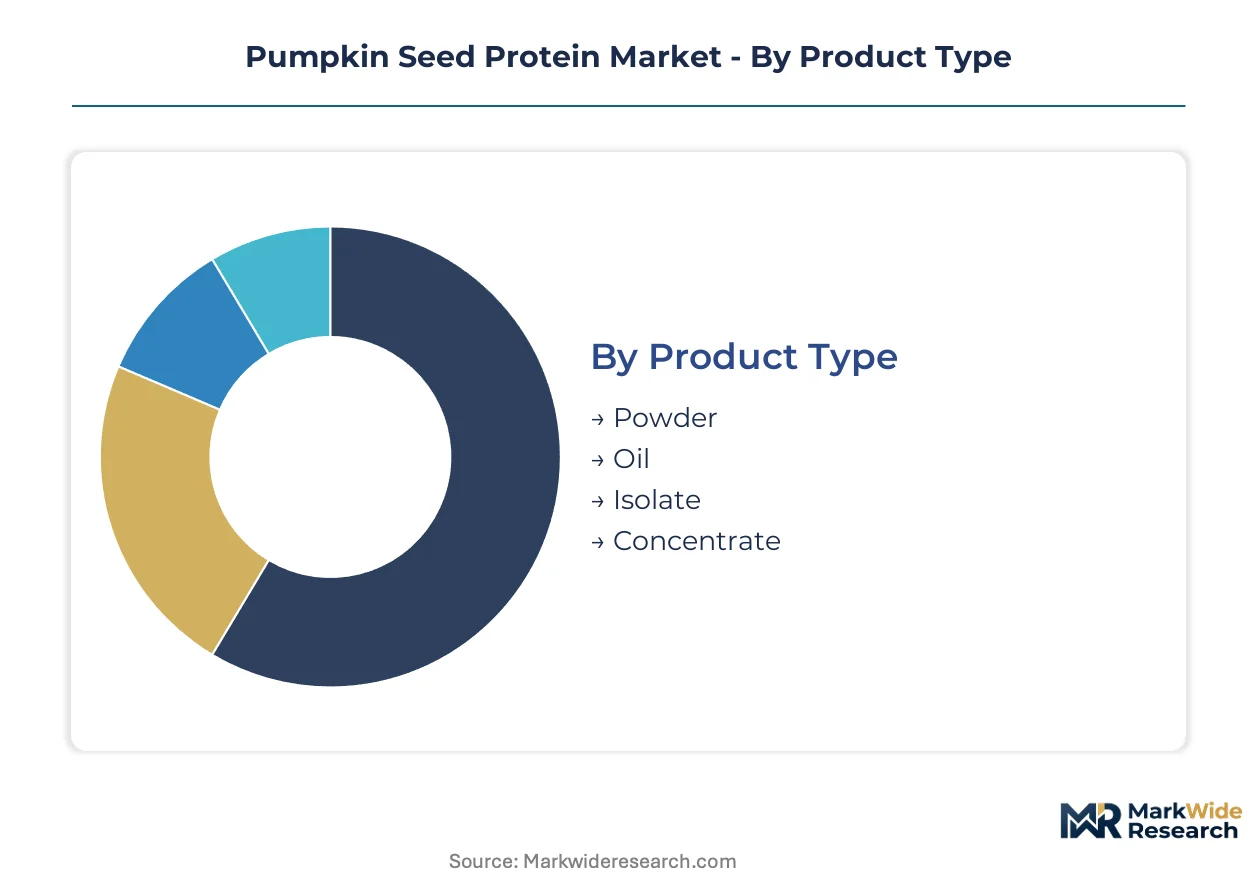
Pumpkin seed protein segmentation reflects divergent processing intensities and end-use performance requirements. Powder formats dominate current procurement volumes for ease of incorporation, while isolate grades capture premium positioning in regulated supplement channels. Understanding these tiered value pools enables suppliers to align extraction investments with buyer willingness to pay for functional properties and certification status.
Product Type:
Powder and isolate formats anchor opposite ends of the value spectrum, with concentrate and oil occupying intermediate positions based on protein fractionation depth and residual lipid content.
- Powder:The defatted, milled seed meal yielding 50-60% protein content serves as the workhorse format for bulk fortification and blended supplement bases. Demand concentrates in German and U.S. sports nutrition manufacturing, where processors prioritize solubility and neutral flavor over maximum protein concentration. FDA labeling enforcement on protein content claims constrains substitution into finished products without additional fractionation.
- Isolate:Further refined through aqueous or enzymatic extraction to achieve 70%+ protein purity with minimal residual fiber and oil. Premium positioning in EFSA-regulated European supplement channels rewards documented amino acid bioavailability and batch-level organic traceability. Cold-press infrastructure constraints in Styrian cooperatives limit supply elasticity for this grade.
- Oil:Cold-pressed lipid fraction retains tocopherols and phytosterols for cosmetic and nutraceutical applications, with defatted cake diverted to protein recovery.
- Concentrate:Intermediate protein grade (60-70%) balances cost and functionality for bakery and snack applications where water-binding capacity matters more than maximum purity.
Today's leader: Powder. Tomorrow's challenger: Isolate.
End User:
Application sophistication varies dramatically across buyer categories, with human nutrition segments demanding certification rigor that animal feed tolerances cannot justify.
- Food & Beverage:Plant-based meat analogue formulators in Germany leverage enzymatic extraction to preserve emulsification properties for texture replication. EFSA novel-food pathways impose multi-year compliance timelines on new ingredient entrants seeking finished-product approval.
- Nutraceuticals:Sleep-support and recovery supplement brands target tryptophan-rich fractions from hydrolyzed isolates, commanding premium pricing in U.S. direct-to-consumer channels. USDA organic certification gaps in domestic pumpkin cultivation force reliance on Austrian supply.
- Cosmetics:Antioxidant oil applications in dermocosmetic formulations exploit seed lipid fractions rather than protein content.
- Animal Feed:Defatted meal byproducts from oil extraction serve as protein feedstock for specialty pet nutrition, bypassing human-grade certification requirements.
Food & Beverage commands current procurement volumes. Nutraceuticals present the steepest expansion trajectory.
Application:
Protein delivery formats impose distinct technical specifications on ingredient selection, with ready-to-mix powders facing different solubility demands than thermally processed baked goods.
- Protein Supplements:Gym-goers and endurance athletes pivoting from whey to hypoallergenic alternatives pull isolate-grade supply into premium SKUs. German sports nutrition brands are disintermediating commodity traders to secure direct relationships with Styrian cooperatives for batch traceability.
- Functional Foods:Clean-label fortification of beverages and meal replacements demands heat-stable emulsification properties preserved through enzymatic rather than solvent extraction.
- Bakery Products:Artisan bread and pastry segments in Austria adopt protein-carbohydrate blends for moisture retention and crumb structure modification.
- Snack Foods:Extruded and puffed applications tolerate lower protein concentration in favor of cost-optimized concentrate grades.
Protein Supplements dominate margin capture. Functional Foods are climbing the fastest as beverage fortification accelerates.
Distribution Channel:
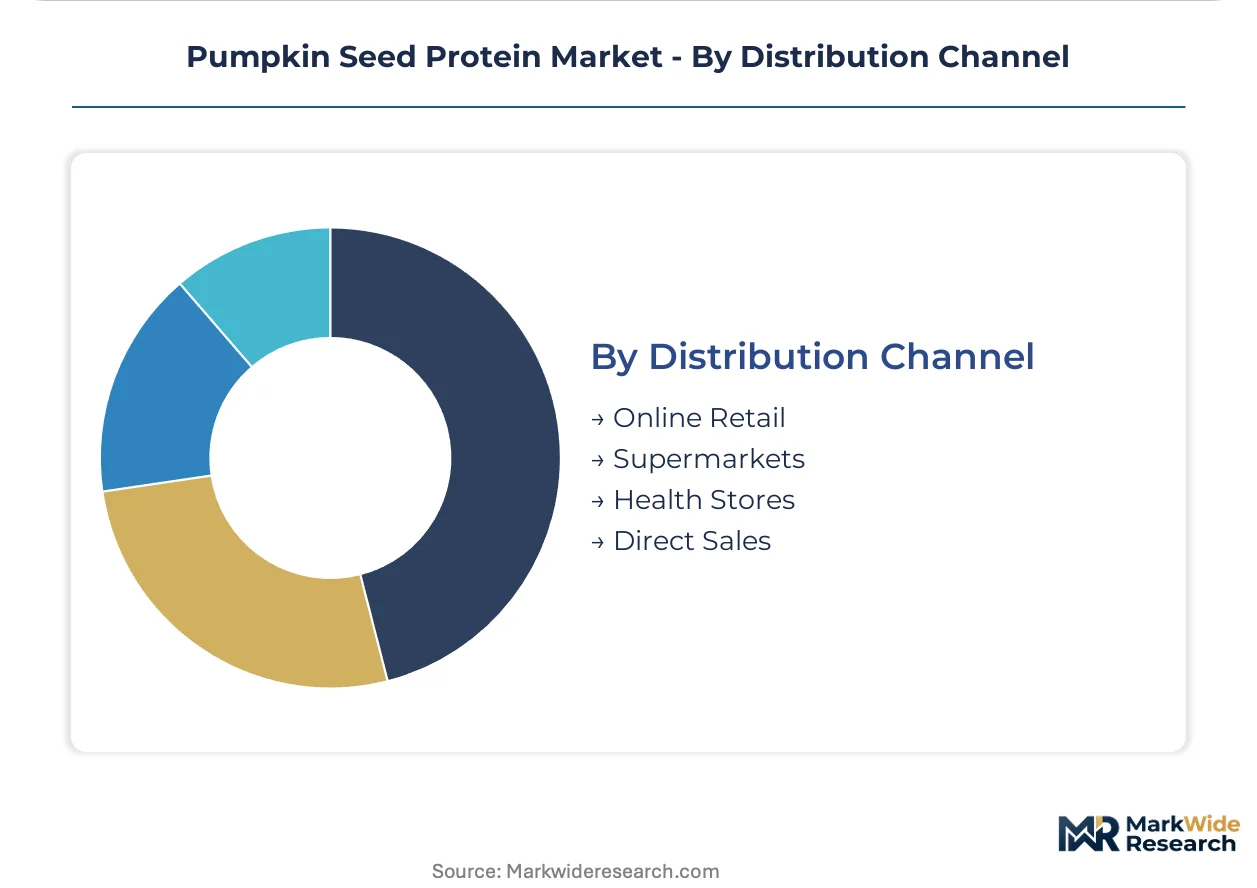
Channel selection determines buyer price sensitivity and certification documentation requirements, with direct procurement relationships emerging as a strategic priority for premium isolate grades.
- Online Retail:Direct-to-consumer supplement brands in the United States bypass traditional distribution to source certified organic isolates with documented chain-of-custody. IRA bioeconomy incentives subsidize domestic cold-press infrastructure investments serving this channel.
- Direct Sales:Long-term offtake agreements between finished-product manufacturers and Styrian processing cooperatives lock in supply security for EFSA-compliant novel food applications.
- Health Stores:Specialty retail channels reward clean-label claims with shelf placement premiums, though volume throughput remains constrained.
- Supermarkets:Mass-market penetration for bakery and snack applications depends on price-competitive concentrate grades with conventional rather than organic certification.
Online Retail leads current growth. Direct Sales are consolidating as the preferred path for regulatory-critical supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting pumpkin seed protein production toward jurisdictions with established organic certification infrastructure and shorter novel-food approval pathways. Processors in Austria and Germany exploit EU Organic Regulation harmonization to serve North American brands facing USDA certification gaps.
Germany
Sports nutrition manufacturers in Cologne and Munich drive isolate-grade procurement for hypoallergenic supplement lines. EFSA novel-food authorization requirements channel investment toward grandfathered suppliers with existing regulatory dossiers. Styrian processing cooperatives near Graz maintain cold-press capacity clusters serving German finished-product brands.
United States
Direct-to-consumer supplement brands in California and Colorado bypass commodity traders to secure batch-traceable organic supply. IRA bioeconomy production credits subsidize domestic solvent-free extraction infrastructure investments in Oregon. FDA labeling enforcement on protein content claims constrains powder-grade substitution without additional fractionation.
Austria
Organic pumpkin cultivation concentrates in Styria and Lower Austria, where weather-dependent harvests create input cost volatility for processors. EU Organic Regulation mandatory handling standards consolidate regional supply advantages for enzymatic extraction specialists. Graz-based cooperatives anchor cold-press capacity serving EFSA-compliant European channels.
Canada
Health Canada novel food regulations impose parallel substantiation requirements to EFSA pathways, extending compliance timelines for new extraction entrants. Prairie province organic oilseed processors explore protein recovery from defatted hemp and pumpkin cake for pet nutrition applications. Vancouver-area nutraceutical brands source dual-certified supply for sleep-support supplement SKUs.
United Kingdom
Post-Brexit divergence from EU novel-food frameworks creates regulatory friction for pumpkin seed protein finished-product approvals. London-based sports nutrition distributors establish direct procurement relationships with Austrian processors to bypass UK-specific authorization delays. Midlands bakery manufacturers adopt protein-carbohydrate blends for clean-label artisan bread fortification.
Pumpkin Seed Protein Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue isolate-grade premium positioning through enzymatic extraction specialization. The vendor base stratifies across integrated multinationals with dairy-alternative portfolios, mid-scale European oilseed processors with cooperative ownership structures, and North American ingredient traders disintermediated by direct-sourcing trends. Three archetypes dominate: allergen-free processing specialists, organic-certified cold-press operators, and functional carbohydrate-protein blenders. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with EFSA regulatory grandfathering serving as a defensive moat.
Among North American ingredient houses, Axiom Foods exemplifies allergen-free processing specialization, while Glanbia Nutritionals anchors scale-driven supply relationships through its dairy-alternative protein portfolio. European functional ingredient positioning is represented by BENEO, which occupies the carbohydrate-protein blending expertise tier for bakery applications. These three entities illustrate the geographic and capability segmentation structuring competitive rivalry across regulated supplement and food channels.
| Leading Market Players |
|---|
| Conagra Brands |
| Axiom Foods |
| AIDP Inc. |
| Glanbia Nutritionals |
| BENEO |
| Jarrow Formulas, Inc. |
| PepsiCo |
| BI Nutraceuticals |
| Bioriginal Food & Science Corporation |
| Others |
Value Network & Pricing Analysis
Food technologists with protease selection expertise concentrate in Styrian oilseed hubs and Graz processing cooperatives, creating labor-cost differentials that widen spreads between premium isolate grades and economy powder tiers. Austrian enzymatic extraction specialists command wage premiums that cascade into finished-product pricing, while North American processors face staffing constraints that compress margins on mid-grade concentrates.
Pricing Analysis
Distributor margins on organic-certified isolates absorb the steepest markup layers, with direct-to-supplement-brand procurement bypassing traditional wholesale channels to capture 15-20 point spreads. Three-tier pricing structure across premium isolate, standard concentrate, and economy powder levels reflects certification depth and amino acid bioavailability documentation. Cost compression in concentrate grades intensifies because conventional cultivation supply competes with organic Styrian harvests. Mass-market bakery manufacturers exhibit highest price sensitivity, while sleep-support nutraceutical brands tolerate premium positioning for tryptophan-rich fractions.
Supply Chain Analysis
Freight costs from Graz cold-press facilities to North American ports impose landed-cost premiums that disadvantage Austrian supply against domestic alternatives. Production gravity centers on Austria, Slovenia, and southern Germany, where EU Organic Regulation infrastructure clusters enzymatic extraction capacity. Raw material flows draw from Styrian pumpkin cultivation, Lower Austrian organic seed cooperatives, and Illinois test plots for USDA certification development. Single-source vulnerability concentrates in Styrian cooperative networks, where weather-dependent harvests create batch-to-batch availability risk. Distribution runs through direct offtake agreements for premium grades, with commodity traders handling residual powder volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Organic Regulation-compliant Austrian supply and USDA certification-deficient North American cultivation, with IRA bioeconomy production credits narrowing the capital-cost differential for domestic solvent-free extraction infrastructure.
For Market Incumbents: Deepen backward integration into Styrian organic pumpkin cultivation to secure batch-level traceability against emerging North American vertically integrated processors. Lock multi-year offtake agreements with German sports nutrition brands before IRA-subsidized domestic capacity reaches commercial scale. EFSA novel-food grandfathering serves as a temporary defensive moat requiring continuous toxicology investment to maintain.
For New Entrants and Emerging Players: The premium-to-economy tier price gap creates entry space for mid-scale enzymatic processors targeting functional bakery applications with 60-70% concentrate grades. Oregon and Illinois offer first-mover positioning for USDA organic-certified cold-press facilities serving direct-to-consumer supplement channels. Partner with established Styrian cooperatives for technology transfer rather than greenfield capacity builds.
For Investors and Strategic Acquirers: Dairy-alternative protein portfolio managers at integrated nutrition multinationals represent the most active acquirer category in this space, seeking allergen-free processing capabilities to complement existing plant-protein lines. Acquisition targets should demonstrate EFSA regulatory dossier completeness and established relationships with Graz-based organic cooperatives. Watch for FDA guidance finalization on seed protein allergen thresholds as the signal indicating formulation preference shifts and valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captures margin pool from Styrian seed supply and secures batch traceability for EFSA compliance. |
| Enzymatic Extraction Capacity Expansion | Preserves heat-sensitive amino acids for sleep-support nutraceutical applications in U.S. direct-to-consumer channels. |
| Dual Certification Investment | Unlocks German sports nutrition procurement by meeting both EU Organic Regulation and pending USDA organic standards. |
| Direct Sourcing Relationship Development | Bypasses commodity traders to lock supply security for isolate-grade contracts with documented chain-of-custody. |
| Functional Bakery Application Partnership | Leverages protein-carbohydrate blending expertise from Austrian ingredient houses for clean-label artisan bread fortification. |
Research Methodology
Direct dialogue with enzymatic extraction technologists, organic certification auditors, sports nutrition formulation directors, and Styrian cooperative procurement managers grounded qualitative findings in operational reality. Secondary validation drew from EFSA novel-food authorization databases, USDA organic handling standard filings, EU Organic Regulation compliance registries, and IRA bioeconomy incentive disbursement records. Bottom-up capacity assessments across Austrian cold-press facilities and top-down demand modeling from German supplement brand procurement data were triangulated to constrain forecast variance.
Segment-level projections across isolate, concentrate, and powder grades incorporated protein content thresholds, certification tier penetration curves, and application-specific solubility requirements throughout the forecast period. CAGRs were derived from elasticity-adjusted price-volume relationships rather than simple trend extrapolation. Enzymatic hydrolysis yield improvements and FDA allergen guidance evolution served as key scenario variables in sensitivity testing.
The model assumes a particular technology adoption path; alternative pathways for aqueous versus solvent extraction scale-up would alter the outlook for Styrian cooperative market share. Forecasts reflect documented assumptions regarding EFSA authorization timeline stability and organic cultivation yield patterns in Lower Austria. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Anti-Aging Ingredients Market
Ingredients
Native Whey Protein Ingredients Market
Ingredients
Konjac Flour Market
Ingredients
South America Vegetable Oil Market
Ingredients
Brazil Starch Derivatives Market
Ingredients
Glucuronolactone Market
Ingredients
Textural Food Ingredients Market
Ingredients
Fermentation Ingredient Market
Ingredients
Protein Ingredients Market
Ingredients
Punica Granatum (Pomegranate) Seed Oil Market
Ingredients
Cosmetic Ingredients Market
Ingredients
Sodium Caseinate Market
Ingredients
Shortening Powder Market
Ingredients
Spray-Dried Isolate Market
Ingredients
India Gelatin Market
Ingredients
North America and Europe Coconut Derivatives Market