
 Australia Agrochemicals Market | 2026-2036
Australia Agrochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Agrochemicals Market Outlook
Biological active ingredients is broadening the accessible price-performance frontier for Australian growers. Nufarm Limited leverages its domestic manufacturing footprint to sustain cost competitiveness against import-reliant rivals. BASF SE anchors its position through specialized fungicide chemistry tailored to Australian disease pressures. Syngenta Group competes via integrated seed-and-crop-protection bundling across eastern grain belts.
Agrochemicals encompass synthetic and biological formulations designed to protect crop yield, manage pest populations, and optimize plant nutrition through specified active ingredient concentrations, application rates, and residual activity windows. Herbicides dominate product-type revenue due to glyphosate-tolerant cropping systems across millions of hectares, while seed treatment exhibits the fastest structural expansion as farmers seek protection at the earliest plant-growth stage. Fertilizer segments concentrate margin pools in specialty micronutrient blends serving high-value horticulture around Bundaberg and the Murray-Darling Basin.
The Australian Pesticides and Veterinary Medicines Authority regulates product registration and residue limits, with Food Standards Australia New Zealand setting maximum residue limits that directly shape export-access requirements for wheat and beef producers. APVMA's 2023 re-registration timelines for neonicotinoid insecticides have forced reformulation investments across multiple suppliers. State-level environmental protection agencies in Queensland and Western Australia impose additional buffer-zone and runoff controls near Great Barrier Reef catchments. Stakeholders must monitor evolving biosecurity protocols and carbon-accounting methodologies that could redefine input intensity benchmarks without explicit regulatory mandate.
Market Dynamics
Precision agriculture hardware and biological active ingredients are compressing traditional synthetic chemistry margins across Australian broadacre and horticulture sectors simultaneously.
Growth Catalysts
- APVMA residue limit tightening:Export-oriented wheat and beef producers are upgrading formulation quality to meet Food Standards Australia New Zealand thresholds, pulling premium product demand.
- Queensland horticulture intensification:Bundaberg and Bowen basin growers are expanding protected cropping, multiplying micronutrient and specialty fungicide requirements per hectare.
- Drone-based application systems:Western Australia's wheat-sheep zone operators are adopting variable-rate spraying, reducing waste and enabling higher-margin precision chemistry.
Market Restraints
- Active ingredient import dependence:Australian formulators rely on Chinese and Indian technical-grade supply, exposing margins to freight and currency volatility.
- Neonicotinoid re-registration timelines:APVMA's extended review periods for seed-treatment insecticides have frozen product line investments across multiple suppliers.
- Great Barrier Reef catchment buffer zones:Queensland environmental protection agencies mandate expanded no-spray corridors, reducing effective arable application area.
Strategic Opportunities
- Tasmanian vegetable seed treatment:Underpenetrated pyrethroid and biological coating demand among Brassica and allium producers offers first-mover positioning.
- Carbon-accounting methodology alignment:Emerging biosecurity protocols that reward input efficiency create premium pricing for low-residue biological portfolios.
- Direct-to-farm digital distribution:Bypassing rural merchandise cooperatives through app-based ordering and on-farm delivery unlocks margin capture in Victoria's Wimmera region.
Industry Challenges
- Precision agriculture technician scarcity:Regional agronomists with drone calibration and variable-rate prescription expertise command salary premiums that dealer networks struggle to absorb.
- Biological product stability certification:APVMA efficacy data requirements for microbials lack standardized shelf-life protocols, extending registration timelines unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Agrochemicals Market |
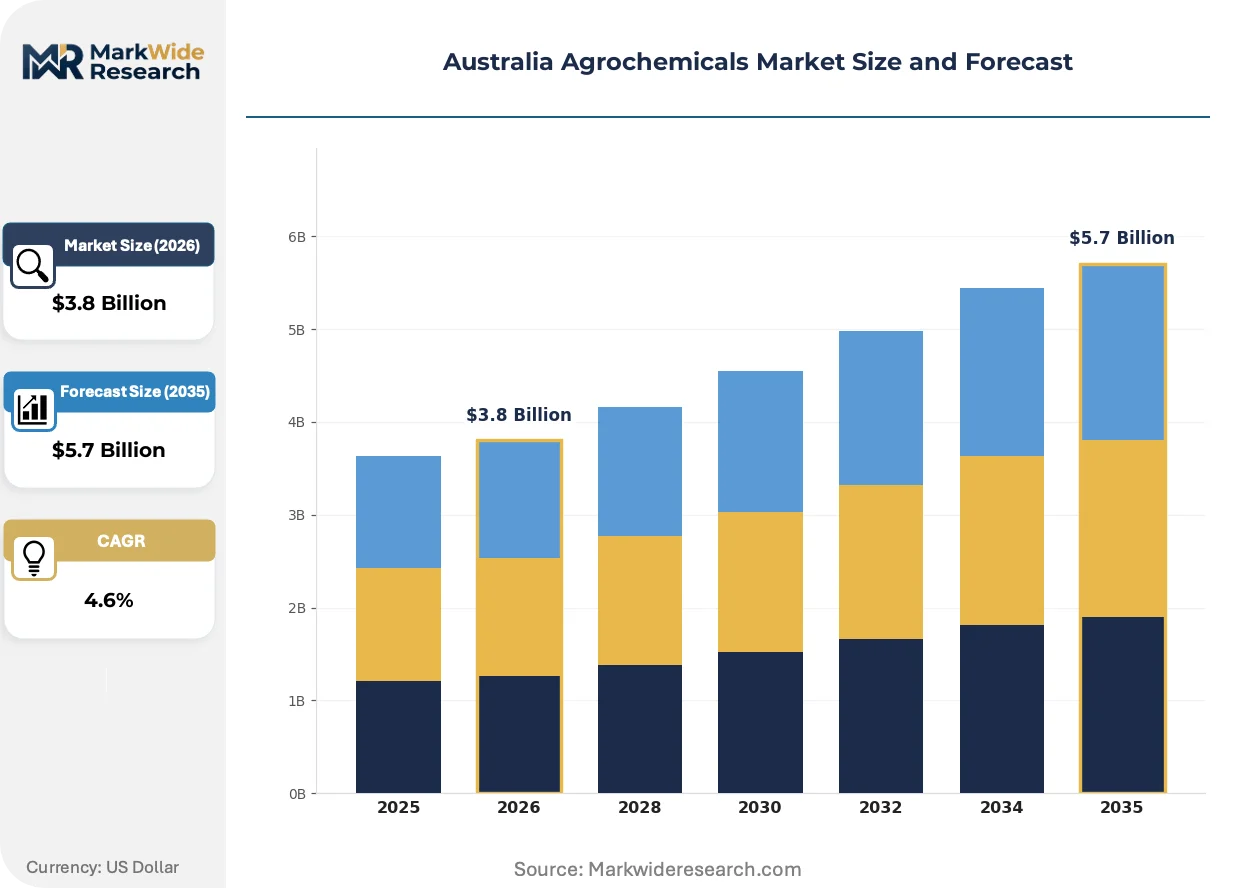
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Fertilizers Application: Crops, Turf, Ornamentals, Seed Treatment End User: Agricultural Producers, Landscape Professionals, Homeowners, Farm Cooperatives Distribution Channel: Direct Sales, Distributors, Retail Stores, Online Platforms |
| Companies Covered | Nufarm Limited, Bayer AG, BASF SE, Syngenta Group, Corteva Agriscience, Nutrien, Yara International ASA, Incitec Pivot Pty Ltd, UPL Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Agrochemicals Market Strategic Shifts
Biological-synthetic hybrid formulations and autonomous application platforms are fragmenting traditional supplier-buyer relationships across Australia's grain belts and irrigation districts.
Drone-mounted multispectral sensing combined with AI-driven prescription maps is automating herbicide spot-spray decisions in Western Australia's wheat-sheep zone. Large-scale broadacre cooperatives are deploying these systems across 50,000-hectare aggregations, reducing glyphosate volumes by one-third while compressing contract application service pricing. The technology is automating field-scouting labor previously performed by seasonal agronomists.
APVMA's 2023 re-registration framework for neonicotinoid seed treatments has forced reformulation investments toward biological alternatives. Suppliers must submit extended aquatic toxicity data, extending approval cycles by 18-24 months for novel chemistries. Queensland's intensive horticulture belt faces the steepest compliance burden, with melon and capsicum producers pivoting to pyrethroid and spinosad alternatives ahead of formal deadline certainty.
Farmer buying committees in the Murray-Darling Basin are consolidating annual chemistry procurement into single-tender events, displacing historical quarterly merchandise purchases. These aggregations bypass traditional rural supply cooperatives, negotiating direct manufacturer pricing for 20,000-hectare-plus commitments. The practice is most visible among cotton and rice irrigation enterprises seeking volume leverage against input cost inflation.
Australia Agrochemicals Market Segmentation
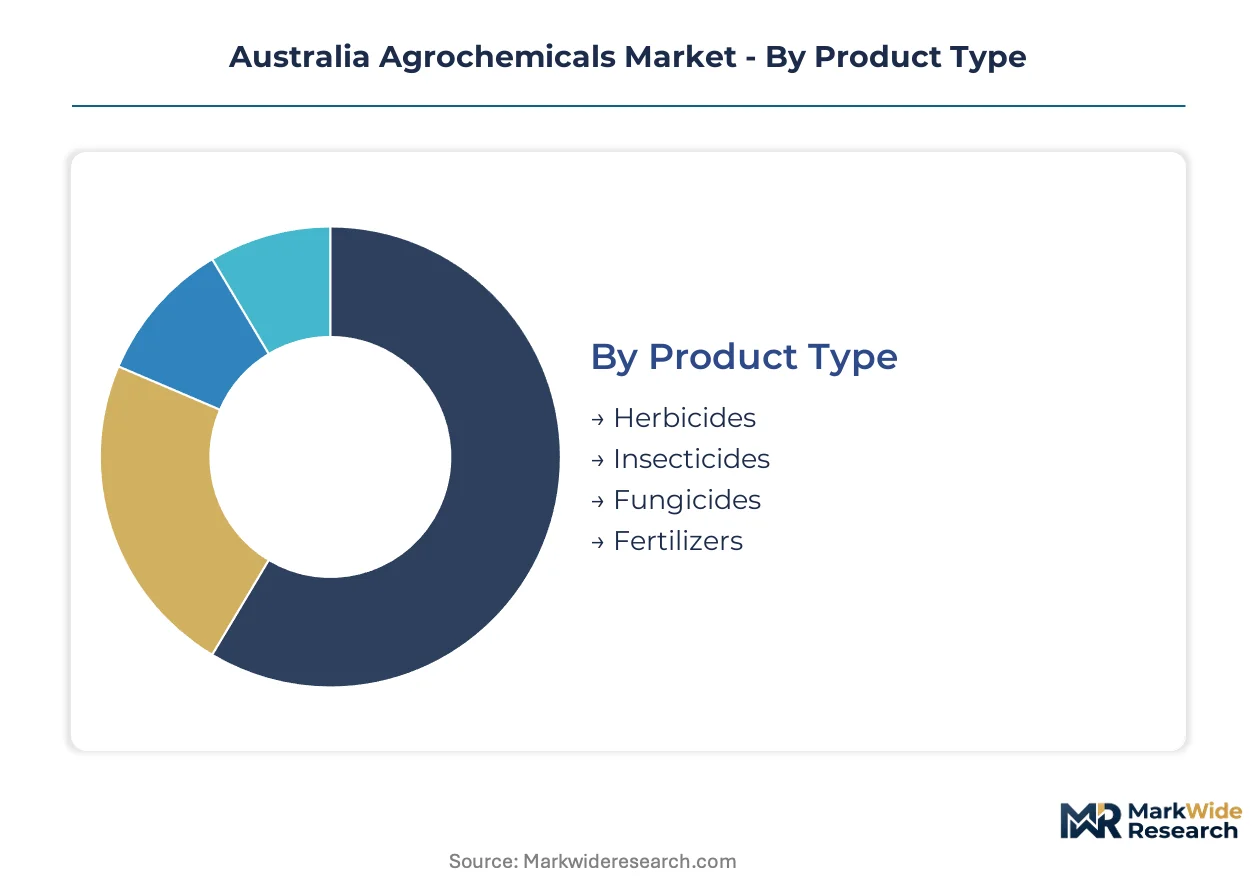
Australian agrochemical demand fragments across product chemistry, application timing, and procurement relationships. Understanding these splits reveals where margin pools concentrate and where supplier positioning faces the greatest pressure.
Product Type:
Volume concentration sits with broad-spectrum chemistry across millions of hectares, while premium pricing attaches to specialized formulations serving export-compliance requirements.
- Herbicides:Glyphosate-tolerant cropping systems across Western Australia's wheat-sheep zone and Queensland's grain belt consume the largest absolute volumes. Demand concentrates in pre-emergent and post-emergent formulations protecting against annual ryegrass and wild radish infestations.
- Insecticides:Neonicotinoid re-registration uncertainty under APVMA timelines has frozen seed-treatment investments and accelerated pyrethroid and spinosad adoption in Queensland horticulture around Bundaberg and Bowen.
- Fungicides:Specialty triazole and SDHI chemistry tailored to Australian stripe rust and Septoria pressures commands premium positioning in high-rainfall zones of Victoria's Wimmera.
- Fertilizers:Micronutrient blends serving Murray-Darling Basin citrus and almond producers capture margin concentration through precision application compatibility.
Mature deployment sits with herbicides across established broadacre rotations. Newer deployment is concentrated in biological-synthetic fungicide hybrids responding to residue limit tightening.
Application:
Crop protection timing determines formulation specification, with earlier-stage applications commanding higher per-hectare chemistry investment.
- Crops:Broadacre cereals and oilseeds across Western Australia and New South Wales drive bulk volume procurement through farm cooperatives. Canola expansion in the medium-rainfall zone multiplies fungicide pass requirements.
- Seed Treatment:Biological coating technologies and pyrethroid alternatives are expanding most quickly as APVMA neonicotinoid reviews extend approval timelines. Tasmanian vegetable producers represent underpenetrated first-mover opportunity for Brassica and allium coatings.
- Turf:Golf course and sports field maintenance in metropolitan Sydney and Melbourne sustains steady demand for selective herbicides and systemic fungicides.
- Ornamentals:Nursery and greenhouse operations around Adelaide's peri-urban fringe require specialized miticide and broad-spectrum insecticide rotations.
Established volume flows through crop applications. Seed treatment exhibits the steepest expansion trajectory as growers seek protection at the earliest plant-growth stage.
End User:
Procurement scale and technical sophistication split the customer base, with large aggregations bypassing traditional supply channels.
- Agricultural Producers:Individual broadacre operators across the wheat-sheep zone balance cost pressure against export residue compliance, driving generic herbicide volume alongside premium fungicide spot purchases.
- Farm Cooperatives:Murray-Darling Basin cotton and rice irrigation enterprises are consolidating annual chemistry procurement into single-tender events, negotiating direct manufacturer pricing for 20,000-hectare-plus commitments and displacing quarterly merchandise purchases.
- Landscape Professionals:Municipal and commercial maintenance contractors in Queensland require buffer-zone compliant formulations near Great Barrier Reef catchments.
- Homeowners:Retail channel dependence concentrates in suburban garden care products with lower active ingredient concentrations.
Traditional purchasing patterns persist among individual agricultural producers. Cooperative consolidation is reshaping supplier relationships fastest in irrigated cropping districts.
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and geographic isolation from metropolitan supply points.
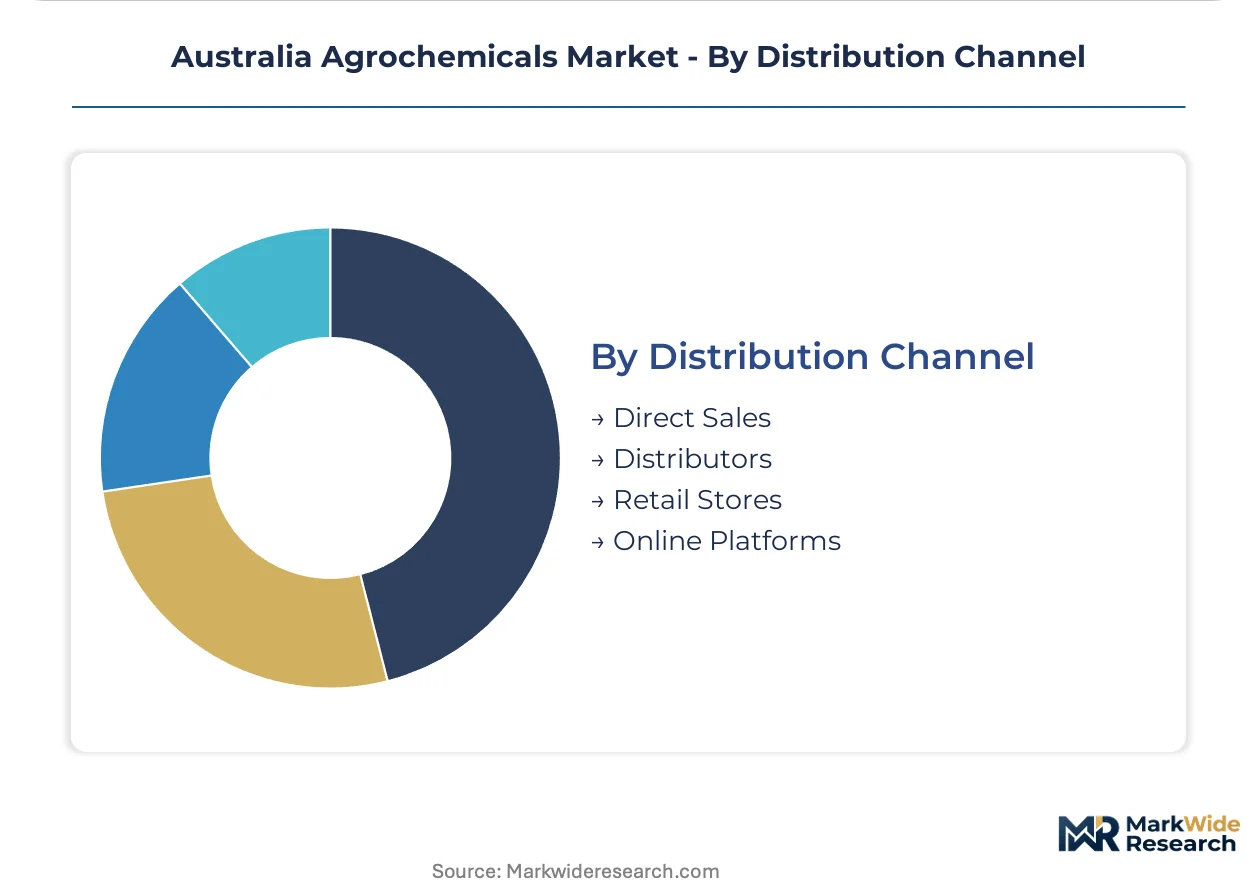
- Distributors:Rural merchandise cooperatives remain the dominant pathway for broadacre chemistry in Western Australia and Queensland, though margin compression from cooperative buying committees is intensifying.
- Direct Sales:Large-scale cotton and grain enterprises in the Murray-Darling Basin negotiate manufacturer-direct contracts, capturing volume leverage and technical agronomist access.
- Retail Stores:Independent rural suppliers and chain hardware outlets serve small-to-medium producers and homeowner segments with standardized product ranges.
- Online Platforms:App-based ordering with on-farm delivery is emerging in Victoria's Wimmera region, bypassing cooperative markups for producers with established prescription maps.
Conventional distributor relationships anchor the largest volume flows. Digital direct-to-farm channels are gaining share fastest among precision-agriculture-enabled operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queensland and Western Australia concentrate agrochemical demand through divergent cropping intensities. Horticulture expansion along the coast contrasts with broadacre mechanization inland. State-level environmental regulations reshape application practices across both zones.
Queensland
Bundaberg and Bowen basin growers drive specialty fungicide and micronutrient procurement through protected cropping expansion. The state's environmental protection agencies enforce Great Barrier Reef catchment buffer zones that reduce effective sprayable area. Melon and capsicum producers around Bundaberg pivot toward pyrethroid alternatives ahead of formal neonicotinoid deadline certainty.
Western Australia
The wheat-sheep zone consumes bulk herbicide volumes through glyphosate-tolerant cropping systems across millions of hectares. APVMA residue limit tightening pulls premium formulation demand from export-oriented wheat producers. Drone-based variable-rate spraying systems spread across 50,000-hectare cooperative aggregations near Geraldton and Esperance.
New South Wales
Murray-Darling Basin cotton and rice irrigation enterprises consolidate annual chemistry procurement into single-tender events. Food Standards Australia New Zealand maximum residue limits directly shape input selection for export-access compliance. Farm cooperatives around Griffith and Deniliquin negotiate direct manufacturer pricing for 20,000-hectare-plus commitments.
Victoria
The Wimmera region exhibits fastest uptake of app-based ordering with on-farm delivery bypassing rural merchandise cooperatives. High-rainfall zones command premium triazole and SDHI fungicide positioning against stripe rust and Septoria pressures. Precision agriculture technician scarcity concentrates salary premiums among regional agronomists with drone calibration expertise.
Tasmania
Brassica and allium producers represent underpenetrated demand for pyrethroid and biological seed treatment coatings. The island's vegetable sector operates outside mainland neonicotinoid review timelines, enabling faster biological alternative adoption. Processing vegetable processors around Devonport and Burnie specify residue profiles that favor low-residue biological portfolios.
Australia Agrochemicals Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with domestic formulators holding cost advantages against import-reliant rivals. The supplier base concentrates around three strategic tiers: multinational integrated players with seed-chemistry bundling, regional specialists with domestic manufacturing footprints, and import-dependent generic distributors. Competitive moves center on reformulation investments responding to APVMA re-registration timelines and direct-to-farm digital channel development bypassing traditional cooperatives.
Within the domestic manufacturing tier, Nufarm Limited leverages its Australian production footprint to sustain cost competitiveness. BASF SE anchors positioning through specialized fungicide chemistry. Syngenta Group competes via integrated seed-and-crop-protection bundling across eastern grain belts. These three exemplify divergent responses to precision agriculture compression and biological active ingredient expansion.
| Leading Market Players |
|---|
| Nufarm Limited |
| Bayer AG |
| BASF SE |
| Syngenta Group |
| Corteva Agriscience |
| Nutrien |
| Yara International ASA |
| Incitec Pivot Pty Ltd |
| UPL Limited |
| Others |
Value Chain & Pricing Dynamics
Farm cooperative buying committees in the Murray-Darling Basin anchor procurement scale and impose contract-based long-term offtake structures that compress distributor markups. Their 20,000-hectare-plus single-tender events extract direct manufacturer pricing, forcing rural merchandise cooperatives to absorb margin erosion or lose volume.
Pricing Analysis
Volume concentration in generic glyphosate formulations across Western Australia's wheat-sheep zone yields thin margins, while premium positioning attaches to specialty fungicide chemistry in Victoria's high-rainfall zones. Price differentiation rests on APVMA residue compliance certification and precision application compatibility. Pricing pressure stems from Chinese and Indian technical-grade import cost volatility. Individual broadacre operators exhibit highest price sensitivity; export-oriented wheat producers accept premium formulations for Food Standards Australia New Zealand compliance.
Supply Chain Analysis
Direct-to-farm digital channels emerging in Victoria's Wimmera region bypass traditional rural merchandise cooperatives for producers with established prescription maps. Active ingredient supply concentrates in China and India, with formulation finishing distributed across Australian domestic plants. Technical-grade chemical dependencies and biological microbial feedstocks feed into finished product. Single-source vulnerability runs through Chinese technical-grade supply for broad-spectrum herbicides. Distribution runs through rural merchandise cooperatives, direct manufacturer contracts, and emerging app-based platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in Australian agrochemicals is accelerating into a vertical-integration race, with domestic manufacturing footprints becoming the decisive cost lever against import-reliant rivals.
For Market Incumbents: Deepen backward integration into active ingredient production to insulate margins from Chinese and Indian supply volatility. Secure APVMA pre-registration data packages for biological alternatives ahead of neonicotinoid deadline certainty. Anchor technical agronomist teams in Queensland's horticulture belt to defend against direct-to-farm digital entrants. For New Entrants and Emerging Players: Begin with Tasmanian vegetable seed treatment, where Brassica and allium producers remain underpenetrated by biological coating technologies. Leverage the island's exemption from mainland neonicotinoid review timelines to fast-track microbial product registration. Pursue app-based ordering partnerships with precision-agriculture-enabled growers in Victoria's Wimmera region. For Investors and Strategic Acquirers: The window for entry favors domestic formulators with captive technical-grade supply or established APVMA registration portfolios. Target acquisition candidates with biological-synthetic hybrid pipelines and Queensland horticulture market presence. Watch APVMA re-registration timeline certainty as the inflection signal for seed-treatment investment restart.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Supply | Captive technical-grade sourcing insulates Nufarm Limited from Chinese import volatility. |
| Biological Product Registration Investment | APVMA microbial efficacy data packages enable Syngenta Group's neonicotinoid alternative pipeline. |
| Direct-to-Farm Digital Channel Development | App-based ordering bypasses rural merchandise cooperatives in Victoria's Wimmera region. |
| Precision Agriculture Technician Training | Drone calibration expertise scarcity commands salary premiums BASF SE must absorb. |
| Great Barrier Reef Buffer Zone Compliance | Queensland environmental protection agency mandates reshape formulation specifications near Bundaberg. |
Study Parameters
Document review covered APVMA registration databases, Food Standards Australia New Zealand residue limit publications, and Australian Bureau of Agricultural and Resource Economics trade data, complemented by interviews with agrochemical formulation plant managers, procurement leads at Murray-Darling Basin cotton cooperatives, Queensland horticulture technical directors, and rural merchandise cooperative category buyers. Secondary validation drew from customs import records, Australian Pesticides and Veterinary Medicines Authority annual reports, and state-level environmental protection agency filings. Bottom-up volume triangulation across product chemistry segments was cross-checked against top-down market value estimates.
Segmented demand projections across herbicide, insecticide, fungicide, and fertilizer chemistry types were generated through the analysis window, with application timing and end-user procurement scale as additional modeling dimensions. CAGRs were derived from historical volume trajectories adjusted for APVMA regulatory timeline impacts and precision agriculture adoption curves. Key inputs included Queensland protected cropping expansion rates and Western Australia drone-based spraying penetration assumptions.
Underlying measurement precision varies by segment; herbicide volume estimates carry tighter precision than emerging biological product forecasts due to longer data histories. Forecasts reflect assumptions about APVMA re-registration timeline resolution and Chinese technical-grade supply stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
Mexico Agrochemicals Market
Agrochemicals
South Africa Agrochemicals Market
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
South America Agrochemicals Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
Global Buprofezin Market
Agrochemicals
Africa Agrochemicals Market
Agrochemicals
Agrochemical Active Ingredients Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
Egypt Agrochemicals Market
Agrochemicals
L-Glufosinate Ammonium Market
Agrochemicals
Canada Agrochemicals Market
Agrochemicals
Superphosphates Market
Agrochemicals
Potassium Humate Market
Agrochemicals
Agrochemical Market
Agrochemicals
India Agrochemicals Market