
 Egypt Agrochemicals Market | 2026-2036
Egypt Agrochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Agrochemicals Market Foresight
Aftermarket technical advisory revenue is reconfiguring margin pools away from pure product sales toward farm-level application services. UPL Limited leverages its distribution network to anchor smallholder outreach programs across the Delta governorates. Kafr El-Zayat Pesticides and Chemicals Co. dominates domestic pesticide formulation with backward integration into active ingredient blending. Abu Qir Fertilizers and Chemicals Industries sustains ammonia-based nitrogen output through pipeline connectivity to Mediterranean port infrastructure.
Agrochemicals comprise synthetic and biological inputs—nitrogen-phosphorus-potassium compounds, organophosphate and pyrethroid active ingredients, microbial inoculants, and adjuvant systems—engineered to enhance crop yield, suppress pest pressure, or modify plant physiology at cellular signaling pathways. Fertilizers occupy the largest value share, with urea and compound grades serving wheat and rice intensification programs. Pesticides represent the fastest-expanding category as fall armyworm and whitefly resistance patterns push farmers toward rotated chemistries and biological alternatives. Liquid formulations gain share in mechanized farming zones where spray drift reduction and tank-mix compatibility reduce field labor hours.
Egypt's Ministry of Agriculture and Land Reclamation governs pesticide registration through residue tolerance protocols aligned with CODEX and EU export market requirements. The Egyptian Organization for Standardization and Quality enforces fertilizer grade labeling under national standards harmonized with ISO 17025 testing methodologies. Stakeholders must monitor groundwater nitrate thresholds in the New Valley reclamation zones where regulatory enforcement is tightening. Water quota allocations under the Nile Basin Cooperative Framework will reshape which crops receive priority for subsidized agrochemical programs.
Market Dynamics
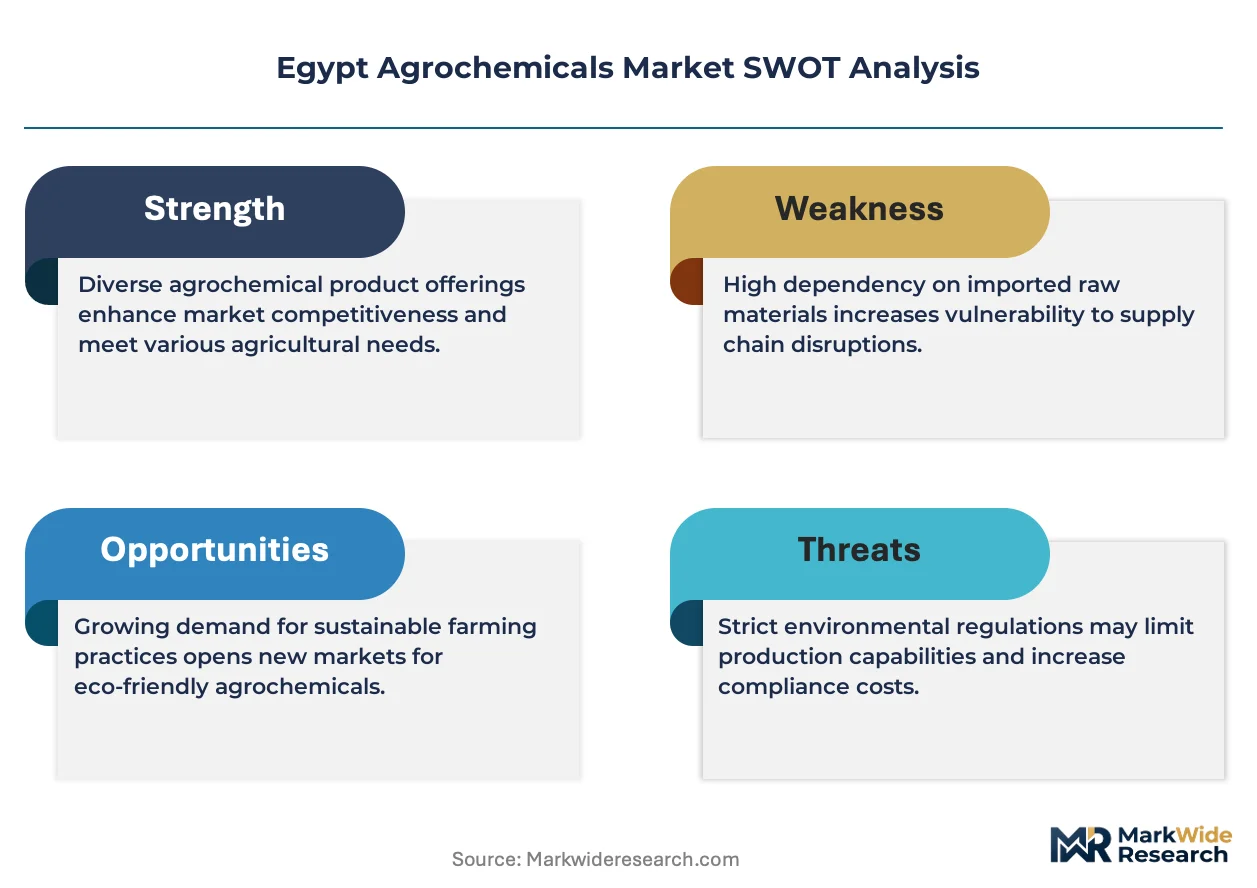
Specialty fertilizer adoption is restructuring Egypt's agrochemical value chain as commercial greenhouse operators in the Nile Delta demand precision nutrient delivery systems that integrate with drip irrigation infrastructure. This shift compresses traditional distribution layers while elevating technical advisory services.
Growth Catalysts
- Nile Basin Cooperative Framework water quotas:Subsidized agrochemical programs now prioritize crops with highest water efficiency, redirecting input demand toward precision-applied formulations in sugarcane and potato belts.
- Fertilizer grade labeling harmonization:ISO 17025 testing methodologies enforced by the Egyptian Organization for Standardization and Quality accelerate import clearance for compound grades serving wheat intensification.
- Drip irrigation expansion:Upper Egypt's mechanized farming zones drive liquid formulation uptake as spray drift reduction and tank-mix compatibility cut field labor hours.
Market Restraints
- Active ingredient import dependency:Backward integration into blending operations remains concentrated among domestic formulators, exposing margins to global petrochemical feedstock volatility.
- Biopesticide registration friction:Tightened import registration requirements from the Ministry of Agriculture and Land Reclamation extend approval timelines for microbial inoculants.
- Groundwater nitrate threshold enforcement:Regulatory monitoring in New Valley reclamation zones restricts nitrogen application rates below crop yield optimization levels.
Strategic Opportunities
- Smallholder outreach programs:Distribution networks anchored in Delta governorates can capture fragmented demand through farm-level application service bundling.
- Biological alternative substitution:Fall armyworm and whitefly resistance patterns create white space for rotated chemistries and microbial inoculants in pesticide portfolios.
- Mediterranean port pipeline connectivity:Ammonia-based nitrogen producers with captive port infrastructure secure export arbitrage into regional deficit markets.
Industry Challenges
- Crop residue tolerance protocol alignment:CODEX and EU export market requirements demand dual-certification testing capacity that strains domestic laboratory throughput.
- Technical advisory talent scarcity:Farm-level application services require agronomists trained in precision nutrient delivery system calibration, a skill set concentrated among multinational distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Agrochemicals Market |
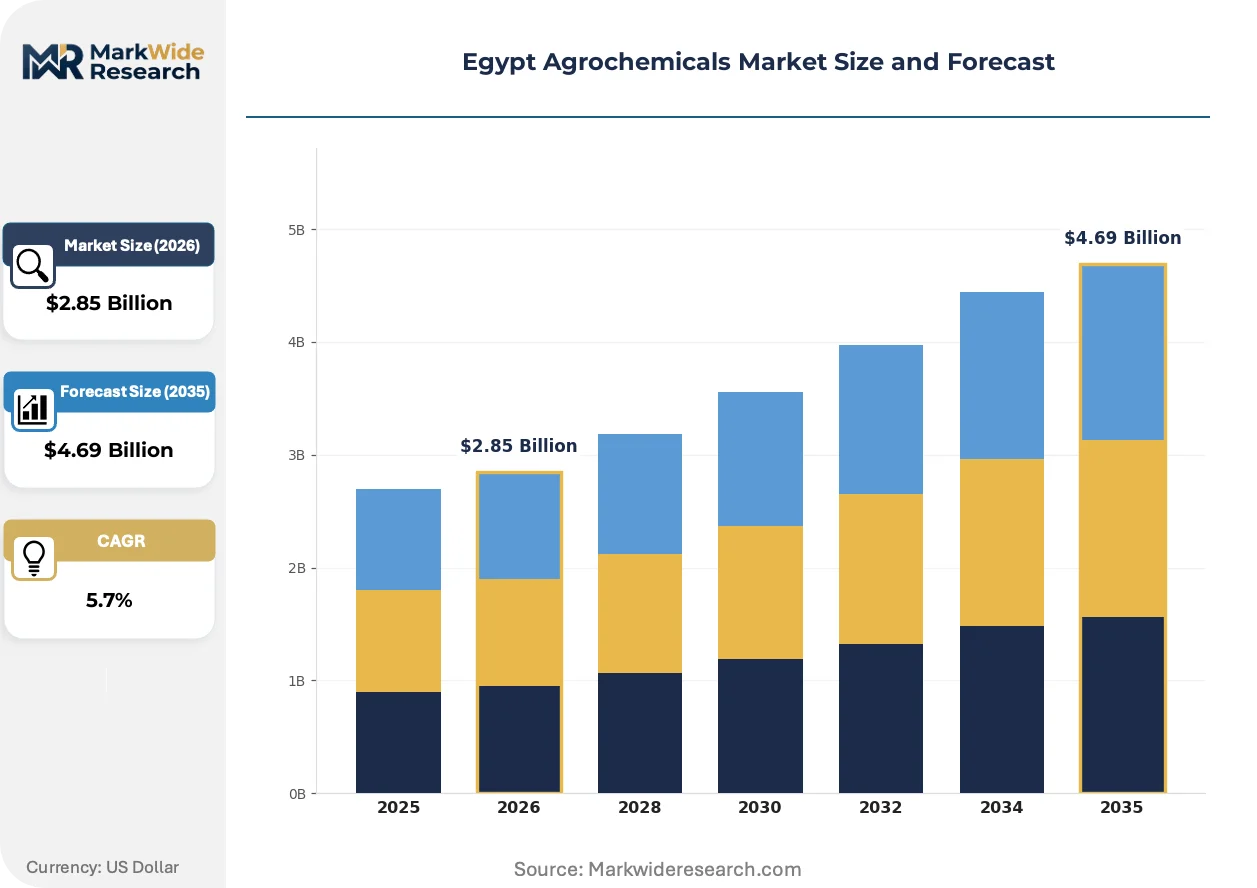
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.69 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fertilizers, Pesticides, Herbicides, Plant Growth Regulators End Use Industry: Agriculture, Horticulture, Landscaping, Turf Formulation Type: Liquid, Granular, Powder, Suspensions Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | UPL Limited, FMC Corporation, Syngenta Group Co., Ltd., Abu Qir Fertilizers and Chemicals Industries, Kafr El-Zayat Pesticides and Chemicals Co., Bayer CropScience Ltd., Corteva Agriscience, Misr Fertilizers Production Company (MOPCO), BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Agrochemicals Market Shifts & Advancements
Digital agronomy platforms are compressing the information asymmetry between input suppliers and Egyptian growers, enabling real-time nutrient prescription adjustments based on soil sensor data and satellite imagery.
Variable-rate application technology is virtualizing traditional blanket fertilization practices. Commercial greenhouse operators in Kafr El-Sheikh and Beheira governorates deploy sensor-guided fertigation systems that map nutrient demand at sub-field resolution. This compression of input waste is reallocating margin pools from product volume toward data-enabled advisory subscriptions.
The Ministry of Agriculture and Land Reclamation's residue tolerance protocols now mandate CODEX-aligned maximum residue limits for export-bound horticulture. This regulatory tightening disqualifies generic organophosphate formulations from grape and strawberry supply chains. Exporters respond by contracting dedicated spray service providers with documented application logs and buffer zone compliance.
Aftermarket technical advisory revenue is unbundling from product sales as Delta-based distributors compete on farm-level outcome guarantees rather than input tonnage. Procurement committees at agricultural cooperatives now evaluate vendor performance on yield response metrics rather than unit pricing. This behavioral shift concentrates contract awards among suppliers with embedded agronomist teams and soil testing capabilities.
Egypt Agrochemicals Market Segmentation
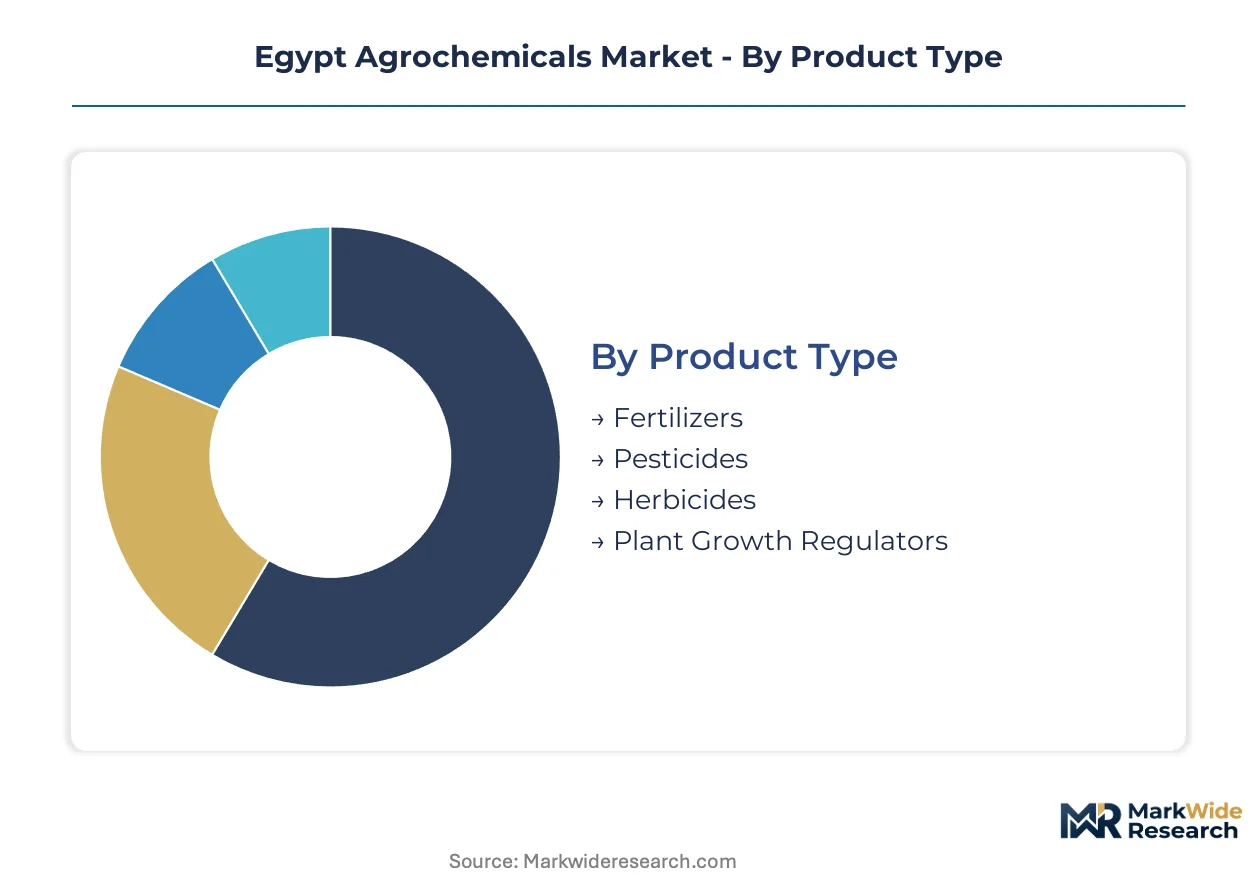
Segmentation in Egypt's agrochemical market reveals distinct service intensity profiles across product categories. Fertilizer buyers demand soil testing and fertigation calibration support, while pesticide purchasers prioritize resistance management advisory and application timing protocols.
Product Type:
After-sales service intensity varies sharply across input categories, with biological formulations requiring ongoing technical handholding that commodity fertilizers rarely need.
- Fertilizers:Urea and compound grades dominate wheat and rice intensification programs across the Delta. Kafr El-Sheikh and Beheira governorate cooperatives bulk-purchase NPK blends under Ministry of Agriculture subsidy quotas tied to water efficiency metrics.
- Pesticides:Organophosphate and pyrethroid formulations face residue tolerance pressure from CODEX-aligned export protocols. Fall armyworm resistance in Upper Egypt sugarcane belts accelerates chemistry rotation toward microbial alternatives.
- Herbicides:Glyphosate and selective grass killers serve mechanized maize and soybean zones where labor scarcity favors pre-emergent spray programs.
- Plant Growth Regulators:Gibberellin and cytokinin applications concentrate in export-oriented grape and strawberry clusters requiring uniform sizing for EU supermarket specifications.
Fertilizers hold the largest share; momentum sits with pesticides as resistance patterns force portfolio renewal.
End Use Industry:
Cost tier differentiation separates subsidized commodity crop programs from premium-priced horticulture advisory bundles.
- Agriculture:Wheat, rice, and sugarcane operations absorb the majority of subsidized urea and compound fertilizer volumes. New Valley reclamation projects face groundwater nitrate threshold enforcement that caps nitrogen application rates below yield optimization.
- Horticulture:Commercial greenhouse operators in the Nile Delta pay premium prices for precision nutrient delivery systems integrated with drip irrigation infrastructure. Kafr El-Sheikh sensor-guided fertigation deployments map nutrient demand at sub-field resolution.
- Landscaping:Municipal and private estate maintenance drives steady demand for broad-spectrum herbicides and slow-release fertilizer formulations.
- Turf:Golf course and sports field operators represent a narrow premium segment focused on aesthetic uniformity and rapid wear recovery.
Agriculture captures volume concentration; horticulture climbs the fastest on export revenue per hectare.
Formulation Type:
Application method dictates margin structure, with liquid concentrates commanding technical advisory premiums that granular commodities cannot extract.
- Liquid:Suspension concentrates and soluble powders dominate mechanized farming zones where spray drift reduction and tank-mix compatibility cut field labor hours. Upper Egypt potato belts favor liquid delivery through center-pivot and drip systems.
- Granular:Broadcasting applications persist in smallholder wheat and rice plots where equipment penetration remains limited. Compound fertilizer grades with polymer coating enable controlled release aligned with crop uptake curves.
- Powder:Wettable powders retain share in fungal disease management where shelf stability and transport economics outweigh mixing inconvenience.
- Suspensions:Oil-based and aqueous suspensions serve tree crop and vine applications requiring extended residual activity and rainfastness.
Granular formulations retain volume leadership; liquid formats gain share fastest on precision agriculture adoption.
Distribution Channel:
Customer type fragmentation—smallholder cooperatives versus integrated commercial farms—forces channel specialization that pure retail or wholesale models cannot serve.
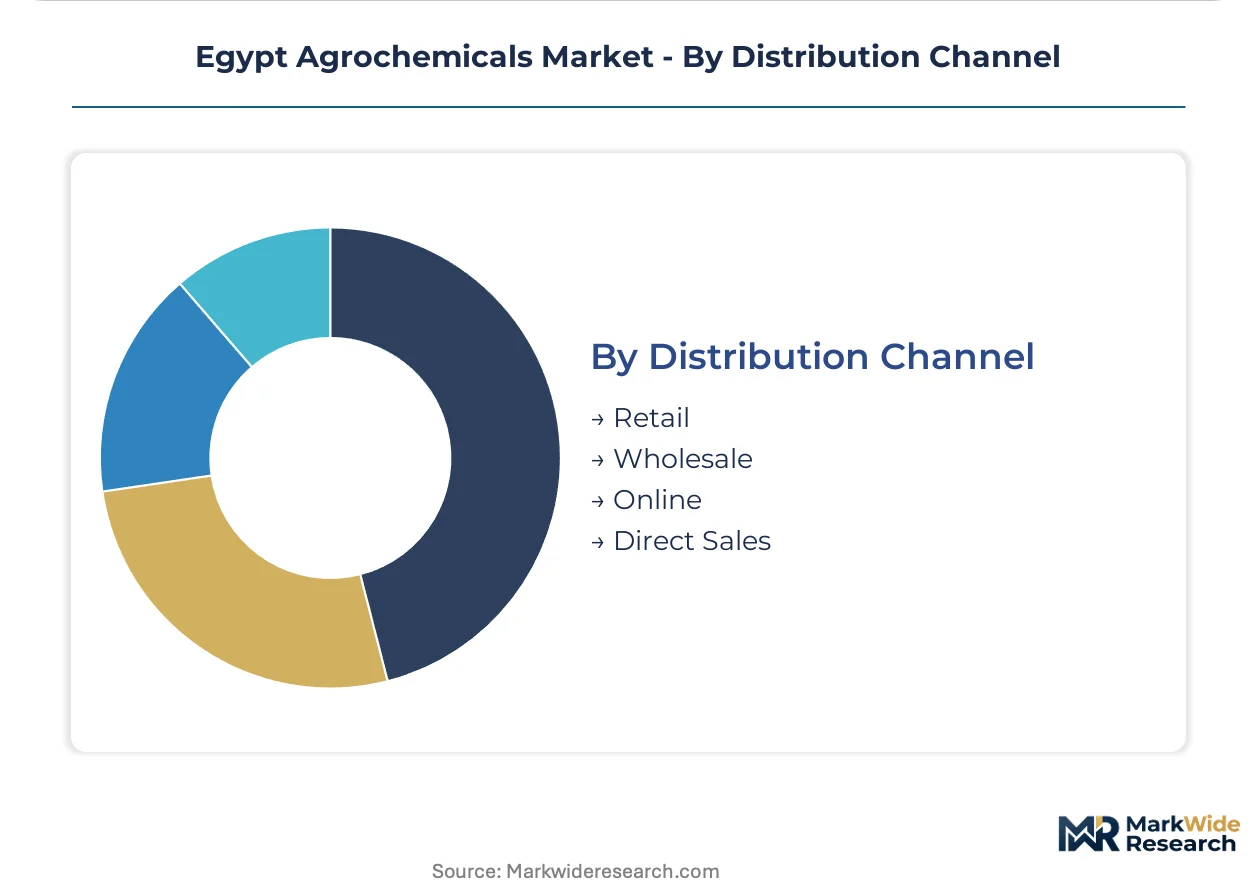
- Retail:Agricultural supply shops in Delta towns serve fragmented smallholder demand for packaged fertilizers and generic pesticides. Shopkeepers double as informal advisors on application rates and timing.
- Wholesale:Governorate-level distributors aggregate cooperative procurement and supply commercial greenhouse clusters with bulk compound grades. UPL Limited anchors smallholder outreach through this layer.
- Online:Digital platforms emerging in Cairo and Alexandria metropolitan areas offer price transparency and technical content access for educated younger farm managers.
- Direct Sales:Multinational suppliers with embedded agronomist teams contract directly with export-oriented horticulture operations for outcome-based service bundles including soil testing and spray log documentation.
Wholesale channels hold the largest share; direct sales expand most quickly on farm-level outcome guarantee adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Egypt's agrochemical landscape diverge sharply between the Nile Delta's intensive horticulture zones and Upper Egypt's mechanized field crop belts. The Delta favors precision nutrient delivery systems integrated with greenhouse infrastructure, while Upper Egypt concentrates on bulk fertilizer applications for sugarcane and potato cultivation.
Nile Delta Governorates
Commercial greenhouse operators in Kafr El-Sheikh and Beheira drive specialty fertilizer demand through sensor-guided fertigation deployments. The Ministry of Agriculture and Land Reclamation ties subsidized input quotas to water efficiency metrics, redirecting procurement toward compound NPK blends. Kafr El-Zayat anchors domestic pesticide formulation capacity with backward integration into active ingredient blending operations.
Upper Egypt
Sugarcane and potato belts in Sohag and Qena governorates absorb liquid formulation uptake through center-pivot and drip irrigation expansion. Groundwater nitrate threshold enforcement from the Egyptian Organization for Standardization and Quality caps nitrogen application rates below yield optimization levels. Drip irrigation infrastructure drives precision nutrient delivery adoption among mechanized farming cooperatives.
New Valley Reclamation Zones
Desert agriculture projects in Toshka and East Oweinat face tightening regulatory monitoring on groundwater contamination from nitrogen runoff. Water quota allocations under the Nile Basin Cooperative Framework reshape priority crop lists for subsidized agrochemical programs. Experimental farms test controlled-release polymer coatings to align fertilizer delivery with crop uptake curves under water scarcity constraints.
Alexandria and Mediterranean Coast
Export-oriented horticulture clusters around Alexandria require CODEX-aligned residue tolerance protocols for grape and strawberry supply chains. Port infrastructure connectivity enables ammonia-based nitrogen producers to secure regional export arbitrage into deficit markets. Dedicated spray service providers with documented application logs contract directly with export packing houses.
Greater Cairo Periphery
Agricultural supply shops in Delta towns serve fragmented smallholder demand for packaged fertilizers and generic pesticides. Digital platforms emerging in Cairo and Alexandria metropolitan areas offer price transparency for educated younger farm managers. Procurement committees at agricultural cooperatives evaluate vendor performance on yield response metrics rather than unit pricing.
Egypt Agrochemicals Market Competitive Landscape
Capability concentration sits with multinational distributors possessing embedded agronomist teams; scale advantage sits with domestic formulators leveraging backward integration into active ingredient operations. The vendor base stratifies across three tiers: global suppliers with outcome-based service bundles, regional distributors anchoring smallholder outreach programs, and domestic blenders serving subsidized commodity crop segments. Dominant competitive moves include farm-level application service bundling and Mediterranean port infrastructure connectivity for export arbitrage.
Among multinational distributors, UPL Limited and Syngenta Group Co., Ltd. occupy positions emphasizing technical advisory capacity and precision agriculture platform deployment. Domestic formulators exemplify scale-driven positioning, with Kafr El-Zayat Pesticides and Chemicals Co. representing backward integration archetypes and Abu Qir Fertilizers and Chemicals Industries anchoring ammonia-based nitrogen production through captive port infrastructure. These named entities illustrate the capability-scale tension structuring competitive dynamics without exhausting the participant roster.
| Leading Market Players |
|---|
| UPL Limited |
| FMC Corporation |
| Syngenta Group Co., Ltd. |
| Abu Qir Fertilizers and Chemicals Industries |
| Kafr El-Zayat Pesticides and Chemicals Co. |
| Bayer CropScience Ltd. |
| Corteva Agriscience |
| Misr Fertilizers Production Company (MOPCO) |
| BASF SE |
| Others |
Supply & Pricing Matrix
Active ingredient manufacturing concentration in China and India funnels pricing power toward multinational formulators while compressing margins for Egyptian blenders dependent on imported technical grade inputs. This upstream concentration reconfigures margin pools downstream toward technical advisory services and farm-level application bundling.
Pricing Analysis
Contract-based long-term offtake agreements dominate ammonia and urea procurement through Abu Qir Fertilizers' pipeline-linked Mediterranean port infrastructure, while spot markets govern active ingredient purchases by domestic formulators. Price differentiation rests on ISO 17025 certification tier and after-sales agronomic support depth, with export-oriented horticulture operations paying premiums for documented spray logs and residue compliance. Cost compression in generic pesticide tiers is intensifying because of CODEX-aligned dual-certification testing requirements. Smallholder cooperatives in Delta governorates exhibit highest price sensitivity, while commercial greenhouse operators in Kafr El-Sheikh demonstrate lowest sensitivity due to yield-response guarantee contracting.
Supply Chain Analysis
Tariff exposure between Egypt and EU regulatory jurisdictions dominates supply chain risk planning for export-bound horticulture inputs facing CODEX maximum residue limit enforcement. Geographic supply concentration centers on China for technical grade active ingredients, Germany for precision fertigation equipment, and Saudi Arabia for ammonia feedstocks. Raw material dependencies include petrochemical-derived organophosphate precursors, phosphate rock from Red Sea deposits, and natural gas for ammonia synthesis. Single-source vulnerability persists in microbial inoculant strains subject to Ministry of Agriculture and Land Reclamation registration delays. Distribution runs through governorate-level wholesale aggregators serving cooperative procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across Egypt's agrochemical landscape creates niche capture opportunities as precision agriculture adoption splits demand between commodity fertilizer bulk purchasers and specialty input service buyers.
For Market Incumbents: Entrench market position through backward integration into active ingredient blending operations and embedded agronomist team expansion across Delta governorates. Kafr El-Zayat Pesticides and Chemicals Co.'s captive blending capacity represents a defensible moat against multinational distributors. Certification investment in ISO 17025 testing methodologies accelerates import clearance and locks in cooperative procurement committee contracts. For New Entrants and Emerging Players: Upper Egypt's sugarcane and potato belts present the most penetrable geography, with drip irrigation expansion driving liquid formulation demand underserved by incumbent granular-focused distributors. Biological alternative substitution for fall armyworm resistance management offers application-specific white space. A go-to-market angle anchored in sensor-guided fertigation system calibration services bypasses capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: Capital is best deployed toward domestic formulators with Mediterranean port pipeline connectivity enabling regional export arbitrage. Long-term viability over the coming decade hinges on water quota adaptation under the Nile Basin Cooperative Framework and precision agriculture platform integration. The signal to watch is Ministry of Agriculture subsidy program reallocation toward water-efficient crop categories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Blending | Kafr El-Zayat Pesticides and Chemicals Co. secures margin control against imported technical grade volatility. |
| Embedded Agronomist Team Expansion | UPL Limited's Delta governorate outreach captures cooperative procurement through yield-response guarantees. |
| ISO 17025 Certification Investment | Accelerates compound fertilizer import clearance under Egyptian Organization for Standardization and Quality enforcement. |
| Sensor-Guided Fertigation Deployment | Commercial greenhouse operators in Beheira achieve sub-field nutrient mapping and input waste compression. |
| Mediterranean Port Pipeline Connectivity | Abu Qir Fertilizers and Chemicals Industries enables ammonia-based nitrogen export arbitrage into regional deficit markets. |
Research Methodology
Desk research of customs trade records, Ministry of Agriculture subsidy program disclosures, and SEC filings from listed agrochemical multinationals preceded structured interviews with procurement committee heads at Delta agricultural cooperatives, technical directors at domestic formulation plants, and regulatory affairs officers at import registration consultancies. Primary fieldwork with commercial greenhouse operators in Kafr El-Sheikh and Beheira governorates validated secondary estimates on precision agriculture adoption rates. Bottom-up demand modeling across crop-specific input intensity metrics triangulated against top-down value chain revenue pool analysis.
Assumptions around Nile Basin Cooperative Framework water quota implementation timelines and Ministry of Agriculture subsidy reallocation priorities were held fixed across baseline scenarios, while biopesticide registration timeline variability and EU export market access conditions were stress-tested through sensitivity bands. Segmentation dimensions modeled include product type tier, end-use crop category, formulation technology, and distribution channel structure. CAGRs were derived from annualized growth rate fitting across the projection horizon, incorporating drip irrigation expansion curves and resistance-driven chemistry rotation patterns as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Egyptian pound exchange rate volatility, natural gas pricing for ammonia feedstock economics, or global petrochemical feedstock indices would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and export market access continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
Superphosphates Market
Agrochemicals
India Agrochemicals Market
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
South America Agrochemicals Market
Agrochemicals
Australia Agrochemicals Market
Agrochemicals
Middle East and Africa Plant Growth Regulators Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
Agrochemical Active Ingredients Market
Agrochemicals
Agrochemical Market
Agrochemicals
Potassium Humate Market
Agrochemicals
South Africa Agrochemicals Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
Global Buprofezin Market
Agrochemicals
Indonesia Agrochemicals Market
Agrochemicals
Africa Agrochemicals Market
Agrochemicals
Canada Agrochemicals Market