
 North America Agrochemicals Market | 2026-2036
North America Agrochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Agrochemicals Market Analytics
Biologicals integration revenue is rewriting margin distribution across the North American crop input value chain. Bayer AG leverages its seed-treatment pipeline to anchor premium positioning in corn and soybean segments. Corteva Agriscience sustains broad herbicide portfolios while navigating glyphosate litigation exposure. Nutrien Ltd. dominates retail distribution through its network of farm-service centers across the U.S. and Canada.
Agrochemicals comprise synthetic and biological formulations designed to enhance crop productivity through nutrient delivery, pest control, or disease management, with active ingredients typically formulated as emulsifiable concentrates, wettable powders, or granules for field application. The primary commercial purpose centers on protecting yield potential across intensive row-crop systems and high-value fruit and vegetable production. Fertilizers occupy the largest value share, reflecting sustained nitrogen demand from corn and wheat growers across the U.S. Midwest, while herbicides face structural pressure from resistant weed populations driving rotation toward novel modes of action. Seed treatment applications within the application dimension are expanding fastest, propelled by farmer preferences for bundled seed-chemistry packages and reduced field-spray passes.
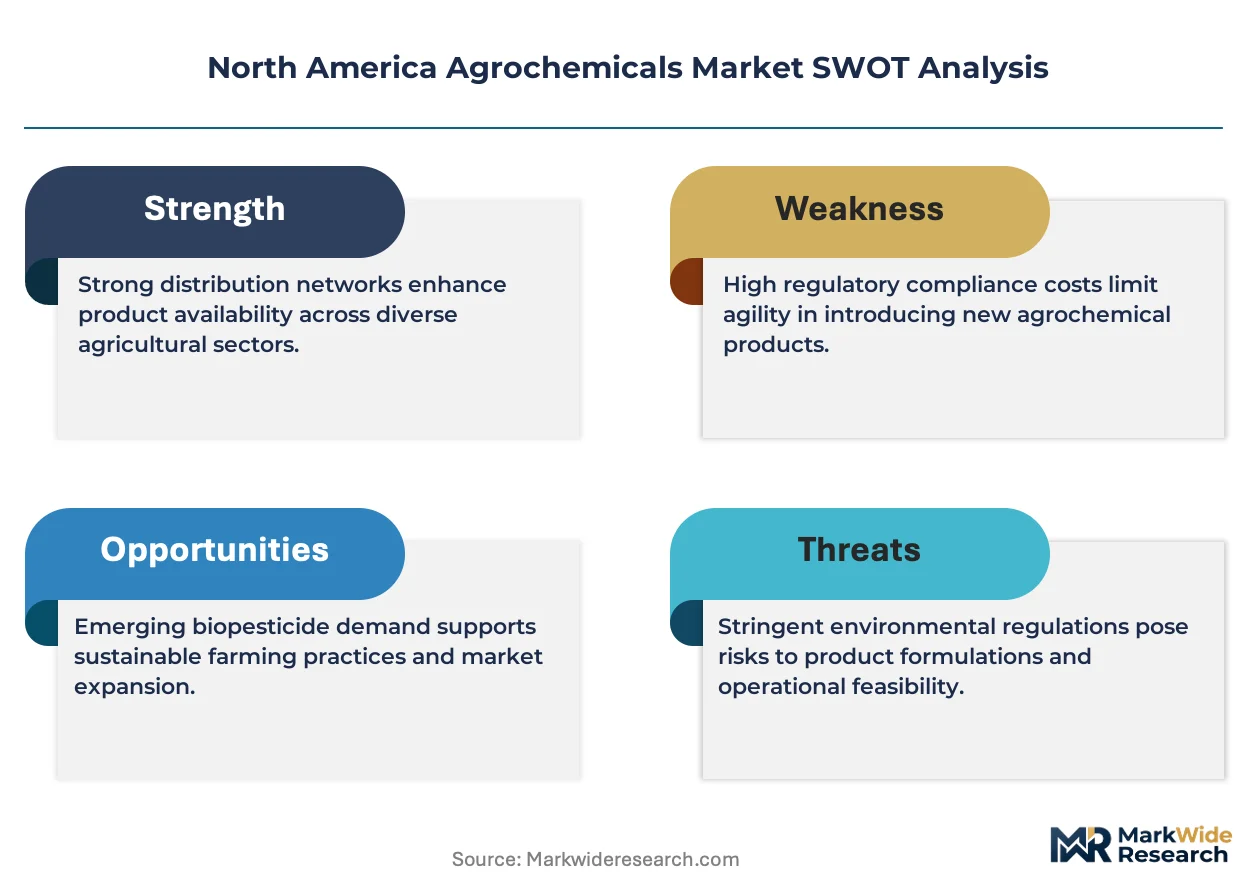
The U.S. EPA governs pesticide registration under FIFRA, with state-level departments of agriculture in Iowa, Illinois, and Nebraska enforcing additional application certification requirements that shape product accessibility. Health Canada's PMRA maintains parallel review timelines, creating asynchronous market entry windows between the U.S. and Canadian jurisdictions. The EU Green Deal's Farm to Fork strategy indirectly influences North American exporter compliance standards, particularly for residue limits on crops destined for European markets. Stakeholders must monitor the trajectory of U.S. state-level neonicotinoid restrictions and their potential cascade into federal re-registration outcomes.
Market Dynamics
Herbicide resistance management protocols across the U.S. Corn Belt are forcing unprecedented rotation toward novel modes of action, compressing product lifecycles and restructuring R&D prioritization across the North American crop protection sector.
Growth Catalysts
- EPA Biopesticide Registration Pathways:Accelerated review timelines under the U.S. EPA's biopesticide division are channeling formulation investments toward microbial and biochemical active ingredients for specialty crop applications.
- Precision Application Technology:Variable-rate spraying systems deployed across California's Central Valley orchards are reducing chemical load per acre while sustaining yield targets through sensor-guided spot treatment.
- Seed-Chemistry Bundling:Farmer preferences for single-pass input decisions are expanding seed treatment attachment rates, particularly in Iowa and Illinois corn-soy rotations.
Market Restraints
- Active Ingredient Import Concentration:Reliance on Chinese-manufactured technical-grade glyphosate and 2,4-D intermediates exposes formulators to tariff volatility and ocean freight disruption.
- Glyphosate Litigation Overhang:Mass tort exposure surrounding glyphosate carcinogenicity claims is constraining balance-sheet flexibility for manufacturers with legacy herbicide portfolios.
- Neonicotinoid Regulatory Friction:State-level restrictions on neonicotinoid seed treatments in New York and Minnesota are creating patchwork compliance burdens that complicate national product registration strategies.
Strategic Opportunities
- Biologicals Integration in Florida Specialty Crops:Citrus greening management protocols are opening substitution pathways for microbial fungicides and biostimulants in integrated pest management programs.
- Carbon-Intensity Scoring:Emerging low-carbon fuel standard credit mechanisms in California and Canada are creating premium pricing tiers for nitrogen efficiency technologies that reduce field emissions.
- Drone Application Services:Aerial application platforms are bypassing traditional ground-spray contractor networks, enabling direct-to-grower service models in fragmented vegetable production regions.
Industry Challenges
- Resistance Monitoring Infrastructure:Systematic weed and pest resistance surveillance requires sustained public-private coordination that remains underfunded across state extension services.
- Formulation Compatibility Complexity:Tank-mixing biological and synthetic chemistries demands validated adjuvant systems that many retail distribution networks lack technical capacity to support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Agrochemicals Market |
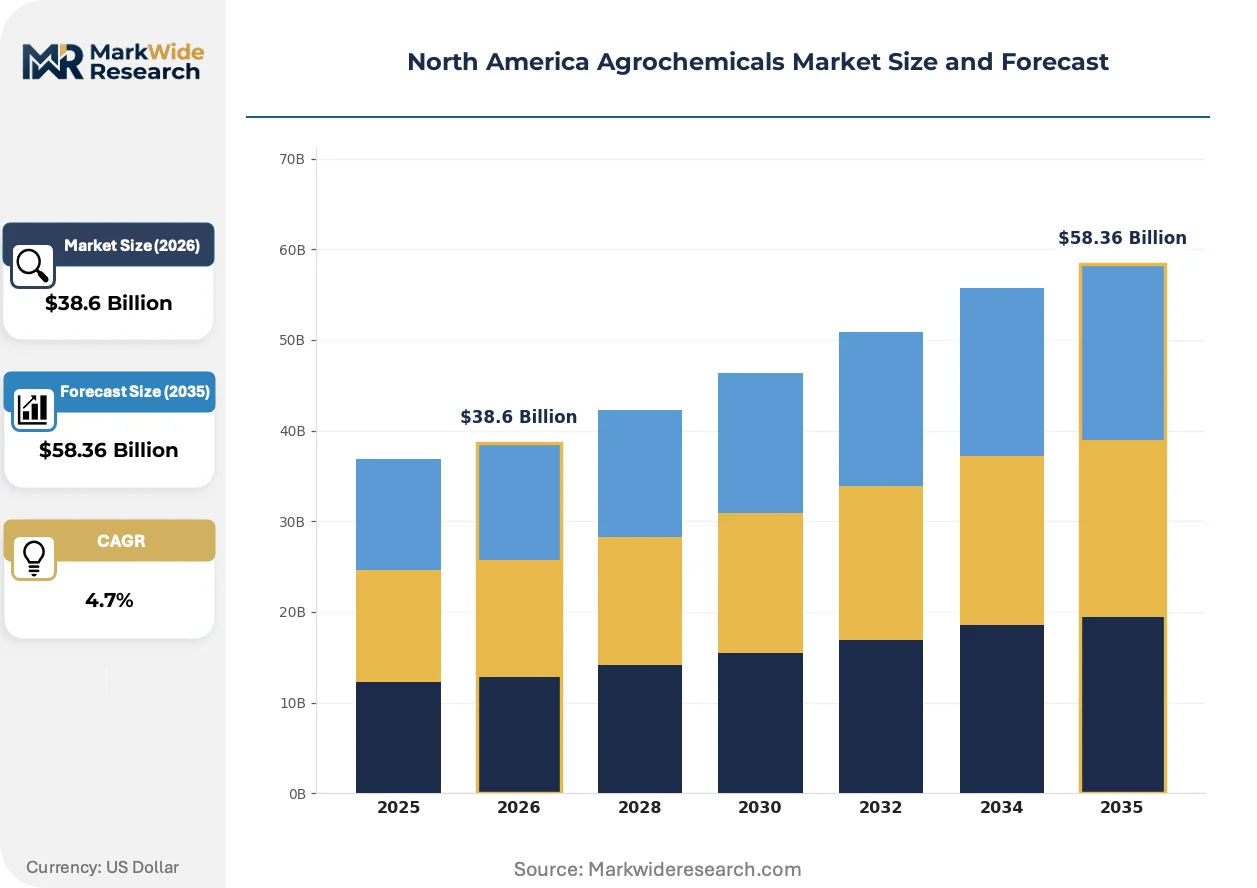
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.36 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fertilizers, Herbicides, Insecticides, Fungicides End Use Industry: Agronomy, Horticulture, Organic Farming, Turf Management Application: Crops, Soil Treatment, Seed Treatment, Post-Harvest Distribution Channel: Online Retail, Agrochemical Dealers, Distributors, Cooperatives |
| Companies Covered | Syngenta Group, Bayer AG, Corteva Agriscience, BASF SE, FMC Corporation, UPL Limited, Nutrien Ltd., The Mosaic Company, Yara International ASA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Agrochemicals Market Evolving Landscape
Digital agriculture platforms are compressing the feedback loop between field observation and input adjustment, while biological formulation science and evolving residue standards reshape product development roadmaps across North America.
Variable-rate application technology is digitizing spray decision-making at the sub-field scale. Iowa and Illinois corn growers are adopting prescription maps derived from satellite imagery and soil conductivity surveys to modulate herbicide rates zone-by-zone. This granularity is digitizing input optimization, reducing chemical volume on low-productivity acres while protecting yield on high-potential zones.
The U.S. EPA's Endangered Species Act consultation requirements are extending pesticide registration timelines for products affecting listed species habitats. Manufacturers are front-loading ecological risk assessments and habitat mitigation proposals to preempt litigation-driven delays. Row-crop herbicides with watershed proximity to salmon-bearing streams in the Pacific Northwest face the most acute procedural constraints.
Outcome-based purchasing arrangements are displacing traditional per-acre chemical pricing in large-scale vegetable operations. California lettuce and strawberry growers are contracting with input suppliers for pest-free harvest guarantees rather than accepting product liability themselves. This risk transfer concentrates in the Salinas and Santa Maria valleys, where processor consolidation enables contract standardization across thousands of acres.
North America Agrochemicals Market Segmentation
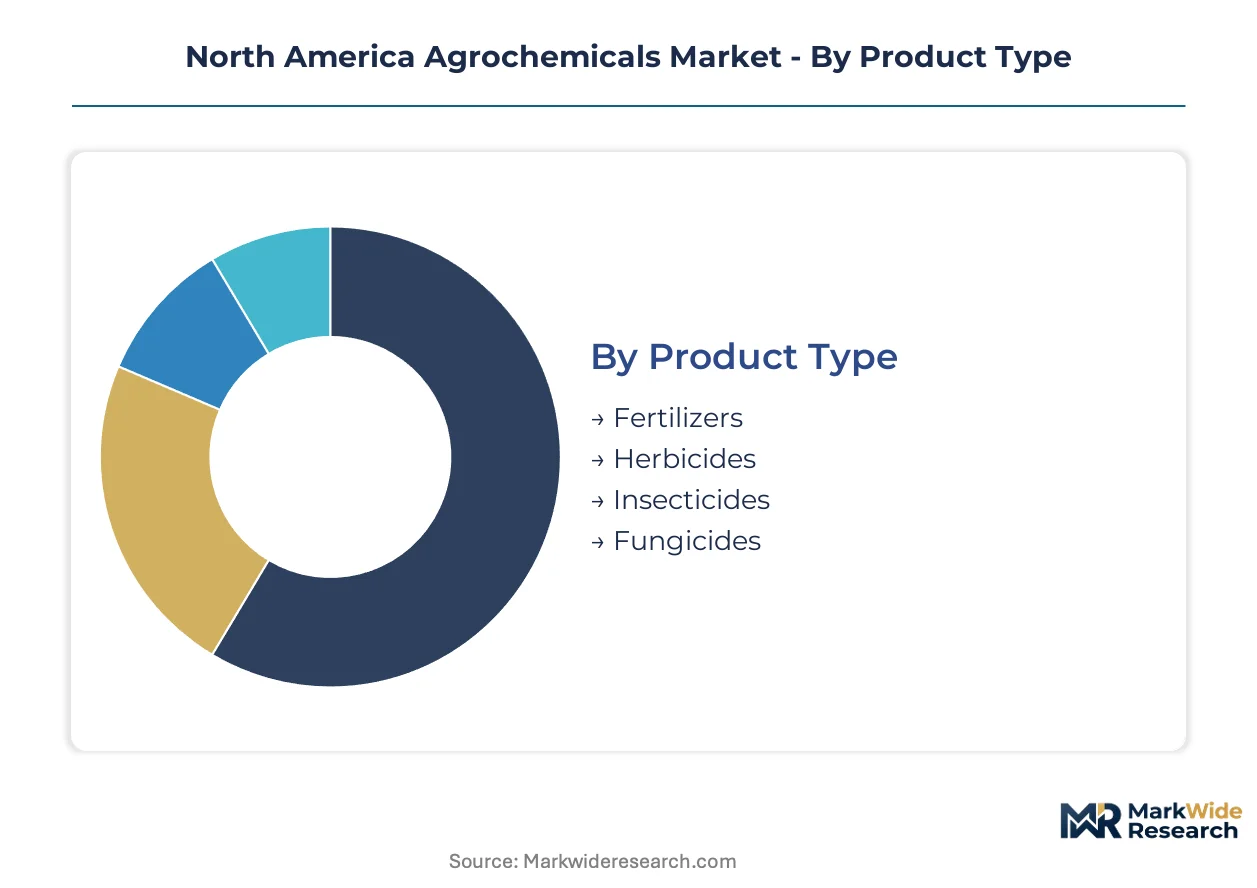
Agrochemical purchasing patterns diverge sharply between intensive row-crop systems and high-value specialty production. Segmentation reveals how formulation chemistry, application timing, and channel access reshape competitive positioning across the North American value chain.
Product Type:
Mature commodity chemistries dominate volume flows while emerging biological formulations capture margin expansion.
- Fertilizers:Nitrogen, phosphorus, and potassium compounds formulated as granular, liquid, or controlled-release products. Corn and wheat growers across Iowa, Illinois, and Nebraska drive sustained demand despite mounting environmental compliance costs for nutrient management plans.
- Herbicides:Synthetic auxins, ALS inhibitors, and PPO inhibitors delivered as emulsifiable concentrates or water-dispersible granules. Resistance management protocols in the U.S. Corn Belt are compressing product lifecycles and accelerating rotation toward novel modes of action.
- Insecticides:Neonicotinoid, pyrethroid, and diamide chemistries targeting chewing and sucking pests. EPA ecological risk assessments and state-level pollinator restrictions are narrowing registration pathways for legacy actives.
- Fungicides:Triazoles, strobilurins, and SDH inhibitors protecting against foliar and soil-borne pathogens. Specialty crop applications in California and Florida sustain premium pricing tiers.
Fertilizers retain volume leadership; herbicides hold the steepest expansion curve as resistance management intensifies.
End Use Industry:
Cost tier stratification separates commodity input purchasers from precision-dependent specialty operators.
- Agronomy:Large-scale row-crop production systems optimizing yield per acre through calibrated nutrient and pest management programs. U.S. Midwest corn-soy rotations represent the core demand concentration.
- Horticulture:Fruit, vegetable, and ornamental production requiring residue-compliant formulations and precise application timing. California Central Valley and Florida citrus belts anchor consumption.
- Organic Farming:Certified operations restricted to OMRI-listed inputs including microbial pesticides and mineral-based fungicides. Supply chain verification requirements create premium channel structures.
- Turf Management:Golf courses, athletic fields, and municipal landscapes demanding aesthetic performance with minimal environmental exposure. Seasonal application windows concentrate purchasing in spring and fall.
Agronomy retains volume leadership; organic farming holds the steepest expansion curve.
Application:
Timing of intervention relative to crop development stage determines formulation selection and equipment compatibility.
- Crops:Foliar sprays and soil-directed applications during vegetative and reproductive growth stages. Variable-rate technology adoption is climbing fastest in Iowa and Illinois corn operations.
- Soil Treatment:Pre-plant incorporated or at-planting applications of fumigants, herbicides, and nutrients. Fumigation demand concentrates in California strawberry production regions.
- Seed Treatment:Prophylactic coating of germplasm with fungicides, insecticides, and biological inoculants. Farmer preferences for bundled seed-chemistry packages are expanding attachment rates in corn and soybean segments.
- Post-Harvest:Storage protectants and surface treatments extending shelf life for grains, fruits, and vegetables. Processor consolidation in the Salinas Valley enables contract standardization.
Crop applications retain volume leadership; seed treatment holds the steepest expansion curve.
Distribution Channel:
Customer type and geography determine whether procurement flows through relationship-based dealer networks or direct digital platforms.
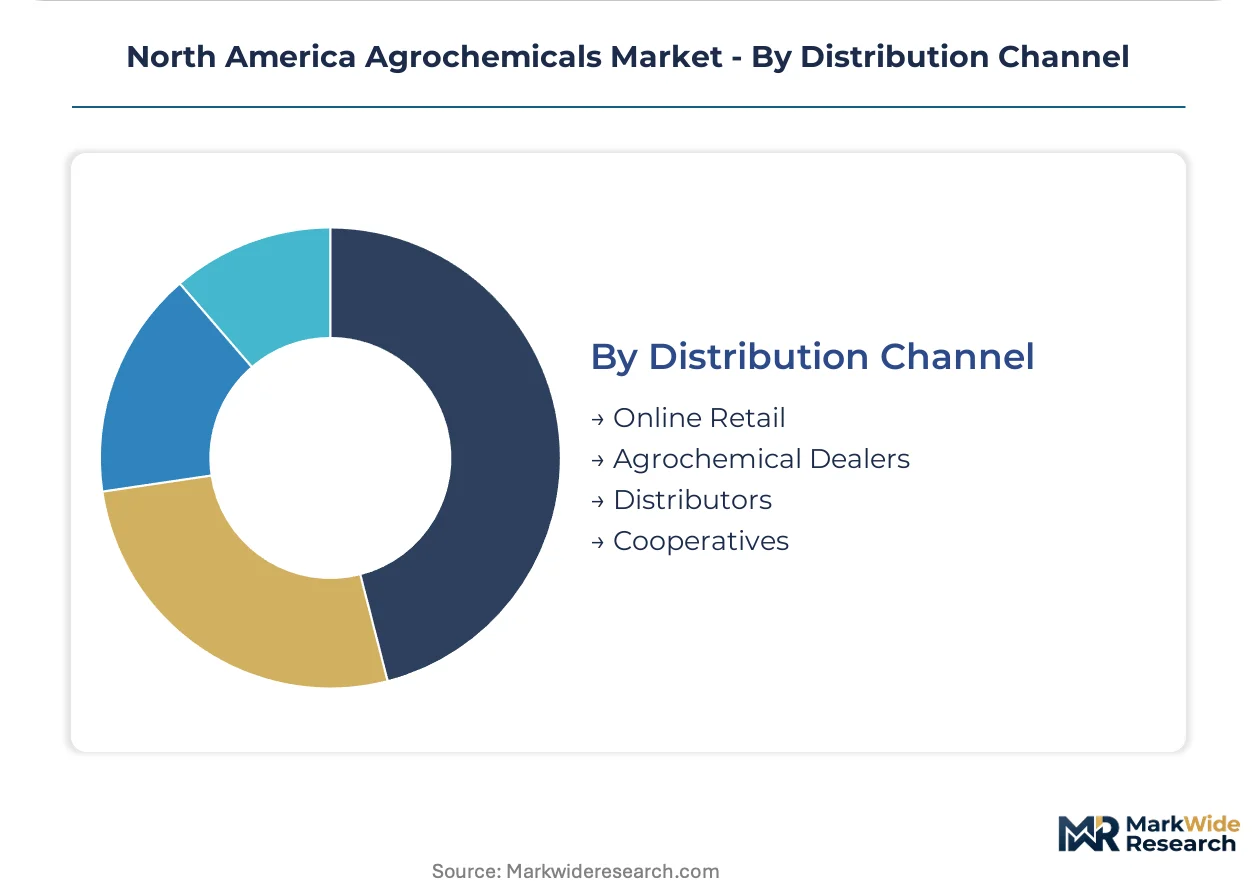
- Online Retail:E-commerce platforms serving smallholder and hobby farm segments with packaged consumer quantities. Digital penetration remains limited in prescription-required crop protection products.
- Agrochemical Dealers:Independent and manufacturer-aligned retail locations providing technical consultation and application services. Nutrien's farm-service center network spans the U.S. and Canadian production belts.
- Distributors:Regional wholesalers consolidating inventory and logistics for dealer networks. Tariff exposure on Chinese-manufactured technical-grade actives compresses margin structures.
- Cooperatives:Member-owned purchasing organizations aggregating volume for price negotiation and shared storage infrastructure. Dominant across the Northern Plains and Prairie provinces.
Agrochemical dealers retain volume leadership; online retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the North American agrochemicals market. Large-scale corn and soybean operators in the U.S. Midwest exhibit high price sensitivity to nitrogen fertilizers, while California specialty crop growers absorb premium pricing for residue-compliant formulations without volume reduction.
United States
The U.S. Corn Belt drives volume concentration for herbicides and nitrogen fertilizers, with Iowa and Illinois corn-soy rotations requiring intensive resistance management protocols. The U.S. EPA's biopesticide registration pathways under FIFRA are accelerating microbial formulation investments. California's Central Valley anchors specialty crop demand, where precision application systems in Fresno County orchards reduce chemical load per acre through sensor-guided spot treatment.
Canada
Prairie province wheat and canola growers sustain fertilizer demand despite carbon pricing pressures on nitrogen emissions. Health Canada's PMRA maintains parallel pesticide review timelines, creating asynchronous market entry windows with U.S. jurisdictions. Ontario's farm-service center networks concentrate retail distribution infrastructure, with Nutrien Ltd. operating integrated supply chains across the province's corn belt.
Mexico
Vegetable export producers in Sinaloa and Baja California face tightening EU residue limits, driving substitution toward biological formulations for crops destined for European markets. Mexico's national phytosanitary regulator enforces application certification requirements that shape product accessibility for smallholder segments. The Bajío region's strawberry and berry production clusters are expanding integrated pest management protocols to maintain supermarket chain contracts.
North America Agrochemicals Market Competitive Landscape
Capability concentration sits with integrated innovation platforms; scale advantage sits with retail distribution networks. The North American agrochemicals market structures around three tiers: global research-based manufacturers with seed-chemistry bundling capacity, regional formulators with import-dependent technical-grade supply chains, and farm-service retailers controlling last-mile customer relationships. Dominant competitive moves include biological portfolio diversification to offset synthetic chemistry litigation exposure and precision agriculture technology partnerships to anchor subscription-based revenue models.
Within the integrated innovation tier, Bayer AG and Corteva Agriscience exemplify divergent strategic positioning. Bayer anchors premium seed-treatment positioning in corn and soybean segments through its germplasm-chemistry bundling infrastructure. Corteva sustains broad herbicide portfolios while navigating glyphosate litigation exposure through portfolio rotation toward novel modes of action. Nutrien Ltd. occupies the scale-driven retail vector, dominating farm-service center networks across U.S. and Canadian production belts with integrated agronomic advisory capacity.
| Leading Market Players |
|---|
| Syngenta Group |
| Bayer AG |
| Corteva Agriscience |
| BASF SE |
| FMC Corporation |
| UPL Limited |
| Nutrien Ltd. |
| The Mosaic Company |
| Yara International ASA |
| Others |
Value Network & Pricing Analysis
Jiangsu province's technical-grade glyphosate manufacturing clusters feed directly into North American formulator pricing power, with capacity utilization swings at Chinese intermediates producers transmitting within one quarter to Midwest distributor contract negotiations. Tariff exposure on 2,4-D acid imports compresses margin structures for regional blenders lacking alternative sourcing pathways.
Pricing Analysis
Long-term offtake contracts between Iowa cooperatives and nitrogen manufacturers dominate fertilizer procurement, while spot purchasing governs emergency herbicide restocking during resistance outbreak seasons. Three-tier pricing structure across premium biological formulations, standard synthetic chemistries, and economy generic alternatives separates residue-compliant specialty crop inputs from commodity row-crop applications. Cost compression in economy-tier glyphosate alternatives is intensifying because Chinese technical-grade oversupply meets tariff-hedging inventory builds. Large-scale corn operators in Illinois exhibit acute price sensitivity to nitrogen timing, whereas California strawberry growers absorb premium biological pricing without volume reduction.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for North American agrochemical formulators. Technical-grade glyphosate, 2,4-D intermediates, and neonicotinoid actives draw from concentrated manufacturing in Jiangsu, Shandong, and Zhejiang provinces. Single-source vulnerability in microbial fermentation capacity for biopesticide active ingredients threatens biological portfolio expansion timelines. Distribution runs through Nutrien's farm-service center network and independent dealer channels across the U.S. Corn Belt and Canadian Prairie provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American agrochemicals market sits in cyclical recovery mode, with herbicide resistance management protocols driving replacement demand for novel modes of action across Midwest corn-soy rotations.
For Market Incumbents: Insulate premium positioning through backward integration into microbial fermentation capacity for biological actives, countering synthetic chemistry litigation exposure. Deepen channel control via exclusive seed-chemistry bundling partnerships with Iowa and Illinois germplasm providers. Lock in long-term offtake with Chinese technical-grade suppliers to neutralize tariff volatility on glyphosate intermediates. For New Entrants and Emerging Players: Establish a beachhead in Florida citrus greening management protocols, where microbial fungicide substitution pathways remain underpenetrated by integrated majors. Target drone application services in California Central Valley vegetable districts, bypassing established ground-spray contractor networks. Pursue direct-to-grower subscription models anchored by sensor-guided variable-rate prescription capabilities. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because biological formulation science is concentrating capability with specialized microbial fermentation operators. Acquisition candidates include regional formulators with validated adjuvant systems for tank-mixing biological and synthetic chemistries. Watch EPA biopesticide registration approval velocity as the inflection signal for margin expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Portfolio Expansion | Microbial fermentation investments offset glyphosate litigation exposure for integrated manufacturers. |
| Precision Agriculture Partnerships | Variable-rate technology alliances anchor subscription revenue with Iowa corn growers. |
| Seed-Chemistry Bundling | Exclusive germplasm-treatment packages lock in multi-year offtake across Illinois soybean rotations. |
| Regional Formulator Acquisition | Validated adjuvant capabilities enable biological-synthetic tank-mix compatibility for retail networks. |
| Drone Application Services | Aerial platforms bypass traditional contractor networks in California vegetable production districts. |
Research Methodology
Desk research of EPA registration databases, customs import records, and state extension service resistance monitoring reports preceded structured interviews with agrochemical R&D directors, farm-service center procurement managers, biological formulation scientists, and specialty crop pest control advisers. Primary fieldwork across Iowa, Illinois, California, and Florida production regions validated secondary trade flow estimates. Bottom-up volume modeling triangulated against top-down manufacturer revenue disclosures.
Assumptions held fixed include EPA biopesticide review timeline parameters and Chinese technical-grade export capacity utilization rates, while variables tested included neonicotinoid state restriction propagation speed and precision agriculture adoption curves across the projection horizon. Segmentation modeling incorporated product type, application timing, end-use industry, and distribution channel dimensions. CAGRs derived from historical volume trajectories adjusted for resistance-driven product lifecycle compression.
Macroeconomic conditions sit as an overlay; deviation in corn futures pricing, fertilizer natural gas feedstock costs, or ocean freight rates would shift the trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
Agrochemical Active Ingredients Market
Agrochemicals
Mexico Agrochemicals Market
Agrochemicals
Global Buprofezin Market
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
Indonesia Agrochemicals Market
Agrochemicals
Middle East and Africa Plant Growth Regulators Market
Agrochemicals
Superphosphates Market
Agrochemicals
Canada Agrochemicals Market
Agrochemicals
L-Glufosinate Ammonium Market
Agrochemicals
Agrochemical Market
Agrochemicals
Australia Agrochemicals Market
Agrochemicals
Potassium Humate Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
South America Agrochemicals Market
Agrochemicals
India Agrochemicals Market
Agrochemicals
Africa Agrochemicals Market