
 Superphosphates Market | 2026-2036
Superphosphates Market Size, Share, and Industry Trends Forecast 2026-2036
Superphosphates Market Analytics
Horticultural greenhouse operations is rebalancing demand away from bulk commodity grades toward water-soluble superphosphate formulations. Nutrien Ltd leverages its Prairie distribution network to sustain wholesale volumes across North American agricultural cooperatives. Yara International ASA anchors European supply through its integrated phosphate rock sourcing from Morocco and Brazil. OCP Group dominates Maghreb export corridors with captive mine-to-port infrastructure that controls landed costs in Asian markets.
Superphosphates are phosphate fertilizers manufactured by reacting phosphate rock with sulfuric acid (single superphosphate, typically 16-20% P₂O₅) or phosphoric acid (triple superphosphate, 44-46% P₂O₅), with granulation or liquid suspension processes determining application method and nutrient release profile. Their primary purpose is correcting phosphorus deficiency in soils to support root development, flowering, and grain formation in cereal and oilseed production. Triple superphosphate leads product type revenue due to higher nutrient density reducing freight costs per unit phosphorus, while liquid superphosphate represents the fastest-growing format as precision fertigation systems penetrate protected cultivation. Agricultural application occupies the largest margin pool through volume scale, though turf management commands premium pricing from golf course and sports field maintenance contracts.
The EPA regulates phosphate mining waste under the Clean Water Act, while the EU Fertilizing Products Regulation enforces cadmium and contaminant thresholds that reshape import sourcing toward low-cadmium rock deposits. Brazil's ANVISA and national agricultural ministry oversee fertilizer registration and micronutrient additive approvals that determine which superphosphate variants gain market access. India's FSSAI and state fertilizer departments manage quality certification and subsidy eligibility that steer farmer purchasing toward certified grades. Stakeholders must monitor evolving contaminant standards and traceability requirements as these frameworks increasingly determine competitive market access rather than pure cost position.
Market Dynamics
Phosphate rock supply concentration in Morocco and Western Sahara is reshaping procurement security calculations for fertilizer manufacturers dependent on seaborne imports. This geographic lock-up of mineable reserves forces buyers into long-term offtake negotiations with limited supplier alternatives.
Growth Catalysts
- EU Fertilizing Products Regulation cadmium limits:Low-cadmium superphosphate grades from Brazilian and Russian rock deposits gain preferential market access as the regulation tightens import thresholds.
- Protected cultivation expansion:Greenhouse vegetable operations in the Netherlands and Spain adopt water-soluble superphosphate formulations for precision fertigation systems.
- India's Nutrient Based Subsidy scheme:State procurement programs for micronutrient-coated variants redirect farmer purchasing toward certified triple superphosphate grades.
Market Restraints
- Sulfuric acid feedstock volatility:Smelter acid supply interruptions from copper and zinc production curtail single superphosphate manufacturing capacity.
- Moroccan export corridor dominance:OCP Group's captive mine-to-port infrastructure concentrates Atlantic shipping lanes for Asian-bound phosphate rock.
- Organic phosphate substitution:Composted manure and bone meal applications displace mineral fertilizers in certified organic cereal and vegetable production.
Strategic Opportunities
- Brazilian specialty crop belt:Coffee and citrus growers in Minas Gerais and São Paulo states generate pull for acidulated phosphate rock and customized granulation blends.
- US Inflation Reduction Act biofuel incentives:Corn and soybean acreage expansion for ethanol and renewable diesel production lifts phosphorus application rates across the Corn Belt.
- Direct-to-farm digital platforms:Cooperative purchasing apps in India's Punjab and Haryana states bypass traditional dealer networks for bulk superphosphate orders.
Industry Challenges
- Process engineering talent scarcity:Wet-process phosphoric acid plant operations require specialized corrosion management expertise that retiring workforces deplete.
- Legacy granulation asset retrofit costs:Converting prilling towers to compacted fertilizer lines demands capital outlays that marginal producers cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superphosphates Market |
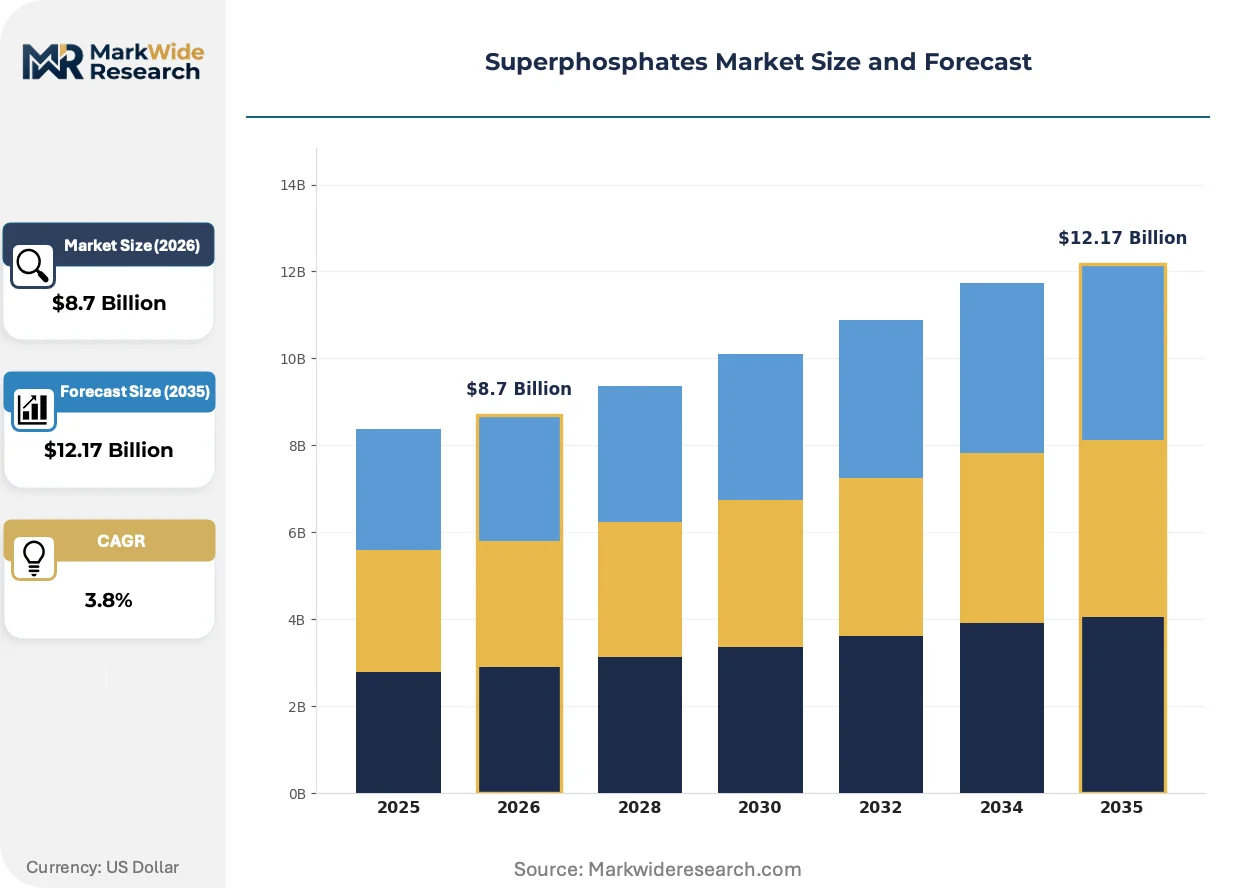
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Superphosphate, Triple Superphosphate, Granulated Superphosphate, Liquid Superphosphate Application: Agricultural, Horticultural, Turf Management, Landscape End User: Farmers, Agricultural Cooperatives, Landscape Contractors, Nurseries Distribution Channel: Retail, Wholesale, Direct Sales, Online Sales |
| Companies Covered | The Mosaic Company, Nutrien Ltd, Yara International ASA, EuroChem Group, PhosAgro Group of Companies, ICL Group, OCP Group, Coromandel International Ltd, Innophos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superphosphates Market Evolving Landscape
Superphosphate manufacturing is pivoting toward precision agriculture compatibility and contaminant traceability as downstream buyers demand input documentation for sustainability certification programs.
Granulation technology is consolidating around compaction and spherodizing methods that produce uniform particle sizes for pneumatic spreader calibration. North American agricultural cooperatives specify these grades for variable-rate application equipment. The shift is compressing demand for traditional prilled superphosphate with broader size distributions.
REACH cadmium and heavy metal testing protocols are forcing importers to document phosphate rock provenance through laboratory certification. Fertilizer blenders in Germany and Poland now reject high-cadmium cargoes from unspecified origins. This regulatory friction is segmenting the European market into certified low-contaminant and uncertified commodity tiers.
Farmer buying collectives are aggregating demand through state-mandated procurement portals that publish tender prices transparently. India's e-URVARAK platform and Brazil's Agronow system displace informal dealer credit relationships with cash-preferred bulk transactions. This channel shift concentrates volume with manufacturers offering direct logistics contracts rather than distributor networks.
Superphosphates Market Segmentation
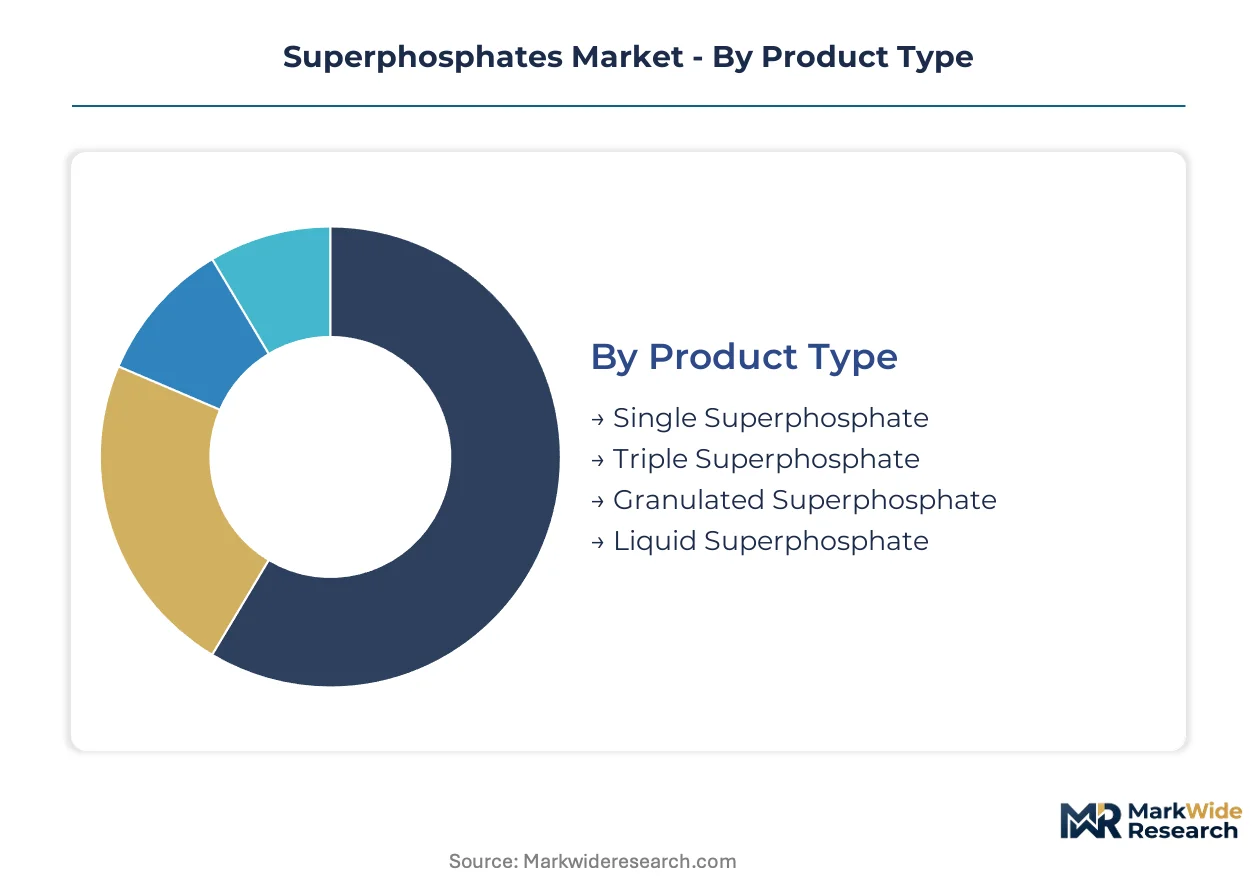
Superphosphate manufacturers navigate divergent certification burdens across product formats and end-use channels. Each segment carries distinct regulatory documentation requirements that determine market access and pricing power.
Product Type:
REACH cadmium testing protocols and Brazil's ANVISA registration requirements apply unevenly across product formats, with liquid variants facing additional micronutrient additive approvals.
- Single Superphosphate:Manufactured through sulfuric acid reaction with phosphate rock, yielding 16-20% P₂O₅ content in powdered or granular form. Demand concentrates in India's wheat-rice belt where state subsidy programs favor lower-cost phosphorus correction for cereal production, though sulfuric acid feedstock volatility from copper smelter interruptions constrains manufacturing capacity.
- Triple Superphosphate:Produced via phosphoric acid reaction achieving 44-46% P₂O₅ density, reducing freight costs per unit phosphorus for long-haul distribution. Specialty crop cultivation in Brazil's Minas Gerais and São Paulo states is rebalancing procurement toward this grade as coffee and citrus growers prioritize nutrient efficiency.
- Granulated Superphosphate:Compaction and spherodizing methods create uniform particle sizes for pneumatic spreader calibration in North American agricultural cooperatives.
- Liquid Superphosphate:Suspension formulations compatible with precision fertigation systems in Dutch and Spanish greenhouse vegetable operations.
Triple Superphosphate sits at the top of the volume ranking, with Liquid Superphosphate climbing the fastest.
Application:
Margin structures vary sharply across application segments, with premium pricing concentrated in maintenance-intensive uses versus commodity-scale agricultural volumes.
- Agricultural:Dominates tonnage through cereal and oilseed production across the US Corn Belt and India's Punjab-Haryana corridor, where corn and soybean acreage expansion for biofuel feedstocks lifts phosphorus application rates.
- Horticultural:Greenhouse vegetable operations in the Netherlands and Spain adopt water-soluble formulations for drip irrigation systems, commanding price premiums over field-grade products.
- Turf Management:Golf course and sports field maintenance contracts in Florida and Arizona specify micronutrient-coated variants with documented contaminant traceability.
- Landscape:Municipal and commercial planting projects in São Paulo and Delhi metro areas generate seasonal demand spikes for rapid-establishment phosphorus sources.
Agricultural commands the largest absolute margin pool, while Turf Management delivers the highest unit profitability.
End User:
Procurement sophistication determines which superphosphate variants gain traction, with organized buyers leveraging collective purchasing power against fragmented individual demand.
- Farmers:India's e-URVARAK platform and Brazil's Agronow system aggregate individual growers into state-mandated tender portals that displace informal dealer credit with transparent cash pricing.
- Agricultural Cooperatives:North American prairie networks specify compaction-grade superphosphate for variable-rate application equipment, consolidating volume with manufacturers offering direct logistics contracts.
- Landscape Contractors:Seasonal project-based purchasing favors wholesale distributors with flexible delivery scheduling.
- Nurseries:Containerized plant production requires acidulated phosphate rock blends with controlled nutrient release profiles.
Agricultural Cooperatives anchor procurement volume, with Farmers gaining purchasing sophistication fastest through digital platform adoption.
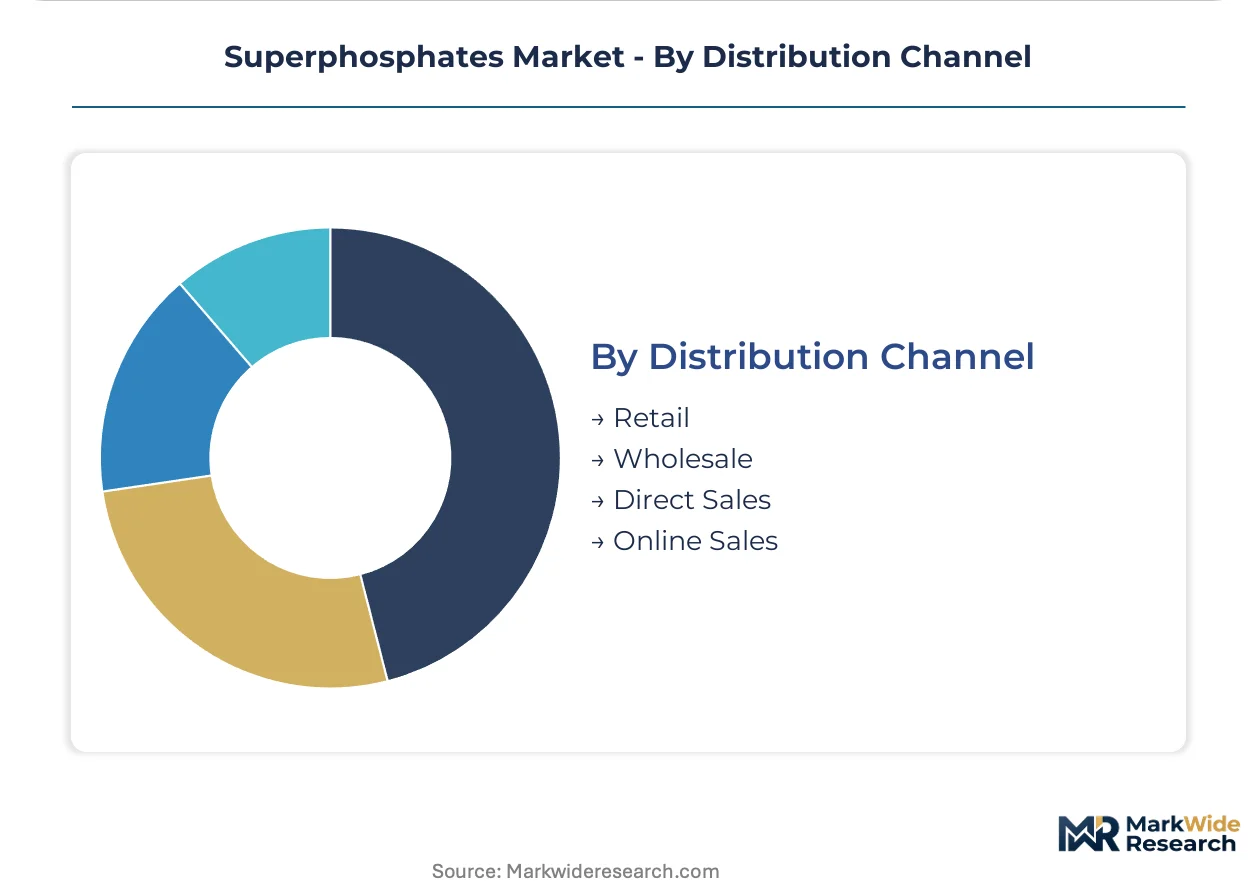
Distribution Channel:
Channel economics are restructuring as direct-to-farm platforms compress traditional distributor margins and accelerate working capital velocity.
- Retail:Rural supply stores in India's Uttar Pradesh and Madhya Pradesh maintain farmer relationships through credit extension and agronomic advisory services.
- Wholesale:Nutrien Ltd leverages its Prairie distribution network to sustain bulk volumes across North American agricultural cooperatives with integrated logistics.
- Direct Sales:OCP Group's captive mine-to-port infrastructure enables landed cost control for Asian-bound phosphate rock through long-term offtake negotiations.
- Online Sales:Cooperative purchasing apps in Punjab and Haryana bypass traditional dealer networks for certified triple superphosphate bulk orders.
Wholesale retains the largest volume share, with Online Sales expanding most quickly as procurement digitization penetrates organized farming regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting superphosphate manufacturing toward jurisdictions with lower compliance costs for cadmium and contaminant thresholds. Brazil and Russia extract phosphate rock with naturally low heavy metal content, granting their processed fertilizers preferential access to EU markets under tightening REACH protocols.
United States
Corn Belt acreage expansion for ethanol and renewable diesel feedstocks is lifting phosphorus application rates across Iowa, Illinois, and Indiana. The EPA regulates phosphate mining waste under the Clean Water Act, constraining domestic rock extraction and forcing reliance on Moroccan imports. Nutrien Ltd leverages its Prairie distribution network to consolidate wholesale volumes with North American agricultural cooperatives.
Brazil
Specialty crop cultivation in Minas Gerais and São Paulo states is rebalancing procurement toward triple superphosphate grades for coffee and citrus production. ANVISA and the national agricultural ministry oversee fertilizer registration and micronutrient additive approvals that determine which superphosphate variants gain market access. The Agronow digital platform aggregates grower demand into state-mandated tender portals.
India
State subsidy programs for micronutrient-coated variants are concentrating demand in the wheat-rice belt of Punjab and Haryana. The FSSAI and state fertilizer departments manage quality certification and subsidy eligibility that steer farmer purchasing toward certified grades. The e-URVARAK platform bypasses traditional dealer networks for bulk triple superphosphate orders.
Morocco
OCP Group dominates Maghreb export corridors with captive mine-to-port infrastructure that controls landed costs in Asian markets. Phosphate rock supply concentration in Morocco and Western Sahara is reshaping procurement security calculations for fertilizer manufacturers dependent on seaborne imports. Long-term offtake negotiations with limited supplier alternatives characterize buyer relationships.
Netherlands
Horticultural greenhouse operations in the Netherlands and neighboring Spain are adopting water-soluble superphosphate formulations for precision fertigation systems. REACH cadmium and heavy metal testing protocols force importers to document phosphate rock provenance through laboratory certification. Fertilizer blenders in Germany and Poland now reject high-cadmium cargoes from unspecified origins.
Superphosphates Market Competitive Landscape
Capacity expansion dominates the current landscape as producers retrofit legacy granulation assets and add compaction-grade lines for precision agriculture compatibility. The market structure consolidates around integrated mining-to-fertilizer conglomerates with captive phosphate rock reserves, mid-tier regional blenders dependent on imported acid, and specialty formulation houses serving protected cultivation. Three archetypes define competitive positioning: resource-backed vertical integrators controlling Atlantic and Pacific shipping lanes; distribution-anchored cooperatives with direct farm relationships; and technology-focused precision agriculture suppliers. M&A activity targets regional blending capacity, while strategic partnerships secure long-term rock offtake from Moroccan and Brazilian deposits.
Among North American integrated players, The Mosaic Company and Nutrien Ltd exemplify the resource-distribution archetype with extensive mine networks and cooperative supply contracts. Yara International ASA anchors European supply through integrated phosphate rock sourcing from Morocco and Brazil. OCP Group occupies a position as the dominant Maghreb exporter with captive infrastructure controlling Asian-bound shipment economics.
| Leading Market Players |
|---|
| The Mosaic Company |
| Nutrien Ltd |
| Yara International ASA |
| EuroChem Group |
| PhosAgro Group of Companies |
| ICL Group |
| OCP Group |
| Coromandel International Ltd |
| Innophos |
| Others |
Value Network & Pricing Analysis
Compaction-grade granulation technology adoption across North American agricultural cooperatives simultaneously compresses per-unit production costs and concentrates volume with manufacturers offering direct logistics contracts rather than distributor networks. This production-method transition reshapes margin structures by displacing traditional prilled superphosphate with broader size distributions that command lower price realizations.
Pricing Analysis
Distributor margin compression runs through the wholesale tier as cooperative purchasing apps in India's Punjab and Haryana states bypass traditional dealer networks for bulk triple superphosphate orders. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and contaminant traceability documentation. Price differentiation separates REACH-compliant low-cadmium grades from uncertified commodity cargoes. Cost compression in the standard tier intensifies because sulfuric acid feedstock volatility from copper smelter interruptions constrains single superphosphate manufacturing capacity. Smallholder farmers in India's wheat-rice belt exhibit the highest price sensitivity, while turf management contractors in Florida and Arizona demonstrate the lowest due to premium maintenance contract structures.
Supply Chain Analysis
Phosphate rock supply rests on Moroccan and Western Sahara mineable reserves, with Brazilian and Russian deposits gaining preferential access to EU markets under tightening cadmium thresholds. Wet-process phosphoric acid and sulfuric acid from copper smelters constitute critical chemical inputs. Granulation equipment and compaction machinery form the capital equipment layer. Single-source vulnerability concentrates in OCP Group's captive mine-to-port infrastructure controlling Atlantic shipping lanes for Asian-bound cargoes. Distribution runs through long-term offtake negotiations with limited supplier alternatives rather than spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Superphosphates Market functions as a stable compounder anchored by irreplaceable phosphorus demand in cereal and oilseed production systems that lack mineral fertilizer substitutes at commercial scale.
For Market Incumbents: To counter organic phosphate substitution in certified organic production, Nutrien Ltd and Yara International ASA should deepen backward integration into low-cadmium phosphate rock deposits in Brazil and Russia that secure EU market access. Capacity addition in compaction-grade lines for North American prairie cooperatives reinforces precision agriculture compatibility. For New Entrants and Emerging Players: Enter via direct-to-farm digital platforms in India's organized farming regions where the e-URVARAK portal aggregates demand into transparent tender mechanisms. Specialty formulation houses serving Dutch and Spanish greenhouse vegetable operations represent the most penetrable segment. A go-to-market angle anchored in micronutrient-coated variants with documented contaminant traceability bypasses commodity price competition. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier regional blenders dependent on imported acid rather than integrated mining-to-fertilizer conglomerates with captive reserves. Long-term viability over a multi-year horizon rests on securing phosphate rock offtake from Moroccan or Brazilian deposits before regulatory arbitrage closes. The signal to watch is EU Fertilizing Products Regulation cadmium threshold enforcement actions against unspecified-origin cargoes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Cadmium Rock Deposits | Brazilian and Russian mining assets secure preferential EU market access under REACH protocols. |
| Compaction-Grade Capacity Expansion | North American prairie cooperatives specify uniform particle sizes for variable-rate application equipment. |
| Direct-to-Farm Digital Platform Launch | India's e-URVARAK and Brazil's Agronow systems displace informal dealer credit relationships. |
| Long-term Supply Agreement with Moroccan Exporters | OCP Group's mine-to-port infrastructure controls landed costs in Asian phosphate markets. |
| Micronutrient-Coated Formulation Development | ANVISA registration and FSSAI certification unlock premium pricing in specialty crop segments. |
Research Methodology
Coverage spans North America, South America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with phosphate plant operations managers, agricultural cooperative procurement leads, fertilizer distribution channel partners, and regulatory affairs directors at major manufacturers. Secondary validation draws from customs and trade data, SEC 10-K filings, OCP Group sustainability disclosures, and EU Fertilizing Products Regulation implementation guidance. Bottom-up volume modeling triangulates against top-down macroeconomic agricultural output projections.
Rate-of-change decomposition separates volume growth from price realization effects across the projection horizon. The analytical framework models segmentation dimensions including product type, application channel, end-user procurement sophistication, and distribution channel digitization. CAGRs were derived through regression analysis of historical agricultural input intensity ratios and forward projection of biofuel-driven acreage expansion. Industry-specific forecast inputs include phosphorus balance sheets from national fertilizer associations and cadmium testing protocol adoption curves.
Inputs from regulatory filing databases and trade statistics were available through the study window; gaps in real-time farmer purchasing behavior from informal dealer networks introduce uncertainty bands around channel-shift timing. Forecasts reflect documented assumptions regarding subsidy program continuity and sulfuric acid supply stability. A small set of named triggers warrants ongoing watch: EU cadmium enforcement actions, Moroccan export corridor disruptions, and organic certification acreage thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
India Agrochemicals Market
Agrochemicals
Middle East and Africa Plant Growth Regulators Market
Agrochemicals
Australia Agrochemicals Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
South Africa Agrochemicals Market
Agrochemicals
Agrochemical Market
Agrochemicals
South America Agrochemicals Market
Agrochemicals
L-Glufosinate Ammonium Market
Agrochemicals
Canada Agrochemicals Market
Agrochemicals
Agrochemical Active Ingredients Market
Agrochemicals
Indonesia Agrochemicals Market
Agrochemicals
Mexico Agrochemicals Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
Egypt Agrochemicals Market
Agrochemicals
Potassium Humate Market