
 Canada Agrochemicals Market | 2026-2036
Canada Agrochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Agrochemicals Market Outlook
Prairie fertilizer production capacity is consolidating around a handful of nitrogen and phosphate complexes in Alberta and Saskatchewan. Nutrien Ltd anchors domestic potash supply through its Saskatchewan mine network, leveraging integrated rail and terminal assets to control export logistics. Bayer AG competes in the crop protection segment with a broad herbicide portfolio, while Corteva Agriscience specializes in seed-applied technologies that bundle traits with chemical inputs.
Canada agrochemicals comprise synthetic and biological inputs—herbicides, insecticides, fungicides, and macro- and micronutrient fertilizers—formulated to protect yield and correct soil fertility across the country's diverse agricultural zones. Active ingredients range from glyphosate and glufosinate ammonium to neonicotinoid and pyrethroid chemistries, applied at rates calibrated to crop type, pest pressure, and provincial environmental regulations. Herbicides command the largest product-type share, reflecting extensive no-till and reduced-till adoption across the Prairies that depends on chemical weed control. Fertilizers represent the fastest-growing segment by value, driven by replacement demand for urea, diammonium phosphate, and potash as growers push for higher per-acre yields in canola and corn.
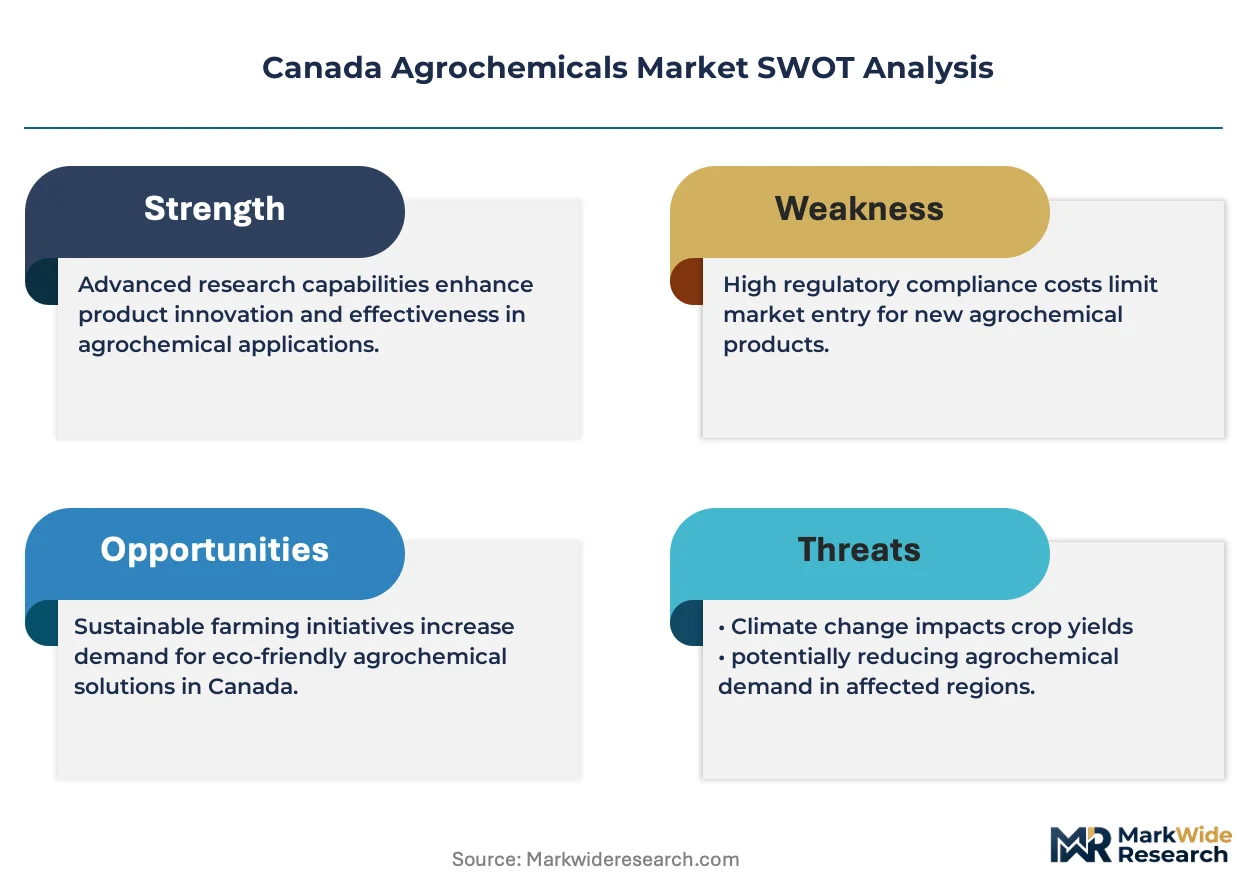
Health Canada and PMRA govern pesticide registration, maximum residue limits, and re-evaluation schedules that determine which chemistries remain available to Canadian growers. The Pest Management Regulatory Agency's accelerated timeline for neonicotinoid specialty reviews and ongoing glyphosate risk assessment reshape product portfolios, forcing distributors to source alternative modes of action. Provincial environmental farm plans and Alberta's pesticide applicator certification requirements add compliance layers that favor suppliers with robust regulatory affairs capacity. Stakeholders must monitor PMRA re-evaluation outcomes and provincial buffer-zone rules to anticipate which product lines will retain market access.
Market Dynamics
PMRA's accelerated re-evaluation schedules for neonicotinoids and glyphosate are forcing manufacturers to rebuild product portfolios around biopesticide alternatives while Prairie growers absorb higher compliance costs.
Growth Catalysts
- Health Canada neonicotinoid specialty reviews:The expedited regulatory timeline compresses product development cycles and opens registration windows for novel biological actives that bypass legacy chemistries.
- Prairie canola-wheat rotation expansion:Saskatchewan and Alberta growers are intensifying herbicide and fertilizer application rates to maximize per-acre yields on expanded acreage.
- No-till adoption:Reduced-till farming systems across the Prairies depend on glyphosate-based weed control, sustaining demand for herbicide formulations despite regulatory headwinds.
Market Restraints
- Natural gas feedstock volatility:Nitrogen fertilizer production costs fluctuate with Alberta natural gas benchmarks, compressing margins for domestic urea and ammonia manufacturers.
- Saskatchewan potash concentration:Nutrien Ltd's integrated mine-rail-terminal network controls export logistics, limiting price competition for domestic fertilizer buyers.
- Buffer-zone compliance burden:Provincial environmental farm plans and Alberta pesticide applicator certification add operational friction that smaller distributors struggle to absorb.
Strategic Opportunities
- Manitoba specialty crop expansion:Potato and vegetable growers in the Red River Valley represent underpenetrated demand for precision fungicide and micronutrient formulations.
- Seed-applied biologicals convergence:Microbial inoculant technology bundled with traited seed creates new input categories that bypass traditional spray application channels.
- Alberta carbon credit frameworks:Provincial agricultural carbon offset protocols incentivize reduced synthetic nitrogen use, opening markets for enhanced-efficiency fertilizers and nitrification inhibitors.
Industry Challenges
- Regulatory affairs talent scarcity:PMRA submission requirements and provincial buffer-zone calculations demand specialized expertise that mid-size distributors cannot retain in-house.
- Legacy inventory reconfiguration:Distributors must liquidate chemistries facing PMRA non-renewal while building biopesticide supply chains with shorter shelf lives and colder storage requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Agrochemicals Market |
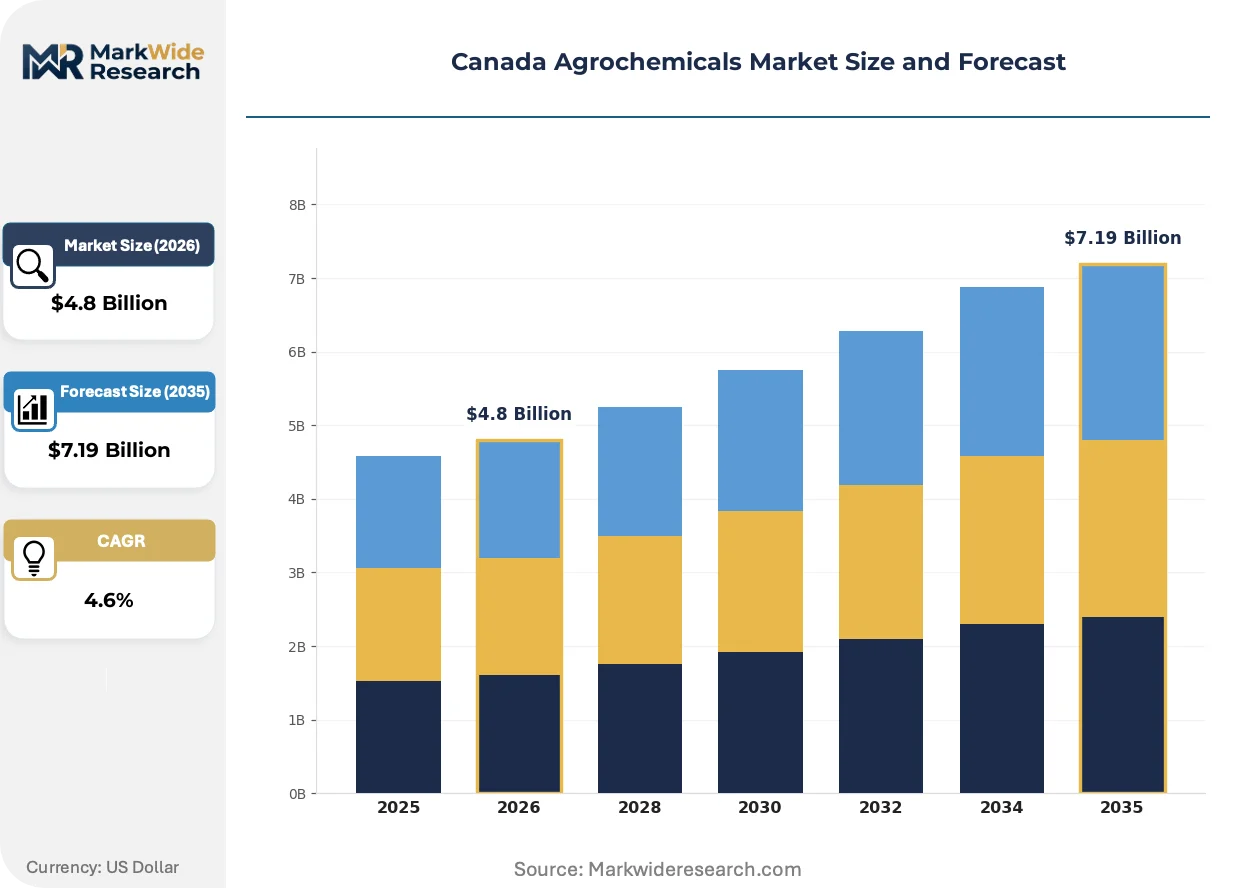
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Fertilizers Application: Crops, Pastures, Lawns, Gardens End User: Farmers, Agricultural Cooperatives, Distributors, Retailers Distribution Channel: Wholesale, Retail, Direct Sales, Online |
| Companies Covered | Nutrien Ltd, Bayer AG, Syngenta Group, BASF SE, Corteva Agriscience, CF Industries Holdings Inc., Dow Inc., DuPont de Nemours Inc., UPL Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Agrochemicals Market Strategic Shifts
Biological input formulations and precision application hardware are compressing the traditional synthetic-chemical product lifecycle while reshaping how Prairie growers purchase and deploy crop protection.
RNA interference pesticides targeting specific pest genomes are decentralizing research and development away from multinational discovery pipelines toward specialized biotechnology firms and university partnerships. Saskatchewan canola growers are piloting foliar-applied RNAi formulations for flea beetle control at commercial scale. This technology is decentralizing market power from broad-spectrum chemistry patent holders toward platform-agnostic biological input suppliers.
Health Canada and PMRA's consolidated pesticide risk assessment framework is compressing registration timelines for biopesticides while extending review periods for conventional chemistries. The policy shift favors microbial and biochemical actives that qualify for expedited regulatory pathways. Prairie herbicide distributors are reallocating technical service resources toward biological product support and grower education.
Direct-to-farm digital procurement platforms are fragmenting traditional ag-retailer relationships as Alberta and Saskatchewan growers compare real-time pricing and bundle crop protection with agronomic advisory subscriptions. Younger farm operators in the Red River Valley are bypassing local co-ops for manufacturer-direct loyalty programs with embedded precision agriculture tools. This channel shift is most visible in canola-growing regions where input cost transparency has become a competitive priority.
Canada Agrochemicals Market Segmentation
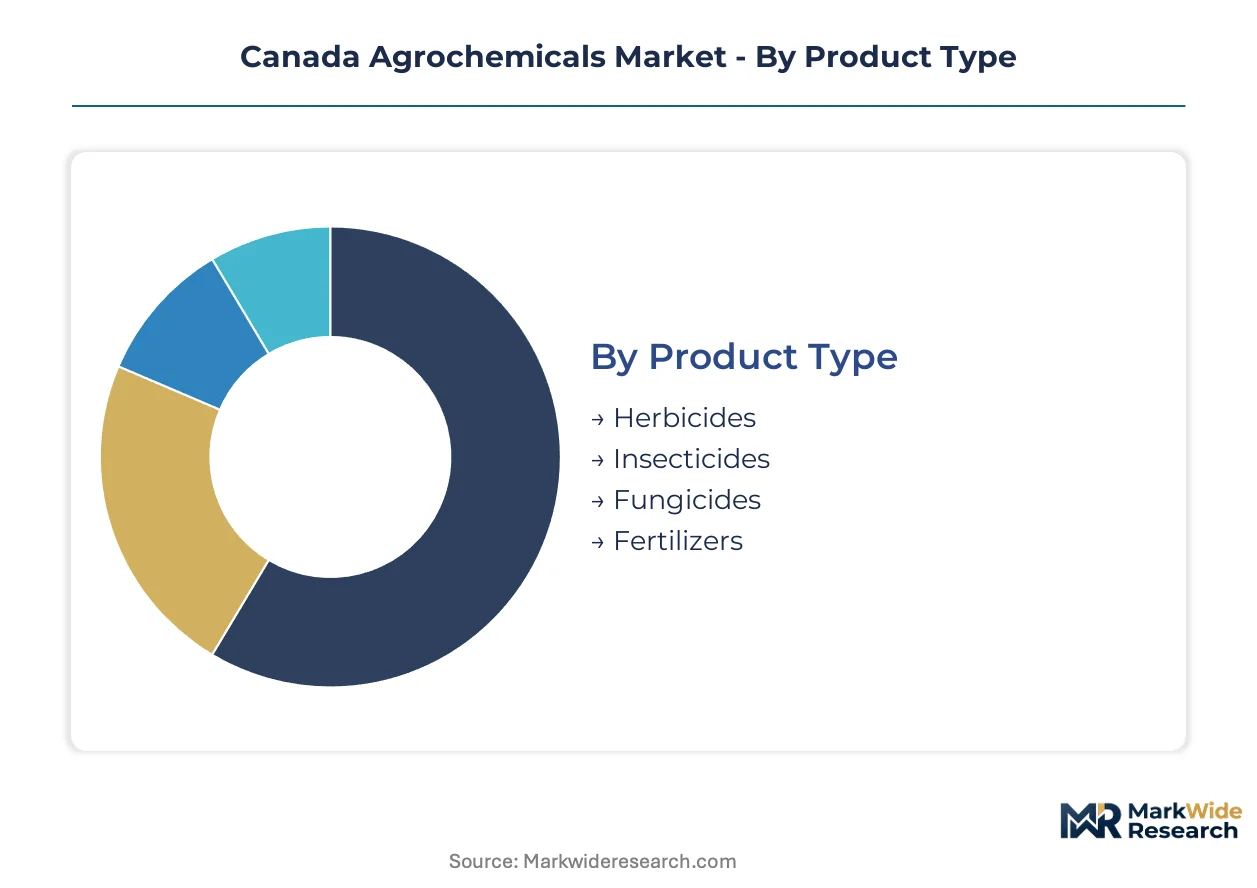
Canada agrochemicals segmentation reflects distinct capital requirements across product categories, with fertilizer manufacturing demanding billion-dollar facility investments while distribution channels operate on working-capital intensity. Understanding these structural differences clarifies where margin pools concentrate and which segments attract integrated players versus specialized entrants.
Product Type:
Fertilizer production anchors the highest capital intensity, with nitrogen complexes requiring integrated natural gas pipelines and ammonia synthesis trains. Herbicide formulation demands intermediate chemical processing infrastructure, while biological inputs need fermentation capacity rather than heavy industrial assets.
- Herbicides:Glyphosate, glufosinate ammonium, and 2,4-D formulations dominate Prairie no-till systems. Saskatchewan and Alberta canola-wheat rotations absorb the majority of national volume as growers combat herbicide-resistant kochia and wild oat populations. Health Canada PMRA re-evaluations are compressing registration timelines for legacy chemistries while opening pathways for bioherbicide alternatives.
- Fertilizers:Nitrogen (urea, anhydrous ammonia), phosphate (diammonium phosphate), and potash (muriate of potash) correct soil fertility across commercial grain operations. Nutrien Ltd's Saskatchewan potash mine network and Alberta nitrogen complexes supply domestic demand while commanding export logistics through captive rail and terminal infrastructure. Alberta carbon credit frameworks are accelerating demand for enhanced-efficiency formulations and nitrification inhibitors.
- Insecticides:Neonicotinoid, pyrethroid, and organophosphate chemistries target flea beetles in canola and wireworms in cereals. PMRA's accelerated specialty reviews for neonicotinoids are forcing portfolio pivots toward microbial and biochemical alternatives with shorter regulatory pathways.
- Fungicides:Azole, strobilurin, and SDHI formulations protect against sclerotinia in canola and fusarium in wheat. Manitoba Red River Valley potato and vegetable growers represent concentrated demand for precision fungicide applications.
Most installed capacity flows through Fertilizers. Expansion is steepest in biological input categories bypassing PMRA's extended conventional chemistry review timelines.
Application:
Volume concentration varies sharply by application, with commercial crop production commanding tank-mix volumes that pasture and amenity segments cannot match. Regulatory scrutiny intensifies proportionally with scale, concentrating compliance burden on crop-focused distributors.
- Crops:Canola, wheat, corn, and soybean production across the Prairie provinces accounts for the dominant share of agrochemical throughput. Saskatchewan and Alberta growers apply inputs at rates calibrated to yield targets, pest pressure maps, and provincial environmental farm plan requirements. Direct-to-farm digital procurement platforms are fragmenting traditional retailer relationships in this segment.
- Pastures:Forage and rangeland applications target weed control in beef cattle operations concentrated in Alberta and British Columbia interior valleys. Lower application frequency and smaller parcel sizes limit formulation customization.
- Lawns:Turf management in urban centers and golf course operations drives demand for selective herbicides and micronutrient packages. Municipal pesticide bylaws in Vancouver and Toronto restrict product availability.
- Gardens:Residential and small-scale horticultural applications represent fragmented demand served through retail garden centers and mass-market channels. Biopesticide penetration is highest here due to consumer preference and regulatory exemptions.
Revenue concentrates in Crops. Biological alternatives are gaining share fastest in Gardens amid municipal restrictions and consumer preference shifts.
End User:
Procurement sophistication separates end-user segments, with large cooperatives negotiating manufacturer-direct contracts while smaller retailers depend on distributor markup layers. Technical service requirements scale with farm size and input complexity.
- Farmers:Prairie grain operations with 2,000+ acre footprints purchase inputs through loyalty programs bundling seed, crop protection, and precision agriculture tools. Younger operators in the Red River Valley are bypassing local co-ops for manufacturer-direct digital platforms.
- Agricultural Cooperatives:Saskatchewan and Alberta grain cooperatives aggregate member demand to negotiate volume discounts and technical service packages. These entities are building in-house regulatory affairs capacity to navigate PMRA submission requirements.
- Distributors:Regional input suppliers manage inventory across multiple manufacturer lines while providing agronomic advisory and application services. Smaller distributors struggle to absorb provincial buffer-zone compliance burdens and biopesticide cold-chain investments.
- Retailers:Farm supply stores and garden centers serve amenity and small-scale agricultural customers with limited technical support. Online channels are compressing margins in this segment.
Input volume flows predominantly through Farmers. Procurement digitization is advancing most quickly among younger farm operators in Alberta and Manitoba.
Distribution Channel:
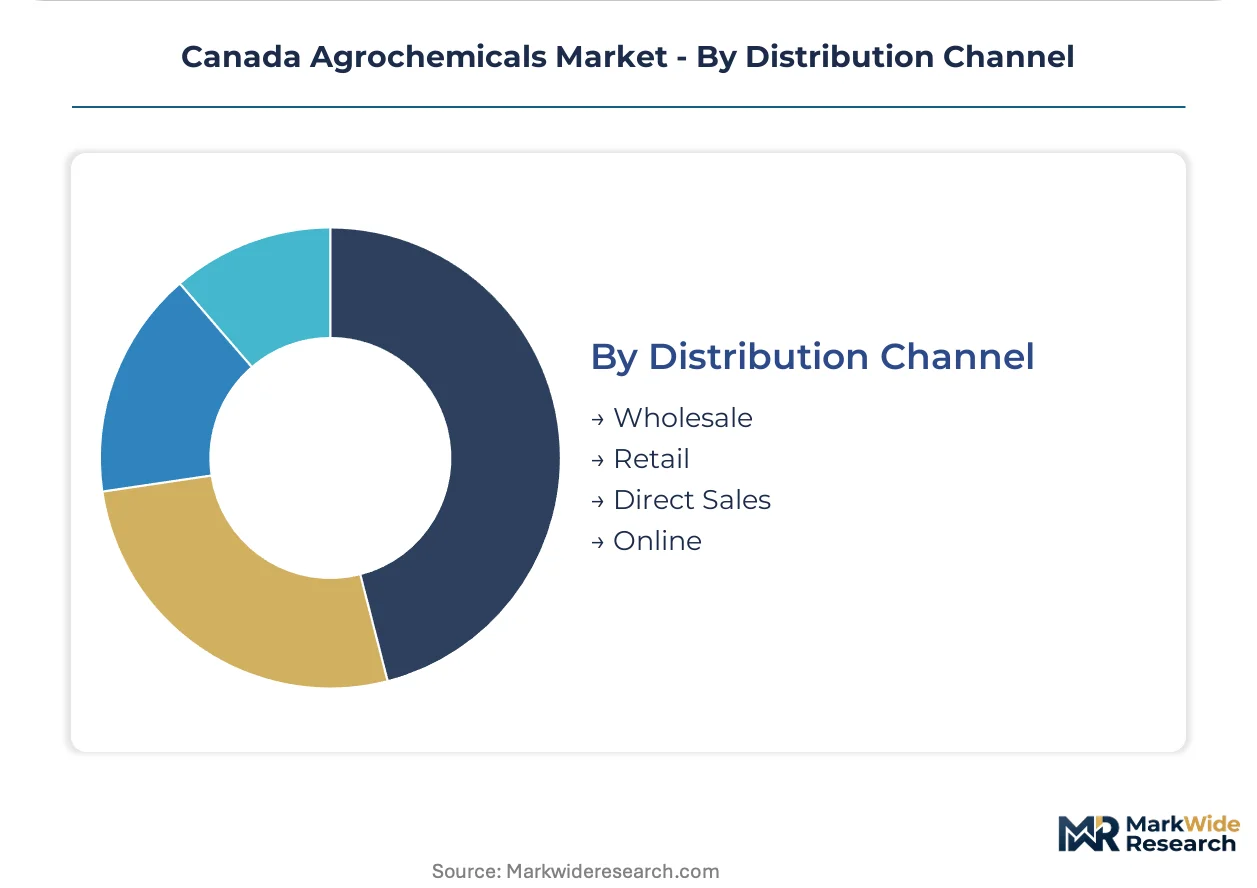
Channel economics reflect working-capital intensity and customer touchpoint requirements, with wholesale operations financing inventory seasons while direct sales demand embedded agronomic expertise.
- Wholesale:Bulk fertilizer and crop protection volume moves through distributor networks serving retail and cooperative accounts. Nutrien Ltd's integrated logistics control Prairie wholesale pricing for potash and nitrogen.
- Retail:Branded farm supply locations combine product sales with application equipment and seasonal credit programs. Traditional co-op relationships are fragmenting as growers compare real-time pricing across channels.
- Direct Sales:Manufacturers bypass intermediaries to serve large farm operations and cooperatives through loyalty programs with embedded precision agriculture subscriptions. Bayer AG and Corteva Agriscience are expanding direct technical service teams.
- Online:Digital procurement platforms enable price transparency and bundle crop protection with agronomic advisory subscriptions. Adoption concentrates among canola-growing regions where input cost transparency has become competitive priority.
Volume concentration remains in Wholesale. Channel shift is most pronounced toward Direct Sales as manufacturers build embedded service capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's agrochemical demand concentrates in the Prairie provinces while Ontario and Quebec sustain distinct specialty crop markets. Provincial regulatory frameworks and soil conditions create sharply differentiated input requirements across these agricultural zones.
Prairie Provinces
Saskatchewan and Alberta drive national herbicide and fertilizer volume through expanded canola-wheat rotations on large-scale commercial operations. PMRA's neonicotinoid specialty reviews force Prairie growers toward alternative chemistries with higher per-acre costs. The Red River Valley and Edmonton-Calgary corridor anchor distribution networks serving 2,000+ acre grain farms.
Ontario
Corn-soybean rotations in southwestern Ontario sustain steady demand for glyphosate-based weed control and nitrogen stabilization products. The province's environmental farm plan requirements impose buffer-zone compliance costs that favor distributors with dedicated regulatory staff. The Guelph-Waterloo agricultural technology cluster supports precision application equipment development for regional growers.
Quebec
Dairy forage and specialty vegetable production in the Saint Lawrence Valley generates concentrated demand for fungicides and micronutrient formulations. Municipal pesticide bylaws in Montreal and Quebec City restrict urban lawn care products while pushing biopesticide penetration in peri-urban horticulture. The province's agro-environmental clubs coordinate collective input purchasing for smaller livestock operations.
British Columbia
Fraser Valley berry and greenhouse operations command premium-priced biological inputs and precision irrigation-chemigation systems. The province's integrated pest management certification program for wine grape growers mandates reduced synthetic pesticide schedules. Vancouver's municipal pesticide restrictions have eliminated conventional lawn care products from urban retail channels.
Atlantic Canada
Potato production in Prince Edward Island and New Brunswick sustains localized fungicide demand for late blight management. Smaller farm scale limits formulation customization while maritime climate conditions compress application windows. Provincial soil conservation programs subsidize cover crop adoption that reduces synthetic nitrogen requirements.
Canada Agrochemicals Market Competitive Environment
Saskatchewan-based producers anchor one tier; multinational specialists with Canadian formulation facilities hold another. The market structures around integrated fertilizer manufacturers with captive mineral reserves, global crop protection firms with broad chemistry portfolios, and regional distributors with embedded agronomic services. Two strategic archetypes dominate: vertically integrated nutrient suppliers controlling mine-to-farm logistics, and technology bundlers combining seed traits with chemical inputs. Competitive moves concentrate on regulatory affairs capacity building and direct-to-farm digital channel development.
Within the integrated nutrient tier, Nutrien Ltd exemplifies the mine-rail-terminal model through its Saskatchewan potash network. Bayer AG and Corteva Agriscience occupy positions as technology bundlers, with the former representing broad-spectrum chemistry portfolios and the latter anchoring seed-applied input convergence. These three entities illustrate how scale and regulatory sophistication separate market participants.
| Leading Market Players |
|---|
| Nutrien Ltd |
| Bayer AG |
| Syngenta Group |
| BASF SE |
| Corteva Agriscience |
| CF Industries Holdings Inc. |
| Dow Inc. |
| DuPont de Nemours Inc. |
| UPL Ltd |
| Others |
Value Chain & Pricing Dynamics
Regulatory affairs specialists concentrated in Ottawa-Gatineau and Saskatoon drive labor-cost differentials that widen pricing spreads between premium biopesticide formulations and commodity synthetic chemistries. Prairie distributors absorbing Health Canada PMRA compliance burdens pass elevated technical-service costs downstream, fragmenting procurement budgets across tiered input categories.
Pricing Analysis
Capacity additions in Alberta nitrogen complexes are reshaping price floors for urea and anhydrous ammonia while Nutrien Ltd's captive potash rail network sustains premium-mid-economy pricing differentiation across Prairie fertilizer markets. Price differentiation hinges on enhanced-efficiency coating technologies and carbon-credit eligibility under provincial offset protocols. Pricing pressure stems from natural gas feedstock volatility compressing margins at Alberta ammonia synthesis facilities. Large-scale Saskatchewan grain cooperatives exhibit lowest price sensitivity due to volume-negotiated contracts, while Manitoba specialty vegetable growers face acute cost compression from precision fungicide requirements.
Supply Chain Analysis
Domestic-content mandates under Health Canada PMRA registration pathways are reshaping sourcing toward Saskatchewan potash mines and Alberta nitrogen complexes rather than offshore urea suppliers. Geographic supply concentration centers on Canada, the United States, and Trinidad and Tobago for ammonia feedstock. Raw material dependencies include Alberta natural gas, Saskatchewan potash ore, and imported phosphate rock from Florida and Morocco. Single-source vulnerability runs through Nutrien Ltd's integrated mine-rail-terminal network controlling Prairie export logistics. Distribution runs through wholesale fertilizer terminals serving retail cooperatives and direct manufacturer-to-farm loyalty programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada agrochemicals function as a geographic-arbitrage play: Saskatchewan's integrated potash rail infrastructure offers cost advantages unavailable to US Corn Belt competitors facing higher inland logistics expenses.
For Market Incumbents: Deepen backward integration into Saskatchewan potash mining and Alberta nitrogen synthesis to defend margin position against biopesticide entrants exploiting PMRA expedited registration pathways. Anchor capacity control through captive rail and terminal assets that limit price competition. Prioritize regulatory affairs talent retention in Ottawa to navigate neonicotinoid re-evaluation timelines. For New Entrants and Emerging Players: Launch via direct-to-farm digital platforms targeting Manitoba Red River Valley potato and vegetable growers, the most penetrable segment for precision fungicide and micronutrient formulations. White-space targets include seed-applied biologicals bundled with traited seed and nitrification inhibitors qualifying for Alberta carbon credit protocols. Bypass traditional cooperative channels through manufacturer-direct loyalty programs with embedded agronomic subscriptions. For Investors and Strategic Acquirers: Integrated fertilizer manufacturers with captive mineral reserves are the most active acquirer in this space, consolidating Prairie wholesale networks to secure mine-to-farm logistics control. Long-term viability frames around biopesticide portfolio pivots and carbon-credit-linked input categories. The signal to watch is PMRA re-evaluation outcomes determining which legacy chemistries retain market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potash Mining | Nutrien Ltd's Saskatchewan mine network secures captive supply for domestic and export markets. |
| Biopesticide Registration Acceleration | PMRA expedited pathways favor microbial actives displacing neonicotinoid chemistries under review. |
| Direct-to-Farm Digital Platform Launch | Bayer AG and Corteva Agriscience bypass co-ops to capture Alberta canola grower loyalty. |
| Carbon-Credit-Linked Fertilizer Formulation | Alberta offset protocols incentivize enhanced-efficiency nitrogen and nitrification inhibitors. |
| Regulatory Affairs Capacity Buildout | Distributors invest in Ottawa-based PMRA submission expertise to navigate buffer-zone compliance. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Saskatchewan grain cooperative procurement managers, Alberta fertilizer plant operators, Health Canada PMRA regulatory affairs leads, Manitoba potato grower association representatives, and Corteva Agriscience seed technology directors with secondary validation against PMRA pesticide registration databases, Statistics Canada agricultural input surveys, Nutrien Ltd SEC 10-K disclosures, and Prairie provincial environmental farm plan records. Bottom-up volume estimates from crop-acreage application rates triangulated against top-down manufacturer shipment data.
Segment-weighting approaches distributed value across product type, application, end user, and distribution channel dimensions, with additional granularity for provincial regulatory cluster effects. CAGRs derived from trend extrapolation of input intensity per acre, crop rotation expansion patterns, and biopesticide penetration curves across the projection horizon. Industry-specific forecast inputs included PMRA re-evaluation timelines and Alberta carbon credit protocol adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated neonicotinoid phase-out schedules or sustained natural gas price spikes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
India Agrochemicals Market
Agrochemicals
Superphosphates Market
Agrochemicals
Agrochemical Market
Agrochemicals
Global Buprofezin Market
Agrochemicals
Egypt Agrochemicals Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
Indonesia Agrochemicals Market
Agrochemicals
South America Agrochemicals Market
Agrochemicals
Middle East and Africa Plant Growth Regulators Market
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
L-Glufosinate Ammonium Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
Australia Agrochemicals Market
Agrochemicals
Africa Agrochemicals Market
Agrochemicals
Mexico Agrochemicals Market
Agrochemicals
Agrochemical Active Ingredients Market