
 Global Glufosinate Market | 2026-2036
Global Glufosinate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glufosinate Market Foresight
Soybean cultivation is consolidating as the dominant end-use vertical for glufosinate applications, displacing traditional cereal crop reliance in key growing regions. BASF SE leverages its LibertyLink seed-trait platform to sustain captive demand for its proprietary glufosinate formulations across North and South American markets. Bayer AG anchors its competitive stance through deep R&D investment in resistance-management protocols, while Nufarm Limited specializes in generic formulation supply across Asia-Pacific distribution networks.
Glufosinate is a broad-spectrum, non-selective phosphinic acid herbicide synthesized through a multi-step Strecker reaction pathway, typically formulated as ammonium salt with aqueous solubility exceeding 1.3 kg per liter at standard temperature. It inhibits glutamine synthetase enzyme activity, causing rapid ammonia accumulation and plant tissue necrosis within three to five days of foliar application. Formulated herbicides command the largest value share due to farmer preference for ready-to-apply solutions, though bio-enhanced variants represent the fastest-expanding category as biological adjuvant integration gains traction among sustainability-focused agricultural cooperatives. Water-dispersible granule formats occupy a niche but growing position where storage stability and reduced packaging weight offset higher per-unit formulation costs.
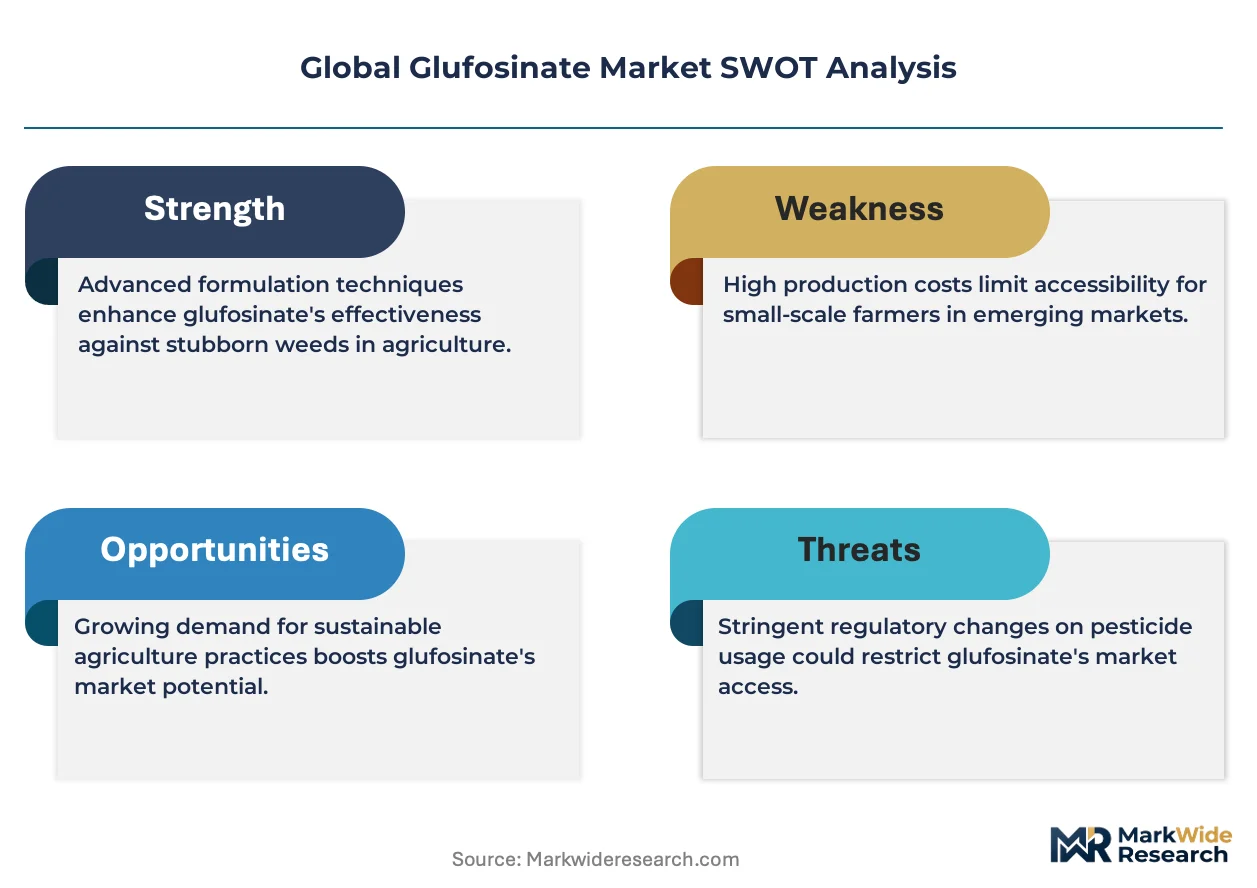
EPA re-registration requirements under the Federal Insecticide, Fungicide, and Rodenticide Act impose escalating toxicological and ecological risk benchmarks on glufosinate manufacturers seeking continued U.S. market access. EFSA and ECHA evaluations under REACH and EU Green Deal pesticide reduction targets are constraining formulation approvals across European member states, redirecting supplier focus toward jurisdictions with less restrictive hazard classification thresholds. China's NMPA and Ministry of Agriculture enforce GB standard compliance for domestic production and import registration, creating divergent compliance burdens for multinational suppliers operating across regulatory regimes. Stakeholders must monitor evolving resistance-weed population dynamics and trait-stacking patent expirations to anticipate shifts in herbicide-tolerant crop adoption curves.
Market Dynamics
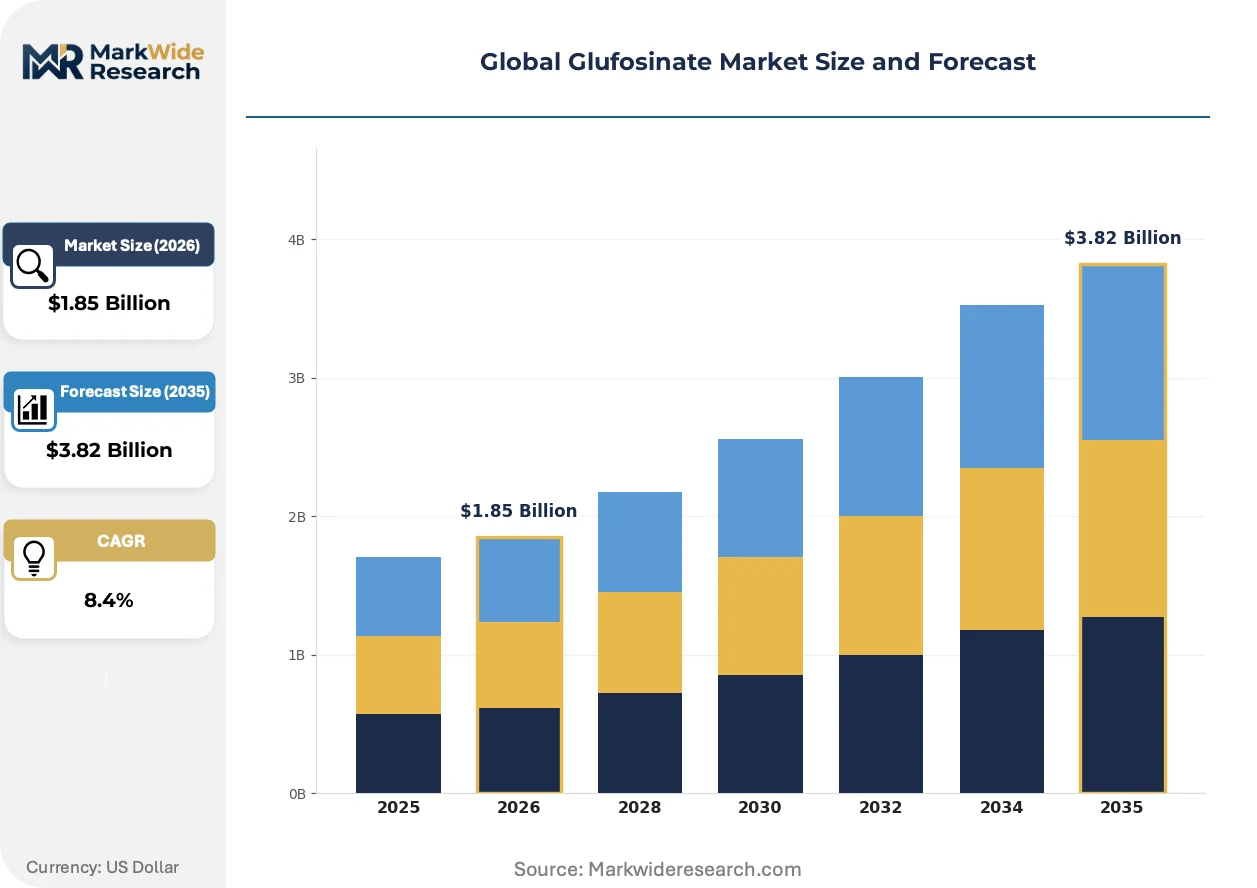
EPA re-registration reviews and EU F-Gas Regulation compliance are compressing formulation approval timelines while trait-stacking patent expirations unlock generic participation in herbicide-tolerant seed systems.
Growth Catalysts
- Herbicide-tolerant soybean expansion:Farmers across Brazil's Cerrado and the U.S. Corn Belt are converting marginal pasture to soybean cultivation, creating anchored demand for glufosinate-based weed control protocols.
- REACH and GB standard harmonization:Regulatory alignment between EU and Chinese technical barriers is streamlining multi-jurisdictional product registrations for suppliers with established toxicological dossiers.
- Resistance-management protocols:Integrated weed management mandates from agricultural extension services in Argentina and Canada are diversifying herbicide rotations beyond glyphosate-dominant programs.
Market Restraints
- Strecker synthesis input volatility:Phosphorus trichloride and acetonitrile feedstock costs fluctuate with Chinese industrial policy and energy pricing, compressing margin stability for non-integrated formulators.
- European formulation approval contraction:EFSA hazard classification upgrades under EU Green Deal pesticide reduction targets are eliminating product labels across member states, forcing portfolio rationalization.
- Biological herbicide substitution:Bioherbicide platforms derived from microbial phytotoxins are capturing organic-certified acreage in California and Italy, constraining glufosinate's addressable market expansion.
Strategic Opportunities
- Underpenetrated Australian broadacre:Canola and pulse crop expansion in Western Australia's wheatbelt offers untapped volume potential for glufosinate-tolerant trait introductions.
- Water-dispersible granule format adoption:Storage stability and reduced packaging weight advantages are penetrating Japanese rice cooperative procurement specifications.
- India PLI scheme alignment:Domestic agrochemical manufacturing incentives under the Production Linked Incentive framework enable tariff-advantaged supply to Southeast Asian export markets.
Industry Challenges
- Resistance-weed population monitoring:Field-level detection of Amaranthus palmeri and Conyza canadensis biotypes with metabolic resistance requires continuous surveillance infrastructure investment.
- Multi-jurisdictional registration synchronization:Divergent data requirements between EPA 40 CFR Part 158 and NMPA GB standards extend product launch timelines and duplicate study costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glufosinate Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical-Grade Glufosinate, Formulated Herbicides, Bio-Enhanced Variants, Water-Dispersible Granules, Others Crop Type: Corn, Soybean, Wheat, Canola, Cotton, Sugar Beet Application Method: Foliar Spray, Soil Treatment, Aerial Application, Seed Treatment End User: Contract Farmers, Agricultural Cooperatives, Crop Consultants, Seed Producers, Custom Applicators |
| Companies Covered | BASF SE, Bayer AG, Syngenta AG, Corteva Agriscience, UPL Limited, Nufarm Limited, Lier Chemical Co. Ltd., DuPont de Nemours Inc., Jiangsu Sevencontinent Green Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glufosinate Market Shifts & Advancements
Bio-enhanced adjuvant integration and precision application hardware are compressing per-hectare chemical load requirements while sustaining efficacy benchmarks.
Water-dispersible granule formulations are consolidating technical adoption among sustainability-focused agricultural cooperatives in Germany and the Netherlands. These solid-phase products eliminate solvent-based shipping hazards and reduce packaging mass by over sixty percent versus emulsifiable concentrates. Cooperative procurement committees are consolidating specification requirements around granule stability under tropical storage conditions.
EPA re-registration requirements under FIFRA Section 3 are compressing the allowable toxicological endpoint range for ecological risk assessments. Manufacturers must submit updated amphibian and pollinator exposure studies to retain existing product registrations. Formulators with captive toxicology facilities are consolidating registration maintenance advantages over generic competitors dependent on contract research organizations.
Farmer purchasing through direct-to-farm digital platforms is consolidating volume away from traditional agricultural retail cooperatives. Brazilian soybean producers in Mato Grosso are aggregating input orders through mobile-enabled procurement networks that bypass distributor markups. Platform-enabled price transparency is compressing regional price dispersion and accelerating switching behavior between generic and proprietary formulations.
Global Glufosinate Market Segmentation
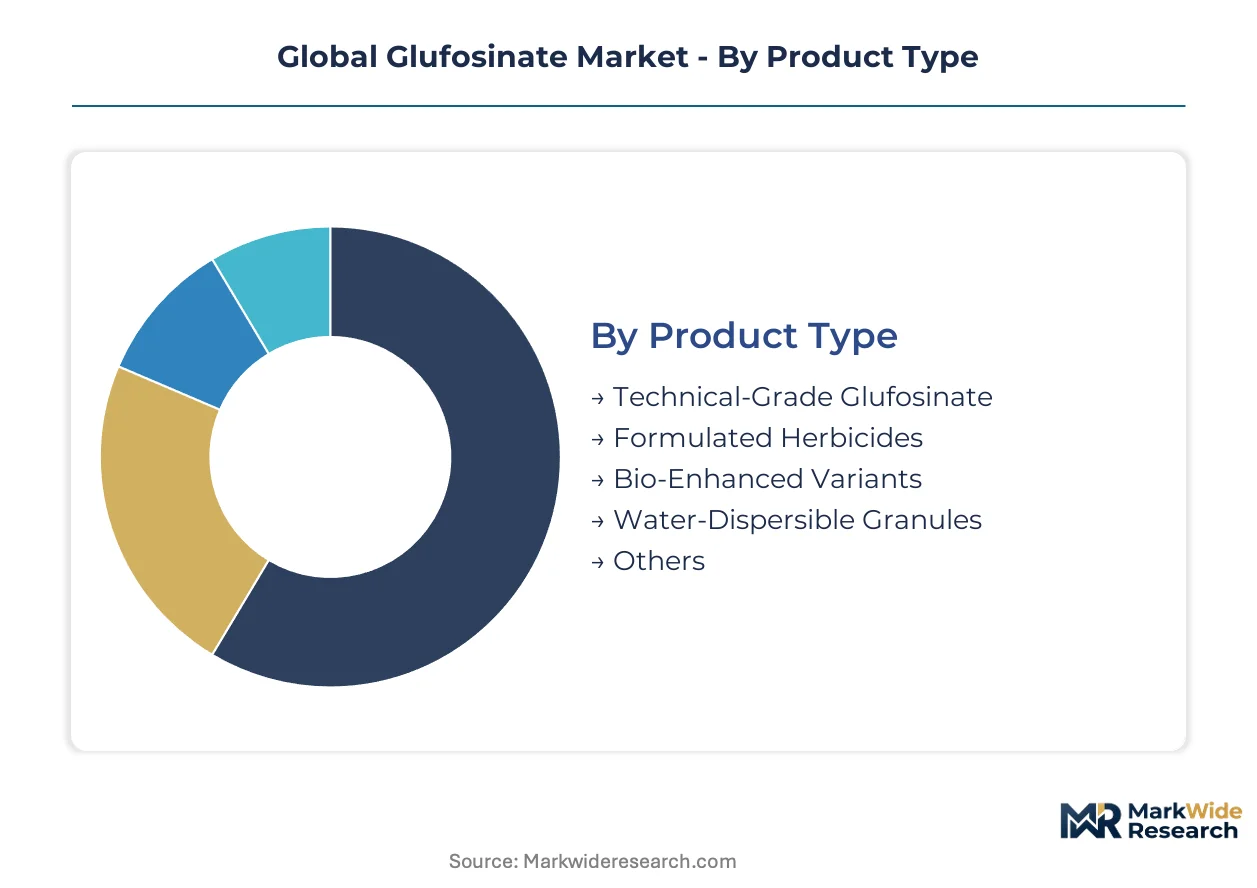
Glufosinate procurement patterns diverge sharply across formulation chemistry, crop biology, and operator scale, requiring suppliers to maintain parallel production lines and registration portfolios. Segmentation reveals where margin pools concentrate and which technical specifications command price premiums.
Product Type:
Supply concentration tilts toward formulators with captive technical-grade production or long-term offtake agreements with phosphorus trichloride suppliers.
- Technical-Grade Glufosinate:The purified ammonium salt intermediate, typically 95% minimum purity, serves as the feedstock for downstream formulation. Chinese manufacturers in Jiangsu and Shandong provinces dominate merchant supply, with BASF retaining captive production for its LibertyLink system.
- Formulated Herbicides:Ready-to-apply aqueous solutions containing 200-280 g/L glufosinate-ammonium command the largest value share. Brazilian soybean growers in Mato Grosso and Goiás specify these formulations for burndown and in-crop applications, prioritizing tank-mix compatibility with residual herbicides.
- Bio-Enhanced Variants:Microbial adjuvant integration accelerates plant uptake and reduces application rates.
- Water-Dispersible Granules:Solid-phase formulations with 50% active ingredient load reduce packaging mass and shipping costs.
- Others:Experimental nano-emulsion and controlled-release formats remain pre-commercial.
Formulated herbicides absorb the bulk of installed capacity; bio-enhanced variants are expanding most quickly.
Crop Type:
Trait licensing agreements determine which crops anchor volume, with patent expirations gradually democratizing access.
- Soybean:Herbicide-tolerant varieties now dominate plantings across Brazil's Cerrado and the U.S. Corn Belt. Glufosinate provides the critical alternative mode-of-action for managing glyphosate-resistant Amaranthus and Conyza populations in these intensive systems.
- Corn:Stacked-trait hybrids incorporating glufosinate tolerance are displacing conventional programs in Argentina's Pampas region. Farmers value the flexibility for pre-plant burndown and post-emergence rescue treatments when atrazine restrictions tighten.
- Wheat:Limited trait penetration constrains adoption to desiccation and pre-harvest weed control in specific jurisdictions.
- Canola:Australian and Canadian growers specify glufosinate-tolerant varieties for blackleg management rotations.
- Cotton:U.S. Mid-South and Australian irrigated systems utilize traited varieties for Palmer amaranth control.
- Sugar Beet:European beet growers deploy glufosinate under strict EFSA-mandated buffer zones for volunteer potato suppression.
Soybean absorbs the bulk of installed capacity; canola is climbing the fastest as Australian plantings expand.
Application Method:
Equipment infrastructure and labor availability shape method selection, with aerial platforms gaining traction where ground access is seasonal.
- Foliar Spray:Ground-based boom sprayers remain the dominant delivery platform. Brazilian contract applicators in Mato Grosso operate self-propelled machines with 36-meter booms and pulse-width modulation nozzles to optimize coverage and minimize drift.
- Aerial Application:Fixed-wing and rotorcraft platforms service the U.S. Southern Plains and Australian wheatbelt where wet seasons restrict field access. Load volumes and buffer requirements limit this method to extensive operations.
- Soil Treatment:Pre-plant incorporation delivers residual activity against emerging weeds.
- Seed Treatment:Micro-dose coatings provide early-season protection in specific canola and cotton systems.
Foliar spray absorbs the bulk of installed capacity; aerial application is gaining share fastest in flood-prone geographies.
End User:
Purchasing scale and technical sophistication determine formulation preferences and price elasticity across the customer base.
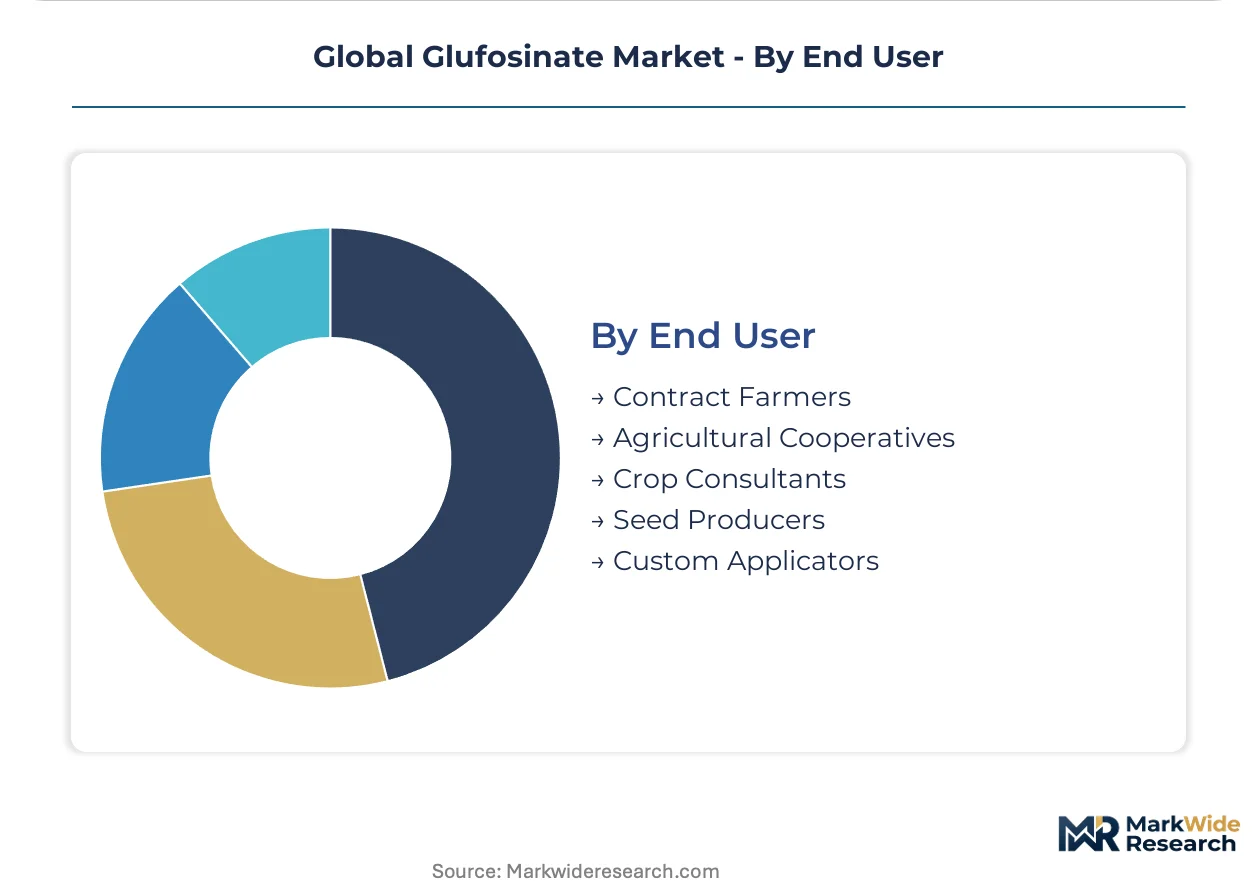
- Agricultural Cooperatives:These consolidated buyers in Germany, the Netherlands, and Japan's Hokkaido rice belt negotiate annual supply contracts with specification requirements for granule stability and packaging sustainability. Their procurement committees increasingly mandate bio-enhanced formulations.
- Contract Farmers:Tenant operators in Brazil's MATOPIBA frontier and Ukraine's black-soil belt purchase through input financing programs tied to grain traders. Price transparency from digital platforms compresses their switching costs between generic and proprietary brands.
- Seed Producers:Trait licensees require guaranteed herbicide supply for stewardship programs.
- Crop Consultants:Independent agronomists in Argentina and Canada specify programs but rarely purchase directly.
- Custom Applicators:Professional spray contractors in the U.S. Corn Belt carry inventory for immediate deployment.
Agricultural cooperatives absorb the bulk of installed capacity; contract farmers are expanding most quickly as leased acreage concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Chinese chemical manufacturing clusters while consumption anchors in Brazilian and U.S. agricultural belts. Manufacturers navigate divergent regulatory regimes across EPA, EFSA, and NMPA jurisdictions. Trait licensing agreements shape demand geography more than raw production location.
United States
Herbicide-tolerant soybean and corn plantings across Iowa, Illinois, and Indiana drive formulation consumption. EPA re-registration under FIFRA Section 3 mandates updated amphibian and pollinator exposure studies. The Corn Belt's custom applicator networks in Iowa and Illinois consolidate procurement through digital platforms.
Brazil
Soybean expansion across Mato Grosso and Goiás in the Cerrado biome anchors regional volume. ANVISA pesticide registration requirements align with OECD test guidelines for toxicological dossiers. Grain traders in Rondonópolis and Sorriso bundle glufosinate into input financing packages for tenant operators.
China
Jiangsu and Shandong provinces host technical-grade manufacturing clusters supplying global formulators. NMPA and Ministry of Agriculture enforce GB standard compliance for domestic production and export registration. Lianyungang chemical industrial parks face escalating environmental inspections under dual carbon policy implementation.
Germany
Agricultural cooperatives in Lower Saxony and Bavaria specify water-dispersible granule formats for storage efficiency. EFSA hazard classification upgrades under EU Green Deal targets eliminate conventional formulation labels. BASF's Ludwigshafen headquarters coordinates LibertyLink trait stewardship programs across European markets.
Australia
Canola expansion in Western Australia's wheatbelt creates untapped volume potential for trait-tolerant varieties. APVMA registration requirements mandate local efficacy trials under Australian climatic conditions. Perth-based grain handlers are piloting direct-to-farm procurement platforms for broadacre input aggregation.
Global Glufosinate Market Competitive Landscape
Top-tier vendors anchor proprietary seed-trait integration, while generic formulators compete on price transparency and regional registration speed. The vendor base stratifies across three tiers: integrated agrochemical-seed conglomerates, mid-scale formulation specialists, and Chinese technical-grade suppliers. Two strategic archetypes dominate: trait-platform owners capturing captive demand, and generic manufacturers exploiting patent cliff windows. Competitive moves concentrate on backward integration into phosphorus trichloride feedstocks and digital platform partnerships for farm-level distribution bypass.
Within the integrated conglomerate tier, BASF SE and Bayer AG exemplify divergent strategic positioning. BASF anchors its stance through the LibertyLink seed-trait platform, creating proprietary demand pull for its glufosinate formulations. Bayer occupies a position emphasizing resistance-management protocol development and R&D depth. Among Asia-Pacific technical-grade suppliers, Lier Chemical Co. Ltd. and Jiangsu Sevencontinent Green Chemical Co. Ltd. represent the merchant manufacturing archetype, serving formulators lacking captive Strecker synthesis capacity. Nufarm Limited sits within the generic formulation specialist tier, concentrating on Asia-Pacific distribution network density.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta AG |
| Corteva Agriscience |
| UPL Limited |
| Nufarm Limited |
| Lier Chemical Co. Ltd. |
| DuPont de Nemours Inc. |
| Jiangsu Sevencontinent Green Chemical Co. Ltd. |
| Others |
Supply & Pricing Matrix
Chinese state-backed chemical conglomerates and family-owned phosphorus trichloride specialists anchor upstream supply, translating feedstock scarcity into disciplined pricing power across formulation tiers. Their captive access to acetonitrile and energy inputs insulates margin structures from spot-market volatility that squeezes non-integrated Western formulators.
Pricing Analysis
Margin tightening in generic formulation tiers reflects phosphorus trichloride feedstock volatility and Brazilian digital platform transparency. Three-tier pricing structure across proprietary trait-bundled, branded generic, and unbranded commodity formulations separates Bayer's resistance-management protocols from Nufarm's regional generics and Chinese spot-market supplies. Price differentiation hinges on EPA registration maintenance costs and LibertyLink trait licensing fees. Contract farmers in Brazil's MATOPIBA zone exhibit highest price sensitivity; German agricultural cooperatives accept premiums for water-dispersible granule sustainability credentials.
Supply Chain Analysis
GB standard certification and EPA FIFRA Section 3 registration gating concentrate technical-grade supply in Jiangsu and Shandong provinces, with BASF retaining captive Ludwigshafen capacity for LibertyLink integration. Strecker synthesis draws from phosphorus trichloride, acetonitrile, and sodium cyanide feedstocks anchored in Chinese industrial clusters. Single-source vulnerability to environmental inspections under China's dual carbon policy threatens merchant supply continuity. Distribution runs through grain trader financing networks in Brazil, agricultural cooperative procurement committees in Germany, and direct-to-farm digital platforms accelerating spot-market switching.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strecker synthesis capacity scarcity in compliant jurisdictions props pricing power for integrated manufacturers. Trait-stacking patent expirations and resistance-weed spread create divergent paths for incumbent defense versus entrant opportunity.
For Market Incumbents: To counter generic formulation price erosion and digital platform disintermediation, BASF and Bayer should deepen captive phosphorus trichloride supply through Shandong province offtake agreements or Ludwigshafen capacity expansion. Accelerate EPA re-registration dossier submission ahead of amphibian toxicity endpoint tightening to lock out contract research organization-dependent competitors. For New Entrants and Emerging Players: Australian grain handlers and Japanese rice cooperatives represent the most penetrable procurement channels for water-dispersible granule specialists lacking trait-platform integration. Target Western Australia's wheatbelt canola expansion and Hokkaido cooperative sustainability mandates through APVMA and METI-aligned registration speed. For Investors and Strategic Acquirers: Trait-stacking patent expiration announcements in soybean and corn systems are the leading indicator that generic-compatible formulation capacity will command scarcity premiums. Position for 5-10 year holding periods around Chinese technical-grade producers with GB standard export registration and emerging European bio-enhanced adjuvant platforms navigating EFSA hazard classification turbulence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Trichloride | Captive feedstock supply insulates margin structures from Chinese energy policy volatility. |
| EPA FIFRA Section 3 Re-registration Acceleration | Updated amphibian toxicity dossiers lock out generic competitors dependent on contract research. |
| Water-Dispersible Granule Format Expansion | Solid-phase formulations penetrate German and Japanese cooperative sustainability procurement. |
| LibertyLink Trait Stewardship Extension | Proprietary seed-herbicide bundling sustains pricing power against patent cliff generics. |
| Direct-to-Farm Digital Platform Partnership | Brazilian mobile-enabled procurement networks bypass distributor markups and compress switching costs. |
Research Methodology
Customs export databases, OECD pesticide registration filings, and SEC 10-K agrochemical segment disclosures formed the secondary backbone for supply-side capacity and trade flow calibration. Primary interviews with BASF and Bayer herbicide portfolio managers, Jiangsu province plant operations directors, Brazilian grain trader input financing leads, and German agricultural cooperative procurement committees validated formulation demand patterns and pricing transparency effects. Bottom-up crop acreage and trait penetration estimates triangulated against top-down manufacturer revenue segmentation.
Bottom-up modeling anchored volume projections in soybean, corn, canola, and cotton acreage expansion across the analysis window, cross-referenced with herbicide-tolerant trait licensing terms. Top-down manufacturer capacity and utilization data from Chinese chemical park disclosures and ECHA registration volumes stress-tested segment-level growth rates. CAGRs derived from regression against historical glyphosate resistance spread curves and EPA registration timeline compression.
Caveats apply where EFSA hazard classification upgrades or NMPA environmental inspection intensity could materially shift the outlook for European and Chinese supply availability. A model refresh is warranted upon material change in Amaranthus palmeri resistance biotype detection rates or LibertyLink trait patent litigation outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
Australia Agrochemicals Market
Agrochemicals
India Agrochemicals Market
Agrochemicals
South Africa Agrochemicals Market
Agrochemicals
Global Buprofezin Market
Agrochemicals
Potassium Humate Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
South America Agrochemicals Market
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
Agrochemical Market
Agrochemicals
L-Glufosinate Ammonium Market
Agrochemicals
Indonesia Agrochemicals Market
Agrochemicals
Egypt Agrochemicals Market
Agrochemicals
Canada Agrochemicals Market
Agrochemicals
Agrochemical Active Ingredients Market
Agrochemicals
Superphosphates Market
Agrochemicals
Mexico Agrochemicals Market