
 South Africa Agrochemicals Market | 2026-2036
South Africa Agrochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Agrochemicals Market Analytics
Specialized formulation grades for resistance management is rotating demand toward higher-efficacy chemistries. Bayer AG leverages its seed-trait pipeline to sustain integrated pest management portfolios across summer rainfall regions. Syngenta Group anchors its position through biologicals research stations near Brits and Malelane. Omnia Group Limited competes on nutrient-pesticide combination products tailored to local soil profiles.
South Africa agrochemicals encompass synthetic and biological crop protection agents, typically formulated as emulsifiable concentrates, wettable powders, or suspension concentrates with specified active ingredient loadings measured in grams per hectare, designed to safeguard yield volumes across commercial farming operations. Herbicides dominate volume flows given expansive maize and soybean plantings, while fungicide demand accelerates in high-humidity coastal production zones. Agricultural cooperatives remain the primary distribution channel for bulk procurement, though e-commerce platforms are gaining traction among mid-scale producers seeking technical advisory bundled with product delivery.
South Africa's Registrar of Act 36 of 1947 governs pesticide registration timelines and residue tolerance thresholds, while the Department of Agriculture, Land Reform and Rural Development enforces aerial application buffer zones near water catchments. Compliance with FAO/WHO Codex Alimentarius standards shapes export-oriented producer purchasing decisions, particularly for fruit destined to EU markets. Stakeholders must monitor pending amendments to the Fertilizers, Farm Feeds, Seeds and Remedies Act that could extend registration review periods and reshape product pipeline planning.
Market Dynamics
Precision application technologies are fragmenting traditional volume-based sales models across South Africa's commercial farming belt. Variable-rate equipment and drone-based spraying are compressing per-hectare chemical loads while elevating formulation quality requirements.
Growth Catalysts
- Free State maize expansion:Large-scale producers in this province are retrofitting planters with section-control systems that synchronize seed and chemical placement, sustaining premium product demand.
- Fertilizers, Farm Feeds, Seeds and Remedies Act amendments:Pending regulatory tightening on residue thresholds is accelerating grower migration toward integrated pest management bundles.
- Drone spraying platforms:Aerial application services in KwaZulu-Natal are cutting water volumes and enabling ultra-low-volume formulations previously uneconomical at scale.
Market Restraints
- Active ingredient import concentration:Technical-grade molecules from Chinese and Indian manufacturers dominate the supply base, exposing formulators to currency volatility and shipping disruptions.
- Registration timeline extension:South Africa's Registrar of Act 36 of 1947 review periods now stretch beyond four years for novel chemistries, freezing pipeline investment.
- Biological substitute acceleration:Bacillus thuringiensis and entomopathogenic fungi are capturing niche segments in Western Cape fruit production, pressuring synthetic fungicide pricing.
Strategic Opportunities
- Eastern Cape underpenetration:Emerging commercial operations in this province lack established cooperative relationships, creating direct-to-farmer channel openings for advisory-heavy suppliers.
- Nutrient-pesticide co-formulation:Soil-specific blends combining micronutrients with herbicide active ingredients address localized acidity and aluminum toxicity in North West farmlands.
- EU export compliance services:Codex Alimentarius-aligned residue management programs for citrus and table grape producers command premium advisory fees alongside product sales.
Industry Challenges
- Application technician scarcity:Calibrated equipment operation and nozzle selection expertise is thinning as experienced operators exit the workforce without structured replacement pipelines.
- Legacy inventory reconciliation:Warehousing systems built for bulk bagged goods struggle to track serialized container lots required under tightened traceability mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Agrochemicals Market |
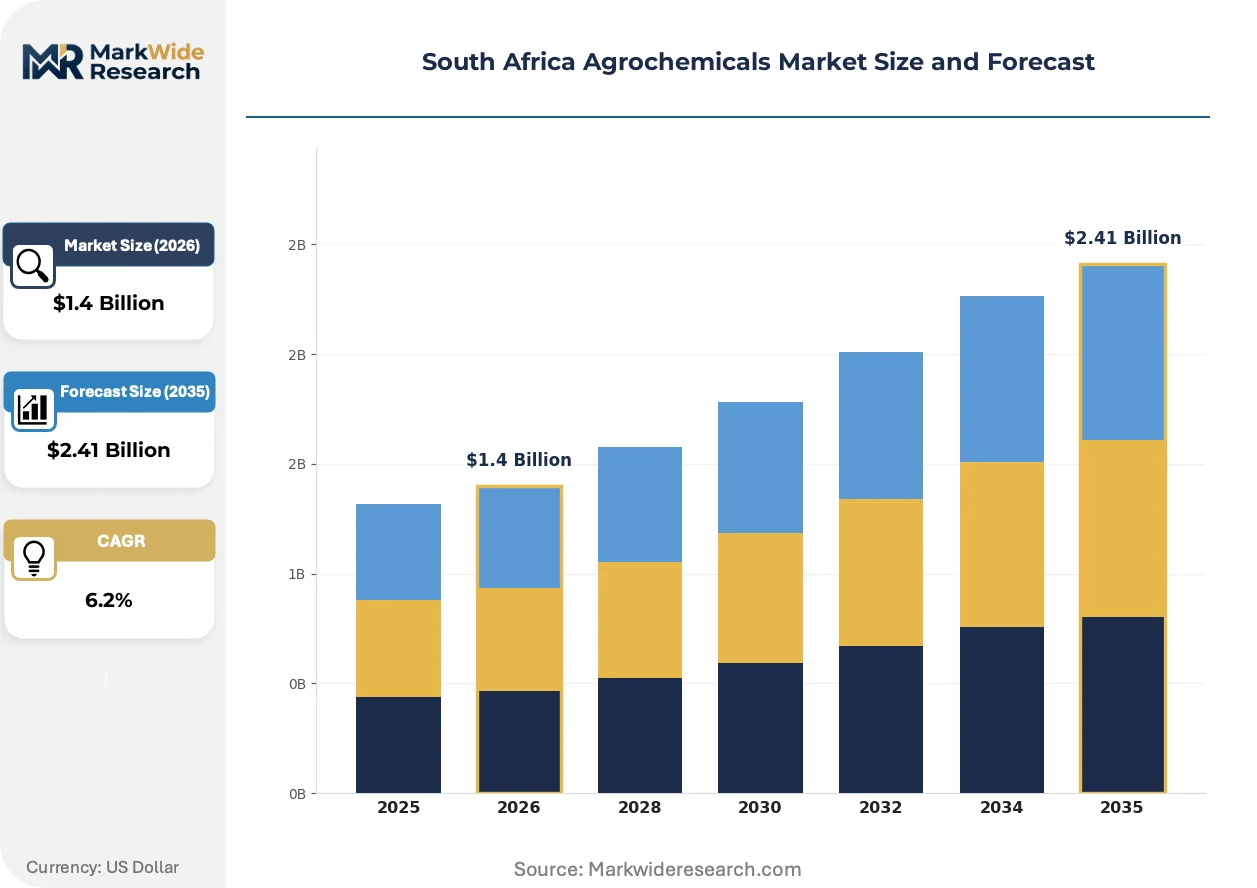
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pesticides, Herbicides, Insecticides, Fungicides End User: Agricultural Producers, Greenhouse Operators, Lawn Care Services, Turf Management Application: Crops, Ornamental Plants, Turf, Soil Treatment Distribution Channel: Retail Stores, E-commerce Platforms, Direct Sales, Agricultural Cooperatives |
| Companies Covered | BASF SE, FMC Corporation, Bayer AG, Sasol Limited, Yara International ASA, Syngenta Group, Omnia Group Limited, K+S Aktiengesellschaft, Corteva Agriscience, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Agrochemicals Market Evolving Landscape
Digital agriculture platforms are dissolving the boundary between chemical procurement and agronomic decision-making. Real-time soil sensors and satellite imagery are compressing the feedback loop between application and outcome assessment.
Biological seed treatment formulations incorporating Trichoderma and Pseudomonas strains are decomposing the traditional split between crop protection and plant nutrition categories. Western Cape wine grape producers are adopting these dual-function products at accelerating rates. This convergence is forcing synthetic fungicide suppliers to reposition around speed-of-control claims rather than standalone efficacy.
South Africa's pending amendments to the Fertilizers, Farm Feeds, Seeds and Remedies Act are extending data requirements for novel active ingredient registrations. Formulators must now submit multi-year residue decline studies under local climatic conditions. Export-oriented fruit producers in Limpopo and Mpumalanga are pre-emptively shifting procurement toward actives with established EU MRL harmonization to avoid future compliance gaps.
Mid-scale producers in KwaZulu-Natal are consolidating chemical purchases through e-commerce platforms bundling satellite prescription maps with product delivery. Agricultural cooperatives that previously controlled bulk procurement are responding with embedded agronomist services to retain membership. This channel tension is most visible in the 500-2,000 hectare operational segment where technical advisory value exceeds pure price competition.
South Africa Agrochemicals Market Segmentation
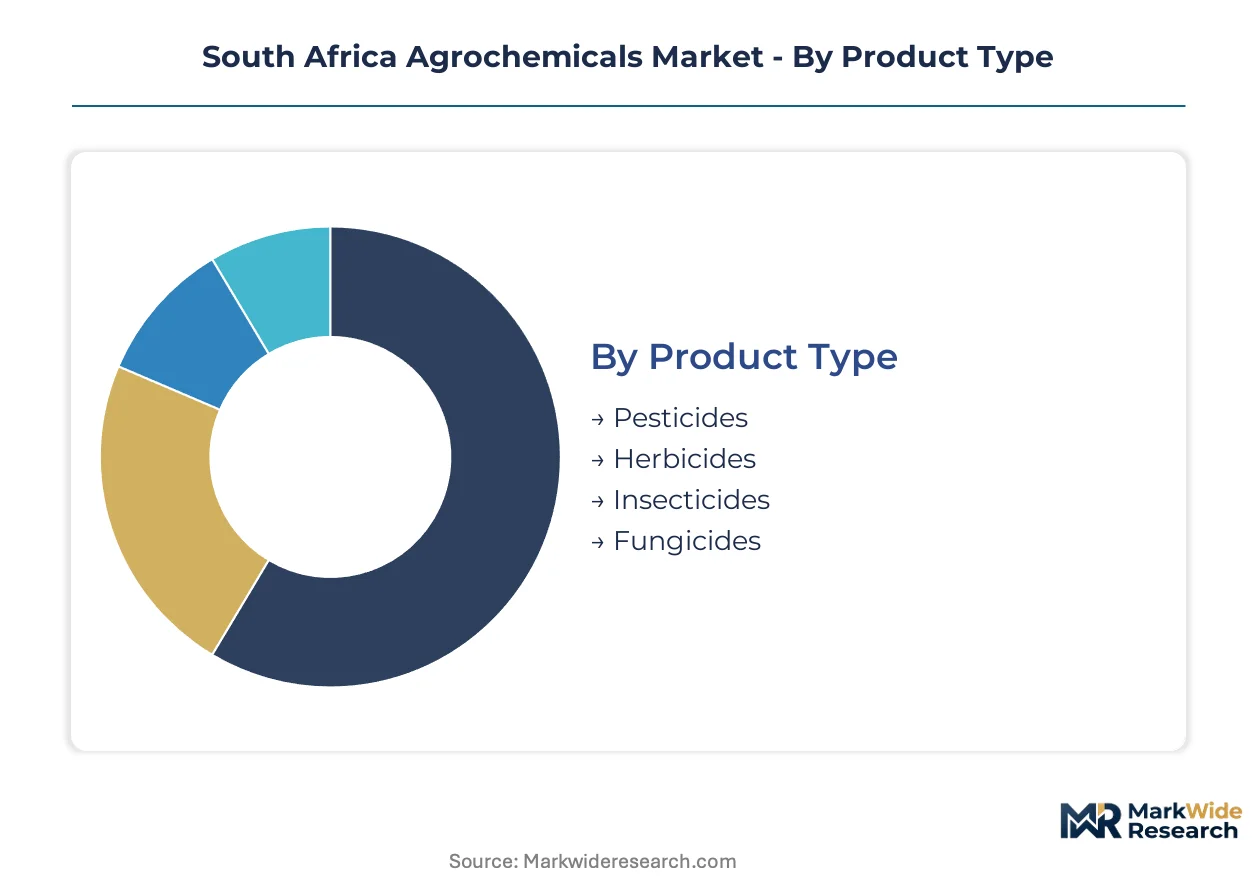
South Africa's agrochemical demand fragments across product chemistry, end-user scale, and channel access. Understanding these splits reveals where formulation premiums concentrate and where volume-based competition dominates procurement decisions.
Product Type:
Domestic grain production drives volume demand across the interior provinces, while export-oriented horticulture in the Western Cape and Limpopo pulls specialized chemistries with residue compliance requirements.
- Herbicides:Formulations containing glyphosate, atrazine, and acetochlor dominate maize and soybean operations across the Free State and North West. Large-scale producers retrofitting planters with section-control systems sustain demand for premium pre-emergent and post-emergent combinations despite per-hectare volume compression from precision application.
- Pesticides:Broad-spectrum synthetic pyrethroids and organophosphates face displacement pressure from Bacillus thuringiensis and entomopathogenic fungi in Western Cape fruit production. Export compliance requirements for EU MRL harmonization are accelerating grower migration toward integrated pest management bundles with biological components.
- Insecticides:Neonicotinoid seed treatments and foliar pyrethroids address aphid and bollworm pressure in summer rainfall regions. Drone spraying platforms in KwaZulu-Natal are enabling ultra-low-volume formulations previously uneconomical at scale.
- Fungicides:Triazole and strobilurin combinations protect high-humidity coastal production zones in KwaZulu-Natal and the Eastern Cape. Biological seed treatment formulations incorporating Trichoderma strains are capturing niche segments in wine grape production.
Herbicides hold the largest share; momentum sits with fungicides as coastal horticulture expands and biological alternatives gain regulatory preference.
End User:
Customer scale determines advisory intensity and channel access, with procurement patterns diverging sharply between cooperative-linked commercial operations and fragmented service providers.
- Agricultural Producers:Commercial farming operations above 500 hectares in the Western Cape and KwaZulu-Natal consolidate purchases through embedded agronomist services or direct manufacturer relationships. These buyers prioritize residue management programs aligned with Codex Alimentarius standards for EU export compliance.
- Greenhouse Operators:Controlled-environment production near Brits and Johannesburg demands specialized biological formulations and low-residue chemistries for local fresh produce markets. Input costs represent a higher share of revenue than field-scale operations, intensifying price sensitivity.
- Lawn Care Services:Municipal and private landscape maintenance contracts in Gauteng and Cape Town metropolitan areas procure generic glyphosate and selective broadleaf herbicides through retail channels. Seasonal demand concentration creates working capital pressures for smaller operators.
- Turf Management:Golf courses and sports field operators require fungicide-intensive programs for disease suppression in high-traffic grass surfaces. Technical advisory value exceeds product margins in this segment, favoring suppliers with localized disease monitoring capabilities.
Agricultural Producers command the dominant revenue pool; Greenhouse Operators are expanding most quickly as urban food security initiatives multiply.
Application:
Soil chemistry and climatic conditions dictate formulation requirements, with acidic North West soils and aluminum-toxic regions demanding co-formulated nutrient-pesticide blends unavailable in standard product ranges.
- Crops:Maize, soybean, and wheat production across the Free State, North West, and Mpumalanga consumes the majority of herbicide and insecticide volumes. Variable-rate equipment adoption is compressing per-hectare chemical loads while elevating formulation quality requirements.
- Ornamental Plants:Nursery operations and floriculture in Gauteng and the Western Cape require low-phytotoxicity fungicides and growth regulators with precise application timing. This segment tolerates higher per-unit pricing due to crop value density.
- Turf:Sports fields, golf courses, and municipal grounds combine herbicide, fungicide, and plant growth regulator applications on a scheduled program basis. Seasonal disease pressure in KwaZulu-Natal's humid coastal climate drives recurring fungicide demand.
- Soil Treatment:Fumigants and nematicides address soil-borne pathogens in high-value vegetable production near Pretoria and Polokwane. Registration requirements under the Fertilizers, Farm Feeds, Seeds and Remedies Act create supply concentration among established formulators with multi-year residue data.
Crops absorb the dominant volume share; Soil Treatment is climbing the fastest as protected cultivation expands and soil health management gains priority.
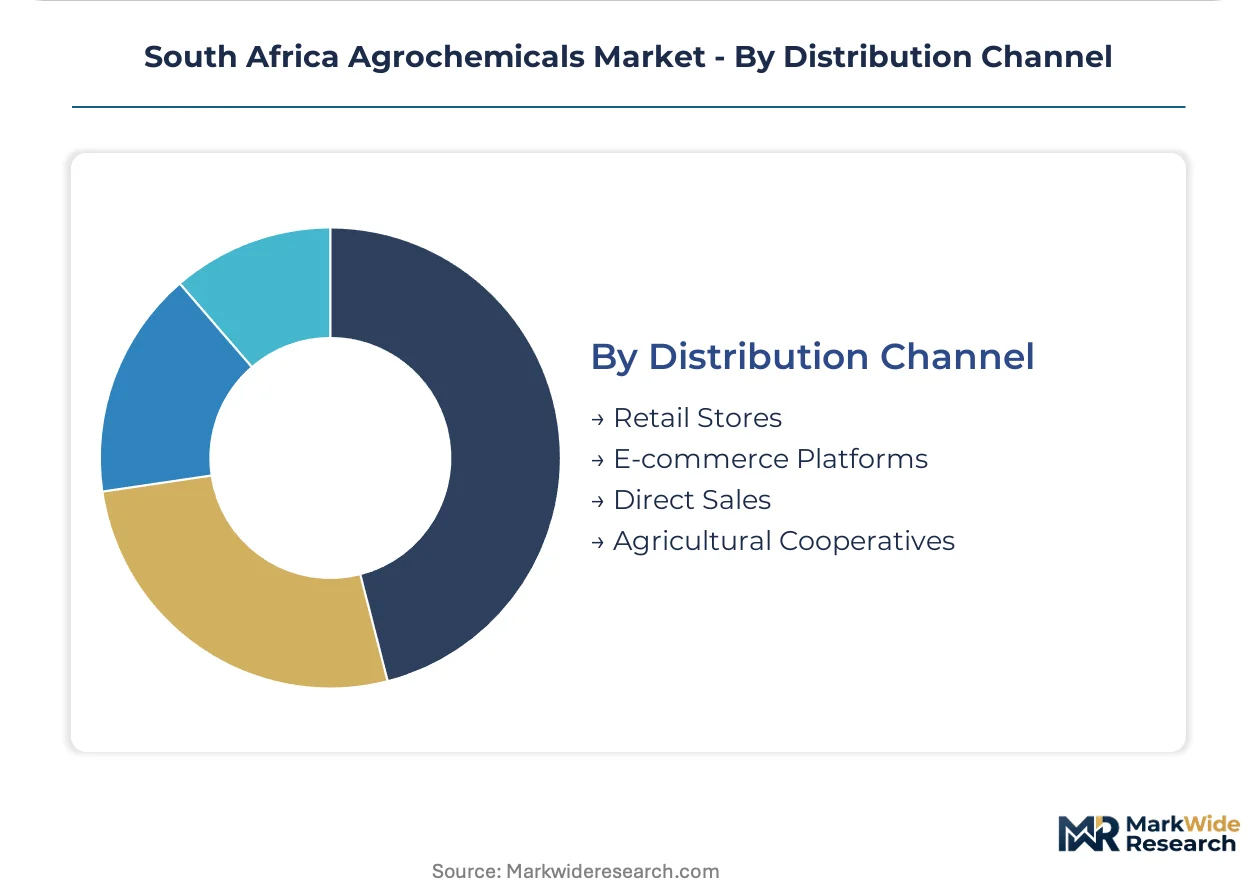
Distribution Channel:
Channel power is fragmenting as mid-scale producers bypass cooperative bulk procurement for direct advisory relationships, forcing legacy distributors to embed technical services or lose membership.
- Agricultural Cooperatives:Historically controlled bulk procurement for commercial grain producers, offering volume pricing and seasonal credit facilities. Cooperatives in the Free State and North West are responding to e-commerce encroachment with embedded agronomist services to retain membership loyalty.
- Direct Sales:Manufacturers and large formulators maintain technical sales teams for operations above 2,000 hectares, bundling satellite prescription maps with product recommendations. This channel captures the highest margin transactions through advisory fee structures.
- E-commerce Platforms:Mid-scale producers in the 500-2,000 hectare range increasingly consolidate chemical purchases through digital platforms bundling technical advisory with delivery. KwaZulu-Natal operations show the fastest adoption rates for this channel.
- Retail Stores:Independent agro-dealers and farm supply outlets serve smallholder and peri-urban producers with generic herbicides and basic protective equipment. Inventory management systems struggle to track serialized container lots required under tightened traceability mandates.
Agricultural Cooperatives retain the largest transaction volume; E-commerce Platforms are gaining share fastest among the mid-scale producer segment where advisory value exceeds pure price competition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's agrochemical trade balance tilts toward import dependency for technical-grade active ingredients, while formulated product exports to neighboring SADC markets partially offset foreign exchange outflows. Provincial demand patterns diverge sharply between summer rainfall grain belts and irrigated coastal horticulture zones.
Free State
Maize and soybean plantings exceeding two million hectares sustain the country's largest herbicide consumption base. The Department of Agriculture, Land Reform and Rural Development enforces aerial application buffer zones near the Vaal River catchment. Large-scale producers around Bethlehem and Sasolburg are retrofitting planters with section-control systems that synchronize seed and chemical placement.
Western Cape
Export-oriented wine grape and table grape production pulls specialized fungicide formulations with EU MRL compliance requirements. The Registrar of Act 36 of 1947 governs residue tolerance thresholds for produce destined to European markets. Biological seed treatment adoption is accelerating in Stellenbosch and Paarl as synthetic fungicide suppliers reposition around speed-of-control claims.
KwaZulu-Natal
High-humidity coastal conditions drive triazole and strobilurin demand for disease suppression in sugarcane and subtropical fruit. Drone spraying platforms around Durban and Richards Bay are enabling ultra-low-volume formulations previously uneconomical at scale. Mid-scale producers in this province show the fastest e-commerce platform adoption for chemical procurement bundled with satellite prescription maps.
North West
Acidic soils with aluminum toxicity create demand for nutrient-pesticide co-formulations unavailable in standard product ranges. The Fertilizers, Farm Feeds, Seeds and Remedies Act amendments are accelerating grower migration toward integrated pest management bundles. Commercial operations near Rustenburg and Potchefstroom are expanding precision application programs to address localized soil chemistry challenges.
Limpopo
Citrus and avocado exports to EU markets require Codex Alimentarius-aligned residue management programs. Export-oriented producers in Tzaneen and Phalaborwa are pre-emptively shifting procurement toward actives with established EU MRL harmonization. Biological substitutes incorporating Bacillus thuringiensis are capturing niche segments in high-value fruit production.
South Africa Agrochemicals Market Competitive Landscape
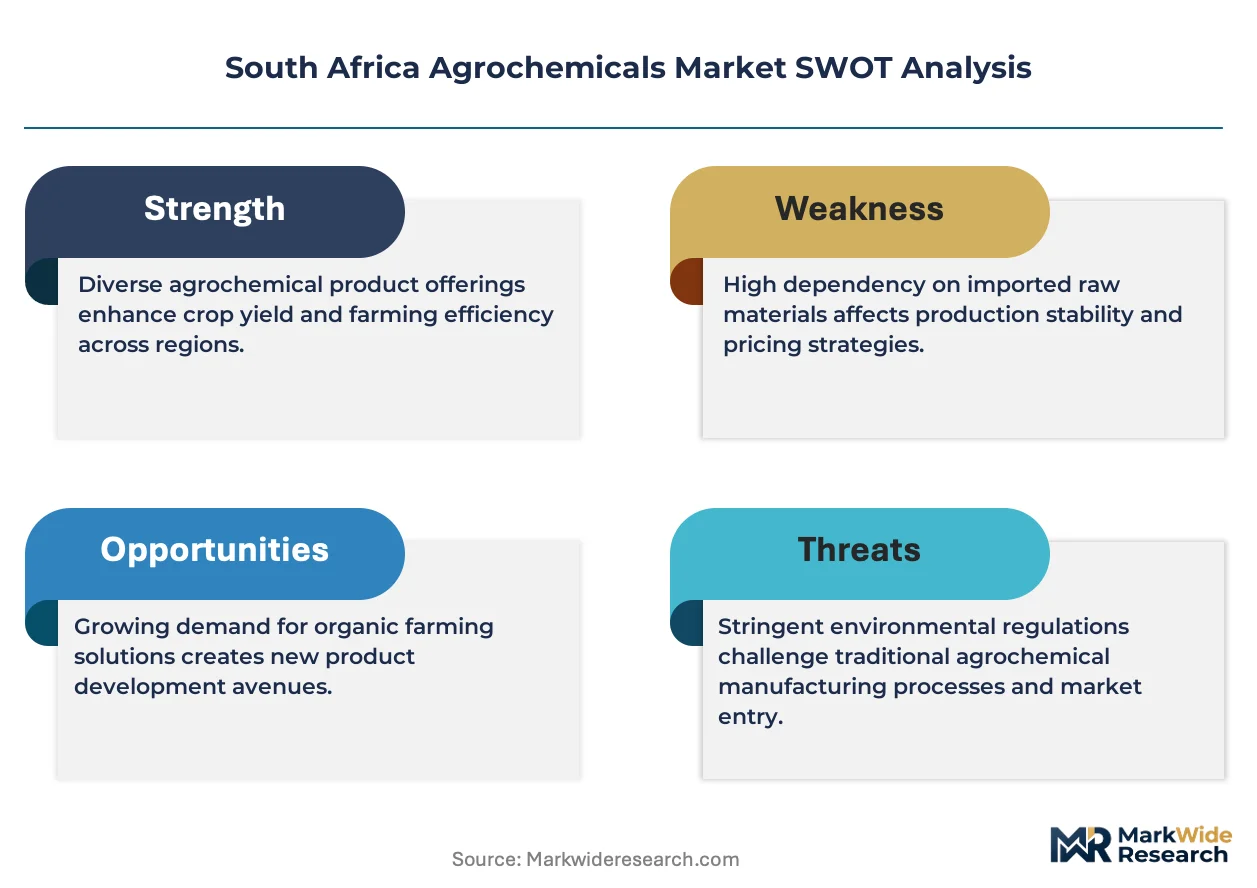
Listed leaders compete with private specialists across formulation technology and distribution reach, creating a tiered structure where scale advantages meet advisory-intensive service models. The market consolidates around integrated crop protection portfolios rather than single-product dominance. Three archetypes define competitive positioning: multinational innovators with seed-trait pipelines, regional formulators with soil-specific blends, and cooperative-linked distributors embedding agronomist services. Dominant competitive moves include backward integration into technical-grade active ingredient sourcing and strategic partnerships with precision agriculture equipment providers.
Within the multinational tier, Bayer AG and Syngenta Group exemplify integrated pest management portfolio strategies, while Omnia Group Limited represents the regional formulator archetype with nutrient-pesticide combination capabilities. These three companies anchor the competitive spectrum from global R&D platforms to localized soil-chemistry specialization.
| Leading Market Players |
|---|
| BASF SE |
| FMC Corporation |
| Bayer AG |
| Sasol Limited |
| Yara International ASA |
| Syngenta Group |
| Omnia Group Limited |
| K+S Aktiengesellschaft |
| Corteva Agriscience |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Free State grain cooperatives and Indian technical-grade suppliers lock in active ingredient access while capping price volatility exposure for formulators serving the maize belt. These arrangements tether South African agrochemical pricing to rupee-dollar exchange movements and Mumbai port throughput capacity.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium formulations carrying EU MRL harmonization command spreads above generic glyphosate sourced through retail channels. Cost compression in economy-tier herbicides is intensifying because Chinese technical-grade oversupply is flooding spot markets. Smallholder producers in peri-urban zones exhibit acute price sensitivity, while export-oriented citrus operations in Limpopo prioritize residue compliance over unit cost.
Supply Chain Analysis
China and India anchor technical-grade active ingredient production for South African formulators, with intermediate synthesis concentrated in Jiangsu and Gujarat chemical parks. Local blending operations draw from imported atrazine technical, glyphosate acid, and pyrethroid intermediates. Single-source vulnerability runs through Ningbo port congestion and Indian API export licensing delays. Distribution runs through agricultural cooperatives in the Free State and North West, though e-commerce platforms are fragmenting channel control in KwaZulu-Natal.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's agrochemical market rewards suppliers who bundle residue management advisory with product sales, as EU export compliance services expand faster than standalone chemical volumes. Recurring revenue from subscription-based agronomic monitoring is displacing transactional procurement in the 500-2,000 hectare segment.
For Market Incumbents: Consolidate backward integration into technical-grade sourcing through long-term offtake partnerships with Indian manufacturers, insulating margin pressure from currency volatility. Embed agronomist services within cooperative relationships to defend against e-platform disintermediation in KwaZulu-Natal. Prioritize capacity addition in North West co-formulation facilities addressing aluminum-toxic soil blends. For New Entrants and Emerging Players: Lead with biological seed treatment formulations targeting Western Cape wine grape producers, where synthetic fungicide displacement is accelerating. The Eastern Cape's emerging commercial operations lack established cooperative ties, creating direct-to-farmer openings for advisory-heavy suppliers. Deploy drone spraying service bundles to capture ultra-low-volume formulation demand in coastal humidity zones. For Investors and Strategic Acquirers: The market sits at a regulatory tightening phase that favors formulators with multi-year residue data archives and established Registrar of Act 36 relationships. Acquisition targets should display captive technical advisory capabilities and cooperative channel integration. Watch for amendments to the Fertilizers, Farm Feeds, Seeds and Remedies Act as the inflection signal that will freeze pipeline investment for undercapitalized entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical-Grade Sourcing | Indian and Chinese API supply concentration demands captive sourcing to stabilize margin exposure. |
| EU MRL Harmonization Certification | Codex Alimentarius alignment unlocks premium pricing in Limpopo and Western Cape export corridors. |
| Drone Spraying Service Partnerships | KwaZulu-Natal aerial platforms enable ultra-low-volume formulations previously uneconomical at scale. |
| Nutrient-Pesticide Co-Formulation Capacity | North West aluminum-toxic soil profiles require soil-specific blends unavailable from standard suppliers. |
| Biological Seed Treatment Pipeline | Western Cape wine grape producers are accelerating Trichoderma adoption, pressuring synthetic fungicide incumbents. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with Free State cooperative procurement managers, North West commercial farm agronomists, Western Cape export compliance officers, and technical sales directors at formulator headquarters. Secondary validation drew from South African customs import records, Department of Agriculture regulatory filings, EU MRL database updates, and SEC 10-K disclosures of listed multinationals. Bottom-up volume estimates from provincial planting data were triangulated against top-down value projections from cooperative transaction records.
Across the analysis window, the forecasting framework modeled product type splits, end-user scale tiers, application method variations, and channel access patterns. CAGRs were derived from trend extrapolation of precision adoption rates and biological substitution curves, calibrated against historical registration timeline impacts from the Registrar of Act 36.
The analysis sits within stated boundaries; outcomes outside sustained summer rainfall patterns, stable rupee-rand exchange rates, or unamended Fertilizers Act timelines would require recalibration. Recalibration cycles align with material shifts in EU MRL harmonization schedules and drone spraying regulatory clarity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
Global Buprofezin Market
Agrochemicals
Agrochemical Market
Agrochemicals
L-Glufosinate Ammonium Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
Potassium Humate Market
Agrochemicals
Mexico Agrochemicals Market
Agrochemicals
Indonesia Agrochemicals Market
Agrochemicals
Superphosphates Market
Agrochemicals
Middle East and Africa Plant Growth Regulators Market
Agrochemicals
Canada Agrochemicals Market
Agrochemicals
Africa Agrochemicals Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
India Agrochemicals Market
Agrochemicals
Australia Agrochemicals Market
Agrochemicals
South America Agrochemicals Market