
 Global Buprofezin Market | 2026-2036
Global Buprofezin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Buprofezin Market Analysis
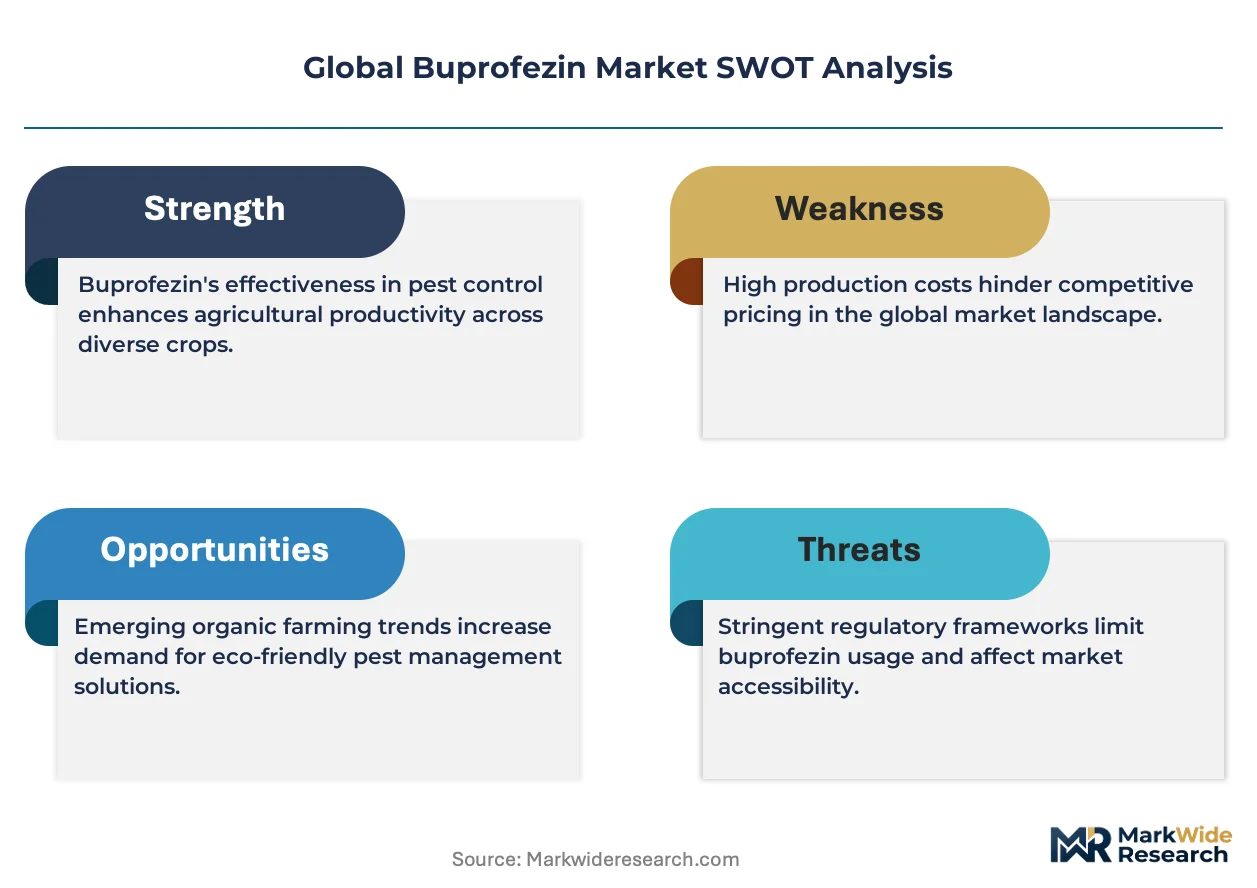
The capital-intensity divergence between integrated manufacturers and formulation-only players is redrawing competitive boundaries in buprofezin supply. Nihon Nohyaku Co., Ltd. leverages captive synthesis of key intermediates to sustain margin resilience against raw material volatility. Jiangsu Yangnong Chemical Co., Ltd. anchors its position through backward integration into thiourea-based precursor production. Sumitomo Chemical Company differentiates via proprietary suspension concentrate technology that commands premium positioning in Japanese domestic channels.
Buprofezin is a thiadiazine insect growth regulator with molecular formula C16H23N3OS, functioning as a chitin synthesis inhibitor that disrupts molting in homopteran pests including whiteflies and planthoppers. The compound exhibits selective toxicity against sucking insects while preserving pollinator populations, making it integral to integrated pest management programs in rice, cotton, and protected vegetable systems. Emulsifiable concentrate formulations dominate volume throughput due to established farmer familiarity and compatibility with conventional spray equipment, though suspension concentrate formats gain traction where drift reduction and operator exposure minimization carry regulatory weight. Wettable powder segments face structural decline as aqueous-based alternatives displace dust-prone legacy products across EU and East Asian markets.
FDA residue tolerance frameworks for imported agricultural commodities shape export-oriented formulation standards, while China's NMPA and MEE jointly enforce stricter environmental impact assessments for agrochemical manufacturing licenses. India's CEA and state-level pollution control boards impose wastewater discharge limits that elevate capital requirements for active ingredient producers. Stakeholders must monitor evolving maximum residue limits under Codex Alimentarius and regional food safety authorities, as divergence between import jurisdictions creates compliance complexity for multinational suppliers.
Market Dynamics
China's NMPA residue limit tightening is forcing active ingredient producers to revalidate manufacturing processes, compressing registration timelines for export-oriented formulations and redrawing competitive boundaries between integrated and non-integrated suppliers.
Growth Catalysts
- Whitefly pressure in Brazilian soybean:Homopteran pest outbreaks in Mato Grosso and Paraná drive demand for chitin synthesis inhibitors as resistance to neonicotinoids spreads.
- EU Green Deal Farm-to-Fork targets:The 50% pesticide reduction mandate accelerates IGR adoption in integrated pest management programs across Spanish and Italian protected vegetable systems.
- Thiourea precursor availability:Jiangsu and Shandong province chemical clusters in China maintain captive intermediate supply, stabilizing formulation input costs for regional exporters.
Market Restraints
- Isopropanol cost volatility:Solvent price swings in Asian spot markets squeeze emulsifiable concentrate margins for non-integrated blenders.
- Single-source intermediate dependence:Three Chinese manufacturers control over 80% of technical-grade buprofezin active ingredient, creating supply concentration risk.
- Neonicotinoid-nematicide combinations:Syngenta and Bayer pipeline products threaten IGR positioning in cotton seed treatment applications.
Strategic Opportunities
- Vietnam Mekong Delta rice expansion:Government irrigation investments in An Giang and Kien Giang provinces expand addressable hectares for planthopper management.
- Suspension concentrate-drift reduction pairing:Japanese aerial application standards favor SC formulations with adjuvant packages that minimize off-target movement.
- India PLI scheme for agrochemical intermediates:Domestic production incentives for thiourea derivatives reduce import dependence for Gujarat and Maharashtra formulation units.
Industry Challenges
- Analytical method validation:Codex Alimentarius MRL divergence between EU and US FDA tolerance frameworks forces duplicate residue studies for multi-destination exporters.
- Wastewater treatment capex:India's CEA mandates zero liquid discharge for active ingredient plants, requiring membrane bioreactor investments that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Buprofezin Market |
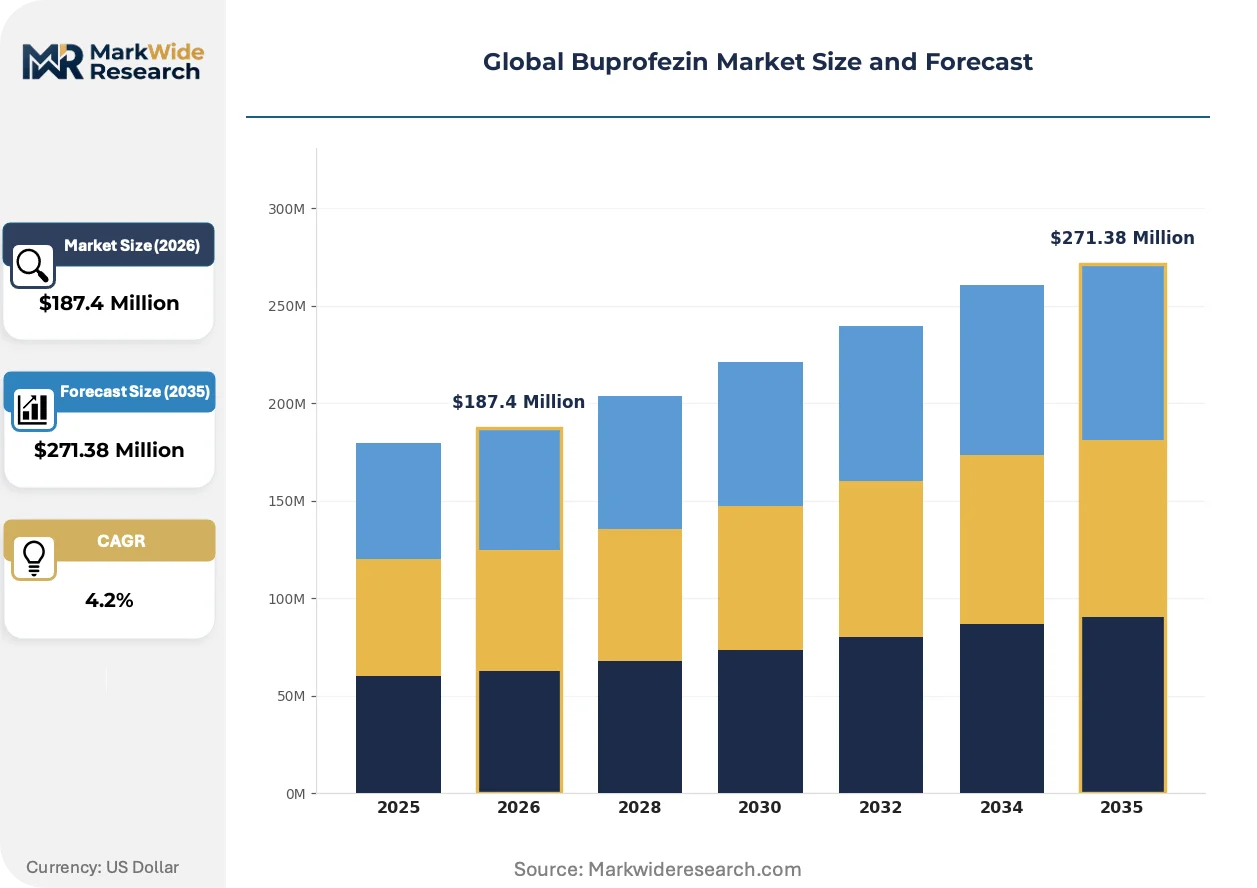
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Wettable Powder, Liquid Concentrate, Emulsifiable Concentrate Application: Crops, Ornamental Plants, Vegetables, Fruits Formulation: SC, WP, EC, WDG Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | Nihon Nohyaku Co., Ltd., Sumitomo Chemical Company, Jiangsu Yangnong Chemical Co., Ltd., Zhejiang Xinan Chemical Industrial Group, Shandong Weifang Rainbow Chemical Co., Ltd., Hebei Veyong Bio-Chemical Co., Ltd., Jiangsu Flag Chemical Industry Co., Ltd., Nantong Jiangshan Agrochemical & Chemical Co., Ltd., Anhui Huaxing Chemical Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Buprofezin Market Emerging Trajectories
Formulation technology and regulatory chemistry are diverging sharply between legacy emulsifiable concentrate systems and next-generation aqueous delivery platforms, with implications for manufacturing asset deployment and regional market access.
Nano-emulsion delivery systems are bifurcating the high-value protected vegetable segment from commodity field crop applications. Dutch and Spanish greenhouse operators adopt these systems for whitefly management in tomato and pepper propagation. The technology is bifurcating premium positioning from volume throughput, compressing margin pools for conventional EC suppliers in Mediterranean markets.
REACH authorization timelines for thiourea derivatives are extending pre-registration data requirements for EU-bound active ingredient shipments. ECHA's 2024 substance evaluation roadmap adds mammalian toxicity endpoints that Chinese technical manufacturers must address. Formulation registrants in Germany and France accelerate substitution assessments to preempt authorization sunset clauses.
Indian cotton belt cooperatives are consolidating procurement through state-level farmer producer organizations, disintermediating traditional distributor networks in Maharashtra and Telangana. These FPOs negotiate direct technical supply agreements with active ingredient exporters, compressing working capital cycles for established formulation brands. The shift is most visible in Vidarbha region where cooperative membership exceeds 40% of cotton-growing households.
Global Buprofezin Market Segmentation
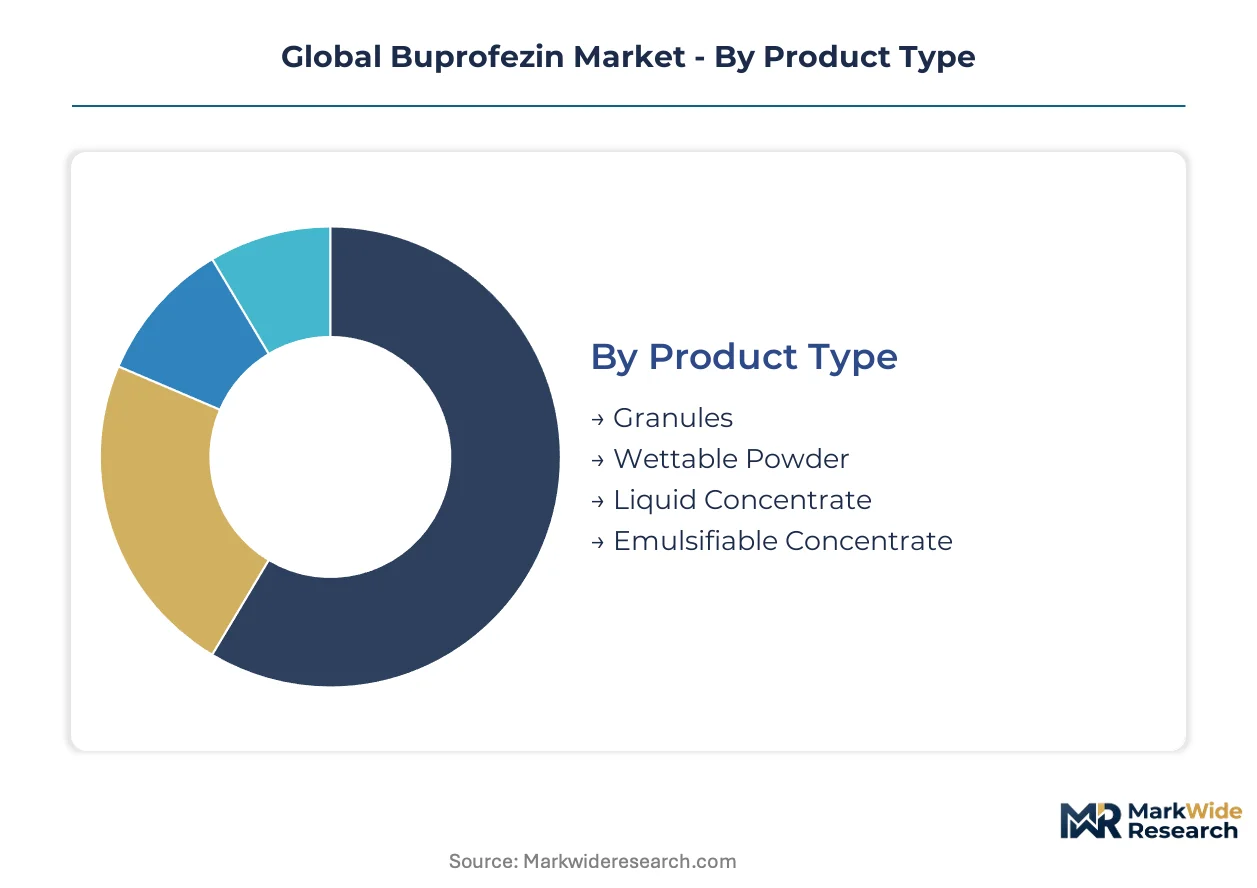
Formulation chemistry and delivery format drive margin capture in buprofezin, with regulatory drift-reduction mandates and farmer application preferences reshaping product mix across rice, cotton, and protected vegetable systems.
Product Type:
Margin pools concentrate in liquid delivery systems where formulation technology barriers protect pricing power against generic competition.
- Emulsifiable Concentrate:Oil-in-water systems blending technical-grade active ingredient with aromatic solvents and emulsifiers. Established farmer familiarity in India, Vietnam, and Brazil sustains volume leadership despite drift exposure liabilities in aerial applications.
- Liquid Concentrate:Pre-diluted aqueous solutions reducing field mixing errors and operator contact. Japanese aerial application standards and EU operator exposure limits accelerate displacement of dry formulations in premium channels.
- Granules:Clay-based carriers for soil incorporation in rice paddy systems. Southeast Asian transplanting operations favor broadcast application convenience over spray logistics.
- Wettable Powder:Dust-prone legacy format facing structural decline as aqueous alternatives displace bagged products across EU and East Asian markets.
The dominant share belongs to Emulsifiable Concentrate, while Liquid Concentrate is closing the gap fastest.
Application:
End-use concentration follows pest pressure intensity and crop value per hectare, with high-value protected systems commanding formulation premiums over commodity field crops.
- Crops:Rice and cotton anchor volume demand, with planthopper management in Southeast Asian paddies and whitefly control in Indian and Brazilian cotton belts driving technical consumption. Resistance to neonicotinoids redirects farmer procurement toward chitin synthesis inhibitors.
- Vegetables:Protected tomato, pepper, and cucumber systems in Spain, Italy, and the Netherlands generate premium pricing for drift-reduced formulations. EU Green Deal pesticide reduction mandates accelerate IGR integration in integrated pest management protocols.
- Fruits:Citrus and grape applications concentrate in Mediterranean climates where whitefly vector control protects export-oriented production.
- Ornamental Plants:Nursery and greenhouse propagation systems in Japan and the Netherlands favor precision application technologies minimizing phytotoxicity risk.
Crops command the volume base, though Vegetables generate the steepest margin expansion trajectory.
Formulation:
Regulatory chemistry divergence between legacy solvent systems and aqueous platforms is fragmenting manufacturing asset deployment and registration pathways.
- SC (Suspension Concentrate):Aqueous dispersion of solid active ingredient particles with surfactant stabilization. Japanese aerial application standards and EU drift reduction mandates position SC formats for premium channel penetration.
- EC (Emulsifiable Concentrate):Solvent-based systems dominating throughput in price-sensitive markets. Isopropanol cost volatility in Asian spot markets compresses blender margins for non-integrated suppliers.
- WP (Wettable Powder):Dry blend format facing displacement as aqueous concentrates reduce operator dust exposure and packaging waste.
- WDG (Water-Dispersible Granules):Low-dust alternative to wettable powders with improved storage stability. Southeast Asian rice cooperatives adopt WDG for bulk procurement efficiency.
EC retains installed base dominance, yet SC formulations are gaining share fastest where regulatory weight favors drift minimization.
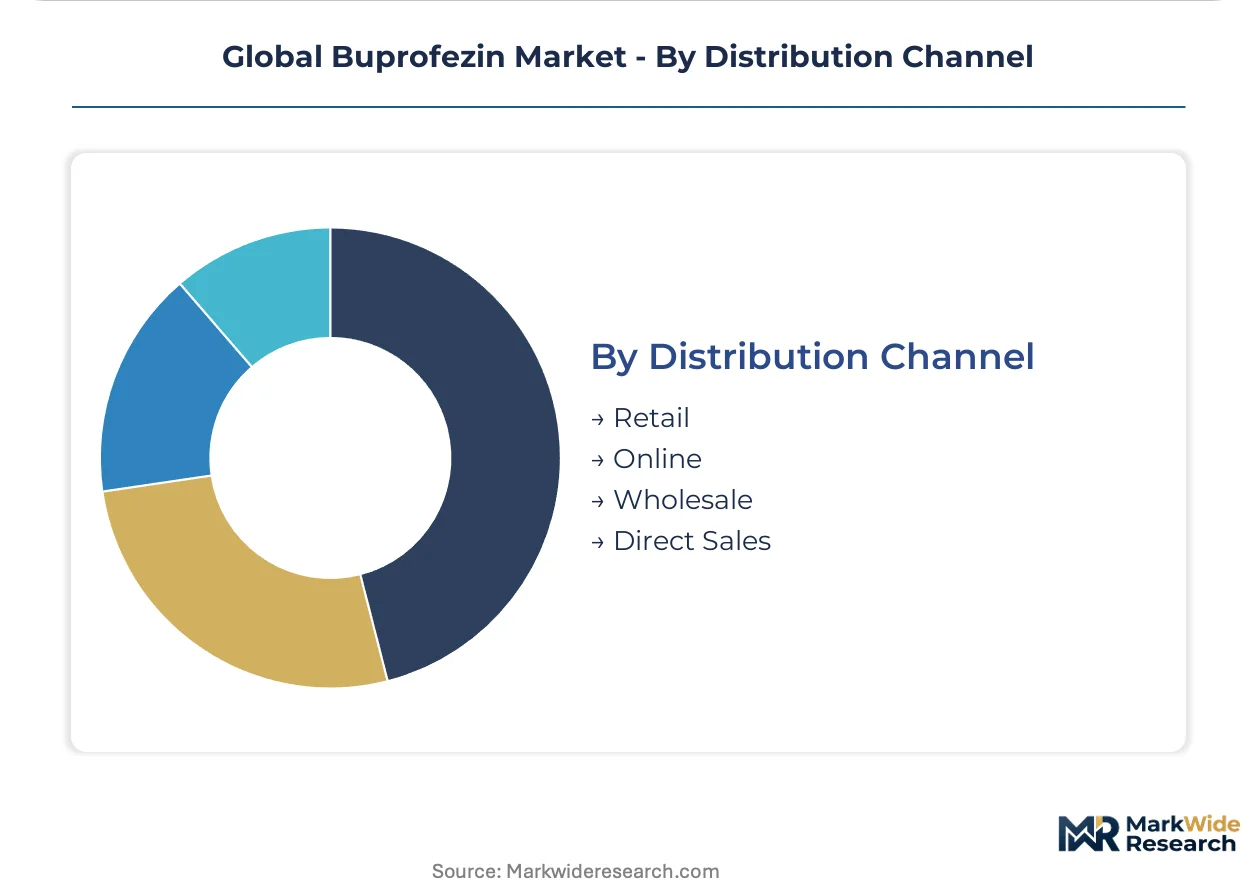
Distribution Channel:
Channel structure is bifurcating between consolidated cooperative procurement in mature markets and fragmented retail networks in emerging agricultural economies.
- Wholesale:Bulk technical supply to formulation blenders and state-level cooperatives. Indian Farmer Producer Organizations in Maharashtra and Telangana negotiate direct agreements, compressing working capital cycles for established brands.
- Retail:Agrochemical dealer networks serving smallholder farmers with credit-linked seasonal sales. Brazil's Mato Grosso distribution infrastructure supports whitefly management product access.
- Direct Sales:Technical-grade active ingredient procurement by integrated manufacturers and large-scale plantation operators. Captive supply agreements reduce price volatility exposure.
- Online:Emerging channel for specialty formulation procurement in developed markets, constrained by hazardous goods shipping regulations and farmer digital adoption gaps.
Wholesale channels capture the dominant volume flow, while Direct Sales are expanding most quickly through cooperative consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for buprofezin formulations diverges sharply across agricultural economies. Indian cotton belt buyers negotiate aggressively on emulsifiable concentrate pricing, while Japanese greenhouse operators absorb premiums for drift-reduced suspension concentrates. This demand-elasticity contrast shapes regional product mix and margin capture.
China
Rice planthopper pressure in Jiangsu and Zhejiang provinces sustains technical-grade consumption. NMPA residue limit tightening forces active ingredient producers to revalidate manufacturing processes, compressing registration timelines for export-oriented formulations. The Shandong chemical cluster maintains captive thiourea precursor supply, stabilizing input costs for regional exporters.
India
Whitefly outbreaks in Maharashtra and Telangana cotton belts redirect procurement toward chitin synthesis inhibitors as neonicotinoid resistance spreads. CEA mandates zero liquid discharge for active ingredient plants, requiring membrane bioreactor investments that strain mid-tier manufacturer balance sheets. Gujarat formulation units leverage PLI scheme incentives for domestic thiourea derivative production.
Brazil
Homopteran pest pressure in Mato Grosso and Paraná soybean regions drives demand for IGR-based management programs. ANVISA registration pathways for imported technical-grade active ingredient require residue study alignment with Mercosur food safety standards. Distribution infrastructure in Mato Grosso supports seasonal whitefly product access through credit-linked dealer networks.
Japan
Protected vegetable systems in Chiba and Ibaraki prefectures generate premium pricing for drift-reduced formulations. METI aerial application standards favor suspension concentrate formats with adjuvant packages minimizing off-target movement. Domestic manufacturers leverage proprietary formulation technology for channel positioning.
Spain
Greenhouse tomato and pepper propagation in Almería and Murcia accelerates IGR integration under EU Green Deal pesticide reduction mandates. ECHA REACH authorization timelines for thiourea derivatives extend pre-registration data requirements for technical shipments. Dutch and Spanish operators adopt nano-emulsion delivery systems for premium whitefly management.
Global Buprofezin Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in buprofezin supply. Captive synthesis of key intermediates separates margin-resilient manufacturers from formulation-only blenders exposed to raw material volatility. Three strategic archetypes dominate: backward-integrated technical producers, proprietary formulation technology holders, and regional export-oriented blenders. Capacity expansion in Chinese thiourea precursor clusters and technology licensing for aqueous delivery platforms represent the dominant competitive moves reshaping supply boundaries.
Within the integrated technical producer tier, Nihon Nohyaku Co., Ltd. and Jiangsu Yangnong Chemical Co., Ltd. exemplify archetypes sustaining margin resilience through upstream control over critical intermediates. Sumitomo Chemical Company occupies a position emphasizing proprietary suspension concentrate technology for premium channel access. These three anchors illustrate how manufacturing depth and formulation differentiation separate competitive positions in a market where input cost stability and regulatory compliance capabilities determine survival.
| Leading Market Players |
|---|
| Nihon Nohyaku Co., Ltd. |
| Sumitomo Chemical Company |
| Jiangsu Yangnong Chemical Co., Ltd. |
| Zhejiang Xinan Chemical Industrial Group |
| Shandong Weifang Rainbow Chemical Co., Ltd. |
| Hebei Veyong Bio-Chemical Co., Ltd. |
| Jiangsu Flag Chemical Industry Co., Ltd. |
| Nantong Jiangshan Agrochemical & Chemical Co., Ltd. |
| Anhui Huaxing Chemical Industry Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
China's NMPA residue limit tightening gates both supply qualification and price differentiation, forcing active ingredient producers to revalidate manufacturing processes while compressing registration timelines for export-oriented formulations. This regulatory threshold simultaneously elevates compliance costs for non-integrated suppliers and creates pricing power for backward-integrated manufacturers with captive thiourea precursor production.
Pricing Analysis
After-sales service contracts and technical support packages drive lifetime value in buprofezin procurement, with formulation manufacturers bundling residue analysis and regulatory guidance into multi-year supply agreements. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with drift-reduced suspension concentrates commanding premiums in Japanese and EU channels while emulsifiable concentrates face cost compression from isopropanol volatility in Asian spot markets. Indian cotton belt cooperatives exhibit highest price sensitivity, negotiating aggressively on seasonal procurement, whereas Japanese greenhouse operators absorb formulation premiums for aerial application compliance.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for technical-grade shipments from Chinese chemical clusters to formulation blenders in India and Brazil. Supply concentrates in China, India, and Japan, with thiourea precursor production anchored in Shandong and Jiangsu provinces, isopropanol solvent sourcing from regional petrochemical complexes, and proprietary adjuvant packages from Japanese specialty chemical manufacturers. Single-source intermediate dependence creates vulnerability, as three Chinese manufacturers control over 80% of technical-grade active ingredient. Distribution runs through state-level cooperatives and agrochemical dealer networks, with direct technical supply agreements bypassing traditional intermediaries in Maharashtra and Telangana.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory chemistry divergence between legacy solvent systems and aqueous delivery platforms fragments manufacturing asset deployment, creating niche opportunities for specialists with formulation technology differentiation or captive intermediate control.
For Market Incumbents: Secure backward integration into thiourea-based precursor production to buffer margin erosion from raw material volatility, while accelerating suspension concentrate capacity additions in Japanese and EU markets where drift-reduction mandates favor aqueous platforms. Neonicotinoid-nematicide combinations from Syngenta and Bayer threaten IGR positioning in cotton seed treatment, requiring defensive patent landscaping and early-stage resistance monitoring investments. For New Entrants and Emerging Players: Custom residue study services for multi-destination exporters represent a service-layer gap where incumbents under-serve, creating entry points for analytical laboratories with Codex Alimentarius and FDA tolerance framework expertise. Target Vietnam's Mekong Delta rice expansion and Indian PLI-supported thiourea derivative production as penetrable geographies, leveraging direct technical supply agreements with state-level farmer producer organizations as the primary go-to-market channel. For Investors and Strategic Acquirers: ECHA's 2024 substance evaluation roadmap for thiourea derivatives reshapes the acquisition landscape, extending pre-registration data requirements that strain mid-tier technical manufacturers without mammalian toxicity endpoint capabilities. Over a 5-10 year horizon, integrated producers with captive synthesis and formulation technology differentiation offer superior viability versus standalone blenders exposed to input cost volatility. Monitor REACH authorization sunset clause acceleration as the signal indicating consolidation pressure on non-compliant technical suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thiourea Precursors | Jiangsu and Shandong chemical clusters stabilize input costs against isopropanol volatility. |
| Suspension Concentrate Capacity Expansion | Japanese METI aerial application standards favor SC formats with drift-minimizing adjuvant packages. |
| Zero Liquid Discharge Compliance Investment | India's CEA mandates membrane bioreactor systems that filter acquisition targets by capital adequacy. |
| Direct Cooperative Supply Agreements | Maharashtra and Telangana farmer producer organizations compress working capital cycles for technical exporters. |
| Nano-Emulsion Delivery Development | Dutch and Spanish greenhouse operators adopt premium systems for whitefly management in tomato propagation. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with plant managers at active ingredient facilities, procurement leads at downstream formulation blenders, distribution channel partners in Indian cotton belts, and technical R&D directors specializing in aqueous delivery systems; and secondary validation through customs and trade data, NMPA and ECHA regulatory filings, SEC 10-K disclosures from listed agrochemical manufacturers, and state-level pollution control board records. Bottom-up technical capacity assessments and top-down formulation demand estimates were triangulated against residue limit divergence patterns across import jurisdictions.
Across the analysis window, forecasts model formulation chemistry, delivery format, end-use crop system, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from production capacity utilization rates, cooperative procurement consolidation trajectories, and drift-reduction mandate adoption curves. Industry-specific inputs include planthopper pressure indices in Southeast Asian rice systems and neonicotinoid resistance monitoring data from Brazilian soybean regions.
Forecasts assume regulatory continuity in China's NMPA residue frameworks, EU REACH authorization timelines, and India's CEA discharge mandates; material policy shifts in thiourea derivative classification or zero liquid discharge stringency would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
South America Agrochemicals Market
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
Mexico Agrochemicals Market
Agrochemicals
India Agrochemicals Market
Agrochemicals
Potassium Humate Market
Agrochemicals
Agrochemical Market
Agrochemicals
Australia Agrochemicals Market
Agrochemicals
South Africa Agrochemicals Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
Indonesia Agrochemicals Market
Agrochemicals
L-Glufosinate Ammonium Market
Agrochemicals
Agrochemical Active Ingredients Market
Agrochemicals
Canada Agrochemicals Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
Middle East and Africa Plant Growth Regulators Market
Agrochemicals
Superphosphates Market