
 India Agrochemicals Market | 2026-2036
India Agrochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
India Agrochemicals Market Foresight
The dealer-retail channel in rural India is fragmenting as e-commerce platforms and farmer producer organizations gain direct procurement traction. UPL leverages its extensive distribution network to sustain deep penetration in tier-three towns and village-level markets. Bayer CropScience Limited anchors its position through specialized high-value crop solutions in cotton and vegetables. Dhanuka Agritech Ltd. competes aggressively on price-accessible formulations for the mass-market cereal segment.
Agrochemicals encompass synthetic and biological substances formulated for crop protection, soil enhancement, and yield optimization, typically manufactured through multi-stage chemical synthesis or fermentation processes with active ingredient concentrations ranging from 5% to 50% by weight. These compounds serve to control pests, diseases, and weeds while improving plant physiology across commercial farming operations. Herbicides command the largest product type share as labor scarcity pushes Indian farmers toward chemical weed management in rice and wheat systems. Bio-pesticides represent the fastest-expanding product category, driven by export-oriented organic farming clusters in Karnataka and Madhya Pradesh seeking residue-free certification. Seed treatment applications concentrate margin pools through proprietary formulation bundling with hybrid seed programs.
The Central Insecticides Board under the Ministry of Agriculture regulates registration and residue limits for all agrochemicals sold in India, while FSSAI monitors pesticide residues in food commodities to enforce consumer safety thresholds. BIS standards govern formulation quality and packaging specifications, creating compliance barriers for unorganized manufacturers. The PLI scheme for agrochemical manufacturing is redirecting investment toward domestic technical-grade production. Stakeholders must monitor evolving draft regulations on drone-based pesticide application and gene-edited crop compatibility with existing chemistries.
Market Dynamics
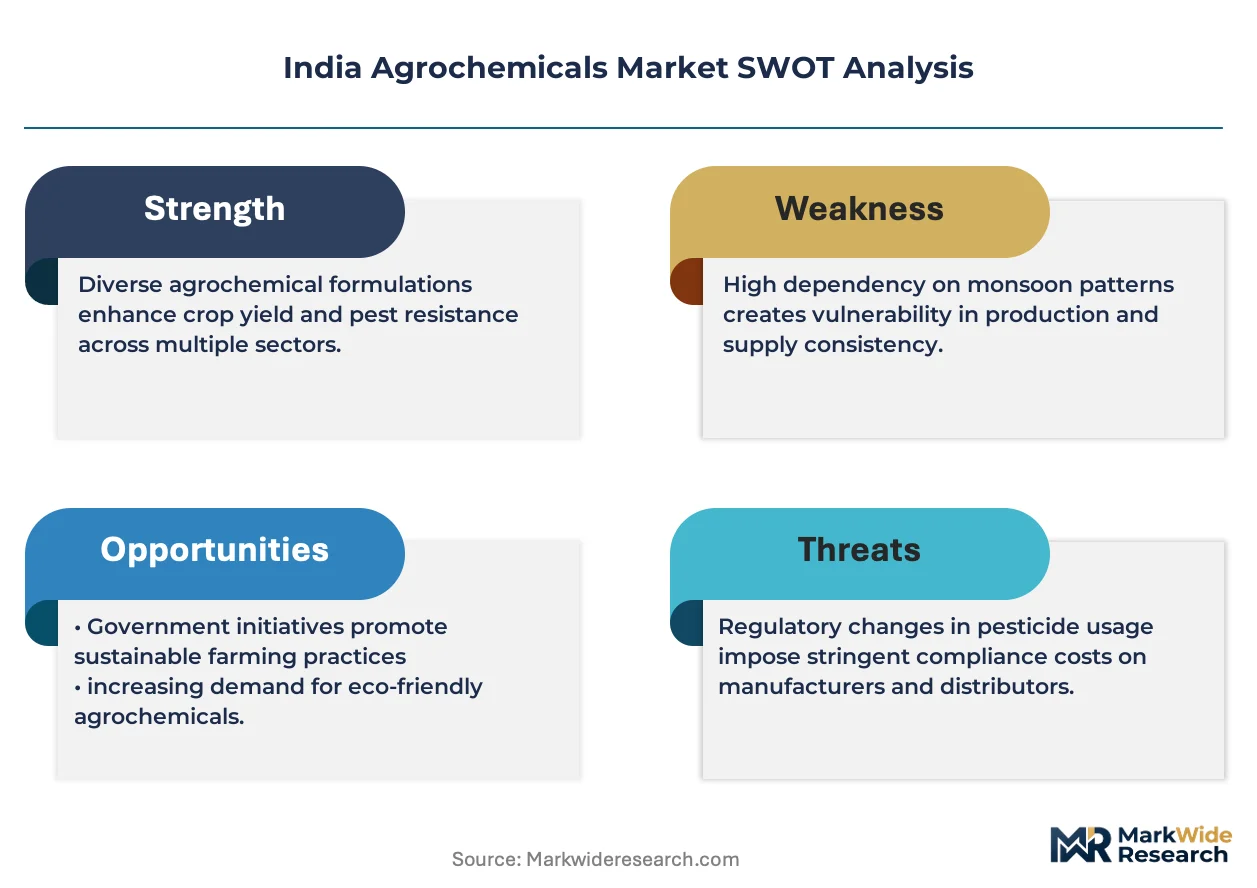
The PLI scheme for agrochemical manufacturing is redirecting capital toward domestic technical-grade production, compressing India's historical dependence on imported active ingredients and reshaping competitive positioning among formulation specialists.
Growth Catalysts
- PLI scheme incentives:Domestic manufacturers are expanding technical-grade capacity to capture production-linked benefits, reducing import exposure for key herbicide actives.
- Labor scarcity in rice-wheat belts:Punjab and Haryana farmers are accelerating herbicide substitution for manual weeding as agricultural wages rise.
- Drone-based application:Aviation regulators and state agriculture departments are piloting unmanned aerial spraying in Maharashtra cotton zones, enabling precision coverage at lower labor cost.
Market Restraints
- Import concentration for technicals:Over half of key pesticide actives still originate from Chinese chemical manufacturers, exposing margins to tariff volatility and supply disruptions.
- FSSAI residue enforcement:Tighter maximum residue limits on export commodities are disqualifying smallholder produce from premium EU and Middle Eastern markets.
- Bio-pesticide efficacy gaps:Microbial formulations struggle to match synthetic pyrethroids in cotton bollworm control, limiting farmer switching in high-pressure pest zones.
Strategic Opportunities
- Seed treatment bundling:Hybrid seed companies in Gujarat and Karnataka are integrating proprietary fungicide coatings, capturing margin pools beyond standalone chemical sales.
- Organic cluster certification:Madhya Pradesh and Uttarakhand export-oriented growers are adopting bio-pesticide protocols to access residue-free premiums in European retail channels.
- Farmer producer organization procurement:FPOs in Telangana and Andhra Pradesh are consolidating chemical purchases through digital platforms, disintermediating traditional dealer networks.
Industry Challenges
- Registration timeline compression:Central Insecticides Board review cycles for novel molecules extend 4-7 years, delaying commercialization of next-generation chemistries.
- Formulation chemist scarcity:Indian Institutes of Technology and state agricultural universities produce insufficient graduates with combined synthesis and field-evaluation expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Agrochemicals Market |
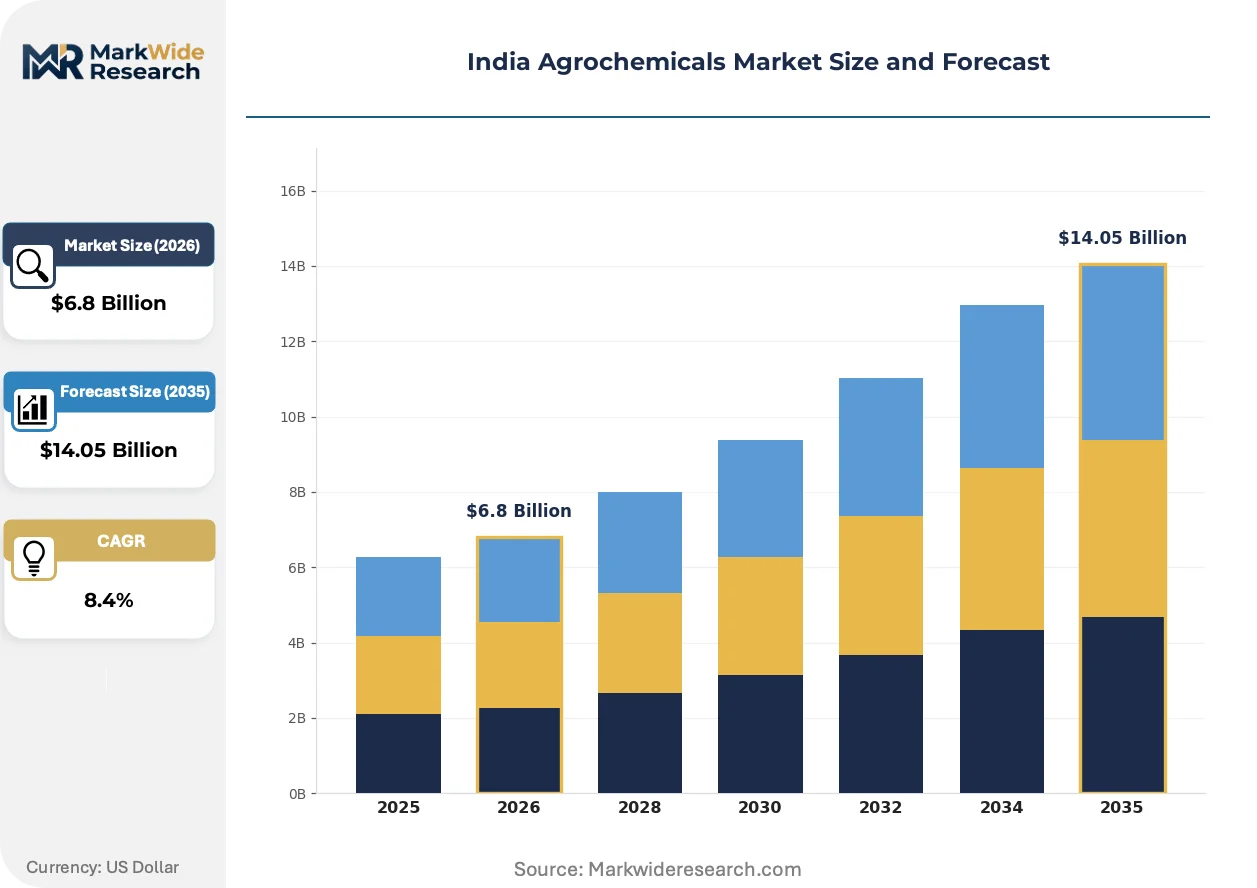
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Bio-Pesticides End Use Industry: Agriculture, Horticulture, Turf, Ornamental Application: Crop Protection, Soil Treatment, Seed Treatment, Post-Harvest Formulation: Granular, Liquid, Powder, Emulsifiable Concentrate |
| Companies Covered | UPL, Bayer CropScience Limited, Syngenta India Private Limited, BASF SE, ADAMA, Dhanuka Agritech Ltd., PI Industries Limited, Sumitomo Chemical India Ltd., Indofil Industries Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Agrochemicals Market Shifts & Advancements
Digital extension services and biological formulation advances are converging to alter how Indian farmers access crop protection advice and products, reducing reliance on traditional dealer-led recommendation models.
Drone-based pesticide application is virtualizing field-level spraying operations across Maharashtra and Gujarat cotton belts. Large landholding farmers and custom hiring service providers are deploying unmanned aerial systems for targeted herbicide and insecticide delivery. This technology is virtualizing the labor-intensive manual spraying infrastructure that has dominated Indian agriculture for decades, compressing application windows and reducing operator exposure risks.
The Central Insecticides Board's draft guidelines on drone-based pesticide use are creating regulatory clarity for aerial application services. State agriculture departments in Gujarat and Telangana are integrating unmanned aerial system permits into existing extension programs. Cotton and sugarcane growers in western India are the most affected, with cooperatives retrofitting procurement criteria to include aerial-capable service providers.
Farmer producer organizations are consolidating chemical procurement through digital platforms and direct manufacturer negotiations. Dealer networks in Punjab and Haryana are losing volume to FPO-led bulk purchasing, with price transparency apps enabling real-time comparison across formulations. This disintermediation is most visible in paddy and wheat belts where land consolidation has enabled collective bargaining at scale.
India Agrochemicals Market Segmentation
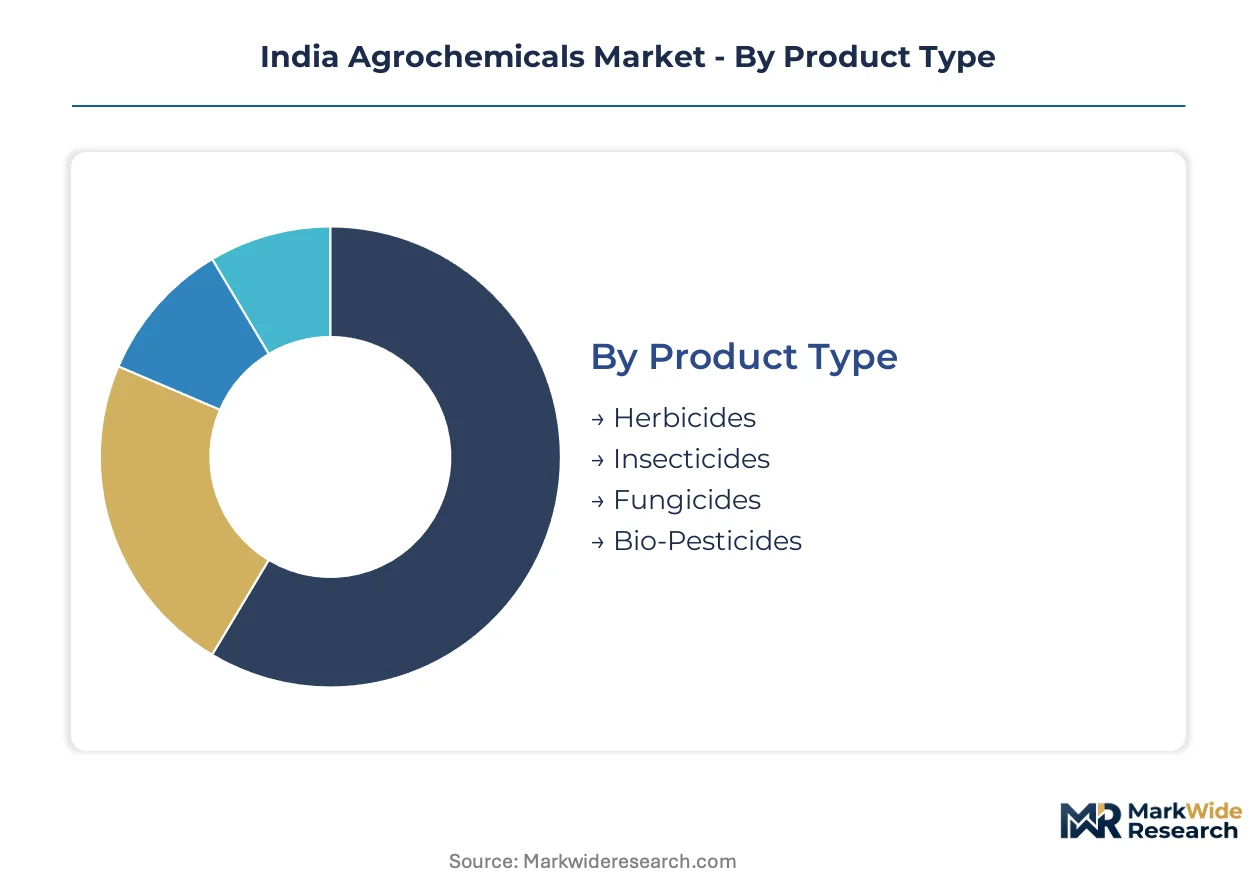
Segmentation in Indian agrochemicals reveals how product chemistry, crop system, and delivery format intersect with state-level farming intensity. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer prioritization.
Product Type:
Cost tier separation across synthetic and biological chemistries determines margin structure and capital requirements for domestic manufacturers.
- Herbicides:These formulations contain active ingredients such as glyphosate, pendimethalin, and 2,4-D designed for selective or non-selective weed control. Demand clusters in Punjab and Haryana rice-wheat systems where labor scarcity forces chemical substitution for manual weeding operations.
- Insecticides:Synthetic pyrethroids, neonicotinoids, and organophosphates target lepidopteran and sucking pest complexes in cotton and vegetable crops. Maharashtra and Gujarat cotton belts drive volume as bollworm pressure necessitates repeated seasonal applications.
- Fungicides:Azole and strobilurin-based protectants manage rusts, blights, and mildews in humid tropical zones.
- Bio-Pesticides:Microbial formulations from Bacillus thuringiensis, Trichoderma, and neem derivatives serve Karnataka and Madhya Pradesh organic export clusters seeking residue-free certification for European retail channels.
Herbicides hold installed capacity. Bio-Pesticides is rotating up the share rankings.
End Use Industry:
Application intensity varies by crop value per hectare and irrigation dependence across India's agro-climatic zones.
- Agriculture:Broad-acre cereal, oilseed, and fiber crops on 140 million hectares constitute the volume foundation. Telangana and Andhra Pradesh rice systems generate repeat purchases through kharif and rabi season cycles.
- Horticulture:High-value fruit and vegetable production in Maharashtra, Karnataka, and Himachal Pradesh commands premium fungicide and insecticide formulations with shorter pre-harvest intervals.
- Turf:Golf courses, cricket stadiums, and urban landscaping in Delhi NCR and Bengaluru metro areas require specialized growth regulators and selective herbicides.
- Ornamental:Commercial floriculture in Tamil Nadu and West Bengal greenhouse clusters drives niche acaricide and systemic insecticide demand for export rose and chrysanthemum production.
Agriculture anchors volume throughput. Horticulture is climbing the fastest on value per hectare metrics.
Application:
Timing relative to crop phenology determines formulation specifications and service bundling opportunities for manufacturers.
- Crop Protection:Foliar sprays and soil drenches applied during vegetative and reproductive growth stages dominate the addressable spend. Gujarat cotton and Maharashtra sugarcane operations account for disproportionate insecticide and herbicide consumption.
- Seed Treatment:Fungicide and insecticide coatings applied to hybrid seeds before planting capture margin pools through proprietary bundling with Bayer and Syngenta genetics programs in Karnataka and Telangana.
- Soil Treatment:Fumigants and nematicides address root-knot and wilt complexes in protected cultivation.
- Post-Harvest:Storage protectants and surface treatments extend shelf life for potato, onion, and mango cold chain operations.
Crop Protection commands the largest application footprint. Seed Treatment is gaining share fastest through hybrid seed penetration.
Formulation:
Physical state dictates manufacturing asset configuration, logistics cost, and farmer handling requirements in last-mile distribution.
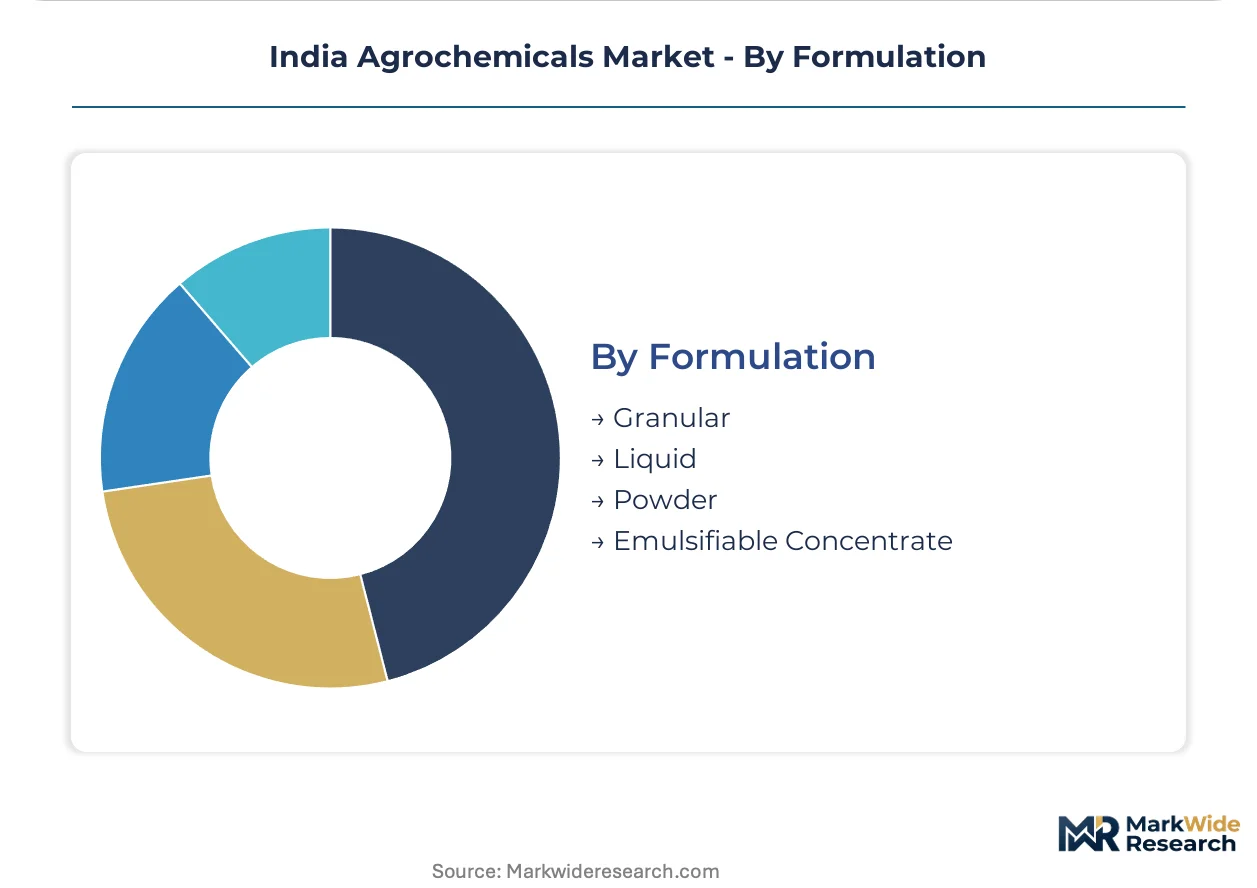
- Liquid:Suspension concentrates and soluble liquids enable precise dosing and tank-mix compatibility for drone-based application services expanding across Maharashtra cotton zones. Water-based carriers reduce dust exposure during handling.
- Granular:Controlled-release formulations for soil application in rice nurseries and sugarcane planting provide labor-efficient basal dressing options in Tamil Nadu and Uttar Pradesh.
- Powder:Wettable powders and dusts serve smallholder vegetable producers with limited spraying equipment access.
- Emulsifiable Concentrate:Oil-based solutions with surfactant systems penetrate waxy leaf surfaces in orchard crops.
Liquid formulations hold installed capacity. Granular is rotating up the share rankings on labor efficiency demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Punjab commands premium pricing for herbicide-intensive rice-wheat systems while Maharashtra extracts margin advantages from cotton-focused insecticide demand. This pricing-power asymmetry reflects irrigation dependence, labor scarcity gradients, and state-level subsidy structures across India's agro-climatic zones.
Maharashtra
Cotton bollworm pressure drives repeated seasonal insecticide applications across the Vidarbha and Marathwada belts. The state agriculture department integrates unmanned aerial system permits into extension programs, accelerating drone-based spraying adoption. Nagpur and Aurangabad host formulation packaging clusters serving western India distribution networks.
Gujarat
Hybrid seed programs in the Saurashtra region generate bundled fungicide and insecticide coatings for cotton and groundnut crops. DGFT export incentive structures support technical-grade production investments under the PLI scheme. Anand and Vadodara concentrate seed treatment formulation facilities supplying domestic and African markets.
Punjab
Rising agricultural wages in the rice-wheat belt force rapid herbicide substitution for manual weeding operations. FSSAI residue monitoring on basmati exports tightens application timing protocols for farmers. Ludhiana and Jalandhar anchor northern India distribution hubs with direct rail connectivity to port terminals.
Karnataka
Organic export clusters in the Malnad region adopt bio-pesticide protocols for residue-free coffee and spice certification. BIS formulation quality standards create compliance barriers for unorganized microbial manufacturers. Bangalore and Mysore host biological research facilities developing Trichoderma and Bacillus thuringiensis formulations.
Telangana
Farmer producer organizations in the Godavari delta consolidate chemical procurement through digital platforms, disintermediating traditional dealer networks. State agriculture department drone pilots target paddy and cotton zones for precision application demonstrations. Hyderabad anchors southern India logistics coordination for multinational formulation supply.
India Agrochemicals Market Competitive Landscape
Integrated technical-grade producers and pure-play formulation specialists split the market along capital intensity lines. The vendor base concentrates around three strategic tiers: multinational patent-holders with hybrid seed bundling capabilities, domestic backward-integrated manufacturers capturing PLI scheme benefits, and regional formulation specialists competing on price-accessible generics. Dominant competitive moves include capacity expansion in technical-grade actives and strategic partnerships with farmer producer organizations for direct procurement channels.
Within the multinational tier, Bayer CropScience Limited and Syngenta India Private Limited exemplify patent-protected positioning through specialized high-value crop solutions. Among domestic integrated manufacturers, UPL leverages extensive distribution networks for deep village-level penetration, while Dhanuka Agritech Ltd. occupies a position in mass-market cereal segments through price-accessible formulations. PI Industries Limited represents the technical-grade investment wave, with domestic synthesis capacity aligning with PLI scheme incentive structures.
| Leading Market Players |
|---|
| UPL |
| Bayer CropScience Limited |
| Syngenta India Private Limited |
| BASF SE |
| ADAMA |
| Dhanuka Agritech Ltd. |
| PI Industries Limited |
| Sumitomo Chemical India Ltd. |
| Indofil Industries Limited |
| Others |
Supply & Pricing Matrix
Chinese technical-grade import dependency compresses margin structures across formulation tiers while amplifying price volatility exposure for domestic manufacturers. This single-source vulnerability forces Indian producers to absorb tariff fluctuations into tiered pricing spreads or sacrifice volume share to multinational patent-holders with captive synthesis capacity.
Pricing Analysis
The customization-premium spread separates proprietary seed-treatment bundling from generic foliar formulations. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FSSAI residue-compliant products commanding spreads over unregistered alternatives. Cost compression in economy generics intensifies as dealer networks disintermediate under FPO pressure. Smallholder cereal farmers in Bihar and Uttar Pradesh exhibit highest price sensitivity, while export-oriented horticulture operators in Karnataka absorb premium fungicide pricing for residue-free certification.
Supply Chain Analysis
Extended payment terms from formulation specialists to dealer networks finance working capital gaps across the kharif-rabi seasonality. Active ingredient synthesis concentrates in China, with supplementary technical-grade capacity in India and Vietnam. Key inputs span chlorinated intermediates, phosphorus derivatives, and solvent carriers. Single-source vulnerability from Chinese chemical manufacturers exposes margins to tariff volatility and supply disruptions. Distribution runs through state-level depots to village-level dealer counters, with FPO platforms emerging as direct procurement alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indian agrochemicals represent an early-cycle expansion story as drone-based application infrastructure penetrates cotton and sugarcane belts, compressing labor constraints and opening precision-chemistry service models.
For Market Incumbents: Insulate technical-grade margins through backward integration into domestic synthesis capacity aligned with PLI scheme incentives. Secure dealer loyalty against FPO disintermediation by embedding digital extension services that replicate agronomic advice previously delivered through personal relationships. Patent cliff exposure from glyphosate resistance management demands accelerated R&D into novel herbicide modes.
For New Entrants and Emerging Players: Eastern India's underpenetrated rice-wheat systems in Odisha and West Bengal offer white-space expansion with limited incumbent distribution density. Bio-pesticide protocols for organic export clusters in Madhya Pradesh present certification-barrier entry points against synthetic incumbents. Direct-to-FPO digital platforms bypass capital-intensive dealer network replication.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors technical-grade specialists with PLI-aligned capacity expansion. Long-term viability hinges on synthesis asset control rather than formulation branding alone. Watch drone-application permit acceleration by state agriculture departments as inflection signal for precision-chemistry service model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical-Grade Synthesis | PLI scheme incentives redirect capital toward domestic active ingredient production, reducing Chinese import exposure. |
| Seed Treatment Bundling Partnerships | Hybrid seed companies in Gujarat capture margin pools through proprietary fungicide-insecticide coating integration. |
| Drone Application Service Infrastructure | Maharashtra cotton cooperatives retrofit procurement criteria to include aerial-capable service providers. |
| Bio-Pesticide Certification Investment | Madhya Pradesh organic clusters access residue-free premiums through European retail channel compliance. |
| FPO Direct Procurement Platform Development | Telangana farmer organizations consolidate chemical purchases through digital manufacturer negotiations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Central Insecticides Board registration databases, DGFT trade statistics, and FSSAI residue monitoring reports. Interviews with formulation plant managers, dealer network operators, state agriculture extension officers, and FPO procurement coordinators informed demand-side validation. Customs data on technical-grade imports and SEC filings of listed manufacturers provided supply-side triangulation. Bottom-up volume estimates from state-level consumption patterns were cross-checked against top-down market sizing from production capacity analysis.
Forecast inputs incorporate product type segmentation, crop system intensity, formulation format adoption, and regional irrigation dependence across the projection horizon. Modeled dimensions span herbicide-insecticide-fungicide-biopesticide chemistry tiers, agriculture-horticulture-turf-ornamental end uses, and liquid-granular-powder-emulsifiable concentrate physical states. CAGRs derive from trend extrapolation of PLI scheme capacity buildout, labor substitution rates in rice-wheat belts, and drone permit issuance velocity by state regulators.
The forecast holds incumbent behavior within observed patterns; aggressive technical-grade investment by multinational patent-holders or sudden Chinese export restriction would shift outcomes. Macroeconomic stress on smallholder credit access, regulatory acceleration of drone-based application guidelines, or gene-edited crop compatibility rulings would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
South Africa Agrochemicals Market
Agrochemicals
Agrochemical Active Ingredients Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
Canada Agrochemicals Market
Agrochemicals
Australia Agrochemicals Market
Agrochemicals
Global Buprofezin Market
Agrochemicals
Potassium Humate Market
Agrochemicals
Middle East and Africa Plant Growth Regulators Market
Agrochemicals
Indonesia Agrochemicals Market
Agrochemicals
Africa Agrochemicals Market
Agrochemicals
Superphosphates Market
Agrochemicals
Mexico Agrochemicals Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
South America Agrochemicals Market
Agrochemicals
Egypt Agrochemicals Market
Agrochemicals
Malaysia Agrochemicals Market