
 Mexico Agrochemicals Market | 2026-2036
Mexico Agrochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Agrochemicals Market Foresight
The capital-intensity divergence between integrated multinationals and local distributors is unwinding traditional channel hierarchies in Mexico's agrochemical sector. BASF SE leverages its Ludwigshafen-based active ingredient synthesis network to supply Mexican formulators directly, bypassing import-layer markups. Yara International ASA anchors its position through captive nitrate capacity at Progreso and dedicated logistics corridors serving the Yucatán Peninsula's horticulture clusters. UPL Limited competes via its India-rooted generic manufacturing scale, offering cost-optimized alternatives to patented molecules in the country's northern grain states.
Mexico agrochemicals comprise synthetic and biological crop protection agents, soil amendments, and plant nutrition products formulated for agricultural productivity enhancement, with active ingredients typically concentrated between 10 and 50 percent by weight depending on application mode and target pest spectrum. Herbicides dominate product-type revenue due to established glyphosate-tolerant soybean and corn rotations across Tamaulipas and Sonora, though biopesticides are gaining fastest traction among organic-certified berry exporters in Michoacán. Foliar spray remains the principal application method for high-value protected vegetables, while soil treatment expands in precision-irrigated tomato operations where root-knot nematode pressure demands pre-plant incorporation.
COFEPRIS registers and evaluates all pesticide formulations under Mexico's Federal Law on Plant Health, while SADER enforces NOM-003-SAG/FITO residue thresholds that determine market access for treated produce entering domestic retail and export channels. The Secretariat of Environment and Natural Resources (SEMARNAT) additionally mandates ecological risk assessments for new active ingredient introductions, lengthening registration timelines but filtering out environmentally persistent chemistries. Stakeholders must monitor pending revisions to Mexico's biocide regulatory alignment with US EPA tolerance harmonization protocols, as divergence would fracture cross-border agricultural supply chains and force dual formulation strategies.
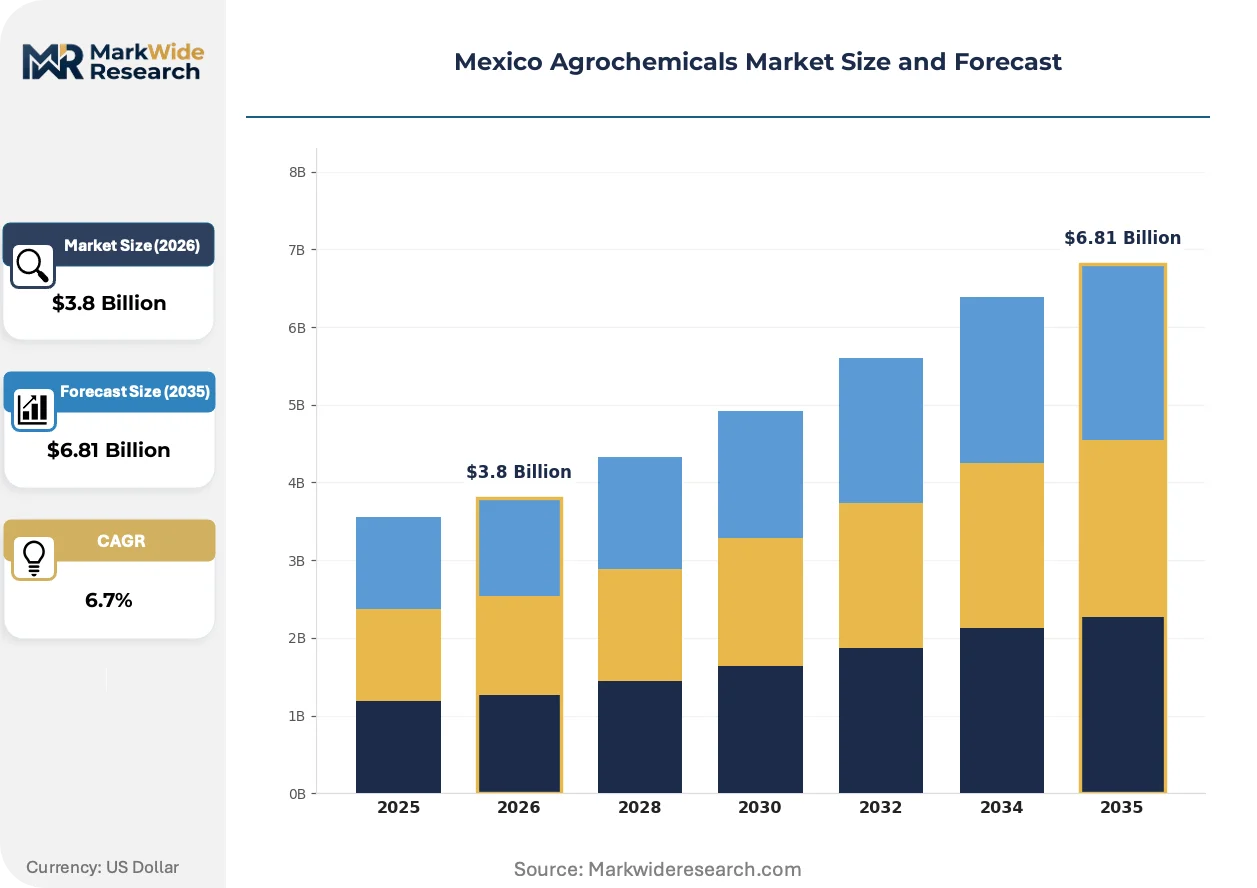
Market Dynamics
COFEPRIS residue limit enforcement is decomposing conventional high-dose formulation strategies across Mexico's vegetable belt, forcing rapid chemistry pivots toward micro-encapsulated and biological alternatives.
Growth Catalysts
- Precision irrigation penetration:Drip-fertigation systems in Guanajuato and Sinaloa create built-in demand for water-soluble chemistries and fertigation-compatible biologicals.
- NOM-003-SAG/FITO alignment pressure:Tighter maximum residue limits for export-bound produce push formulators toward lower-dose, higher-efficacy molecule development.
- Organic certification expansion:Michoacán's berry export sector drives biopesticide adoption as growers seek EU and US market access compliance.
Market Restraints
- Active ingredient import dependency:Mexico relies on Chinese and Indian synthesis capacity for generic herbicide intermediates, exposing formulators to shipping cost volatility and currency fluctuation.
- Registration timeline friction:SEMARNAT ecological risk assessments extend new molecule approval cycles, delaying product launches versus competitor markets with streamlined pathways.
- Glyphosate substitution pressure:Judicial and consumer scrutiny of conventional herbicides accelerates demand for alternatives before cost-competitive replacements reach scale.
Strategic Opportunities
- Yucatán Peninsula horticulture clusters:Dedicated logistics corridors and captive nitrate capacity create integrated supply positions for peninsula-bound fertilizer and crop protection bundles.
- Drone application services:Aerial precision spraying penetrates row-crop segments in Sonora and Tamaulipas where labor costs and terrain favor mechanized coverage.
- Biostimulant regulatory harmonization:Pending biocide alignment with US EPA tolerance protocols would enable single-formulation strategies for cross-border agricultural supply chains.
Industry Challenges
- Technical agronomist scarcity:Precision application programs require trained personnel for prescription mapping and variable-rate calibration, skills concentrated in Jalisco and Sinaloa while northern grain states face gaps.
- Legacy channel reconfiguration:Direct manufacturer-to-cooperative supply relationships disrupt traditional distributor networks, forcing inventory and credit restructuring among regional agrochemical wholesalers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Agrochemicals Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Biopesticides End Use Industry: Crops, Turf & Ornamental, Aquatic, Forestry Application Method: Foliar Spray, Soil Treatment, Seed Treatment, Granular Application Packaging Type: Bulk, Bags, Jars, Bottles |
| Companies Covered | BASF SE, Corteva Inc., Bayer AG, ADAMA Ltd., FMC Corporation, Syngenta Crop Protection AG, Yara International ASA, Sumitomo Chemical Co., Ltd., UPL Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Agrochemicals Market Shifts & Advancements
Biological formulation science and digital application infrastructure are converging to reshape product development priorities and field-level execution across Mexico's diverse cropping systems.
RNA interference-based biopesticides are decomposing the traditional binary between synthetic chemistry and biological efficacy. Protected vegetable growers in Querétaro and Puebla pilot these precision-targeted molecules against lepidopteran pests. The technology compresses development timelines for resistance management while enabling residue-free harvest windows for export contracts.
SADER's pending biocide regulatory alignment with US EPA tolerance harmonization protocols is forcing dual-track formulation development. Domestic retail channels tolerate higher residue thresholds than export-bound operations. Formulators now maintain parallel product lines for Guanajuato's domestic tomato supply versus Michoacán's berry export clusters.
Cooperative procurement consortia in Chihuahua and Durango are consolidating input purchasing power across grain operations. These buying groups bypass traditional distributor markups through direct manufacturer negotiations. The shift compresses working capital cycles for formulators while concentrating price negotiation leverage among fewer decision-makers in Mexico's northern breadbasket states.
Mexico Agrochemicals Market Segmentation
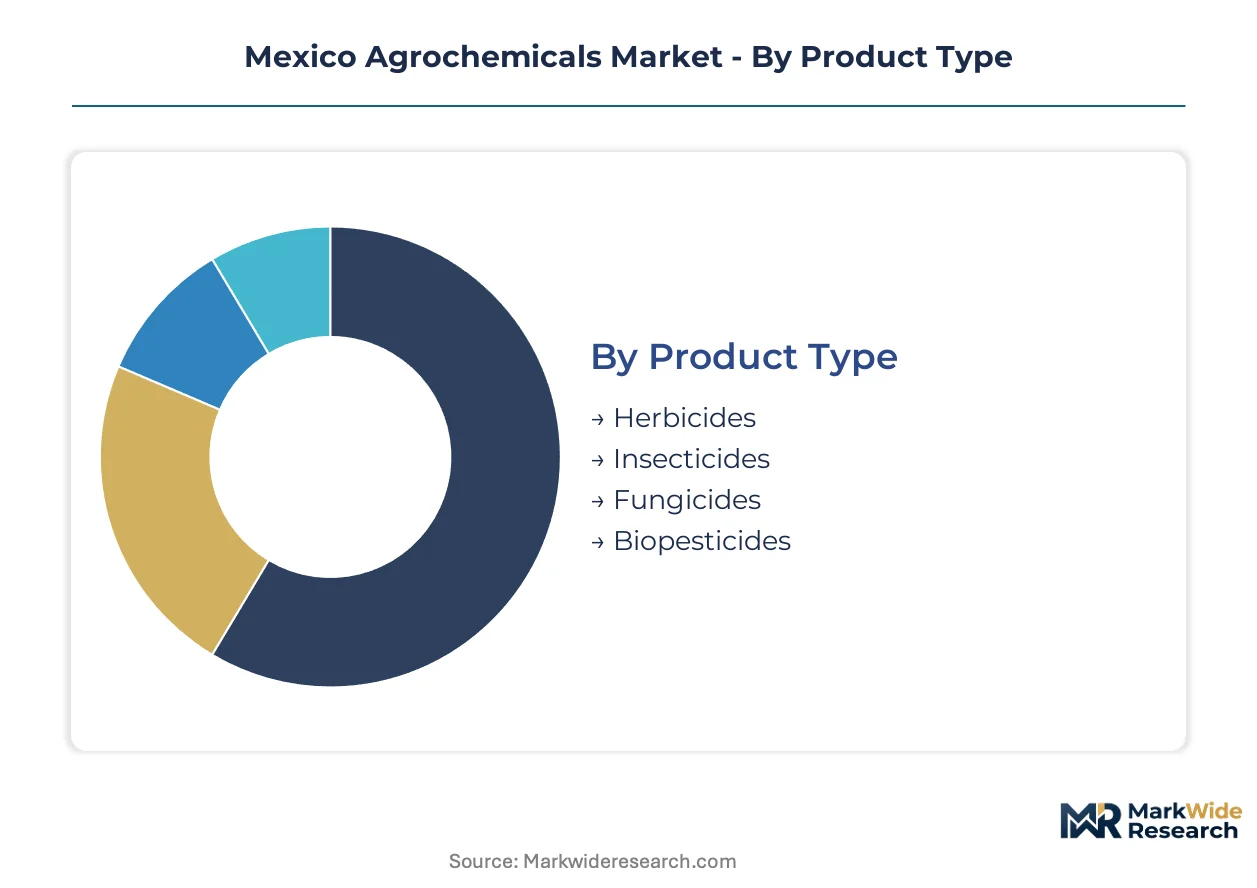
Segmentation in Mexico's agrochemical market reflects divergent regulatory pressures across COFEPRIS residue tiers and SADER enforcement zones. Product portfolios must align with both domestic retail tolerance thresholds and export-bound NOM-003-SAG/FITO compliance requirements.
Product Type:
COFEPRIS residue limit tiers split formulation strategies between conventional synthetics and biological alternatives, with registration pathways determining commercial viability in each segment.
- Herbicides:Glyphosate-tolerant soybean and corn rotations across Tamaulipas and Sonora anchor volume demand. Judicial scrutiny of conventional chemistries accelerates substitution programs before cost-competitive alternatives achieve scale.
- Insecticides:Neonicotinoid restrictions under SEMARNAT ecological assessments favor pyrethroid and biological pivots. Protected vegetable operations in Querétaro drive precision-targeted molecule adoption for lepidopteran control.
- Fungicides:Triazole and strobilurin chemistries dominate high-value protected crops. Michoacán's berry export clusters demand residue-free harvest windows that constrain synthetic selection.
- Biopesticides:RNA interference-based formulations and microbial agents gain traction among organic-certified operations. EU and US market access requirements for Michoacán berry exporters propel steepest expansion trajectory in this category.
Established volume favors herbicides; emerging adoption favors biopesticides.
End Use Industry:
Customer procurement patterns diverge between consolidated cooperative buyers in grain belts and fragmented specialty crop operations requiring technical support.
- Crops:Field corn, soybean, and wheat operations in Chihuahua and Durango consolidate through cooperative procurement consortia. These buying groups bypass traditional distributor markups through direct manufacturer negotiations.
- Turf & Ornamental:Golf course and landscape maintenance segments in Jalisco and Nuevo León demand aesthetic-performance chemistries with minimal environmental persistence. Municipal water quality regulations constrain runoff-prone formulations.
- Aquatic:Algaecide and aquatic weed control applications serve irrigation reservoir management and aquaculture operations. SEMARNAT ecological risk assessments extend registration timelines for water-body chemistries.
- Forestry:Pine plantation protection in Durango and Chihuahua requires long-residual soil treatments against bark beetle pressure. SADER phytosanitary enforcement drives preventive application protocols.
Revenue concentration sits with crops; margin expansion potential concentrates in turf and ornamental.
Application Method:
Equipment infrastructure and labor availability determine method selection across Mexico's heterogeneous terrain and farm scale distribution.
- Foliar Spray:High-volume ground application dominates row-crop segments where equipment penetration is mature. Drone services penetrate Sonora and Tamaulipas where labor costs and terrain favor mechanized coverage.
- Soil Treatment:Pre-plant incorporation expands in precision-irrigated tomato operations where root-knot nematode pressure demands targeted delivery. Guanajuato's intensive vegetable belt leads adoption.
- Seed Treatment:Systemic protection of germinating seedlings reduces early-season foliar applications. Northern grain states favor this method for cost efficiency at planting.
- Granular Application:Slow-release formulations serve perennial crops and soil amendment integration. Yucatán Peninsula horticulture clusters utilize captive nitrate capacity through this delivery mode.
Operational scale favors foliar spray; precision agriculture transition favors soil treatment.
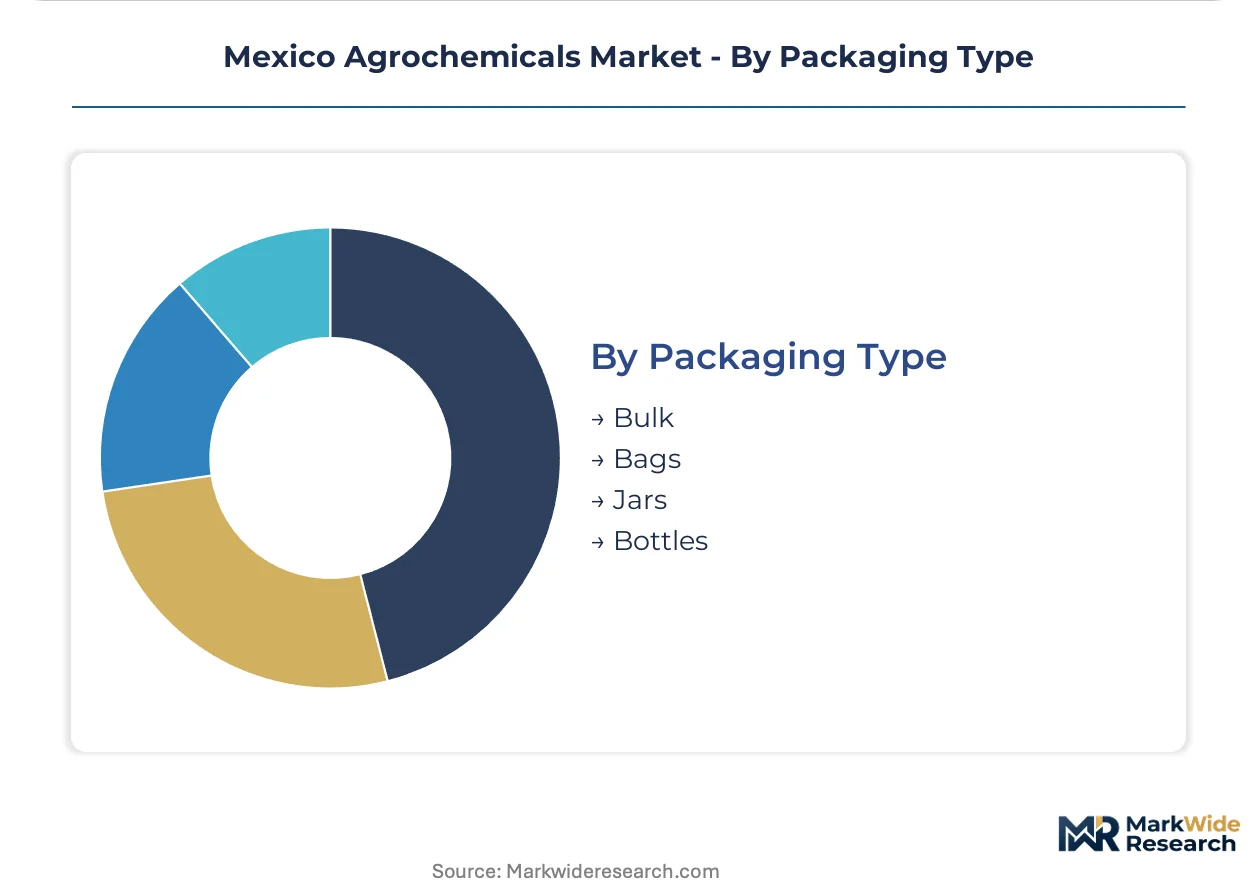
Packaging Type:
Channel restructuring between direct manufacturer supply and legacy distributor networks reshapes packaging requirements and unit economics.
- Bulk:Cooperative procurement consortia in northern grain states drive tanker and tote demand for direct-to-farm delivery. Working capital compression favors larger unit sizes.
- Bags:Water-soluble and granular formulations for drip-fertigation compatibility dominate Sinaloa and Jalisco specialty crop segments. Precision application programs require calibrated packaging.
- Jars:Small-volume biological and specialty formulations serve protected vegetable operations with limited acreage. Retail channel presence maintains this format.
- Bottles:Convenience packaging for spot treatments and homeowner segments persists in peri-urban markets. COFEPRIS labeling requirements increase compliance costs for smaller units.
Channel consolidation favors bulk; specialty crop fragmentation sustains jars.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Sinaloa and Jalisco specialty crop belts, while northern grain states face margin compression from cooperative procurement consolidation. This asymmetry reshapes regional investment priorities across Mexico's agrochemical value chain.
Sinaloa
Precision application programs for protected vegetables and berries drive water-soluble chemistry demand. COFEPRIS residue limit enforcement under NOM-003-SAG/FITO pushes formulators toward micro-encapsulated alternatives. The Culiacán-Mazatlán corridor anchors specialty crop exports to US and EU markets.
Jalisco
Turf and ornamental segments in Guadalajara metro area demand aesthetic-performance chemistries with minimal environmental persistence. Municipal water quality regulations constrain runoff-prone formulations. Puerto Vallarta's golf course maintenance clusters favor slow-release granular applications.
Bajío Region
Guanajuato's intensive vegetable belt leads drip-fertigation integration, displacing conventional broadcast methods. SADER phytosanitary enforcement tightens maximum residue limits for domestic retail channels. Irapuato-Salamanca tomato operations drive pre-plant soil treatment adoption for root-knot nematode management.
Northern Border States
Chihuahua and Durango grain operations consolidate through cooperative procurement consortia, bypassing traditional distributor markups. Currency fluctuation exposure from Chinese and Indian active ingredient imports pressures formulator margins. Ciudad Juárez and Torreón anchor glyphosate-tolerant soybean and corn rotations.
Yucatán Peninsula
Captive nitrate capacity at Progreso creates integrated supply positions for peninsula-bound fertilizer bundles. Dedicated logistics corridors serve emerging horticulture clusters in Campeche and Yucatán states. Mérida's protected vegetable expansion drives demand for fertigation-compatible biologicals.
Mexico Agrochemicals Market Competitive Landscape
Concentration sits with integrated multinationals possessing captive synthesis capacity and direct-to-farm distribution networks. Three archetypes dominate: German and Swiss conglomerates with Ludwigshafen- or Basel-based active ingredient manufacturing, Indian generic specialists leveraging cost-optimized scale, and Nordic fertilizer-crop protection integrators with captive raw material positions. Competitive moves center on backward integration into synthesis capacity and strategic bypass of traditional import-layer markups through direct manufacturer-to-cooperative relationships.
Among European-headquartered conglomerates, BASF SE and Bayer AG exemplify the integrated archetype with in-house active ingredient production networks. Yara International ASA anchors the Nordic integration model through captive nitrate capacity and dedicated logistics infrastructure. UPL Limited represents the India-rooted generic manufacturing scale that competes on cost-optimized alternatives to patented molecules. These three occupy positions spanning synthesis depth, geographic reach, and price-point segmentation across Mexico's divergent regional demand profiles.
| Leading Market Players |
|---|
| BASF SE |
| Corteva Inc. |
| Bayer AG |
| ADAMA Ltd. |
| FMC Corporation |
| Syngenta Crop Protection AG |
| Yara International ASA |
| Sumitomo Chemical Co., Ltd. |
| UPL Limited |
| Others |
Supply & Pricing Matrix
Glyphosate substitution programs are simultaneously redrawing raw material sourcing maps from China and India toward European specialty synthesis hubs while compressing margin structures for Mexican formulators caught between import cost volatility and COFEPRIS-mandated formulation complexity upgrades.
Pricing Analysis
The customization-premium spread in Mexico's agrochemical market separates standard glyphosate-based formulations from residue-optimized micro-encapsulated alternatives demanded by Michoacán berry exporters. Pricing stratifies across premium, standard, and economy tiers with differentiation driven by COFEPRIS certification grade and drip-fertigation compatibility. Cost compression in the standard herbicide tier is intensifying because cooperative procurement consortia in Chihuahua and Durango consolidate bargaining power. Grain cooperatives exhibit highest price sensitivity while protected vegetable operations in Sinaloa absorb premiums for export-compliant chemistries.
Supply Chain Analysis
Port congestion at Veracruz and Lázaro Cárdenas and container availability constraints on Asia-Pacific trade lanes expose Mexican formulators to working capital compression from extended inventory cycles. Active ingredient supply concentrates in China and India for generic herbicide intermediates, with German and Swiss specialty synthesis capacity serving precision-chemistry demand. Formulation draws from glyphosate technical, neonicotinoid alternatives, and microbial fermentation inputs. Single-source vulnerability from Chinese intermediate dependency threatens supply continuity. Distribution runs through direct manufacturer-to-cooperative channels in northern grain states and legacy distributor networks serving fragmented specialty crop operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
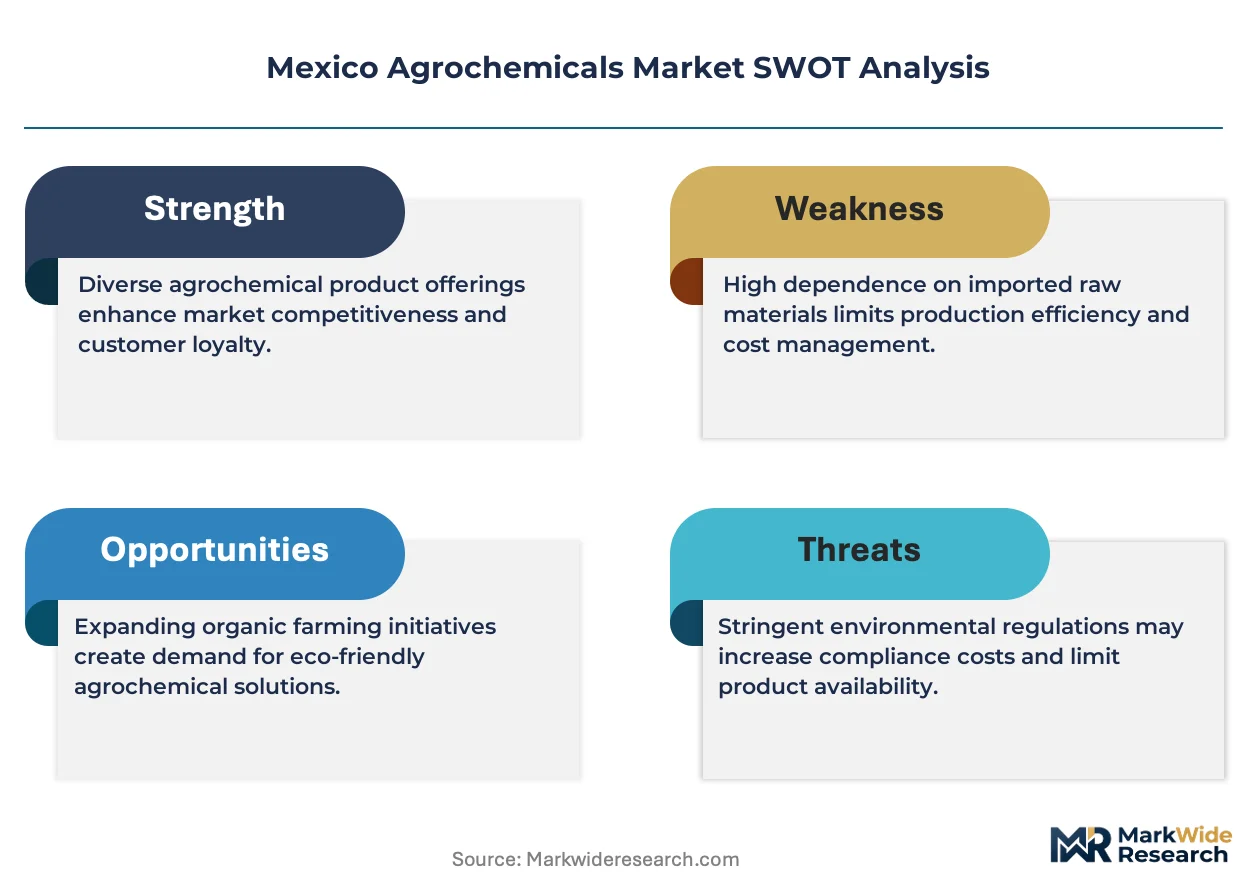
COFEPRIS residue tier fragmentation creates specialized formulation niches as export-bound operations diverge from domestic retail channels under divergent NOM-003-SAG/FITO enforcement intensity.
For Market Incumbents: Fortify backward integration into active ingredient synthesis through European specialty chemistry partnerships to offset Chinese import cost volatility. Deepen captive supply of micro-encapsulated formulation capacity in Guanajuato to serve precision-irrigation vegetable operations. SEMARNAT ecological risk assessment delays threaten first-mover advantages for new molecule introductions. For New Entrants and Emerging Players: Lead with drone application service platforms in Sonora and Tamaulipas row-crop segments where labor scarcity and terrain favor mechanized coverage. Target biopesticide formulation white space in Michoacán organic berry clusters where EU market access requirements outpace incumbent biological portfolios. Pursue cooperative procurement consortium direct relationships bypassing legacy distributor markups. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors integrated manufacturers with captive synthesis capacity and residue-optimized formulation expertise. Long-term viability over the next decade hinges on biocide alignment execution with US EPA tolerance harmonization protocols. Acquisition targets should demonstrate SADER registration track records and Yucatán Peninsula logistics corridor access. Watch pending NOM-003-SAG/FITO revision timing as inflection indicator for dual-formulation strategy requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Reduces Chinese intermediate dependency exposure for Mexican formulators facing currency fluctuation. |
| Micro-Encapsulated Formulation Capacity Expansion | Addresses COFEPRIS residue limit enforcement in Guanajuato drip-fertigation vegetable operations. |
| Drone Application Service Platform Launch | Captures labor-scarce row-crop segments in Sonora where terrain favors aerial precision spraying. |
| Biological Registration Pipeline Acceleration | Secures EU market access compliance for Michoacán organic berry export clusters ahead of competitors. |
| Yucatán Peninsula Logistics Corridor Development | Leverages Progreso captive nitrate capacity for integrated fertilizer-crop protection bundle distribution. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with SADER regulatory affairs officers, COFEPRIS registration specialists, cooperative procurement managers, and precision irrigation agronomists; and secondary validation through customs trade records, SEC filings of listed agrochemical manufacturers, COFEPRIS registration databases, and SADER phytosanitary enforcement reports. Bottom-up volume estimates from state-level crop protection consumption patterns triangulated against top-down manufacturer revenue disclosures.
Across the analysis window, the forecasting framework modeled product type segmentation alongside application method infrastructure penetration, end-use cooperative consolidation intensity, and regional regulatory enforcement tier differentiation. CAGRs derived from historical trajectory analysis adjusted for NOM-003-SAG/FITO alignment pressure and precision irrigation adoption curves. Key inputs included drip-fertigation installation rates in Guanajuato and glyphosate substitution program progression timelines.
Forecasts assume regulatory continuity in COFEPRIS registration pathways and SADER residue limit enforcement; material policy shifts including biocide divergence from US EPA protocols would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
Agrochemical Market
Agrochemicals
Canada Agrochemicals Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
Potassium Humate Market
Agrochemicals
Indonesia Agrochemicals Market
Agrochemicals
Middle East and Africa Plant Growth Regulators Market
Agrochemicals
South America Agrochemicals Market
Agrochemicals
Agrochemical Active Ingredients Market
Agrochemicals
Africa Agrochemicals Market
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
India Agrochemicals Market
Agrochemicals
Superphosphates Market
Agrochemicals
Egypt Agrochemicals Market
Agrochemicals
Global Buprofezin Market
Agrochemicals
South Africa Agrochemicals Market
Agrochemicals
L-Glufosinate Ammonium Market