
 Malaysia Agrochemicals Market | 2026-2036
Malaysia Agrochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Agrochemicals Market Foresight
China's agrochemical manufacturing expansion is reconfiguring supply dynamics for Malaysian distributors and formulators. Bayer AG leverages its herbicide portfolio to sustain brand loyalty among oil palm growers across the peninsula. Syngenta Group anchors its position through integrated crop protection solutions tailored to tropical conditions. UPL Limited competes on generic pricing while extending its reach into East Malaysian states through local distributor partnerships.
Agrochemicals comprise synthetic and biological substances formulated to protect crops, enhance yields, and manage pests, weeds, and diseases through active ingredients typically measured in grams per hectare application rates. These inputs serve commercial agriculture by preserving output quality and reducing pre-harvest losses across monoculture and diversified farming systems. Herbicides dominate product type revenue due to oil palm's intensive weed management requirements, while insecticides represent the fastest-growing category as fall armyworm and bagworm pressures intensify. The farmer end-user segment controls the largest volume channel, though agriculture cooperatives concentrate bargaining power and increasingly negotiate direct procurement terms with manufacturers.
BIS standards alignment and the Department of Agriculture's Pesticides Board registration protocols shape product approval timelines and active ingredient eligibility for Malaysian entry. The Environmental Quality Act and evolving EU-equivalent residue standards for palm oil exports are forcing reformulation investments among suppliers serving the sector. Stakeholders must monitor regulatory divergence between domestic tolerance levels and destination market requirements to avoid trade access disruptions.
Market Dynamics
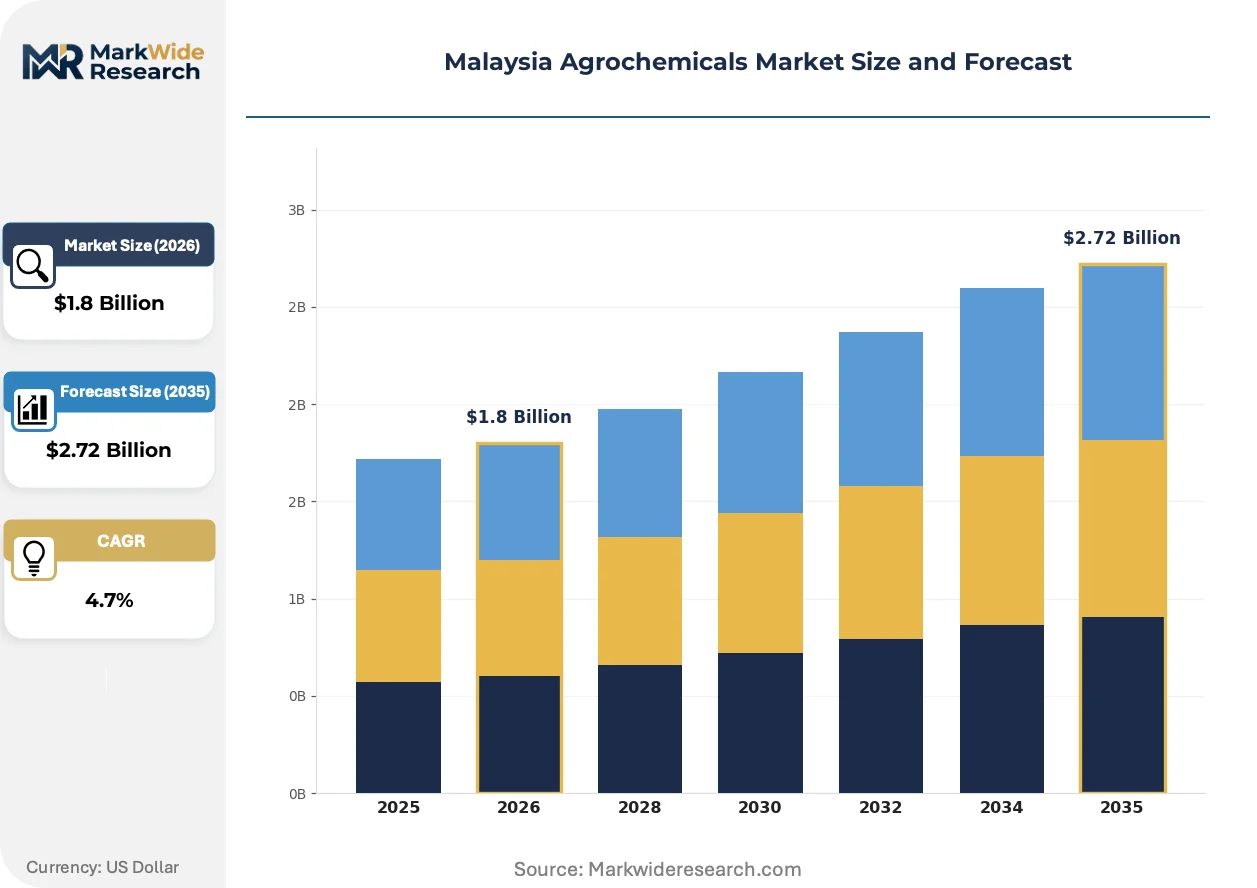
Malaysia's agrochemicals sector operates under tightening residue standards for palm oil exports to the EU, forcing active ingredient substitution and reformulation investments across the supply base. This regulatory compression intersects with rising Chinese manufacturing capacity to reshape procurement economics for Malaysian distributors.
Growth Catalysts
- EU Deforestation Regulation compliance deadlines:Malaysian palm oil exporters accelerating integrated pest management adoption to meet traceability and residue thresholds, expanding biological input demand.
- Fall armyworm pressure in Peninsular Malaysia:Invasive pest spread through Johor and Pahang driving insecticide rotation requirements and technical advisory service attachment.
- Precision application technologies:Drone spraying services penetrating East Malaysian smallholder networks, reducing labor dependency and chemical runoff exposure.
Market Restraints
- Active ingredient import concentration:Over 60 percent of technical-grade inputs sourced from Chinese manufacturers, creating foreign exchange and supply continuity exposure.
- Department of Agriculture registration timelines:Pesticides Board evaluation periods extending 18-24 months for novel molecules, delaying product launch windows.
- Glyphosate substitution pressure:EU-equivalent residue limits forcing herbicide portfolio restructuring without proven tropical efficacy alternatives.
Strategic Opportunities
- Sarawak smallholder consolidation:State land development schemes aggregating fragmented plots into contract farming arrangements, creating centralized input procurement channels.
- Biopesticide registration fast-track:Department of Agriculture prioritizing microbial and botanical formulations under national sustainable agriculture roadmap.
- Digital agronomy platforms:Mobile-based pest identification and prescription services embedding e-commerce functionality for direct manufacturer-to-farmer transactions.
Industry Challenges
- Field agronomist shortage:Specialized tropical crop protection expertise concentrated among aging extension officers, constraining technical service scaling.
- Legacy formulation facility upgrades:Water-based and micro-encapsulation production lines requiring capital deployment to meet environmental discharge standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Agrochemicals Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pesticides, Herbicides, Fungicides, Insecticides Application: Crops, Fruits, Vegetables, Ornamental Plants End User: Farmers, Agriculture Cooperatives, Distributors, Retailers Distribution Channel: Direct Sales, Online Retail, Agricultural Stores, Wholesalers |
| Companies Covered | Hextar Group of Companies, Corteva, Inc., Bayer AG, UPL Limited, FMC Corporation, Syngenta Group, Ancom Nylex Berhad, ADAMA Ltd., BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Agrochemicals Market Shifts & Advancements
Digital infrastructure and biological formulation science are converging to displace conventional product-centric models across Malaysian agrochemical distribution. These shifts compress traditional advisory hierarchies while opening direct channel architectures.
Biological seed treatment formulations incorporating Trichoderma and Bacillus strains are virtualizing the preventive pest management category for oil palm nurseries. Large plantation groups in Selangor and Perak are piloting these applications across clonal seedling programs. This virtualization is compressing the historical reliance on soil-applied synthetic nematicides and redefining early-stage crop protection economics.
The Department of Agriculture's Pesticides Board has aligned maximum residue limit protocols with EU-equivalent standards for palm oil destined for European refineries. This regulatory convergence forces active ingredient withdrawals and accelerated re-registration cycles for legacy chemistries. Formulators serving the export-oriented plantation segment are prioritizing residue-compliant molecule portfolios over cost-optimized alternatives.
Cooperative procurement consolidation is restructuring input acquisition patterns across Peninsular Malaysia's central crop belts. Felda and Risda-linked farmer organizations are negotiating direct supply agreements with manufacturers, disintermediating traditional distributor networks. This concentration is most visible in Perak and Kedah, where paddy and oil palm cooperatives now control volume allocation decisions previously managed by independent retailers.
Malaysia Agrochemicals Market Segmentation
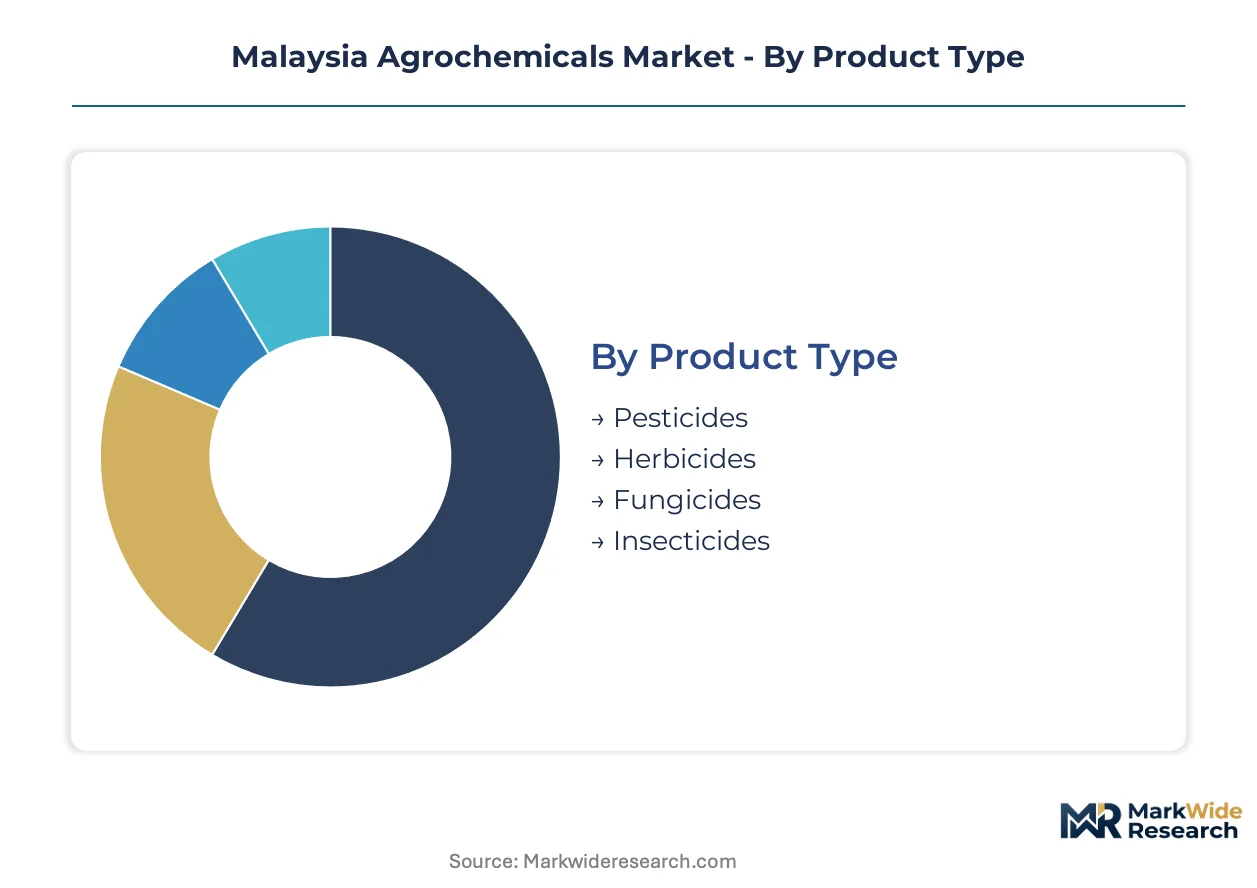
Malaysia's agrochemicals sector fragments across four structural dimensions that determine procurement patterns and margin capture. Product type dictates formulation complexity and regulatory scrutiny, while application scope and end-user concentration shape pricing power and channel economics.
Product Type:
Herbicides and insecticides turn inventory fastest due to seasonal pest pressure cycles, whereas fungicides and specialty pesticides move slower with disease-dependent demand spikes.
- Herbicides:Glyphosate-based and selective formulations dominate oil palm plantation procurement for understory weed management. Intensive weed control protocols across Selangor and Perak estates sustain repeat purchase frequency.
- Insecticides:Pyrethroid and neonicotinoid chemistries target fall armyworm and bagworm infestations with acute treatment windows. Johor and Pahang smallholders drive emergency procurement surges during outbreak peaks.
- Fungicides:Triazole and strobilurin active ingredients protect against basal stem rot and leaf spot diseases in perennial crops.
- Pesticides:Broad-spectrum synthetic and biological formulations address multi-pest complexes in diversified cropping systems.
Herbicides anchor the volume base while insecticides gain share at the steepest rate.
Application:
Cost tier stratification separates commodity crop protection from high-value horticultural inputs, with ornamental applications commanding premium pricing per hectare.
- Crops:Oil palm and paddy cultivation absorb the majority of agrochemical tonnage through scheduled preventive programs. Felda and Risda cooperative networks in Perak and Kedah centralize procurement for member smallholders.
- Fruits:Durian and pineapple production requires specialized fungicide and insecticide rotations for export-grade residue compliance. Peninsular Malaysia's tropical fruit belts prioritize pre-harvest interval management for China-bound shipments.
- Vegetables:Chili and leafy green cultivation in Cameron Highlands and other upland zones demands intensive pesticide application due to short cropping cycles.
- Ornamental Plants:Nursery and landscape operations in urban corridors around Kuala Lumpur and Johor Bahru utilize lower-volume, higher-margin specialty formulations.
Crop applications absorb the dominant procurement volume while fruit sector inputs expand most quickly under export quality pressures.
End User:
Customer type determines technical service intensity and price elasticity, with cooperatives consolidating bargaining power against fragmented retailer networks.
- Farmers:Individual smallholders and estate managers constitute the dispersed demand base with varying technical sophistication. East Malaysian states exhibit higher reliance on distributor advisory services due to extension officer shortages.
- Agriculture Cooperatives:Felda, Risda, and state land development authority affiliates negotiate direct manufacturer contracts. These entities now control volume allocation decisions previously managed through independent retail channels in Perak and Kedah.
- Distributors:Regional formulators and import agents manage technical-grade sourcing and local blending operations.
- Retailers:Independent agricultural supply shops serve last-mile access for unaffiliated smallholders across Peninsular Malaysia's central crop belts.
Farmers represent the largest user count while agriculture cooperatives capture procurement share fastest through consolidation.
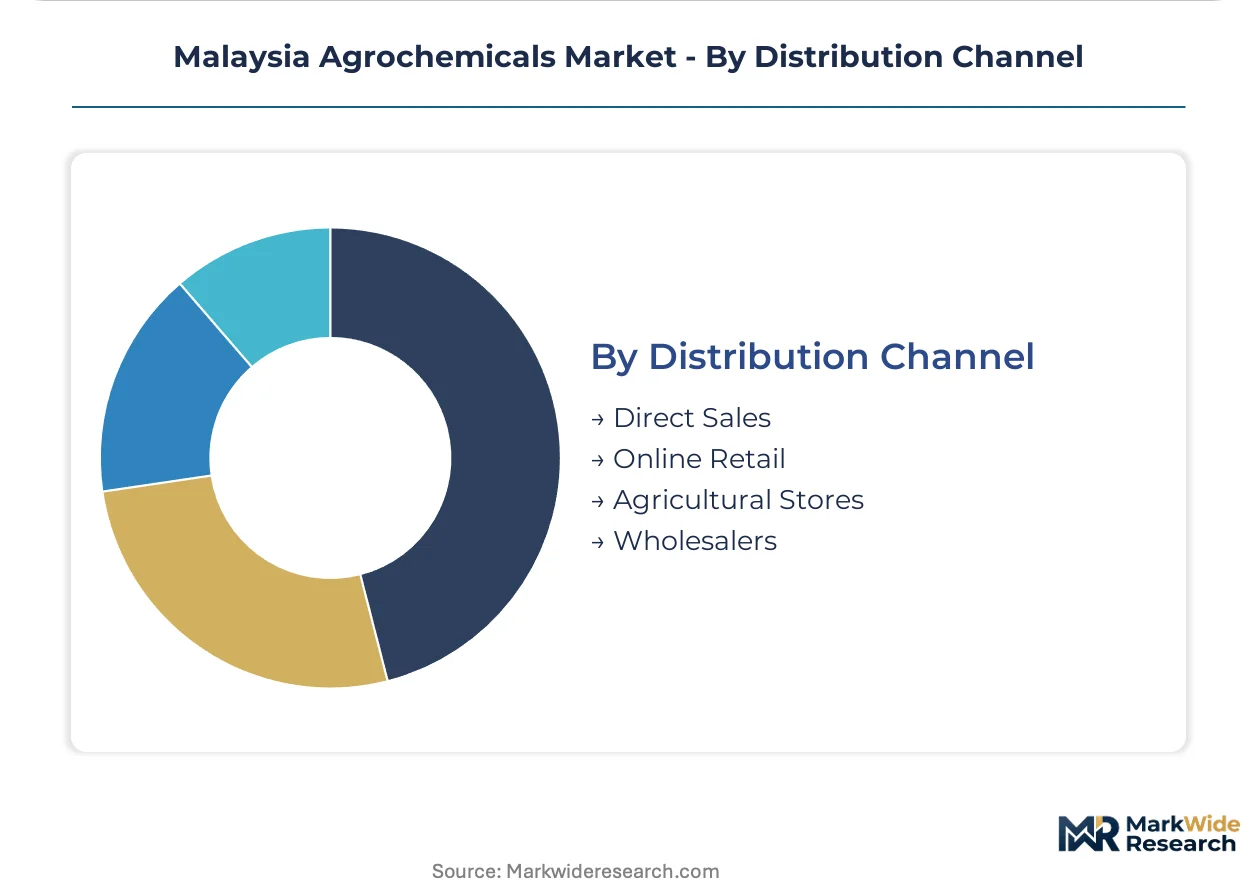
Distribution Channel:
Geography drives channel selection, with plantation concentration favoring direct sales and smallholder dispersion sustaining retail fragmentation.
- Direct Sales:Manufacturers and large formulators contract directly with plantation groups and cooperatives for bulk supply. Sarawak's emerging contract farming schemes through state land development programs are creating new direct procurement corridors.
- Wholesalers:Regional distributors aggregate demand across multiple districts and provide credit terms to smaller retailers. Chinese technical-grade supply concentration shapes wholesaler inventory risk and foreign exchange exposure.
- Agricultural Stores:Independent retail outlets maintain physical presence in district towns and farming communities.
- Online Retail:Mobile-based platforms and e-commerce functionality are embedding into digital agronomy services for manufacturer-to-farmer transactions.
Direct sales and wholesalers dominate volume flows while online retail climbs the fastest through platform-enabled advisory integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese technical-grade manufacturing concentrates supply leverage over Malaysian formulators, while domestic demand clusters in Peninsular Malaysia's plantation belts. The Department of Agriculture's Pesticides Board registration protocols create 18-24 month approval windows that shape product availability timelines.
Selangor
Oil palm estates and contract farming schemes in Kuala Selangor and Sabak Bernam drive herbicide and insecticide procurement volumes. The Department of Agriculture's extension services coordinate integrated pest management trials across Felda settlements. Large plantation groups in the Klang Valley corridor pilot precision spraying technologies through drone service partnerships.
Perak
Paddy cultivation in the Kerian and Tanjung Tualang irrigation schemes sustains fungicide demand for blast and sheath rot management. Risda cooperative networks negotiate direct manufacturer contracts for member smallholders. The state's northern crop belt around Kuala Kangsar hosts blending facilities serving cross-border demand into southern Thailand.
Pahang
Fall armyworm infestations across oil palm and maize plots in Jerantut and Raub trigger emergency insecticide procurement surges. The Department of Agriculture's pest surveillance units issue outbreak alerts that accelerate distributor inventory turns. Central Pahang's plantation concentration supports dedicated agronomist teams from major suppliers.
Johor
Durian export zones in Segamat and Kluang enforce pre-harvest interval compliance for China-bound shipments. The Department of Agriculture's residue monitoring program aligns with destination market standards. Southern Johor's proximity to Singapore refineries creates specialized supply chains for EU-compliant palm oil production.
Sarawak
State land development schemes in the Baram and Rajang basins aggregate fragmented smallholder plots into centralized procurement channels. The Department of Agriculture's regional offices prioritize biological input registration under the national sustainable agriculture roadmap. Emerging contract farming arrangements in Miri Division attract direct manufacturer presence bypassing Peninsular distributors.
Malaysia Agrochemicals Market Competitive Landscape
Integrated multinationals and regional formulators split the market along advisory intensity and price positioning vectors. The vendor base organizes into three strategic archetypes: patent-protected innovators bundling technical services, generic specialists competing on procurement economics, and domestic blenders leveraging regulatory familiarity and last-mile reach. Competitive moves concentrate on portfolio reformulation for residue compliance and cooperative direct contracting that disintermediates traditional distribution layers.
Within the integrated multinational tier, Bayer AG and Syngenta Group exemplify patent-protected positioning through tropical-adapted crop protection portfolios. UPL Limited occupies the generic specialist archetype with price-driven penetration into East Malaysian markets through distributor partnerships. Hextar Group of Companies and Ancom Nylex Berhad represent domestic blending capacity with formulation facilities aligned to Department of Agriculture registration pathways.
| Leading Market Players |
|---|
| Hextar Group of Companies |
| Corteva, Inc. |
| Bayer AG |
| UPL Limited |
| FMC Corporation |
| Syngenta Group |
| Ancom Nylex Berhad |
| ADAMA Ltd. |
| BASF SE |
| Others |
Supply & Pricing Matrix
The Port of Tanjung Pelepas freight corridor carries technical-grade active ingredients from Chinese manufacturers to Malaysian formulators, with container rates compressing margins at both ends of the value chain. This logistics backbone funnels over sixty percent of herbicide and insecticide inputs through a single gateway, amplifying foreign exchange exposure while downstream plantation buyers negotiate residue-compliant premiums against generic alternatives.
Pricing Analysis
The Department of Agriculture's Pesticides Board registration protocols dictate the pricing tier structure across Malaysian agrochemical distribution. Pricing stratifies across premium, standard, and economy tiers based on residue compliance certification and bundled technical advisory intensity. Cost compression in the standard tier is intensifying because Chinese generic manufacturers are expanding direct-to-distributor reach. Smallholder farmers in East Malaysian states exhibit the highest price sensitivity, while Felda and Risda cooperatives in Perak and Kedah leverage volume scale for least-sensitive procurement terms.
Supply Chain Analysis
Chinese technical-grade manufacturers including Jiangsu Yangnong Chemical and Zhejiang Wynca Chemical hold dominant contract-manufacturing capacity for pyrethroid and glyphosate intermediates. Malaysian formulators draw from this concentrated supply base while sourcing specialty solvents from India and packaging materials from Thailand. Single-source vulnerability runs through the Strait of Malacca chokepoint for containerized chemical shipments. Distribution runs through Peninsular Malaysia's wholesaler network with credit-extension functions, though cooperative direct contracting is displacing traditional retail layers in Selangor and Perak plantation belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's agrochemical sector sits in early-cycle expansion as biological input adoption accelerates under the national sustainable agriculture roadmap. This penetration tailwind creates asymmetric opportunity for portfolio repositioning ahead of EU Deforestation Regulation compliance deadlines.
For Market Incumbents: Entrench residue-compliant formulation leadership by accelerating Trichoderma and Bacillus biological seed treatment registrations through the Department of Agriculture's fast-track pathway. Backward integration into Chinese technical-grade sourcing through joint venture structures mitigates foreign exchange exposure while locking supply continuity. Defend against cooperative disintermediation by embedding digital agronomy platforms with e-commerce functionality directly into Felda and Risda procurement workflows. For New Entrants and Emerging Players: Sarawak's Baram and Rajang basin smallholder consolidation under state land development schemes offers the most penetrable geographic entry point. Target biological input categories prioritized under the national sustainable agriculture roadmap where registration timelines compress competitive response windows. Build go-to-market presence through direct manufacturer relationships with emerging contract farming arrangements in Miri Division, bypassing entrenched Peninsular distributor networks. For Investors and Strategic Acquirers: Domestic blending specialists with Department of Agriculture registration expertise and established East Malaysian distribution reach represent the highest-conviction acquisition archetype. Long-term viability hinges on biological formulation capability buildout and residue compliance infrastructure rather than synthetic chemistry scale. Watch for inflection when the Pesticides Board publishes accelerated re-registration timelines for legacy chemistries, signaling portfolio restructuring velocity among target assets.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Input Registration Fast-Track | Department of Agriculture prioritization accelerates market entry for microbial formulations ahead of synthetic substitution cycles. |
| Cooperative Direct Contracting | Felda and Risda volume aggregation disintermediates traditional distributor layers and compresses procurement margins. |
| Precision Application Technology Deployment | Drone spraying partnerships in Selangor and Sarawak reduce labor dependency while opening advisory service attachment revenue. |
| Residue-Compliant Portfolio Restructuring | EU-equivalent MRL alignment forces active ingredient withdrawals and creates first-mover advantage for compliant formulators. |
| East Malaysian Distribution Expansion | Sarawak and Sabah smallholder consolidation through state land schemes creates centralized procurement channels bypassing Peninsular intermediaries. |
Research Methodology
Cross-validation between primary interviews with plantation agronomists, cooperative procurement officers, and Department of Agriculture extension coordinators anchors the qualitative findings against secondary validation from customs import records, Pesticides Board registration databases, and Malaysian Palm Oil Board production statistics. Bottom-up triangulation against top-down trade flow analysis ensures demand estimates reflect actual hectare application rates rather than distributor inventory positioning.
Calibration against historical CAGRs from parallel Southeast Asian agrochemical markets informs the projection framework across the analysis window. Segmentation dimensions include product type, application crop, end-user concentration, and distribution channel complexity. Modeled outputs incorporate active ingredient substitution velocity under EU-equivalent residue standards and biological input penetration curves derived from Department of Agriculture subsidy program uptake rates.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by multinational formulators or accelerated Chinese direct-to-farmer platform launches would shift outcomes beyond modeled ranges. Quarterly review of Pesticides Board registration queue lengths and cooperative procurement tender volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
Indonesia Agrochemicals Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
Agrochemical Market
Agrochemicals
L-Glufosinate Ammonium Market
Agrochemicals
Africa Agrochemicals Market
Agrochemicals
South Africa Agrochemicals Market
Agrochemicals
Egypt Agrochemicals Market
Agrochemicals
Global Buprofezin Market
Agrochemicals
Mexico Agrochemicals Market
Agrochemicals
Agrochemical Active Ingredients Market
Agrochemicals
Potassium Humate Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
South America Agrochemicals Market
Agrochemicals
Middle East and Africa Plant Growth Regulators Market
Agrochemicals
Superphosphates Market
Agrochemicals
Canada Agrochemicals Market