
 India Used Car Financing Market | 2026-2036
India Used Car Financing Market Size, Share, and Industry Trends Forecast 2026-2036
India Used Car Financing Market Foresight
Securitization of used car loan receivables is rewriting competitive dynamics by allowing non-bank lenders to access institutional capital pools previously reserved for banks. Shriram Finance leverages its rural branch density to dominate semi-urban and rural origination. Cholamandalam Investments & Finance anchors its position through captive tie-ups with used car dealer networks across South India. Bajaj Finance competes via its digital-first underwriting platform that compresses loan disbursal timelines.
Used car financing denotes secured lending instruments collateralized by pre-owned passenger vehicles, with loan-to-value ratios typically calibrated against depreciated asset valuations and borrower credit scores. The primary commercial purpose is to unlock vehicle ownership for creditworthy buyers who lack liquidity for outright purchases, while generating interest income and fee-based revenue for originators. Dealer financing leads origination volumes due to point-of-sale convenience and embedded inventory financing arrangements, yet peer-to-peer lending platforms represent the fastest-growing channel as algorithmic credit scoring expands addressable borrower pools. Medium-term loans spanning 36-60 months capture the dominant margin pool, balancing default risk against interest income duration.
RBI prudential norms on scale-based regulation and digital lending guidelines shape capital adequacy requirements and customer protection standards for lenders. SEBI regulations on securitization and BIS certification requirements for vehicle valuation standards further structure market access and product standardization. Stakeholders must monitor evolving co-lending guidelines and embedded finance partnerships as these frameworks determine which business models achieve sustainable origination scale.
Market Dynamics
RBI's tightened digital lending guidelines and co-lending norms are forcing non-bank lenders to restructure capital partnerships and underwriting workflows, accelerating the shift toward securitized receivables and formalized dealer network integrations.
Growth Catalysts
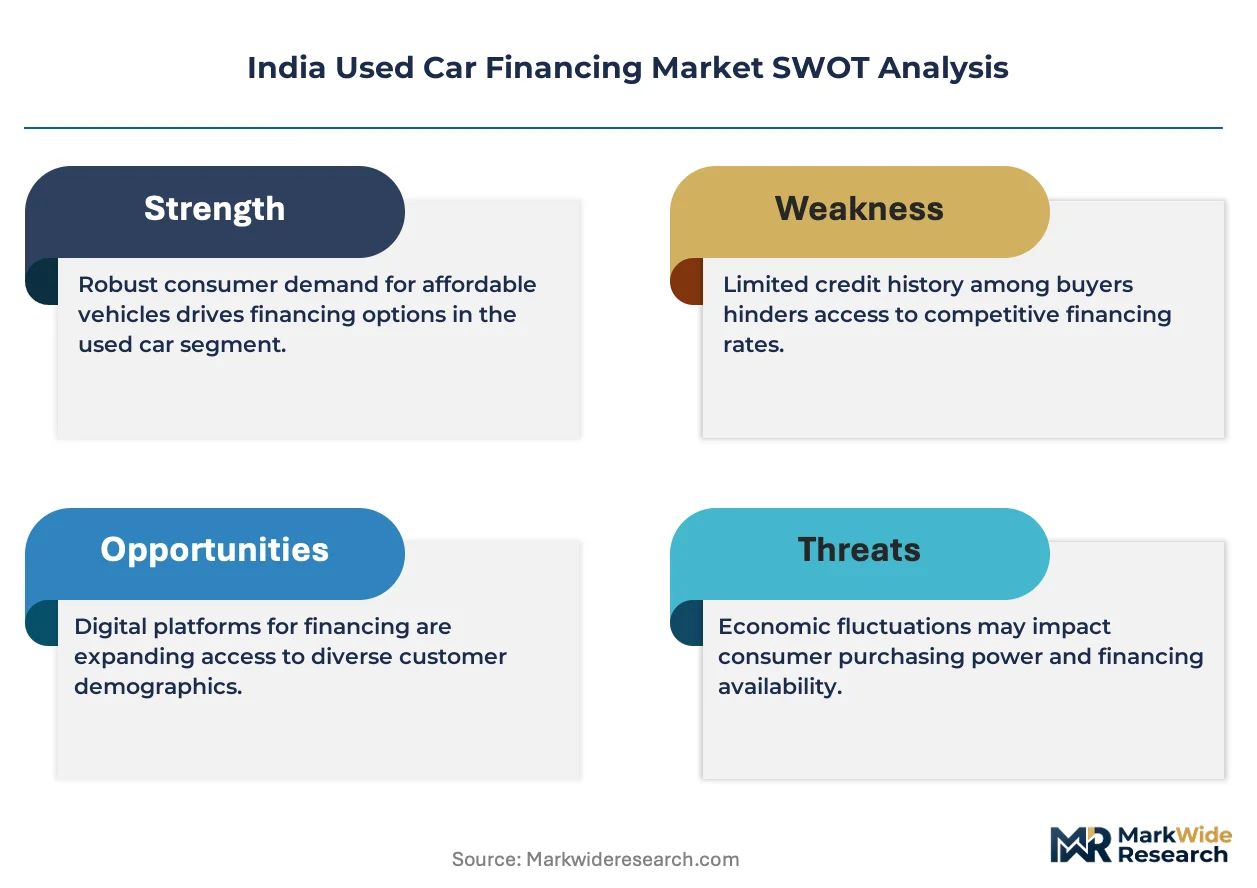
- Semi-urban demand surge:Tier-2 city salaried professionals are emerging as a high-volume borrower segment with improving credit bureau visibility and vehicle ownership aspirations.
- Co-lending framework expansion:RBI's co-lending norms enable NBFCs to pool balance sheet capacity with banks, lowering cost of funds for used car originators.
- Algorithmic underwriting:Machine-learning credit scoring models are expanding addressable borrower pools beyond traditional income-documentation requirements.
Market Restraints
- Asset valuation opacity:Depreciation schedules lack standardization across India's fragmented used car market, complicating loan-to-value calibration.
- Regional supply concentration:Organized inventory pipelines cluster in Maharashtra and Gujarat, limiting financing origination scale in eastern and northeastern states.
- Digital lending compliance burden:RBI's scale-based digital lending guidelines impose tiered capital adequacy and customer protection costs on mid-sized NBFCs.
Strategic Opportunities
- Peer-to-peer platform penetration:Direct borrower-lender matching channels represent underexploited origination volume in Tier-3 towns and rural clusters.
- Embedded finance partnerships:Integration with automotive marketplaces and classified platforms creates point-of-sale financing capture outside traditional dealer networks.
- Securitization market deepening:SEBI's regulatory framework for loan receivables enables NBFCs to access institutional capital pools previously reserved for bank balance sheets.
Industry Challenges
- Legacy system integration:Mid-tier lenders face technical debt when connecting digital underwriting engines to core banking platforms and dealer management systems.
- Valuation standardization delays:BIS certification requirements for vehicle assessment tools remain unevenly adopted across India's used car appraisal ecosystem.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Used Car Financing Market |
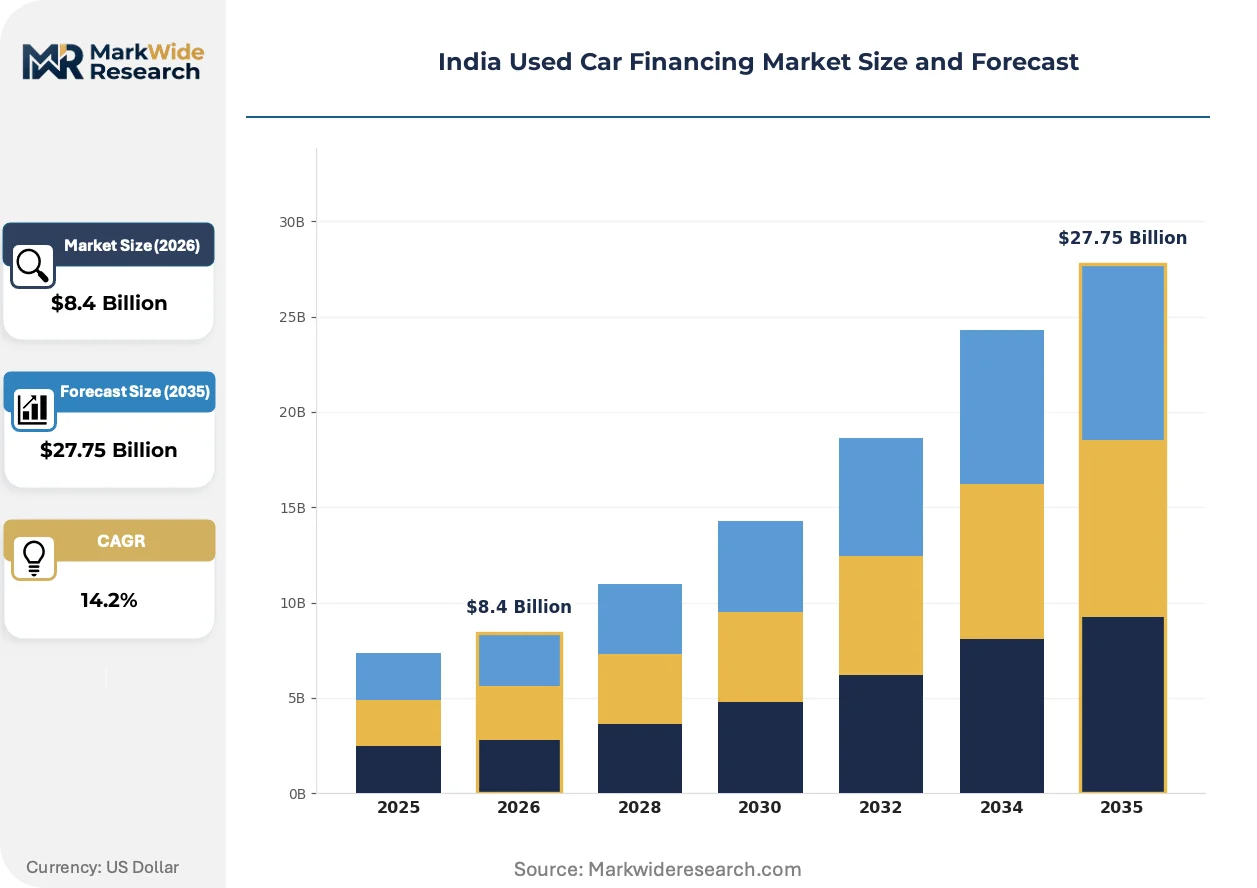
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $27.75 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
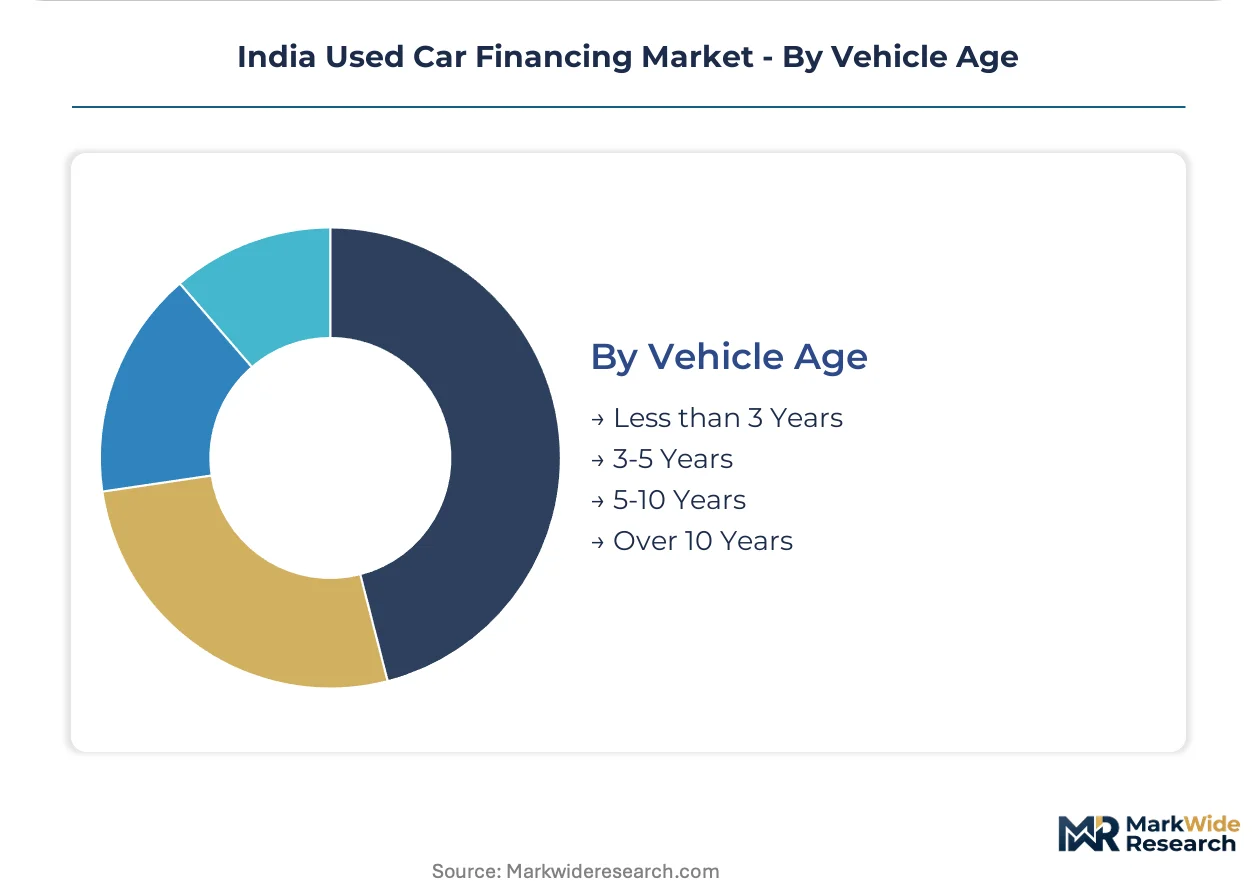
| Segmentation | Financing Type: Bank Loans, Credit Unions, Dealer Financing, Peer-to-Peer Lending Loan Duration: Short-Term, Medium-Term, Long-Term, Flexible Tenure Customer Profile: First-Time Buyers, Repeat Buyers, Corporate Clients, Self-Employed Individuals Vehicle Age: Less than 3 Years, 3-5 Years, 5-10 Years, Over 10 Years |
| Companies Covered | Axis Bank, Shriram Finance, State Bank of India, Bajaj Finance, Mahindra & Mahindra Financial Services, HDFC Bank, Kotak Mahindra Bank, Cholamandalam Investments & Finance, ICICI Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Used Car Financing Market Shifts & Advancements
Digital origination infrastructure is compressing loan disbursal timelines from days to hours, while regulatory pressure on customer data protection and algorithmic transparency is reshaping lender technology stacks and partnership structures.
Telematics-enabled asset monitoring is migrating from fleet management applications to retail used car financing, allowing lenders to track vehicle location and usage patterns as dynamic collateral inputs. NBFCs in South India are piloting GPS-integrated loan products for sub-prime borrower segments. This technology is migrating from commercial vehicle tracking to personal automobile securitization, compressing default recovery timelines and enabling usage-based interest pricing.
RBI's digital lending guidelines mandate explicit consent layers and grievance redressal mechanisms for algorithmic credit decisions, raising compliance costs for automated underwriting platforms. Lenders must now maintain explainable AI audit trails and human-in-the-loop escalation protocols. The guidelines most acutely affect fintech-NBFC partnerships targeting first-time borrowers with thin credit files.
Dealer financing dominance is eroding as direct-to-consumer digital channels capture borrower discovery and pre-approval stages before dealership contact. Automotive classified platforms and OEM-certified pre-owned programs are building captive financing interfaces that bypass traditional dealer commission structures. This channel disintermediation is most visible in Gujarat and Karnataka, where digital-native buyers in metropolitan clusters complete loan applications through marketplace-embedded workflows.
India Used Car Financing Market Segmentation

Segmentation in used car financing determines origination velocity, risk-adjusted pricing, and capital deployment strategies across India's heterogeneous borrower base. Lenders calibrate underwriting models, dealer commissions, and securitization tranches based on these dimensional splits. Understanding which segments turn over fastest versus which lock up capital longest shapes portfolio construction for NBFCs and banks alike.
Financing Type:
Dealer financing compresses disbursal cycles to same-day completion, while peer-to-peer platforms stretch origination timelines through algorithmic matching and document verification workflows.
- Bank Loans:Public and private sector banks deploy balance sheet capacity with RBI-mandated priority sector lending quotas, concentrating origination in Maharashtra and Gujarat where organized inventory pipelines feed standard collateral valuation. SBI and HDFC Bank leverage branch networks to capture salaried professionals with established credit histories, though documentation requirements extend cycle times to 3-5 days.
- Dealer Financing:Point-of-sale convenience and embedded inventory financing arrangements dominate origination volumes, with dealer commissions bundling vehicle purchase and loan disbursal into single-transaction closure. This channel turns fastest—approvals complete within hours—because dealers pre-negotiate lender terms and submit standardized borrower documentation through integrated management systems.
- Credit Unions:Member-owned cooperative structures serve localized borrower pools with relationship-based underwriting, limiting geographic scale but reducing default rates through community enforcement mechanisms.
- Peer-to-Peer Lending:Algorithmic credit scoring platforms expand addressable borrower pools beyond traditional income documentation, matching retail investors directly with used car purchasers; regulatory compliance under RBI's digital lending guidelines lengthens onboarding but broadens sub-prime access.
Dealer financing anchors the volume base while peer-to-peer lending gains share at the steepest rate.
Loan Duration:
Cost tier stratification separates premium interest margins on short-term products from volume-driven, thin-spread long-term structures that dominate securitization pools.
- Medium-Term:Loans spanning 36-60 months capture the dominant margin pool, balancing default risk exposure against interest income duration and enabling predictable cash flow matching for securitization tranches. NBFCs prioritize this band for balance sheet efficiency, with Shriram Finance and Cholamandalam Investments deploying 70% of used car disbursements here.
- Short-Term:Tenures under 24 months command premium pricing for borrowers seeking rapid ownership equity buildup, typically first-time buyers in Tier-2 cities with limited credit history who accept elevated EMIs for faster collateral release.
- Long-Term:72-84 month structures minimize monthly obligations for self-employed borrowers with irregular income streams, spreading depreciation risk across extended amortization schedules.
- Flexible Tenure:Step-up and bullet repayment options accommodate seasonal income patterns among agricultural and trading communities in rural Karnataka and Tamil Nadu.
Medium-term products anchor the volume base while flexible tenure structures are climbing the fastest among non-salaried borrower segments.
Customer Profile:
Application-driven segmentation separates individual ownership aspirations from fleet procurement and commercial utilization patterns that demand distinct collateral monitoring.
- First-Time Buyers:Thin credit file borrowers entering formal financing for the first time, concentrated in Tier-2 cities with improving bureau visibility; algorithmic scoring and co-lending partnerships with banks expand approval rates beyond traditional income documentation thresholds.
- Self-Employed Individuals:Traders, contractors, and small business owners with irregular cash flows; GST return-based underwriting and bank statement analysis replace salary slip verification, with South Indian NBFCs pioneering sector-specific scoring models for this segment.
- Repeat Buyers:Established borrowers with demonstrated repayment history commanding preferential loan-to-value ratios and reduced processing fees; retention-focused lenders deploy pre-approved top-up offers triggered by credit bureau triggers.
- Corporate Clients:Fleet operators and employee vehicle programs requiring bulk origination capabilities, centralized documentation, and telematics-integrated collateral monitoring for asset recovery efficiency.
First-time buyers anchor the volume base while self-employed individuals are expanding most quickly as algorithmic underwriting penetrates informal income segments.
Vehicle Age:
Supply concentration in organized inventory channels dictates financing penetration, with newer vehicles commanding standardized valuation and older assets requiring bespoke appraisal expertise.
- Less than 3 Years:OEM-certified pre-owned programs and organized dealer networks dominate supply, enabling BIS-compliant valuation tools and standardized depreciation schedules that support 85-90% loan-to-value ratios; Gujarat and Maharashtra inventory pipelines feed disproportionate origination here.
- 3-5 Years:The sweet spot for financing penetration—sufficient depreciation to create affordability for Tier-2 salaried professionals, yet young enough to retain organized channel distribution and residual value predictability.
- 5-10 Years:Fragmented supply through unorganized dealers and individual sellers; valuation opacity compresses loan-to-value ratios to 60-70% and extends underwriting cycle times as lenders deploy physical inspection protocols.
- Over 10 Years:Minimal institutional financing penetration; borrower pools rely on informal moneylenders or family capital, with sporadic NBFC pilot programs testing GPS-collateralized products for commercial repurposing.
3-5 year vehicles anchor the volume base while under-3-year certified pre-owned units are gaining share fastest as OEM financing subsidiaries expand captive programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RBI's co-lending framework and priority sector lending mandates are channeling institutional capital into state-level used car financing ecosystems, with sub-regional origination patterns tracking organized inventory concentration and bureau penetration gradients.
Maharashtra
Mumbai and Pune metropolitan clusters generate the highest financing origination volumes through organized dealer networks and OEM-certified pre-owned pipelines. RBI's scale-based digital lending guidelines impose tiered compliance costs on NBFCs operating here, compressing margins for mid-sized originators. Thane-Nashik corridor dealers leverage integrated management systems to complete same-day disbursals with partner lenders.
Gujarat
Ahmedabad-Surat automotive trading hubs feed disproportionate inventory into financing channels, with merchant communities driving self-employed borrower segment growth. SEBI's securitization regulations enable local NBFCs to package receivables for institutional investors, lowering cost of funds. Gandhinagar-based fintech platforms are piloting algorithmic underwriting for thin-file first-time buyers.
Karnataka
Bengaluru's salaried technology workforce anchors demand for 3-5 year vehicle financing, with digital-native buyers completing pre-approval through marketplace-embedded workflows. BIS certification requirements for valuation tools remain unevenly adopted here, extending physical inspection protocols for older assets. Mysuru-Hubli corridor NBFCs test GPS-collateralized products for sub-prime segments.
Tamil Nadu
Chennai's organized used car auction infrastructure supports standardized depreciation scheduling and residual value predictability. Coimbatore-Madurai manufacturing belt lenders deploy sector-specific scoring models for trader and contractor income profiles. RBI's tightened co-lending norms are restructuring bank-NBFC partnerships in this state, favoring larger originators with formalized dealer integrations.
Delhi-NCR
Noida-Gurugram logistics corridors concentrate fleet financing demand from corporate clients requiring telematics-integrated collateral monitoring. Delhi's fragmented unorganized dealer base complicates loan-to-value calibration for 5-10 year vehicles, compressing institutional penetration. Haryana-side lenders face legacy system integration costs when connecting digital underwriting engines to core banking platforms.
India Used Car Financing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across origination architecture, with market structure consolidating around four archetypes: rural branch-dense NBFCs, digital-first fintech platforms, bank-led co-lending partnerships, and captive OEM financing subsidiaries. Dominant competitive moves include securitization market deepening to access institutional capital pools and embedded finance partnerships with automotive marketplaces to capture pre-dealership borrower discovery.
Among rural-anchored NBFCs, Shriram Finance exemplifies branch-density-driven origination in semi-urban and rural clusters, while Cholamandalam Investments & Finance occupies a position tied to South Indian dealer network captivity. Bajaj Finance represents the digital-first underwriting archetype, compressing disbursal timelines through algorithmic platforms. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Axis Bank |
| Shriram Finance |
| State Bank of India |
| Bajaj Finance |
| Mahindra & Mahindra Financial Services |
| HDFC Bank |
| Kotak Mahindra Bank |
| Cholamandalam Investments & Finance |
| ICICI Bank |
| Others |
Supply & Pricing Matrix
Organized inventory pipelines in Maharashtra and Gujarat concentrate collateral valuation expertise, directing margin pools toward lenders with certified appraisal capabilities and integrated dealer management systems. This upstream supply concentration forces pricing power toward originators who control point-of-sale financing capture, while fragmenting margins for mid-tier NBFCs lacking formalized dealer network integrations.
Pricing Analysis
Certification level for vehicle valuation tools creates the primary spread between premium and standard financing tiers, with BIS-compliant appraisal systems supporting 85-90% loan-to-value ratios against 60-70% for unstandardized assessments. Interest rate differentiation tracks borrower credit bureau visibility and income documentation completeness, with salaried professionals in Tier-2 cities commanding 50-150 basis point spreads over self-employed segments. Pricing pressure stems from RBI's scale-based digital lending guidelines raising compliance costs for automated underwriting platforms. First-time buyers with thin credit files exhibit highest price sensitivity, while repeat buyers with established repayment histories accept premium pricing for expedited disbursal.
Supply Chain Analysis
Tariff exposure between organized dealer networks and unorganized inventory channels dominates supply chain risk for collateral sourcing, with 3-5 year vehicle availability concentrated in Maharashtra, Gujarat, and Tamil Nadu auction infrastructure. Used car supply draws from OEM-certified pre-owned programs, organized dealer consignments, and fragmented individual seller markets, with valuation standardization varying sharply across these tiers. Single-source vulnerability exists for lenders dependent on specific dealer management systems for real-time inventory feeds. Distribution runs through captive financing interfaces at automotive marketplaces, direct-to-consumer digital platforms, and traditional dealer commission structures, with channel control determining origination velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's used car financing market represents early-cycle expansion, with Tier-2 city salaried professionals and algorithmic underwriting penetration creating addressable borrower pool growth that outpaces mature market saturation patterns.
For Market Incumbents: Harden dealer network captivity through embedded inventory financing arrangements and integrated management system deployments, as direct-to-consumer digital channels threaten point-of-sale capture. Deepen securitization capabilities to access institutional capital pools before co-lending framework revisions favor larger originators with formalized balance sheet partnerships. Prioritize BIS certification investment for valuation tools to defend loan-to-value positioning against fintech-NBFC partnerships.
For New Entrants and Emerging Players: Eastern and northeastern states present the most penetrable geographic white space, with organized inventory pipeline gaps creating first-mover advantages for lenders building physical appraisal expertise. Target sub-prime self-employed segments in Karnataka and Tamil Nadu manufacturing belts with GST return-based underwriting models. Deploy peer-to-peer platform architectures with algorithmic credit scoring to bypass dealer commission structures entirely.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fintech platforms possessing digital underwriting engines but lacking dealer network density for origination scale. Long-term viability hinges on regulatory adaptation capacity across RBI's evolving digital lending and co-lending frameworks. Monitor SEBI securitization market depth and BIS certification adoption velocity as inflection indicators for portfolio liquidity and collateral standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Integration | Captures point-of-sale financing volume through embedded inventory financing arrangements with organized dealer management systems. |
| Securitization Market Participation | Enables NBFCs to package loan receivables for institutional investors, lowering cost of funds and diversifying capital sources. |
| Algorithmic Underwriting Deployment | Expands addressable borrower pools beyond traditional income documentation through machine-learning credit scoring models. |
| Co-Lending Partnership Formation | Pools balance sheet capacity with banks under RBI norms, reducing funding costs and meeting priority sector lending quotas. |
| Telematics-Enabled Collateral Monitoring | Pilots GPS-integrated loan products for sub-prime segments, compressing default recovery timelines and enabling usage-based pricing. |
Research Methodology
Initial hypotheses were tested against primary input from used car financing executives, dealer network operators, NBFC portfolio managers, and RBI regulatory specialists, and refined through secondary validation across SEBI securitization disclosures, RBI circular archives, and automotive marketplace transaction data. Bottom-up triangulation combined borrower segment interviews with top-down analysis of state-level origination patterns and co-lending partnership structures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions spanning financing type, loan duration, customer profile, and vehicle age tier. CAGRs were derived through iterative reconciliation of origination volume trajectories against capital deployment capacity and regulatory constraint evolution. Industry-specific forecast inputs incorporated co-lending framework penetration rates and BIS certification adoption curves for valuation standardization.
Practitioners should monitor RBI digital lending guideline enforcement intensity and securitization market liquidity conditions for early signals requiring forecast revision. Forecasts reflect assumptions about co-lending partnership durability and algorithmic underwriting regulatory acceptance. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
Florida Digital Lending Market
Loans and Leasing
Battery Leasing Service Market
Loans and Leasing
Asia-Pacific Syndicated Loans Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
Loan Servicing Software Market
Loans and Leasing
North America Motorcycle Loan Market
Loans and Leasing
India Auto Loan Market
Loans and Leasing
France Car Loan Market
Loans and Leasing
Asset-Based Lending Market