
 Germany Auto Loan Market | 2026-2036
Germany Auto Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Auto Loan Market Insights
The divergence between premium captive finance and commodity digital lending is broadening in Germany. Volkswagen Bank GmbH leverages its manufacturing parent to sustain closed-loop vehicle-financing ecosystems. Deutsche Bank AG competes through open-architecture platforms that extend across independent dealership networks.
Germany auto loans are structured credit products collateralized by vehicle titles or manufacturer guarantees, with loan-to-value ratios typically ranging from 70% to 90% depending on residual value assessments and borrower credit scoring. Their primary commercial purpose channels household liquidity into durable automotive consumption while generating interest income for originators. Secured loans dominate origination volumes due to lower risk-weighted capital requirements under Basel frameworks, while lease financing captures margin pools from corporate fleet renewals. Fixed-rate products anchor retail borrower preference amid ECB policy volatility.
BaFin supervises consumer credit disclosures and affordability standards, while the ECB's monetary policy transmission directly affects refinancing costs for German auto lenders. KBA vehicle type-approval requirements influence residual value calculations that underpin secured loan structuring. Stakeholders must monitor how digital onboarding platforms interact with BaFin's conduct supervision as online originators gain share.
Market Dynamics
BaFin's consumer credit disclosure requirements and ECB interest rate transmission are restructuring how German auto lenders originate, price, and securitize vehicle-backed receivables.
Growth Catalysts
- ECB Rate Transmission:Fixed-rate auto loan products attract retail borrowers seeking payment certainty amid monetary policy volatility. Deutsche Bundesbank refinancing facilities stabilize lender funding costs.
- Electric Vehicle Fleet Expansion:Corporate sustainability mandates accelerate financing demand from logistics operators renewing diesel-powered commercial vehicle pools.
- Bavaria Manufacturing Corridor:Concentrated OEM assembly plants generate captive finance origination volumes through employee purchase programs and dealership floorplan arrangements.
Market Restraints
- Residual Value Uncertainty:KBA type-approval changes for battery-electric vehicle categories complicate collateral valuation models used in secured loan structuring.
- Capital Requirement Intensity:BaFin's implementation of Basel III risk-weighted asset rules elevates minimum equity thresholds for non-captive auto lenders.
- Interest Rate Sensitivity:ECB deposit facility rate adjustments transmit directly to German auto loan pricing, compressing net interest margins during tightening cycles.
Strategic Opportunities
- Used Vehicle Digital Platforms:Online remarketing channels enable lenders to capture residual value upside through direct-to-consumer sales of repossessed collateral.
- Subscription-to-Ownership Pathways:Flexible mobility contracts convert short-term users into term loan borrowers through embedded purchase options.
- BaFin Sandbox Framework:Regulatory innovation permits testing of AI-driven credit scoring models with modified disclosure requirements for digital-first originators.
Industry Challenges
- Legacy Core System Integration:Incumbent lenders face technical debt when embedding real-time payment initiation into decades-old loan servicing platforms.
- Data Science Talent Scarcity:Predictive default modeling requires specialized quantitative skills that German financial services employers compete aggressively to secure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Auto Loan Market |
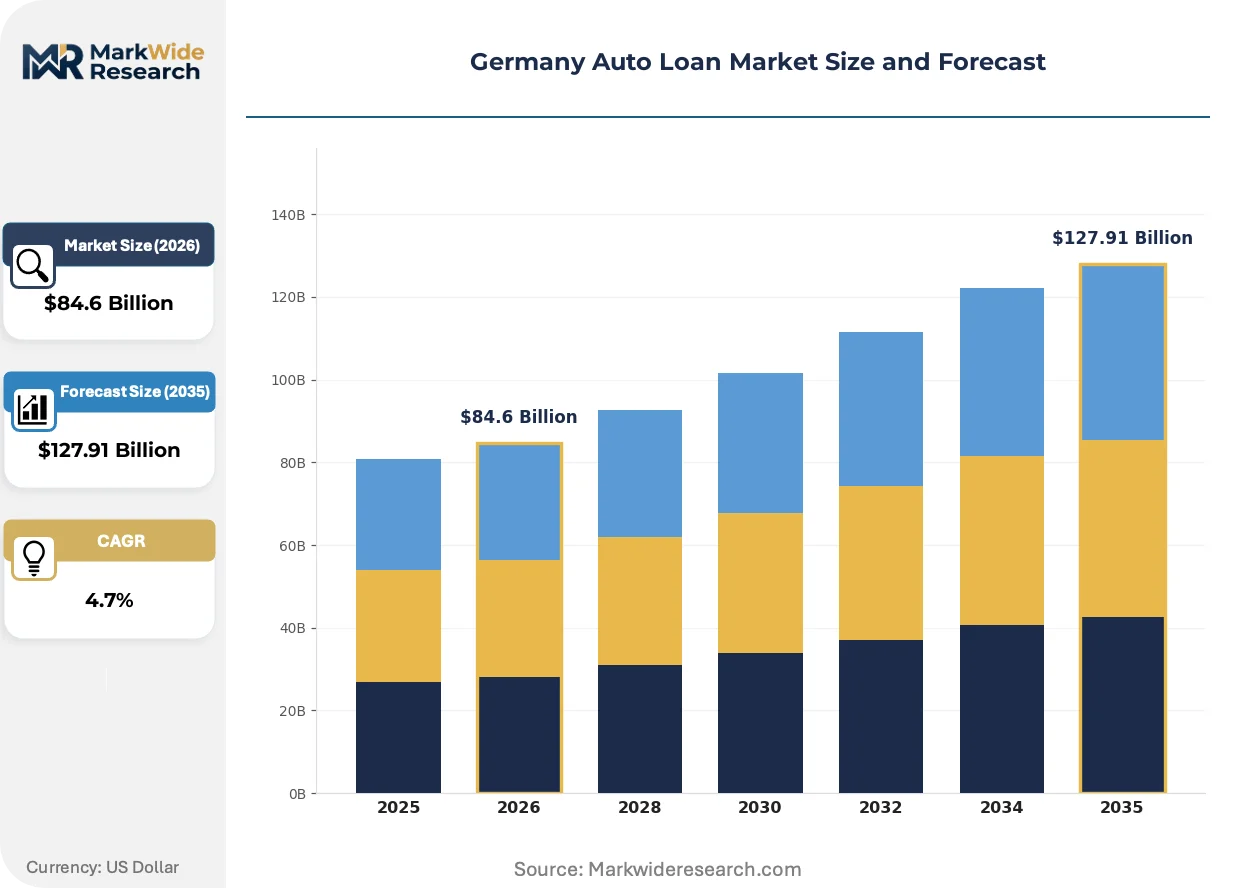
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $127.91 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Secured Loans, Unsecured Loans, Lease Financing, Personal Loans Borrower Profile: Individual Consumers, Small Businesses, Corporates, Dealerships Loan Tenure: Short-Term, Medium-Term, Long-Term, Flexible Terms Interest Rate Type: Fixed Rates, Variable Rates, Promotional Rates, Others |
| Companies Covered | Bank11 für Privatkunden und Handel GmbH, Deutsche Bank AG, Volkswagen Bank GmbH, Auto Empire Trading GmbH, Nordfinanz GmbH, Mercedes-Benz Bank AG, Süd-West-Kreditbank Finanzierung GmbH, Smava GmbH, Banque PSA Finance S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Auto Loan Market Trends and Innovations
Digital onboarding infrastructure and embedded finance architectures are compressing origination timelines while fragmenting distribution control between captive and independent channels.
API-connected loan origination systems is modularizing the underwriting workflow into discrete microservices. Mid-sized regional banks adopt component-based credit decision engines to compete with Volkswagen Bank GmbH's integrated platforms. This architecture is modularizing risk assessment, document verification, and fund disbursement into separately optimizable functions.
BaFin's consumer credit directive amendments mandate granular affordability stress-testing for variable-rate products. Lenders must document borrower capacity at interest rate scenarios 200 basis points above origination levels. Retail installment contracts face the most stringent documentation requirements, pushing originators toward fixed-rate product standardization.
Fleet procurement departments now bundle vehicle acquisition with maintenance and telematics in single financing structures. Full-service leasing contracts disaggregate into unbundled asset finance plus service-level agreements. Corporate logistics operators in North Rhine-Westphalia demonstrate the strongest preference for this componentized contracting approach.
Germany Auto Loan Market Segmentation
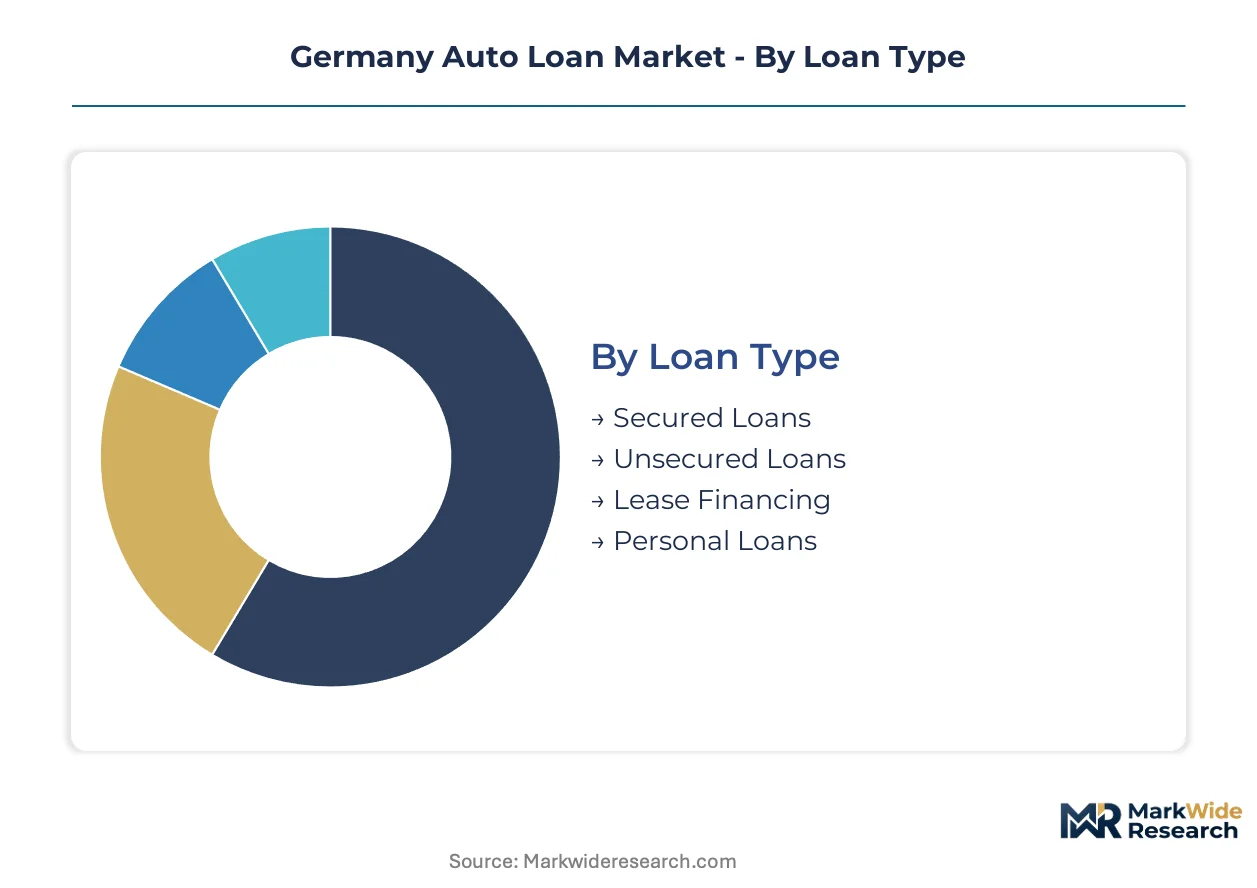
Auto loan structuring in Germany follows distinct collateral and borrower risk profiles that determine capital requirements under BaFin supervision. Each segmentation dimension channels different liquidity sources into vehicle acquisition while shaping lender pricing power and residual value exposure.
Loan Type:
Replacement cycles for ICE vehicles against accelerating BEV adoption reshape collateral quality across loan structures.
- Secured Loans:Vehicle titles serve as primary collateral with LTV ratios calibrated against KBA residual value tables. Bavarian OEM captive finance arms dominate origination through closed-loop ecosystems linking assembly plants to dealership floorplans.
- Lease Financing:Closed-end contracts transfer residual value risk to lessors while bundling maintenance and warranty coverage. Corporate fleet operators in North Rhine-Westphalia favor this structure for commercial vehicle renewals driven by sustainability mandates.
- Unsecured Loans:Signature-based credit relies on Schufa scoring without collateral attachment, commanding higher risk-weighted capital charges under Basel III.
- Personal Loans:General-purpose consumer credit applied to vehicle purchases bypasses manufacturer guarantee structures entirely.
Secured Loans sit at the top of the volume ranking, with Lease Financing climbing the fastest.
Borrower Profile:
Cost tier differentiation separates mass-market retail from specialized commercial underwriting workflows.
- Individual Consumers:Household borrowers anchor retail installment contract volumes with preference for fixed-rate payment certainty amid ECB policy volatility.
- Corporates:Fleet procurement departments negotiate unbundled asset finance plus service-level agreements with telematics integration.
- Small Businesses:Owner-operator commercial vehicle financing combines personal credit guarantees with equipment collateral.
- Dealerships:Floorplan financing structures inventory acquisition through revolving credit facilities tied to vehicle turnover velocity.
Individual Consumers retain the dominant share position, while Corporates demonstrate the steepest expansion trajectory.
Loan Tenure:
Application-based structuring aligns payment schedules with vehicle usage intensity and technological obsolescence risk.
- Medium-Term:36-60 month maturities balance affordable monthly payments against reasonable interest cost accumulation for standard passenger vehicles.
- Long-Term:Extended 72-84 month structures compress payments for premium segment acquisitions while extending residual value uncertainty windows.
- Short-Term:Sub-24 month maturities serve near-new used vehicle purchases with rapid principal amortization.
- Flexible Terms:Balloon payment structures defer substantial principal to contract conclusion, common in subscription-to-ownership conversion pathways.
Medium-Term contracts command the highest origination volume, with Flexible Terms gaining share fastest.
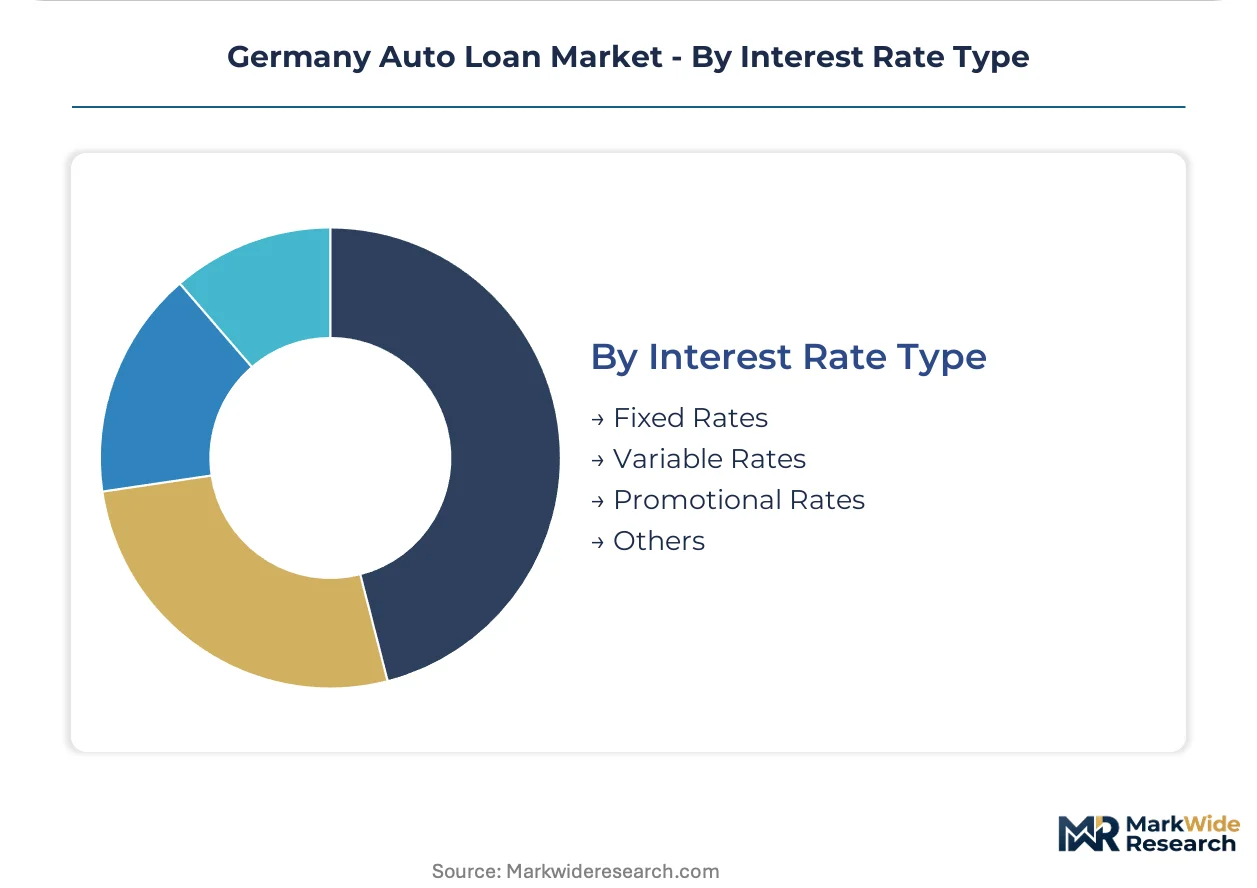
Interest Rate Type:
Customer type segmentation separates rate-sensitive retail borrowers from sophisticated corporate treasury functions.
- Fixed Rates:Payment certainty products dominate retail preference as ECB deposit facility adjustments transmit directly to German auto loan pricing.
- Variable Rates:Euribor-linked structures appeal to corporate treasurers with interest rate hedging capabilities and working capital flexibility.
- Promotional Rates:Subsidized financing from captive lenders supports new vehicle sales campaigns with manufacturer-absorbed interest cost.
- Others:Hybrid structures combining initial fixed periods with subsequent variable adjustment mechanisms.
Fixed Rates anchor the product mix, while Promotional Rates expand most quickly amid competitive new vehicle sales pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's concentration of automotive finance talent clusters around Stuttgart, Munich, and Frankfurt, where captive lenders, commercial banks, and fintech platforms compete for quantitative risk specialists and regulatory compliance expertise.
Bavaria
OEM employee purchase programs and dealership floorplan financing drive origination volumes across the southern manufacturing belt. KBA vehicle type-approval requirements shape residual value calculations for secured loan structuring. Munich anchors captive finance headquarters for Volkswagen Bank GmbH and BMW Group Financial Services, processing fleet procurement contracts for corporate logistics operators.
North Rhine-Westphalia
Corporate fleet renewals accelerate financing demand from logistics operators replacing diesel-powered commercial vehicle pools. BaFin's consumer credit disclosure standards apply uniformly across this industrial heartland. Düsseldorf and Cologne host regional banking centers that underwrite unbundled asset finance plus service-level agreements with telematics integration for freight operators.
Baden-Württemberg
Premium vehicle manufacturing sustains closed-loop financing ecosystems linking assembly plants to dealership networks. The ECB's deposit facility rate adjustments transmit directly to auto loan pricing across Stuttgart's banking corridor. Mercedes-Benz Bank AG originates captive finance products tied to Sindelfingen and Untertürkheim assembly output.
Hesse
Frankfurt's status as Germany's financial capital concentrates commercial banking expertise for auto loan securitization and refinancing operations. Deutsche Bundesbank facilities stabilize lender funding costs for regional originators. The city hosts back-office infrastructure for several nationwide auto loan platforms managing digital onboarding workflows.
Lower Saxony
Wolfsburg's manufacturing density generates concentrated demand for employee vehicle financing and supplier fleet renewal programs. Volkswagen Bank GmbH maintains integrated platforms connecting assembly operations to retail lending channels. Hanover and Braunschweig support regional dealership networks with inventory floorplan credit facilities.
Germany Auto Loan Market Competitive Landscape
Top-tier vendors anchor captive finance ecosystems, while mid-tier commercial banks compete through open-architecture distribution. The market structure splits between manufacturer-captive lenders with closed-loop vehicle financing and independent banks serving fragmented dealership networks. Two strategic archetypes dominate: integrated captive platforms leveraging manufacturing parent relationships, and modular digital originators compressing underwriting timelines through API-connected systems. Competitive moves center on embedded finance partnerships and residual value risk transfer mechanisms.
Among Germany-based captive lenders, Volkswagen Bank GmbH and Mercedes-Benz Bank AG exemplify integrated manufacturing-finance structures that control distribution from assembly plant to retail borrower. Deutsche Bank AG occupies a position within the commercial banking tier, competing through scale advantages in refinancing and securitization infrastructure. Smava GmbH represents the digital-native archetype, aggregating loan offers across multiple lender balance sheets without direct balance sheet exposure.
| Leading Market Players |
|---|
| Bank11 für Privatkunden und Handel GmbH |
| Deutsche Bank AG |
| Volkswagen Bank GmbH |
| Auto Empire Trading GmbH |
| Nordfinanz GmbH |
| Mercedes-Benz Bank AG |
| Süd-West-Kreditbank Finanzierung GmbH |
| Smava GmbH |
| Banque PSA Finance S.A. |
| Others |
Pricing and Supply Chain Analysis
Captive finance arms anchored to Stuttgart and Munich manufacturing parents enforce pricing discipline through closed-loop vehicle financing ecosystems that internalize residual value risk and compress independent lender margins. This ownership concentration channels pricing power toward OEM-controlled distribution while fragmenting commodity lending across regional banking networks competing on rate transparency.
Pricing Analysis
Bundled full-service leasing contracts command rate premiums against unbundled asset finance plus separate service-level agreements. Price differentiation hinges on residual value guarantee coverage and telematics integration depth. Pricing pressure stems from ECB deposit facility rate adjustments transmitting directly to net interest margins during tightening cycles. Corporate fleet operators in North Rhine-Westphalia demonstrate lowest price sensitivity due to sustainability mandate compliance requirements, while individual retail borrowers in Hesse gravitate toward fixed-rate products prioritizing payment certainty over rate optimization.
Supply Chain Analysis
Dual-sourcing requirements from BaFin-supervised lenders mandate multi-funder qualification for dealership floorplan networks across Germany. Geographic supply concentration centers on Bavarian captive finance headquarters, Frankfurt commercial banking infrastructure, and Düsseldorf regional lending operations. Raw material dependencies include vehicle collateral pools, Schufa credit data feeds, and Bundesbank refinancing facilities. Supply chain risk concentrates in single-source vulnerability to ECB monetary policy transmission. Distribution runs through integrated captive platforms linking assembly plants to dealership networks alongside open-architecture digital aggregators serving independent channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
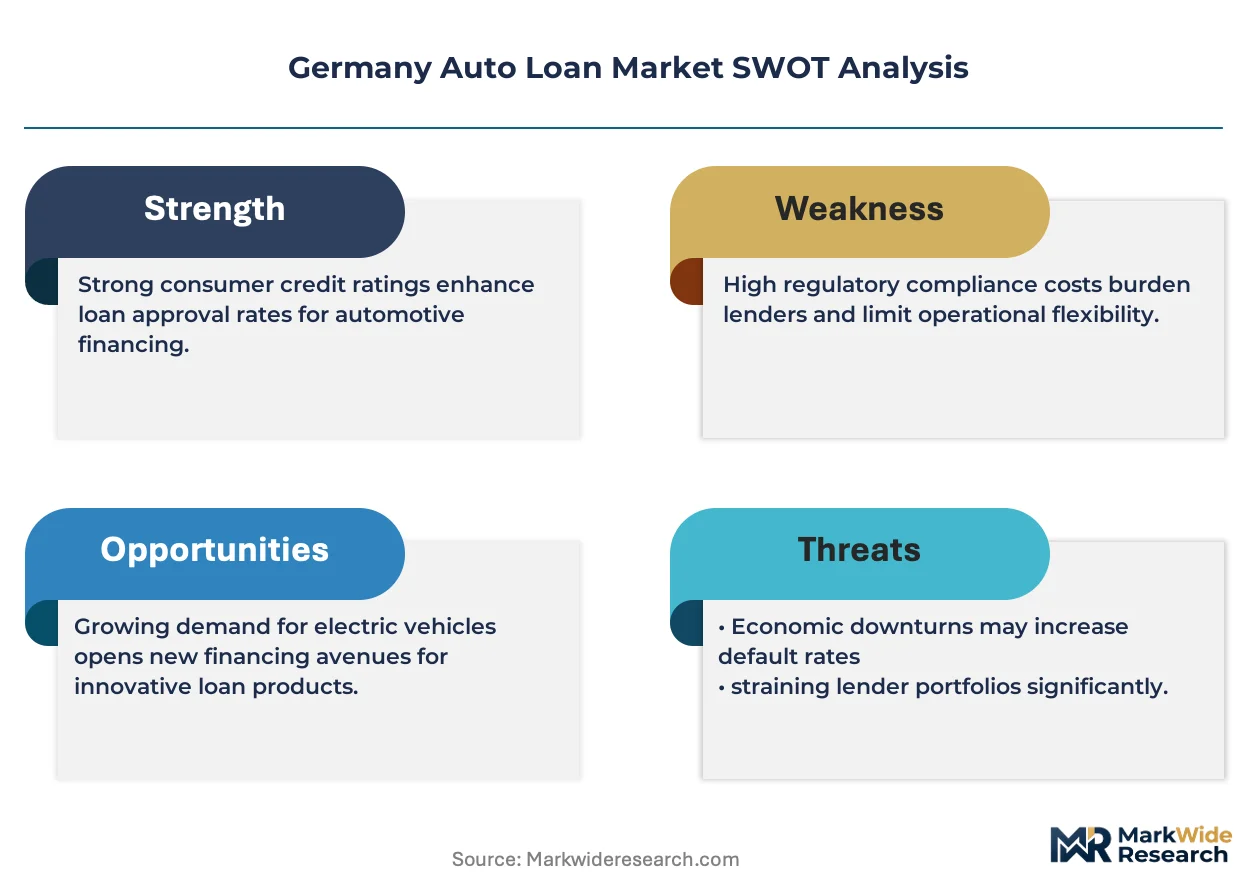
Germany auto loan origination functions as a geographic-arbitrage play between BaFin's stringent consumer credit disclosure standards and the lighter touch of digital-first platforms operating under sandbox frameworks. Regulatory cost differentials between captive finance ecosystems and independent digital originators create margin expansion opportunities for modular underwriting specialists.
For Market Incumbents: Cement closed-loop financing ecosystems by deepening captive integration between assembly plant output and dealership floorplan arrangements. Volkswagen Bank GmbH and Mercedes-Benz Bank AG should harden residual value guarantee structures against KBA battery-electric vehicle type-approval uncertainty. Channel control through employee purchase programs and supplier fleet renewals remains the critical defensive lever against digital aggregators compressing origination timelines. For New Entrants and Emerging Players: Small-business owner-operators in Lower Saxony represent the most penetrable buyer archetype currently underserved by standardized corporate fleet products. White-space targets include subscription-to-ownership conversion pathways for flexible mobility users and AI-driven credit scoring for thin-file borrowers in BaFin's regulatory sandbox. Go-to-market execution should anchor in API-connected loan origination systems that modularize underwriting into discrete microservices. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized regional banks with legacy core systems requiring technical debt remediation for real-time payment integration. Long-term viability across the analysis window favors acquisition targets with established dealership network relationships and unbundled asset finance capabilities. The signal to watch is ECB deposit facility rate trajectory as inflection indicator for net interest margin compression versus expansion cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Residual Value Guarantee Structuring | KBA battery-electric vehicle type-approval changes demand recalibrated collateral valuation models. |
| API-Connected Origination Platforms | Modular microservices architecture compresses underwriting timelines for mid-sized regional banks. |
| Subscription-to-Ownership Pathways | Flexible mobility contracts convert short-term users into term loan borrowers through embedded purchase options. |
| BaFin Sandbox Participation | Regulatory innovation permits AI-driven credit scoring testing with modified disclosure requirements. |
| Telematics-Integrated Fleet Finance | Corporate logistics operators in North Rhine-Westphalia demand unbundled asset finance plus service-level agreements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with captive finance executives, commercial banking underwriters, dealership operations managers, and BaFin regulatory compliance officers with secondary validation. Bundesbank refinancing data, KBA vehicle registration statistics, ECB monetary policy disclosures, and Schufa credit bureau aggregates anchored the quantitative foundation. Bottom-up origination volume modeling and top-down macroeconomic scenario triangulation cross-validated projections.
Comparable-period anchoring tied projection horizons to historical reference intervals spanning ECB rate cycles and vehicle replacement demand patterns. Segmentation dimensions modeled encompassed loan type, borrower profile, loan tenure, and interest rate structure alongside propulsion architecture differentiation between internal combustion and battery-electric collateral pools. CAGRs were derived through regression-based trending adjusted for policy transmission effects. Forecast inputs incorporated residual value table revisions and digital onboarding platform adoption curves.
Underlying measurement precision varies by segment; captive finance origination volumes carry tighter precision than fragmented independent lending due to consolidated reporting structures. Forecasts reflect assumptions around ECB policy trajectory, KBA regulatory implementation timing, and electric vehicle fleet turnover velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Consumer Credit Market
Loans and Leasing
Latin America Motorcycle Loan Market
Loans and Leasing
Enterprise Asset Leasing Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
Europe Used Car Financing Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
Vehicle Leasing Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
United States Car Loan Market
Loans and Leasing
India Auto Loan Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
Student Loan Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
Europe Syndicated Loans Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Brazil Auto Loan Market