
 Automobile Rental and Leasing Market | 2026-2036
Automobile Rental and Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Automobile Rental and Leasing Market Analysis
Germany is rewriting fleet procurement norms across Europe. Enterprise Holdings leverages its airport dominance to sustain pricing power in business travel corridors. Sixt anchors premium positioning through technology leadership in mobile-first booking platforms. Localiza competes aggressively in Latin America with specialized long-term lease structures for corporate clients.
Automobile rental and leasing encompasses the short-term provision and medium-to-long-term financing of vehicles through contractual arrangements that transfer use rights without full ownership, typically governed by residual value calculations, mileage caps, and maintenance bundling. The primary commercial purpose centers on converting fixed automotive assets into variable operating expenses for mobility-dependent enterprises and consumers. Short-term rental commands mature margin pools at major airport hubs, while long-term lease structures capture expanding corporate demand for fleet electrification and predictable total cost of ownership. Corporate lease segments increasingly integrate telematics-enabled usage tracking, differentiating service tiers across customer type dimensions from tourists to enterprise procurement departments.
The EU's F-Gas Regulation and Green Deal framework shape fleet composition mandates, pushing rental operators toward zero-emission vehicle procurement quotas. The US EPA tailpipe standards and NHTSA fuel economy rules similarly redirect capital allocation across North American fleet portfolios. India's BIS certification requirements and PLI scheme incentives for electric vehicle manufacturing create divergent compliance pathways for multinational operators. Fleet managers must monitor regulatory phase-in timelines against charging infrastructure deployment rates to calibrate asset replacement cycles.
Market Dynamics
Fleet electrification mandates are compressing residual value calculations while telematics penetration rewrites utilization economics across rental portfolios. Asset-heavy operators face simultaneous pressure to de-risk balance sheets and absorb charging infrastructure capital requirements.
Growth Catalysts
- EU Green Deal vehicle emissions standards:Zero-emission procurement quotas accelerate electric vehicle fleet turnover and create predictable replacement cycles for lessors.
- Corporate procurement centralization:Enterprise fleet managers consolidate vendor relationships through digital platforms, favoring operators with integrated telematics and maintenance bundling.
- Telematics-enabled usage tracking:Real-time asset monitoring allows dynamic pricing models and improved residual value forecasting for long-term lease structures.
Market Restraints
- Residual value volatility:Rapid battery technology evolution and policy-driven obsolescence compress electric vehicle resale premiums versus internal combustion assets.
- Charging infrastructure gaps:Uneven deployment across urban corridors and rural networks limits fleet utilization rates and expands operational dead zones.
- Semiconductor supply concentration:Taiwan and South Korea manufacturing dominance creates vulnerability for vehicle delivery timelines and fleet refresh schedules.
Strategic Opportunities
- India PLI scheme incentives:Domestic electric vehicle manufacturing subsidies enable localized fleet assembly and reduced import duty exposure for multinational lessors.
- Subscription mobility models:Flexible monthly vehicle access contracts capture younger demographics eschewing ownership in Germany and Nordic markets.
- Vehicle-to-grid integration:Bidirectional charging capabilities transform idle fleet assets into distributed energy storage resources for grid stabilization services.
Industry Challenges
- Technician certification pipelines:High-voltage electric vehicle maintenance training lags fleet electrification timelines, creating service bottlenecks and warranty risk.
- Legacy fleet management system integration:Proprietary telematics platforms resist interoperability with third-party charging networks and energy management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automobile Rental and Leasing Market |
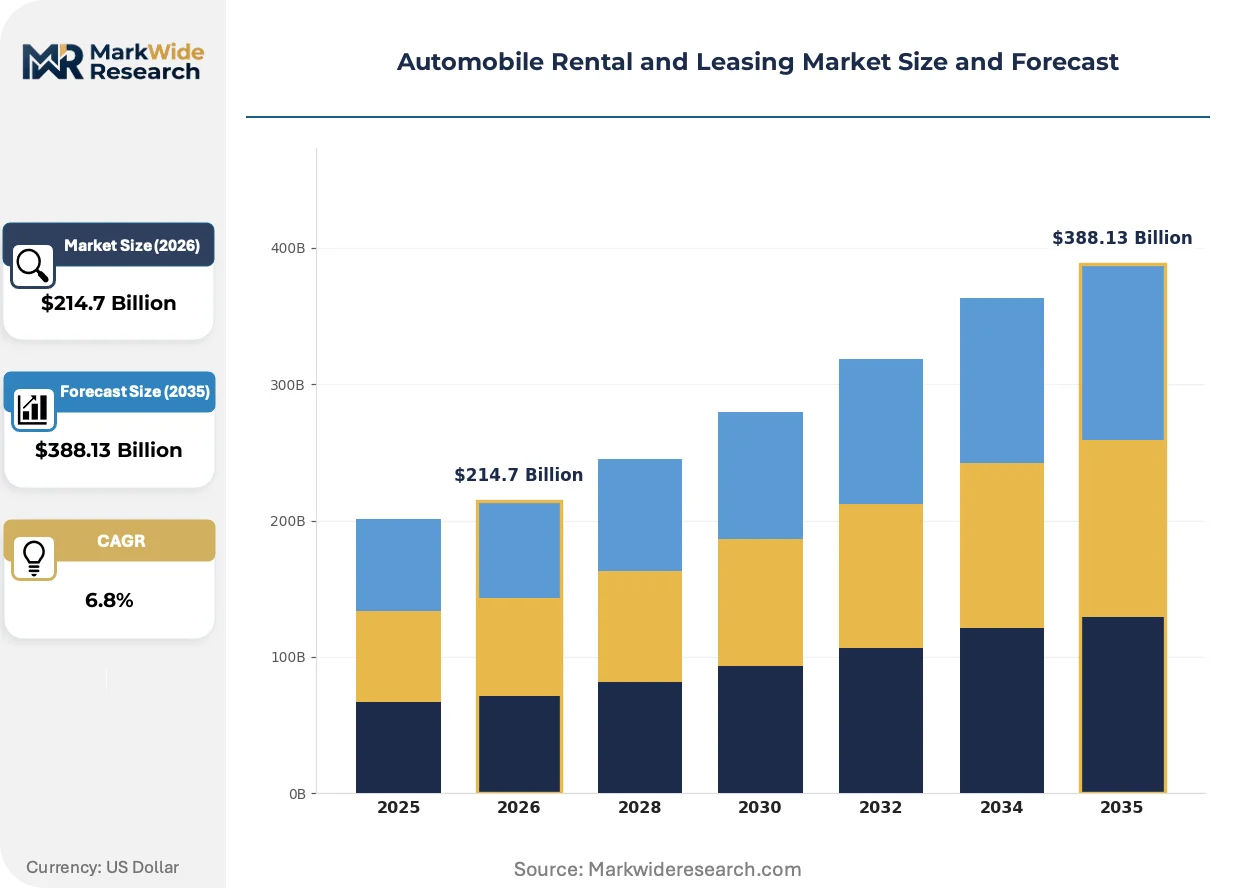
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $388.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Luxury Car Service Type: Short-Term Rental, Long-Term Lease, Corporate Lease, Ride-Sharing Customer Type: Tourists, Business Travelers, Local Residents, Companies Distribution Channel: Online Booking, Travel Agents, Direct Sales, Franchise Locations |
| Companies Covered | LeasePlan, Sixt, Enterprise Holdings, BlueLine Rental, Localiza, The Hertz Corporation, Europcar Mobility Group, National Car Rental, Avis Budget Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automobile Rental and Leasing Market Emerging Trajectories
Digital-native booking interfaces and connected vehicle architectures are collapsing traditional segmentation between short-term rental and long-term lease products. Operators now compete on data integration depth rather than fleet scale alone.
Artificial intelligence-driven demand forecasting is hybridizing static fleet allocation models with dynamic repositioning algorithms. Airport-based operators deploy predictive analytics to pre-stage vehicle classes before flight arrivals. This capability compresses customer wait times and reduces empty-mile logistics costs.
The EU F-Gas Regulation and complementary national zero-emission zones are forcing diesel vehicle phase-outs ahead of natural replacement cycles. German fleet operators face municipal entry restrictions in Hamburg, Stuttgart, and Berlin that strand internal combustion assets. Leasing contracts now incorporate flexible early termination clauses tied to local air quality enforcement timelines.
Corporate travel managers increasingly bundle ground transportation with carbon accounting requirements. Sustainability-linked lease pricing ties monthly rates to verified emissions reporting through CSRD-aligned disclosure frameworks. Germany and France lead this behavioral shift, with procurement departments prioritizing operators offering Scope 3 data transparency.
Automobile Rental and Leasing Market Segmentation
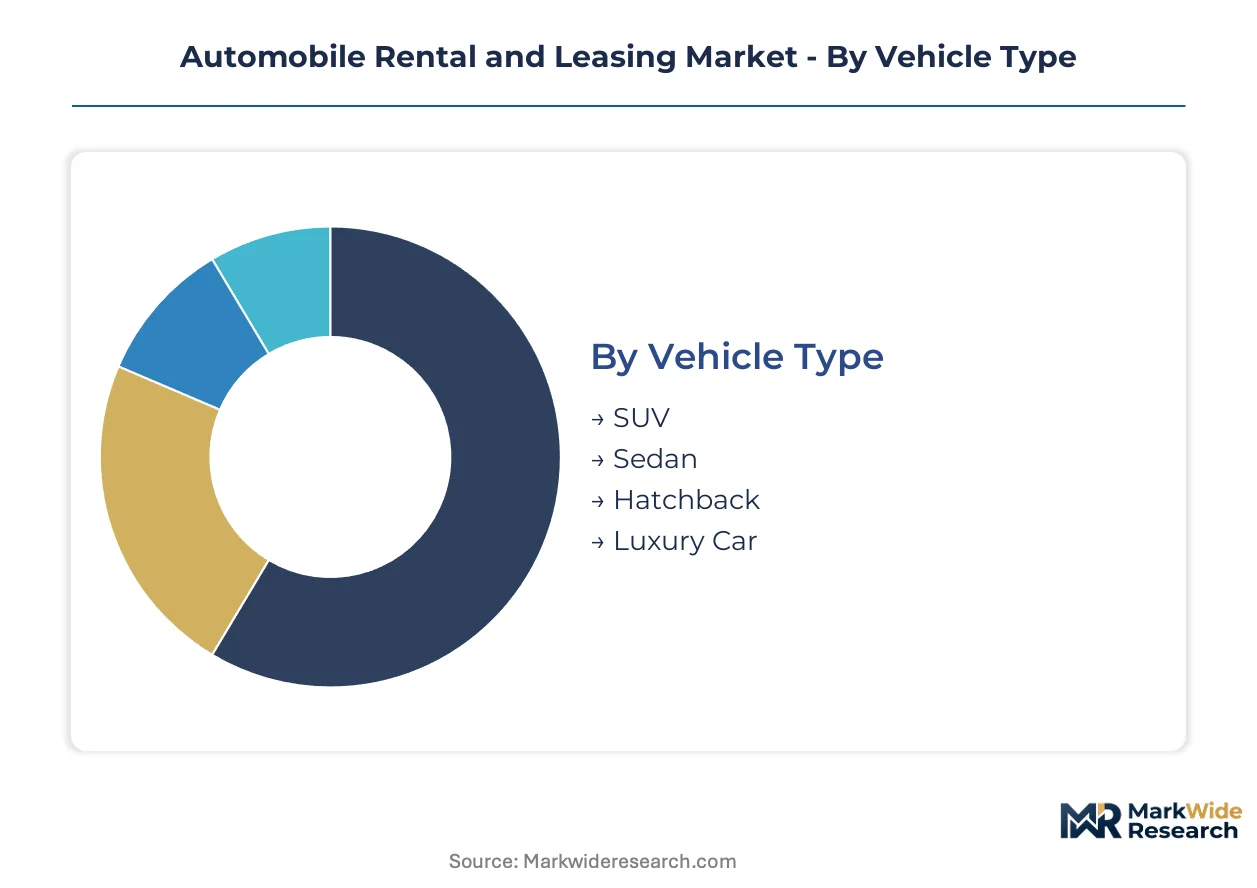
Segmentation in automobile rental and leasing reveals how asset allocation, pricing architecture, and channel economics diverge across mobility use cases. Fleet operators calibrate depreciation schedules, telematics bundling, and residual value guarantees differently for each dimension.
Vehicle Type:
Cost tier differentiation governs fleet procurement priorities and maintenance bundling strategies across vehicle classes.
- SUV:Higher ground clearance and cargo capacity attract family vacation segments and rural corporate deployments. German fleet operators prioritize SUV allocations for Alpine tourism corridors and executive shuttle contracts where all-weather capability commands rate premiums.
- Sedan:Three-box architecture optimized for airport transfer efficiency and trunk-loading business luggage. Demand concentrates among business travelers at Frankfurt, Munich, and Berlin hubs where sedan fleets rotate faster than other segments due to predictable replacement cycles.
- Hatchback:Compact footprint suits urban car-sharing pools and price-sensitive local resident contracts. European cities with congestion charging zones favor hatchback density for street-parking logistics.
- Luxury Car:Premium marques with advanced driver assistance and concierge service tiers. Corporate procurement departments in Frankfurt and Paris specify luxury segments for C-suite mobility programs where total cost of ownership includes image depreciation calculations.
Sedan holds installed capacity. SUV is rotating up the share rankings.
Service Type:
Application duration determines capital intensity, telematics integration depth, and contract flexibility structures.
- Short-Term Rental:Daily or weekly use rights with mileage caps and fuel-return policies. Airport-based operators at Frankfurt, Paris Charles de Gaulle, and Amsterdam Schiphol capture inbound tourist demand through dynamic pricing algorithms tied to flight arrival data.
- Long-Term Lease:Multi-year contracts with residual value guarantees and bundled maintenance. German corporate fleet managers favor 36-48 month structures for electric vehicle transitions where battery degradation risk shifts to lessors.
- Corporate Lease:Enterprise-scale procurement with centralized billing and sustainability reporting. France and Germany lead adoption as CSRD-aligned disclosure requirements mandate Scope 3 transportation emissions tracking.
- Ride-Sharing:Platform-mediated access with per-trip revenue sharing and driver-owned or fleet-supplied vehicles. Urban density in Berlin, Hamburg, and Munich supports dedicated ride-sharing pools with rapid-charging infrastructure commitments.
Short-Term Rental holds installed capacity. Corporate Lease is climbing the fastest as electrification mandates reshape procurement specifications.
Customer Type:
Volume concentration patterns diverge between episodic leisure demand and contracted enterprise mobility.
- Tourists:Episodic demand spikes tied to seasonal travel patterns and visa-free access corridors. Mediterranean and Alpine destination airports in Italy, France, and Austria calibrate fleet surges to summer and winter peak windows.
- Business Travelers:Predictable midweek demand with corporate rate negotiations and loyalty program integration. Frankfurt and London City airport operators maintain dedicated business traveler lanes with expedited vehicle handoff protocols.
- Local Residents:Substitution demand from urban households eschewing ownership for subscription access. German cities with restricted low-emission zones drive local resident migration toward electric fleet subscriptions.
- Companies:Fleet procurement departments with total cost of ownership optimization mandates and sustainability key performance indicators. DAX-listed corporations centralize vendor relationships through digital platforms integrating telematics and carbon accounting.
Business Travelers holds installed capacity. Companies is gaining share fastest as procurement centralization accelerates.
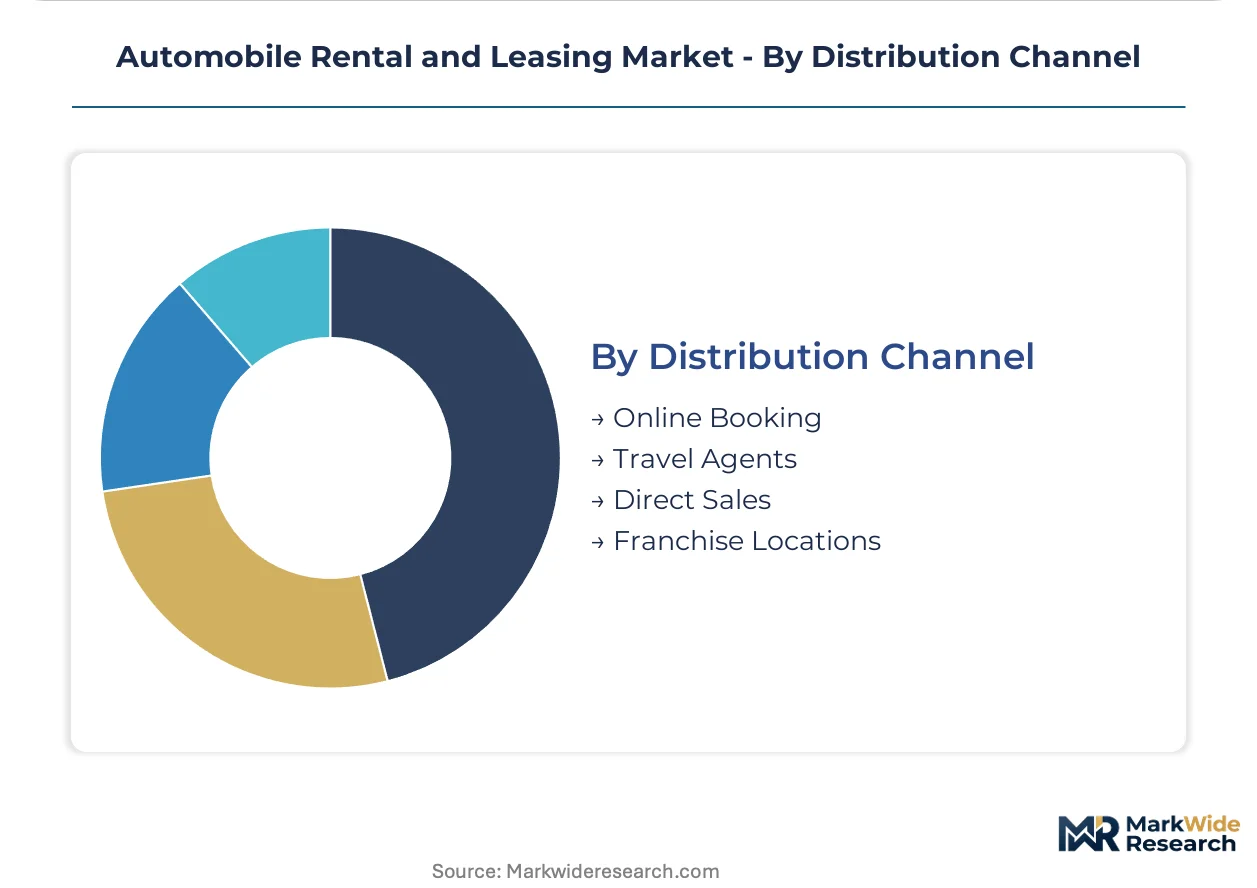
Distribution Channel:
Margin capture and customer acquisition costs vary sharply across direct and intermediated booking pathways.
- Online Booking:Native mobile applications with artificial intelligence-driven upselling and real-time fleet visibility. Sixt and Enterprise Holdings deploy proprietary platforms with dynamic pricing tied to inventory positioning and competitor rate monitoring.
- Travel Agents:Intermediated bookings with commission structures and package bundling for international arrivals. German tour operators consolidate ground transportation procurement through preferred lessor partnerships.
- Direct Sales:Account-based relationship management for corporate fleet managers with negotiated rate cards. Long-term lease contracts in France and Germany originate predominantly through direct sales teams with sustainability consulting capabilities.
- Franchise Locations:Owner-operated storefronts with brand standards and local market adaptation. Eastern European markets rely on franchise density for geographic coverage where corporate-owned infrastructure remains underdeveloped.
Franchise Locations holds installed capacity. Online Booking is expanding most quickly as mobile-first platforms displace legacy reservation systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and F-Gas Regulation anchor fleet transformation across Germany, where KBA enforces zero-emission vehicle quotas that cascade through European procurement standards. National regulators in target markets calibrate electrification timelines against charging infrastructure deployment.
Germany
Corporate fleet managers in Frankfurt and Munich consolidate long-term lease contracts through digital procurement platforms. The KBA enforces stringent CO2 fleet average mandates that accelerate electric vehicle turnover timelines. Hamburg, Stuttgart, and Berlin operate municipal low-emission zones that restrict internal combustion vehicle access and strand legacy fleet assets.
United States
Enterprise procurement departments at Dallas-Fort Worth and Atlanta airports drive demand for integrated telematics and dynamic pricing platforms. The EPA tailpipe standards and NHTSA fuel economy rules redirect capital allocation toward electrified fleet portfolios. California's Advanced Clean Cars II regulation forces accelerated zero-emission vehicle procurement quotas ahead of federal timelines.
China
Ride-sharing platform operators in Shanghai and Shenzhen expand dedicated electric vehicle pools with rapid-charging infrastructure commitments. MIIT dual carbon goals and GB standards mandate new energy vehicle penetration rates across commercial fleets. The Yangtze River Delta cluster concentrates battery-swapping station networks that enable utilization-intensive fleet operations.
India
Corporate mobility managers in Mumbai and Bangalore negotiate long-term lease structures with bundled maintenance and residual value guarantees. The PLI scheme for electric vehicle manufacturing and BIS certification requirements create localized assembly incentives for multinational lessors. The Delhi-NCR region enforces odd-even vehicle rationing and congestion charging that shift demand toward subscription-based electric fleet access.
Brazil
Localiza and corporate fleet operators in São Paulo and Rio de Janeiro specialize in long-term lease structures with telematics-enabled usage tracking. ANVISA regulates commercial vehicle safety standards while central bank monetary policy affects lease rate pricing. The Southeast industrial corridor concentrates fleet management service providers serving mining and agribusiness logistics demand.
Automobile Rental and Leasing Market Vendor Landscape
Airport-dominant operators and technology-integrated specialists split the market between scale-driven yield management and premium service differentiation. Consolidation pressure intensifies as electrification capital requirements favor balance-sheet-heavy incumbents. Three archetypes predominate: legacy airport hub operators, mobile-first platform integrators, and regional fleet specialists with localized lease expertise. Competitive dynamics center on telematics partnership networks and charging infrastructure access agreements rather than fleet size alone.
Within the legacy hub-operator tier, Enterprise Holdings and The Hertz Corporation exemplify scale-driven positioning through airport corridor dominance and corporate rate negotiation leverage. Sixt occupies a technology-leadership position among European operators with mobile-first booking platform architecture. Localiza anchors Latin American market presence through specialized long-term lease structures and corporate fleet management depth.
| Leading Market Players |
|---|
| LeasePlan |
| Sixt |
| Enterprise Holdings |
| BlueLine Rental |
| Localiza |
| The Hertz Corporation |
| Europcar Mobility Group |
| National Car Rental |
| Avis Budget Group |
| Others |
Supply Flow & Price Mechanics
Taiwanese semiconductor fabrication clusters anchor vehicle telematics module supply, concentrating pricing power among fleet operators with direct procurement relationships to Taipei-based component distributors. This geographic concentration compresses margins for rental operators lacking volume scale or captive supply agreements, while charging infrastructure capital requirements intensify cost pressure across electrified fleet portfolios.
Pricing Analysis
Frankfurt airport corridors command rate premiums 15-25% above regional German averages during peak business travel windows. Three-tier pricing structure across premium, standard, and economy levels segments demand by traveler archetype, with corporate procurement departments locking fixed rates through annual contracts. Cost compression in economy tiers is intensifying because ride-sharing platforms absorb price-sensitive local resident demand. Tourists exhibit highest price sensitivity, while C-suite mobility programs demonstrate inelastic demand for luxury segments with concierge bundling.
Supply Chain Analysis
US export controls on advanced semiconductor manufacturing equipment constrain Taiwanese and South Korean fab capacity expansion, limiting telematics chip availability for connected vehicle platforms. Vehicle supply draws from Germany, China, and Mexico for ICE platforms, with battery cell sourcing anchored in China, South Korea, and Japan for electric fleet transitions. Single-source vulnerability concentrates in lithium-ion cathode precursors from Chinese chemical processors. Distribution runs through OEM-direct fleet sales channels and third-party lessor procurement platforms with residual value guarantee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from mobility-as-a-service platforms that disintermediate fleet ownership entirely, requiring defensive repositioning around asset-light service architectures.
For Market Incumbents: Build switching-cost moats through integrated telematics platforms that embed fleet managers into proprietary data ecosystems. Consolidate charging infrastructure partnerships in Hamburg and Stuttgart corridors before municipal zero-emission zones expand. Absorb residual value risk through battery health monitoring capabilities that differentiate lease pricing from emerging fleet-subscription competitors. For New Entrants and Emerging Players: Pursue white-space expansion in India's PLI-subsidized electric vehicle assembly corridor, where localized production incentives reduce import duty exposure for multinational lessors. Target corporate lease segments in Bangalore and Mumbai with bundled maintenance structures that incumbent operators lack bandwidth to customize. Deploy direct sales teams with sustainability consulting capabilities to capture CSRD-aligned procurement mandates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with charging infrastructure access agreements and telematics platform depth over pure fleet-scale players. Long-term viability rests on bidirectional grid integration capabilities that monetize idle fleet assets. Acquisition targets should demonstrate vehicle-to-grid pilot deployments or exclusive fast-charging network partnerships. Watch municipal low-emission zone expansion timelines as inflection indicators for stranded ICE asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Exclusive fast-charging access in Berlin and Munich secures fleet utilization rates against operational dead zones. |
| Telematics Platform Integration | Proprietary usage tracking enables dynamic pricing models that improve residual value forecasting accuracy. |
| Vehicle-to-Grid Pilot Deployment | Bidirectional charging capabilities transform idle assets into grid stabilization revenue streams. |
| Battery Supply Agreement | Direct cathode precursor sourcing from South Korean processors reduces single-China supply vulnerability. |
| Corporate Sustainability Consulting | CSRD-aligned disclosure support captures procurement mandates from DAX-listed fleet managers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers at DAX-listed corporations, telematics platform engineers, charging infrastructure developers, and residual value analysts at major lessors. Secondary validation incorporated KBA registration data, EU F-Gas Regulation implementation timelines, PLI scheme disclosure filings, and customs records for vehicle component trade flows. Bottom-up fleet size estimates triangulated against top-down market value reconstructions.
Calibration against historical fleet turnover rates and electrification mandate phase-in schedules anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle class, lease duration structure, propulsion architecture, customer archetype, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for electric vehicle penetration combined with elasticity-adjusted pricing trajectories. Forecast inputs incorporated charging infrastructure deployment rates and battery degradation warranty cost curves.
Macroeconomic conditions sit as an overlay; deviation in central bank monetary policy and commercial fleet capex cycles would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement timelines and technology cost curves. Material shifts in EU Green Deal implementation pace or Taiwan semiconductor supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
United States Car Loan Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
China Mortgage/Loan Brokers Market
Loans and Leasing
Loan Management Software Market
Loans and Leasing
Machinery Rental and Leasing Market
Loans and Leasing
Asset-Based Lending Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
Refinancing Market
Loans and Leasing
Loan Servicing Software Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
Europe Used Car Financing Market