
 North America Used Car Financing Market | 2026-2036
North America Used Car Financing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Used Car Financing Market Analytics
Digital origination platforms and AI-driven underwriting engines are reshaping how used car financing is sourced, priced, and disbursed across North America. Ally Financial leverages its captive dealer relationships and proprietary digital tools to sustain volume leadership in indirect auto lending. Santander Consumer Finance specializes in non-prime segments, dominating risk-adjusted pricing models that competitors struggle to replicate. Westlake Financial Services anchors its position through deep integration with independent dealership networks across the southern United States.
Used car financing encompasses secured lending instruments collateralized by pre-owned vehicles, typically structured as simple-interest installment contracts with loan-to-value ratios calibrated against wholesale auction data and vehicle depreciation curves. The primary commercial purpose centers on enabling vehicle ownership for consumers lacking full purchase liquidity while generating interest income and fee revenue for originators. Dealer financing occupies the largest volume share due to its embedded placement at the point of sale, though credit unions are gaining structural ground by offering lower rate spreads and member-centric servicing. Medium-term loan durations represent the fastest-growing structural category as consumers balance affordable monthly payments against total interest cost accumulation.
The Consumer Financial Protection Bureau monitors auto lending for fair lending violations and deceptive marketing practices, while state usury laws and the Truth in Lending Act govern rate disclosure and contract transparency across the United States. The Office of the Comptroller of the Currency supervises national bank originators, ensuring capital adequacy and compliance management systems keep pace with portfolio growth in higher-risk segments. Stakeholders must monitor how evolving federal preemption standards and state-level rate cap initiatives interact to reshape permissible lending economics across jurisdictions.
Market Dynamics
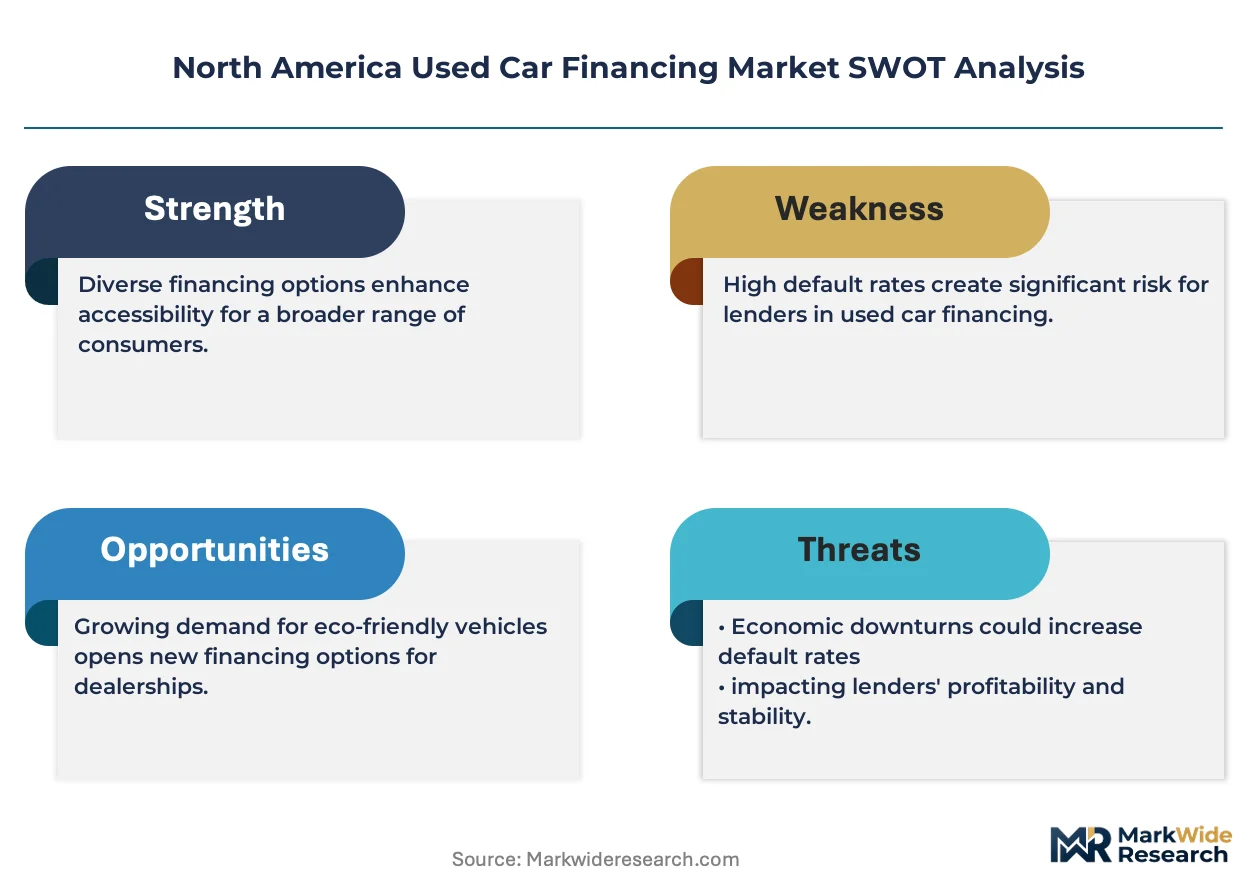
The Consumer Financial Protection Bureau's intensified scrutiny of dealer markup practices is compressing origination economics and forcing lenders toward direct-to-consumer channels across the United States and Canada.
Growth Catalysts
- Alternative credit scoring:Cash-flow underwriting models incorporating bank transaction data expand access for thin-file borrowers in Texas and Florida. TransUnion's expanded data partnerships accelerate risk-model refinement.
- Embedded finance APIs:Dealer management system integrations reduce application abandonment rates. RouteOne and Dealertrack platforms streamline instant decisioning at point-of-sale terminals.
- Electric vehicle residual value stabilization:Improved battery health diagnostics support longer loan terms on used EVs. Black Book and KBB valuation engines now incorporate battery state-of-health metrics.
Market Restraints
- Wholesale auction concentration:Manheim and ADESA control 85% of US used vehicle price discovery. Disruption at either platform immediately distorts loan-to-value calculations.
- State usury fragmentation:Rate caps in California, New York, and Illinois create origination dead zones. Lenders must maintain jurisdiction-specific pricing engines.
- Interest rate volatility:Federal Reserve policy shifts compress net interest margins. Hedging costs for fixed-rate portfolios have doubled since 2022.
Strategic Opportunities
- Credit union channel expansion:Member-centric servicing models capture prime-borrower defections from bank-owned captives. Pentagon Federal and Navy Federal demonstrate scalable direct-lending templates.
- Subscription-to-ownership bridges:Lease-end buyout financing captures vehicle equity for ride-share drivers. Uber and Lyft partner programs create captive conversion pipelines.
- Mexico cross-border origination:US-dollar lending for Mexican nationals with US income documentation remains underserved. Santander's border-state infrastructure provides template replication.
Industry Challenges
- Legacy servicing system integration:Core banking platforms from FIS and Jack Henry require costly API middleware for real-time payment processing. Fintech-native competitors bypass this constraint entirely.
- Title perfection delays:Electronic lien and title (ELT) adoption varies by state, extending funding timelines. Texas and California backlogs create 14-day average hold periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Used Car Financing Market |
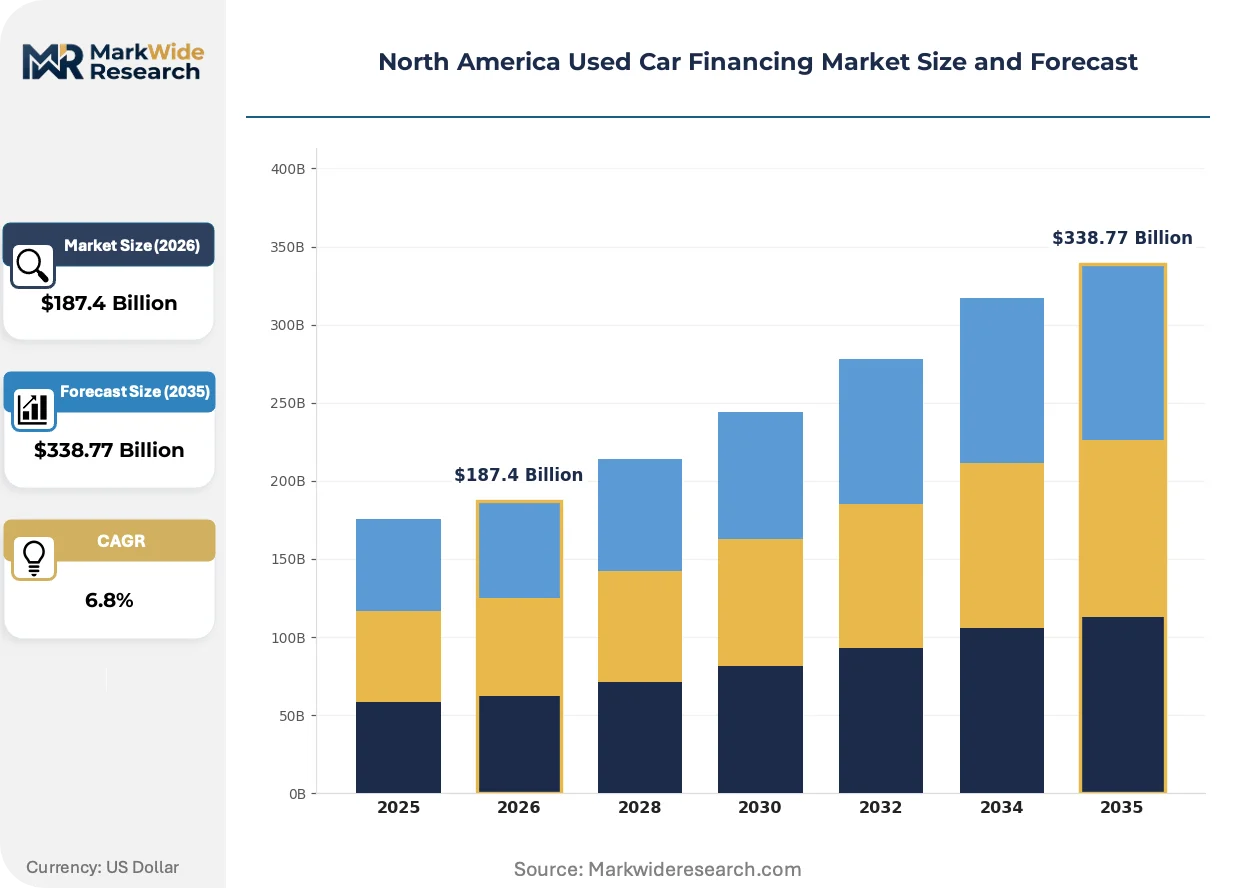
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Financial Product: Personal Loans, Credit Unions, Dealer Financing, Bank Loans Vehicle Type: Sedan, SUV, Truck, Coupe Customer Segment: First-Time Buyers, Repeat Customers, Businesses, Leasing Companies Loan Duration: Short-Term, Medium-Term, Long-Term, Flexible-Term |
| Companies Covered | Ally Financial, Capital One Auto Finance, Santander Consumer Finance, Westlake Financial Services, Toyota Financial Services, Bank of America, Chase Auto Finance, General Motors Financial Company, Wells Fargo Auto Finance, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Used Car Financing Market Evolving Landscape
Artificial intelligence is rewriting underwriting workflows while regulatory pressure on dealer compensation models accelerates channel diversification across North American auto lending.
Machine learning credit decisioning is migrating from traditional FICO-centric scoring toward alternative data composites. Subprime specialists now ingest utility payment histories and rental records through Plaid and Finicity connections. This shift compresses approval times from hours to seconds while expanding addressable borrower pools beyond legacy credit-bureau coverage.
The Consumer Financial Protection Bureau's 2023 guidance on dealer participation limits has triggered structural repricing across indirect lending channels. Captive finance arms now cap dealer reserve spreads at 100 basis points in California and New York. Independent dealerships respond by steering volume toward credit unions and direct lenders with flat-fee compensation structures.
Digital retailing platforms are unbundling the traditional showroom experience into discrete online transactions. Carvana and Vroom conditioned consumers to complete financing without physical dealer contact. This behavioral shift concentrates most heavily in Arizona and Nevada, where vehicle delivery logistics and sparse dealer density favor remote origination workflows.
North America Used Car Financing Market Segmentation
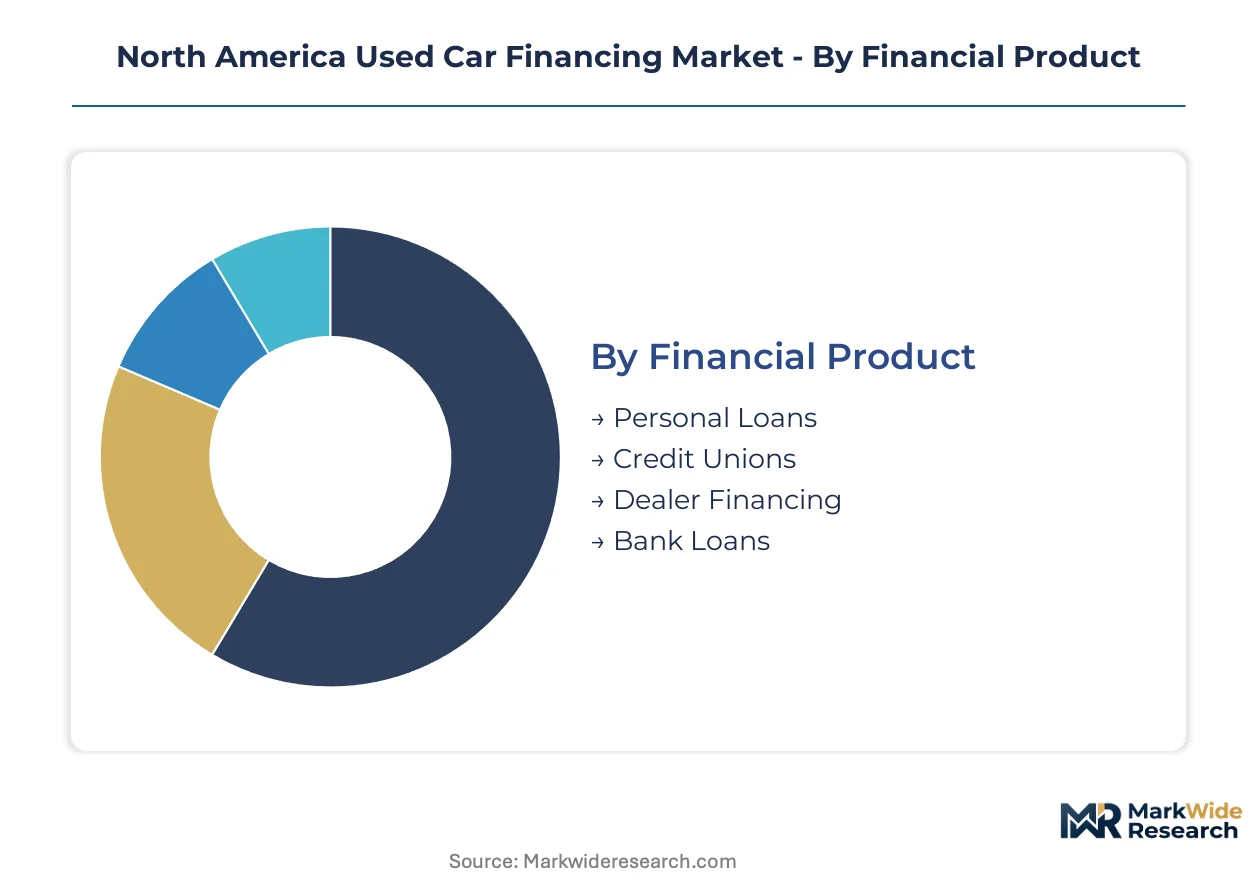
Used car financing segments reflect divergent risk appetites and origination economics across North America. Lenders calibrate product structures, collateral profiles, and servicing intensity to match borrower liquidity constraints and vehicle depreciation trajectories.
Financial Product:
Mature products dominate origination volume while emerging digital channels reshape distribution economics.
- Dealer Financing:Indirect lending embedded at point-of-sale through captive finance arms and independent dealership networks. Volume concentrates in Texas and Florida where dealer density and state regulatory permissiveness sustain markup economics. The Consumer Financial Protection Bureau's dealer participation limits are compressing spreads in California and New York.
- Credit Unions:Member-owned cooperatives offering below-market rate spreads and personalized servicing. Pentagon Federal and Navy Federal demonstrate scalable direct-lending templates capturing prime-borrower defections from bank captives. Lower cost of funds enables aggressive pricing in competitive markets.
- Personal Loans:Unsecured installment credit from fintech platforms and marketplace lenders. Plaid and Finicity bank connections enable cash-flow underwriting for thin-file borrowers outside traditional credit-bureau coverage.
- Bank Loans:Direct origination through branch networks and digital portals. National banks leverage balance sheet scale for competitive pricing, though legacy core systems constrain real-time decisioning speed.
Dealer financing handles the majority of throughput; credit unions are expanding most quickly on share.
Vehicle Type:
Collateral risk profiles diverge sharply across body styles and residual value trajectories.
- Truck:Full-size and mid-size pickups command premium pricing power and slower depreciation curves in southern United States markets. Fleet demand from construction and energy sectors sustains elevated loan-to-value ratios.
- SUV:Crossover and sport-utility vehicles dominate household financing in suburban and exurban geographies. Black Book valuation engines track segment-specific depreciation patterns against wholesale auction benchmarks.
- Sedan:Traditional passenger cars face compressed residual values as consumer preference shifts toward larger vehicles. Financing terms shorten to match accelerated depreciation schedules.
- Coupe:Two-door performance and luxury vehicles attract niche financing with specialized collateral monitoring. Lower volume throughput requires tailored underwriting expertise.
SUV and truck segments together anchor collateral value stability; electric vehicle variants within SUV are gaining share fastest.
Customer Segment:
Borrower lifecycle position determines pricing elasticity and servicing intensity requirements.
- Repeat Customers:Established payment histories enable streamlined re-approval and rate concessions. Refinancing activity and trade-in equity deployment concentrate origination efficiency.
- First-Time Buyers:Thin credit files necessitate alternative data integration and higher risk-adjusted pricing. Cash-flow underwriting models from TransUnion partnerships expand addressable pools.
- Businesses:Commercial fleet financing structured around depreciation schedules and tax optimization. Entity-level underwriting replaces consumer FICO reliance.
- Leasing Companies:Lease-end buyout financing captures residual equity for fleet operators and ride-share drivers. Uber and Lyft partner programs create captive conversion pipelines.
Repeat customers generate the majority of portfolio profitability; first-time buyer channels are climbing the fastest on origination volume.
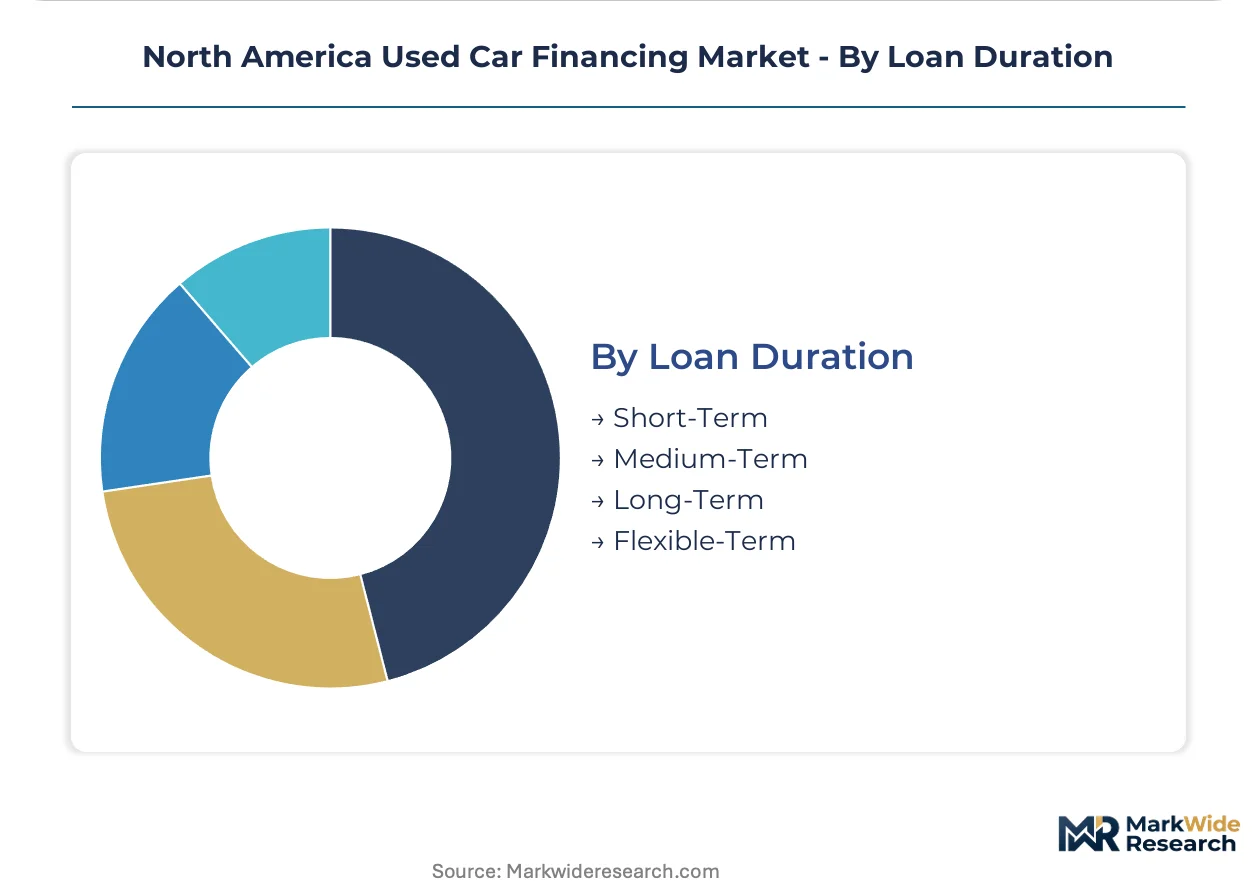
Loan Duration:
Term structure calibration balances monthly affordability against total interest cost accumulation.
- Medium-Term:48-to-60-month structures optimize payment-to-income ratios for prime and near-prime borrowers. This category captures the fastest expansion as consumers resist extended amortization schedules.
- Long-Term:72-to-84-month terms reduce monthly obligations while elevating total interest expense and negative equity risk. Subprime specialists deploy these structures to qualify marginal borrowers.
- Short-Term:24-to-36-month financing minimizes interest cost for cash-flow-strong borrowers. Credit unions and prime-direct channels dominate this compressed-yield segment.
- Flexible-Term:Adjustable amortization with balloon structures or payment holidays. Emerging fintech platforms test these configurations for gig-economy income volatility.
Medium-term structures handle the majority of new origination flow; flexible-term products are gaining traction fastest among alternative lenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian originators export financing structures to United States dealer networks, while Mexican nationals with cross-border income documentation drive demand for US-dollar denominated products in border states.
United States
Texas and Florida sustain the highest origination volumes through dealer density and permissive regulatory environments. The Consumer Financial Protection Bureau enforces dealer participation limits and fair lending standards across indirect channels. Southern metropolitan clusters including Houston, Dallas, and Miami anchor captive finance arm penetration.
Canada
Credit union networks capture prime-borrower defections through member-centric servicing models and below-market rate spreads. The Office of the Superintendent of Financial Institutions supervises national bank originators for capital adequacy and compliance management. Ontario and British Columbia concentrate digital direct-lending adoption in Toronto and Vancouver corridors.
Mexico
Cross-border income documentation for Mexican nationals working in United States markets sustains underserved demand for US-dollar lending products. The Comisión Nacional Bancaria y de Valores regulates peso-denominated auto lending while dollar products fall under US jurisdiction. Northern border states including Nuevo León and Chihuahua channel Santander's infrastructure template replication.
North America Used Car Financing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across origination workflows. The market structures around three tiers: captive finance arms with embedded dealer relationships, independent non-prime specialists with risk-adjusted pricing expertise, and credit unions with cost-of-fund advantages. Strategic archetypes include indirect-lending volume leaders, alternative-data underwriters, and member-owned direct lenders. Dominant competitive moves encompass API integration with dealer management systems and geographic expansion into underserved sub-prime corridors.
Among United States-based diversified financial services companies, Ally Financial and Capital One Auto Finance exemplify indirect-lending scale archetypes. Santander Consumer Finance anchors the non-prime specialist position through risk-model differentiation. Westlake Financial Services occupies a channel-integration position within independent dealership networks across southern United States markets.
| Leading Market Players |
|---|
| Ally Financial |
| Capital One Auto Finance |
| Santander Consumer Finance |
| Westlake Financial Services |
| Toyota Financial Services |
| Bank of America |
| Chase Auto Finance |
| General Motors Financial Company |
| Wells Fargo Auto Finance |
| Others |
Value Network & Pricing Analysis
The I-35 freight corridor connecting Texas manufacturing clusters to Midwest distribution hubs shapes cost dynamics across the North American used car financing ecosystem. Concentrated auction volume through Manheim and ADESA facilities along this route compresses logistics expenses for lenders collateralizing inventory, while originators in California and New York absorb elevated transport costs that feed into rate spread differentials for distant borrowers.
Pricing Analysis
Technology-generation pricing gaps separate AI-enabled underwriting platforms from legacy FICO-centric systems and emerging blockchain-based title verification tools. Three-tier pricing structure across premium algorithmic scoring, standard bureau-based assessment, and economy manual review segments dominates origination economics. Pricing pressure stems from credit union rate competition in prime segments, compressing bank captive margins. First-time buyers exhibit highest price sensitivity, while repeat customers with established payment histories accept modest rate premiums for convenience.
Supply Chain Analysis
Export-control regimes limiting cross-border data flows constrain alternative credit scoring partnerships between US originators and Mexican data providers. Geographic supply concentration centers on Texas, Florida, and California as origination volume anchors. Raw material dependencies include wholesale auction data feeds, electronic lien and title infrastructure, and dealer management system API integrations. Single-source vulnerability sits with Manheim and ADESA controlling price discovery. Distribution runs through captive finance arms, independent dealership networks, and direct-to-consumer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in real-time alternative data integration capabilities separates competitive winners from legacy originators struggling with core banking platform constraints. Lenders lacking Plaid or Finicity connectivity face widening approval speed disadvantages.
For Market Incumbents: Harden API infrastructure against fintech-native competitors bypassing legacy core banking constraints through middleware investments with FIS and Jack Henry. Consolidate dealer relationships in Texas and Florida where markup economics remain permissive, countering credit union prime-borrower poaching with rate-matching programs. Vertical integration into direct-to-consumer channels offsets indirect lending compression from Consumer Financial Protection Bureau dealer participation limits. For New Entrants and Emerging Players: Pursue cross-border origination for Mexican nationals with US income documentation in Nuevo León and Chihuahua, replicating Santander's border-state infrastructure template. Target first-time buyer segments underserved by FICO-dependent underwriters through cash-flow scoring partnerships with TransUnion. Deploy embedded finance APIs integrating with RouteOne and Dealertrack platforms as primary go-to-market angle. For Investors and Strategic Acquirers: Consumer Financial Protection Bureau preemption standard evolution reshapes the acquisition landscape, favoring originators with compliance infrastructure spanning multiple state jurisdictions. Long-term viability concentrates in entities with alternative data underwriting capabilities and direct-lending channel diversification. Monitor electronic lien and title adoption rates across Texas and California as signal for operational efficiency inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Data Partnership | Plaid and Finicity integrations compress approval timelines from hours to seconds for thin-file borrowers. |
| Direct-to-Consumer Channel Buildout | Carvana-conditioned consumer behavior in Arizona and Nevada favors remote origination workflows. |
| Credit Union Competitive Response | Pentagon Federal and Navy Federal templates demonstrate scalable member-centric servicing models. |
| Cross-Border Infrastructure Expansion | Santander's border-state presence provides replicable framework for Mexican national lending. |
| API Middleware Investment | Real-time payment processing capabilities bypass legacy FIS and Jack Henry platform constraints. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, wholesale auction data, and credit bureau partnership disclosures. Conversations with auto lending executives, dealer operations managers, credit union portfolio directors, and fintech platform engineers informed origination workflow assessments. Secondary validation drew from Consumer Financial Protection Bureau enforcement actions, Office of the Comptroller of the Currency guidance, state usury law compilations, and dealer management system integration documentation. Bottom-up loan origination volume estimates triangulated against top-down market sizing from collateral value and transaction frequency data.
Forecast inputs incorporate vehicle depreciation curves, migration-driven demand shifts, and regulatory enforcement intensity variations across the projection horizon. Segmentation modeling spans financial product type, vehicle collateral class, borrower lifecycle position, and loan duration structure. CAGRs derive from compound growth trajectory fitting against historical origination patterns and macroeconomic elasticity assumptions. Electric vehicle residual value stabilization and embedded finance API adoption rates constitute industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Federal Reserve policy trajectory, unemployment rates in Texas and Florida, and cross-border labor mobility would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement continuity and wholesale auction platform stability. Material shifts in state usury law preemption standards or electronic lien and title adoption mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
Europe Syndicated Loans Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Latin America Motorcycle Loan Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
Cash Advance Services Market
Loans and Leasing
Canada Student Loan Market
Loans and Leasing
United States Car Loan Market
Loans and Leasing
Alternative Lending Platform Market
Loans and Leasing
NPL Servicing Market
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Brazil Auto Loan Market
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
India Home Loan Market