
 Asset-Based Lending Market | 2026-2036
Asset-Based Lending Market Size, Share, and Industry Trends Forecast 2026-2036
Asset-Based Lending Market Analysis
Commercial bank syndication channels is rewriting how asset-based credit reaches middle-market borrowers. JPMorgan Chase and Co. anchors the upper-tier corporate segment through its wholesale lending infrastructure. White Oak Financial LLC specializes in non-bank direct lending for asset-heavy enterprises outside traditional bank coverage. Wells Fargo and Company sustains broad geographic distribution through its regional commercial banking network.
Asset-based lending denotes secured credit facilities collateralized by tangible business assets, typically advancing 70-85% against eligible receivables and 50-60% against appraised inventory, with loan-to-value ratios governed by periodic field examinations and borrowing base certificates. Working capital loans dominate transaction volume as seasonal manufacturers and distributors draw against fluctuating receivable pools. Equipment financing commands tighter margins but longer tenors, attracting private equity firm capital seeking yield through physical asset security. Accounts receivable collateralization leads among collateral types because automated invoice verification and lockbox structures reduce monitoring costs for commercial banks.
US regulators including the Federal Reserve, OCC, and FDIC impose risk-based capital requirements that steer bank holding companies toward fully collateralized facilities. SEC disclosure obligations for registered borrowers shape covenant packages and reporting frequency across syndicated asset-based transactions. Stakeholders must track how AI-driven collateral monitoring and real-time borrowing base platforms alter examiner expectations and competitive positioning in secured lending.
Market Dynamics
Basel III capital adequacy frameworks are compressing bank balance sheets toward secured lending structures, redirecting institutional capital into collateralized credit facilities as risk-weighted asset optimization becomes mandatory.
Growth Catalysts
- Basel III Implementation:Risk-weighted capital requirements under US Federal Reserve and OCC guidelines steer bank holding companies toward fully collateralized facilities, expanding the addressable pool for asset-backed structures.
- Manufacturing Inventory Cycles:Seasonal middle-market manufacturers in automotive parts and industrial equipment deploy revolving credit lines against fluctuating receivable pools to manage working capital gaps.
- AI-Driven Collateral Monitoring:Real-time borrowing base platforms with automated invoice verification reduce examiner oversight costs and accelerate drawdown velocity for commercial bank syndicates.
Market Restraints
- Appraisal Cost Inflation:Field examination fees for inventory and equipment valuations have risen substantially, compressing net returns on smaller facility sizes below minimum bank profitability thresholds.
- Receivables Concentration Risk:Single-obligor exposure limits in syndicated structures restrict advance rates against customer pools where one debtor exceeds 15% of total eligible collateral.
- Substitution by Cash Flow Lending:Unsecured term loans from private credit funds compete directly for middle-market borrowers with strong EBITDA profiles, bypassing collateral complexity entirely.
Strategic Opportunities
- India Working Capital Gap:The Reserve Bank of India's priority sector lending mandates create structural demand for receivables financing among MSME manufacturers underserved by traditional term credit.
- ESG-Linked Facility Structures:Sustainability performance pricing tied to carbon disclosure metrics offers differentiation for borrowers seeking capital from ESG-mandated institutional investors.
- Supply Chain Finance Convergence:Integration of dynamic discounting platforms with traditional ABL structures creates unified working capital solutions linking buyers, suppliers, and lenders.
Industry Challenges
- Legacy System Integration:Borrowing base certificate automation requires API connectivity between borrower ERP systems and lender collateral monitoring platforms, creating implementation friction for mid-sized enterprises.
- Specialized Underwriting Talent:Field examiners with dual expertise in UCC Article 9 perfection and industry-specific inventory valuation remain scarce, extending facility onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asset-Based Lending Market |
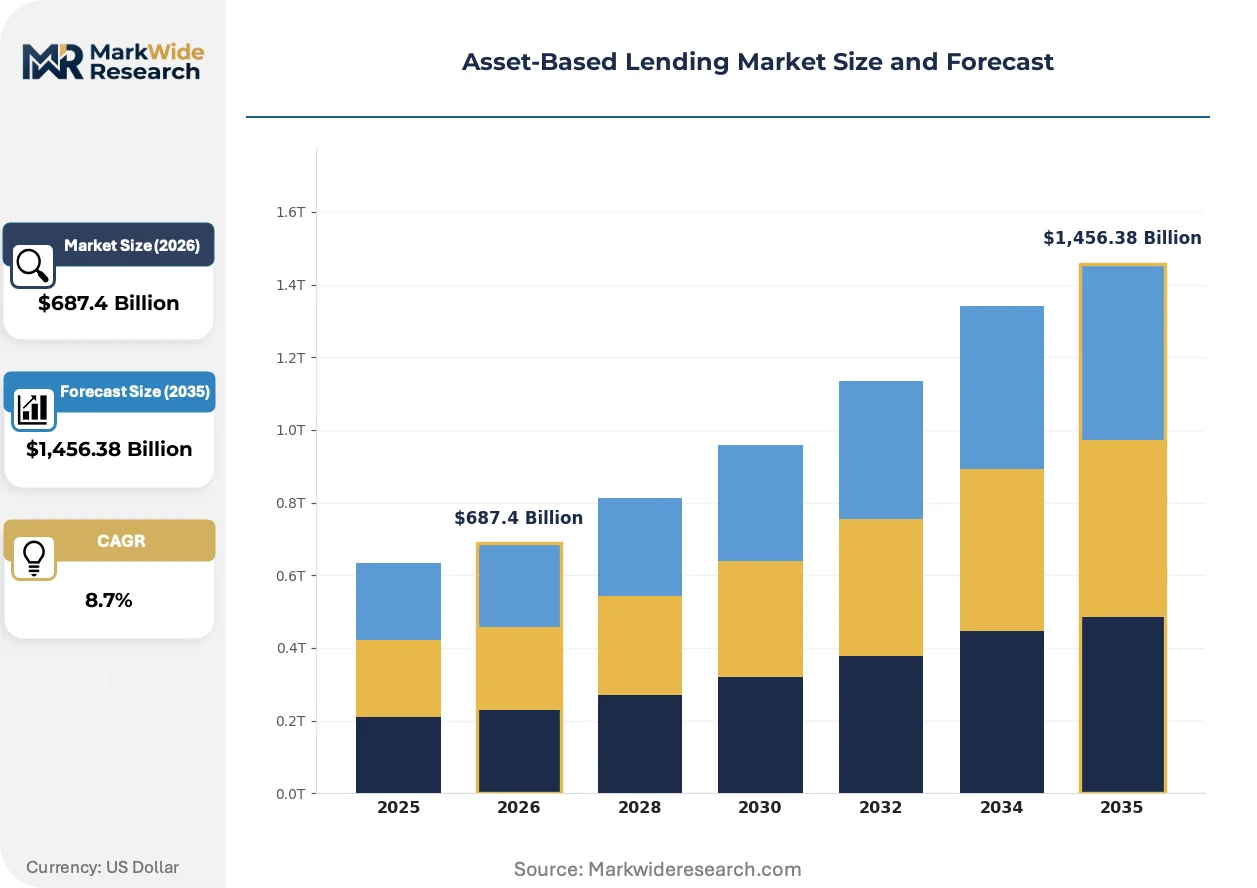
| Market Size in 2026 | $687.4 Billion |
| Market Size in 2035 | $1,456.38 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Working Capital Loans, Equipment Financing, Inventory Financing, Real Estate Loans Client Segment: Small Businesses, Large Enterprises, Startups, Nonprofits Collateral Type: Accounts Receivable, Inventory, Equipment, Real Estate Service Provider: Commercial Banks, Private Equity Firms, Finance Companies, Credit Unions |
| Companies Covered | Goldman Sachs Group Inc., Barclays Bank PLC, JPMorgan Chase and Co., White Oak Financial LLC, Huntington Business Credit, Wells Fargo and Company, BMO Harris Bank N.A., CIT Group, HSBC Holdings plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asset-Based Lending Market Emerging Trajectories
Digital collateral monitoring and automated borrowing base certification are compressing facility administration costs while enabling real-time covenant compliance tracking across distributed borrower portfolios.
Blockchain-based smart contracts for receivables verification are migrating from pilot programs to production deployments at major commercial banks. JPMorgan Chase and Co. has integrated distributed ledger technology into its wholesale lending infrastructure for invoice authentication. This migration from manual audit trails to cryptographically secured transaction records is reducing field examination frequency and accelerating cash availability for qualified borrowers.
The EU's Corporate Sustainability Reporting Directive imposes granular disclosure obligations on large borrowers regarding supply chain financing arrangements. ABL facilities must now document ESG-linked pricing mechanisms and collateral origination standards in syndicated credit agreements. European middle-market manufacturers are responding by segregating eligible receivables from high-carbon-intensity counterparties to preserve advance rate capacity.
Buyers are consolidating vendor relationships and demanding integrated treasury solutions that bundle ABL facilities with cash management and FX hedging. Regional commercial banks face disintermediation unless they can offer unified working capital platforms. This pattern is most visible in the United States, where middle-market distributors increasingly source all liquidity products from single relationship banks rather than fragmented specialty lenders.
Asset-Based Lending Market Segmentation
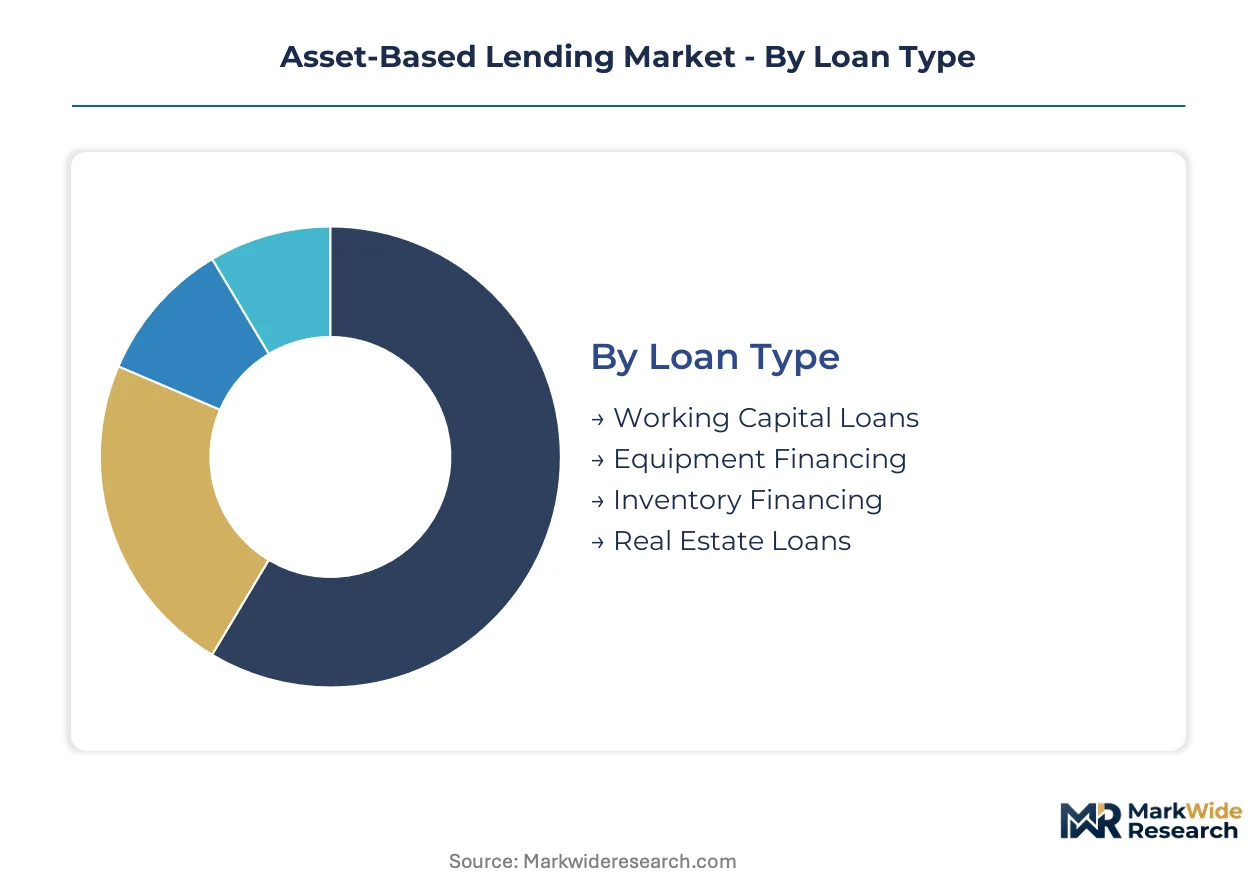
Asset-based lending structures vary dramatically in collateral turnover velocity and monitoring intensity. Borrowing base certificates reset weekly for receivables-backed facilities but stretch to annual appraisals for real estate collateral. Understanding these cycle-time differentials shapes lender staffing models and borrower liquidity planning.
Loan Type:
Working capital facilities turn over fastest as receivable pools refresh every 30-90 days, while real estate loans lock capital for years with minimal collateral fluctuation.
- Working Capital Loans:Revolving credit structures collateralized by eligible receivables and short-term inventory with borrowing base certificates submitted monthly. US middle-market manufacturers in automotive parts and industrial equipment draw against seasonal receivable peaks to fund production ramps.
- Equipment Financing:Term loans secured by machinery and vehicles with longer amortization schedules reflecting physical asset depreciation curves. Private equity sponsors favor these structures for yield stability through collateral recovery rights.
- Inventory Financing:Advance rates against finished goods and raw materials require field examinations and perpetual inventory tracking. Retail distributors with seasonal merchandise cycles deploy these facilities to bridge procurement-to-sale gaps.
- Real Estate Loans:Commercial mortgage structures on owner-occupied or investment properties with appraisal-based loan-to-value ratios. These facilities carry the longest tenors and tightest spreads in secured lending portfolios.
Working capital loans anchor the volume base while equipment financing gains share at the steepest rate among institutional capital providers.
Client Segment:
Enterprise scale determines facility complexity, with large borrowers accessing syndicated structures and small businesses limited to single-lender relationships with higher all-in costs.
- Small Businesses:Borrowers with annual revenues under $50 million access asset-based credit through regional commercial banks and finance companies. These facilities face higher effective rates due to disproportionate underwriting and monitoring costs relative to facility size.
- Large Enterprises:Corporate borrowers with syndicated multi-bank facilities leverage receivable pools across multiple jurisdictions. JPMorgan Chase and Wells Fargo compete for lead arranger roles on these upper-tier transactions.
- Startups:Venture-backed companies with limited operating history collateralize equipment and intellectual property through specialized non-bank lenders. White Oak Financial targets this segment with tailored advance rate structures.
- Nonprofits:Hospitals and educational institutions pledge real estate and grant receivables to secure tax-exempt financing. These borrowers face unique covenant restrictions on asset disposition.
Large enterprises dominate committed capital while startups attract the most specialized underwriting talent.
Collateral Type:
Liquidity and valuation certainty separate collateral classes, with receivables converting to cash fastest and real estate requiring extended marketing periods.
- Accounts Receivable:Invoice pools verified through lockbox arrangements and automated aging reports with advance rates typically 70-85%. Commercial banks favor this collateral for real-time monitoring feasibility and rapid liquidation pathways.
- Inventory:Raw materials, work-in-process, and finished goods subject to field examination and obsolescence reserves. Automotive and aerospace manufacturers with long production cycles face stricter eligibility criteria.
- Equipment:Machinery and vehicles with standardized resale markets command advance rates tied to forced liquidation value. Yellow iron and transportation equipment carry the most reliable secondary markets.
- Real Estate:Commercial properties with third-party appraisals and environmental assessments supporting longer-term facilities. These assets require the most intensive due diligence but provide collateral stability.
Accounts receivable collateral anchors the volume base while inventory financing climbs the fastest as automated tracking technologies reduce examiner costs.
Service Provider:
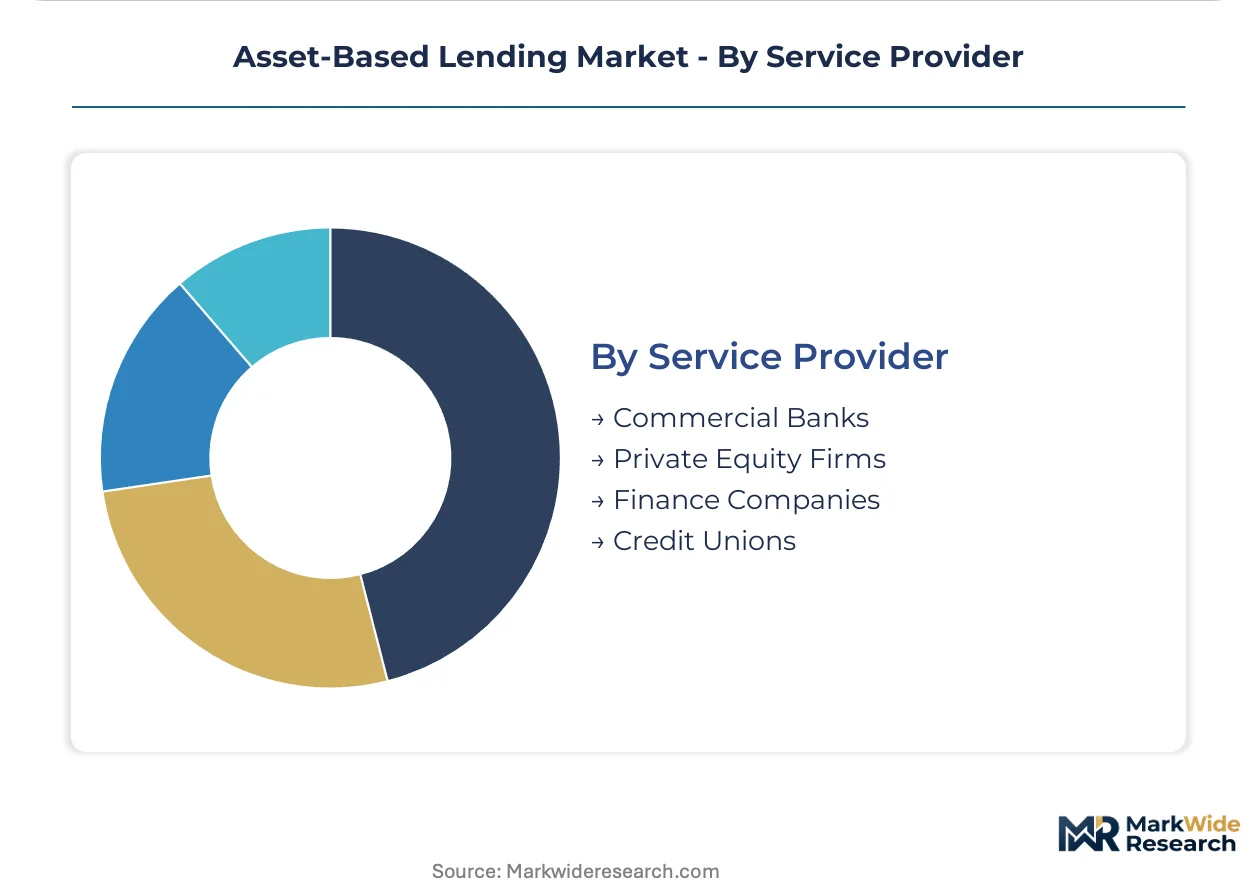
Capital source determines pricing, flexibility, and covenant intensity, with banks optimizing for regulatory capital efficiency and private funds targeting yield enhancement.
- Commercial Banks:Regulated depositories with Basel III risk-weighted capital advantages pricing secured facilities tighter than unsecured alternatives. OCC and Federal Reserve oversight shapes collateral documentation standards.
- Private Equity Firms:Non-bank capital providers including business development companies and direct lending funds seeking yield through specialized collateral expertise. These lenders accept complexity that banks avoid.
- Finance Companies:Captive and independent lenders focusing on equipment and vehicle collateral with residual value underwriting capabilities. Their cost of funds sits between banks and private equity.
- Credit Unions:Member-owned cooperatives with community charter limitations serving small business borrowers in defined geographic footprints. NCUA regulations constrain concentration limits and collateral types.
Commercial banks anchor the volume base while private equity firms expand most quickly into bank-exited segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of New York and New Jersey's freight rail interconnections anchor North American working capital velocity, while Singapore's port infrastructure underwrites Asia-Pacific trade finance flows. These logistics backbones determine where asset-based credit concentrates against receivable and inventory collateral.
United States
Middle-market manufacturers in automotive parts and industrial equipment deploy revolving credit lines against seasonal receivable pools. Federal Reserve risk-based capital requirements steer bank holding companies toward fully collateralized facilities under Basel III frameworks. Chicago's commodity trading floors and Houston's energy distribution hubs generate concentrated demand for inventory-backed working capital structures.
Germany
Mittelstand manufacturers in precision engineering and automotive supply chains leverage equipment and receivable collateral to fund export-driven production cycles. The European Central Bank's collateral eligibility criteria shape advance rate structures for cross-border facilities. Bavaria's industrial corridor around Munich and Stuttgart anchors the densest concentration of asset-backed working capital deployment in continental Europe.
United Kingdom
Post-trade finance receivables from London's commodity and shipping brokers feed specialized collateral monitoring platforms. The Prudential Regulation Authority's implementation of Basel III standards compresses bank balance sheets toward secured lending. The Midlands manufacturing belt and Thames Valley distribution networks sustain regional demand for inventory financing against finished goods.
India
MSME manufacturers in textiles and automotive components face structural working capital gaps underserved by traditional term credit. Reserve Bank of India priority sector lending mandates create regulatory pull for receivables financing structures. Gujarat's petrochemical clusters and Tamil Nadu's automotive assembly plants generate concentrated collateral pools for asset-backed facilities.
China
Private manufacturers in Zhejiang and Guangdong provinces collateralize export receivables against volatile working capital needs. The People's Bank of China's collateral management framework governs eligible asset classes for secured credit extension. The Yangtze River Delta's electronics assembly corridors and Pearl River Delta's consumer goods exporters anchor the largest receivable-backed facility volumes in Asia.
Asset-Based Lending Market Vendor Landscape
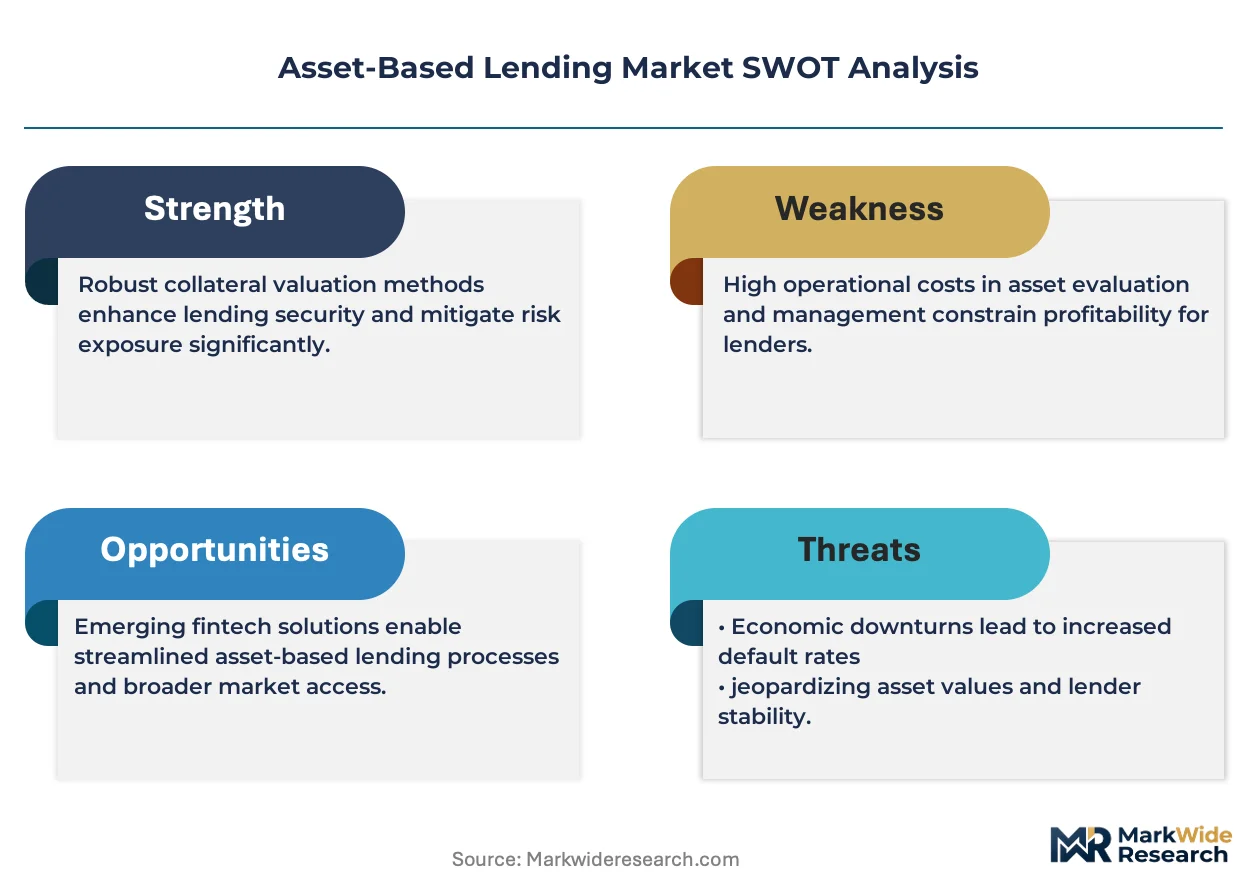
On the supply side, the industry is tiered between regulated depositories optimizing for capital efficiency and non-bank specialists capturing complexity premiums. Commercial banks with Basel III risk-weighted advantages price secured facilities tighter than unsecured alternatives, while private credit funds accept collateral structures that regulated lenders avoid. Strategic archetypes include universal bank syndicators, direct lending specialists, and regional commercial banking networks. Dominant competitive moves center on technology platform integration for real-time collateral monitoring and geographic expansion into underserved middle-market corridors.
Within the universal banking tier, JPMorgan Chase and Co. and Wells Fargo and Company exemplify scale-driven syndication capabilities across multi-jurisdictional receivable pools. White Oak Financial LLC occupies a specialist position among non-bank direct lenders targeting asset-heavy enterprises outside traditional bank coverage parameters. These three entities represent contrasting archetypes: regulated balance sheet depth, distributed regional infrastructure, and specialized collateral expertise respectively.
| Leading Market Players |
|---|
| Goldman Sachs Group Inc. |
| Barclays Bank PLC |
| JPMorgan Chase and Co. |
| White Oak Financial LLC |
| Huntington Business Credit |
| Wells Fargo and Company |
| BMO Harris Bank N.A. |
| CIT Group |
| HSBC Holdings plc |
| Others |
Supply Flow & Price Mechanics
The Port of New York and New Jersey's freight rail interconnections generate cost dynamics that concentrate supply among syndicated bank groups while forcing regional lenders toward price differentiation through service bundling and geographic specialization.
Pricing Analysis
Volume-discount tiering structures dominate asset-based lending, with three-tier pricing separating syndicated multi-bank facilities from single-lender regional arrangements and specialized non-bank structures. Price differentiation rests on facility size scale and collateral monitoring automation level, with AI-enabled real-time borrowing base platforms commanding premium pricing. Cost compression in smaller facility tiers is intensifying because field examination fees have risen disproportionately relative to facility returns. Small businesses with revenues under $50 million exhibit the highest price sensitivity due to disproportionate underwriting costs, while large enterprises with syndicated structures leverage competitive bidding among lead arrangers.
Supply Chain Analysis
Supplier-financing angles including extended payment terms and dynamic discounting platforms now integrate with traditional asset-based structures, creating unified working capital solutions. Geographic supply concentration draws from the United States, Germany, and India, with each anchoring distinct collateral origination patterns around automotive receivables, precision engineering equipment, and textile inventory respectively. Raw material dependencies span finished goods inventory, machinery depreciation curves, and invoice verification technologies. Single-source vulnerability in field examiner talent pools creates onboarding bottlenecks. Distribution runs through commercial bank syndication channels, direct non-bank lending relationships, and captive finance company networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power in asset-based lending is shifting toward consolidated middle-market distributors demanding integrated treasury solutions, fragmenting regional bank relationships as single-source banking replaces fragmented specialty lender arrangements.
For Market Incumbents: Build data moats through API-integrated collateral monitoring platforms that lock borrower ERP connectivity. Defensive moves require acquiring specialized field examination firms to secure scarce dual-expertise talent in UCC Article 9 perfection and industry-specific inventory valuation. The threat of private credit funds offering unsecured cash flow lending bypassing collateral complexity entirely demands countermeasures through faster drawdown velocity enabled by real-time borrowing base automation. For New Entrants and Emerging Players: Establish a beachhead in India's MSME manufacturing corridor where Reserve Bank of India priority sector lending mandates create structural demand underserved by traditional term credit. White-space targets include Gujarat's petrochemical clusters and Tamil Nadu's automotive assembly plants for receivables financing specialization. The most penetrable segment combines automated invoice verification with lockbox structures for textile and automotive component manufacturers. A direct go-to-market angle through supply chain finance convergence linking buyers, suppliers, and lenders bypasses entrenched bank relationships. For Investors and Strategic Acquirers: Non-bank direct lending specialists with proprietary collateral monitoring technology represent the priority acquisition archetype for yield-enhancing portfolio diversification. Long-term viability across the projection horizon depends on regulatory arbitrage between Basel III-constrained bank balance sheets and private capital flexibility. The inflection signal to watch is migration velocity of blockchain-based smart contracts from pilot programs to production deployments at major commercial banks, indicating technology platform maturation.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Collateral Platform Integration | JPMorgan Chase's distributed ledger deployment for invoice authentication reduces field examination frequency and accelerates cash availability. |
| ESG-Linked Facility Structure Development | Sustainability performance pricing tied to carbon disclosure metrics attracts capital from ESG-mandated institutional investors in European markets. |
| Supply Chain Finance Convergence | Dynamic discounting platform integration with traditional ABL structures creates unified working capital solutions linking buyers, suppliers, and lenders. |
| Specialized Underwriting Talent Acquisition | Field examiners with dual expertise in UCC Article 9 perfection and industry-specific inventory valuation remain scarce, extending facility onboarding timelines. |
| Geographic Expansion into Underserved Corridors | India's MSME manufacturing clusters in Gujarat and Tamil Nadu face structural working capital gaps underserved by traditional term credit. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with asset-based lending officers, collateral monitoring platform engineers, middle-market CFOs, and field examination specialists; and secondary validation through SEC 10-K filings of major commercial banks, Federal Reserve Senior Loan Officer Opinion Surveys, OCC examination guidance documents, and borrowing base certificate automation vendor disclosures. Bottom-up facility sizing and top-down market sizing triangulated volume estimates across the analysis window.
Forecast inputs considered loan type segmentation by collateral turnover velocity, client segment stratification by enterprise scale and facility complexity, collateral type differentiation by liquidity and valuation certainty, and service provider categorization by regulatory capital regime. CAGRs were derived through regression analysis of historical facility origination trends against macroeconomic indicators and regulatory implementation timelines. Industry-specific forecast inputs included Basel III risk-weighted asset optimization mandates and AI-driven collateral monitoring adoption curves.
Stress conditions across interest rate volatility, collateral valuation uncertainty, and regulatory examination intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sustained middle-market manufacturing demand and continued regulatory preference for secured lending structures. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
United States Digital Lending Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
Russia Auto Loan Market
Loans and Leasing
United States Car Loan Market
Loans and Leasing
Europe Syndicated Loans Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
India Student Loan Market
Loans and Leasing
Japan Auto Loan Market
Loans and Leasing
France Mortgage/Loan Brokers Market
Loans and Leasing
Brazil Home Equity Lending Market
Loans and Leasing
Loan Servicing Software Market
Loans and Leasing
Digital Lending Platform Market
Loans and Leasing
Loan Brokers Market