
 Brazil Car Loan Market | 2026-2036
Brazil Car Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Car Loan Market Insights
Buyer concentration among repeat purchasers and fleet operators is hardening as interest-rate volatility pushes individual first-time buyers toward longer deliberation cycles. Banco do Brasil leverages its expansive branch network and government payroll partnerships to dominate public-sector vehicle financing. Itaú Unibanco competes through proprietary credit-scoring algorithms that integrate alternative data streams beyond traditional bureau scores. Bradesco anchors its position in the used-vehicle segment through captive relationships with certified pre-owned dealer networks.
A Brazil car loan constitutes a secured or unsecured credit instrument collateralized by vehicle title, structured with fixed or floating interest rates tied to the TR reference rate or IPCA inflation index, and disbursed through direct consumer lending or indirect dealer-channel arrangements. Its commercial purpose channels household liquidity into durable-goods acquisition while generating interest income and fee-based revenue for originating institutions. Secured loan structures and dealer financing occupy the dominant share of origination volume, reflecting Brazilian regulatory preference for titled collateral and manufacturer-captive liquidity support. Subprime and near-prime credit-score tiers represent the fastest-expanding margin pools as alternative-data underwriting expands addressable populations previously excluded by bureau-reliant scoring.
Brazil's central bank (BCB) open-banking regulations and PIX instant-payment infrastructure reshape disbursement velocity and cost structures, while ANVISA and CONTRAN vehicle-safety standards indirectly influence loan-to-value ratios through collateral-residual-value calculations. The Securities and Exchange Commission of Brazil (CVM) governs securitization of auto-receivables portfolios, constraining non-bank lenders' funding flexibility. Stakeholders must monitor how BCB's ongoing adjustments to reserve requirements and consumer-credit rules recalibrate pricing power across secured and unsecured product lines.
Market Dynamics
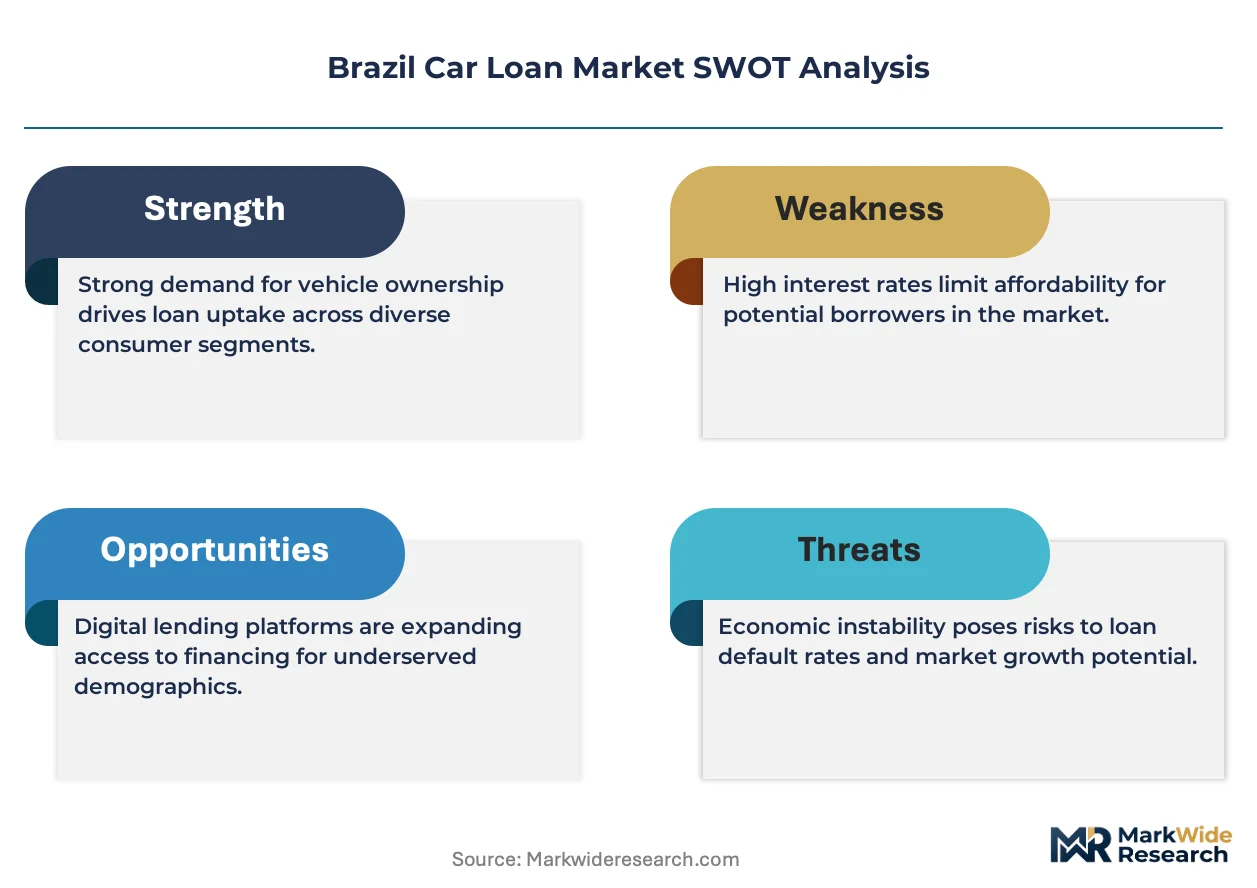
PIX instant-payment infrastructure and open-banking mandates from Brazil's central bank are compressing disbursement timelines from days to minutes, eliminating documentation friction that previously excluded informal workers from formal credit access.
Growth Catalysts
- Payroll-deduction auto credit:Formal employment channels in Brazil's Northeast and Central-West regions are concentrating demand as this instrument penetrates public and private sector payroll systems.
- Alternative-data underwriting:Credit-scoring algorithms integrating utility payments and mobile transaction histories are expanding addressable populations previously excluded by bureau-reliant models.
- Digital onboarding platforms:São Paulo's metropolitan corridor lenders are reducing KYC friction through biometric identity verification and automated document collection.
Market Restraints
- TR reference rate volatility:Floating-rate loan structures expose borrowers to payment shock when Brazil's central bank adjusts monetary policy, lengthening deliberation cycles among first-time buyers.
- Collateral residual-value uncertainty:ANVISA and CONTRAN vehicle-safety standard updates create depreciation risk that compresses loan-to-value ratios for older vehicle vintages.
- Securitization constraints:CVM governance of auto-receivables portfolios limits non-bank lenders' funding flexibility, concentrating origination capacity among deposit-taking institutions.
Strategic Opportunities
- Subprime near-prime margin pools:Credit-score tiers below prime represent expanding addressable markets as alternative-data sources validate repayment capacity invisible to traditional scoring.
- Used-vehicle certified pre-owned networks:Dealer-channel captive relationships unlock inventory financing and residual-value guarantees that reduce lender collateral risk.
- IPCA-indexed fixed-rate products:Inflation-linked structures offer payment predictability that attracts rate-sensitive borrowers away from TR-linked floating exposure.
Industry Challenges
- Legacy core system integration:Incumbent banks face technical debt when embedding open-banking APIs and real-time PIX settlement into decades-old loan origination platforms.
- Alternative-data compliance:LGPD privacy framework creates friction in collecting and processing non-traditional credit signals, requiring governance investment that delays product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Car Loan Market |
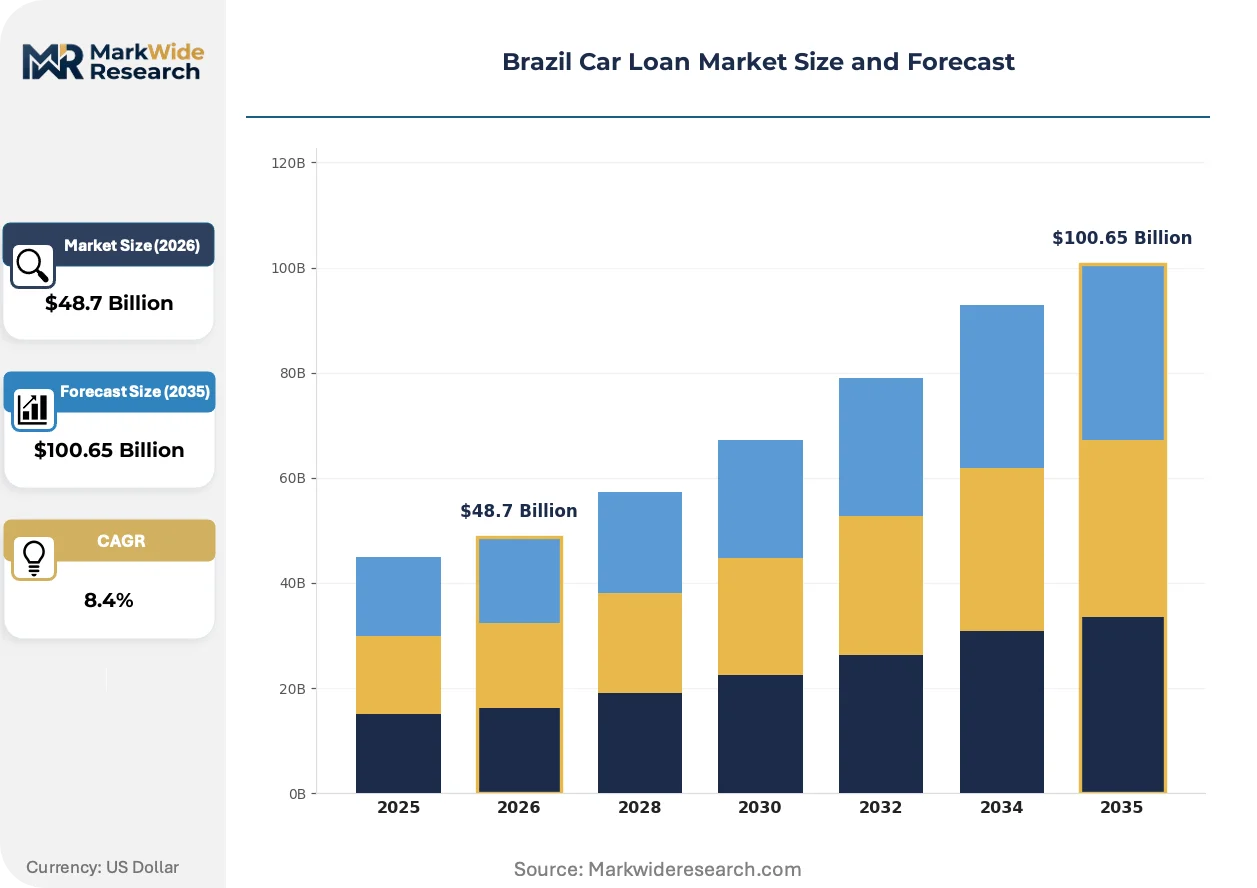
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Secured Loan, Unsecured Loan, Personal Loan, Dealer Financing Customer Demographic: First-Time Buyers, Repeat Buyers, Business Owners, Students Credit Score: Prime, Subprime, Near-Prime, Bad Credit Duration: Short-Term, Medium-Term, Long-Term, Flexible Term |
| Companies Covered | Banco do Brasil, Itaú Unibanco, Bradesco, Santander Brasil, Caixa Econômica Federal, BV Financeira, Banco Safra, Banco Pan, Volkswagen Financial Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Car Loan Market Trends and Innovations
Three interconnected shifts are restructuring how vehicle credit originates, prices, and distributes across Brazil's formal and informal employment corridors.
Machine-learning credit-scoring engines are automating risk assessment for thin-file borrowers previously invisible to bureau-dependent models. Fintech lenders and digital arms of major banks deploy these systems to underwrite payroll-deduction auto credit for informal workers with consistent digital payment histories. The technology is automating approval decisions that previously required manual review, compressing origination costs and expanding margin capture in subprime segments.
Brazil's central bank open-banking regulations mandate standardized API access to customer financial data, dismantling information asymmetries that protected incumbent lenders. The framework forces institutions to compete on algorithmic pricing precision rather than proprietary data hoarding. Public-sector payroll partnerships and fintech platforms are responding by building consent-management layers that convert regulatory compliance into customer acquisition channels.
First-time buyers in São Paulo's metropolitan corridor are abandoning branch-based deliberation for mobile-first comparison platforms that aggregate pre-qualified offers across multiple lenders. Dealer indirect channels face disintermediation pressure as digital marketplaces enable direct consumer-lender matching with transparent rate disclosure. This behavioral pivot is most visible among younger formal-sector workers who prioritize disbursement speed over relationship-based origination.
Brazil Car Loan Market Segmentation
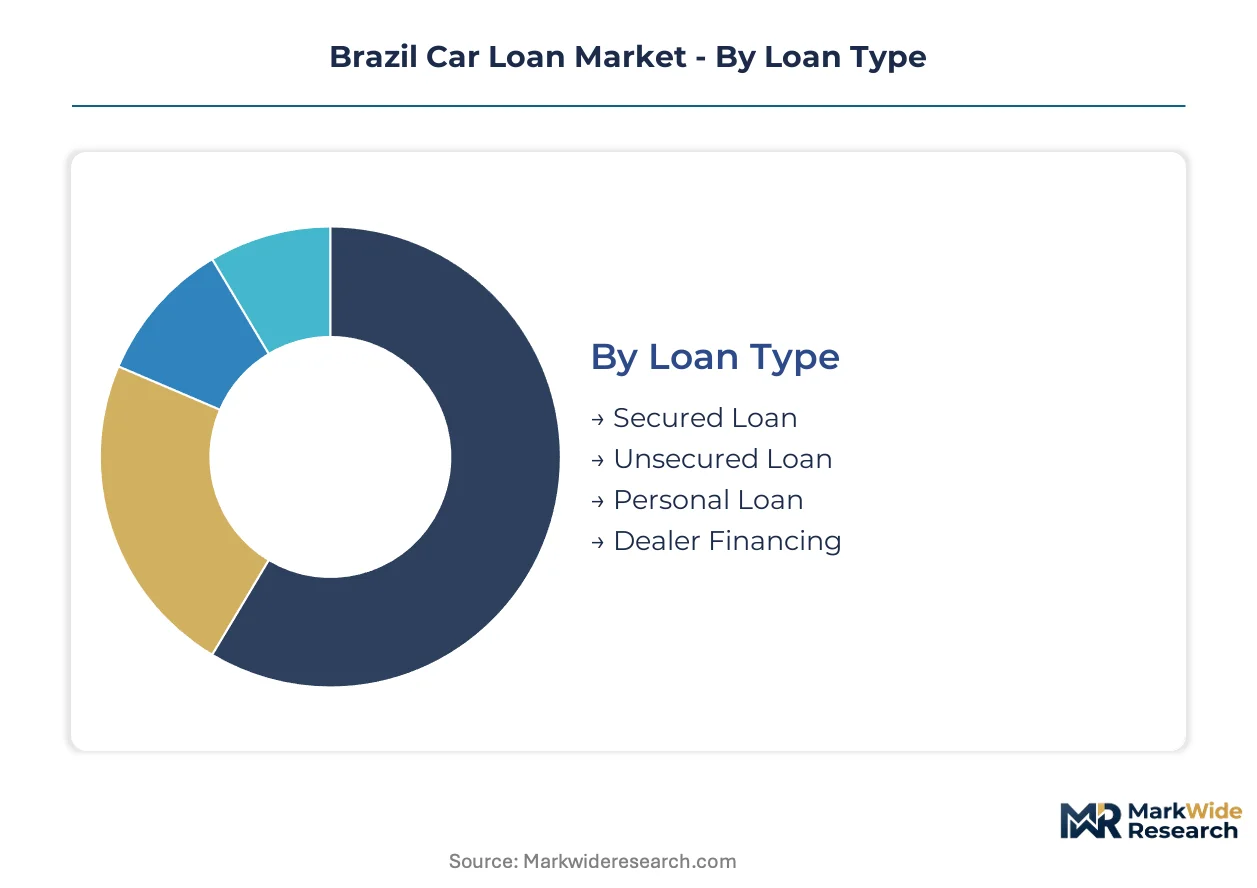
Segmentation in Brazil's car loan market determines pricing precision, risk calibration, and channel strategy for lenders navigating the country's formal-informal employment divide. Each dimension reveals distinct origination patterns across payroll-deduction corridors, credit-score tiers, and digital onboarding preferences.
Loan Type:
Standalone loan products operate independently of dealer systems, while embedded financing integrates directly into point-of-sale vehicle transactions.
- Secured Loan:Vehicle title serves as collateral, reducing lender risk and enabling lower interest rates tied to TR reference rate movements. Demand concentrates among public-sector workers in São Paulo's metropolitan corridor where payroll deduction automates repayment. Banco do Brasil dominates this segment through government employment partnerships.
- Unsecured Loan:No collateral requirement drives higher pricing to offset default risk, attracting borrowers with established credit histories who prioritize speed over rate optimization. Itaú Unibanco's alternative-data algorithms expand addressable populations here. Northeast region informal workers with consistent PIX payment histories represent the fastest-expanding customer base.
- Personal Loan:General-purpose credit structure repurposed for vehicle acquisition, typically carrying shorter tenors and higher rates than dedicated auto products.
- Dealer Financing:Indirect origination through captive finance arms and certified pre-owned networks, with Bradesco anchoring market position via exclusive dealer relationships.
Secured loans lead volumes today; unsecured products are gaining share fastest among digitally-native first-time buyers.
Customer Demographic:
Cost-tier differentiation separates mass-market acquisition from premium relationship-based origination strategies.
- First-Time Buyers:Thin-file borrowers without established bureau histories, requiring alternative-data validation of repayment capacity through utility and mobile payment records. Digital onboarding platforms in São Paulo reduce documentation friction for this price-sensitive segment.
- Repeat Buyers:Established credit relationships enable preferential pricing and accelerated approval workflows, though interest-rate volatility has lengthened deliberation cycles.
- Business Owners:Commercial vehicle financing with tax-deduction structures and fleet-scale negotiation leverage.
- Students:Co-signed or income-contingent products targeting formal education enrollees with future earnings potential.
Repeat buyers anchor current origination volumes; first-time buyers are expanding most quickly as PIX infrastructure democratizes credit access.
Credit Score:
Application-based segmentation aligns risk tiers with specific employment-channel penetration strategies.
- Prime:Top-tier borrowers with comprehensive bureau histories qualifying for TR-linked floating rates or IPCA-indexed fixed products. Public and private sector formal employment channels in Southeast region concentrate demand.
- Subprime:Below-threshold bureau scores requiring alternative-data supplementation through open-banking consented transaction histories. Machine-learning scoring engines from fintech lenders automate approvals previously requiring manual review.
- Near-Prime:Borderline profiles benefiting from enhanced data integration, representing expanding margin pools as payroll-deduction auto credit penetrates Central-West formal employment.
- Bad Credit:Recovery-focused products with secured structures and conservative loan-to-value ratios mitigating collateral depreciation risk.
Prime segments dominate outstanding balances; subprime and near-prime tiers show steepest expansion trajectory as alternative-data underwriting matures.
Duration:
Volume concentration varies across maturity structures reflecting borrower cash-flow profiles and vehicle residual-value expectations.
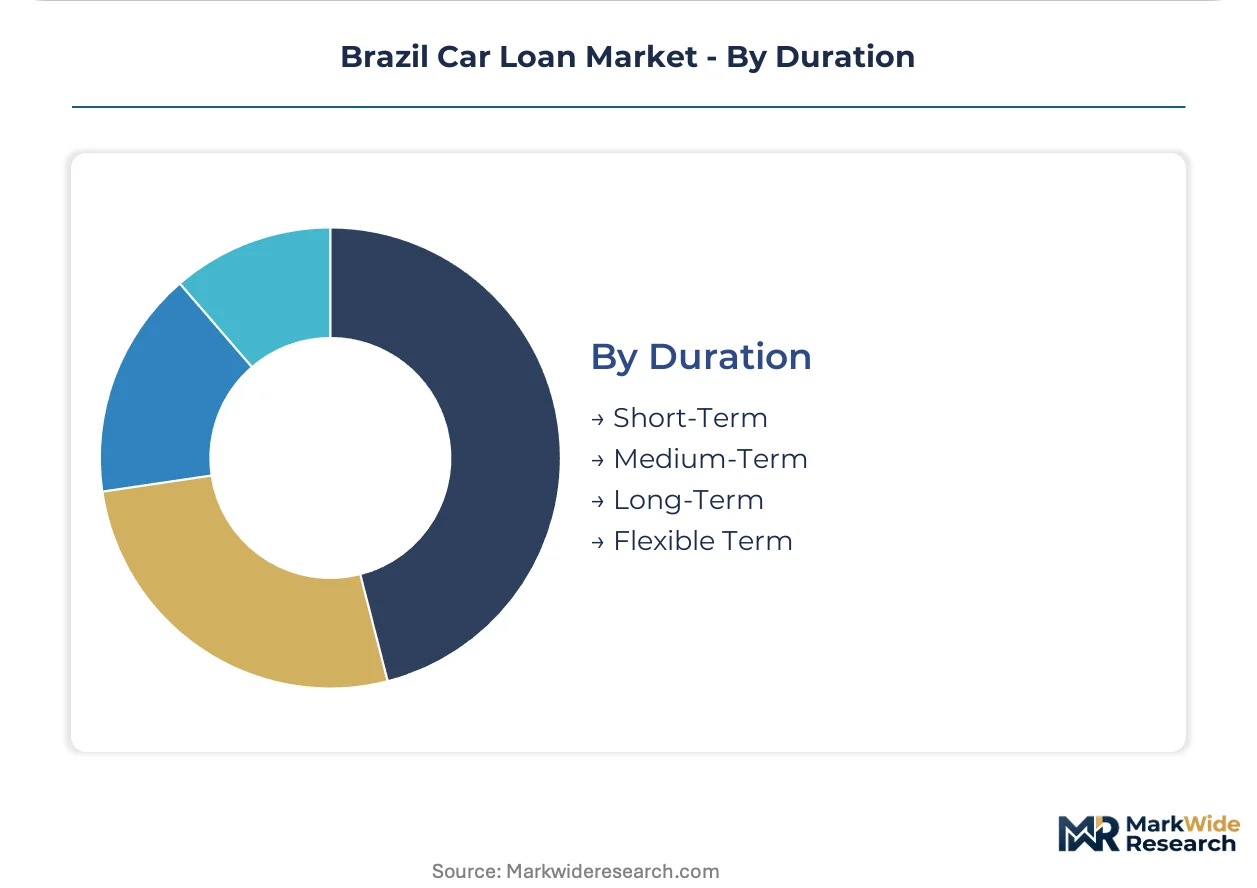
- Short-Term:Tenors under 24 months for used-vehicle acquisition or high-equity borrowers minimizing interest burden. Certified pre-owned networks in Bradesco's dealer channel favor this structure.
- Medium-Term:24-48 month standard for new-vehicle financing balancing affordability with depreciation alignment.
- Long-Term:Extended tenors stretching 60-72 months to accommodate first-time buyer payment capacity, prevalent in Northeast payroll-deduction penetration.
- Flexible Term:Adjustable amortization responding to income seasonality, particularly relevant for informal workers with irregular PIX-based earnings patterns.
Medium-term structures lead origination volumes today; flexible-term products are climbing the fastest among gig-economy participants in São Paulo's metropolitan corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Northeast region trails São Paulo's metropolitan corridor in origination velocity, yet payroll-deduction penetration is accelerating faster in Salvador and Recife than in the Southeast's mature markets. This geographic divergence shapes lender deployment strategies across the country's formal employment corridors.
São Paulo
Digital onboarding platforms and PIX-enabled disbursement infrastructure concentrate demand in Brazil's financial capital. Banco Central do Brasil's open-banking mandates force institutions to compete on algorithmic pricing rather than proprietary data hoarding. First-time buyers in the metropolitan corridor abandon branch-based deliberation for mobile-first comparison platforms.
Minas Gerais
Belo Horizonte anchors payroll-deduction auto credit expansion through public and private sector formal employment channels. ANVISA vehicle-safety standards influence loan-to-value calculations for collateral residual values. Near-prime credit tiers show steepest expansion as alternative-data underwriting penetrates manufacturing and mining employment bases.
Rio Grande do Sul
Porto Alegre's industrial economy sustains repeat buyer origination volumes despite interest-rate volatility lengthening deliberation cycles. CONTRAN regulatory updates create depreciation uncertainty for older vehicle vintages. Bradesco's certified pre-owned dealer networks dominate used-vehicle financing in this southern concentration.
Bahia
Salvador's formal employment growth drives subprime segment expansion as machine-learning scoring engines validate thin-file borrowers. LGPD privacy compliance creates friction in alternative-data collection, delaying product launches. Long-term tenors stretching 60-72 months accommodate first-time buyer payment capacity.
Paraná
Curitiba's diversified economy balances prime and near-prime origination mix. CVM securitization governance constrains non-bank lender funding flexibility, concentrating capacity among deposit-taking institutions. IPCA-indexed fixed-rate products attract rate-sensitive borrowers away from TR-linked floating exposure.
Brazil Car Loan Market Competitive Landscape
Southeast-based banking conglomerates anchor the premium tier; regional specialists and captive finance arms hold differentiated positions in dealer-channel and subprime segments. The vendor structure concentrates origination capacity among five deposit-taking institutions with government payroll partnerships, while fintech platforms and manufacturer captives fragment remaining share. Two strategic archetypes dominate: legacy banks leveraging branch density and public-sector relationships, and digital-native lenders deploying alternative-data algorithms. Competitive moves center on open-banking API integration and payroll-deduction channel expansion.
Within the legacy banking tier, Banco do Brasil exemplifies public-sector payroll dominance through government employment partnerships. Itaú Unibanco occupies a position defined by proprietary credit-scoring algorithms integrating alternative data streams. Bradesco anchors the used-vehicle segment through dealer-channel captive relationships, representing the indirect origination archetype.
| Leading Market Players |
|---|
| Banco do Brasil |
| Itaú Unibanco |
| Bradesco |
| Santander Brasil |
| Caixa Econômica Federal |
| BV Financeira |
| Banco Safra |
| Banco Pan |
| Volkswagen Financial Services |
| Others |
Pricing and Supply Chain Analysis
Prime-subprime rate divergence between payroll-deduction corridors and thin-file digital channels manifests in both pricing spreads and funding-source configurations across Brazil's auto credit ecosystem. Banco Central do Brasil reserve requirements and CVM securitization governance concentrate low-cost funding among deposit-taking institutions while fintech platforms absorb higher wholesale costs.
Pricing Analysis
Capacity additions in digital onboarding infrastructure are reshaping price floors for unsecured auto credit products. Pricing stratifies across payroll-linked floating rates, IPCA-indexed fixed structures, and unsecured digital-channel premiums. Cost compression in subprime segments intensifies because machine-learning scoring engines automate previously manual underwriting. First-time buyers in São Paulo's metropolitan corridor exhibit highest price sensitivity; public-sector payroll borrowers show lowest sensitivity due to automatic deduction convenience.
Supply Chain Analysis
Funding supply rests on Brazil's deposit-taking institutions, CVM-governed securitization markets, and manufacturer captive finance arms. Raw material dependencies include retail deposit bases, auto-receivables portfolios, and interbank liquidity facilities. Single-source vulnerability concentrates in Banco Central do Brasil monetary policy transmission. Distribution runs through direct consumer lending platforms, indirect dealer-channel arrangements, and payroll-deduction employment partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's car loan market represents a late-cycle quality story as first-time buyers migrate toward IPCA-indexed fixed-rate products that prioritize payment predictability over rate optimization.
For Market Incumbents: Anchor dominance in payroll-deduction channels through deeper public-sector employment partnerships while hardening proprietary credit-scoring algorithms against open-banking data commoditization. Banco Central do Brasil reserve requirement adjustments threaten net interest margins; vertical integration into certified pre-owned dealer networks preserves collateral-value visibility. For New Entrants and Emerging Players: BCB open-banking regulations in Brazil open a window for thin-file underwriting specialization targeting Northeast and Central-West informal workers with consistent PIX payment histories. Subprime near-prime tiers offer the most penetrable white space. Go-to-market execution should prioritize mobile-first consent-management layers that convert regulatory compliance into customer acquisition velocity. For Investors and Strategic Acquirers: Consolidation pressure builds where legacy core system technical debt impedes real-time PIX settlement integration. Long-term viability favors deposit-taking institutions with government payroll partnerships over wholesale-funded fintech platforms. Watch BCB consumer-credit rule adjustments as the inflection signal for pricing power recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Open-Banking API Integration | BCB mandates force algorithmic pricing competition dismantling proprietary data hoarding advantages. |
| Payroll-Deduction Channel Expansion | Public and private sector formal employment partnerships automate repayment reducing default probability. |
| Alternative-Data Scoring Investment | Machine-learning engines validate thin-file borrowers invisible to bureau-dependent traditional models. |
| IPCA-Indexed Product Development | Inflation-linked structures attract rate-sensitive first-time buyers away from TR-linked floating exposure. |
| Certified Pre-Owned Network Partnership | Dealer-channel captive relationships unlock residual-value guarantees reducing lender collateral risk. |
Research Methodology
Bottom-up loan origination modeling reconciled against top-down funding-source tracking forms the analytical core of this study. Primary interviews with auto finance executives, credit risk officers, dealer network managers, and payroll system administrators combined with secondary validation from BCB regulatory filings, CVM securitization disclosures, ANFAVEA production statistics, and Serasa Experian credit bureau data. Triangulation across stakeholder perspectives and official data sources ensures consistency.
Input-output matrices map disbursement volume through segmentation dimensions including loan type, customer demographic, credit-score tier, and regional employment corridor across the projection horizon. CAGRs derive from fitted trend analysis incorporating BCB monetary policy trajectories, PIX adoption curves, and payroll-deduction penetration rates. Forecast inputs include open-banking API transaction volumes and alternative-data scoring engine deployment counts.
Revisions become necessary when BCB reserve requirement adjustments, CVM securitization rule changes, or ANVISA vehicle-safety standard updates materially alter collateral-residual-value assumptions. Forecasts reflect documented assumptions about formal employment growth and PIX infrastructure expansion. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Factoring Market
Loans and Leasing
Asia-Pacific Car Loan Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
Auto Finance Market
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
Microfinance Market
Loans and Leasing
US Factoring Services Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
China Mortgage/Loan Brokers Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
South Korea Car Loan Market
Loans and Leasing
Home Equity Lending Market
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
India Home Loan Market
Loans and Leasing
Truck Financial Leasing Market
Loans and Leasing
Russia Student Loan Market