
 Asia-Pacific Syndicated Loans Market | 2026-2036
Asia-Pacific Syndicated Loans Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Syndicated Loans Market Insights
Bank distribution channels across Southeast Asia is fragmenting as digital origination platforms and direct lender consortiums bypass traditional lead arranger hierarchies. Oversea-Chinese Banking Corporation leverages its Singapore hub to anchor cross-border infrastructure mandates throughout ASEAN. MUFG Bank competes through deep relationships with Japanese trading houses financing regional energy transitions. Standard Chartered Bank differentiates via its Africa-Asia corridor expertise, sustaining competitive position in emerging market syndications.
Asia-Pacific syndicated loans represent multi-bank credit facilities structured for single borrowers requiring capital amounts exceeding individual bank risk appetite limits, typically governed by facility agreements specifying margin grids, covenant packages, and intercreditor arrangements. Term loans dominate volume flows for project finance and acquisition funding, while revolving credit facilities serve working capital needs for regional corporates navigating currency volatility. Floating rate structures linked to replacement benchmarks now lead pricing conventions as LIBOR cessation forces documentation migration across outstanding portfolios.
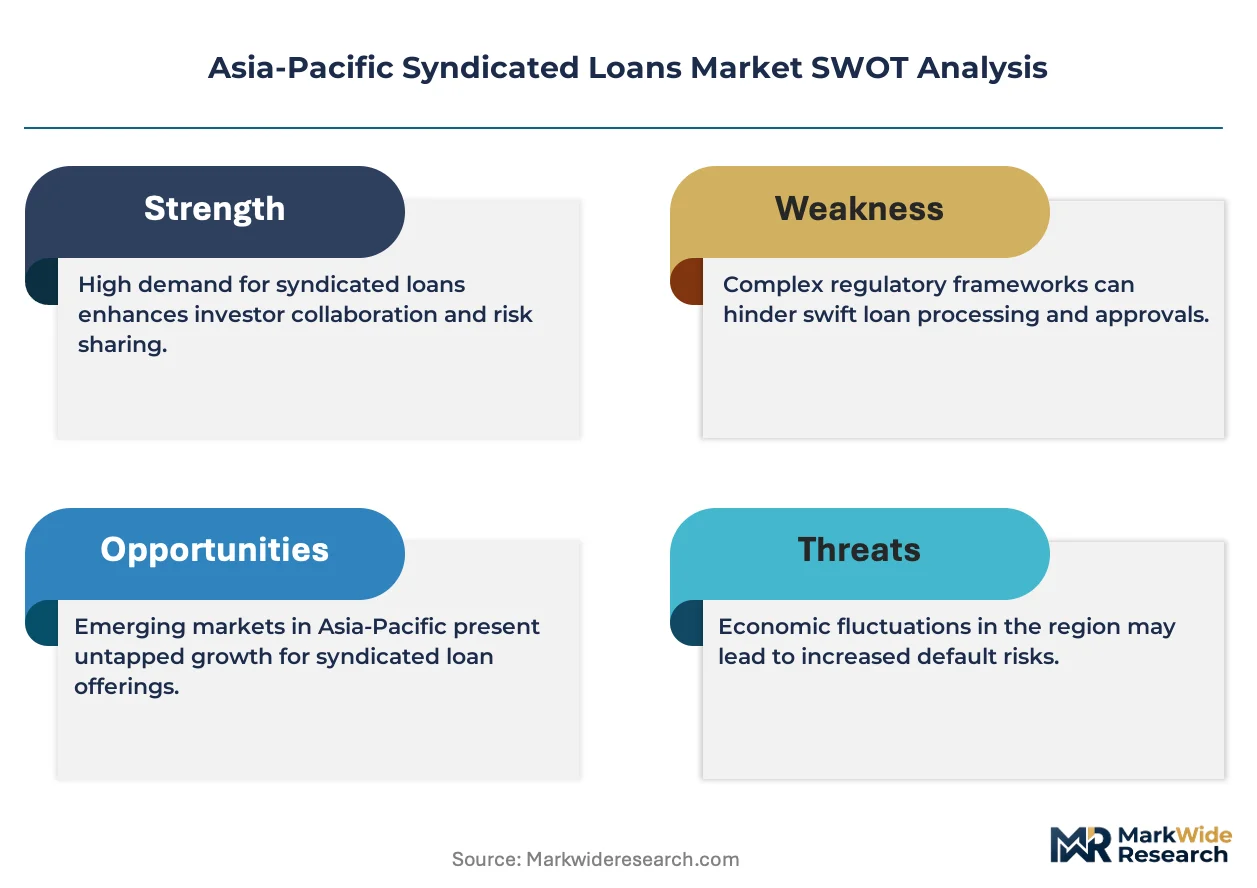
Monetary Authority of Singapore, Reserve Bank of India, and Australian Prudential Regulation Authority shape demand through capital adequacy requirements, large exposure limits, and foreign currency hedging rules that determine bank participation capacity. India's RBI mandates priority sector lending quotas that redirect syndicated flows toward infrastructure and renewable energy borrowers. Stakeholders must monitor reference rate transition completion, cross-border data localization requirements, and evolving green loan taxonomy alignment as these factors determine future structuring feasibility and investor participation depth.
Market Dynamics
Asia-Pacific syndicated loans face structural pressure from the transition away from LIBOR toward risk-free reference rates, forcing wholesale documentation revisions across trillion-dollar outstanding portfolios and compressing pricing conventions throughout the region.
Growth Catalysts
- Southeast Asian Infrastructure Mandates:Indonesia's Trans-Java toll road and Vietnam's North-South expressway generate multi-bank credit facilities exceeding single-lender risk limits. National development banks in the Philippines and Thailand provide partial risk guarantees that expand commercial bank participation.
- RBI Priority Sector Lending Quotas:India's central bank mandates directed credit flows toward renewable energy and infrastructure borrowers, redirecting syndicated loan volumes into solar parks and transmission networks. State-level discom reform programs create additional origination pipelines.
- Digital Origination Platforms:API-enabled loan marketplaces connecting borrowers directly to lender consortiums compress arrangement timelines from weeks to days. Singapore's fintech sandbox approvals accelerate platform deployment across ASEAN.
Market Restraints
- Reference Rate Transition Friction:Legacy LIBOR-linked contracts require bilateral amendments to adopt SARON, TONA, or BBSW replacements. Documentation ambiguity around fallback trigger definitions creates legal uncertainty for outstanding facilities.
- Concentrated Lead Arranger Capacity:Cross-border infrastructure mandates depend on a narrow tier of Singapore-headquartered banks with ASEAN regulatory licenses. Australian domestic miners face reduced international bank appetite during commodity price troughs.
- Currency Hedging Cost Volatility:Indian renewable borrowers face elevated forward premium costs when rupee depreciation accelerates. Reserve Bank of India foreign currency hedging rules limit natural hedge alternatives for project sponsors.
Strategic Opportunities
- Vietnam Power Sector Privatization:Equitization of state-owned generation assets creates greenfield financing demand for combined-cycle gas and offshore wind portfolios. EVN restructuring opens independent power producer syndication opportunities previously restricted to bilateral state lending.
- Sustainability-Linked Margin Structures:KPI-tied pricing grids tied to renewable capacity additions or emissions reductions attract ESG-focused institutional lenders. ASEAN Taxonomy for Sustainable Finance provides standardized eligibility criteria.
- Direct Lending Consortium Formation:Australian superannuation funds and Asian insurance pools bypass bank intermediation to originate senior secured term loans. Melbourne and Sydney fund managers build in-house credit underwriting capabilities.
Industry Challenges
- Intercreditor Agreement Complexity:Multi-tranche project finance structures involving export credit agencies, commercial banks, and development finance institutions require bespoke subordination frameworks. Negotiation timelines extend 4-6 months for greenfield infrastructure.
- Covenant Monitoring Automation:Borrower reporting obligations across 15-25 lender syndicates demand standardized data formats. Legacy loan administration systems lack API connectivity for real-time compliance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Syndicated Loans Market |
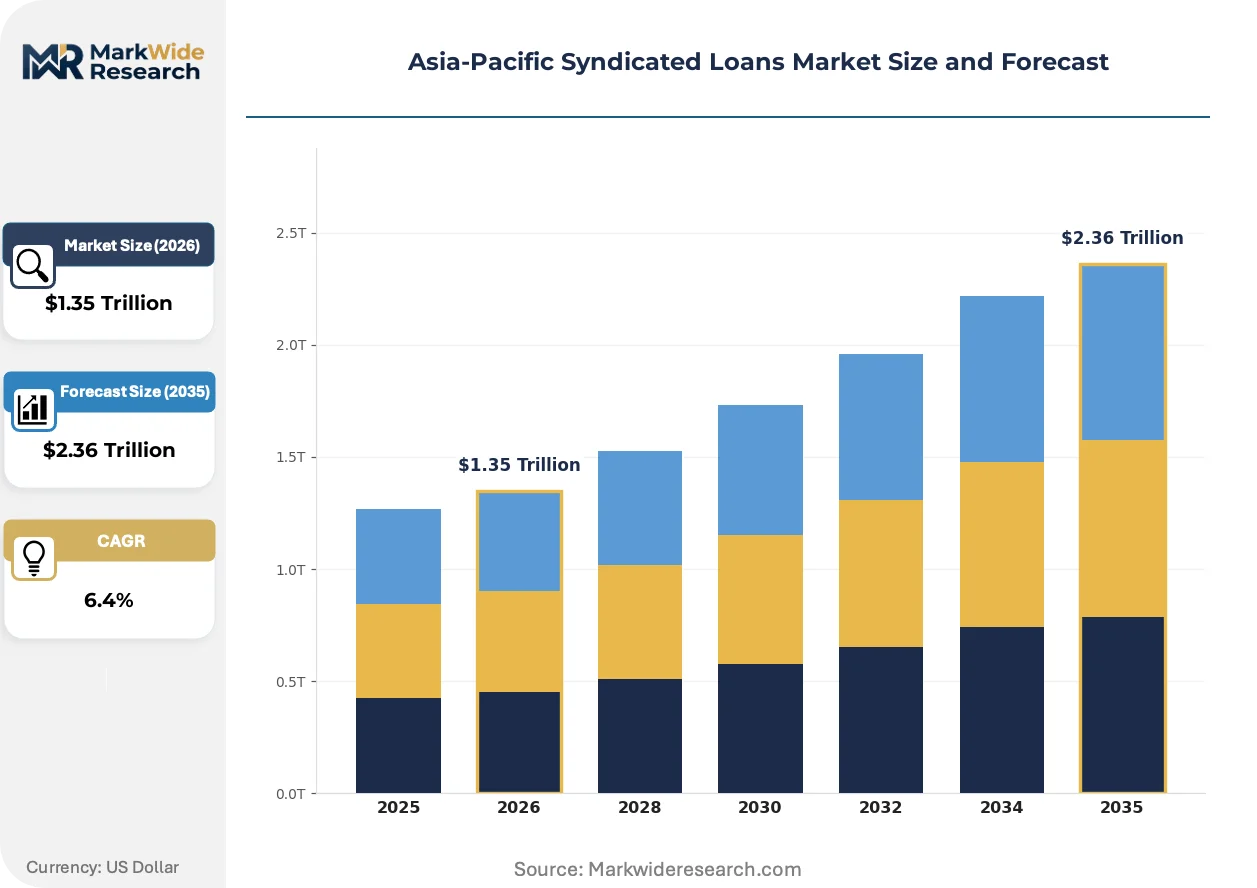
| Market Size in 2026 | $1.35 Trillion |
| Market Size in 2035 | $2.36 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Secured Loans, Unsecured Loans, Revolving Credit, Term Loans Borrower Type: Corporates, Financial Institutions, Governments, Infrastructure Projects Interest Rate Type: Fixed Rate, Floating Rate, Hybrid Rate, LIBOR-based Industry Sector: Telecommunications, Energy, Real Estate, Transportation |
| Companies Covered | Oversea-Chinese Banking Corporation, ANZ Banking Group, DBS Bank, Mizuho Bank, Bank of China, Standard Chartered Bank, MUFG Bank, Maybank, United Overseas Bank, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Syndicated Loans Market Trends and Innovations
Documentation automation and ESG-linked pricing mechanics are compressing traditional arranger fee structures while expanding participation pools beyond conventional bank lenders across the Asia-Pacific loan market.
Blockchain-based smart contract platforms for loan administration are rendering obsolete manual agent bank processes for interest calculations and covenant compliance tracking. Australian mining corporates and Indian renewable developers pilot these systems for revolving credit facilities with 12-15 lender syndicates. Distributed ledger verification cuts administrative costs by eliminating reconciliation disputes between borrowers and facility agents.
Monetary Authority of Singapore's transition roadmap for SOR cessation mandates complete SARON adoption by mid-2024, forcing documentation migration for all SGD-denominated syndicated facilities. Facility agreements now incorporate compounded in-arrears rate calculations and spread adjustment mechanisms. Indonesian and Malaysian borrowers with SGD tranches face accelerated legal review timelines to meet compliance deadlines.
Buyers now unbundle arrangement fees from ongoing agency services, selecting specialized third-party administrators for post-close loan operations. Singapore-based fund administrators and Mumbai financial service providers capture agency mandates from traditional lead banks. This procurement fragmentation is most visible in Australian acquisition finance where private equity sponsors drive vendor selection for facility agent roles.
Asia-Pacific Syndicated Loans Market Segmentation
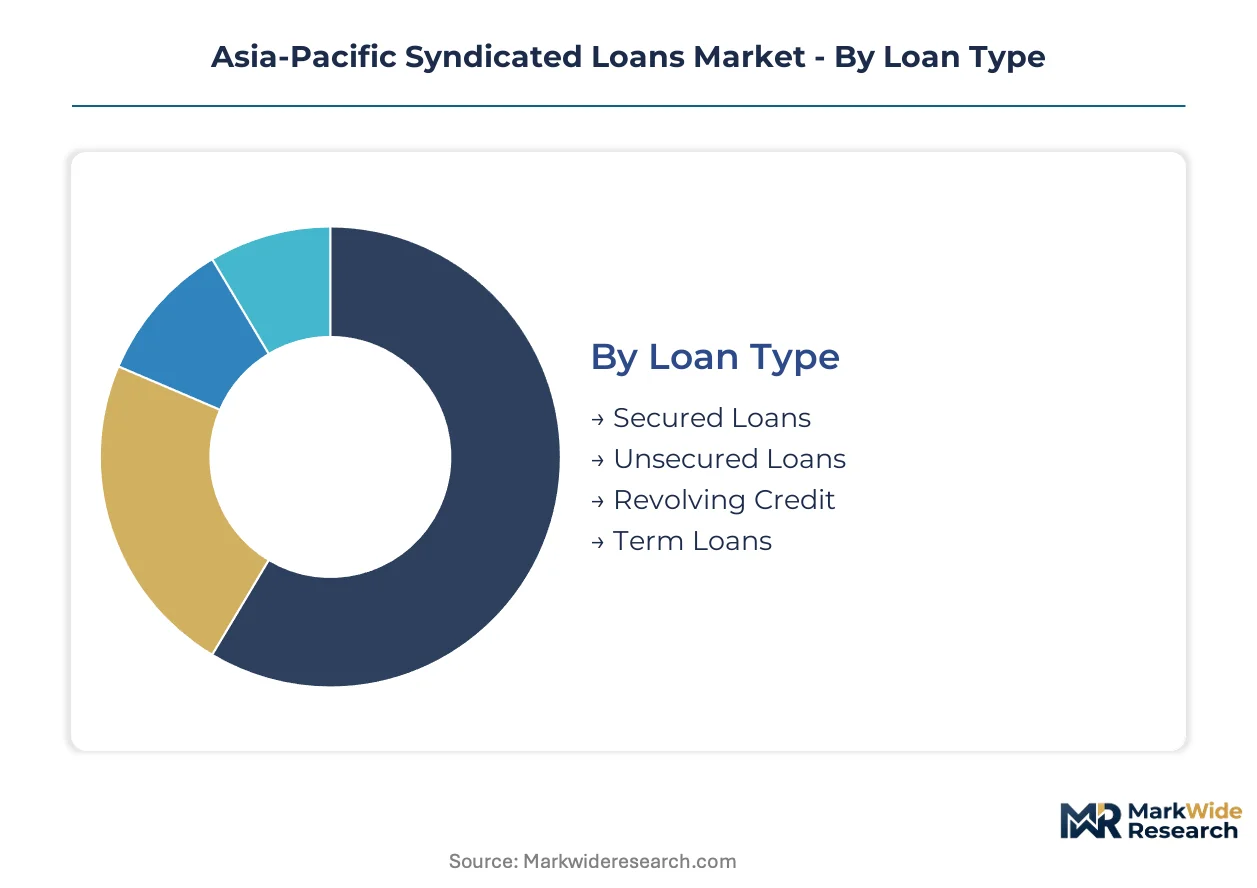
Syndicated loan structuring varies fundamentally across borrower risk profiles, collateral frameworks, and regulatory treatment. Segmentation reveals how facility design adapts to single-borrower concentration limits and cross-border enforcement complexity.
Loan Type:
Mature collateral-backed structures dominate institutional portfolios while emerging unsecured formats test risk appetite in volatile credit cycles.
- Secured Loans:Asset-backed facilities with first-ranking security over mining equipment, power generation assets, or toll road concessions. Australian mining corporates and Indonesian infrastructure sponsors concentrate demand here as lenders enforce collateral perfection across ASEAN jurisdictions.
- Unsecured Loans:Covenant-heavy facilities relying on borrower cash flow coverage without specific asset pledges. Investment-grade corporates in Singapore and Hong Kong access these structures where cross-border collateral enforcement remains legally uncertain.
- Revolving Credit:Working capital facilities with drawdown flexibility for seasonal commodity traders and regional supply chain operators.
- Term Loans:Amortizing structures for acquisition finance and project completion milestones with bullet repayment profiles.
Term loans retain volume leadership; revolving credit holds the steepest expansion curve.
Borrower Type:
Cost tier stratification separates investment-grade access from development bank-dependent segments requiring risk mitigation wrappers.
- Corporates:Multinational manufacturers and regional conglomerates funding working capital, capex programs, and cross-border M&A. Pricing grids reflect leverage ratios and ESG rating differentials.
- Financial Institutions:Banks and non-bank lenders accessing wholesale funding for on-lending operations. Basel III liquidity coverage ratios determine tenor appetite.
- Governments:Sovereign and sub-sovereign borrowers tapping syndicated markets for budget support and liability management.
- Infrastructure Projects:Greenfield SPVs with offtake-backed revenue streams dominating Vietnam power and Indonesia toll road mandates.
Corporates anchor absolute volume; infrastructure projects command the widest syndicate participation.
Interest Rate Type:
Application-driven selection separates benchmark-referenced working capital from hedged long-dated project exposures.
- Floating Rate:Facilities tied to SARON, TONA, or BBSW replacing legacy LIBOR structures. Indian renewable developers and Australian miners dominate uptake as natural hedges against commodity price cycles.
- Fixed Rate:Bond-style amortizing structures with swapped liabilities for infrastructure assets with predictable revenue profiles.
- Hybrid Rate:Split structures combining initial fixed periods with subsequent floating resets for acquisition finance.
- LIBOR-based:Legacy contracts undergoing mandatory transition with spread adjustment mechanisms and fallback trigger renegotiation.
Floating rate structures dominate outstanding stock; hybrid formats are gaining share fastest among sponsor-backed transactions.
Industry Sector:
Geographic concentration of sector expertise shapes arranger specialization and lender consortium formation.
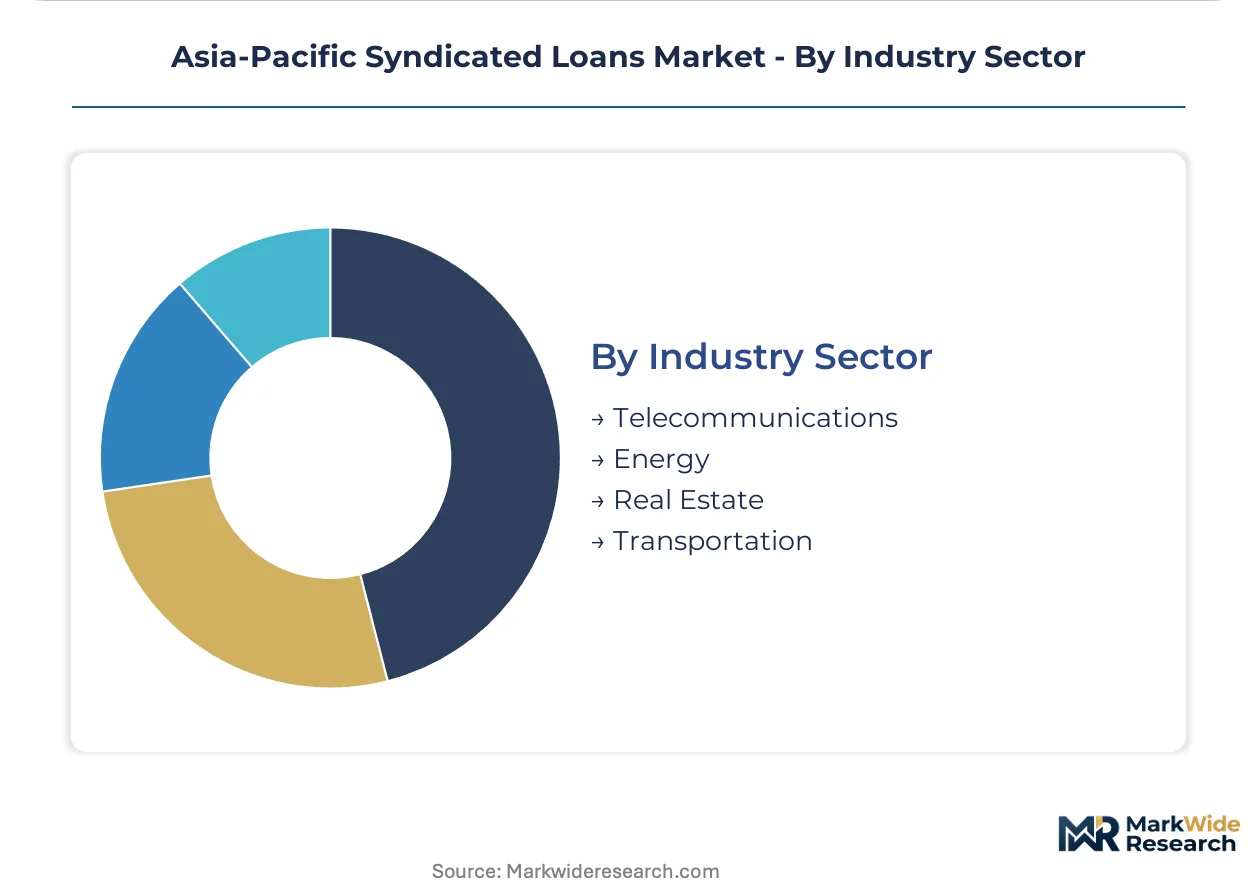
- Energy:Upstream oil and gas, LNG terminals, and integrated power utilities requiring multi-tranche project finance. Japanese trading houses and Korean ECAs anchor participation.
- Real Estate:Commercial and residential development with REIT acquisition financing concentrated in Singapore and Australian gateway cities.
- Telecommunications:5G spectrum acquisition and tower infrastructure rollouts across Indonesia and Philippines.
- Transportation:Airport privatization, port concessions, and rail electrification with government availability payment structures.
Energy commands the deepest liquidity pools; transportation infrastructure shows the most pronounced origination pipeline expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reserve Bank of India's priority sector lending mandates and Australia's prudential framework are redirecting syndicated credit flows toward infrastructure and energy transition assets across the region.
Australia
Mining-energy corporates in Western Australia and Queensland dominate secured term loan demand for capital-intensive extraction projects. Australian Prudential Regulation Authority capital adequacy requirements shape bank participation capacity for cross-border mandates. Melbourne and Sydney fund managers are building direct lending capabilities to bypass traditional bank intermediation for acquisition finance.
India
Renewable energy developers in Gujarat and Rajasthan require multi-bank facilities for solar park construction and transmission network expansion. RBI-mandated priority sector lending quotas redirect syndicated volumes toward infrastructure borrowers. Mumbai-based arrangers are structuring sustainability-linked margin grids tied to emissions reduction targets for ESG-focused institutional participation.
Singapore
Cross-border infrastructure mandates throughout ASEAN anchor at Singapore's financial hub, leveraging the city-state's regulatory licenses and legal framework. Monetary Authority of Singapore's SARON transition roadmap forces documentation migration for all SGD-denominated facilities. DBS Bank and Oversea-Chinese Banking Corporation compete for lead arranger roles on Indonesian toll road and Vietnamese power sector transactions.
Indonesia
Trans-Java toll road and port privatization programs generate greenfield financing demand exceeding single-lender risk appetite limits. National development bank partial risk guarantees expand commercial bank participation in infrastructure syndications. Jakarta-based project sponsors are negotiating multi-tranche structures involving export credit agencies and development finance institutions.
Vietnam
North-South expressway and power sector equitization are creating independent power producer financing opportunities previously restricted to bilateral state lending. State-owned EVN restructuring opens syndicated markets for combined-cycle gas and offshore wind portfolios. Ho Chi Minh City and Hanoi developers are engaging Singapore-headquartered arrangers for cross-border facility structures.
Asia-Pacific Syndicated Loans Market Competitive Landscape
On the supply side, the industry is consolidating around Singapore-domiciled banks with ASEAN regulatory licenses and Japanese megabanks with trading house relationships. Tier-one arrangers compete through geographic coverage depth, while specialist platforms differentiate via sector expertise in mining or renewables. Strategic moves center on digital origination platform deployment and sustainability-linked product development.
Within the Singapore-headquartered tier, Oversea-Chinese Banking Corporation, DBS Bank, and United Overseas Bank anchor cross-border infrastructure mandates throughout Southeast Asia. These institutions leverage the city-state's legal framework and regulatory sandbox approvals to compress arrangement timelines. Japanese megabanks including MUFG Bank and Mizuho Bank compete through deep relationships with trading houses financing regional energy transitions. Standard Chartered Bank occupies a position linking Africa-Asia corridor expertise to emerging market syndications.
| Leading Market Players |
|---|
| Oversea-Chinese Banking Corporation |
| ANZ Banking Group |
| DBS Bank |
| Mizuho Bank |
| Bank of China |
| Standard Chartered Bank |
| MUFG Bank |
| Maybank |
| United Overseas Bank |
| Others |
Pricing and Supply Chain Analysis
Singapore's financial hub concentrates lead arranger capacity for cross-border infrastructure mandates, with DBS Bank and Oversea-Chinese Banking Corporation commanding premium pricing power on Indonesian toll road and Vietnamese power sector transactions. Their regulatory licenses and ASEAN legal framework expertise compress competitor timelines and sustain arrangement fee premiums.
Pricing Analysis
Deal complexity tiering creates the primary spread between vanilla corporate revolvers and multi-tranche project finance structures. Arrangement fees stratify across plain-vanilla working capital facilities, acquisition finance with covenant-heavy packages, and greenfield infrastructure with export credit agency involvement. Pricing pressure stems from digital origination platforms connecting borrowers directly to lender consortiums, bypassing traditional lead bank hierarchies. Private equity sponsors in Australian acquisition finance exhibit highest price sensitivity, while infrastructure SPVs with limited financing alternatives accept premium pricing for execution certainty.
Supply Chain Analysis
Regulatory licensing concentration between Singapore, Hong Kong, and Tokyo creates structural vulnerability for cross-border mandate execution. Capital provision draws from Japanese megabanks, Singapore-domiciled ASEAN specialists, and Australian superannuation funds building direct lending capabilities. Single-source dependency on Monetary Authority of Singapore's SARON transition timeline compresses documentation capacity for SGD-denominated facilities. Distribution runs through lead arranger hierarchies with facility agent roles increasingly unbundled to third-party administrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across digital origination platforms and direct lending consortiums creates entry niches for specialists with sector-specific underwriting capabilities. Borrower demand for compressed arrangement timelines rewards platform investments and sustainability-linked product development.
For Market Incumbents: Build regulatory license moats across ASEAN jurisdictions to defend cross-border infrastructure mandates. Deepen relationships with Japanese trading houses financing energy transitions. Add in-house agency services to capture post-close revenue streams unbundled from arrangement fees. Counter direct lending consortium formation by embedding ESG-linked pricing mechanics that institutional investors cannot replicate independently.
For New Entrants and Emerging Players: Build out sector-specific credit underwriting in Australian mining-energy or Indian renewable energy verticals where incumbent coverage gaps exist. Target Vietnamese power sector privatization opportunities where state-owned EVN restructuring opens previously restricted financing channels. Lead with sustainability-linked margin structure expertise to attract ESG-focused institutional capital seeking direct syndicated loan exposure.
For Investors and Strategic Acquirers: Long-term, this sits as a financial infrastructure play because reference rate transition and documentation automation create persistent demand for specialized loan administration capabilities. Acquisition targets include Mumbai-based financial service providers capturing facility agent mandates and Singapore fund administrators with API-enabled covenant monitoring systems. Watch SARON transition completion and green loan taxonomy alignment as inflection indicators for platform scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Origination Platform Deployment | API-enabled marketplaces connecting borrowers to lender consortiums compress arrangement timelines from weeks to days. |
| Sustainability-Linked Margin Structure Development | KPI-tied pricing grids attract ESG-focused institutional lenders seeking emissions-linked credit exposure. |
| Facility Agent Capability Buildout | Third-party administrators capture post-close mandates unbundled from traditional lead bank arrangements. |
| ASEAN Regulatory License Expansion | Cross-border infrastructure mandates require Singapore, Indonesia, and Vietnam regulatory approvals for execution. |
| Reference Rate Transition Completion | SARON, TONA, and BBSW adoption eliminates legacy LIBOR documentation uncertainty across outstanding portfolios. |
Research Methodology
A standing panel of syndicated loan originators, facility agents, project finance sponsors, and ESG investment officers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through Monetary Authority of Singapore circulars, Reserve Bank of India priority sector lending directives, and Australian Prudential Regulation Authority capital adequacy disclosures. Bottom-up facility-level data triangulated against top-down banking system flow-of-funds statistics.
Scenario bracketing around reference rate transition timelines, commodity price cycles, and regulatory sandbox approvals anchored the analytical framework. Segmentation modeling spanned loan type, borrower category, interest rate structure, and industry sector dimensions across the projection horizon. CAGRs derived from facility origination run-rates, lender capacity constraints, and infrastructure pipeline visibility. Forecast inputs incorporated RBI priority sector lending quota compliance trajectories and ASEAN Taxonomy for Sustainable Finance adoption curves.
Stress conditions across rupee depreciation velocity, SARON spread adjustment disputes, and development bank guarantee availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on lender consortium formation timelines and greenfield project completion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
USA Home Loan Market
Loans and Leasing
United States Car Loan Market
Loans and Leasing
Cash Advance Services Market
Loans and Leasing
NPL Servicing Market
Loans and Leasing
India Auto Loan Market
Loans and Leasing
Used Car Financing Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
Canada Home Equity Lending Market
Loans and Leasing
France Auto Loan Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
Home Equity Lending Market
Loans and Leasing
Unsecured Business Loans Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Loan Brokers Market